
 Global Fruit Spreads Market | 2026-2036
Global Fruit Spreads Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fruit Spreads Market Foresight
Foodservice buyers are unwinding legacy retail-centric purchasing patterns as hotel breakfast programs and cafe operators expand direct procurement of premium fruit spreads. The J.M. Smucker Company leverages its institutional distribution network to sustain volume leadership in North American foodservice channels. Hero Group anchors its competitive position through specialized organic and reduced-sugar formulations that command premium placement in European retail. St. Dalfour differentiates via its no-added-sugar positioning and glass jar packaging that signals quality to discerning buyers across multiple continents.
Fruit spreads encompass processed fruit preparations with minimum soluble solids content typically ranging from 65 to 68 degrees Brix, preserved through sugar concentration, pectin gelation, or thermal processing for shelf-stable distribution to retail and foodservice endpoints. Jam formulations dominate current value generation due to their versatility across breakfast and baking applications, while preserves and fruit butters represent faster-growing niches as consumers seek textured, less-processed alternatives with visible fruit content. Glass jar packaging maintains premium positioning despite higher logistics costs, whereas squeeze bottle formats are gaining traction in convenience-oriented channels and child-focused product lines.
FDA standards of identity for fruit preserves and jams govern permissible fruit and sugar ratios in US commerce, while EFSA and EU food labeling directives mandate nutritional transparency and origin declarations that shape formulation decisions across export-oriented manufacturers. BIS certification requirements in India and FSSAI quality parameters influence market access for imported spreads in South Asian retail. Stakeholders must monitor evolving sugar taxation proposals and single-use packaging restrictions across multiple jurisdictions, as these policy trajectories will determine which product formats and ingredient profiles retain channel access over the coming decade.
Market Dynamics
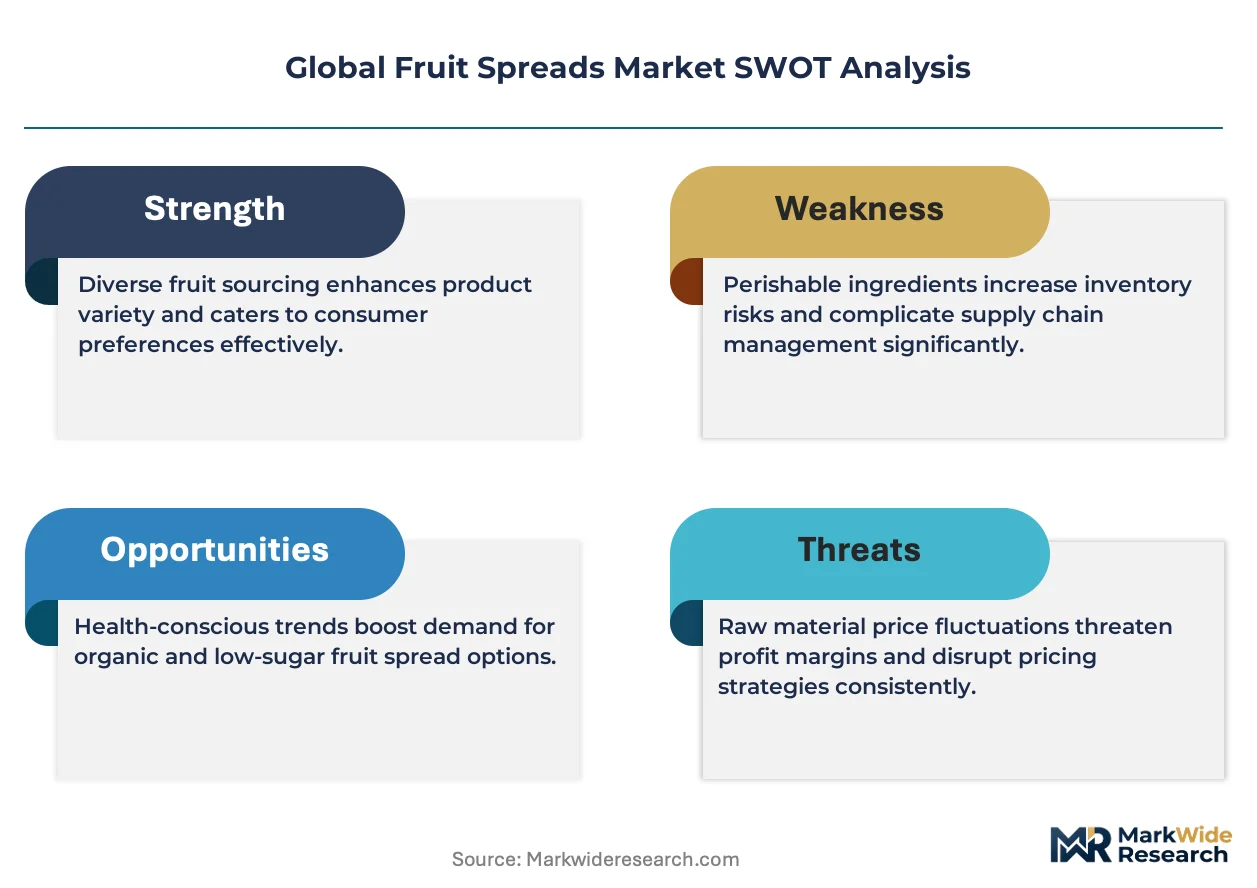
Clean-label formulation mandates from FDA and EFSA are forcing wholesale recipe reformulation across fruit spread manufacturers, compressing margins while opening premium positioning for compliant producers. Sugar reduction targets and single-use packaging restrictions are simultaneously reshaping ingredient sourcing and format decisions.
Growth Catalysts
- EU Food Labeling Directives:Nutritional transparency mandates accelerate clean-label product development, creating competitive differentiation for manufacturers with reformulation capabilities.
- Hotel Breakfast Programs:Foodservice buyers in hospitality are expanding direct procurement of premium preserves, unwinding legacy retail-centric purchasing patterns.
- Pectin Gelation Advances:Modified pectin technologies enable reduced-sugar formulations without sacrificing texture, supporting clean-label positioning.
Market Restraints
- Sugar Price Volatility:Beet and cane sugar input costs fluctuate with climate-impacted harvests, squeezing formulation economics for mass-market producers.
- Glass Supply Concentration:Premium jar packaging depends on concentrated European glass manufacturing, exposing logistics costs to energy price shocks.
- Fruit Butter Substitution:Less-processed alternatives with visible fruit content capture health-conscious buyers, pressuring traditional jam volumes.
Strategic Opportunities
- India FSSAI Certification:Quality parameter alignment unlocks South Asian retail access for imported spreads in an underpenetrated market.
- Squeeze Bottle Formats:Convenience-oriented packaging gains traction in child-focused product lines and on-the-go consumption occasions.
- US IRA Bioenergy Provisions:Incentives for sustainable agriculture feedstock support organic fruit sourcing cost structures.
Industry Challenges
- Reformulation Expertise Gap:Clean-label compliance requires food scientists skilled in natural preservation and texture engineering, talent that remains scarce.
- Multi-Jurisdiction Compliance Timelines:Simultaneous FDA, EFSA, and BIS certification processes extend product launch cycles and strain regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fruit Spreads Market |
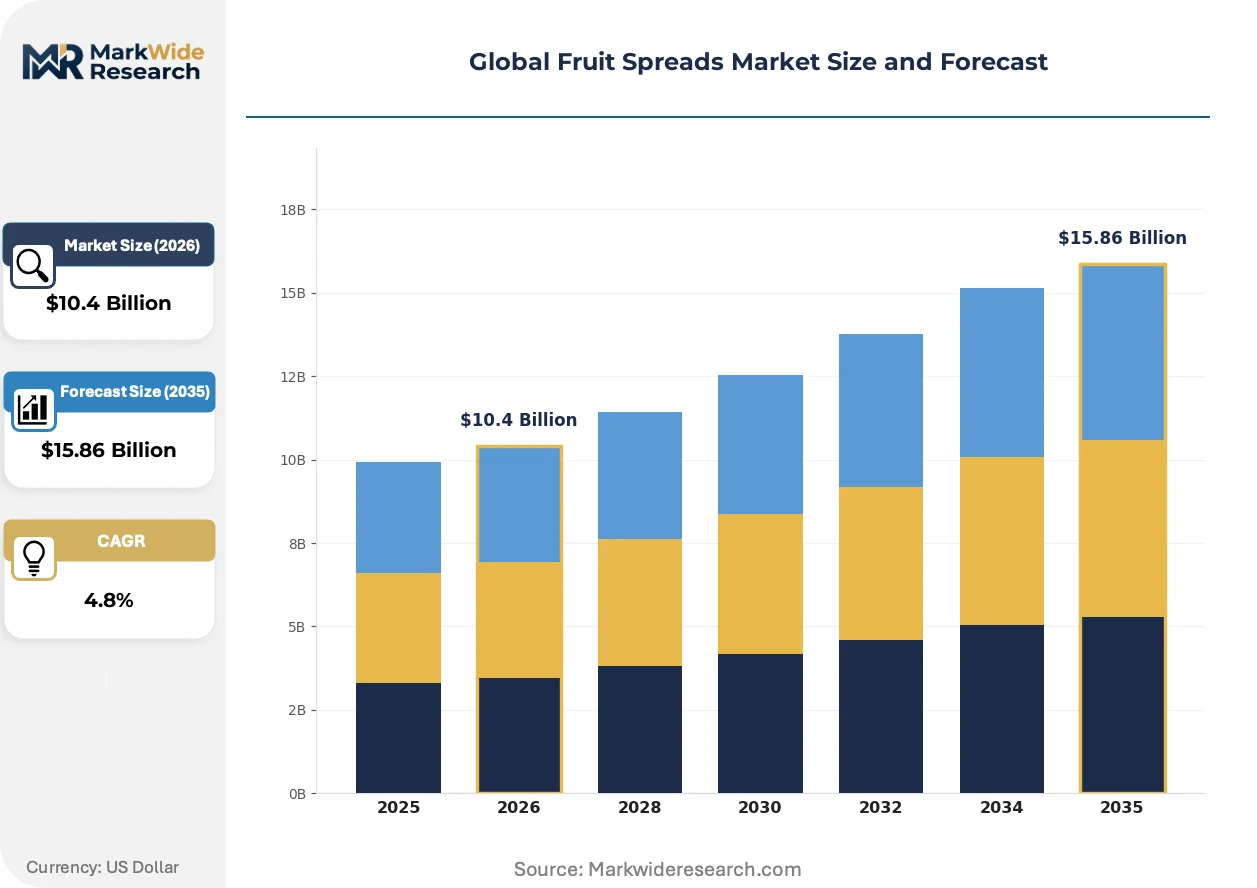
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jam, Jelly, Marmalade, Preserves, Fruit Butter, Conserve Fruit Base: Strawberry, Blueberry, Apricot, Mango, Raspberry, Peach Packaging Type: Glass Jar, Plastic Tub, Squeeze Bottle, Sachet, Aluminum Tube Distribution Channel: Supermarkets & Hypermarkets, Convenience Stores, Online Retail, Specialty Stores, Direct Sales |
| Companies Covered | Crofters Food, Hero Group, The J.M. Smucker Company, Orkla ASA, St. Dalfour, National Grape Co-operative Association, Polaner, Bonne Maman, Cascadian Farm Organic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fruit Spreads Market Shifts & Advancements
Formulation chemistry and packaging formats are diverging simultaneously as manufacturers respond to incompatible pressures: sugar reduction mandates clash with texture preservation needs, while premium glass positioning conflicts with logistics efficiency demands.
High-pressure processing technology is fragmenting traditional thermal pasteurization dominance in premium fruit spread manufacturing. Artisanal producers in Germany and specialty brands in North America are adopting cold-processing to preserve volatile flavor compounds and nutrient density. This technology is fragmenting the quality tier structure, enabling smaller producers to claim sensory superiority without scale economies.
EFSA's evolving guidance on novel food ingredients and additive approvals is compressing formulation flexibility for European manufacturers. The industrial consequence is accelerated investment in natural preservation research and pectin sourcing diversification. Reduced-sugar and organic segments face the steepest compliance burdens, with reformulation timelines extending 18-24 months for major product lines.
Direct procurement from manufacturers is displacing distributor intermediaries in foodservice channels. Hotel and cafe operators now negotiate volume contracts for premium preserves, bypassing traditional wholesale grocery networks. This pattern is most visible in German bakery pairings and North American boutique hospitality, where procurement teams prioritize origin transparency and batch traceability.
Global Fruit Spreads Market Segmentation
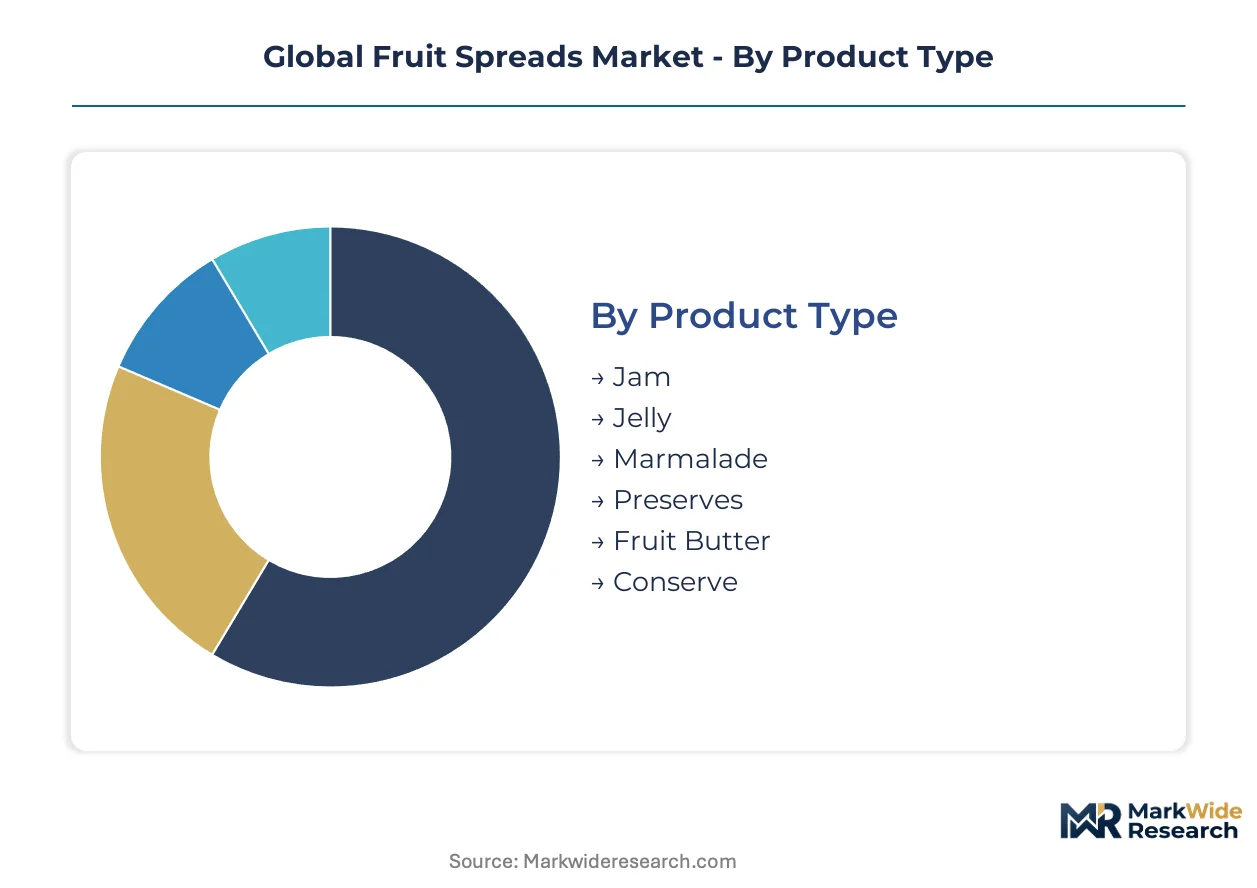
Fruit spread manufacturers navigate divergent technical requirements across product formats, each demanding distinct pectin chemistry, thermal processing parameters, and shelf-stability engineering. Segmentation clarity enables targeted formulation investments and channel-specific packaging decisions that align with end-use consumption contexts.
Product Type:
Jam formulations anchor domestic production volumes across North American and European manufacturing bases, while preserves and fruit butters command disproportionate export premiums in Asian retail channels.
- Jam:Pectin-gelled spreads with uniform fruit distribution and 65-68 degrees Brix soluble solids dominate breakfast service procurement in German hotels and North American cafes. Texture consistency requirements favor centralized manufacturing with standardized thermal processing.
- Jelly:Clarified fruit juice preparations without particulate matter serve baking applications and institutional foodservice where smooth spreadability is prioritized. Demand concentrates in US school nutrition programs and commercial bakery supply chains.
- Marmalade:Citrus-based formulations incorporating peel fragments retain niche positioning in British and Irish retail, with export volumes concentrated in Commonwealth markets.
- Preserves:Large fruit pieces suspended in syrup command premium placement in French and Italian specialty retail. Visible fruit content aligns with clean-label positioning requirements under EFSA guidance.
- Fruit Butter:Slow-cooked purees with reduced moisture content attract health-conscious buyers in California and Pacific Northwest farmers' markets, though thermal processing extends production cycles.
- Conserve:Nut-inclusive formulations with dried fruit additions occupy gifting segments in Middle Eastern retail, where texture complexity justifies elevated price positioning.
Jam holds the largest share; momentum sits with preserves as visible-fruit positioning gains traction in European clean-label retail.
Fruit Base:
Cost tier stratification separates commodity berries from tropical imports, with procurement geography dictating margin structure and formulation flexibility.
- Strawberry:The most widely cultivated berry base supports mass-market production across California, Poland, and Mexico, with harvest timing determining annual cost curves for processors.
- Blueberry:Wild lowbush varieties from Maine and Quebec command organic premiums, while cultivated highbush supply from Chile extends Southern Hemisphere sourcing windows for year-round production.
- Apricot:Mediterranean basin harvests from Turkey and Spain concentrate supply for European marmalade and conserve manufacturers, with irrigation-dependent yields exposed to climate volatility.
- Mango:Alphonso and Kent variety imports from India and Mexico sustain tropical spread production, with FSSAI certification requirements governing Indian supply access.
- Raspberry:Fragile perishability limits processing to proximity sourcing in Serbia, Poland, and Pacific Northwest growing regions, constraining scale economies.
- Peach:Clingstone varieties from Georgia and South Carolina anchor Southern US production, with freestone alternatives preferred in Mediterranean formulations for texture retention.
Strawberry dominates volume; steepest expansion trajectory belongs to blueberry as antioxidant positioning penetrates premium retail.
Packaging Type:
Application context drives format selection, with foodservice bulk requirements diverging sharply from retail convenience priorities.
- Glass Jar:Premium positioning in European and North American specialty retail depends on Italian and German glass manufacturing concentration, exposing logistics costs to natural gas price fluctuations.
- Plastic Tub:Polypropylene formats reduce freight weight for export shipments to Southeast Asian markets, though migration testing requirements under FDA and EFSA frameworks extend qualification timelines.
- Squeeze Bottle:Child-focused product lines in US and UK retail favor inverted dispensing formats, with silicone valve engineering preventing post-dispense dripping.
- Sachet:Single-serve portions dominate airline catering and hotel breakfast programs in Dubai and Singapore, where portion control reduces waste in high-volume service environments.
- Aluminum Tube:Collapsible formats retain niche presence in German outdoor recreation and military supply channels, where durability under temperature extremes outweighs cost premiums.
Glass jar retains the largest share; squeeze bottles are gaining share fastest in convenience-oriented North American retail.
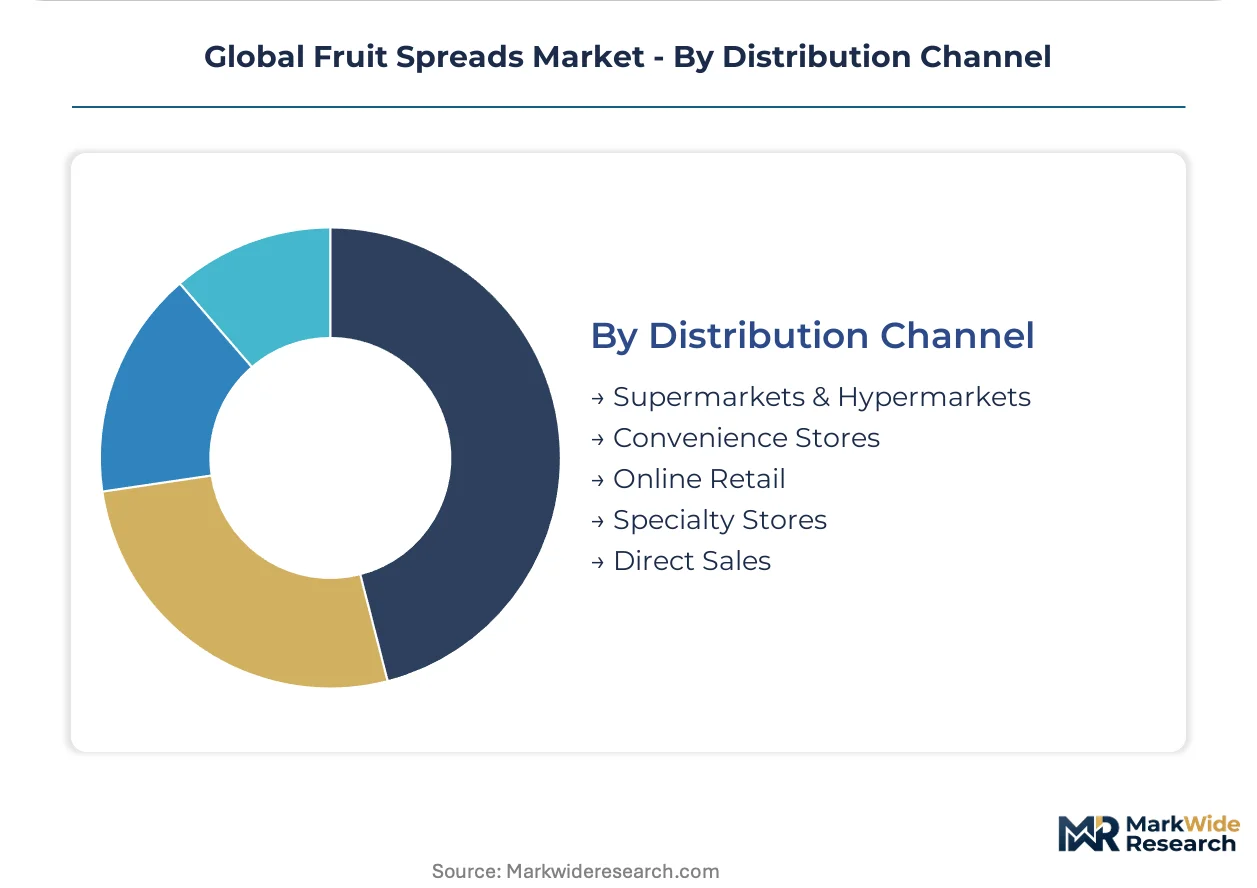
Distribution Channel:
Customer type fragmentation separates price-sensitive mass retail from traceability-focused direct procurement relationships.
- Supermarkets & Hypermarkets:Multi-brand shelf sets in Tesco, Carrefour, and Kroger networks drive volume throughput, with slotting fee structures favoring established manufacturers with promotional budgets.
- Convenience Stores:Grab-and-go positioning in 7-Eleven and Lawson formats emphasizes squeeze bottles and sachets for immediate consumption occasions in urban Japanese and South Korean markets.
- Online Retail:Amazon and Ocado fulfillment centers enable artisanal producer access without physical retail presence, though glass jar breakage rates elevate packaging engineering requirements.
- Specialty Stores:Biocoop in France and Whole Foods in the US command organic certification and origin transparency that excludes conventional supply chains.
- Direct Sales:Hotel and cafe operators in Berlin and Copenhagen now negotiate manufacturer contracts bypassing wholesale intermediaries, prioritizing batch traceability and custom formulation.
Supermarkets and hypermarkets hold the largest share; direct sales are expanding most quickly as foodservice procurement unwinds legacy distributor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass manufacturing clusters in Italy and Germany concentrate premium jar supply for European fruit spread producers. Energy price volatility at these sites ripples through packaging economics worldwide. Demand fragmentation now separates German artisanal bakery pairings from North American foodservice bulk procurement.
Germany
Artisanal fruit spread consumption in bakery pairings outpaces broader European averages, with Berlin and Munich hotels expanding direct manufacturer contracts. EFSA clean-label directives force reformulation investments across domestic producers. The Baden-Württemberg region hosts specialized organic pectin research facilities serving reduced-sugar formulation development.
United States
Hotel breakfast programs and cafe operators unwind legacy retail-centric purchasing patterns through direct premium preserve procurement. FDA standards of identity govern permissible fruit and sugar ratios in interstate commerce. California's Central Valley fruit processing corridor supplies strawberry and peach bases to North American jam manufacturers.
India
FSSAI quality parameters and BIS certification requirements shape market access for imported spreads in underpenetrated South Asian retail. Alphonso mango variety exports sustain tropical spread production for European and North American premium channels. Maharashtra's Ratnagiri district concentrates Alphonso cultivation governed by Geographical Indication protections.
France
Preserves with visible fruit pieces command premium placement in specialty retail across Paris and Lyon metropolitan markets. EU food labeling directives mandate nutritional transparency and origin declarations that shape export-oriented manufacturer decisions. The Provence-Alpes-Côte d'Azur region anchors apricot and citrus supply for marmalade production.
United Kingdom
Citrus-based marmalade formulations retain niche positioning in British retail with export volumes concentrated in Commonwealth markets. Single-use packaging restrictions under evolving environmental regulations pressure format decisions for domestic producers. London foodservice buyers prioritize squeeze bottle formats for convenience-oriented child-focused product lines.
Global Fruit Spreads Market Competitive Landscape
Concentration sits with diversified food conglomerates possessing institutional distribution networks and specialized organic formulators commanding premium retail placement. The competitive structure separates volume-driven foodservice suppliers from clean-label specialists. Three archetypes dominate: multinational packaged food corporations, European organic specialists, and regional artisanal producers. Dominant competitive moves include direct procurement relationship cultivation with hospitality buyers and pectin chemistry partnerships enabling reduced-sugar claims.
Within the multinational tier, The J.M. Smucker Company and Orkla ASA represent scale-driven supply chain architectures spanning multiple continents. Hero Group and St. Dalfour exemplify the European specialist archetype, with the former anchoring organic and reduced-sugar formulation capabilities and the latter occupying no-added-sugar positioning. Crofters Food sits within the North American organic specialist segment. These named entities illustrate how competitive positioning fragments across institutional scale, clean-label premiumization, and regional sourcing transparency rather than converging on a single dominant model.
| Leading Market Players |
|---|
| Crofters Food |
| Hero Group |
| The J.M. Smucker Company |
| Orkla ASA |
| St. Dalfour |
| National Grape Co-operative Association |
| Polaner |
| Bonne Maman |
| Cascadian Farm Organic |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between European glass manufacturers and premium fruit spread producers lock in jar supply access while anchoring price visibility against energy cost volatility. These arrangements concentrate purchasing power among scale buyers while exposing smaller artisanal producers to spot-market glass pricing.
Pricing Analysis
FDA standards of identity dictate the pricing tier structure for fruit spreads in US commerce, separating premium preserves meeting stricter fruit-to-sugar ratios from economy formulations. Three-tier pricing structure across premium organic, standard conventional, and private-label economy levels reflects certification grade and glass packaging investment. Cost compression in mass-market jam tiers is intensifying because beet sugar harvest volatility and concentrated glass manufacturing inflate input costs. Foodservice buyers in hotel breakfast programs demonstrate lowest price sensitivity, prioritizing batch traceability and origin transparency over per-unit cost.
Supply Chain Analysis
Italy and Germany anchor premium glass jar manufacturing for European and North American fruit spread producers. Pectin supply draws from citrus peel processors in Mexico and apple pomace facilities in Germany, while strawberry and blueberry concentrates source from California, Poland, and Chile. Single-source vulnerability in Italian glass manufacturing exposes logistics costs to natural gas price shocks. Distribution runs through institutional foodservice networks and retail grocery channels, with direct manufacturer contracts displacing wholesale intermediaries in hospitality procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward foodservice operators consolidating direct procurement relationships, fragmenting legacy distributor influence across European and North American hospitality channels.
For Market Incumbents: Fortify pectin chemistry partnerships and captive organic fruit sourcing to defend against clean-label specialists capturing premium placement. Hero Group's reduced-sugar formulation capabilities and St. Dalfour's no-added-sugar positioning threaten conventional jam volumes. Backward integration into Alphonso mango cultivation in Maharashtra or highbush blueberry operations in Quebec secures supply continuity. For New Entrants and Emerging Players: Differentiate on high-pressure processing technology and cold-processed texture claims to capture artisanal segments in German bakery pairings and Pacific Northwest farmers' markets. Underpenetrated South Asian retail offers white-space expansion through FSSAI certification alignment. Direct-to-hotel contracts in Copenhagen and Berlin bypass slotting fee barriers of Tesco and Carrefour shelf sets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among organic specialists with institutional foodservice contracts and reduced-sugar formulation pipelines. Long-term viability favors targets with pectin diversification capabilities and multi-jurisdiction compliance infrastructure. The signal to watch is sugar taxation proposal advancement in EU member states and US jurisdictions, which would accelerate reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | EFSA and FDA compliance mandates compress margins while opening premium positioning for compliant producers. |
| Direct Foodservice Contracting | Bypassing wholesale intermediaries captures Berlin and Copenhagen hotel procurement prioritizing traceability. |
| Pectin Chemistry Partnership | Modified pectin technologies enable reduced-sugar claims without sacrificing texture consistency. |
| Organic Fruit Sourcing Integration | US IRA bioenergy provisions support cost structures for sustainable agriculture feedstock procurement. |
| Squeeze Bottle Format Expansion | Silicone valve engineering captures child-focused product lines in convenience-oriented North American retail. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA standards filings, EFSA guidance documents, FSSAI certification databases, and EU food labeling directives. Primary interviews engaged fruit spread manufacturing executives, hotel procurement managers, organic certification specialists, and glass packaging procurement leads. Secondary validation drew from customs trade records, Nielsen retail audit data, and SEC filings of diversified food conglomerates. Bottom-up volume modeling triangulates against top-down category expenditure estimates.
Segmentation dimensions modeled include product type, fruit base, packaging format, and distribution channel across the analysis window. CAGRs derive from regression analysis against historical consumption patterns and elasticity estimates for sugar-reduced alternatives. Forecast inputs incorporate pectin technology adoption curves and foodservice direct procurement penetration rates.
Material uncertainties — sugar taxation legislation, single-use packaging restrictions, and climate-impacted fruit harvests — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and energy cost normalization in European glass manufacturing. Recalibration cycles align with material shifts in EFSA additive approvals and FDA standards revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Saudi Arabia Ready Meals Market
Packaged Foods
Coffee Pouch Market
Packaged Foods
Wet Food Pouch Market
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
Impulse Ice-Cream Market
Packaged Foods
Canned Fruits Market
Packaged Foods
Pastry Fillings Market
Packaged Foods
Man-Made Sausage Casing Market
Packaged Foods
Jams and Spreads Market
Packaged Foods
Europe Free from Food Market
Packaged Foods
Global Aseptic Packaging in Food Market
Packaged Foods
Europe Food Spread Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
Private Label Food and Beverage Market
Packaged Foods
North America Chewing Gum Market
Packaged Foods
Packaged Rice Noodles Market