
 Influenza Vaccine Market | 2026-2036
Influenza Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Influenza Vaccine Market Intelligence
The capital investment required for next-generation vaccine platforms is bifurcating the competitive landscape. Large, established players like Sanofi sustain market share through immense manufacturing scale and broad distribution networks. CSL Seqirus leverages its leadership in cell-based vaccine production to differentiate its portfolio. Meanwhile, technology-focused firms such as Moderna compete on the basis of novel mRNA platform innovations, requiring significant R&D expenditure.
An influenza vaccine is a biological preparation designed to stimulate active acquired immunity against specific influenza virus strains. These vaccines typically target viral hemagglutinin and neuraminidase proteins to prevent infection. While traditional inactivated vaccines remain the largest category by volume, recombinant and cell-based vaccine types are showing significant uptake. The elderly target population constitutes a primary revenue source due to higher recommended vaccination rates and reimbursement policies.
Market access is governed by stringent regulatory approvals from bodies like the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA). The World Health Organization's GISRS network dictates annual strain selection, which directly impacts all manufacturers' production cycles. Navigating the compressed timeline between annual strain recommendations and the delivery of finished doses remains a central operational challenge for all vaccine producers.
Market Dynamics
The central dynamic shaping the influenza vaccine market is the operational tension between the WHO's annual strain selection and the compressed manufacturing timeline. This pressure is accelerating the industrial shift from slower egg-based methods to faster cell-based and recombinant platforms.
Growth Catalysts
- Targeted Public Health Programs:National immunization initiatives in countries like the United States and the United Kingdom, which fund and promote annual vaccination for elderly and at-risk populations, directly stimulate consistent demand.
- Advanced Manufacturing Platforms:The adoption of cell-based production technology offers a key advantage by eliminating reliance on egg supply and reducing the manufacturing timeline, enabling a faster response to strain recommendations.
- Expanded Distribution Channels:The increasing role of retail pharmacies as primary vaccination sites, particularly in North America, improves patient access and convenience, thereby broadening the vaccinated population base beyond traditional clinical settings.
Market Restraints
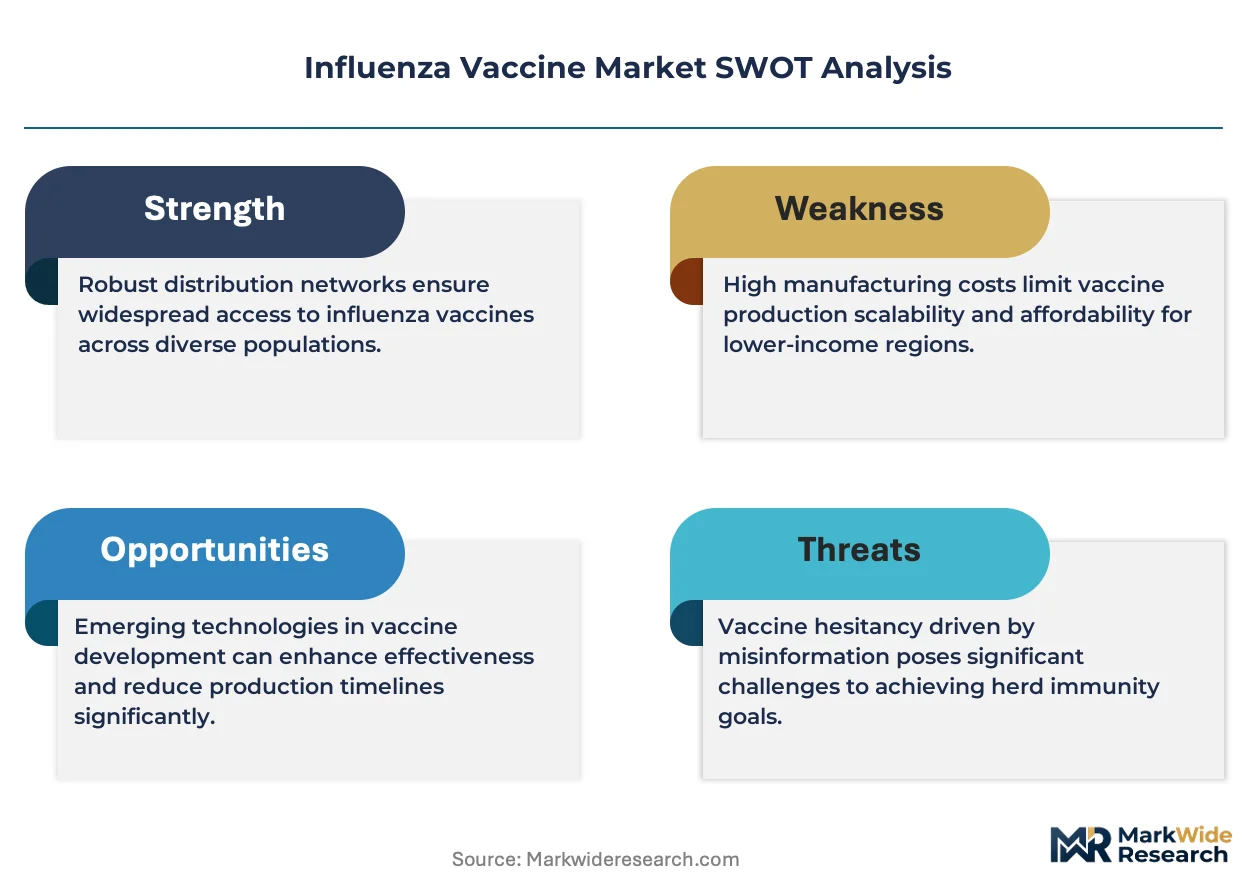
- High Capital Investment:The significant upfront capital required to construct and validate cGMP-compliant facilities for cell-based or recombinant vaccine production acts as a substantial barrier to entry for new competitors.
- Variable Vaccine Efficacy:Antigenic drift in circulating influenza viruses can lead to a mismatch with vaccine strains, resulting in lower-than-expected effectiveness in some seasons and potentially impacting public perception and uptake.
- Inflexible Production Cycles:The rigid annual timeline dictated by the WHO's strain selection process leaves manufacturers with minimal flexibility to adjust production volumes or formulations once manufacturing has commenced.
Strategic Opportunities
- Universal Vaccine Development:Pursuit of a universal influenza vaccine that provides broad, long-lasting protection against multiple strains represents a transformative opportunity, potentially eliminating the need for annual reformulation and vaccination.
- Combination Vaccine Formulations:Developing and marketing combination vaccines that protect against influenza, COVID-19, and RSV in a single dose offers a path to improve patient compliance and simplify immunization schedules.
- Geographic Market Expansion:There is significant opportunity to increase vaccine penetration in large, middle-income countries across Latin America and Southeast Asia through partnerships with national health authorities and localized distribution strategies.
Industry Challenges
- Global Cold Chain Logistics:Maintaining the integrity of the vaccine cold chain from manufacturing plant to final administration remains a persistent operational challenge, especially in regions with underdeveloped infrastructure.
- Annual Demand Forecasting:Manufacturers face the annual challenge of accurately forecasting demand for differentiated products like quadrivalent versus trivalent vaccines, risking either stockouts or costly write-offs of unused inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Influenza Vaccine Market |
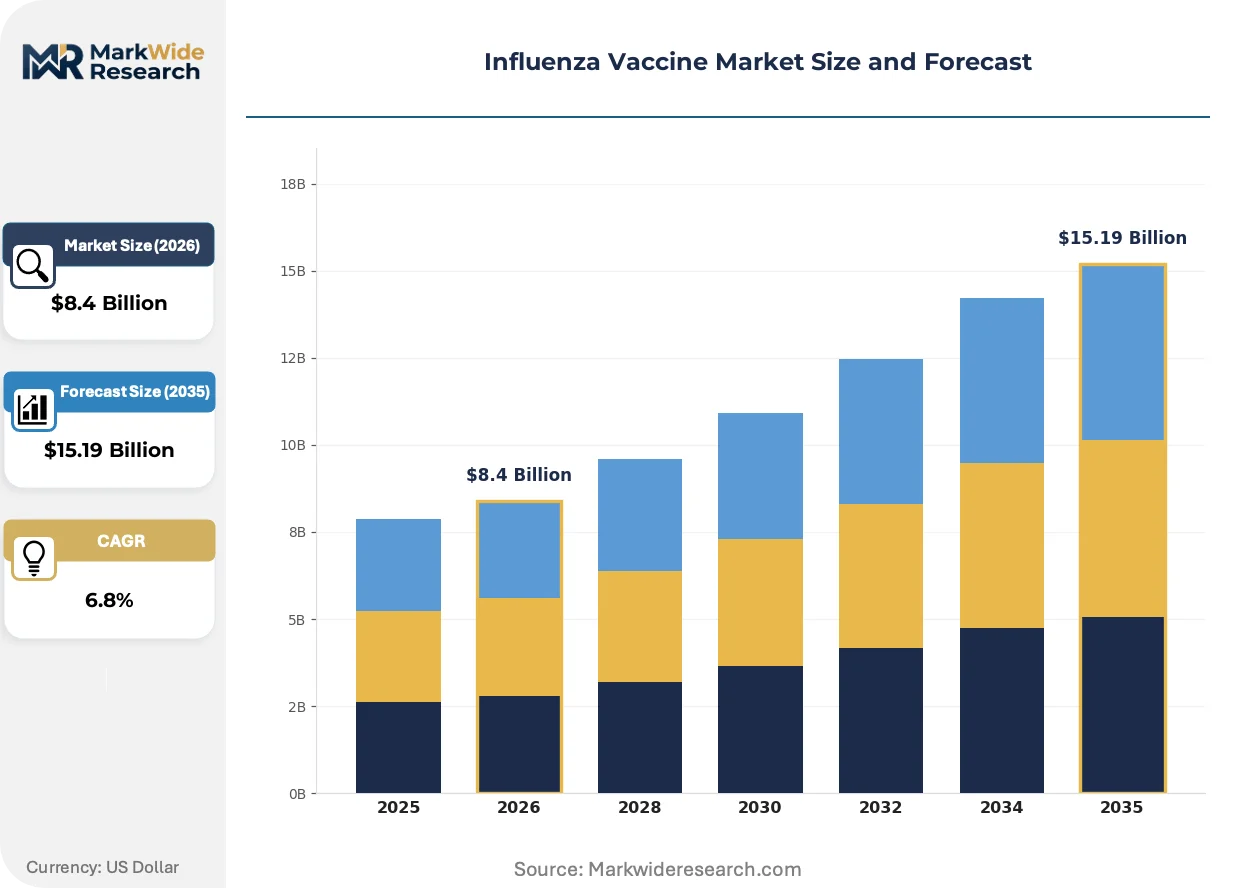
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Inactivated, Live Attenuated, Recombinant, Cell-Based Target Population: Children, Adults, Elderly, Pregnant Women, Immunocompromised Distribution Channel: Pharmacies, Hospitals, Clinics, Community Health Centers, Occupational Health Services Application Setting: Public Health Programs, Travel Immunization, Corporate Wellness, Seasonal Campaigns |
| Companies Covered | Sanofi, GlaxoSmithKline plc, CSL Seqirus, AstraZeneca, Moderna, Seqirus, BIKEN Co., Ltd., Pfizer, Novavax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Influenza Vaccine Market Strategic Shifts & Innovations
Platform technologies are fundamentally altering the influenza vaccine landscape. The industry is moving from a purely reactive, seasonal manufacturing model toward a more proactive development posture capable of rapid response to both seasonal and pandemic threats.
mRNA Vaccine Platforms
Messenger RNA technology provides a synthetic, rapid-response platform for designing vaccines that encode for specific viral antigens. Biotech innovators and established pharmaceutical firms are advancing mRNA candidates through clinical trials for seasonal influenza. The sheer speed of this development modality is fragmenting the traditional, slow-moving production cycle historically dominated by egg-based manufacturing.
Accelerated Regulatory Pathways
Regulatory bodies like the European Medicines Agency (EMA) are implementing fast-track assessment programs for vaccines that address significant public health needs. This framework incentivizes manufacturers to invest in adaptable platform technologies that can be quickly modified for new pandemic threats. Consequently, developers targeting the EU market are aligning their clinical and manufacturing strategies with these expedited review criteria.
Channel Decentralization
A notable demand-side shift involves the decentralization of vaccine administration away from traditional physicians' offices. Retail pharmacies and employer-sponsored workplace clinics have emerged as major vaccination hubs for adults. This trend is most visible in the United States, where pharmacy chains leverage their extensive retail footprints to capture a substantial portion of the seasonal immunization market.
Influenza Vaccine Market Segmentation
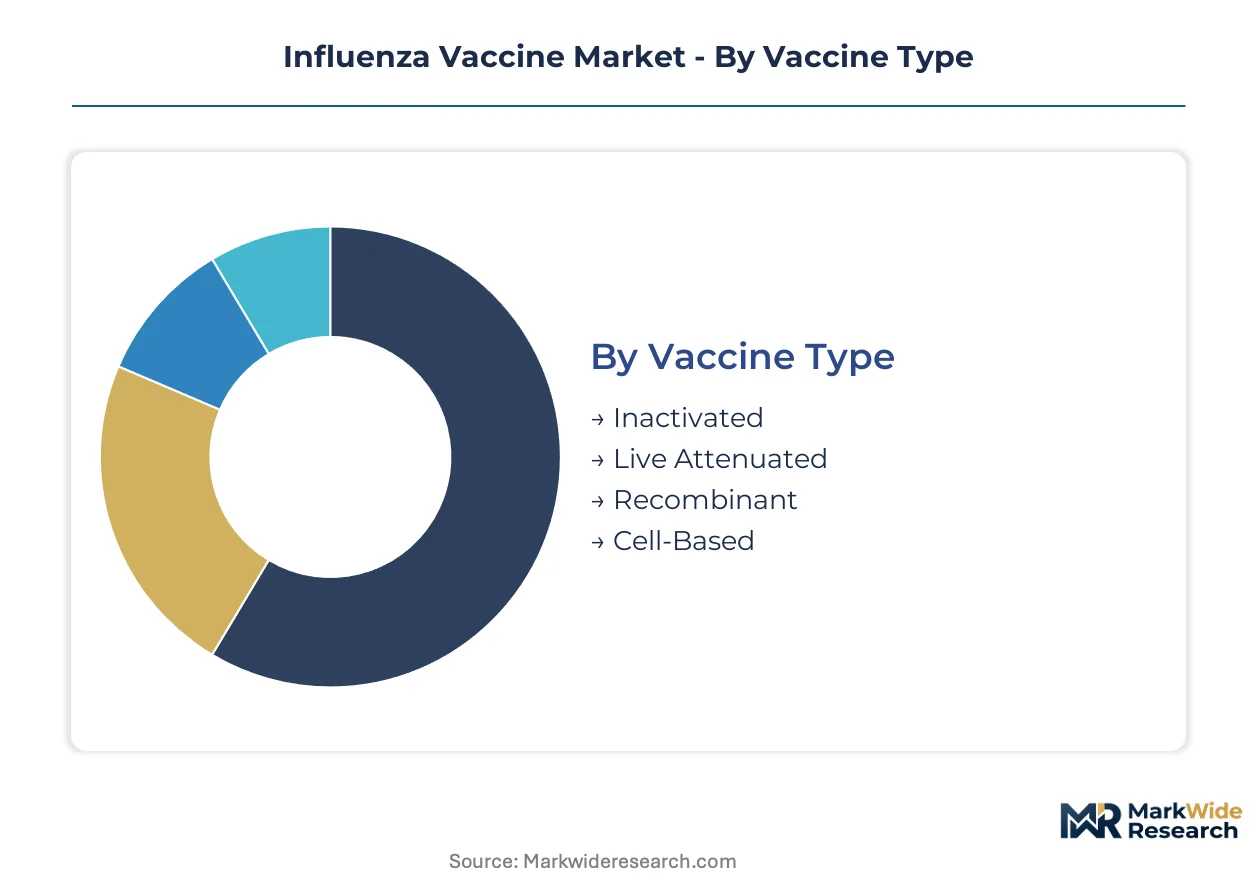
The influenza vaccine market is segmented to understand the varied product offerings, target demographics, and operational avenues that define its structure. This detailed categorization helps in identifying specific demand drivers and strategic intervention points across the vaccine value chain.
Vaccine Type:
Different vaccine types flow through distinct distribution channels, influencing their market penetration and reach. For instance, traditional inactivated vaccines are widely available, while newer technologies may have more specialized supply chains initially.
- Inactivated:These vaccines contain killed influenza viruses or components, stimulating an immune response without causing illness. They constitute the largest category by volume, widely distributed through established public health and retail pharmacy networks due to their proven safety profile and manufacturing scale.
- Cell-Based:Produced using cell culture rather than chicken eggs, these vaccines offer a faster manufacturing timeline and reduced reliance on egg supply. Demand is concentrating in high-income countries like the United States and European nations, driven by public health initiatives seeking rapid response capabilities.
- Live Attenuated:These vaccines use weakened live viruses, typically administered intranasally, and are primarily targeted at specific age groups in clinical settings.
- Recombinant:Developed using genetic engineering to produce viral proteins, these platforms offer high purity and do not use egg products.
Inactivated vaccines dominate the installed base. Cell-based vaccine technologies are where expansion concentrates.
Target Population:
The application of influenza vaccines varies significantly based on the target population, influencing product formulation and public health recommendations.
- Elderly:This demographic, typically aged 65 and above, represents a primary revenue source due to higher recommended vaccination rates and robust reimbursement policies. Demand is consistently high in developed economies like Japan and Germany, driven by targeted public health campaigns.
- Adults:Encompassing individuals aged 18-64, this broad segment is crucial for achieving herd immunity and reducing disease burden. Uptake is significant in the United States and the United Kingdom, facilitated by widespread pharmacy-led vaccination programs.
- Children:Vaccination programs for children aim to protect a vulnerable group and limit community transmission, often integrated into routine immunization schedules.
- Pregnant Women:Vaccinating pregnant women protects both the mother and the newborn, with specific recommendations from health authorities globally.
- Immunocompromised:This group requires specialized vaccine considerations due to weakened immune systems, often necessitating higher-dose or adjuvanted formulations.
The elderly population consistently drives revenue, while specific programs target immunocompromised individuals.
Distribution Channel:
Patient convenience and access are key factors determining the effectiveness of various distribution channels in delivering influenza vaccines.
- Pharmacies:Retail pharmacies serve as a critical and expanding channel, particularly in North America, offering accessible vaccination services. This channel significantly improves patient access and convenience, broadening the vaccinated population base beyond traditional clinical settings.
- Hospitals:Hospitals remain a foundational channel for inpatient and outpatient vaccination, especially for high-risk patients and healthcare workers. This setting provides comprehensive care, often integrating vaccination into broader patient management protocols.
- Clinics:Physician offices and general practice clinics are traditional sites for vaccine administration, offering personalized medical consultation.
- Community Health Centers:These centers play a vital role in reaching underserved populations and ensuring equitable access to immunization services.
- Occupational Health Services:Workplace clinics and employer-sponsored programs facilitate vaccination for employees, promoting public health in professional environments.
Retail pharmacies are rapidly expanding their reach, complementing the established infrastructure of hospitals.
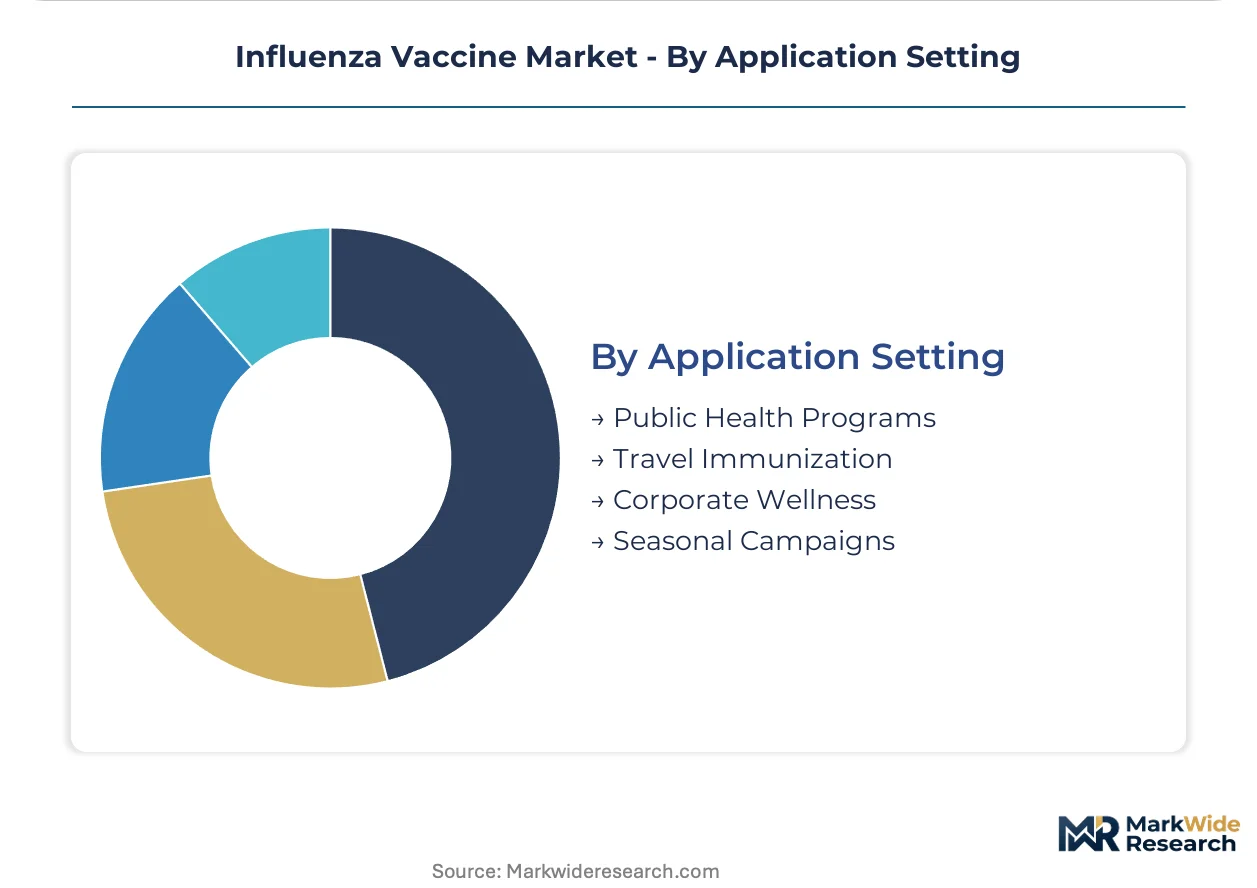
Application Setting:
The volume of vaccine demand is heavily influenced by the specific application setting, ranging from widespread public health efforts to niche travel immunization.
- Seasonal Campaigns:Annual seasonal vaccination campaigns form the backbone of influenza prevention strategies, driving the largest volume of vaccine demand globally. These campaigns are foundational in countries with well-established public health infrastructures, such as Canada and Australia.
- Public Health Programs:Government-funded and organized initiatives target specific at-risk populations, ensuring broad vaccine coverage and disease control. These programs provide consistent demand and are critical in nations like the United Kingdom and France for managing population health.
- Travel Immunization:Travelers often seek influenza vaccination as part of pre-travel health advice, particularly for destinations with different seasonal patterns.
- Corporate Wellness:Employer-sponsored wellness programs offer on-site vaccination, enhancing employee health and reducing absenteeism.
Annual seasonal campaigns are foundational, with public health initiatives ensuring broad access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The influenza vaccine market exhibits varied demand elasticity across regions, with highly developed economies demonstrating lower price sensitivity due to established public health funding mechanisms. Conversely, emerging markets often prioritize cost-effectiveness while balancing the need for broad population coverage. This regional divergence influences product uptake and distribution strategies for manufacturers.
United States
The United States drives substantial influenza vaccine demand through expansive seasonal vaccination campaigns and pharmacy-led distribution. The US Food and Drug Administration (FDA) stringently regulates vaccine approvals, ensuring product safety and efficacy. Major pharmaceutical hubs like Boston and Research Triangle Park actively innovate in advanced vaccine platforms.
Germany
Germany's elderly population constitutes a primary revenue source, supported by robust reimbursement policies and high recommended vaccination rates. The European Medicines Agency (EMA) oversees market access for vaccines across the European Union, including Germany. Pharmaceutical companies in cities such as Frankfurt and Berlin focus on developing and distributing specialized formulations for vulnerable groups.
Japan
Japanese demand for influenza vaccines is consistently high within its significant elderly demographic, benefiting from targeted public health campaigns. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures rigorous regulatory oversight for all biological preparations entering the market. Research centers in Tokyo and Osaka contribute to vaccine development, often exploring advanced manufacturing techniques.
United Kingdom
National immunization initiatives in the United Kingdom significantly stimulate consistent vaccine demand, especially for elderly and at-risk populations. The UK's Medicines and Healthcare products Regulatory Agency (MHRA) approves vaccines, ensuring they meet public health standards. Pharmaceutical clusters around London and Cambridge engage in R&D for novel vaccine technologies.
Brazil
Brazil presents a strategic opportunity for increased vaccine penetration, particularly within its large population base. The Agência Nacional de Vigilância Sanitária (ANVISA) regulates vaccine distribution and use across the country. Manufacturing facilities in states like São Paulo are expanding capacity to meet national immunization program requirements.
Influenza Vaccine Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the influenza vaccine market, contributing to a bifurcated competitive landscape. This market structure features large, established pharmaceutical companies alongside agile, technology-focused biotech firms. Dominant strategic archetypes include scale manufacturers with broad distribution networks, specialized platform innovators focusing on next-generation technologies, and regional distribution specialists. Strategic partnerships to expand market access and significant capacity expansion for advanced manufacturing platforms are common competitive moves.
Within the established scale manufacturing tier, Sanofi, a global pharmaceutical entity, exemplifies market presence through immense manufacturing scale and broad distribution networks. CSL Seqirus, leveraging its leadership in cell-based vaccine production, occupies a specialized position by differentiating its portfolio with advanced technologies. Technology-focused firms such as Moderna represent the novel mRNA platform innovators, driving significant R&D expenditure to develop future vaccine solutions that challenge traditional production cycles. These companies collectively illustrate the diverse approaches to securing market share and advancing vaccine science.
| Leading Market Players |
|---|
| Sanofi |
| GlaxoSmithKline plc |
| CSL Seqirus |
| AstraZeneca |
| Moderna |
| Seqirus |
| BIKEN Co., Ltd. |
| Pfizer |
| Novavax |
| Others |
Cost & Logistics Intelligence
Cell-based production's displacement of traditional egg-based manufacturing reshapes influenza vaccine supply geography and pricing economics. This shift accelerates manufacturing timelines and reduces reliance on volatile egg supplies, impacting global vaccine availability and cost structures.
Pricing Analysis
Robust reimbursement policies, particularly for elderly populations, drive the sustained value of influenza vaccines, underpinning a market that operates on a contract-based long-term offtake model for public health programs. Price differentiation stems from manufacturing platform advancements and specific regulatory approval status. Cost compression in cell-based vaccine production is intensifying due to increased competition and scaling efficiencies. Middle-income countries like Brazil exhibit higher price sensitivity compared to developed economies such as the United States and Germany.
Supply Chain Analysis
Global cold chain logistics costs, particularly for maintaining temperature integrity across diverse trade lanes, present a significant inbound challenge for influenza vaccine supply. Manufacturing concentrates in countries such as the United States, Germany, and Japan, relying on critical inputs like cell culture media and specific viral strains dictated by the WHO. Annual demand forecasting accuracy and global cold chain integrity represent structural risks. Downstream distribution runs primarily through retail pharmacies and established hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The influenza vaccine market presents a substitution defense challenge, as incumbents must navigate the disruptive potential of novel mRNA vaccine platforms. These platforms offer rapid development and production, threatening traditional manufacturing models.
For Market Incumbents: Secure leadership in advanced manufacturing platforms through strategic capital investments in cell-based and recombinant technologies. Expand existing distribution networks, particularly leveraging retail pharmacy partnerships in North America, to counter emerging competitive pressures. This strategy helps maintain market share against agile, technology-focused firms like Moderna. Invest in R&D for combination vaccines to offer broader protection and simplify immunization schedules.
For New Entrants and Emerging Players: Lead with novel mRNA platform innovations to target the accelerated regulatory pathways offered by bodies like the European Medicines Agency. Focus on developing universal influenza vaccine candidates, representing a significant white-space opportunity for long-term, broad-spectrum protection. Penetrate underserved middle-income countries in Latin America and Southeast Asia through localized distribution strategies. This approach capitalizes on technological agility and unmet medical needs.
For Investors and Strategic Acquirers: Accelerated regulatory pathways in the EU for public health needs reshape the acquisition landscape, favoring firms with adaptable platform technologies. Long-term viability hinges on acquiring companies specializing in mRNA or universal vaccine development, offering sustained protection beyond annual seasonal campaigns. Target technology-focused biotech firms with strong R&D pipelines and proven rapid response capabilities. Watch for early-stage clinical trial success in universal vaccine candidates as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Cell-Based Manufacturing Capacity | This move reduces reliance on egg supply, accelerating production timelines for major players like CSL Seqirus. |
| Develop Combination Vaccine Formulations | Combination vaccines against influenza, COVID-19, and RSV improve patient compliance and simplify immunization schedules. |
| Expand Retail Pharmacy Partnerships | This strategy enhances patient access in North America, broadening the vaccinated population base beyond clinical settings. |
| Pursue Universal Vaccine R&D | Universal vaccines offer broad, long-lasting protection, potentially eliminating the need for annual reformulation and vaccination. |
| Target Latin America and Southeast Asia | Geographic expansion into middle-income countries increases vaccine penetration and addresses unmet public health needs. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and rigorous secondary validation. Primary insights were gathered from drug development executives, regulatory affairs leads, and hospital procurement managers. Secondary data sources included FDA filings, EMA submissions, and World Health Organization reports. This approach facilitated a comprehensive bottom-up and top-down triangulation of market dynamics.
Market projections were developed using a robust analytical framework across the analysis window. Segmentation dimensions modeled included vaccine type, target population, distribution channel, and application setting. Compound annual growth rates were derived through a synthesis of historical trends and projected technological advancements. Key forecast inputs included annual WHO strain recommendations and national immunization program funding levels.
Forecasts assume regulatory continuity in US FDA and European EMA regimes; material policy shifts would require re-modeling. The analysis reflects current public health priorities and manufacturing capabilities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Insulin Market
Biopharmaceuticals
Oral Chemotherapy Market
Biopharmaceuticals
Next Generation Antibody Therapeutics Market
Biopharmaceuticals
Purified Protein Derivative Market
Biopharmaceuticals
North America Diabetes Drugs Market
Biopharmaceuticals
Conjugated Estrogen Market
Biopharmaceuticals
Tuberculosis Drugs Market
Biopharmaceuticals
Paediatric Oncology Therapeutics Market
Biopharmaceuticals
Europe Monoclonal Antibodies Market
Biopharmaceuticals
Latin America Human Insulin Drugs Market
Biopharmaceuticals
Global Kinase Inhibitors Market
Biopharmaceuticals
Global Swine Fever Vaccine Market
Biopharmaceuticals
North America HIV Drugs Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
Ovarian Cancer Drugs Market
Biopharmaceuticals
North America Monoclonal Antibody Market