
 Conjugated Estrogen Market | 2026-2036
Conjugated Estrogen Market Size, Share, and Industry Trends Forecast 2026-2036
Conjugated Estrogen Market Analytics
North American pharmaceutical manufacturing capacity is reconfiguring around specialty hormone production as domestic supply chain priorities shift. Pfizer Inc. leverages its established biologics infrastructure to maintain formulation leadership in conjugated estrogen tablets. Teva Pharmaceutical Industries Ltd. competes aggressively through its generic portfolio, while AbbVie Inc. anchors its position via integrated endocrinology pipelines and specialty distribution networks.
Conjugated estrogens comprise a blend of water-soluble estrogen sulfates derived primarily from equine urine sources, typically containing sodium estrone sulfate and sodium equilin sulfate as principal active constituents in standardized potency ratios. These compounds function as estrogen receptor agonists to restore systemic hormonal balance in patients with ovarian insufficiency or menopausal transition. Tablets dominate current revenue flows due to decades of clinical familiarity and pharmacy reimbursement precedent, though transdermal patches represent the fastest-expanding delivery category as clinicians seek to minimize hepatic first-pass metabolism and thromboembolic risk profiles. Hormone replacement therapy retains the largest therapy area footprint, while osteoporosis prevention applications are gaining traction amid expanded screening protocols in ambulatory settings.
FDA oversight of hormone therapy risk communication and EMA pharmacovigilance requirements for thrombotic event reporting collectively elevate compliance costs and documentation burdens for manufacturers seeking multi-regional market access. The Drug Enforcement Administration and national health technology assessment bodies in France and Germany impose additional layer controls on estrogen-containing products through scheduling classifications and value-based pricing reviews. Stakeholders must monitor evolving regulatory posturing on compounded bioidentical alternatives and their potential to disrupt conventional conjugated estrogen market positioning.
Market Dynamics
Domestic manufacturing repatriation for hormone APIs is compressing supplier margins while elevating batch traceability requirements across North American pharmaceutical networks.
Growth Catalysts
- Homecare Administration Expansion:Ambulatory menopausal symptom management protocols are extending prescription durations outside institutional settings. The FDA's updated hormone therapy labeling guidance supports extended-use authorization pathways.
- Osteoporosis Screening Mandates:Expanded bone density assessment protocols in United States ambulatory clinics are broadening preventive estrogen prescriptions. Medicare reimbursement codes now cover dual-energy x-ray absorptiometry as a preventive service.
- EMA Pharmacovigilance Harmonization:Standardized thrombotic event reporting frameworks across European member states are streamlining multi-national product registrations. This regulatory convergence reduces documentation duplication for manufacturers.
Market Restraints
- Equine Urine Supply Concentration:Raw material sourcing depends on a limited number of specialized equine husbandry operations in Canada and the United States. Climate volatility and animal welfare compliance costs constrain herd expansion.
- FDA Black Box Warning Persistence:Mandatory cardiovascular and thromboembolic risk disclosures on all conjugated estrogen packaging limit prescriber comfort with first-line therapy positioning. This labeling requirement dates to the Women's Health Initiative findings.
- Compounded Bioidentical Substitution:Pharmacy-compounded estradiol formulations from 503A and 503B facilities compete on customization claims. These alternatives bypass traditional new drug application pathways and capture price-sensitive patients.
Strategic Opportunities
- Transdermal Patch Formulation Gaps:United States clinicians increasingly prefer transdermal delivery to circumvent hepatic first-pass metabolism. Manufacturers with patch manufacturing capabilities capture this preference shift.
- Specialty Distribution Channel Expansion:Integrated endocrinology clinics and women's health networks offer direct-to-practice distribution models. These channels reduce pharmacy benefit manager rebate compression.
- IRA Drug Pricing Negotiation Exclusions:Small-molecule hormone therapies currently fall outside Medicare price negotiation timelines. This temporary exclusion preserves pricing autonomy for established products.
Industry Challenges
- Complex Sulfate Chemistry Workforce Scarcity:Specialized organic chemists capable of equine estrogen sulfate characterization and potency standardization remain concentrated at legacy manufacturers. Academic programs have reduced natural product chemistry training.
- Legacy ERP Integration with Track-and-Trace Systems:Batch-level serialization requirements under the Drug Supply Chain Security Act demand substantial middleware investment. Smaller generic manufacturers face disproportionate compliance burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conjugated Estrogen Market |
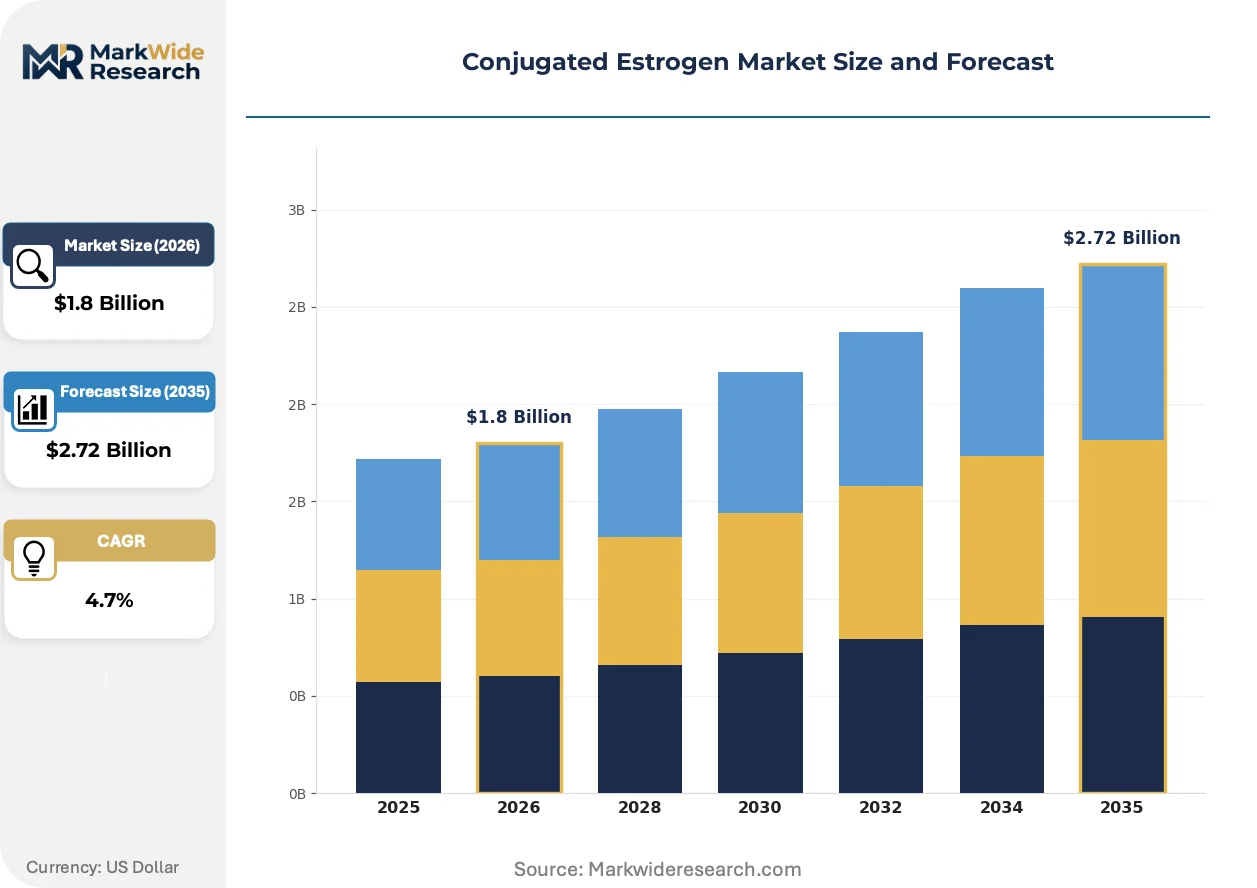
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Creams, Injections, Transdermal Patches Therapy Area: Hormone Replacement Therapy, Menopausal Symptoms, Osteoporosis Prevention, Abnormal Uterine Bleeding Delivery Mode: Oral, Topical, Injectable, Transdermal End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., AbbVie Inc., Bayer AG, Novartis AG, Eli Lilly and Company, Novo Nordisk A/S, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conjugated Estrogen Market Evolving Landscape
Digital manufacturing controls and patient-administered delivery systems are compressing the traditional pharmaceutical value chain from synthesis to bedside administration.
Process analytical technology is digitizing conjugated estrogen manufacturing through real-time sulfate potency monitoring and automated batch release protocols. Pfizer and Teva manufacturing sites in the United States are deploying in-line near-infrared spectroscopy to replace offline quality control testing. This digitizing infrastructure reduces cycle times from fermentation to finished tablet by compressing quarantine periods and enabling continuous processing economics.
EMA's updated good manufacturing practice Annex 1 requirements for sterile medicinal products are extending containment expectations to hormone API handling. Manufacturers must now demonstrate closed-system processing for all potent estrogen operations. United States facilities supplying European markets are retrofitting isolator technology and single-use containment systems to maintain EMA inspection readiness.
Patient self-administration preferences are fragmenting traditional pharmacy dispensing relationships. United States health systems are deploying direct-to-patient subscription models for transdermal patch therapies. This channel disintermediation concentrates fulfillment volume with specialty pharmacies possessing cold-chain and compliance packaging capabilities, compressing retail pharmacy margins on maintenance prescriptions.
Conjugated Estrogen Market Segmentation
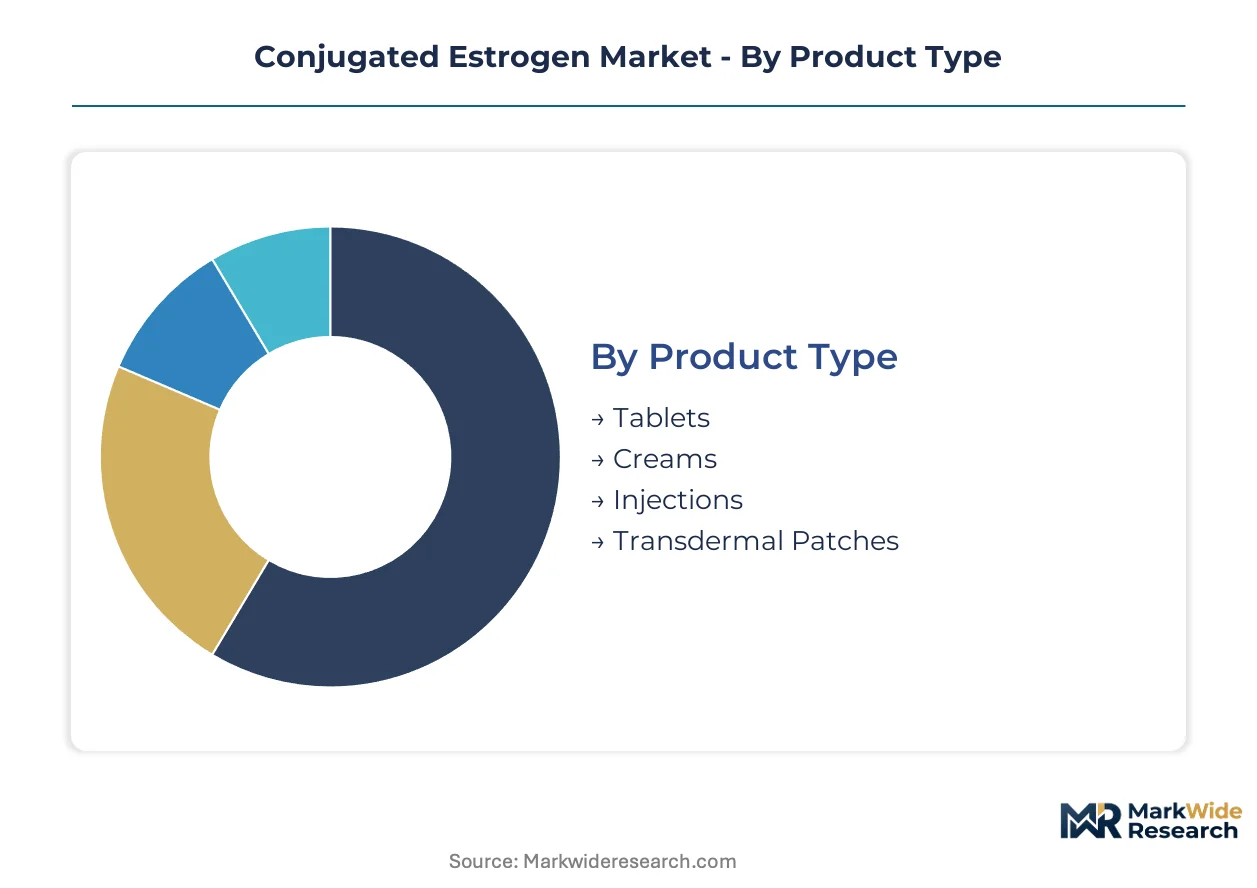
Conjugated estrogen formulations span distinct administration pathways and clinical indications, each carrying unique reimbursement codes and patient compliance profiles. Segmentation reveals where formulation innovation outpaces legacy prescribing habits.
Product Type:
Use-case spectrum ranges from acute symptom relief to chronic maintenance, with delivery technology determining prescriber confidence and patient adherence.
- Tablets:Compressed sodium estrone sulfate and sodium equilin sulfate formulations dominate pharmacy dispensing volumes due to decades of clinical familiarity. United States Medicare Part D reimbursement precedent reinforces tablet primacy for maintenance hormone replacement, though hepatic first-pass metabolism limits dosing flexibility in high-risk cardiovascular patients.
- Transdermal Patches:Matrix-based or reservoir systems deliver estrogens through intact skin, bypassing hepatic metabolism entirely. United States ambulatory clinics increasingly prescribe patches for patients with thromboembolic risk factors, driving fastest-expanding category adoption among delivery modalities.
- Creams:Topical emulsions concentrate dosing for localized genitourinary symptom management. Compounding pharmacies capture significant volume through customized potency adjustments.
- Injections:Intramuscular or subcutaneous depot formulations serve patients with severe malabsorption or non-compliance with daily regimens. Hospital outpatient departments administer the majority of injectable volumes.
Established volume favors tablets; emerging adoption favors transdermal patches.
Therapy Area:
Clinical application breadth spans preventive, curative, and palliative endpoints, with screening protocol expansion reshaping addressable patient pools.
- Hormone Replacement Therapy:Systemic estrogen restoration for ovarian insufficiency or surgical menopause constitutes the foundational indication. United States prescribing patterns concentrate in integrated women's health networks with dedicated menopause specialists.
- Osteoporosis Prevention:Bone mineral density preservation in postmenopausal women leverages estrogen's anti-resorptive effects. Medicare reimbursement for dual-energy x-ray absorptiometry screening expands preventive prescribing in ambulatory settings.
- Menopausal Symptoms:Vasomotor symptom management represents the most visible patient-driven demand category. Direct-to-consumer advertising influences symptom reporting and treatment-seeking behavior.
- Abnormal Uterine Bleeding:Cycle regulation through endometrial stabilization serves perimenopausal patients before definitive surgical intervention. Gynecology practices manage complex cases requiring co-administered progestin protocols.
Preventive applications gain share fastest; symptom management retains the largest patient base.
Delivery Mode:
Route of administration determines pharmacokinetic profiles, safety monitoring requirements, and patient self-efficacy in long-term therapy.
- Oral:Gastrointestinal absorption with extensive hepatic first-pass metabolism produces estrone-dominant serum profiles. Convenience drives patient preference despite metabolic complexity.
- Transdermal:Percutaneous absorption maintains physiological estradiol-to-estrone ratios and avoids liver enzyme induction. Patch manufacturing capabilities concentrate at specialty contract development organizations.
- Topical:Localized application limits systemic exposure for genitourinary indications. Cream and gel formulations require patient education on application technique.
- Injectable:Depot formulations ensure compliance in institutional settings or cognitively impaired populations. Cold-chain requirements constrain distribution to specialty pharmacies.
Self-administration channels favor transdermal and oral routes; institutional control favors injectable delivery.
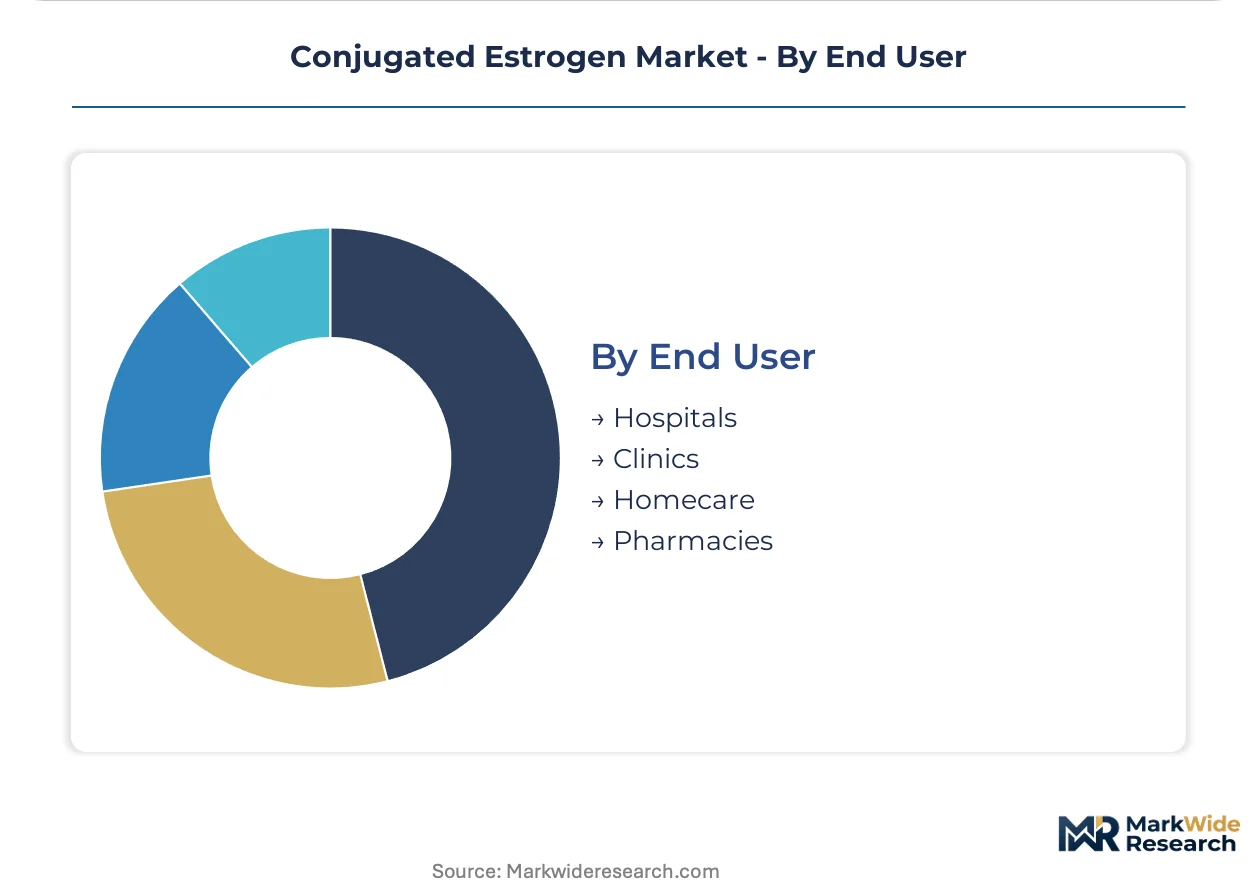
End User:
Care setting determines prescription authority, reimbursement mechanics, and patient education responsibilities.
- Homecare:Patient-directed administration outside institutional settings extends prescription durations and reduces per-episode costs. United States telehealth expansion enables remote monitoring of therapy response.
- Hospitals:Acute care facilities manage surgical menopause, trauma-related ovarian failure, and complex bleeding emergencies. Formulary committees restrict product selection to established generic equivalents.
- Clinics:Outpatient women's health and endocrinology practices generate the majority of new therapy initiations. Specialty distribution networks serve these sites directly.
- Pharmacies:Retail and mail-order dispensing relationships face disintermediation pressure from direct-to-patient subscription models for maintenance therapies.
Institutional volume concentrates in hospitals and clinics; patient preference shifts favor homecare administration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Vancouver anchors North American equine urine raw material flows, connecting Canadian prairie husbandry operations to United States pharmaceutical manufacturing corridors through integrated cold-chain logistics networks.
United States
Medicare Part D reimbursement infrastructure and aging demographic concentration drive prescription volumes in Florida, Arizona, and California retirement corridors. FDA updated hormone therapy labeling guidance in 2023 extends authorized use durations for symptomatic patients. Greater Boston's biopharmaceutical cluster hosts formulation development centers where Pfizer and AbbVie maintain active conjugated estrogen tablet production lines.
Canada
Specialized equine husbandry operations in Alberta and Saskatchewan supply sodium estrone sulfate raw materials to North American manufacturers. Health Canada maintains aligned pharmacovigilance protocols with FDA thromboembolic event reporting standards. Toronto-Waterloo corridor pharmaceutical services firms provide contract potency testing and sulfate characterization for cross-border batch certification.
Germany
EMA centralized marketing authorization procedures position German regulatory consultancies as gatekeepers for European market access. Value-based pricing reviews by the Federal Joint Committee (G-BA) constrain reimbursement levels for hormone replacement therapies. Frankfurt-Rhine-Main logistics hubs coordinate temperature-controlled distribution of transdermal patch formulations to ambulatory networks across Central Europe.
Switzerland
Swissmedic's streamlined clinical trial approval processes attract phase III hormone therapy studies from multinational sponsors. Basel's pharmaceutical services ecosystem hosts contract manufacturing organizations specializing in potent compound containment. Zürich-based reinsurance groups underwrite product liability coverage for estrogen-containing therapies distributed across European markets.
India
CDSCO accelerated approval pathways for generic hormone formulations attract contract manufacturing investment from United States and European sponsors. Active pharmaceutical ingredient synthesis capabilities in Hyderabad and Ahmedabad expand beyond traditional steroid chemistry into specialized estrogen sulfate production. Maharashtra FDA state-level inspections enforce good manufacturing practice compliance for export-oriented facilities supplying regulated markets.
Conjugated Estrogen Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in raw material and contract manufacturing niches. The conjugated estrogen market exhibits tiered consolidation around legacy innovators with established biologics infrastructure and aggressive generic challengers competing on price. Three archetypes dominate: integrated pharmaceutical conglomerates with endocrinology pipelines, specialty generic manufacturers with high-volume tablet capacity, and contract development organizations with transdermal patch expertise. Capacity expansion and strategic portfolio diversification into preventive osteoporosis applications represent the dominant competitive moves.
Among integrated pharmaceutical conglomerates, Pfizer Inc. and AbbVie Inc. occupy positions exemplifying platform-scale hormone therapy development, while Teva Pharmaceutical Industries Ltd. represents the generic manufacturing archetype competing through volume production and pharmacy benefit manager contracting relationships.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| AbbVie Inc. |
| Bayer AG |
| Novartis AG |
| Eli Lilly and Company |
| Novo Nordisk A/S |
| GlaxoSmithKline plc |
| Others |
Value Network & Pricing Analysis
Canadian prairie equine husbandry operations in Alberta and Saskatchewan concentrate raw material supply for sodium estrone sulfate, anchoring margin pools downstream with United States tablet manufacturers who command pharmacy reimbursement premiums against generic patch competitors.
Pricing Analysis
FDA black box warning requirements dictate the pricing tier structure across the conjugated estrogen market, stratifying products by cardiovascular risk profile and prescriber confidence levels. Three-tier pricing structure across premium, standard, and economy levels separates legacy brand tablets from authorized generics and compounded alternatives. Price differentiation rests on FDA approval status and clinical trial pedigree, with pharmacy benefit manager rebate compression intensifying cost pressure in the generic tablet segment. Hospital outpatient departments demonstrate lowest price sensitivity due to formulary lock-in, while retail pharmacy patients exhibit highest sensitivity to co-pay differentials.
Supply Chain Analysis
Extended payment terms from United States pharmaceutical manufacturers to Canadian raw material suppliers now stretch 90-120 days, reflecting working capital pressure downstream. Geographic supply concentration centers on Canada for equine urine collection, the United States for sulfate processing and tablet finishing, and India for emerging API synthesis capabilities. Raw material dependencies include specialized mare herd maintenance, pharmaceutical-grade sodium sulfate reagents, and cold-chain logistics infrastructure. Single-source vulnerability around Prairie province husbandry operations exposes manufacturers to climate disruption and animal welfare regulatory tightening. Distribution runs through specialty pharmaceutical wholesalers with temperature-controlled warehousing, bypassing generalist distributors for hormone-containing products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated pharmacy benefit managers and specialty distribution networks as formulary consolidation reduces manufacturer pricing autonomy across outpatient settings.
For Market Incumbents: Harden formulation differentiation through transdermal patch manufacturing capacity additions in United States corridors, insulating against compounded bioidentical substitution threats. Secure backward integration into Canadian equine husbandry operations to control sodium estrone sulfate raw material flows. Invest in FDA risk communication strategy to mitigate black box warning impact on prescriber comfort. For New Entrants and Emerging Players: Build out contract manufacturing capabilities for EMA-compliant transdermal patch production, targeting European ambulatory networks underserved by legacy tablet suppliers. Penetrate the osteoporosis prevention segment where screening expansion outpaces established hormone replacement therapy saturation. Deploy direct-to-patient subscription models to bypass pharmacy benefit manager rebate compression. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialty generic manufacturers holding high-volume tablet capacity but lacking patch formulation expertise. Five-to-ten year viability hinges on regulatory moat durability against compounded alternatives and transdermal adoption curves. Signal to watch: FDA enforcement posture on 503A/503B compounding facilities and bioidentical marketing claims.| Strategic Initiative | Industry Significance |
|---|---|
| Transdermal Patch Manufacturing Scale-Up | United States clinicians increasingly prescribe patches to circumvent hepatic first-pass metabolism risks. |
| Backward Integration into Equine Husbandry | Captive supply of sodium estrone sulfate raw materials insulates against Prairie province climate volatility. |
| Specialty Distribution Channel Expansion | Direct-to-practice models reduce pharmacy benefit manager rebate compression in integrated women's health networks. |
| EMA Good Manufacturing Practice Compliance Investment | Isolator technology retrofitting maintains European market access under Annex 1 containment requirements. |
| Digital Manufacturing Control Implementation | Process analytical technology deployment at Pfizer and Teva sites compresses batch release cycle times. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA pharmacovigilance databases, ClinicalTrials.gov records, and Medicare Part D reimbursement data. Interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers informed demand-side assumptions. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical manufacturer revenue disclosures.
Forecast inputs span treatment line positioning, dosage form preference shifts, administration route adoption curves, and regional regulatory cluster alignment. Segmentation dimensions include product type, therapy area, delivery mode, and end-user care setting. CAGRs were derived from patient population projections, screening protocol expansion rates, and reimbursement code evolution across the analysis window. Industry-specific inputs incorporate equine herd capacity constraints and FDA labeling guidance trajectory.
Stress conditions across equine supply disruption, compounded bioidentical substitution acceleration, and transdermal patch manufacturing capacity bottlenecks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory stability and prescriber behavior continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Antibiotics Market
Biopharmaceuticals
Global Biopharma Buffer Market
Biopharmaceuticals
Human Immunodeficiency Virus (HIV) Drugs Market
Biopharmaceuticals
Europe Insulin Pens Market
Biopharmaceuticals
Cephalosporin Market
Biopharmaceuticals
Ovarian Cancer Drugs Market
Biopharmaceuticals
Botanical and Plant Derived Drugs Market
Biopharmaceuticals
Anti-Tumor Drugs Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Olaparib API Market
Biopharmaceuticals
Russia Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Echinocandins Market
Biopharmaceuticals
Insulin Aspart Market
Biopharmaceuticals
Spectinomycin Market
Biopharmaceuticals
Antibody Discovery Market
Biopharmaceuticals
Oral Chemotherapy Market