
 Europe Monoclonal Antibodies Market | 2026-2036
Europe Monoclonal Antibodies Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Monoclonal Antibodies Market Insights
European biopharmaceutical manufacturing is consolidating around high-capacity antibody production hubs in Switzerland, Germany, and the United Kingdom. F. Hoffmann-La Roche Ltd anchors its position through deep vertical integration across diagnostic and therapeutic platforms. Novartis AG leverages its Basel-based R&D infrastructure to sustain pipeline productivity in immunology and oncology segments. AstraZeneca PLC competes aggressively through Cambridge-Stockholm dual headquarters coordination, positioning its antibody portfolio for EMA centralized procedure advantages.
Monoclonal antibodies are homogenous immunoglobulin proteins engineered for selective binding to defined antigenic targets, typically manufactured through mammalian cell culture in Chinese hamster ovary lines with subsequent purification via protein A chromatography. These agents serve primarily as targeted therapeutics for malignancy, autoimmunity, and infectious disease modulation. Oncology applications dominate value generation across the European market, reflecting prolonged treatment durations and premium positioning in hematologic and solid tumor indications. Subcutaneous delivery modes are gaining structural importance as healthcare systems prioritize outpatient administration and reduced infusion center burden. IgG subclasses occupy the core of commercial portfolios, given their favorable half-life, effector function profiles, and established manufacturing expertise.
EMA centralized marketing authorization procedures, EU MDR device companion diagnostic requirements, and EMA biosimilar comparability guidelines collectively determine market access timelines and competitive substitution dynamics. REACH chemical safety obligations and ECHA substance registration protocols additionally govern raw material sourcing and manufacturing site qualification across European production networks. Stakeholders must monitor evolving HTA convergence mechanisms under EUnetHTA and national reimbursement authority pricing negotiations, as these processes increasingly determine commercial viability prior to launch.
Market Dynamics
EMA's evolving biosimilar comparability guidelines are compressing originator exclusivity windows while accelerating competitive substitution across European oncology and immunology segments. Swiss and German manufacturing hubs are consolidating antibody production capacity to capture economies of scale before patent cliffs materialize.
Growth Catalysts
- EU MDR companion diagnostic mandates:The regulation is tightening alignment between therapeutic antibodies and diagnostic devices, expanding addressable patient populations through biomarker-driven screening.
- Subcutaneous delivery platforms:Outpatient administration technologies are reducing infusion center dependency and extending treatment access to community hospital settings.
- Germany's hospital procurement centralization:Regional purchasing alliances are standardizing antibody formularies, creating volume commitments that stabilize manufacturer revenue predictability.
Market Restraints
- Chinese hamster ovary cell line supply concentration:Mammalian cell culture inputs depend on a limited supplier base, exposing production schedules to raw material availability shocks.
- EMA centralized procedure timelines:Marketing authorization reviews extend development-to-commercialization intervals, compressing effective patent protection periods.
- Biosimilar substitution thresholds:EMA comparability requirements create technical barriers that delay generic entry without fully protecting originator pricing power.
Strategic Opportunities
- Poland and Eastern European infusion networks:Underdeveloped specialized treatment infrastructure offers first-mover advantages for subcutaneous formulation penetration.
- REACH chemical safety data monetization:Compliance documentation investments can be repurposed for ECHA substance registration services to third-party manufacturers.
- Dual-targeting antibody engineering:Bispecific platform convergence with established IgG manufacturing expertise opens novel mechanism-of-action categories.
Industry Challenges
- Bioprocess engineering talent scarcity:Mammalian cell culture optimization and protein A chromatography scale-up expertise concentrates in Basel and Cambridge clusters, constraining facility expansion timelines.
- Legacy batch record system integration:Digital transformation of manufacturing execution systems requires capital deployment without immediate yield improvement visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Monoclonal Antibodies Market |
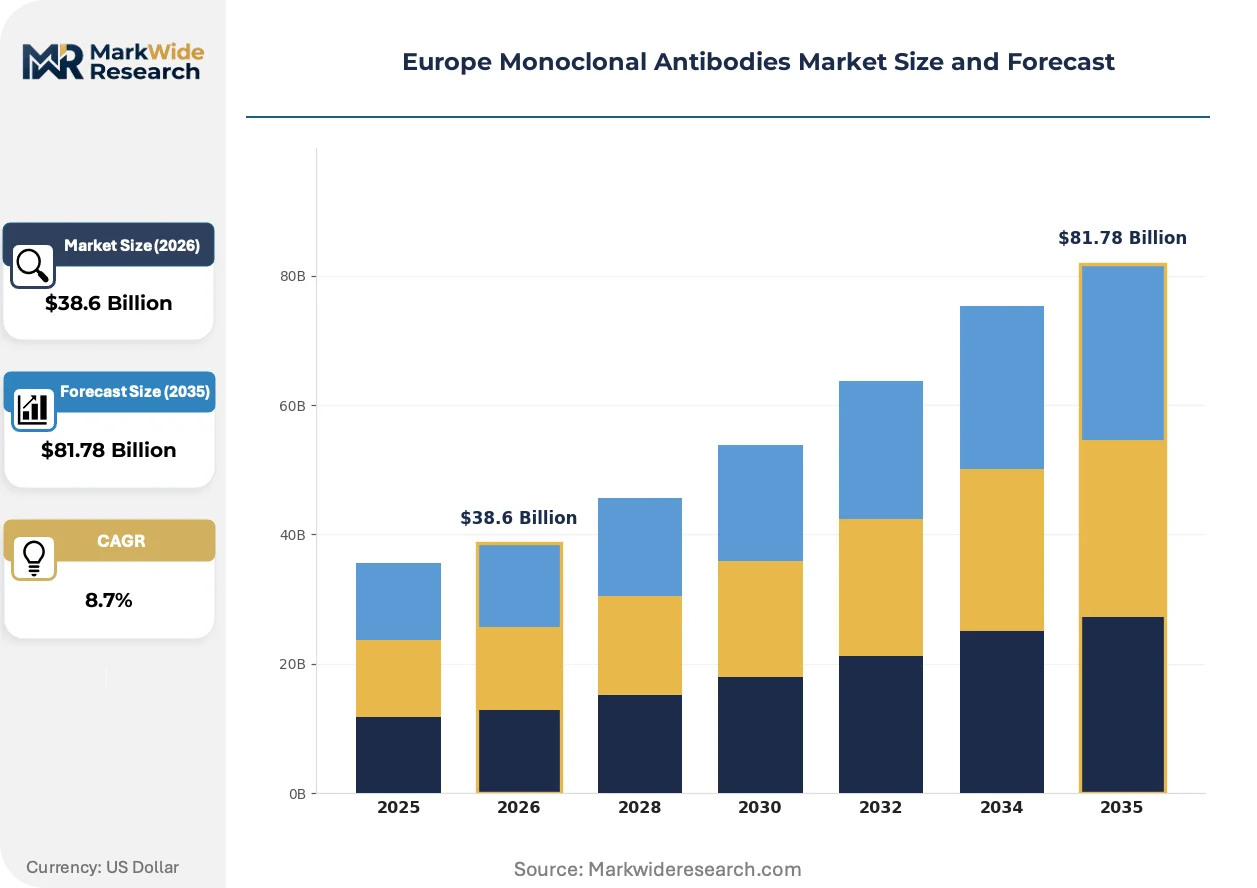
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IgG, IgM, IgA, IgE Therapy Area: Oncology, Immunology, Infectious Diseases, Neurology Delivery Mode: Subcutaneous, Intravenous, Intramuscular, Oral End User: Hospitals, Clinics, Laboratories, Research Institutions |
| Companies Covered | F. Hoffmann-La Roche Ltd, Novartis AG, Merck KGaA, Pfizer Inc., Eli Lilly and Company, GlaxoSmithKline plc, AstraZeneca PLC, Amgen Inc., Bristol-Myers Squibb Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Monoclonal Antibodies Market Trends and Innovations
Antibody engineering platforms are converging with automated bioprocessing systems, compressing development timelines while expanding modality diversity beyond traditional IgG architectures. European regulatory science is simultaneously adapting to evaluate novel formats without established comparability frameworks.
Continuous bioprocessing technology is electrifying traditional fed-batch manufacturing economics. Mid-scale European CMOs are adopting perfusion cell culture systems to improve facility utilization rates. The shift is enabling flexible production campaigns that match output to demand volatility without batch-size penalties.
EMA's revised biosimilar immunogenicity guidance is tightening clinical evidence requirements for interchangeability designation. Originators are extending lifecycle management investments to defend positioning against substitution mandates. The hematology segment faces the most acute pricing compression as national reimbursement authorities reference biosimilar tenders.
Hospital purchasing alliances are consolidating antibody procurement decisions across multi-site networks. Community oncology clinics are losing direct supplier relationships as regional tenders centralize volume commitments. France and Italy exhibit the fastest alliance formation rates, compressing vendor negotiation leverage.
Europe Monoclonal Antibodies Market Segmentation
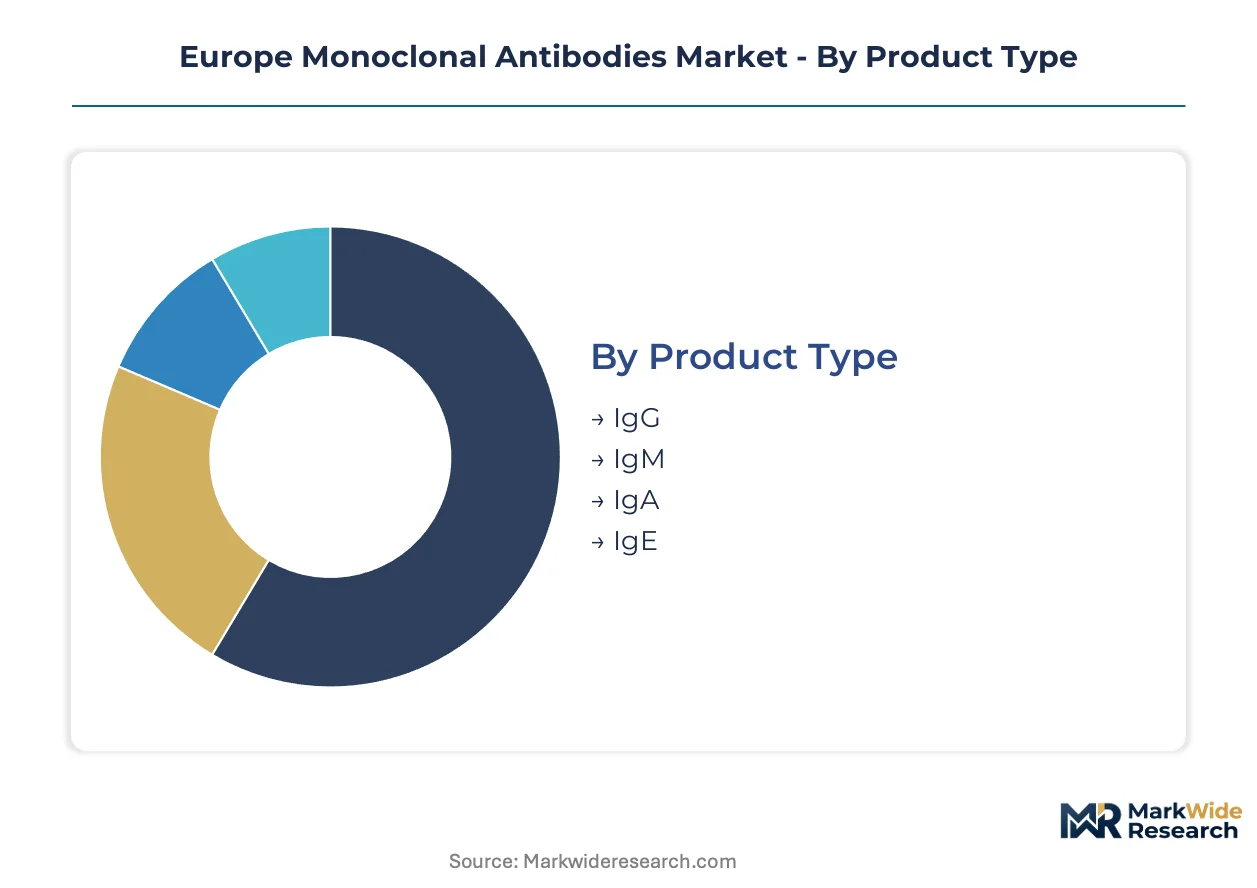
Antibody portfolio decisions in Europe hinge on manufacturing scalability, reimbursement pathways, and administration infrastructure. Segmentation reveals where EMA regulatory frameworks and national HTA processes concentrate commercial viability across molecular formats and care settings.
Product Type:
Bioprocess engineering constraints and half-life optimization drive manufacturer investment decisions across immunoglobulin classes.
- IgG:These four-subclass immunoglobulins dominate commercial manufacturing through established protein A chromatography protocols and Chinese hamster ovary cell line optimization. German and Swiss production hubs concentrate IgG capacity due to mature downstream processing infrastructure and EMA centralized procedure familiarity.
- IgM:Pentameric structures with high antigen-binding avidity serve diagnostic applications and emerging therapeutic targets where complement activation proves advantageous. Pentameric complexity limits current production scale, constraining penetration beyond specialized research use in United Kingdom and Netherlands academic medical centers.
- IgA:Mucosal immunity applications drive development for respiratory and gastrointestinal indications, though manufacturing yields lag IgG benchmarks significantly.
- IgE:Allergen-specific targeting mechanisms support diagnostic and limited therapeutic applications, with production concentrated in contract manufacturing organizations serving French and Italian biotech sponsors.
Volume sits with IgG; growth tilts toward IgM as novel engineering platforms resolve production bottlenecks.
Therapy Area:
Reimbursement authority pricing negotiations and treatment duration economics determine commercial prioritization across disease categories.
- Oncology:Hematologic and solid tumor indications generate sustained revenue through prolonged administration protocols and premium positioning in combination regimens. United Kingdom Cancer Drugs Fund and France's HAS evaluation processes anchor European access negotiations for novel antibody-drug conjugates and immune checkpoint inhibitors.
- Immunology:Rheumatoid arthritis, psoriasis, and inflammatory bowel disease indications benefit from expanding subcutaneous delivery adoption and maintenance therapy structures. German statutory health insurance rebate negotiations compress net pricing for established anti-TNF agents while preserving margins for next-generation IL-targeting biologics.
- Infectious Diseases:Antiviral and antibacterial monoclonal antibodies address resistant pathogen challenges, with procurement concentrated in national stockpiling programs and hospital pharmacy committees.
- Neurology:Blood-brain barrier penetration limitations constrain therapeutic application, though Alzheimer's disease antibody approvals are reshaping prescriber expectations in Scandinavian specialist centers.
Revenue concentrates in oncology; pipeline activity is climbing fastest in neurology as delivery technology advances.
Delivery Mode:
Healthcare system capacity constraints and patient preference data are redirecting formulation development priorities.
- Subcutaneous:Self-administration protocols and reduced infusion center burden align with Germany's hospital procurement centralization and France's community care expansion policies. Prefilled syringe and autoinjector platforms from Swiss and Irish device manufacturers support outpatient transition.
- Intravenous:Hospital-based infusion maintains dominance for high-dose oncology protocols and first-line immunology induction, with capacity concentrated in United Kingdom NHS trusts and Italian regional hospital networks.
- Intramuscular:Rapid immune response requirements drive infectious disease prophylaxis applications, with distribution through national immunization programs.
- Oral:Gastrointestinal stability challenges limit antibody bioavailability, though enteric coating advances are attracting early-stage investment from Danish biotechnology firms.
Administration burden favors intravenous for acute settings; convenience premiums are expanding most quickly for subcutaneous alternatives.
End User:
Purchasing authority consolidation and diagnostic integration requirements determine channel strategy effectiveness.
- Hospitals:Regional purchasing alliances in France, Italy, and Spain concentrate antibody procurement decisions across multi-site networks, with formulary placement contingent on EMA centralized authorization and national reimbursement listing.
- Clinics:Community oncology and rheumatology practices in Germany and the Netherlands are losing direct supplier relationships as tender centralization progresses, though subcutaneous delivery platforms enable some independent prescribing.
- Laboratories:Companion diagnostic mandates under EU MDR are tightening therapeutic antibody alignment with in vitro testing infrastructure, particularly in United Kingdom and Belgium reference laboratory networks.
- Research Institutions:Academic medical centers in Sweden, Denmark, and Switzerland anchor early-phase clinical trial activity and biosimilar immunogenicity assessment for EMA guideline development.
Procurement volume aggregates at hospitals; research institutions are gaining influence fastest through biosimilar evidence generation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese hamster ovary cell lines anchor European monoclonal antibody production, with mammalian culture inputs flowing through Basel, Cambridge, and German manufacturing clusters before EMA centralized authorization.
Germany
Statutory health insurance rebate negotiations compress net pricing for established anti-TNF agents while preserving margins for next-generation IL-targeting biologics. Germany's hospital procurement centralization through regional purchasing alliances standardizes antibody formularies. North Rhine-Westphalia and Bavaria concentrate production capacity around protein A chromatography scale-up expertise.
United Kingdom
The Cancer Drugs Fund anchors European access negotiations for novel antibody-drug conjugates and immune checkpoint inhibitors. NHS trusts maintain hospital-based infusion dominance for high-dose oncology protocols. Cambridge and Greater London clusters coordinate dual headquarters operations for EMA centralized procedure advantages.
Switzerland
Swissmedic authorization runs parallel to EMA procedures, creating dual-track market access for Basel-based manufacturers. F. Hoffmann-La Roche Ltd maintains deep integration across diagnostic and therapeutic platforms. The Basel biopharmaceutical hub concentrates mammalian cell culture optimization talent and downstream processing infrastructure.
France
Haute Autorité de Santé evaluation processes determine reimbursement listing for novel antibody formats. Community care expansion policies accelerate subcutaneous delivery adoption in rheumatology and dermatology settings. Île-de-France and Auvergne-Rhône-Alpes anchor infusion network development alongside reference laboratory diagnostic integration.
Italy
Regional hospital networks consolidate antibody procurement decisions through multi-site tender centralization. Italian biosimilar substitution mandates reference EMA comparability guidelines for interchangeability designation. Lombardy and Emilia-Romagna exhibit the fastest alliance formation rates, compressing vendor negotiation leverage.
Europe Monoclonal Antibodies Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and EMA regulatory familiarity. The vendor base clusters around three tiers: vertically integrated pharmaceutical conglomerates with diagnostic-therapeutic platforms, mid-cap biotech specialists with single-asset dependencies, and contract manufacturing organizations serving sponsor pipelines. Dominant competitive moves include backward integration into cell line development and strategic partnerships for subcutaneous delivery device co-development.
Among Swiss- and German-based integrated pharmaceutical groups, F. Hoffmann-La Roche Ltd, Novartis AG, and Merck KGaA occupy positions exemplifying the vertical-integration archetype. These Basel- and Darmstadt-anchored entities represent manufacturing scale advantages through captive Chinese hamster ovary cell line supply and protein A chromatography infrastructure. AstraZeneca PLC sits within the dual-headquarters vector, with Cambridge-Stockholm coordination positioning its portfolio for centralized EMA procedure navigation.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Merck KGaA |
| Pfizer Inc. |
| Eli Lilly and Company |
| GlaxoSmithKline plc |
| AstraZeneca PLC |
| Amgen Inc. |
| Bristol-Myers Squibb Company |
| Others |
Pricing and Supply Chain Analysis
Chinese hamster ovary cell line supply costs cascade through EMA-authorized manufacturing tiers, with Basel-anchored producers commanding premium positioning against contract manufacturing competitors facing REACH chemical safety compliance burdens.
Pricing Analysis
Service bundling separates originator portfolios from biosimilar competitors, with lifecycle management support and diagnostic co-development included in premium therapeutic antibody contracts. Pricing stratifies across originator, biosimilar, and tender-awarded tiers, driven by manufacturing scale and EMA centralized procedure familiarity. Cost compression in the biosimilar tier is intensifying as national reimbursement authorities reference interchangeability tenders. Hospital purchasing alliances exhibit highest price sensitivity, while specialized academic medical centers prioritize clinical evidence over acquisition cost.
Supply Chain Analysis
Dual-sourcing mandates from German and French hospital procurement alliances require qualified backup suppliers for protein A chromatography resins and cell culture media. Production gravity centers on Switzerland, Germany, and the United Kingdom, drawing from Chinese hamster ovary cell line repositories and specialized filtration membrane suppliers. Single-source vulnerability concentrates in mammalian cell culture optimization expertise anchored in Basel and Cambridge clusters. Distribution runs through regional hospital networks and specialized infusion centers coordinated under national tender frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe monoclonal antibodies market is consolidating around captive control of cell line development and downstream processing infrastructure, with backward integration into diagnostic platforms emerging as the decisive competitive lever.
For Market Incumbents: Hedge against biosimilar substitution by accelerating subcutaneous formulation lifecycle extensions and securing companion diagnostic alignment under EU MDR mandates. Deepen backward integration into protein A chromatography resin supply to insulate margins from raw material volatility. Prioritize EMA centralized procedure expertise retention as biosimilar comparability guidelines compress exclusivity windows. For New Entrants and Emerging Players: Capture Poland and Eastern European infusion network expansion through subcutaneous delivery platform partnerships with Irish and Swiss device manufacturers. Poland's underdeveloped specialized treatment infrastructure offers the most penetrable geography for outpatient administration transition. Pursue contract manufacturing organization partnerships with mid-scale perfusion cell culture adopters to bypass capital-intensive facility construction. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European CMOs with perfusion bioprocessing capability in German and Swiss manufacturing corridors. Long-term viability hinges on regulatory science adaptability as EMA evaluates novel antibody formats without established comparability frameworks. Monitor EMA biosimilar immunogenicity guidance revisions as the critical inflection signal for substitution mandate acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Reduces infusion center dependency and aligns with Germany's hospital procurement centralization policies. |
| Companion Diagnostic Integration | EU MDR mandates tighten therapeutic antibody alignment with United Kingdom and Belgium reference laboratory networks. |
| Continuous Bioprocessing Adoption | Perfusion cell culture systems improve facility utilization rates for mid-scale European CMOs. |
| Cell Line Development Captivity | In-house Chinese hamster ovary line control insulates production schedules from supplier concentration risk. |
| Biosimilar Interchangeability Investment | EMA immunogenicity evidence requirements determine substitution mandate timing and pricing compression severity. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists across European markets. EMA centralized procedure documentation, ClinicalTrials.gov entries, and national reimbursement authority pricing decisions provided validation layers. Bottom-up antibody production volume estimates triangulated against top-down therapeutic area expenditure analyses.
Granularity extended to IgG subclass, therapy area, delivery mode, and end-user channel dimensions across the projection horizon. CAGRs derived from segmented demand modeling incorporating treatment duration economics, biosimilar penetration curves, and subcutaneous adoption rates. Manufacturing capacity utilization assumptions and EMA review timeline distributions informed supply-side constraints.
The model holds under stable EMA biosimilar comparability guideline interpretation; deviation in immunogenicity evidence requirements or REACH chemical safety enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Triptorelin Market
Biopharmaceuticals
Mammalian Derived Proteins Market
Biopharmaceuticals
Antibacterial Drugs Market
Biopharmaceuticals
Pruritus Therapeutics Market
Biopharmaceuticals
North America HIV Drugs Market
Biopharmaceuticals
Botanical and Plant Derived Drugs Market
Biopharmaceuticals
Global Swine Fever Vaccine Market
Biopharmaceuticals
Beta Interferon Market
Biopharmaceuticals
Recombinant Human Serum Albumin Market
Biopharmaceuticals
Human Chorionic Gonadotropin Market
Biopharmaceuticals
Biological Drugs Market
Biopharmaceuticals
Sezary Syndrome Market
Biopharmaceuticals
Daptomycin Market
Biopharmaceuticals
Vaccine Ampoules Market
Biopharmaceuticals
Macrolide Antibiotics Market
Biopharmaceuticals
Global Pegylated Proteins Market