
 Tuberculosis Drugs Market | 2026-2036
Tuberculosis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Tuberculosis Drugs Market Outlook
India's pharmaceutical manufacturing corridor is reshaping supply dynamics for tuberculosis drugs. Johnson & Johnson Services anchors its bedaquiline production through backward integration into active pharmaceutical ingredient synthesis. Lupin Limited dominates the generic first-line drug segment with high-volume manufacturing of rifampicin and isoniazid combinations. Sanofi competes through sustained investment in pediatric TB formulations and heat-stable drug delivery technologies.
Tuberculosis drugs comprise antimicrobial agents designed to eliminate Mycobacterium tuberculosis, typically formulated as fixed-dose combinations containing rifamycins, isoniazid, pyrazinamide, and ethambutol with specified bioequivalence thresholds. These agents serve the primary purpose of curing active infection and preventing latent progression in exposed populations. First-line drugs occupy the largest revenue pool due to standardized procurement by national TB programs, while drug-resistant TB therapies command premium positioning despite smaller volumes. Combination therapies represent the fastest-growing category as WHO-endorsed shorter regimens replace sequential monotherapy protocols.
FDA, EMA, and WHO prequalification standards govern market access for tuberculosis drugs, with stringent bioequivalence requirements for generic substitutions in donor-funded procurement channels. India's CDSCO and South Africa's national pharmaceutical regulator enforce local quality certification that shapes which manufacturers qualify for government tenders. Stakeholders must monitor evolving WHO guideline revisions and national essential medicines list updates that directly determine procurement volumes and formulary inclusion.
Market Dynamics
Shorter WHO-endorsed drug regimens are collapsing the traditional sequential monotherapy protocol, forcing manufacturers to reconfigure combination therapy portfolios and supply chains around fixed-dose formulations.
Growth Catalysts
- CDSCO quality certification:India's streamlined approval pathways for bioequivalent generics accelerate manufacturer entry into government procurement channels.
- Pediatric TB formulations:WHO dosing guidelines for children create dedicated demand pools for dispersible tablets and weight-band stratified products.
- Heat-stable technologies:Reformulation investments enable distribution through ambient-temperature supply chains in tropical climates.
Market Restraints
- API concentration in China:Rifamycin and pyrazinamide intermediate supply depends on concentrated chemical manufacturing clusters.
- WHO prequalification timelines:Stringent bioequivalence documentation requirements delay generic market entry by 18-24 months.
- Platinum-group metal catalysts:Rifampicin synthesis requires palladium and rhodium inputs subject to commodity volatility.
Strategic Opportunities
- Sub-Saharan Africa procurement:National TB program capacity building creates demand for integrated diagnostics-treatment packages.
- Digital adherence technologies:Medication event monitoring systems pair with drug supply to improve treatment completion rates.
- PLI scheme incentives:India's production-linked incentives for active pharmaceutical ingredients attract backward-integrated manufacturing investments.
Industry Challenges
- Pharmacovigilance infrastructure:Post-market surveillance for drug-resistant TB therapies requires specialized adverse event reporting systems.
- Multidrug resistance diagnostics integration:Supply chains must synchronize molecular testing turnaround with targeted therapy initiation.
- Cold chain fragmentation:Bedaquiline and delamanid distribution networks demand -20°C storage capabilities absent in peripheral health facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tuberculosis Drugs Market |
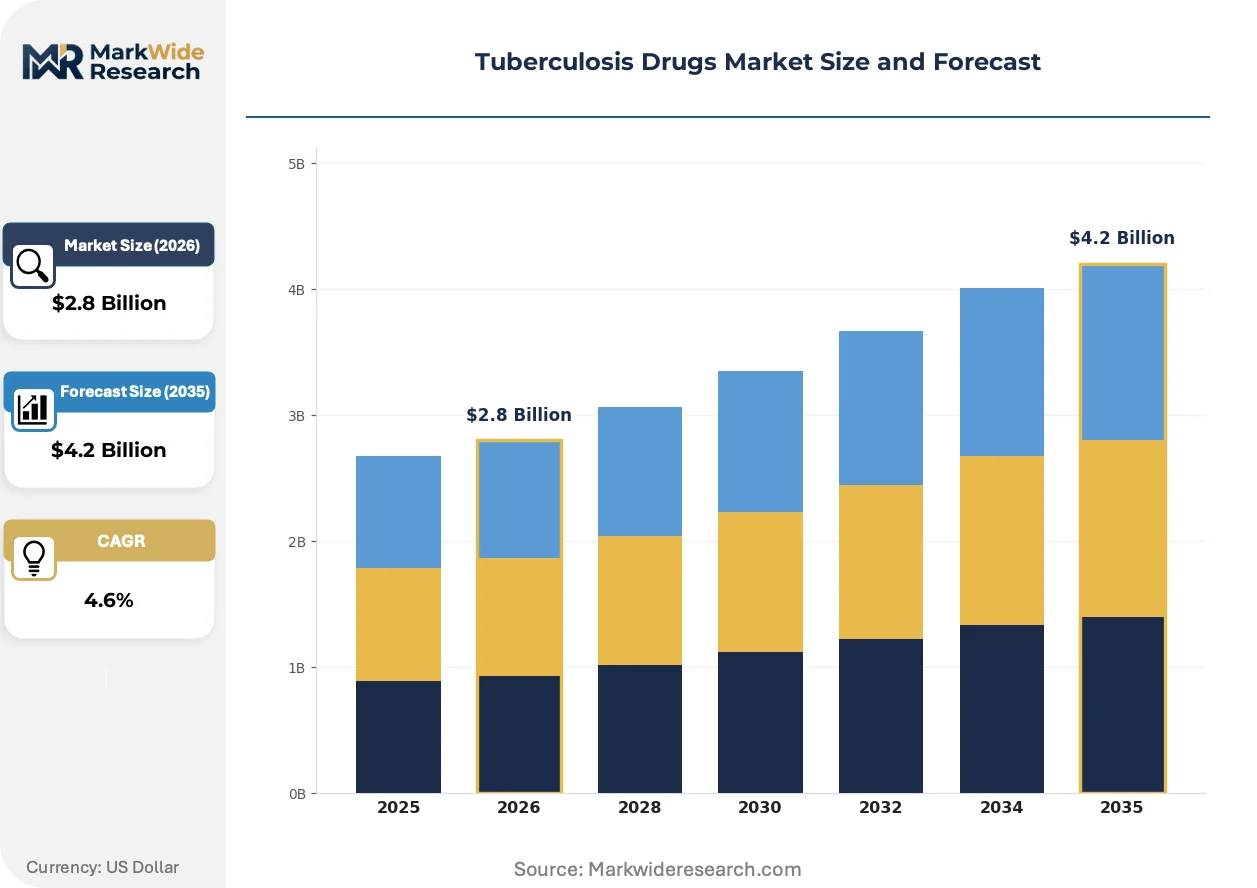
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: First-Line Drugs, Second-Line Drugs, Combination Therapies, Supportive Treatments Therapy Area: Drug-Sensitive TB, Drug-Resistant TB, Latent TB Infection, Pediatric TB End User: Hospitals, Clinics, Research Institutions, Home Care Delivery Mode: Oral, Injectable, Inhaled, Intravenous |
| Companies Covered | Johnson & Johnson Services, Lupin Limited, AstraZeneca, Sanofi, Novartis AG, Macleods Pharmaceuticals Ltd, Viatris Inc, Sun Pharmaceutical Industries Ltd, Pfizer Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tuberculosis Drugs Market Strategic Shifts
Novel drug combinations are compressing treatment duration from six months to four months, creating formulation complexity that favors manufacturers with integrated development capabilities.
Artificial intelligence-driven molecular design is collapsing the traditional empirical screening process for new tuberculosis drug candidates. Insilico Medicine and structural biology consortia deploy generative models to predict mycobacterial target binding. This acceleration enables smaller biotech entrants to compete with established pharmaceutical discovery engines.
WHO guideline revisions are mandating universal drug susceptibility testing before regimen selection. The 2022 consolidated guidelines require molecular diagnostics for all diagnosed patients. Sub-Saharan African national programs are retrofitting laboratory networks to comply, redirecting procurement budgets toward integrated diagnostic-therapeutic platforms.
Buyer concentration through pooled procurement mechanisms is consolidating national TB program purchasing power. The Global Drug Facility aggregates demand from 140 countries to negotiate volume-based pricing. Generic manufacturers now compete on total cost of ownership including technical assistance and supply security guarantees rather than unit price alone.
Tuberculosis Drugs Market Segmentation
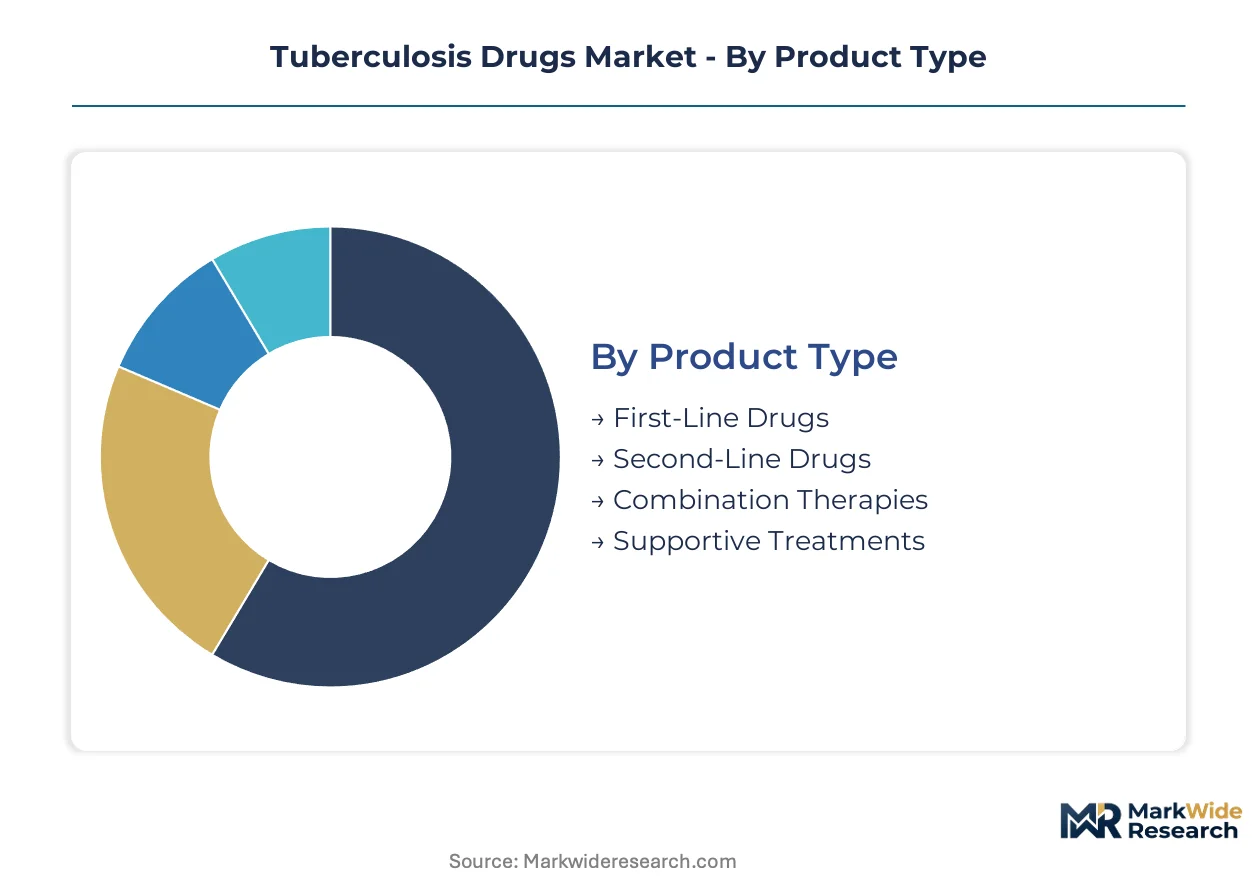
TB drug procurement operates on divergent replenishment cycles. First-line combination therapies turn over in high-volume national program tenders, while drug-resistant regimens move through specialized channels with extended qualification timelines. Understanding these velocity differentials shapes portfolio allocation and manufacturing capacity planning.
Product Type:
Cycle times stretch from six-month tender cycles for standardized regimens to multi-year development timelines for novel formulations.
- First-Line Drugs:Fixed-dose combinations of rifampicin, isoniazid, pyrazinamide, and ethambutol dominate procurement volumes. India's national TB program drives bulk purchasing through centralized tenders, with CDSCO bioequivalence certification determining supplier eligibility.
- Combination Therapies:WHO-endorsed shorter regimens are displacing sequential monotherapy protocols. Demand concentrates in low- and middle-income countries where treatment completion rates determine program funding allocations.
- Second-Line Drugs:Bedaquiline and delamanid serve multidrug-resistant cases requiring specialized cold chain distribution.
- Supportive Treatments:Adjunctive therapies manage adverse effects and co-morbidities in prolonged treatment courses.
First-Line Drugs dominate installed base. Combination Therapies are where expansion concentrates.
Therapy Area:
Cost tiers separate mass-market procurement from premium-priced resistant-TB portfolios.
- Drug-Sensitive TB:Standard six-month regimens account for the majority of treated cases. Procurement runs through Global Drug Facility pooled purchasing with volume-based pricing mechanisms.
- Drug-Resistant TB:Second-line and novel agents command premium positioning. Treatment duration extends 18-24 months, with bedaquiline requiring specialized pharmacovigilance infrastructure.
- Latent TB Infection:Preventive therapy targets high-risk populations including HIV-positive patients and household contacts. Shorter rifapentine-based regimens are gaining regulatory traction.
- Pediatric TB:Weight-band stratified dispersible tablets address dosing precision requirements. WHO guidelines mandate child-appropriate formulations in national essential medicines lists.
Drug-Sensitive TB dominates installed base. Drug-Resistant TB is where margin expansion concentrates.
End User:
Customer type determines service intensity and technical assistance bundling.
- Hospitals:Tertiary centers manage complicated drug-resistant cases requiring inpatient initiation and adverse event monitoring. India's district hospital network anchors first-line treatment distribution.
- Clinics:Primary health facilities deliver directly observed therapy for standard regimens. South Africa's clinic-based TB program demonstrates decentralized care models.
- Research Institutions:Clinical trial sites drive demand for investigational combinations and novel delivery technologies.
- Home Care:Community-based treatment support reduces facility burden. Digital adherence technologies pair with home delivery in emerging program designs.
Hospitals dominate installed base. Home Care is where service model innovation concentrates.
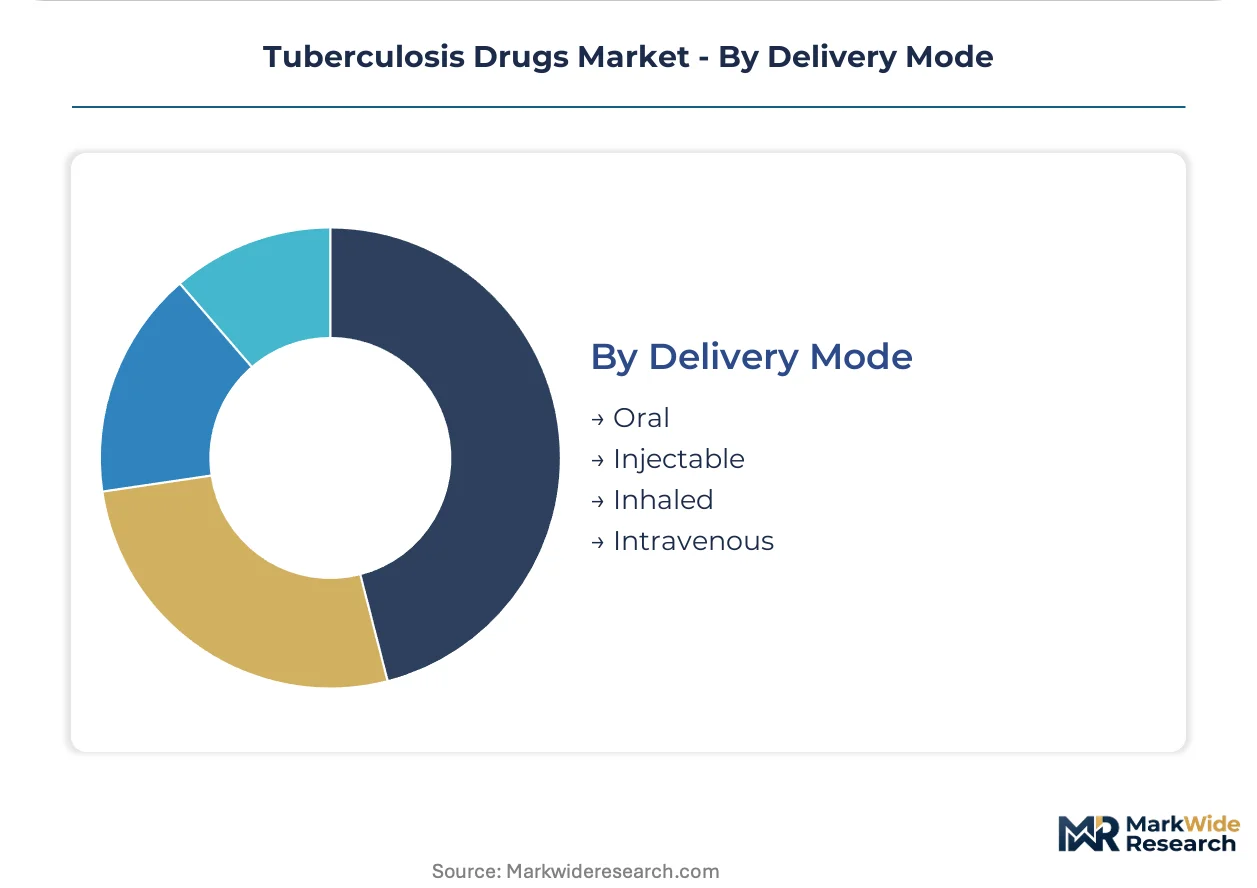
Delivery Mode:
Supply concentration favors oral solid dosage forms with established ambient-temperature distribution networks.
- Oral:Fixed-dose tablets and dispersible formulations serve the majority of patients. Heat-stable technologies enable tropical distribution without cold chain dependency.
- Injectable:Streptomycin and kanamycin retain niche utility in treatment-intolerant cases. Administration requires trained healthcare personnel.
- Inhaled:Investigational aerosolized delivery targets localized pulmonary infection with reduced systemic exposure.
- Intravenous:Reserved for severe disseminated TB or central nervous system involvement in hospital settings.
Oral dominates installed base. Inhaled is where technology development concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes tuberculosis drugs through high-volume national program tenders, while South Africa and Brazil prioritize drug-resistant TB portfolios with premium cold-chain regimens. This consumption-mix differential shapes manufacturer portfolio allocation across geographies.
India
India's national TB program drives the world's largest procurement volumes for fixed-dose combinations of rifampicin and isoniazid. CDSCO bioequivalence certification determines supplier eligibility for government tenders. The pharmaceutical manufacturing corridor in Maharashtra and Gujarat hosts backward-integrated API synthesis operations serving domestic and export demand.
South Africa
South Africa's clinic-based TB program demonstrates decentralized care models with high drug-resistant case detection rates. The country's national pharmaceutical regulator enforces local quality certification that shapes manufacturer qualification for government procurement. Cape Town and Johannesburg anchor specialized distribution networks for bedaquiline cold-chain logistics.
Brazil
Brazil's unified health system procures combination therapies through centralized federal tenders with volume-based pricing mechanisms. ANVISA governs market access with stringent bioequivalence requirements for generic substitutions. São Paulo's pharmaceutical cluster concentrates formulation manufacturing for Latin American export markets.
China
China's domestic TB program sources rifamycin and pyrazinamide intermediates from concentrated chemical manufacturing clusters. NMPA quality standards align with WHO prequalification to enable export eligibility for donor-funded procurement channels. Shandong and Jiangsu provinces host captive API production serving both domestic formulation and international intermediate supply.
United States
The United States addresses latent TB infection in high-risk populations through targeted preventive therapy programs. FDA approval pathways for rifapentine-based shorter regimens create dedicated demand pools distinct from active disease treatment. Research institutions in Boston and San Francisco anchor clinical trial networks for novel combination development.
Tuberculosis Drugs Market Competitive Environment
Capability concentration sits with research-intensive developers of novel regimens; scale advantage sits with high-volume generic manufacturers of established combinations. The market structures around three tiers: multinational innovators with novel drug portfolios, Indian generic specialists with backward-integrated API operations, and regional formulation players serving national program tenders. Competitive dynamics center on M&A activity consolidating manufacturing capacity and strategic partnerships pairing drug supply with diagnostic platforms.
Among the innovator tier, Johnson & Johnson Services exemplifies integrated development capabilities spanning bedaquiline synthesis through distribution. Indian generic specialists Lupin Limited and Sun Pharmaceutical Industries Ltd occupy positions defined by CDSCO-certified bioequivalence and high-volume rifampicin production. These three anchors represent the capability-scale bifurcation shaping procurement negotiations.
| Leading Market Players |
|---|
| Johnson & Johnson Services |
| Lupin Limited |
| AstraZeneca |
| Sanofi |
| Novartis AG |
| Macleods Pharmaceuticals Ltd |
| Viatris Inc |
| Sun Pharmaceutical Industries Ltd |
| Pfizer Inc |
| Others |
Value Chain & Pricing Dynamics
Palladium and rhodium commodity volatility in rifampicin synthesis determines both margin compression in first-line generics and the geographic redistribution of API manufacturing toward platinum-group metal hedging strategies. This input cost instability compresses pricing tiers while accelerating backward integration investments by Indian manufacturers seeking supply security.
Pricing Analysis
Price spreads between South African bedaquiline cold-chain regimens and Indian first-line combination therapies exceed threefold, reflecting distribution complexity premiums alongside bioequivalence certification grade. Three-tier pricing structure across WHO-prequalified, CDSCO-certified, and non-certified supply separates donor-funded procurement from government tenders and private pharmacy channels. Cost compression in standard rifampicin-isoniazid combinations intensifies as Lupin and Sun Pharmaceutical expand Maharashtra API capacity. National TB programs exhibit extreme price sensitivity, while hospital procurement for drug-resistant cases prioritizes supply security over unit cost.
Supply Chain Analysis
Extended payment terms from the Global Drug Facility to generic manufacturers stretch working capital cycles, favoring diversified pharmaceutical conglomerates over pure-play formulation specialists. API supply draws from concentrated chemical manufacturing clusters in Shandong and Jiangsu provinces, with captive pyrazinamide intermediate production serving both domestic Chinese formulation and international export. Single-source vulnerability in streptomycin injectable supply from legacy fermentation facilities threatens treatment-intolerant case management. Distribution runs through ambient-temperature national program networks for first-line drugs, while bedaquiline requires specialized -20°C logistics through Johannesburg and Cape Town cold-chain hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital adherence technologies and medication event monitoring systems represent a service-attach layer expanding faster than pharmaceutical supply, creating recurring revenue streams alongside drug procurement. These platforms capture treatment completion data that determines program funding allocations in low- and middle-income countries.
For Market Incumbents: Entrench formulary position through CDSCO bioequivalence certification renewal and heat-stable formulation investments that extend ambient-temperature distribution reach. Indian generic specialists face margin pressure from platinum-group metal cost volatility; backward integration into Maharashtra API synthesis secures cost position against Chinese intermediate suppliers. Defensive patent strategies around novel combination dosing protocols protect against biotech entrants deploying AI-driven molecular design. For New Entrants and Emerging Players: Build out pharmacovigilance infrastructure capabilities targeting drug-resistant TB therapy adverse event reporting, a specialized function absent in peripheral health facilities. Sub-Saharan African national programs present the most penetrable geography, with procurement capacity building creating demand for integrated diagnostics-treatment packages. Go-to-market through Global Drug Facility technical assistance bundling rather than unit price competition. For Investors and Strategic Acquirers: WHO guideline revisions mandating universal drug susceptibility testing reshape the acquisition landscape toward diagnostic-therapeutic platform convergence. Five-to-ten year viability favors manufacturers with integrated bedaquiline synthesis and molecular testing partnerships over pure-play generic formulation. Target acquisition archetype: Indian mid-caps with CDSCO certification and latent pediatric formulation capabilities. Signal to monitor: WHO prequalification timeline compression for bioequivalent generics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Synthesis | Maharashtra and Gujarat captive production reduces platinum-group metal exposure and Chinese intermediate dependency. |
| Heat-Stable Formulation Development | Ambient-temperature distribution unlocks tropical national program tenders without cold chain infrastructure. |
| Digital Adherence Platform Partnership | Medication event monitoring systems improve treatment completion rates and secure program funding allocations. |
| Pediatric Dispersible Portfolio Expansion | WHO weight-band stratified guidelines mandate child-appropriate formulations in essential medicines lists. |
| Pharmacovigilance Infrastructure Buildout | Specialized adverse event reporting capabilities qualify suppliers for drug-resistant TB therapy procurement. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and WHO prequalification databases. Primary interviews engaged regulatory affairs leads at Indian generic manufacturers, formulary directors at national TB programs, hospital procurement managers in South Africa and Brazil, and payer access specialists at the Global Drug Facility. Bottom-up demand modeling from patient volume and treatment regimen data triangulates against top-down market sizing from customs records and pharmaceutical trade flows.
Forecast inputs incorporate treatment line segmentation, dosage form stratification, regional regulatory cluster differentiation, and patient population epidemiology across the projection horizon. CAGRs derive from regression analysis of historical procurement volumes against WHO guideline revision timelines and national program budget cycles. Modeled variables include rifamycin intermediate pricing volatility, CDSCO approval pathway velocity, and cold-chain infrastructure expansion rates in Sub-Saharan Africa.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-cap Indian specialists or accelerated AI-driven drug discovery by biotech entrants would shift outcomes. Assumptions reflect documented procurement practices, bioequivalence certification timelines, and national program funding trajectories. Macroeconomic commodity volatility in platinum-group metals, regulatory deviation in WHO prequalification standards, or technological breakthrough in inhaled delivery formulations would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
US Generic Drug Market
Biopharmaceuticals
Cancer Drug Market
Biopharmaceuticals
Anti-Neoplastic Pharmaceutical Agents Market
Biopharmaceuticals
Olaparib API Market
Biopharmaceuticals
Global Human Recombinant Insulin Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
Combination Antibody Therapy Market
Biopharmaceuticals
HIV Market
Biopharmaceuticals
Tetracycline Market
Biopharmaceuticals
Anti-Tumor Drugs Market
Biopharmaceuticals
Botanical and Plant Derived Drugs Market
Biopharmaceuticals
Mammalian Polyclonal Igg Antibody Market
Biopharmaceuticals
Global Infertility Drugs Market
Biopharmaceuticals
Human Combinatorial Antibody Libraries (Hucal) Market
Biopharmaceuticals
Theranostics Market
Biopharmaceuticals
US Influenza Vaccine Market