
 Next Generation Antibody Therapeutics Market | 2026-2036
Next Generation Antibody Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Antibody Therapeutics Market Outlook
Modular dosing regimens paired with companion diagnostic bundling is realigning how oncology buyers evaluate antibody platforms. F. Hoffmann-La Roche Ltd. leverages its diagnostic-antibody integration to sustain premium positioning across infusion networks. Bristol-Myers Squibb Company anchors its competitiveness through scaled manufacturing of T-cell engagers. Genmab A/S specializes in differentiated half-life extension technologies that reduce dosing frequency for chronic indications.
Next generation antibody therapeutics comprise engineered immunoglobulin constructs including bispecific formats, antibody-drug conjugates with cleavable linkers, and Fc-modified variants optimized for effector function or extended circulation. These modalities target tumor microenvironments, autoimmune signaling cascades, and infectious pathogen neutralization through precise antigen engagement mechanisms. Antibody-drug conjugates command concentrated margin pools due to payload potency requirements and complex conjugation chemistry. Bispecific antibodies represent the fastest-growing configuration as developers pursue simultaneous dual-target engagement. Monoclonal antibodies retain volume leadership in autoimmune and oncology maintenance settings where established manufacturing infrastructure supports cost-efficient supply.
FDA breakthrough therapy designation and EMA PRIME eligibility compress development timelines and shape trial design investments for developers. The EU AI Act introduces algorithmic transparency requirements that affect computational antibody discovery platforms seeking European market access. ISO 13485 quality management standards govern contract manufacturing organizations producing clinical-grade biologics across multiple jurisdictions. Stakeholders must monitor evolving biosimilar interchangeability standards and their impact on originator pricing power.
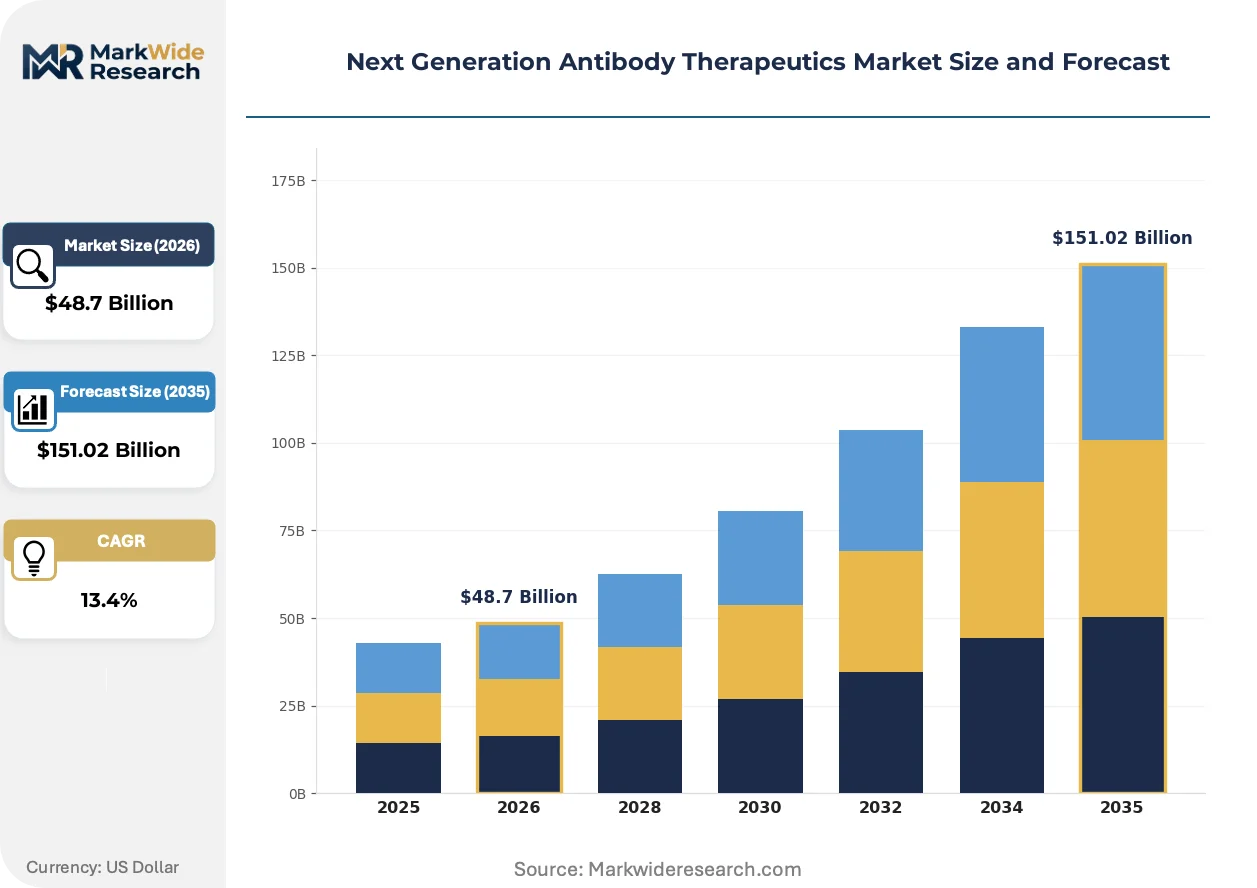
Market Dynamics
FDA breakthrough therapy designations and EMA PRIME eligibility are compressing clinical development timelines from decade-long cycles to six-to-eight-year windows, forcing developers to front-load manufacturing scale-up investments before Phase II data matures.
Growth Catalysts
- Accelerated Approval Pathways:FDA breakthrough therapy and EMA PRIME designations compress Phase I-to-approval timelines. Developers front-load CMC investments to capture priority review vouchers.
- Infusion Center Network Density:United States reimbursement infrastructure supports specialized oncology infusion networks. Bispecific antibodies with complex dosing schedules require site-of-care capabilities concentrated in major hospital systems.
- Computational Antibody Engineering:Machine learning platforms for epitope prediction and developability scoring reduce lead optimization cycles. Biotechs integrate AlphaFold-derived structural models into early discovery.
Market Restraints
- Payload-Linker Cost Concentration:Antibody-drug conjugates depend on cytotoxic payloads manufactured by a concentrated supplier base in Switzerland and Japan. Input cost volatility for auristatin and maytansinoid derivatives squeezes margin pools.
- Fc Engineering Patent Thickets:Half-life extension technologies via FcRn recycling enhancement face dense intellectual property landscapes. New entrants navigate licensing complexity with established platform patent holders.
- EMA Algorithmic Transparency Mandates:EU AI Act requirements for computational discovery platforms introduce documentation burdens. European market access delays for AI-designed antibody candidates extend regulatory timelines.
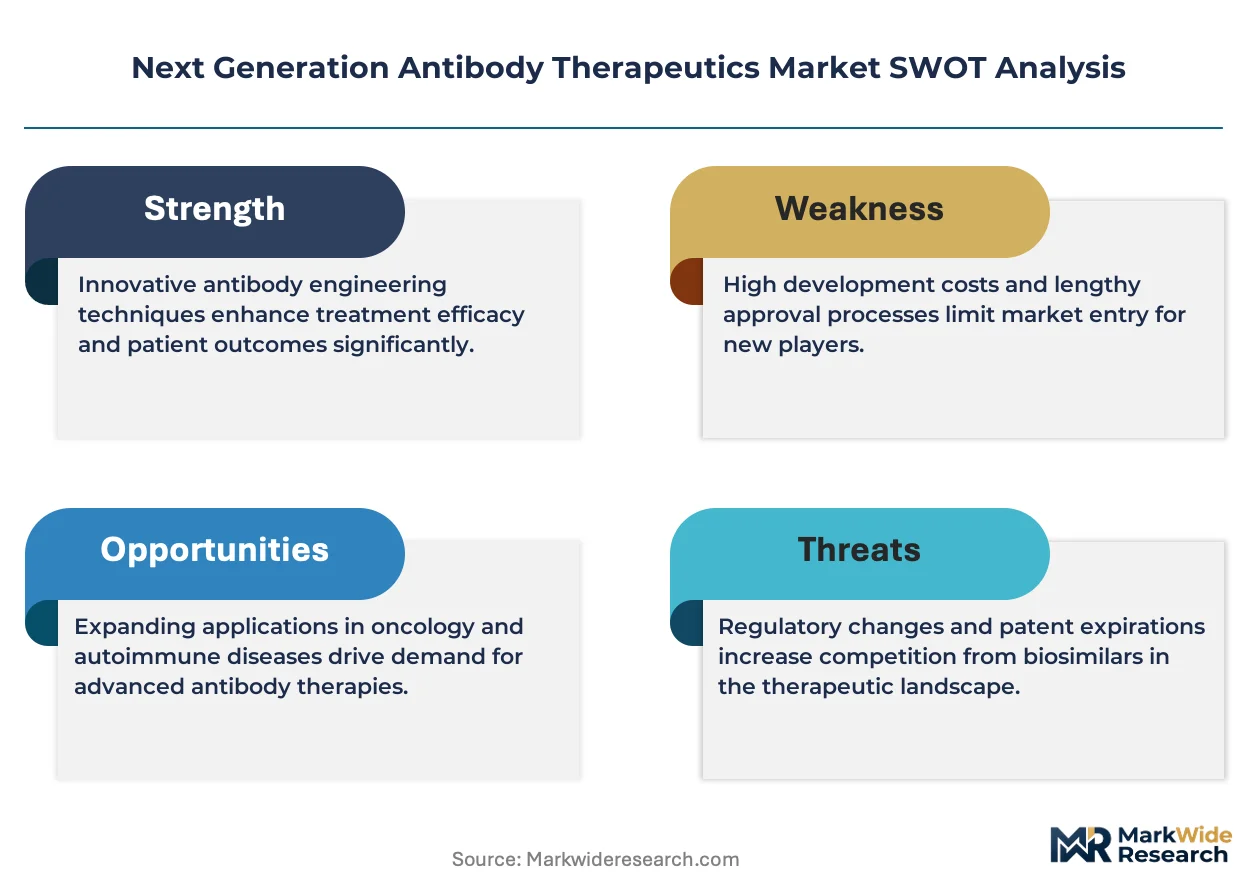
Strategic Opportunities
- Autoimmune Indication Expansion:Bispecific formats targeting IL-17 and IL-23 pathways address underpenetrated dermatology and gastroenterology segments. Chronic dosing requirements extend revenue duration beyond oncology.
- Companion Diagnostic Bundling:CDx-therapeutic integration creates prescribing stickiness. Diagnostic-antibody platform combinations capture premium positioning across payer formularies.
- Japan PMDA Sakigake Pathway:Japan's regenerative medicine and breakthrough therapy designation offers priority review for novel modalities. Developers establish early clinical presence in Tokyo-Osaka hospital networks.
Industry Challenges
- Cell Line Development Bottlenecks:Stable high-titer production cell lines for bispecific formats require 18-24 month timelines. CMC teams face capacity constraints at contract manufacturing organizations holding ISO 13485 certification.
- Biosimilar Interchangeability Uncertainty:Evolving FDA and EMA standards for originator-biosimilar substitution threaten pricing power for legacy monoclonal antibodies approaching patent expiry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Antibody Therapeutics Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $151.02 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Bispecific Antibodies, Antibody-Drug Conjugates, Fusion Proteins Therapy Area: Oncology, Autoimmune Disorders, Infectious Diseases, Neurological Disorders Delivery Mode: Subcutaneous, Intravenous, Oral, Intramuscular End User: Hospitals, Research Laboratories, Specialty Clinics, Pharmaceutical Companies |
| Companies Covered | F. Hoffmann-La Roche Ltd., AstraZeneca plc, Pfizer Inc., Bristol-Myers Squibb Company, Seagen Inc., Amgen Inc., Regeneron Pharmaceuticals Inc., Genmab A/S, Merck & Co Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Antibody Therapeutics Market Strategic Shifts
Modular antibody engineering platforms are collapsing the traditional boundary between discovery and manufacturing, enabling developers to retarget scaffolds across multiple indications without rebuilding core production infrastructure from first principles.
Site-specific conjugation chemistry via engineered cysteine residues and enzymatic ligation is electrifying antibody-drug conjugate development. Oncology departments at tertiary care centers in Germany and the United States are prioritizing ADCs with defined drug-to-antibody ratios for their predictable pharmacokinetic profiles. This precision is enabling payload escalation previously limited by off-target toxicity, compressing the safety-efficacy window that has constrained earlier generation conjugates.
EMA's Medical Device Regulation and the EU AI Act are converging to impose algorithmic transparency requirements on computational antibody discovery platforms. Developers deploying machine learning for epitope prediction must document training data provenance and model validation protocols. European market access for AI-designed candidates now requires supplementary technical documentation that extends regulatory submission preparation by six to twelve months.
Hospital procurement committees are consolidating antibody purchasing through integrated delivery networks that negotiate indication-specific bundles across oncology and immunology portfolios. Site-of-care economics now dominate therapeutic selection, with infusion center throughput and nursing labor intensity outweighing per-dose cost differentials. This behavioral shift is most visible in United States health systems where specialty pharmacy carve-outs concentrate purchasing authority within centralized pharmacy and therapeutics committees.
Next Generation Antibody Therapeutics Market Segmentation
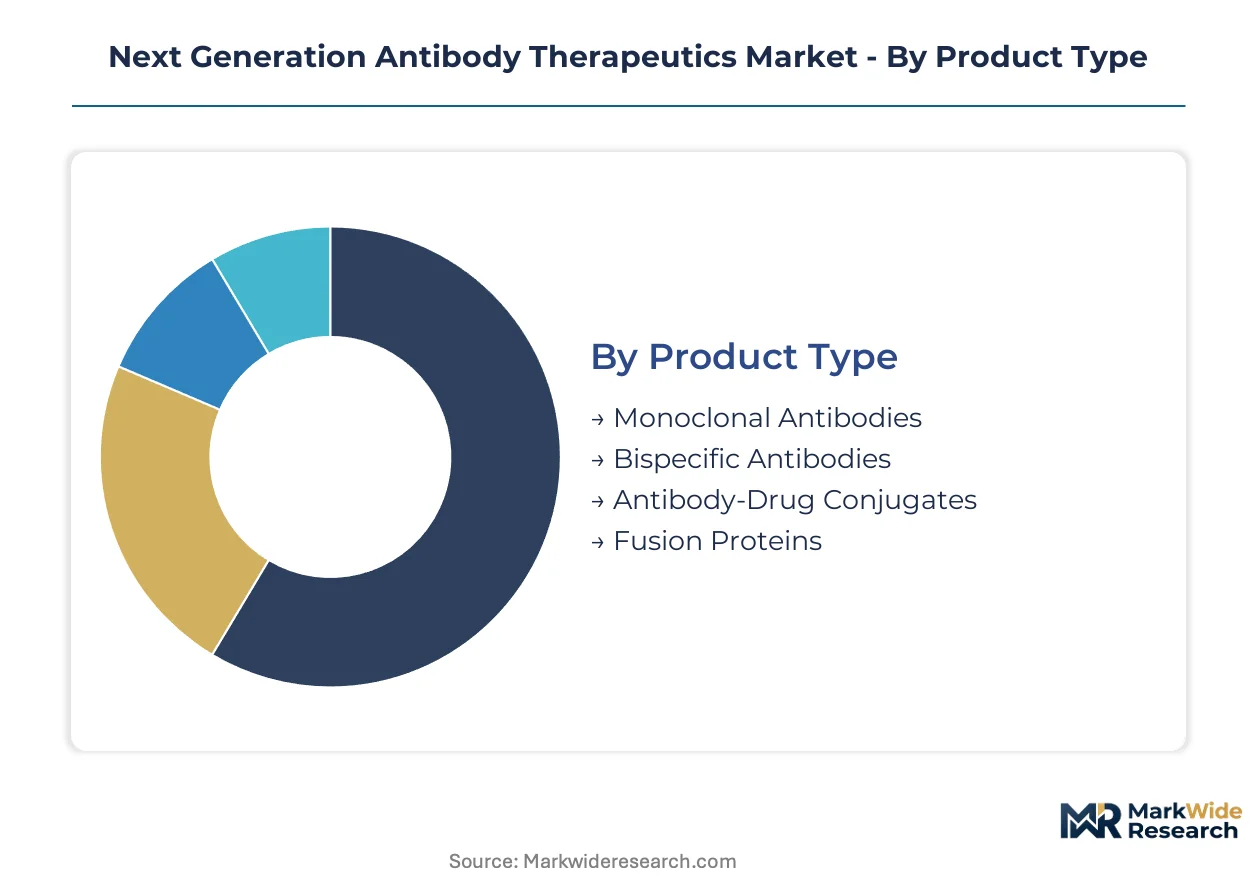
Segmentation in next generation antibody therapeutics determines manufacturing scale-up priorities, regulatory pathway selection, and site-of-care infrastructure investments. Product format and delivery mode choices cascade through clinical trial design, payer reimbursement negotiations, and hospital procurement committee evaluations.
Product Type:
Buyers differentiate by manufacturing complexity tolerance and payload potency requirements.
- Bispecific Antibodies:Engineered immunoglobulins engage dual antigens simultaneously through asymmetric heavy-light chain pairing or common light chain architectures. Demand concentrates in United States oncology infusion centers where complex dosing schedules align with specialized nursing capabilities and reimbursement infrastructure.
- Antibody-Drug Conjugates:Monoclonal antibodies tether cytotoxic payloads via cleavable or non-cleavable linkers, enabling targeted delivery to tumor microenvironments. Swiss and Japanese suppliers dominate auristatin and maytansinoid payload manufacturing, creating input cost concentration that squeezes margin pools for developers.
- Monoclonal Antibodies:Established manufacturing infrastructure supports cost-efficient supply for autoimmune maintenance and oncology settings.
- Fusion Proteins:Recombinant constructs combine antibody Fc domains with cytokine or receptor ligand moieties for extended half-life or dual mechanism activity.
Volume sits with monoclonal antibodies; growth tilts toward bispecific formats.
Therapy Area:
Revenue duration and dosing frequency separate chronic from acute therapeutic profiles.
- Oncology:Cytotoxic mechanisms dominate bispecific T-cell engagers and ADC pipelines, with FDA breakthrough therapy designations compressing development timelines. United States hospital systems prioritize site-of-care economics over per-dose cost differentials.
- Autoimmune Disorders:IL-17 and IL-23 pathway bispecifics address underpenetrated dermatology and gastroenterology segments with chronic dosing requirements.
- Infectious Diseases:Neutralizing antibody cocktails target respiratory and emerging pathogens through Fc-modified variants optimized for effector function.
- Neurological Disorders:Blood-brain barrier penetration challenges constrain antibody engineering approaches for neurodegenerative indications.
Margin concentration favors oncology; expansion trajectory steepest in autoimmune.
Delivery Mode:
Patient compliance and healthcare resource intensity drive route selection trade-offs.
- Intravenous:Infusion center networks in United States and Germany handle complex bispecific dosing with nursing supervision and adverse event monitoring capabilities.
- Subcutaneous:Self-administration formats reduce site-of-care burden for chronic autoimmune indications, extending addressable patient populations beyond hospital catchment areas.
- Intramuscular:Rapid depot release kinetics suit prophylactic infectious disease applications with lower potency requirements.
- Oral:Gastrointestinal degradation barriers limit current applicability, though FcRn-targeted delivery platforms under early development may eventually enable mucosal absorption.
Revenue pools center on intravenous; patient preference momentum builds behind subcutaneous.
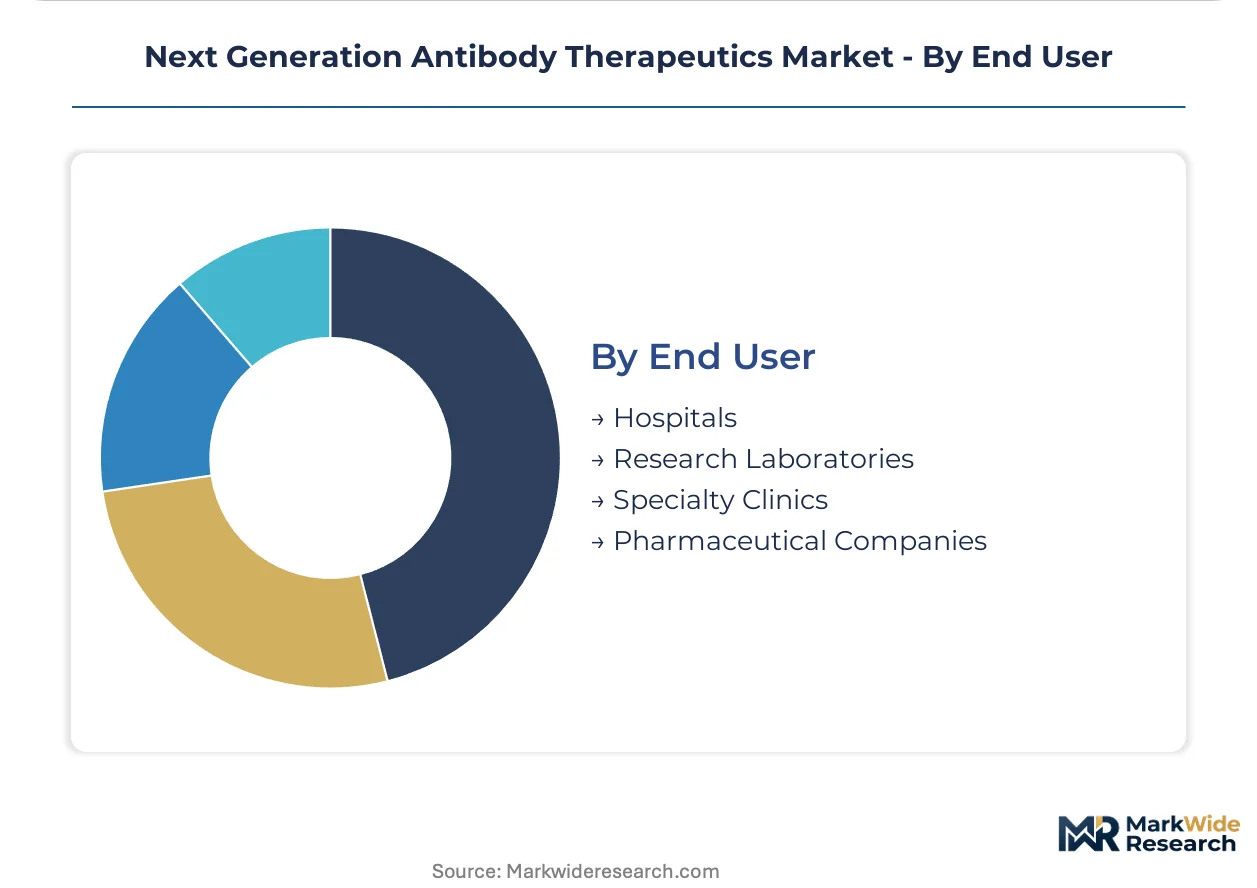
End User:
Purchasing authority and formulary control determine pricing power and competitive positioning.
- Hospitals:Integrated delivery networks in United States consolidate antibody purchasing across oncology and immunology portfolios, with pharmacy and therapeutics committees negotiating indication-specific bundles.
- Specialty Clinics:Dermatology and gastroenterology practices in Germany and Japan adopt subcutaneous bispecifics for chronic autoimmune management outside hospital infusion networks.
- Research Laboratories:Academic medical centers and contract research organizations source early-stage candidates for investigator-initiated trials and biomarker discovery programs.
- Pharmaceutical Companies:In-licensing and co-development partnerships concentrate among mid-cap biotechs seeking manufacturing scale-up capabilities from established platform holders.
Procurement volume aggregates at hospitals; growth opportunity concentrates in specialty clinic networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Switzerland and Japan for payload-linker chemistry, while consumption concentrates in United States hospital systems with specialized infusion infrastructure. This geographic split shapes regulatory strategy and supply chain investments across the forecast window.
United States
FDA breakthrough therapy designations compress Phase I-to-approval timelines for bispecific platforms. The 21st Century Cures Act provisions accelerate regenerative medicine approvals. Tertiary care centers in Boston, New York, and Houston anchor infusion network density for complex dosing regimens.
Germany
EMA centralized procedures enable simultaneous EU-wide market access for antibody-drug conjugates. The Medical Device Regulation imposes post-market surveillance requirements on companion diagnostic bundling. Heidelberg and Munich hospital networks prioritize site-specific conjugation chemistry for defined drug-to-antibody ratios.
Japan
PMDA Sakigake designation offers priority review for novel bispecific formats targeting solid tumors. The Pharmaceuticals and Medical Devices Act streamlines regenerative medicine approval pathways. Tokyo-Osaka hospital clusters concentrate early clinical presence for T-cell engager development.
Switzerland
Swissmedic maintains alignment with EMA standards while offering rapid scientific advice for ADC payload optimization. The country's dual bilateral agreements with EU and EFTA jurisdictions facilitate cross-border manufacturing. Basel and Zurich host concentrated supplier bases for auristatin and maytansinoid derivatives.
China
NMPA conditional approval pathways enable earlier market entry for locally manufactured bispecifics. The National Reimbursement Drug List expansion improves oncology therapy access. Shanghai and Suzhou biotech clusters attract foreign partnership investments for cell line development capabilities.
Next Generation Antibody Therapeutics Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across platform technology, manufacturing scale, and diagnostic integration dimensions. Market structure tilts toward consolidation at the top tier, with mid-cap biotechs occupying niche modality positions. Three archetypes dominate: vertically integrated pharmaceutical conglomerates with diagnostic arms, specialized antibody engineering platforms with half-life extension IP, and contract manufacturing organizations with ISO 13485 certification. Competitive moves center on strategic partnerships for cell line access and geographic licensing arrangements for priority review vouchers.
Among diversified pharmaceutical conglomerates, F. Hoffmann-La Roche Ltd. and AstraZeneca plc exemplify diagnostic-therapeutic integration strategies that capture premium positioning across payer formularies. Bristol-Myers Squibb Company occupies a position within the T-cell engager manufacturing tier, while Genmab A/S represents the specialized half-life extension archetype with differentiated Fc engineering capabilities. These anchors illustrate how competitive positioning flows from platform patent depth and manufacturing scale rather than single-product differentiation.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| AstraZeneca plc |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| Seagen Inc. |
| Amgen Inc. |
| Regeneron Pharmaceuticals Inc. |
| Genmab A/S |
| Merck & Co Inc. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up contract manufacturing specialists have consolidated biologics production capacity across Switzerland and Japan, tightening supply discipline and anchoring premium pricing for antibody-drug conjugate payloads. Their ownership structures prioritize yield optimization over volume expansion, translating concentrated supply into sustained margin capture for originator developers.
Pricing Analysis
Cost-down pressure on bispecific antibody developers accelerates because cell line development timelines stretch eighteen to twenty-four months while FDA breakthrough therapy designations compress approval windows. Three-tier pricing structure across premium originator, authorized biosimilar, and emerging market supply tiers separates Roche's diagnostic-integrated bundles from mid-tier T-cell engagers and economy-positioned autoimmune maintenance therapies. Price differentiation hinges on ISO 13485 certification status and companion diagnostic bundling depth. Hospital procurement committees in United States integrated delivery networks exhibit highest price sensitivity, prioritizing site-of-care economics over per-dose differentials.
Supply Chain Analysis
Returns and refurbishment flows are negligible in biologics supply chains, shifting risk management focus to cold-chain integrity and batch release timing. Payload-linker chemistry concentrates in Switzerland, Japan, and select United States facilities, drawing from auristatin and maytansinoid derivatives manufactured by consolidated supplier bases. Stable high-titer production cell lines and specialized conjugation equipment constitute critical input dependencies. Single-source vulnerability pervades cytotoxic payload supply, with tariff exposure minimal but regulatory inspection delays at Swissmedic and PMDA facilities creating chokepoints. Distribution runs through specialized oncology infusion networks and hospital pharmacy channels rather than traditional wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell line development bottlenecks at ISO 13485-certified contract manufacturers prop pricing power for developers with captive capacity, framing this market as supply-constrained despite accelerating clinical demand.
For Market Incumbents: Anticipate biosimilar interchangeability rulings from FDA and EMA by securing diagnostic-therapeutic bundling contracts that create formulary stickiness. Defensive consolidation through backward integration into payload-linker chemistry reduces auristatin supply vulnerability. Priority lever: manufacturing scale-up in Switzerland or Japan to capture priority review vouchers from PMDA Sakigake and FDA breakthrough pathways. For New Entrants and Emerging Players: The mid-tier pricing gap between premium bispecifics and economy monoclonals creates entry space for subcutaneous autoimmune bispecifics targeting dermatology and gastroenterology practices outside hospital infusion networks. White-space targets include IL-17 and IL-23 pathway candidates with reduced dosing frequency enabled by FcRn recycling enhancement. Go-to-market angle: specialty clinic partnerships in Germany and Japan bypassing centralized hospital procurement. For Investors and Strategic Acquirers: FDA breakthrough therapy designation acceleration for T-cell engagers is the leading indicator that manufacturing capacity scarcity will deepen, favoring platform-holding mid-caps with cell line development capabilities over single-asset developers. Long-term viability concentrates on backward-integrated specialists with half-life extension IP and diagnostic partnerships. Acquisition target archetype: bispecific platform holders with validated common light chain architectures. Signal to monitor: PMDA Sakigake approvals for novel modalities as predictor of Japan market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captures FDA priority review vouchers by front-loading CMC investments before Phase II data matures. |
| Companion Diagnostic Bundling | Locks in formulary positioning across United States payer networks through CDx-therapeutic integration. |
| Regulatory Approval Pathway | Compresses timelines via EMA PRIME eligibility and PMDA Sakigake designation for bispecific platforms. |
| Backward Integration | Reduces payload-linker cost volatility by securing auristatin supply from Swiss and Japanese suppliers. |
| Clinical Trial Advancement | Validates subcutaneous dosing formats for autoimmune expansion beyond oncology infusion centers. |
Study Parameters
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Bottom-up patient-flow modeling and top-down revenue triangulation validated segmentation outputs across product format, therapy area, and delivery mode dimensions.
Historical approval timelines and regulatory panel input cross-referenced to derive expansion trajectories across the projection horizon. Segmentation dimensions modeled include antibody format class, target indication, administration route, and regional regulatory cluster. CAGRs reflect patient population penetration curves, pricing elasticity by buyer archetype, and manufacturing capacity absorption rates.
Inputs from FDA, EMA, and PMDA regulatory databases were available through the study window; gaps in early-stage pipeline disclosure and confidential manufacturing contracts introduce uncertainty bands around capacity expansion timing. Forecasts reflect assumptions on accelerated approval pathway utilization and biosimilar interchangeability standards. Practitioners should monitor PMDA Sakigake designation rates and EU AI Act algorithmic transparency enforcement for early signals of regulatory timeline compression or extension.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Combination Antibody Therapy Market
Biopharmaceuticals
Mammalian Derived Proteins Market
Biopharmaceuticals
France Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Drug Resistant Pulmonary Tuberculosis Market
Biopharmaceuticals
Anti-Neprilysin Market
Biopharmaceuticals
Middle East and Africa Plasma Fractionation Market
Biopharmaceuticals
Octreotide Market
Biopharmaceuticals
Asia-Pacific Plant-Based Biologics Market
Biopharmaceuticals
Oseltamivir Market
Biopharmaceuticals
Canada Generic Drug Market
Biopharmaceuticals
Influenza Vaccine Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Insulin Market
Biopharmaceuticals
Daptomycin Market
Biopharmaceuticals
Cancer Drug Market
Biopharmaceuticals
Lupus Nephritis Market