
 Global Kinase Inhibitors Market | 2026-2036
Global Kinase Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Kinase Inhibitors Market Foresight
Companion diagnostic testing revenue is reconfiguring how pharmaceutical firms capture value across the kinase inhibitor value chain. AstraZeneca plc leverages its oncology portfolio breadth to anchor positioning in EGFR and PARP combination strategies. Novartis AG sustains leadership in targeted therapy development through its established hematology franchise. Pfizer Inc. competes via manufacturing scale and global distribution infrastructure for small-molecule kinase programs.
Kinase inhibitors are small-molecule or biologic agents that selectively block ATP-binding sites on protein kinases, typically exhibiting IC50 values in the nanomolar range against specific oncogenic signaling pathways; they serve primarily to interrupt aberrant cell proliferation in malignant and autoimmune conditions. Tyrosine kinase inhibitors occupy the dominant commercial position due to extensive validation in solid tumor indications, while multi-kinase inhibitors represent the fastest-expanding category as resistance mechanisms drive demand for broader target coverage. Among therapy areas, oncology commands the primary margin pool, though immunology applications are gaining traction as JAK and SYK inhibitors secure approvals beyond cancer.
The FDA maintains stringent chemistry, manufacturing, and controls requirements that shape clinical trial design and commercial launch timelines for kinase inhibitor developers. EMA's centralized marketing authorization process determines European access, while China's NMPA accelerated review pathways attract multinational sponsors seeking earlier entry. Japan's PMDA orphan drug designation system creates additional regulatory incentives for niche kinase targets. Stakeholders must monitor evolving bioequivalence standards for biosimilar kinase inhibitors and the shifting reimbursement criteria for combination regimens across major markets.
Market Dynamics
Resistance mutation profiles in EGFR and ALK-positive non-small cell lung carcinoma are compressing first-line therapy durations and forcing developers to front-load combination trial investments. This molecular evolution pressure is restructuring clinical development budgets across the entire oncology pipeline.
Growth Catalysts
- FDA Accelerated Approval Pathway:The breakthrough therapy designation compresses Phase II-to-launch timelines for kinase inhibitors targeting unmet oncologic needs. Sponsors leverage this to secure conditional market entry based on surrogate endpoints.
- Companion Diagnostic Integration:Biomarker-driven patient stratification is expanding addressable populations for targeted therapies. Pathology laboratories are embedding next-generation sequencing into standard-of-care workflows.
- China NMPA Priority Review:The innovative drug approval channel attracts multinational sponsors seeking earlier access to the world's second-largest pharmaceutical market. Domestic biotechnology firms are leveraging this to fast-track novel kinase targets.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Synthetic route complexity for multi-step kinase scaffolds concentrates manufacturing among specialized contract development organizations in India and China. Geopolitical friction threatens supply continuity.
- Patent Cliff Dynamics:Imatinib and erlotinib generic erosion has compressed pricing power for follow-on agents in chronic myeloid leukemia and lung cancer. Payers are demanding equivalence demonstrations before formulary inclusion.
- Cardiotoxicity Surveillance Requirements:EMA's extended pharmacovigilance mandates for BCR-ABL and VEGF inhibitors impose post-market monitoring costs that deter development of marginal efficacy candidates.
Strategic Opportunities
- Central Nervous System Penetration:Brain metastasis indications remain underserved due to blood-brain barrier limitations. Second-generation EGFR and ALK inhibitors with improved CNS exposure are capturing this white space.
- JAK Inhibitor Expansion:Rheumatoid arthritis and atopic dermatitis applications are diversifying revenue beyond oncology. Dermatology and gastroenterology prescribing is accelerating as oral alternatives to biologic injections.
- Japan PMDA Orphan Designation:Rare kinase-driven malignancies qualify for tax incentives and extended exclusivity. Sponsors are prioritizing niche targets with defined patient registries.
Industry Challenges
- Translational Pharmacology Talent Scarcity:The specialized skill set bridging structural biology and clinical pharmacokinetics commands premium compensation. Contract research organizations report 18-month backlogs for experienced kinase program leads.
- Biosimilar Bioequivalence Complexity:Large-molecule kinase inhibitors face analytical characterization challenges that prolong development timelines. Reference product variability complicates immunogenicity risk assessment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Kinase Inhibitors Market |
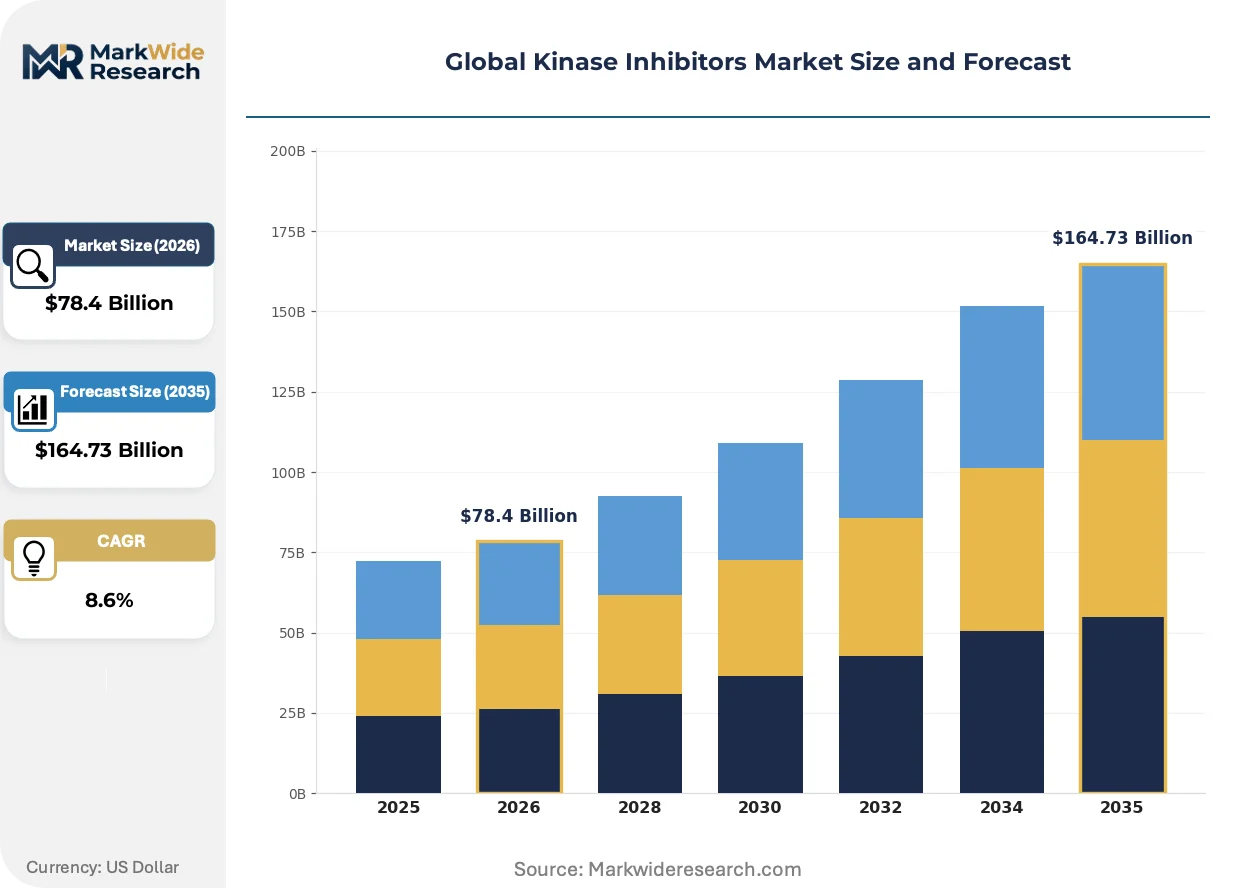
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tyrosine Kinase Inhibitors, Serine Threonine Kinase Inhibitors, Lipid Kinase Inhibitors, Multi-Kinase Inhibitors Therapy Area: Oncology, Immunology, Neurology, Inflammation, Cardiovascular Diseases End User: Research Laboratories, Pharmaceutical Companies, Biotechnology Firms, Academic Institutions Delivery Mode: Oral, Intravenous, Subcutaneous, Topical |
| Companies Covered | AstraZeneca plc, Novartis AG, Pfizer Inc., F. Hoffmann-La Roche Ltd, Bristol Myers Squibb Company, AbbVie Inc., Bayer AG, Takeda Pharmaceutical Company Limited, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Kinase Inhibitors Market Shifts & Advancements
Allosteric inhibition mechanisms and covalent binding strategies are displacing orthosteric ATP-competitive approaches across the discovery landscape. These modalities promise improved selectivity profiles against kinases with high sequence homology.
Covalent kinase inhibitors are collapsing the therapeutic index advantage of traditional reversible binding agents. Oncology-focused biotechnology firms are advancing irreversible EGFR and BTK candidates into registrational trials. The FDA's chemistry manufacturing controls guidance is adapting to accommodate reactive warhead specifications.
EMA's centralized marketing authorization process is harmonizing bioequivalence standards for kinase inhibitor generics across member states. The MDR's strengthened clinical evidence requirements are elevating post-approval study commitments. Hematology-oncology departments in Germany and France are restructuring formulary committees to evaluate real-world evidence submissions.
Hospital procurement consortia are consolidating purchasing power for oral oncology agents through tender-based frameworks. United States academic medical centers are displacing traditional wholesale distribution with direct manufacturer arrangements. China's volume-based procurement program is compressing net prices for mature kinase inhibitor categories.
Global Kinase Inhibitors Market Segmentation
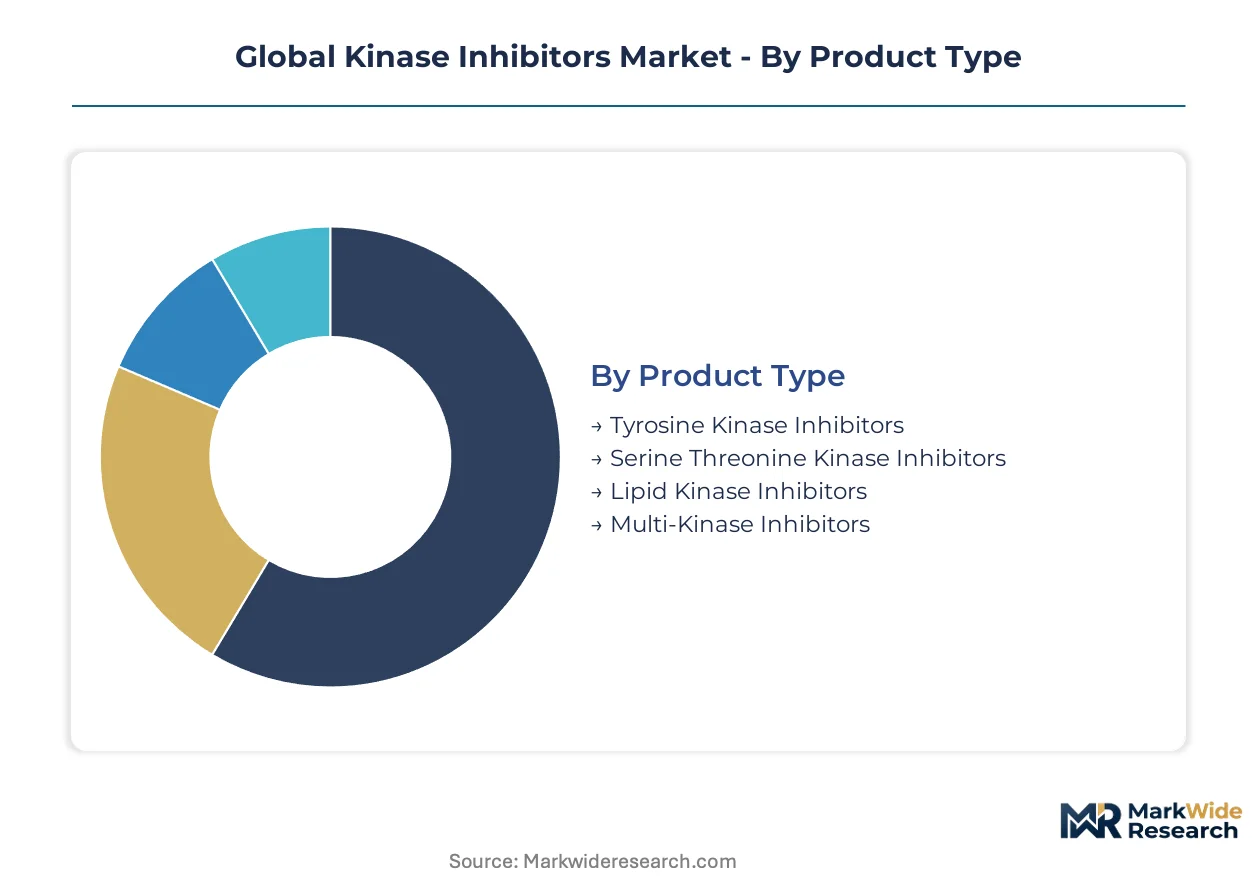
Kinase inhibitor commercialization demands precise segment alignment between molecular target profiles and clinical deployment settings. Developers structure portfolio investments around therapy area concentration and delivery mode preferences that dictate reimbursement pathways.
Product Type:
The use-case spectrum spans targeted monotherapy to broad-spectrum intervention against resistance mechanisms.
- Tyrosine Kinase Inhibitors:ATP-competitive small molecules targeting EGFR, ALK, and BCR-ABL dominate solid tumor and hematologic malignancy protocols. Hospital networks in the United States prioritize these agents for first-line lung and leukemia regimens where companion diagnostic infrastructure supports patient stratification.
- Multi-Kinase Inhibitors:Polypharmacology agents simultaneously block VEGFR, PDGFR, and c-KIT signaling axes to circumvent single-target resistance. Demand concentrates in Germany and China where progressive disease protocols favor broader target coverage over sequential monotherapy.
- Serine Threonine Kinase Inhibitors:Modulators of mTOR, AKT, and CDK pathways serve combination strategies in breast and renal cell carcinoma.
- Lipid Kinase Inhibitors:PI3K isoform-selective agents address hematologic malignancies with differentiated safety profiles from pan-PI3K approaches.
Established volume favors Tyrosine Kinase Inhibitors; emerging adoption favors Multi-Kinase Inhibitors.
Therapy Area:
Cost tier stratification separates premium oncology indications from expanding immunology applications.
- Oncology:Solid tumor and hematologic malignancy applications command the primary revenue pool with concentrated prescribing in academic medical centers. The FDA's accelerated approval pathway reinforces development prioritization for breakthrough-designated kinase programs in lung, breast, and colorectal cancers.
- Immunology:JAK and SYK inhibitors for rheumatoid arthritis, atopic dermatitis, and inflammatory bowel disease represent the steepest expansion trajectory. Dermatology and gastroenterology practices in France and Japan are displacing biologic injections with oral kinase alternatives.
- Neurology:CNS-penetrant candidates target neurodegenerative mechanisms with blood-brain barrier optimization as the critical technical barrier.
- Inflammation:Beyond immunology, broader anti-inflammatory applications in psoriasis and hidradenitis suppurativa are gaining formulary traction.
- Cardiovascular Diseases:Cardioprotective kinase modulation remains exploratory with toxicity surveillance requirements constraining development investment.
Margin concentration anchors Oncology; volume expansion potential sits with Immunology.
End User:
Customer type determines regulatory engagement intensity and procurement pathway structure.
- Pharmaceutical Companies:Integrated developers internalize kinase programs from discovery through commercialization, leveraging manufacturing scale and global distribution infrastructure for small-molecule portfolios.
- Biotechnology Firms:Specialized innovators advance novel target hypotheses and covalent binding modalities, partnering with contract research organizations for translational pharmacology capabilities.
- Research Laboratories:Academic and institutional screening facilities demand tool compounds and probe libraries for target validation studies.
- Academic Institutions:Investigator-initiated trials and early-phase clinical research units require flexible supply arrangements for experimental kinase combinations.
Procurement scale favors Pharmaceutical Companies; innovation sourcing favors Biotechnology Firms.
Delivery Mode:
Application setting dictates route selection between outpatient convenience and inpatient control.
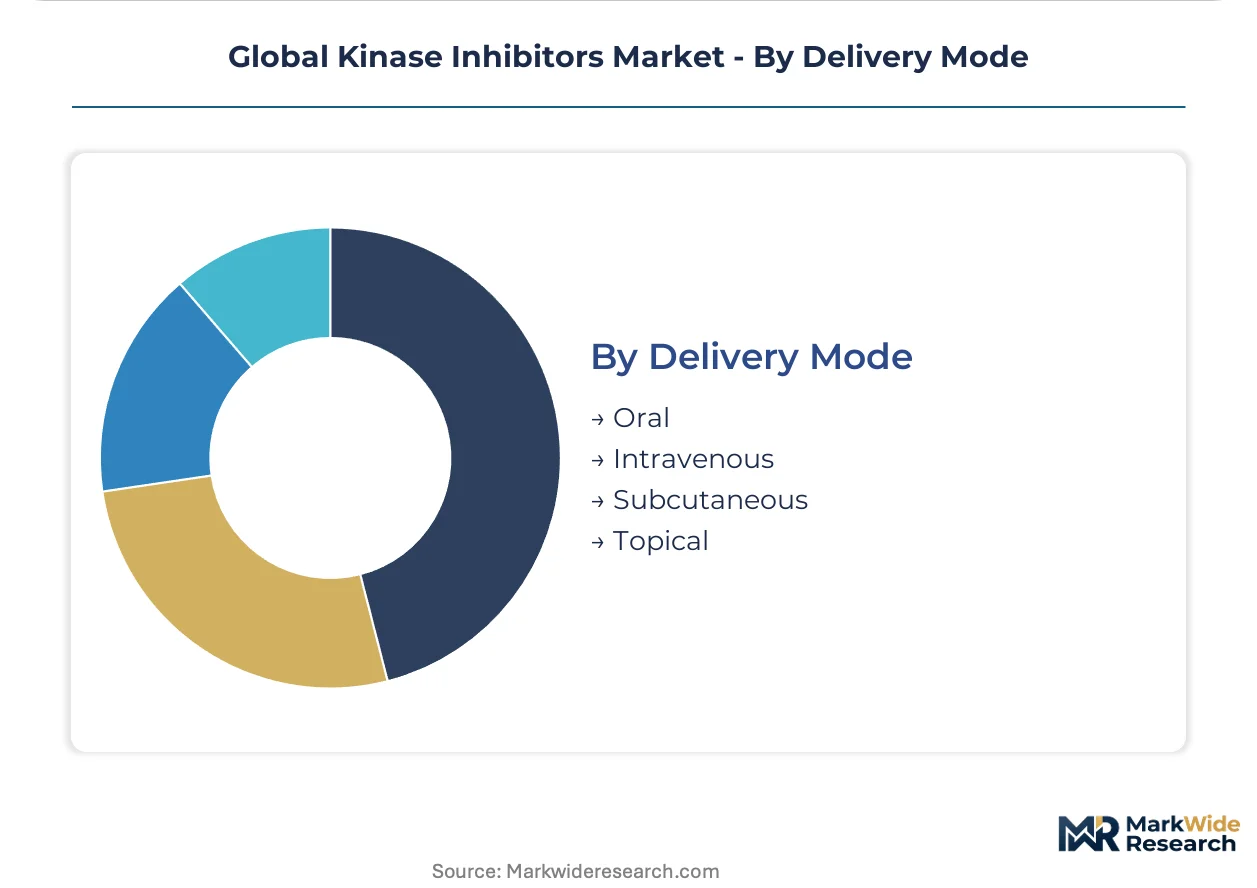
- Oral:Small-molecule kinase inhibitors achieve patient preference and adherence advantages in chronic administration settings. China's volume-based procurement program targets mature oral categories for price compression.
- Intravenous:Hospital-administered biologic kinase agents and high-dose small molecules suit acute intervention and combination protocols requiring therapeutic drug monitoring.
- Subcutaneous:Self-administration potential for select biologic formats competes with oral convenience in rheumatology and dermatology.
- Topical:Localized kinase inhibition for dermatologic conditions minimizes systemic exposure though formulation challenges limit target breadth.
Patient preference momentum favors Oral; clinical control requirements sustain Intravenous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic manufacturing for kinase inhibitor active pharmaceutical ingredients concentrates among specialized contract development organizations in India and China, while consumption clusters in markets with mature precision medicine infrastructure and favorable reimbursement frameworks.
United States
Oncology departments across academic medical centers in Boston, Houston, and New York are expanding precision medicine programs with embedded next-generation sequencing workflows. FDA's breakthrough therapy designation compresses Phase II-to-launch timelines for novel kinase targets. The Research Triangle Park cluster in North Carolina anchors translational pharmacology capabilities bridging structural biology to clinical development.
China
Domestic biotechnology firms in Shanghai and Suzhou are leveraging NMPA's innovative drug approval channel to fast-track novel kinase targets for lung and hematologic malignancies. Volume-based procurement programs compress net prices for mature oral kinase inhibitor categories. The Zhangjiang Hi-Tech Park concentrates discovery-stage biotechs advancing covalent binding modalities and allosteric inhibition strategies.
Germany
Hospital procurement consortia in Bavaria and North Rhine-Westphalia are consolidating purchasing power for oral oncology agents through tender-based frameworks. EMA's centralized marketing authorization process determines European access for kinase inhibitor developers seeking reimbursement across member states. The Heidelberg-Mannheim corridor anchors hematology-oncology research units restructuring formulary committees to evaluate real-world evidence submissions.
Japan
Dermatology and gastroenterology practices in Tokyo and Osaka are displacing biologic injections with oral JAK inhibitors for rheumatoid arthritis and atopic dermatitis. PMDA's orphan drug designation system creates tax incentives and extended exclusivity for rare kinase-driven malignancies. The Kobe biomedical cluster concentrates specialized contract research organizations supporting translational pharmacology for CNS-penetrant candidates.
Switzerland
Integrated pharmaceutical developers in Basel leverage manufacturing scale and global distribution infrastructure for small-molecule kinase portfolios. Swissmedic's marketing authorization process aligns with EMA standards while offering streamlined pathways for priority review. The Basel-Zurich corridor anchors hematology franchise operations sustaining leadership in targeted therapy development through established clinical trial networks.
Global Kinase Inhibitors Market Competitive Landscape
Integrated pharmaceutical conglomerates and specialized oncology biotechnology firms split the market based on manufacturing scale versus target innovation capabilities. The vendor base concentrates around three strategic archetypes: diversified majors with global distribution infrastructure, mid-cap hematology specialists with established clinical trial networks, and emerging biotechs advancing covalent and allosteric modalities. Dominant competitive moves include strategic partnerships for companion diagnostic integration and geographic expansion through priority review pathways in China and Japan.
Among diversified pharmaceutical majors, AstraZeneca plc and Novartis AG exemplify contrasting strategic positions within the competitive structure. AstraZeneca anchors EGFR and PARP combination strategies through portfolio breadth in solid tumor indications. Novartis occupies a position sustaining leadership in targeted therapy development through its established hematology franchise. Pfizer Inc. represents the scale-driven archetype competing via manufacturing infrastructure for small-molecule kinase programs.
| Leading Market Players |
|---|
| AstraZeneca plc |
| Novartis AG |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd |
| Bristol Myers Squibb Company |
| AbbVie Inc. |
| Bayer AG |
| Takeda Pharmaceutical Company Limited |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Overcapacity in China's synthetic API sector is compressing contract manufacturing margins and forcing kinase inhibitor developers to renegotiate long-term offtake terms, while simultaneously creating procurement leverage for hospital networks in Germany and the United States.
Pricing Analysis
Companion diagnostic bundling drives lifetime value capture across the kinase inhibitor value chain. Three-tier pricing structure across premium, standard, and economy levels stratifies by biomarker complexity and regulatory pathway—FDA breakthrough-designated agents command premium positioning while volume-based procurement in China compresses mature oral categories. Cost compression in first-generation tyrosine kinase inhibitors is intensifying because of imatinib and erlotinib generic erosion. Academic medical centers exhibit lowest price sensitivity due to formulary autonomy; tender-based hospital consortia in Germany demonstrate highest sensitivity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for multi-step kinase scaffolds. Active pharmaceutical ingredient synthesis concentrates in India and China, with specialized contract development organizations in Hyderabad and Suzhou anchoring capacity. Manufacturing draws from fluorinated intermediates, palladium catalysts, and high-purity solvents. Single-source vulnerability persists for cryogenic reaction steps requiring specialized equipment. Distribution runs through wholesale distributors for oral oncology agents and direct manufacturer arrangements for hospital-administered biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kinase inhibitor market functions as a defensive-moat structure where regulatory entrenchment—specifically FDA accelerated approval pathways and companion diagnostic co-development requirements—creates substantial barriers to rapid competitive displacement.
For Market Incumbents: Harden manufacturing scale advantages by securing captive supply of fluorinated intermediates through backward integration into Indian API partnerships. Deepen companion diagnostic integration to lock in formulary positioning against emerging covalent binding modalities. The threat of biosimilar kinase inhibitors with complex immunogenicity profiles demands preemptive bioequivalence investment. For New Entrants and Emerging Players: Pursue central nervous system penetration as the most penetrable white space, where blood-brain barrier optimization remains technically underserved for EGFR and ALK-driven brain metastases. Target Japan's orphan drug designation pathway for rare kinase-driven malignancies with defined patient registries. A go-to-market angle anchored to PMDA priority review and academic medical center investigator-initiated trials accelerates clinical validation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across oral small-molecule kinase programs as synthetic route efficiencies mature, while biologic kinase inhibitor development requires sustained high capital deployment. Long-term viability favors platforms with demonstrated CNS exposure capabilities and established hematology franchise infrastructure. The acquisition target archetype is mid-cap biotechnology firms with covalent binding patent estates and translational pharmacology talent depth. The signal to watch is NMPA approval velocity for domestic Chinese innovators as an indicator of competitive intensity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Biomarker-driven stratification expands addressable populations for EGFR and ALK inhibitors in lung cancer protocols. |
| Covalent Binding Modality Advancement | Irreversible warhead chemistry collapses therapeutic index advantages of traditional reversible ATP-competitive agents. |
| Central Nervous System Optimization | Brain metastasis indications capture underserved demand as second-generation inhibitors improve blood-brain barrier penetration. |
| China NMPA Priority Review Navigation | Innovative drug approval channel accelerates entry into the world's second-largest pharmaceutical market for novel targets. |
| Japan PMDA Orphan Designation Pursuit | Tax incentives and extended exclusivity for rare kinase-driven malignancies enhance niche target economics. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, formulary directors at academic medical centers, and payer access specialists. Secondary validation drew from FDA filings, EMA centralized marketing authorization submissions, ClinicalTrials.gov protocol registries, and hospital procurement databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing across the analysis window.
Calibration against historical approval timelines and pricing trajectories informed the analytical framework. Segmentation dimensions modeled include product type, therapy area, delivery mode, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year estimates. Forecast inputs incorporated resistance mutation epidemiology and companion diagnostic penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic biotechnology firms with NMPA fast-track capabilities would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Thrombin Market
Biopharmaceuticals
Progesterone Market
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
Diabetes Drugs Market
Biopharmaceuticals
Pruritus Therapeutics Market
Biopharmaceuticals
Antimycobacterial Drugs Market
Biopharmaceuticals
Vaccine Adjuvants Market
Biopharmaceuticals
Latin America G-CSF/ PEG-G-CSF Market
Biopharmaceuticals
Linaclotide API Market
Biopharmaceuticals
Cancer Drug Market
Biopharmaceuticals
Mammalian Derived Proteins Market
Biopharmaceuticals
Europe Monoclonal Antibodies Market
Biopharmaceuticals
Cephalosporin Market
Biopharmaceuticals
Tuberculosis Drugs Market
Biopharmaceuticals
Thailand Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Anti-Infective Drugs Market