
 Global Resistant Pseudomonas Aeruginosa Infections Drugs Market | 2026-2036
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market Foresight
The R&D funding gap between large-cap developers and mid-tier firms is bifurcating competitive trajectories in this space. Pfizer Inc. leverages its established anti-infectives infrastructure to sustain late-stage clinical pipelines across multiple drug classes. Merck & Co Inc. anchors its position through specialized carbapenem programs targeting ventilator-associated pneumonia. Bristol Myers Squibb Co. competes by concentrating manufacturing scale on polymyxin derivatives for critical care settings.
Resistant Pseudomonas aeruginosa infections drugs comprise antimicrobial agents engineered to overcome efflux pump mechanisms, biofilm formation, and enzymatic degradation characteristic of this Gram-negative pathogen, with minimum inhibitory concentration thresholds typically requiring enhanced dosing protocols or combination regimens to achieve therapeutic efficacy in immunocompromised hosts. These pharmaceuticals serve primarily to reduce mortality in hospital-acquired infections where standard antibiotic therapy fails. Carbapenems and polymyxins currently occupy the deepest margin pools due to their last-resort clinical positioning in intensive care units. Beta-lactam combinations represent the fastest-expanding category as developers engineer beta-lactamase inhibitors to restore susceptibility against emerging resistant strains.
The FDA's Qualified Infectious Disease Product designation and EMA's PRIME eligibility pathway reshape development economics by extending market exclusivity and accelerating review timelines for novel anti-pseudomonal agents. WHO's priority pathogens list intensifies public funding flows toward resistant Gram-negative therapeutics, directly influencing national reimbursement policies across OECD markets. Stakeholders must monitor regulatory divergence between accelerated approval frameworks and post-market evidence requirements as they calibrate portfolio risk against commercialization timelines.
Market Dynamics
Carbapenem resistance rates exceeding 30% in tertiary care centers across the United States, Germany, and Japan are forcing protocol revisions toward combination beta-lactam therapies. This structural pressure is compressing development timelines for novel anti-pseudomonal agents while expanding FDA QIDP designations.
Growth Catalysts
- FDA QIDP Program:Extended market exclusivity provisions accelerate commercialization timelines for developers targeting multidrug-resistant Gram-negative pathogens.
- Intensive Care Units:Rising ventilator-associated pneumonia incidence drives protocol adoption of polymyxin-carbapenem combinations in tertiary hospitals.
- WHO Priority Pathogens List:Public funding reallocations toward resistant Pseudomonas aeruginosa therapeutics strengthen reimbursement frameworks in OECD markets.
Market Restraints
- API Supply Concentration:Polymyxin active pharmaceutical ingredient production concentrates in Chinese and Indian manufacturing clusters, creating single-source vulnerability.
- Clinical Trial Costs:Patient recruitment for resistant infection studies requires expanded site networks across multiple jurisdictions, elevating per-patient expenditures.
- Carbapenem Stewardship Programs:Hospital antibiotic committees impose restrictive authorization protocols that compress utilization rates for novel agents.
Strategic Opportunities
- Inhaled Antibiotic Delivery:Nebulized formulations for cystic fibrosis patients create differentiated positioning against intravenous-standard therapy.
- Biofilm Disruption Technologies:Adjunctive therapies targeting sessile bacterial colonies address the 65% treatment failure rate in device-associated infections.
- Japan's Sakigake Designation:Priority review vouchers for anti-pseudomonal agents reduce regulatory timelines for developers entering Asian markets.
Industry Challenges
- Microbiology Specialist Shortage:Hospital-based infectious disease pharmacists with resistance profiling expertise remain critically underrepresented in emerging markets.
- Diagnostic-therapy Integration:Rapid susceptibility testing platforms require capital deployment and workflow reconfiguration that delays protocol implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Resistant Pseudomonas Aeruginosa Infections Drugs Market |
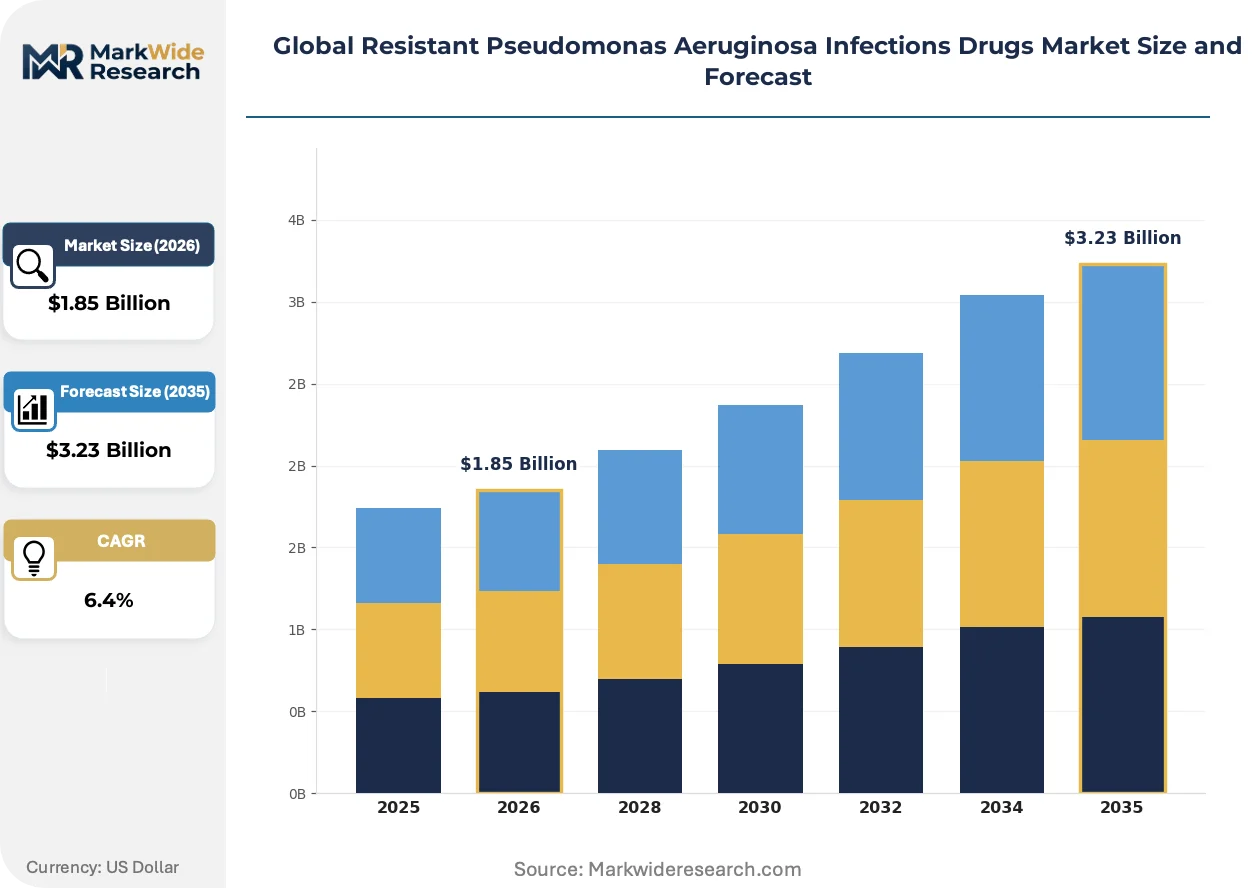
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Beta-lactams, Aminoglycosides, Fluoroquinolones, Polymyxins, Carbapenems Infection Type: Ventilator-associated Pneumonia, Urinary Tract Infection, Bacteremia, Skin & Soft Tissue Infection, Burn Wound Infection Patient Care Setting: Intensive Care Units, General Wards, Outpatient Facilities, Long-term Care Centers, Surgical Units Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Wholesale Distributors, Specialty Clinics |
| Companies Covered | AbbVie Inc., Bristol Myers Squibb Co., Teva Pharmaceutical Industries Ltd, Pfizer Inc., Merck & Co Inc., Novartis AG, Johnson & Johnson, AstraZeneca, Janssen Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market Shifts & Advancements
Next-generation beta-lactamase inhibitors are restructuring competitive positioning by restoring susceptibility against serine- and metallo-beta-lactamase producing strains. These molecular advances are compressing the clinical utility window for traditional carbapenem monotherapy.
Avibactam-relebactam combinations are decomposing the historical dominance of meropenem and imipenem in ventilator-associated pneumonia protocols. Academic medical centers in the United States and Germany are adopting these agents as empiric first-line therapy for suspected carbapenem-resistant infections. This shift is decomposing the market share concentration of legacy beta-lactams while elevating pricing power for protected combination products.
EMA's PRIME eligibility pathway is compressing regulatory review timelines for novel anti-pseudomonal agents targeting priority pathogen designations. Developers receiving PRIME status gain accelerated assessment and enhanced scientific dialogue with rapporteurs. European intensive care units are responding by pre-qualifying these agents for hospital formularies ahead of formal reimbursement decisions.
Hospital procurement committees are consolidating antibiotic purchasing through centralized therapeutic class reviews that favor broad-spectrum agents with resistance suppression data. This consolidation is displacing fragmented physician-directed prescribing in favor of protocol-driven formulary adherence. The transformation is most visible in United States integrated delivery networks and German hospital federations where pharmacy and therapeutics committees exercise centralized control.
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market Segmentation
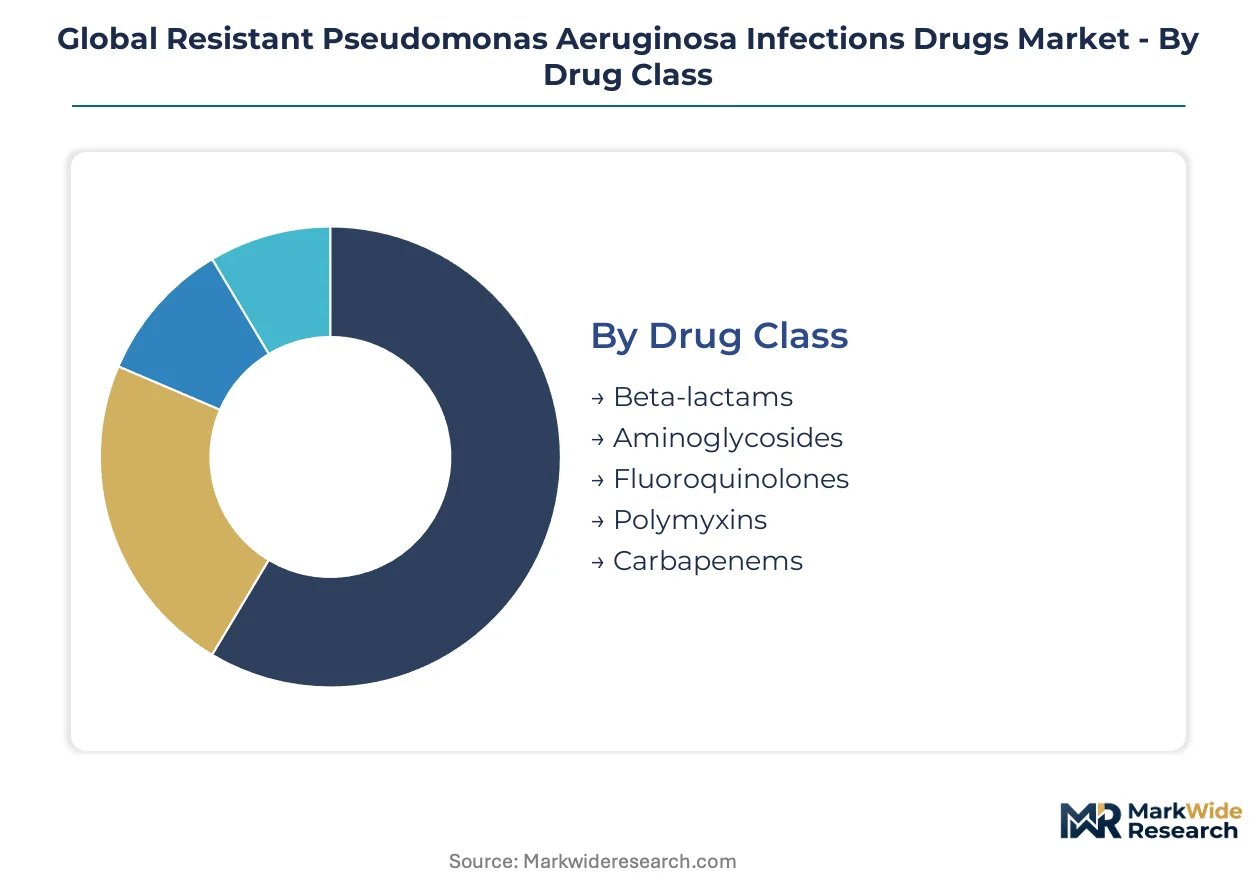
Segmentation in the resistant Pseudomonas aeruginosa infections drugs market reveals distinct procurement pathways and clinical utility patterns. Drug class and infection type determine reimbursement tiers, while patient care setting and distribution channel shape commercial access strategies for developers.
Drug Class:
Hospital formularies route beta-lactam combinations through centralized pharmacy and therapeutics committees, while polymyxins and carbapenems flow through restricted authorization protocols in intensive care units.
- Carbapenems:Broad-spectrum beta-lactams with stability against extended-spectrum beta-lactamases serve as empiric backbone therapy in tertiary care centers. Demand concentrates in United States academic medical centers where ventilator-associated pneumonia protocols mandate carbapenem-containing regimens, though stewardship programs tighten utilization controls.
- Polymyxins:Cyclic lipopeptides disrupting bacterial outer membrane integrity function as last-resort agents for extensively drug-resistant strains. German and Japanese intensive care units drive volume for colistin and polymyxin B amid carbapenem resistance rates exceeding institutional thresholds, constrained by nephrotoxicity monitoring requirements.
- Beta-lactams:Penicillin and cephalosporin derivatives with anti-pseudomonal activity.
- Aminoglycosides:Protein synthesis inhibitors requiring therapeutic drug monitoring.
- Fluoroquinolones:DNA gyrase inhibitors with declining susceptibility profiles in nosocomial isolates.
Carbapenems dominate installed base across formulary tiers. Beta-lactam combinations with novel inhibitors are where expansion concentrates.
Infection Type:
Cost tier stratification separates device-associated infections requiring prolonged intravenous therapy from ambulatory-compatible urinary tract indications with shorter course durations.
- Ventilator-associated Pneumonia:Lower respiratory tract colonization in mechanically ventilated patients demands broad-spectrum empiric coverage with rapid de-escalation protocols. United States hospital systems account for concentrated demand as bundled payment models incentivize reduced length-of-stay outcomes, elevating pressure for rapid microbiological identification.
- Burn Wound Infection:Cutaneous colonization in thermal injury patients creates biofilm-protected reservoirs with polymicrobial complexity. Specialized burn centers in Germany and Japan generate protocol-driven demand for topical and systemic anti-pseudomonal combinations, complicated by wound penetration pharmacokinetics.
- Urinary Tract Infection:Catheter-associated and complicated infections with Pseudomonas aeruginosa.
- Bacteremia:Bloodstream infections requiring source control and prolonged antimicrobial therapy.
- Skin & Soft Tissue Infection:Diabetic foot and surgical site infections with Gram-negative components.
Ventilator-associated pneumonia commands premium pricing tiers. Burn wound infection represents the application with steepest unmet need trajectory.
Patient Care Setting:
Volume concentration tracks bed capacity and acuity, with tertiary hospital intensive care units generating disproportionate utilization against outpatient and long-term care channels.
- Intensive Care Units:High-acuity environments with invasive devices and immunocompromised hosts generate the majority of resistant Pseudomonas aeruginosa treatment episodes. United States integrated delivery networks and German hospital federations centralize procurement through therapeutic class reviews that favor broad-spectrum agents with resistance suppression documentation.
- General Wards:Step-down and intermediate care units with moderate acuity.
- Outpatient Facilities:Ambulatory parenteral antimicrobial therapy programs and infusion centers.
- Long-term Care Centers:Skilled nursing facilities with endemic multidrug-resistant organism colonization.
- Surgical Units:Perioperative prophylaxis and post-operative infection management.
Intensive care units anchor revenue concentration. Outpatient facilities are where channel expansion efforts focus.
Distribution Channel:
Supply concentration in hospital pharmacies reflects formulary control consolidation, while specialty clinics and online channels serve fragmented cystic fibrosis and chronic infection populations.
- Hospital Pharmacies:Centralized dispensing with antimicrobial stewardship oversight governs access to restricted agents. United States health systems and Japanese university hospitals operate closed formularies that require infectious disease consultation for carbapenem and polymyxin release, creating gatekeeper dynamics that shape manufacturer account management strategies.
- Specialty Clinics:Cystic fibrosis centers and infectious disease practices with chronic Pseudomonas aeruginosa management protocols.
- Retail Pharmacies:Community dispensing for oral fluoroquinolone step-down therapy.
- Online Pharmacies:Direct-to-patient delivery for maintenance inhaled antibiotic regimens.
- Wholesale Distributors:Inventory management and cold chain logistics for institutional customers.
Hospital pharmacies control access to high-value parenteral agents. Specialty clinics are where patient stratification for novel inhaled formulations concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for novel anti-pseudomonal agents concentrates in the United States and Germany, where bundled reimbursement models and hospital federation procurement sustain premium tiers. Japanese and UK markets operate under tighter price controls that compress margins for carbapenem combinations. Emerging volume growth clusters in tertiary care centers across India and Brazil face formulary restrictions that delay access to next-generation beta-lactamase inhibitors.
United States
Integrated delivery networks in Texas and Florida drive concentrated demand for ventilator-associated pneumonia protocols. FDA QIDP designations accelerate market entry timelines for developers targeting carbapenem-resistant strains. Academic medical centers in Boston and Houston anchor clinical trial recruitment for novel beta-lactam combinations.
Germany
Hospital federations in Bavaria and North Rhine-Westphalia centralize antibiotic procurement through therapeutic class reviews. EMA PRIME eligibility pathways compress regulatory timelines for priority pathogen therapeutics. The Cologne-Düsseldorf corridor hosts specialized infectious disease pharmacists who shape resistance profiling protocols.
Japan
University hospitals in Tokyo and Osaka generate protocol-driven demand for polymyxin B amid carbapenem resistance surveillance alerts. PMDA's Sakigake designation reduces review timelines for anti-pseudomonal agents entering Asian markets. The Kansai region concentrates cystic fibrosis centers adopting inhaled antibiotic delivery systems.
United Kingdom
NHS England's antimicrobial stewardship programs restrict carbapenem authorization in London and Manchester intensive care units. NICE technology appraisals determine reimbursement thresholds for combination therapies against multidrug-resistant Gram-negative infections. The Oxford-Cambridge corridor anchors resistance surveillance network coordination.
India
Tertiary hospitals in Maharashtra and Karnataka face endemic carbapenem resistance rates exceeding institutional thresholds. CDSCO accelerated approval pathways for anti-infectives expand access to novel agents in Delhi-NCR and Mumbai clusters. Private hospital chains in Hyderabad and Chennai pilot rapid susceptibility testing integration.
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in this market. Large-cap pharmaceutical developers sustain late-stage clinical pipelines through established anti-infectives infrastructure and specialized carbapenem programs. Mid-tier firms concentrate manufacturing scale on polymyxin derivatives and beta-lactam combinations. The competitive terrain rewards portfolio diversification into biofilm disruption technologies and strategic partnerships for inhaled delivery formulations.
Among large-cap developers, Pfizer Inc., Merck & Co Inc., and Bristol Myers Squibb Co. occupy positions that exemplify divergent strategic archetypes. Pfizer represents the diversified infrastructure model leveraging broad anti-infectives capabilities. Merck & Co Inc. anchors the specialized therapeutic focus archetype through concentrated carbapenem development. Bristol Myers Squibb Co. exemplifies manufacturing-scale positioning on last-resort agents for critical care settings.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Bristol Myers Squibb Co. |
| Teva Pharmaceutical Industries Ltd |
| Pfizer Inc. |
| Merck & Co Inc. |
| Novartis AG |
| Johnson & Johnson |
| AstraZeneca |
| Janssen Pharmaceuticals, Inc. |
| Others |
Supply & Pricing Matrix
FDA QIDP designation gates both supply qualification and price differentiation simultaneously, extending market exclusivity for developers while compressing approval timelines that justify premium positioning for novel anti-pseudomonal agents against generic carbapenem alternatives.
Pricing Analysis
Configured-to-order pricing for patient-specific combination regimens commands substantial premiums over standard carbapenem monotherapy protocols. Contract-based long-term offtake agreements with integrated delivery networks dominate hospital procurement, with price differentiation driven by resistance suppression documentation and therapeutic drug monitoring bundling. Cost compression in polymyxin generics is intensifying because of API oversupply from Indian manufacturing clusters. Academic medical centers demonstrate lowest price sensitivity due to bundled reimbursement models, while emerging market tertiary hospitals face acute budget constraints.
Supply Chain Analysis
Strategic stockpiling of polymyxin APIs persists among Japanese and German hospital federations amid geopolitical supply risks, contrasting with just-in-time inventory practices for beta-lactam combinations in United States health systems. Active pharmaceutical ingredient production concentrates in China and India for polymyxins, with cephalosporin intermediates sourcing from Italy and Spain. Single-source vulnerability characterizes colistin sulfate raw material flows. Distribution runs through wholesale distributors with cold chain logistics for parenteral formulations, supplemented by direct hospital contracting for high-value novel agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where rapid susceptibility testing integration creates interoperability standards that reshape formulary access and procurement consolidation across integrated delivery networks.
For Market Incumbents: Shield market position by deepening captive supply of beta-lactamase inhibitor APIs through backward integration into Chinese and Indian fermentation capacity. Fortify hospital formulary lock-in through resistance surveillance data partnerships with microbiology laboratories, countering emerging entrant challenge from biofilm disruption technology specialists.
For New Entrants and Emerging Players: Differentiate on inhaled antibiotic delivery platforms for cystic fibrosis centers, where nebulized formulations create white-space positioning against intravenous-standard therapy. Target Japan's Sakigake-designated priority review pathway for accelerated market entry, deploying direct specialty clinic engagement to bypass consolidated hospital pharmacy gatekeepers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across next-generation beta-lactamase inhibitor development programs, favoring platform acquisitions over de novo pipeline construction. Acquire mid-tier firms with differentiated manufacturing scale on polymyxin derivatives and established EMA PRIME eligibility track records. Monitor FDA QIDP designation velocity as inflection indicator for portfolio reallocation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates patient recruitment across United States academic medical centers for carbapenem-resistant pneumonia protocols. |
| Regulatory Approval Pathway | FDA QIDP designation extends exclusivity timelines for novel beta-lactam combinations entering priority pathogen indications. |
| Manufacturing Scale-Up | Expands polymyxin API fermentation capacity in Indian clusters to address hospital federation procurement consolidation. |
| Pipeline Diversification | Adds biofilm disruption adjuncts to address device-associated infection treatment failures in intensive care units. |
| Strategic Partnership | Links rapid susceptibility testing platforms with formulary pre-qualification protocols in German hospital federations. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Primary interviews with infectious disease pharmacists and payer access specialists combined with secondary validation through SEC 10-K disclosures and hospital procurement databases. Bottom-up patient volume modeling and top-down therapeutic class expenditure analysis enabled triangulation across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks from resistance surveillance networks and national health expenditure reports. The analytical framework segmented by drug class, infection type, patient care setting, and regional regulatory cluster over the projection horizon. CAGRs were derived from epidemiological trend extrapolation and protocol adoption curve modeling, with inputs including carbapenem resistance rate trajectories and stewardship program authorization stringency indices.
Forecasts assume regulatory continuity in FDA QIDP and EMA PRIME eligibility pathways; material policy shifts would require re-modeling of commercialization timeline assumptions. Revision becomes warranted when carbapenem resistance surveillance thresholds cross institutional protocol revision triggers or when API supply disruptions exceed strategic stockpile depletion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Bioactive Protein and Peptides Market
Biopharmaceuticals
Triclabendazole Market
Biopharmaceuticals
Antibiotics Market
Biopharmaceuticals
Cancer Drug Market
Biopharmaceuticals
Global Bovine Blood Plasma Derivatives Market
Biopharmaceuticals
Somatostatin Analogs Market
Biopharmaceuticals
Antibacterial Drugs Market
Biopharmaceuticals
Beta Interferon Market
Biopharmaceuticals
Drug Resistant Pulmonary Tuberculosis Market
Biopharmaceuticals
Theranostics Market
Biopharmaceuticals
6-Azauracil Market
Biopharmaceuticals
Generic Drugs Market
Biopharmaceuticals
Generic Injectables Market
Biopharmaceuticals
Latin America Insulin Pens Market
Biopharmaceuticals
Canada Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Recombinant Erythropoietin Market