
 Strand Displacement Amplicon (SDA) Market | 2026-2036
Strand Displacement Amplicon (SDA) Market Size, Share, and Industry Trends Forecast 2026-2036
Strand Displacement Amplicon (SDA) Market Insights
Platform licensing revenue is tilting from standalone instrument sales toward integrated assay-recurring models. Becton Dickinson and Company leverages its installed base in clinical microbiology to anchor SDA consumable pull-through. Hologic Inc. competes through women's health screening channels where molecular amplification occupies a defensible niche. Bio-Rad Laboratories Inc. specializes in research-use reagents that sustain margin pools in academic and biopharma accounts.
Strand displacement amplicon denotes an isothermal nucleic acid amplification method employing DNA polymerases with strand-displacing activity and restriction enzyme-mediated nicking to generate exponential signal without thermal cycling, operating typically at temperatures between 50°C and 65°C for point-of-care and laboratory diagnostic applications. The technology segment shows nucleic acid amplification methods retaining structural importance for rapid pathogen detection, while CRISPR-integrated SDA workflows represent the fastest-growing configuration as diagnostic developers seek combined amplification and targeting specificity. Within application categories, diagnostic testing commands the dominant margin pool due to reimbursement attach rates, whereas environmental monitoring remains nascent with concentrated pilot deployment among industrial hygiene laboratories.
FDA premarket review pathways for nucleic acid amplification devices shape product development timelines and clinical validation requirements for US market entrants, while the EU IVDR imposes notified body conformity assessment that filters smaller kit suppliers from European distribution. ISO 13485 quality management systems and WHO prequalification standards additionally govern procurement eligibility for public health programs in low-resource settings. Stakeholders must monitor evolving companion diagnostic guidance and decentralized testing waivers that could redirect SDA platform investment toward CLIA-waived or near-patient configurations.
Market Dynamics
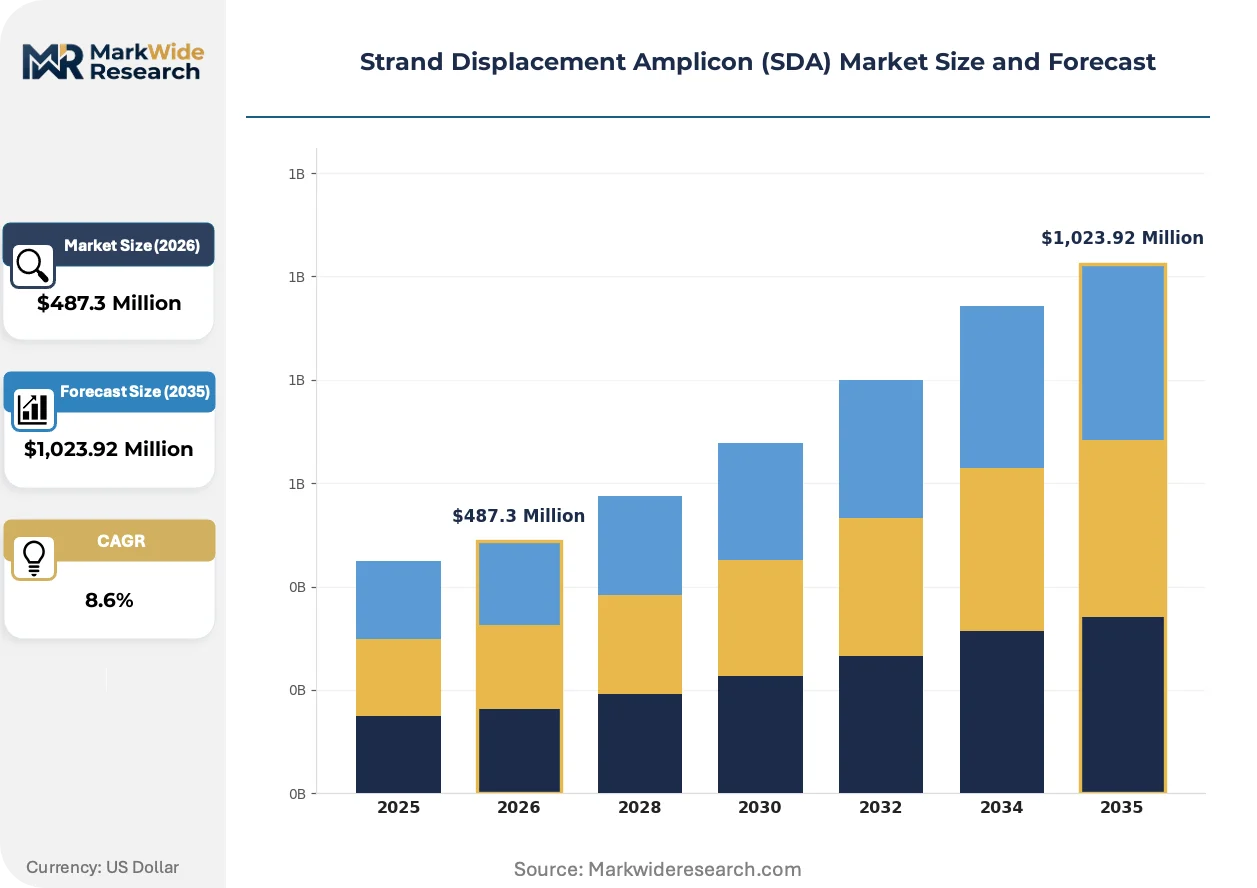
The transition from thermal-cycler PCR to isothermal amplification methods is compressing capital requirements for molecular diagnostics while expanding point-of-care deployment possibilities. Hospital laboratory consolidation in the United States and compliance mandates under the EU IVDR are simultaneously reshaping vendor selection criteria toward integrated platform-recurring revenue models.
Growth Catalysts
- EU IVDR Conformity Assessment:The 2022 implementation of the In Vitro Diagnostic Regulation is filtering smaller kit suppliers from European distribution, creating procurement concentration among validated SDA platform holders.
- Isothermal Amplification Chemistry:Strand-displacing DNA polymerases operating at 50°C–65°C eliminate thermal cycling hardware requirements, enabling CLIA-waived configurations for decentralized testing workflows.
- Hospital Laboratory Consolidation:United States health system mergers are standardizing on high-throughput molecular platforms that favor consumable pull-through over standalone instrument sales.
Market Restraints
- Restriction Enzyme Supply Concentration:Nicking endonucleases required for exponential SDA signal generation derive from concentrated bioreagent suppliers, exposing kit manufacturers to input cost volatility and allocation risk.
- CRISPR Diagnostic Substitution:CRISPR-Cas12/13 detection systems with direct nucleic acid recognition threaten to bypass amplification entirely in low-complexity pathogen detection applications.
- FDA Premarket Review Timelines:The 510(k) and De Novo pathways for nucleic acid amplification devices impose 18–36 month clinical validation requirements that compress development capital efficiency.
Strategic Opportunities
- Environmental Monitoring Applications:Industrial hygiene laboratories in Germany and the Netherlands are piloting SDA-based microbial surveillance for pharmaceutical cleanrooms and food processing facilities.
- WHO Prequalification Pathway:Compliance with the World Health Organization's quality standards for in vitro diagnostics opens procurement eligibility for public health programs in low-resource settings.
- CRISPR-SDA Convergence:Diagnostic developers are integrating Cas12a-mediated signal amplification with strand displacement chemistry to combine targeting specificity with isothermal operational simplicity.
Industry Challenges
- ISO 13485 Certification Timeline:Quality management system implementation for medical device manufacturing requires 12–18 months of documented process validation before notified body audit.
- Legacy LIS Integration Complexity:Hospital information systems in the United States and United Kingdom require HL7/FHIR interface development that extends deployment timelines for new molecular platforms.
- Assay Development Talent Scarcity:The specialized skill set combining primer design, enzyme kinetics, and clinical validation expertise concentrates among a limited pool of molecular diagnostic scientists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strand Displacement Amplicon (SDA) Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assays, Reagents, Kits, Tools Technology: Polymerase Chain Reaction, Nucleic Acid Amplification, CRISPR, Sequencing Technologies Application: Diagnostic Testing, Research & Development, Forensic Analysis, Environmental Monitoring End User: Hospitals, Laboratories, Academic Institutions, Biotechnology Companies |
| Companies Covered | Becton Dickinson and Company, Hologic Inc., Bio-Rad Laboratories Inc., New England Biolabs, QuidelOrtho Corporation, NuProbe, Lucigen Corporation, NIPPON Genetics Co Ltd, Geno Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strand Displacement Amplicon (SDA) Market Trends and Innovations
Digital microfluidic integration and CRISPR-enhanced specificity are converging to expand SDA applications beyond infectious disease into oncology and pharmacogenomics. These developments are compressing the traditional boundaries between amplification, detection, and target identification.
Real-time fluorescent readout systems employing intercalating dyes and molecular beacons are rendering obsolete endpoint gel electrophoresis confirmation for SDA products. Clinical diagnostic laboratories in France and Japan are adopting these integrated detection chemistries to reduce turnaround times from hours to minutes. The structural consequence is a collapse in ancillary equipment revenue as single-instrument workflows capture margin previously distributed across multiple hardware categories.
REACH regulation compliance for enzyme reagents and plastic consumables is forcing European SDA kit manufacturers to reformulate buffer matrices and transition to recycled-content reaction vessels. The industrial consequence is a 15–20% increase in raw material qualification costs that filters toward premium product tiers. German and Swiss diagnostic suppliers are responding by consolidating supplier audits and implementing mass-balance certification for polymerase production lines.
Academic medical centers in the United States are unbundling after-sales service contracts from instrument procurement, instead negotiating time-and-materials support or in-house biomedical engineering coverage. This behavioral shift compresses recurring service revenue for platform vendors while transferring maintenance competency to hospital staff. The pattern is most visible in tertiary care institutions with established molecular pathology divisions in Massachusetts and California.
Strand Displacement Amplicon (SDA) Market Segmentation
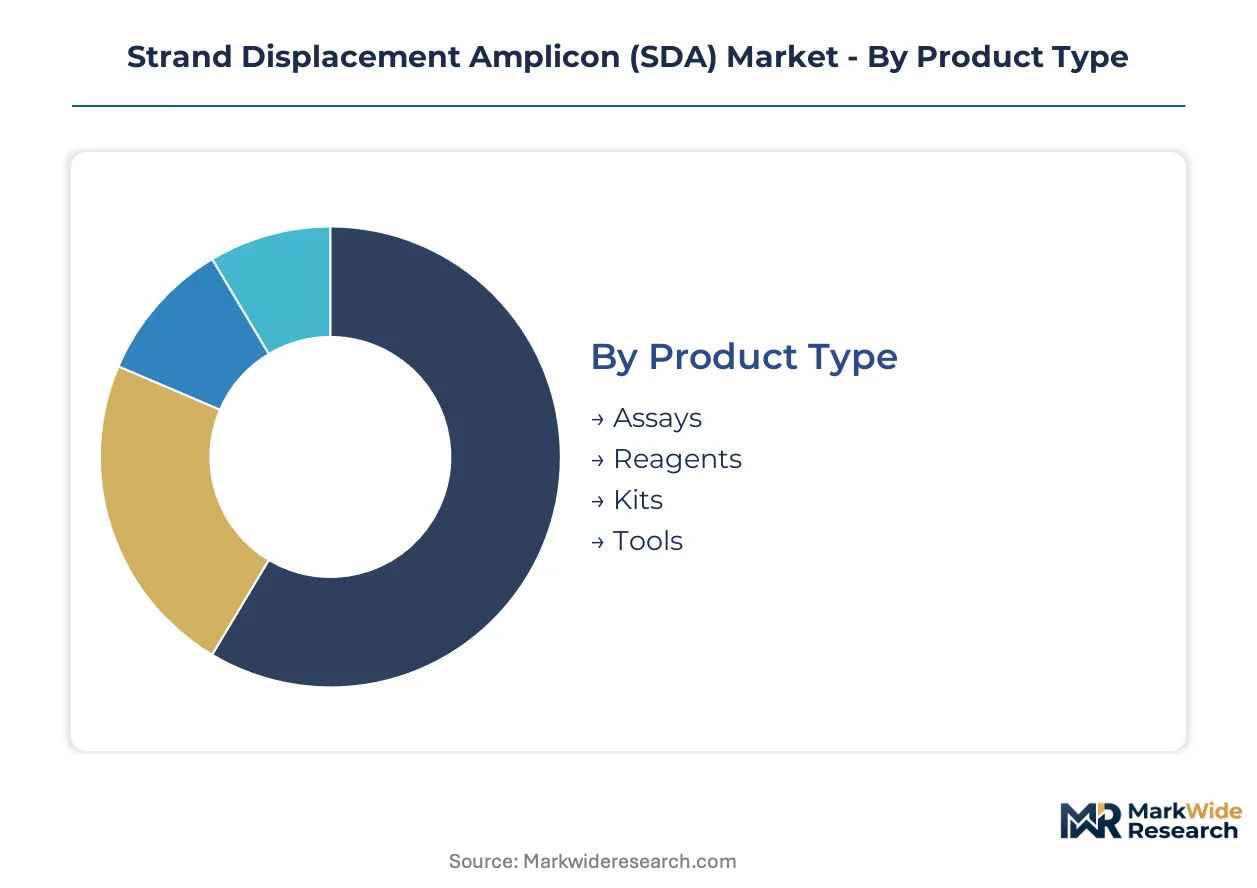
SDA market segmentation reveals how value pools concentrate across consumable formats, amplification chemistries, and customer workflows. Each dimension carries distinct margin profiles and regulatory pathways that shape vendor investment priorities.
Product Type:
Cost tier differentiation separates high-margin proprietary assays from commodity reagent inputs, with kit bundling strategies capturing intermediate value.
- Assays:Pre-validated reaction formulations with optimized primer-nicking enzyme ratios command premium positioning in clinical diagnostic laboratories. United States hospital systems standardizing on high-throughput infectious disease panels drive procurement concentration toward FDA-cleared assay formats with integrated quality controls.
- Reagents:Bulk polymerases, restriction endonucleases, and modified nucleotides supply in-house assay development programs. Biotechnology companies in Massachusetts and California source strand-displacing enzymes for custom workflow optimization, though supply concentration among specialized bioreagent manufacturers creates allocation vulnerability.
- Kits:Complete reaction assemblies with pre-aliquoted components target laboratories lacking formulation expertise. Academic medical centers in the United Kingdom favor kit formats for rapid protocol implementation.
- Tools:Specialized reaction vessels, microfluidic cartridges, and detection accessories support integrated platform workflows. German industrial hygiene laboratories pilot tool configurations for environmental monitoring applications.
Assays command the established base. The steepest expansion runs through kits.
Technology:
Application requirements determine amplification chemistry selection, with isothermal methods displacing thermal-cycler dependence in point-of-care configurations.
- Polymerase Chain Reaction:Thermal-cycling amplification retains installed-base dominance in centralized laboratories. Legacy PCR workflows in French and Japanese clinical diagnostic laboratories sustain reagent demand despite isothermal substitution pressure.
- Nucleic Acid Amplification:Isothermal methods including SDA eliminate thermal cycler capital requirements. Point-of-care testing programs in low-resource settings prioritize amplification technologies operating at 50°C–65°C for instrument-free deployment.
- CRISPR:Cas12a and Cas13a-mediated detection integrates with SDA signal generation for combined specificity and amplification. Diagnostic developers in the United States and Switzerland converge CRISPR targeting with isothermal chemistry for next-generation infectious disease panels.
- Sequencing Technologies:Next-generation and nanopore sequencing provide orthogonal confirmation for SDA-positive samples. Research-use applications in academic institutions employ sequencing for variant identification downstream of amplification.
Nucleic acid amplification methods anchor the installed base. CRISPR integration represents the steepest technology trajectory.
Application:
Customer workflow characteristics segment demand across regulated diagnostic environments and exploratory research settings with divergent validation requirements.
- Diagnostic Testing:Clinical infectious disease detection commands the dominant margin pool through reimbursement attach rates. United States hospital laboratories consolidate procurement around FDA-cleared SDA platforms for respiratory and sexually transmitted infection panels.
- Research & Development:Exploratory assay development and biomarker discovery sustain academic and biopharma demand. Biotechnology companies in California and Massachusetts employ SDA for rapid pathogen screening in preclinical studies.
- Forensic Analysis:DNA profiling applications leverage isothermal amplification for field-deployable evidence processing. Law enforcement agencies in the United Kingdom pilot SDA-based rapid DNA analysis for point-of-collection identification.
- Environmental Monitoring:Microbial surveillance in pharmaceutical cleanrooms and food processing facilities represents nascent deployment. Industrial hygiene laboratories in Germany and the Netherlands pilot SDA workflows for contamination detection.
Diagnostic testing commands the established base. Environmental monitoring gains share fastest.
End User:
Procurement sophistication and regulatory compliance requirements differentiate customer tiers, with consolidated health systems favoring integrated platform contracts.
- Hospitals:Clinical microbiology and molecular pathology departments drive high-volume consumable consumption. United States health system mergers standardize on single-vendor SDA platforms to simplify training and service contracts.
- Laboratories:Independent and hospital-affiliated reference laboratories balance throughput requirements against capital constraints. Commercial laboratories in France and Japan adopt real-time fluorescent SDA systems to reduce turnaround times.
- Academic Institutions:Research laboratories prioritize reagent flexibility and protocol customization over validated kit formats. Universities in Massachusetts and California maintain in-house assay development capabilities for grant-funded studies.
- Biotechnology Companies:Drug developers and diagnostic firms source SDA components for proprietary test development. Swiss and German biotechs integrate SDA into companion diagnostic pipelines for infectious disease therapeutics.
Hospitals command the established base. Biotechnology companies represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. United States hospital systems prioritize throughput and FDA clearance over unit cost, while public health programs in low-resource settings demand instrument-free configurations at minimal per-test economics.
United States
Hospital laboratory consolidation drives procurement concentration toward integrated SDA platforms with consumable pull-through contracts. FDA premarket review pathways for nucleic acid amplification devices impose rigorous clinical validation standards that favor established vendors. The Boston-Cambridge biotechnology cluster anchors custom assay development for infectious disease and oncology applications.
Germany
Industrial hygiene laboratories in pharmaceutical manufacturing regions pilot SDA-based environmental monitoring for cleanroom contamination detection. REACH regulation compliance for enzyme reagents and plastic consumables forces buffer reformulation and supplier audit consolidation. The Rhine-Main metropolitan area concentrates diagnostic platform development alongside chemical and pharmaceutical production facilities.
China
Domestic diagnostic manufacturers accelerate isothermal amplification platform development to reduce dependence on imported thermal-cycler systems. NMPA medical device registration requirements for nucleic acid amplification tests are streamlining under revised review guidelines. The Yangtze River Delta biotechnology corridor in Shanghai and Suzhou hosts contract research organizations integrating SDA into infectious disease test pipelines.
Japan
Clinical diagnostic laboratories adopt real-time fluorescent SDA systems to compress turnaround times for respiratory pathogen panels. PMDA consultation pathways for novel nucleic acid amplification technologies guide pre-submission strategy for domestic and foreign manufacturers. The Kansai region around Osaka maintains specialized reagent production capabilities for isothermal amplification chemistries.
Switzerland
Biotechnology companies integrate SDA into companion diagnostic development for infectious disease therapeutics targeting European and emerging markets. Swissmedic conformity assessment for in vitro diagnostics aligns with EU IVDR standards while maintaining distinct national notification procedures. The Basel biopharma cluster drives demand for high-specificity amplification methods in precision medicine applications.
Strand Displacement Amplicon (SDA) Market Competitive Landscape
Capability concentration sits with specialized enzyme and reagent suppliers; scale advantage sits with diversified diagnostic platform manufacturers. The market structures around three tiers: integrated system vendors with installed-base leverage, component specialists controlling critical enzyme inputs, and emerging CRISPR-convergence developers. Competitive moves center on assay-recurring revenue model expansion and strategic partnerships to secure restriction enzyme supply allocation.
Among diversified diagnostic platform manufacturers, Becton Dickinson and Company and Hologic Inc. exemplify the integrated-system archetype, leveraging clinical microbiology and women's health screening channels respectively to anchor consumable pull-through. Bio-Rad Laboratories Inc. occupies a distinct position within the research-use reagent tier, sustaining margin pools in academic and biopharma accounts through specialized workflow components. These three entities collectively illustrate how vendor strategy diverges between platform integration and component specialization.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Hologic Inc. |
| Bio-Rad Laboratories Inc. |
| New England Biolabs |
| QuidelOrtho Corporation |
| NuProbe |
| Lucigen Corporation |
| NIPPON Genetics Co Ltd |
| Geno Technology Inc. |
| Others |
Pricing and Supply Chain Analysis
Restriction enzyme single-source dependency determines both tiered pricing spreads across premium assay kits and bulk reagent formats and supply chain vulnerability to allocation risk from concentrated bioreagent manufacturers. This input concentration cascades through contract structures and geographic sourcing decisions.
Pricing Analysis
After-sales service revenue from extended maintenance contracts and time-and-materials support drives lifetime value capture more than standalone instrument placement. Three-tier pricing structure across premium FDA-cleared assays, standard research-use kits, and economy bulk reagents separates clinical diagnostic laboratories from academic accounts. Cost compression in economy reagent tiers intensifies because hospital laboratory consolidation favors bundled platform contracts. Biotechnology companies in Massachusetts exhibit lowest price sensitivity due to grant-funded customization requirements.
Supply Chain Analysis
Contract manufacturing for microfluidic cartridges and reaction vessels concentrates among specialized polymer foundries in Germany, Switzerland, and the United States. Strand-displacing DNA polymerases and nicking endonucleases draw from captive production lines and third-party bioreagent specialists in the same three-country cluster. Single-source vulnerability for restriction enzyme inputs exposes kit manufacturers to allocation risk during supply disruptions. Distribution runs through direct platform vendor relationships with consolidated health systems and distributor networks serving fragmented academic accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CRISPR-SDA convergence chemistry represents a high-growth disruption justified by FDA premarket review pathways accelerating for combined amplification-detection platforms. This technological inflection compresses development timelines for next-generation infectious disease panels.
For Market Incumbents: Pre-empt CRISPR diagnostic substitution by securing exclusive restriction enzyme supply allocation through long-term bioreagent partnerships. Deepen backward integration into polymerase production to defend margin position against input cost volatility. Anchor consumable pull-through through integrated assay-recurring models that resist hospital laboratory consolidation pressures.
For New Entrants and Emerging Players: Environmental monitoring applications in German pharmaceutical manufacturing regions represent the most penetrable entry point with nascent competitive density. WHO prequalification pathways for low-resource settings offer second white-space targeting with procurement eligibility advantages. Pursue regulatory sandbox partnerships with notified bodies to compress EU IVDR conformity assessment timelines.
For Investors and Strategic Acquirers: Specialized enzyme suppliers with ISO 13485 certification and restricted distribution rights present priority acquisition targets given capability concentration in SDA chemistry inputs. Long-term viability frames around platform-recurring revenue models displacing standalone instrument sales over the next decade. Monitor FDA De Novo submission volumes for CRISPR-integrated SDA devices as inflection signal for technology convergence maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Restriction Enzyme Supply Agreement | Secures allocation priority from New England Biolabs for nicking endonuclease inputs. |
| CLIA-Waived Configuration Development | Expands addressable market into point-of-care settings under FDA decentralized testing guidance. |
| WHO Prequalification Pathway | Unlocks procurement eligibility for public health programs in low-resource African and Asian markets. |
| CRISPR-SDA Convergence R&D | Combines Cas12a targeting specificity with isothermal operational simplicity for next-generation panels. |
| Hospital System Partnership | Locks in consumable pull-through through integrated platform contracts with consolidated US health systems. |
Research Methodology
Initial hypotheses were tested against primary input from clinical microbiology directors, diagnostic platform procurement managers, biomedical engineers, and molecular assay development scientists and refined through secondary validation against FDA 510(k) and De Novo submission databases, EU IVDR notified body conformity assessment records, hospital GPO contract filings, and WHO prequalification status reports. Bottom-up triangulation across consumable volume estimates and top-down reconciliation against platform vendor revenue disclosures anchored market sizing.
Demand-supply-balance framing modeled nucleic acid amplification technology adoption, application category migration, end-user procurement consolidation, and regional regulatory pathway complexity across the projection horizon. CAGRs derived from segment-level growth rate convergence analysis incorporating infectious disease testing volume trends, point-of-care expansion trajectories, and environmental monitoring pilot scale-up rates.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles or bioreagent input commodity costs would shift the trajectory. Forecasts reflect assumptions regarding regulatory pathway stability and enzyme supply continuity. Quarterly review of FDA submission volumes and notified body audit backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Cell Analysis Market
Biomedical Technology
Structural Biology and Molecular Modeling Techniques Market
Biomedical Technology
Northern Blotting Market
Biomedical Technology
Life Science Analytics Market
Biomedical Technology
Bone Marrow Aspirate Concentrates (BMAC) Market
Biomedical Technology
Global Ligation Market
Biomedical Technology
ST2 Biomarker Market
Biomedical Technology
Fluoro Enzymatic Assays Market
Biomedical Technology
Global RNA-Interference (Rnai) Market
Biomedical Technology
Global Nicotinamide Adenine Dinucleotide (NAD) Market
Biomedical Technology
Global Molecular Biosensors Market
Biomedical Technology
Live Cell RNA Detection Market
Biomedical Technology
Particle-Enhanced Turbidimetric Immunoassays Market
Biomedical Technology
Global Cell Counting Market
Biomedical Technology
Strand Displacement Amplification (SDA) Market
Biomedical Technology
Global Biological Stains Market