
 Targeted Cancer Drugs Market | 2026-2036
Targeted Cancer Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Targeted Cancer Drugs Market Outlook
The capital-intensity divergence between large-cap biopharmaceutical platforms and emerging precision therapy developers is unwinding competitive stability across the sector. Roche leverages its integrated diagnostics-drug development engine to sustain leadership in companion biomarker strategies. Novartis anchors its position through deep manufacturing scale in radioligand therapies. Bristol-Myers Squibb competes aggressively in immune checkpoint modulation, extending its presence into novel combination regimens.
Targeted cancer drugs are therapeutics engineered to interfere with specific molecular pathways driving malignant cell proliferation, typically requiring companion diagnostic validation and biomarker patient stratification to achieve clinical efficacy. Monoclonal antibodies occupy mature, high-volume positions with established infusion infrastructure and biosimilar pressure compressing margins. Antibody-drug conjugates represent the fastest-expanding structural segment, concentrating margin pools where linker-payload innovation differentiates clinical outcomes. Small molecule inhibitors retain durable demand in oral therapy paradigms, particularly within lung and prostate cancer settings where patient convenience drives prescribing patterns.
FDA accelerated approval frameworks and EMA conditional marketing authorization pathways shape demand by compressing development timelines while mandating confirmatory evidence generation. The EU AI Act and evolving FDA guidance on real-world evidence integration are forcing stakeholders to restructure post-market surveillance capabilities. Stakeholders must monitor how regulator convergence on biomarker standardization reshapes portfolio prioritization and geographic launch sequencing.
Market Dynamics
FDA's accelerated approval pathways compress commercialization timelines while mandating confirmatory evidence generation, forcing developers to restructure post-market surveillance capabilities around real-world evidence integration.
Growth Catalysts
- Companion diagnostic mandates:Biomarker-driven patient stratification protocols expand addressable populations for precision therapies across oncology clinics in the United States.
- EMA conditional marketing authorization:European pathways compress development timelines for radioligand therapies, accelerating geographic expansion beyond initial approval markets.
- Antibody-drug conjugate innovation:Linker-payload engineering advances differentiate clinical outcomes in solid tumor indications, concentrating investment in manufacturing scale.
Market Restraints
- Isotope supply concentration:Radioligand therapy production depends on limited nuclear reactor infrastructure concentrated in North America and Europe, creating geographic vulnerability.
- Biosimilar margin compression:Monoclonal antibody portfolios face pricing pressure as reference product exclusivity expires, eroding revenue from mature infusion infrastructure.
- Biomarker testing fragmentation:Inconsistent companion diagnostic standardization across jurisdictions delays patient identification and therapy initiation.
Strategic Opportunities
- Japan's PMDA oncology innovation scheme:Regulatory tailwinds for novel mechanism drugs create accelerated entry pathways for immune checkpoint combination developers.
- Community oncology channel expansion:Oral small molecule inhibitors enable treatment delivery outside infusion centers, capturing convenience-driven prescribing in prostate and lung settings.
- AI-enabled patient identification:Machine learning integration with electronic health records surfaces biomarker-positive candidates missed by conventional screening protocols.
Industry Challenges
- Radiochemistry talent scarcity:Specialized isotope handling expertise concentrates at limited academic centers, constraining manufacturing workforce expansion for radioligand platforms.
- Legacy clinical trial infrastructure:Site activation timelines lag behind compressed regulatory pathways, creating enrollment bottlenecks for confirmatory studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Targeted Cancer Drugs Market |
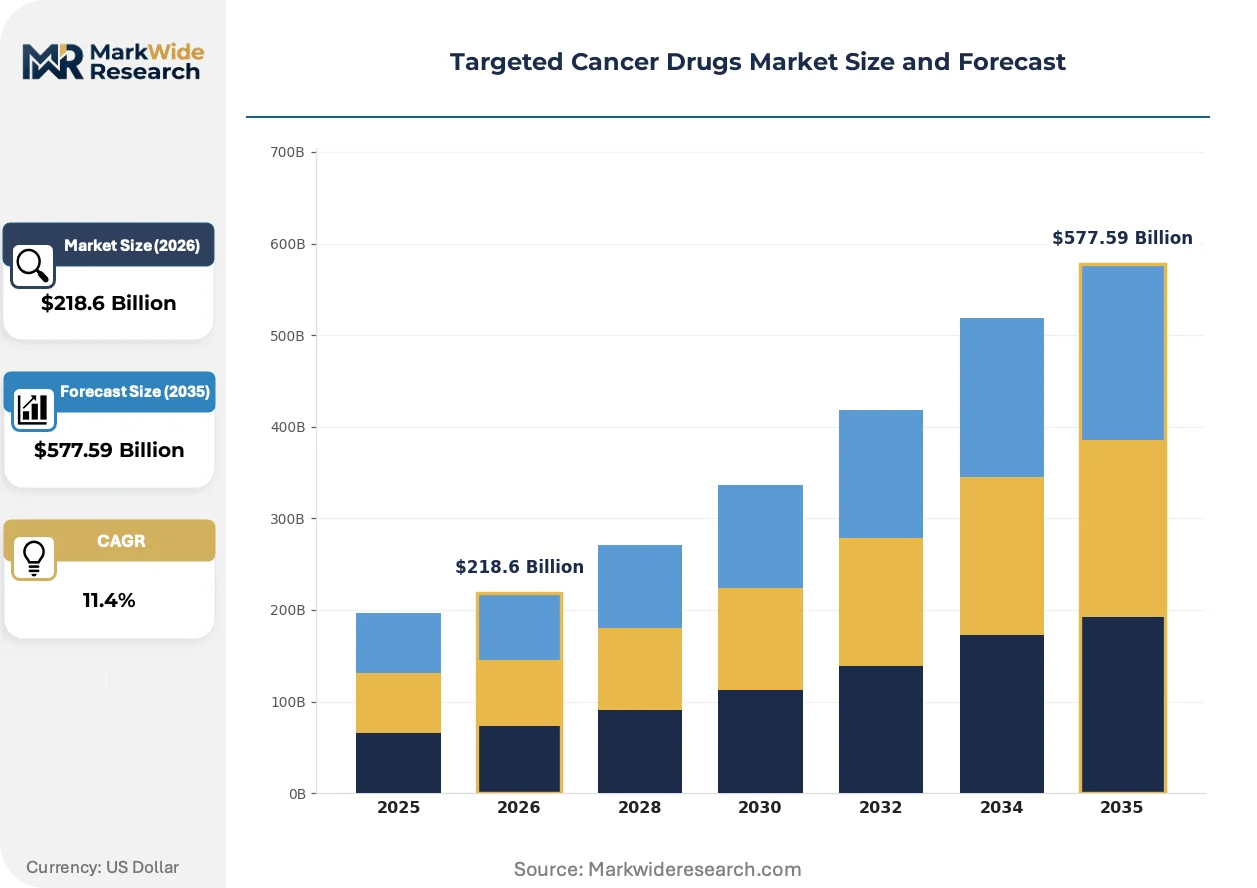
| Market Size in 2026 | $218.6 Billion |
| Market Size in 2035 | $577.59 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Monoclonal Antibodies, Small Molecule Inhibitors, Immune Checkpoint Inhibitors, Antibody-Drug Conjugates Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Oncology Clinics, Research Institutions, Homecare Therapy Area: Breast Cancer, Lung Cancer, Colorectal Cancer, Prostate Cancer |
| Companies Covered | Roche, Novartis, Bristol-Myers Squibb, Merck & Co., Pfizer, AstraZeneca, Johnson & Johnson, Eli Lilly and Company, Amgen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Targeted Cancer Drugs Market Strategic Shifts
Precision therapy development converges with diagnostic innovation, reshaping how molecular targets are validated, manufactured, and delivered across fragmented care settings.
Next-generation antibody-drug conjugates incorporate site-specific conjugation chemistry and novel payload classes including topoisomerase inhibitors and kinesin spindle protein antagonists. Oncology clinics in the United States and Germany are adopting these constructs at accelerating pace for HER2-low and TROP2-expressing indications. This engineering precision is supplanting conventional chemotherapy backbones in later-line solid tumor protocols, compressing the addressable market for cytotoxic infusion regimens.
The EU AI Act mandates algorithmic transparency for clinical decision support tools used in biomarker interpretation and patient stratification. European developers must restructure machine learning validation documentation to satisfy conformity assessment procedures. Companion diagnostic manufacturers serving EMA-authorized products face the steepest compliance burden, with several firms establishing dedicated AI governance functions ahead of enforcement timelines.
Integrated delivery networks are consolidating oncology pharmacy procurement under centralized formularies with outcome-based utilization criteria. Hospital systems in the United States increasingly contract directly with manufacturers for antibody-drug conjugate supply, bypassing traditional wholesale distribution. This channel compression concentrates negotiating leverage among the largest networks while marginalizing independent community practices unable to meet volume commitments or data-sharing requirements.
Targeted Cancer Drugs Market Segmentation
Precision therapy development demands granular patient stratification across molecular subtypes and care settings. Segmentation reveals where manufacturing scale, reimbursement infrastructure, and diagnostic capabilities align to concentrate commercial opportunity.
Drug Type:
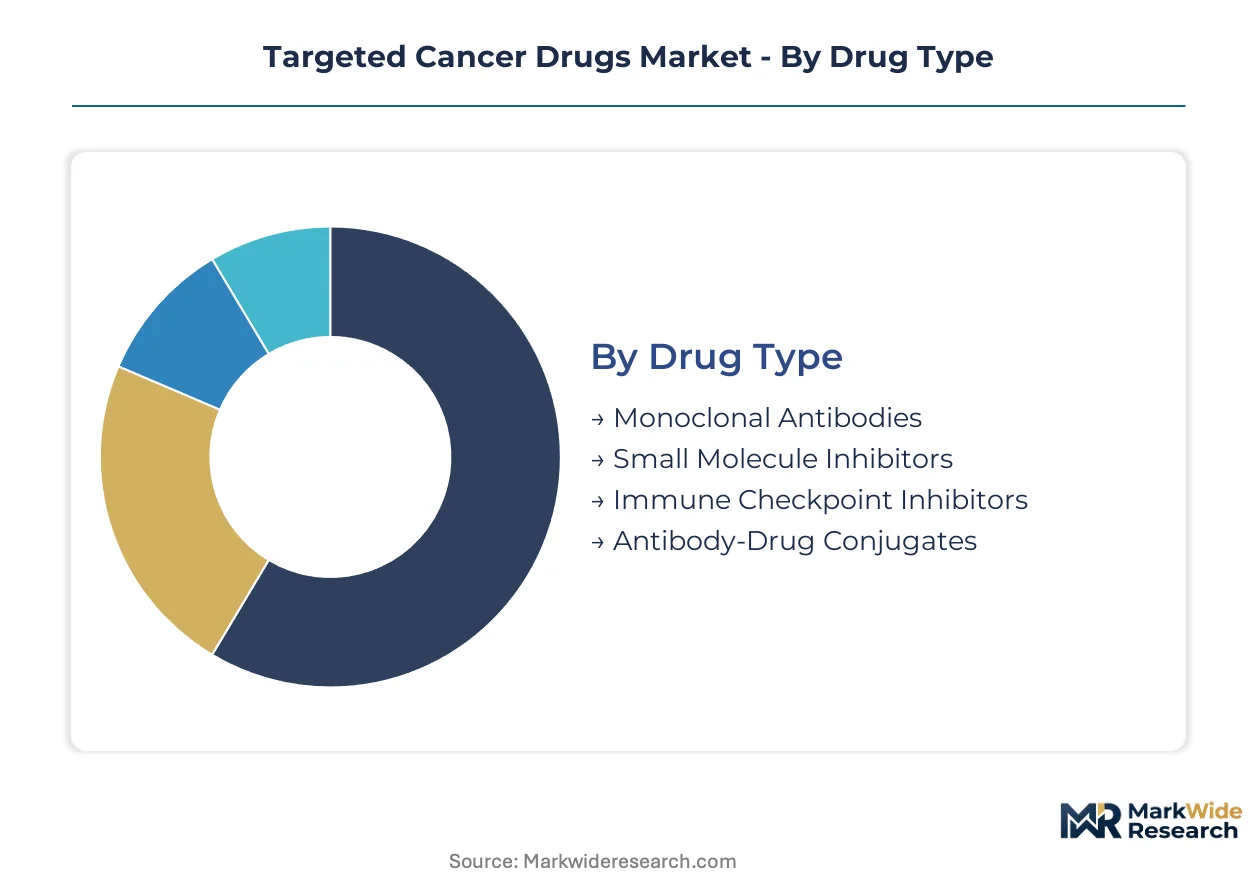
Monoclonal antibodies dominate domestic infusion center volume in the United States, while antibody-drug conjugates and small molecule inhibitors attract export-led demand from European and Asian markets seeking differentiated clinical outcomes.
- Monoclonal Antibodies:Engineered immunoglobulins targeting specific tumor-associated antigens, delivered through established hospital infusion infrastructure. Demand concentrates in United States oncology clinics where biosimilar pressure now compresses margins on legacy products.
- Small Molecule Inhibitors:Oral kinase inhibitors interfering with intracellular signaling pathways driving malignant proliferation. Prescribing concentrates in prostate and lung cancer settings across Germany and Japan where patient convenience drives protocol selection.
- Immune Checkpoint Inhibitors:Monoclonal antibodies blocking PD-1/PD-L1 or CTLA-4 interactions to restore anti-tumor immunity.
- Antibody-Drug Conjugates:Tumor-targeting antibodies linked to cytotoxic payloads via engineered linker chemistry.
Monoclonal antibodies command the established base. The steepest expansion runs through antibody-drug conjugates.
Delivery Mode:
Cost tier stratification separates high-complexity infusion administration from convenient oral dispensing, with subcutaneous formulations capturing premium positioning through reduced healthcare utilization.
- Intravenous:Hospital-based infusion requiring specialized nursing staff and adverse event monitoring infrastructure. Demand concentrates in academic medical centers across the United States and France where complex combination protocols mandate supervised administration.
- Oral:Self-administered small molecule therapy enabling treatment outside clinical facilities. Adoption accelerates in community oncology settings across Germany and the United Kingdom where pharmacy benefit design favors dispensing convenience.
- Subcutaneous:Self-injection formulations reducing healthcare facility dependency.
- Topical:Localized application for superficial malignancies and premalignant lesions.
Intravenous delivery commands the established base. The steepest expansion runs through oral administration.
End User:
Customer type fragmentation reflects divergent procurement capabilities, with integrated hospital systems leveraging volume negotiating power against fragmented community practice purchasing.
- Hospitals:Academic and community institutions with centralized pharmacy formularies and outcome-based contracting. Demand concentrates in United States integrated delivery networks and German university hospitals where CAR-T and radioligand therapies require specialized infrastructure.
- Oncology Clinics:Dedicated cancer treatment centers with focused infusion capacity and biomarker testing integration. Expansion concentrates in United States community settings where oral therapy protocols enable practice-scale efficiency.
- Research Institutions:Clinical trial sites and early-phase development centers.
- Homecare:Home infusion and nursing services for selected subcutaneous and oral regimens.
Hospitals command the established base. The steepest expansion runs through oncology clinics.
Therapy Area:
Maturity gradients separate breast and lung cancer settings with established biomarker infrastructure from prostate and colorectal indications where companion diagnostic penetration remains incomplete.
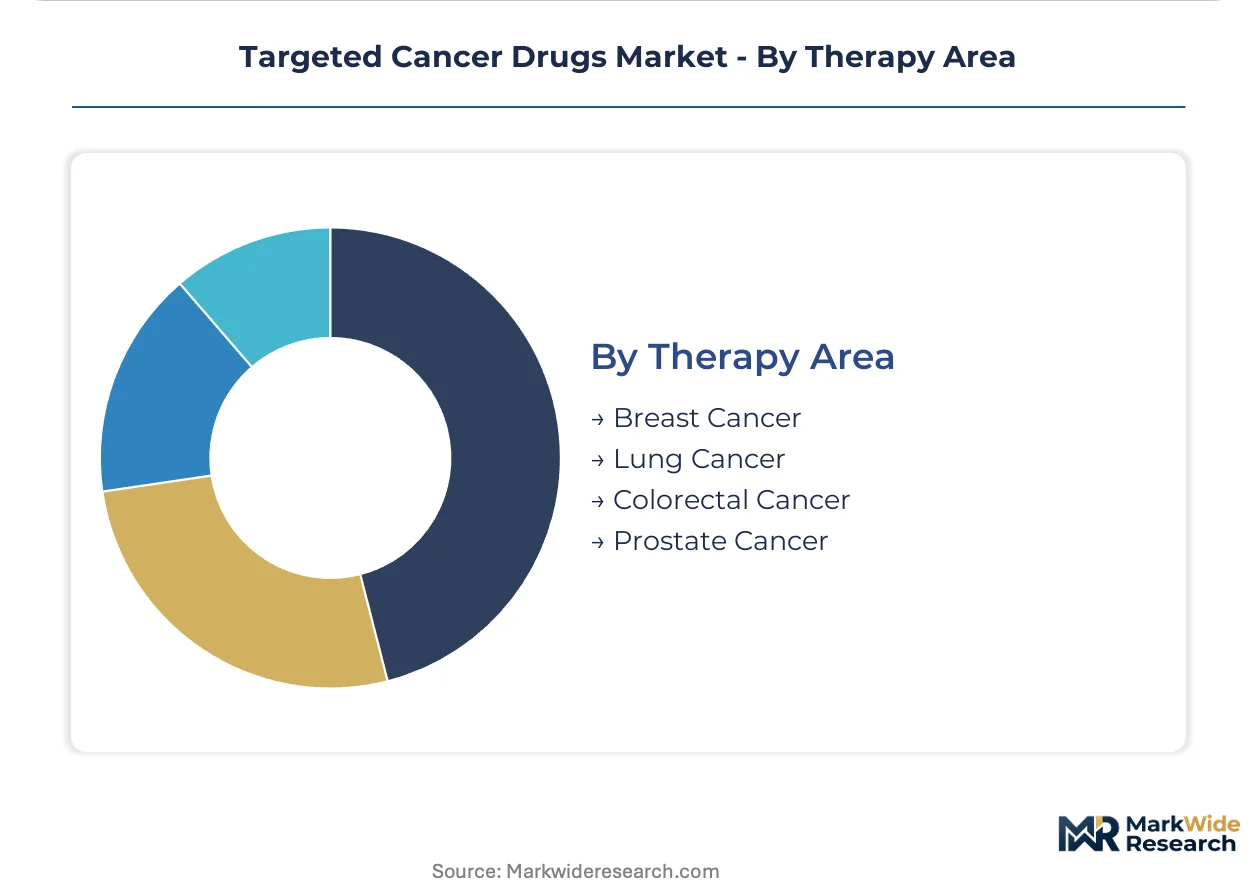
- Breast Cancer:HER2, HR-positive, and triple-negative subtypes with mature companion diagnostic pathways. Demand concentrates in United States and German clinics where HER2-low definitions expanded antibody-drug conjugate eligibility.
- Lung Cancer:Non-small cell and small cell histologies with EGFR, ALK, and KRAS biomarker stratification. Prescribing concentrates in Japan and South Korea where EGFR mutation frequency drives targeted therapy penetration.
- Colorectal Cancer:MSI-high and RAS-wildtype subsets with evolving immunotherapy and anti-EGFR positioning.
- Prostate Cancer:Castration-resistant and metastatic hormone-sensitive settings with PARP inhibitor and radioligand therapy integration.
Breast cancer commands the established base. The steepest expansion runs through lung cancer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States oncology clinics command premium pricing power that German university hospitals cannot replicate, creating a structural asymmetry in revenue capture across the Atlantic. This divergence concentrates investment flows toward FDA-aligned development programs while compressing margins in European reimbursement environments.
United States
Oncology clinics across Texas and Florida are expanding precision therapy infusion capacity to capture antibody-drug conjugate demand. The FDA's accelerated approval pathways enable earlier commercialization with confirmatory evidence requirements. Academic medical centers in Boston and Houston are consolidating CAR-T cell therapy manufacturing under centralized pharmacy formularies.
Germany
University hospitals in Munich and Heidelberg are anchoring radioligand therapy adoption through deep manufacturing partnerships with isotope suppliers. The EMA conditional marketing authorization framework compresses development timelines for novel mechanisms. The Rhine-Ruhr corridor is concentrating radiochemistry expertise at academic centers with specialized nuclear medicine infrastructure.
Japan
Tokyo and Osaka oncology networks are driving immune checkpoint inhibitor penetration in EGFR-mutant lung cancer settings. The PMDA oncology innovation scheme creates accelerated entry pathways for combination regimen developers. Kansai region hospitals are integrating companion diagnostic testing into standardized clinical pathways for biomarker-driven patient stratification.
United Kingdom
London and Manchester integrated care systems are consolidating oncology pharmacy procurement under outcome-based utilization criteria. The NHS England specialized commissioning framework shapes access negotiations for high-cost precision therapies. The Golden Triangle research cluster is anchoring early-phase clinical trial density for novel antibody-drug conjugate constructs.
Switzerland
Basel and Zurich hospital networks are leveraging proximity to pharmaceutical R&D headquarters for rapid protocol adoption. Swissmedic's streamlined authorization procedures enable earlier patient access compared to neighboring jurisdictions. The Lake Geneva region is concentrating diagnostic innovation partnerships that bridge biomarker validation with therapeutic development.
Targeted Cancer Drugs Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated diagnostic-drug platforms commanding premium positioning against pure-play developers. Large-cap biopharmaceuticals sustain advantage through manufacturing scale and companion biomarker ecosystems. Mid-cap precision therapy specialists compete on linker-payload engineering and radiochemistry expertise. The dominant competitive moves are strategic partnerships for isotope supply security and portfolio diversification into combination regimens.
Among Swiss-based pharmaceutical platforms, Roche and Novartis exemplify the integrated diagnostics-therapeutics archetype through their respective positioning in companion biomarker strategies and radioligand manufacturing scale. Bristol-Myers Squibb represents the immune checkpoint modulation specialist tier with extended presence in novel combination protocols. These three anchors demonstrate how geographic clustering around regulatory hubs and manufacturing infrastructure shapes competitive positioning in precision oncology.
| Leading Market Players |
|---|
| Roche |
| Novartis |
| Bristol-Myers Squibb |
| Merck & Co. |
| Pfizer |
| AstraZeneca |
| Johnson & Johnson |
| Eli Lilly and Company |
| Amgen |
| Others |
Value Chain & Pricing Dynamics
Ninety-day isotope inventory buffers at radioligand manufacturing sites tether pricing power to reactor scheduling reliability, concentrating margin capture among developers with captive supply agreements across North America and Europe. This lead-time exposure amplifies cost pass-through capacity for antibody-drug conjugates while squeezing monoclonal antibody portfolios facing biosimilar erosion.
Pricing Analysis
The customization-premium spread between site-specific conjugation chemistry and conventional linker-payload manufacturing commands substantial price differentiation in antibody-drug conjugate supply contracts. Value-based pricing anchored to progression-free survival endpoints dominates radioligand therapy positioning, while oral small molecule inhibitors compete on pharmacy benefit design tiering. Cost compression in mature monoclonal antibody franchises stems from reference product exclusivity expiration. Community oncology clinics exhibit highest price sensitivity; academic medical centers with outcome-based contracts demonstrate lowest sensitivity due to risk-sharing structures.
Supply Chain Analysis
Strait of Hormuz transit vulnerability exposes isotope shipments to Middle Eastern processing facilities, creating geographic chokepoint risk for radioligand therapy production. Active pharmaceutical ingredient manufacturing draws from India, China, and Switzerland for small molecule kinase inhibitors, while antibody production rests on Chinese hamster ovary cell line supply from the United States and Germany. Single-source vulnerability concentrates in lutetium-177 and actinium-225 isotope supply. Distribution runs through integrated delivery network centralized formularies in the United States and German university hospital pharmacy consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA accelerated approval pathway compression and EMA conditional marketing authorization convergence are reshaping commercialization timelines faster than legacy clinical infrastructure can adapt, creating asymmetric opportunity for agile developers.
For Market Incumbents: Consolidate manufacturing scale in radioligand therapies through isotope supply security partnerships, defending against emerging precision therapy specialists with captive reactor access. Deepen companion diagnostic integration to lock in biomarker-driven patient stratification protocols. Prioritize vertical integration into linker-payload engineering capabilities to differentiate antibody-drug conjugate clinical outcomes.
For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-track enables earlier revenue recognition for novel mechanism immune checkpoint combinations, creating entry wedge against established PD-1 franchises. Target Japan's PMDA oncology innovation scheme for accelerated geographic expansion. Pursue community oncology channel partnerships for oral small molecule distribution to bypass hospital formulary gatekeeping.
For Investors and Strategic Acquirers: Long-term, this sits as a capability-scarcity play because radiochemistry expertise concentrates at limited academic centers with nuclear medicine infrastructure, constraining manufacturing workforce expansion for radioligand platforms. Acquisition targets should display deep isotope handling partnerships or site-specific conjugation chemistry IP. Monitor confirmatory study enrollment velocity as inflection indicator for accelerated approval sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerated approval pathways compress development timelines while mandating confirmatory evidence generation through FDA frameworks. |
| Manufacturing Scale-Up | Radioligand therapy production expansion hinges on nuclear reactor infrastructure partnerships across North America and Europe. |
| Regulatory Approval Pathway | EMA conditional marketing authorization enables earlier European commercialization for novel mechanism precision therapies. |
| Licensing Agreement | Companion diagnostic co-development partnerships secure biomarker-driven patient stratification protocols for targeted therapy eligibility. |
| Pipeline Diversification | Combination regimen development extends immune checkpoint inhibitor positioning into novel protocol settings beyond monotherapy. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists across the United States, Germany, and Japan. Secondary validation incorporated FDA accelerated approval filings, EMA conditional marketing authorization submissions, ClinicalTrials.gov protocol registries, and integrated delivery network formulary databases. Bottom-up patient population modeling and top-down revenue triangulation were cross-referenced to anchor segmentation outputs.
Across the analysis window, the forecasting framework modeled treatment line stratification, administration route differentiation, regional regulatory cluster clustering, and companion diagnostic penetration rates. CAGRs were derived from segment-level growth rate synthesis anchored to biomarker prevalence epidemiology and reimbursement access velocity. Forecast inputs incorporated isotope supply capacity expansion schedules and biosimilar launch sequencing assumptions.
Underlying assumptions cover confirmatory study completion rates and reimbursement policy stability, with deviation risk concentrated in accelerated approval withdrawal scenarios and radioligand manufacturing disruption events. Practitioners should keep alternative scenarios live as FDA confirmatory evidence requirements and EMA conditional authorization renewal criteria evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Europe Cell Culture Market
Medical Biotechnology
Global Preimplantation Genetic Diagnosis (PGD) Market
Medical Biotechnology
Antimicrobial Peptides Market
Medical Biotechnology
Nerve Growth Factor (NGF) Market
Medical Biotechnology
Recombinant Human Endostatin Market
Medical Biotechnology
Global DNA Vaccines Market
Medical Biotechnology
X-Linked Hypophosphatemia Market
Medical Biotechnology
Leprosy Vaccines Market
Medical Biotechnology
Amoxicillin Market
Medical Biotechnology
Global Metformin-Pioglitazone Market
Medical Biotechnology
Mitochondrial Myopathies Market
Medical Biotechnology
Becker Muscular Dystrophy Market
Medical Biotechnology
Morgellons Disease Market
Medical Biotechnology
Mecobalamin Injection Market
Medical Biotechnology
Anti-Cathepsin B Market
Medical Biotechnology
Cell and Tissue Preservation Market