
 Paediatric Oncology Therapeutics Market | 2026-2036
Paediatric Oncology Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Paediatric Oncology Therapeutics Market Analytics
Specialty pharmacy distribution is narrowing as hospital-centric procurement tightens control over high-cost paediatric oncology therapies. Pfizer Inc. leverages its established hospital formulary relationships to secure preferred positioning for infused agents. Novartis AG anchors its presence through dedicated paediatric commercial teams that navigate complex reimbursement pathways for rare childhood malignancies. Bristol Myers Squibb Company differentiates via immuno-oncology platforms calibrated for adolescent and young adult protocols.
Paediatric oncology therapeutics comprise age-appropriate formulations of cytotoxic, targeted, and immunomodulatory agents, dosed by body surface area or weight with pharmacokinetic adjustments for developing organ systems, intended to achieve disease remission while minimizing long-term developmental toxicity. Chemotherapy retains the largest volume share but carries compressed margins due to generic erosion, whereas immunotherapy commands premium positioning as checkpoint inhibitors expand into relapsed settings. Targeted therapy occupies the fastest-expanding margin pool as biomarker-directed protocols in leukemia and lymphoma shift standard-of-care expectations.
The FDA mandates paediatric investigation plans under the Best Pharmaceuticals for Children Act, compelling sponsors to generate age-specific safety data or face delayed exclusivity, while the EMA enforces comparable obligations through its Paediatric Committee, elevating development costs but expanding labelled indications. The EU's Clinical Trials Regulation harmonizes multi-country study execution, reducing redundant ethical reviews across member states. Stakeholders must monitor how real-world evidence requirements from both agencies reshape post-approval commitment burdens and portfolio prioritization decisions.
Market Dynamics
The FDA's paediatric investigation mandate and EMA's Paediatric Committee obligations are forcing sponsors to generate age-specific safety data before approval, elevating development costs while expanding labelled indications for childhood malignancies.
Growth Catalysts
- Biomarker-directed protocols:Leukaemia and lymphoma treatment pathways increasingly integrate genomic profiling, shifting standard-of-care expectations toward precision dosing regimens calibrated for developing organ systems.
- EU Clinical Trials Regulation:Harmonized multi-country study execution reduces redundant ethical reviews across member states, accelerating patient recruitment timelines for rare paediatric oncology indications.
- United States referral networks:Consolidated childhood cancer centres in Boston, Houston, and Memphis concentrate trial-ready patient populations, enabling faster endpoint achievement for sponsors.
Market Restraints
- Small molecule API volatility:Cytotoxic chemotherapy feedstock costs fluctuate with petrochemical derivatives and specialized fermentation capacity constraints in India and China.
- Paediatric formulation complexity:Age-appropriate dosing requires liquid suspensions, taste-masked tablets, or weight-calibrated infusions that extend manufacturing timelines beyond adult-equivalent products.
- Exclusivity delay risk:Sponsors failing to submit paediatric study plans face FDA-mandated extension of approval timelines, compressing effective patent life for blockbuster candidates.
Strategic Opportunities
- Adolescent and young adult protocols:The 15-39 age bracket remains underserved by both paediatric and adult oncology services, creating white space for cross-listed indications and dedicated trial infrastructure.
- Real-world evidence pathways:Both FDA and EMA are expanding post-approval commitment frameworks that reward sponsors generating long-term developmental toxicity data with extended labelling.
- Hospital-centric procurement consolidation:Integrated delivery networks in Germany and Japan are centralizing oncology pharmacy operations, creating preferred vendor status for suppliers with dedicated paediatric commercial teams.
Industry Challenges
- Paediatric pharmacokinetic expertise scarcity:Qualified investigators capable of designing body-surface-area dosing studies with developmental toxicity endpoints are concentrated at fewer than fifty academic medical centres worldwide.
- Long-term follow-up infrastructure:Five-year survival endpoints require sustained registry participation that strains hospital administrative resources and patient retention protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paediatric Oncology Therapeutics Market |
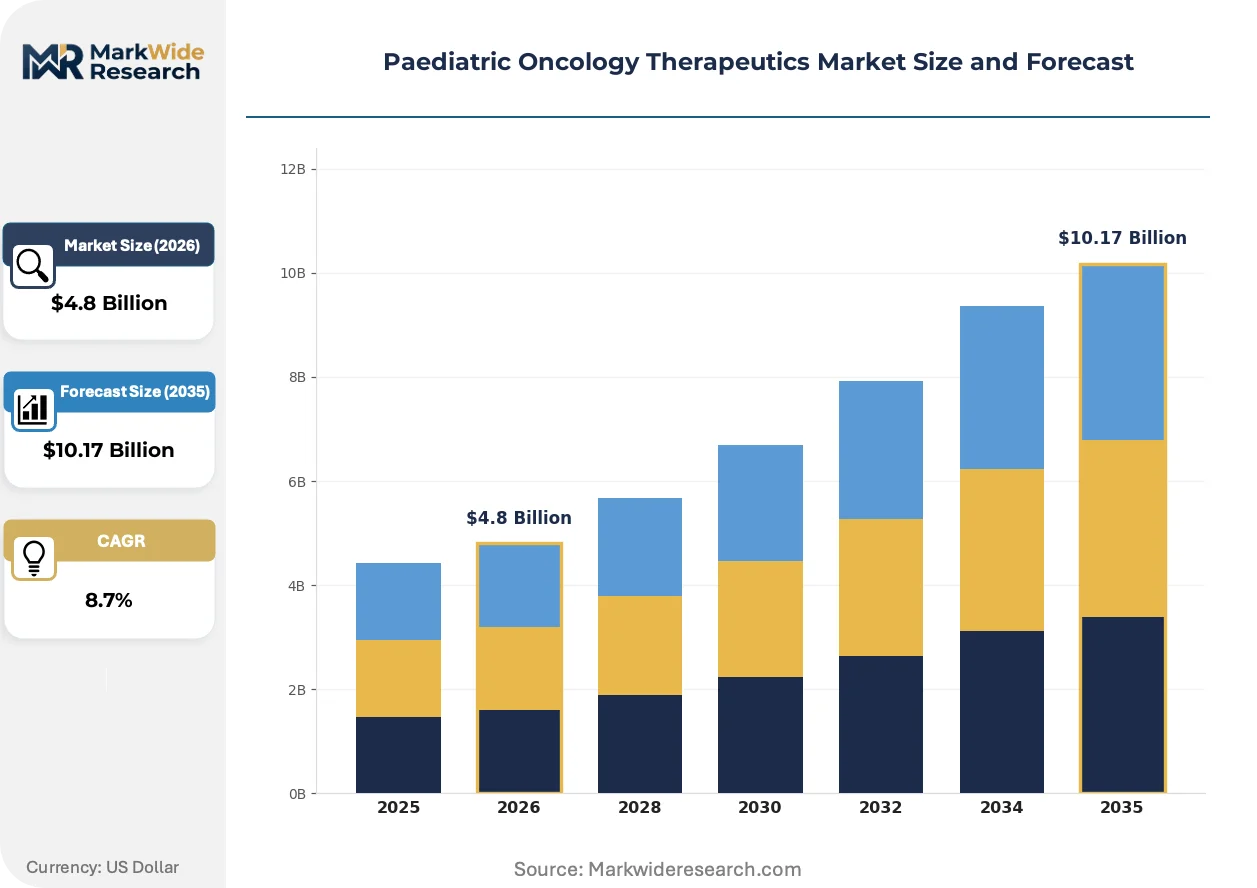
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Hormonal Therapy Therapy Area: Lymphoma, Leukemia, Neuroblastoma, Wilms Tumor Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular End User: Pediatric Hospitals, Research Institutions, Oncology Clinics, Outpatient Facilities |
| Companies Covered | Pfizer Inc., Novartis AG, F. Hoffmann-La Roche Ltd., Bristol Myers Squibb Company, Merck & Co., Inc., Sanofi S.A., AbbVie Inc., Takeda Pharmaceutical Company Limited, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paediatric Oncology Therapeutics Market Evolving Landscape
Checkpoint inhibitor expansion into relapsed paediatric settings is compressing chemotherapy's historical dominance, while biomarker adoption and procurement consolidation reshape how therapies reach paediatric patients.
Chimeric antigen receptor T-cell therapy is rendering obsolete salvage chemotherapy protocols for B-cell acute lymphoblastic leukaemia. Children's hospitals in Philadelphia and Cincinnati have adopted CAR-T as second-line standard, compressing admission volumes for high-dose cytarabine regimens and reallocating pharmacy budgets toward cell processing infrastructure.
REACH registration requirements for novel chemical entities are tightening impurity specifications for paediatric oncology APIs manufactured in European Economic Area facilities. Sponsors sourcing active pharmaceutical ingredients from third-party manufacturers in India must now demonstrate compliance with enhanced genotoxic impurity thresholds, delaying CMC timelines for new molecular entities by six to twelve months.
Consolidated buying by hospital formularies is displacing specialty pharmacy distribution for infused paediatric oncology agents. Integrated delivery networks in the United States now require sole-source contracts for high-cost immunotherapies, stripping margin from independent specialty pharmacies and concentrating negotiating leverage with procurement officers at academic medical centres in New York, California, and Texas.
Paediatric Oncology Therapeutics Market Segmentation
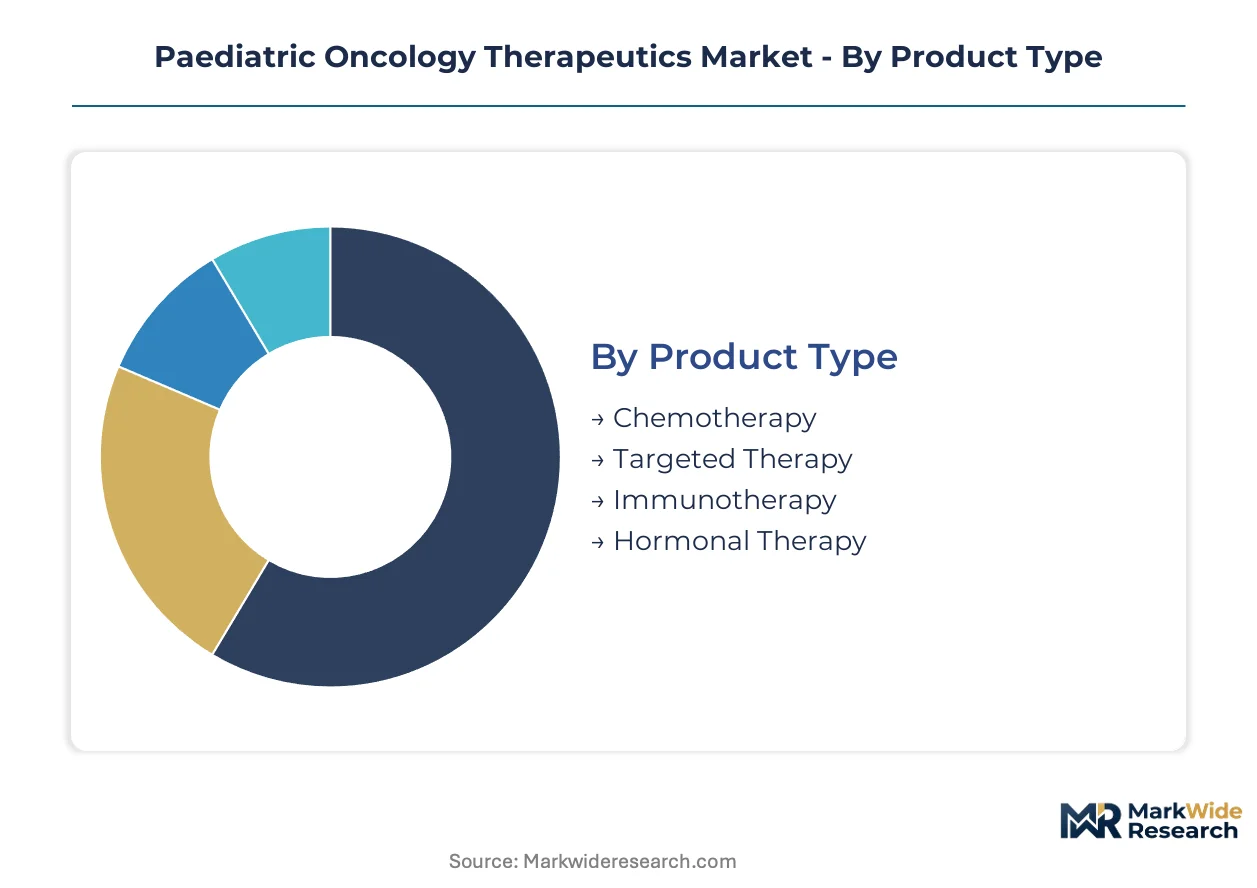
Paediatric oncology therapeutics demand divergent formulation strategies across treatment modalities, with dosing complexity and organ-system maturity dictating viable delivery pathways. Segmentation reveals where hospital procurement concentrates spending versus where development pipelines allocate clinical trial resources.
Product Type:
Use-case spectrum spans curative intent protocols through palliative regimens, with each modality carrying distinct manufacturing, reimbursement, and toxicity-monitoring requirements.
- Chemotherapy:Cytotoxic alkylating agents, antimetabolites, and plant alkaloids dosed by body surface area retain the largest prescription volume. Demand concentrates in United States academic medical centres for front-line leukemia protocols, though generic erosion compresses margins and limits sponsor investment in novel formulations.
- Targeted Therapy:Small-molecule inhibitors and monoclonal antibodies directed at specific oncogenic drivers. Adoption is climbing fastest in European precision medicine networks for relapsed acute lymphoblastic leukemia with actionable mutations, where biomarker-directed protocols justify premium reimbursement.
- Immunotherapy:Checkpoint inhibitors and biologic response modifiers calibrated for immature immune systems. CAR-T cell therapies and PD-1 inhibitors are displacing salvage chemotherapy in Philadelphia and Cincinnati children's hospitals.
- Hormonal Therapy:Corticosteroids and growth-suppression agents used in combination regimens for specific malignancies. Demand tracks pediatric endocrinology referral patterns at specialized centres in Boston and Houston.
Established volume favors chemotherapy; emerging adoption favors targeted therapy.
Therapy Area:
Patient population size and five-year survival benchmarks determine where pharmaceutical development resources concentrate.
- Lymphoma:Hodgkin and non-Hodgkin subtypes with relatively favorable prognosis. United States referral networks in Memphis and Houston drive protocol standardization, with checkpoint inhibitors expanding into relapsed settings.
- Leukemia:Acute lymphoblastic and myeloid leukemias representing the largest childhood cancer category. CAR-T therapy has rendered obsolete salvage chemotherapy protocols at Philadelphia and Cincinnati children's hospitals.
- Neuroblastoma:Peripheral nervous system malignancy requiring multimodal therapy. European centres in Paris and London anchor immunotherapy trials for high-risk disease.
- Wilms Tumor:Renal malignancy with surgical and chemotherapeutic management. Volume concentrates at specialized surgical oncology units within German pediatric hospital networks.
Leukemia commands the deepest development pipeline; lymphoma offers the most mature real-world evidence infrastructure.
Delivery Mode:
Formulation feasibility and patient compliance constraints shape viable administration pathways across age groups.
- Intravenous:Infused cytotoxic and biologic agents requiring hospital-based administration. Procurement is tightening within United States integrated delivery networks, with sole-source contracts displacing specialty pharmacy distribution.
- Oral:Liquid suspensions and taste-masked tablets for maintenance therapy. Formulation complexity extends manufacturing timelines beyond adult equivalents, particularly for weight-calibrated dosing in toddlers.
- Subcutaneous:Cytokine and supportive care agents enabling outpatient administration. Adoption is expanding in German and Japanese hospital-centric procurement systems for reduced admission duration.
- Intramuscular:Limited applications for specific hormonal and supportive therapies. Volume concentrates at outpatient facilities with dedicated pediatric nursing capability.
Hospital control favors intravenous; home-based care models favor oral and subcutaneous alternatives.
End User:
Procurement authority and clinical trial access determine where therapeutic revenues concentrate.
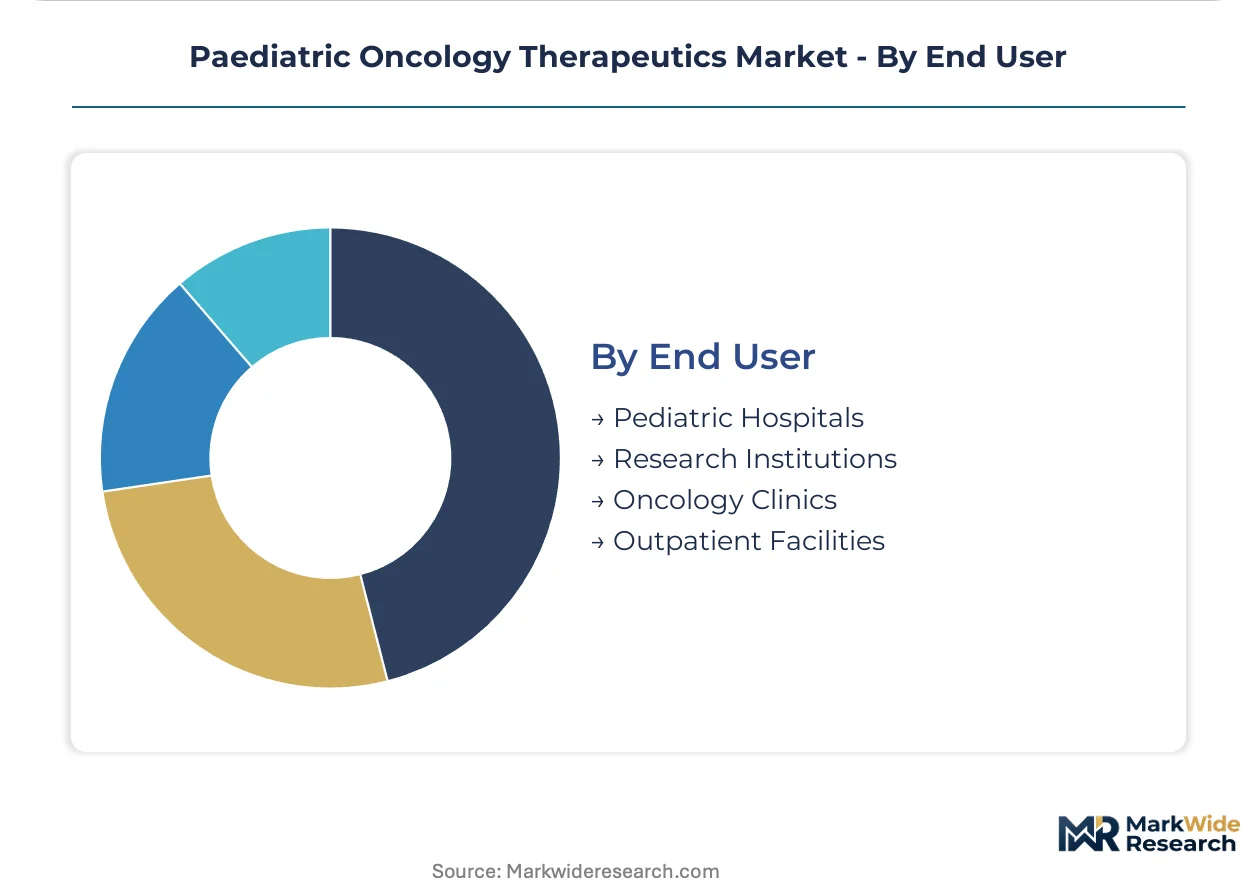
- Pediatric Hospitals:Dedicated oncology units with pharmacy infrastructure for high-cost infusions. Expansion across United States, German, and Japanese markets is consolidating buying power.
- Research Institutions:Academic medical centres with phase I/II trial capability. FDA-mandated pediatric investigation plans and EMA Paediatric Committee obligations anchor sponsor relationships.
- Oncology Clinics:Community-based facilities for stable disease monitoring and supportive care. Reimbursement complexity limits penetration of novel immunotherapies outside academic networks.
- Outpatient Facilities:Ambulatory settings for oral therapy administration and follow-up. Growth tracks expansion of home-based care models in United States referral networks.
Procurement consolidation favors pediatric hospitals; trial access favors research institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paediatric oncology therapeutics development concentrates where regulatory mandates intersect with established referral infrastructure and pharmaceutical manufacturing capacity. The FDA's paediatric investigation requirements and the EMA's Paediatric Committee obligations create compliance gravity centers that shape sponsor investment decisions across major markets.
United States
Memphis, Houston, and Boston anchor the densest concentration of childhood cancer referral networks, with St. Jude Children's Research Hospital and Texas Children's Hospital driving protocol standardization. The FDA mandates paediatric study plans under the Best Pharmaceuticals for Children Act, compelling sponsors to generate age-specific safety data or face delayed exclusivity. Integrated delivery networks in New York, California, and Texas now require sole-source contracts for high-cost immunotherapies, stripping margin from independent specialty pharmacies.
Germany
Heidelberg and Berlin host Europe's most active paediatric oncology trial sites, with the German Childhood Cancer Registry providing longitudinal outcome data that supports EMA submissions. The EU's Clinical Trials Regulation harmonizes multi-country study execution, reducing redundant ethical reviews across member states. Hospital-centric procurement consolidation across Bavaria and North Rhine-Westphalia is centralizing oncology pharmacy operations, creating preferred vendor status for suppliers with dedicated paediatric commercial teams.
Japan
Tokyo and Osaka pediatric hospitals are expanding dedicated oncology units with pharmacy infrastructure for high-cost infusions. The PMDA aligns with ICH E11 guidelines for paediatric clinical trials while maintaining distinct pharmacovigilance requirements for developmental toxicity monitoring. METI's healthcare innovation funding supports cell processing infrastructure investments at academic medical centers in the Kanto region.
United Kingdom
London and Manchester concentrate the NHS's paediatric oncology specialist centers, with the Cancer Research UK Children's Cancer Trials Team coordinating multi-site protocol execution. The MHRA's paediatric investigation plan enforcement mirrors FDA obligations post-Brexit, maintaining alignment with EU Paediatric Committee standards. Real-world evidence frameworks from NICE increasingly reward sponsors generating long-term developmental toxicity data with extended labelling.
France
Paris and Lyon anchor the SFCE (Société Française de Lutte contre les Cancers et Leucémies de l'Enfant et l'Adolescent) network, with Gustave Roussy Institute driving immunotherapy trial access. ANSM's paediatric regulatory science unit provides early dialogue pathways for sponsors developing age-appropriate formulations. The EU's REACH registration requirements tighten impurity specifications for APIs manufactured in European Economic Area facilities, extending CMC timelines for new molecular entities.
Paediatric Oncology Therapeutics Market Competitive Landscape
On the supply side, the industry is consolidating around hospital-centric procurement relationships and specialized paediatric commercial capabilities. Large-cap pharmaceutical incumbents with established hospital formulary access dominate infused agent categories, while mid-tier biotech specialists compete on biomarker-directed protocols. Three archetypes define positioning: diversified giants with paediatric-dedicated commercial teams, immuno-oncology platform specialists, and targeted therapy developers focused on rare childhood malignancies. Competitive moves concentrate on securing preferred vendor status at integrated delivery networks and navigating complex reimbursement pathways for high-cost cell therapies.
Within the diversified pharmaceutical tier, Pfizer Inc. and Novartis AG exemplify archetypes built on hospital formulary depth and dedicated paediatric infrastructure. Bristol Myers Squibb Company occupies a distinct position calibrated toward adolescent and young adult protocols, reflecting immuno-oncology platform specialization. These three entities represent the dominant competitive anchors against which reimbursement negotiations and trial access decisions are benchmarked across United States, German, and Japanese referral networks.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| F. Hoffmann-La Roche Ltd. |
| Bristol Myers Squibb Company |
| Merck & Co., Inc. |
| Sanofi S.A. |
| AbbVie Inc. |
| Takeda Pharmaceutical Company Limited |
| GlaxoSmithKline plc |
| Others |
Value Network & Pricing Analysis
Heidelberg and Berlin anchor European paediatric oncology API manufacturing capacity, where REACH registration compliance costs and specialized fermentation constraints translate directly into downstream pricing power for high-purity cytotoxic feedstocks. Hospital-centric procurement consolidation across German integrated delivery networks strips negotiating leverage from independent distributors, concentrating margin capture with academic medical centre pharmacy directors.
Pricing Analysis
Certification level (FDA-grade versus EMA-grade versus standard GMP) creates the primary spread across paediatric oncology therapeutics, with FDA-mandated paediatric investigation plans commanding premium positioning due to exclusivity protection value. Three-tier pricing structure across premium biologics, standard targeted agents, and economy cytotoxic generics reflects reimbursement complexity rather than manufacturing cost alone. Cost compression in chemotherapy tiers is intensifying because of generic erosion and sole-source contract demands from United States integrated delivery networks. Community oncology clinics exhibit highest price sensitivity due to limited formulary access, while academic medical centres with dedicated paediatric commercial teams absorb premium immunotherapy pricing through research grant offsets.
Supply Chain Analysis
Upstream petrochemical derivatives and specialized fermentation capacity in India and China supply cytotoxic chemotherapy APIs, while biologic response modifiers draw from mammalian cell culture facilities in the United States and Switzerland. Active pharmaceutical ingredients for targeted small molecules rest on rare earth mineral processing and sophisticated chromatography resin production concentrated in Germany and Japan. Single-source vulnerability pervades CAR-T cell processing infrastructure, where vector manufacturing and patient-specific leukapheresis handling create irreplaceable bottlenecks at Philadelphia and Cincinnati children's hospitals. Distribution runs through hospital pharmacy direct procurement, displacing specialty pharmacy intermediaries for infused agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where CAR-T cell therapy infrastructure and biomarker-directed protocol interoperability are reshaping competitive boundaries around data-sharing networks rather than molecule exclusivity alone.
For Market Incumbents: Pre-empt biosimilar erosion in cytotoxic chemotherapy by securing backward integration into specialized fermentation capacity in India, while simultaneously anchoring hospital formulary relationships through dedicated paediatric commercial teams that navigate FDA paediatric study plan requirements. Defensive consolidation must address the threat of CAR-T platform displacement by building cell processing infrastructure partnerships at Memphis and Houston referral networks. For New Entrants and Emerging Players: Establish a beachhead in adolescent and young adult protocols, the 15-39 age bracket underserved by both paediatric and adult oncology services, where cross-listed indication pathways offer faster regulatory traction. White space concentrates in real-world evidence generation platforms for long-term developmental toxicity monitoring, with go-to-market angles anchored through academic medical centre registry partnerships rather than traditional sales force deployment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors targeted therapy developers with biomarker-directed protocol capabilities over diversified cytotoxic chemotherapy portfolios facing generic compression. Long-term viability across the projection horizon hinges on CAR-T manufacturing infrastructure and FDA paediatric exclusivity assets. The acquisition target archetype combines paediatric pharmacokinetic expertise with hospital-centric procurement relationships. Watch FDA paediatric study plan submission timelines as the inflection signal for exclusivity value realization.| Strategic Initiative | Industry Significance |
|---|---|
| Paediatric Investigation Plan Submission | FDA-mandated age-specific safety data generation secures extended exclusivity for blockbuster candidates. |
| CAR-T Cell Processing Infrastructure | Hospital-based manufacturing partnerships at Philadelphia and Cincinnati compress salvage chemotherapy admission volumes. |
| Biomarker-Directed Protocol Development | Genomic profiling integration in leukemia and lymphoma shifts standard-of-care expectations toward precision dosing. |
| Hospital Formulary Sole-Source Contracting | Integrated delivery networks in New York and Texas strip margin from independent specialty pharmacies. |
| Real-World Evidence Registry Participation | Long-term developmental toxicity data generation supports EMA and FDA post-approval commitment frameworks. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up prescription volume modeling and top-down market size triangulation anchored segmentation outputs across treatment modalities.
Forecast inputs considered therapy line positioning, dosage form feasibility, administration route infrastructure, patient population referral patterns, and regional regulatory cluster obligations across the analysis window. CAGRs were derived from patient incidence trajectories, protocol adoption curves, and reimbursement evolution assumptions. Paediatric pharmacokinetic study completion rates and hospital formulary contract renewal cycles provided industry-specific forecast anchors.
Sensitivities concentrate around FDA paediatric study plan submission delays, REACH registration timeline extensions for API impurities, and CAR-T manufacturing capacity constraints at academic medical centres. Cross-checking against EMA Paediatric Committee approval databases and United States integrated delivery network procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Endocrinology Drugs Market
Biopharmaceuticals
Global Rheumatoid Arthritis Drugs Market
Biopharmaceuticals
Polyclonal Antibodies Market
Biopharmaceuticals
Immunocytokines Market
Biopharmaceuticals
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market
Biopharmaceuticals
North America Diabetes Drugs Market
Biopharmaceuticals
Global Anti-Tuberculosis Therapeutics Market
Biopharmaceuticals
Insulin Market
Biopharmaceuticals
Thailand Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Prokaryotic Recombinant Protein Market
Biopharmaceuticals
Purified Protein Derivative Market
Biopharmaceuticals
Middle East and Africa Insulin Delivery Devices Market
Biopharmaceuticals
Octreotide Market
Biopharmaceuticals
Next Generation Antibody Therapeutics Market
Biopharmaceuticals
Biologic Response Modifiers Market
Biopharmaceuticals
Global Biopharmaceuticals Market