
 Global Swine Fever Vaccine Market | 2026-2036
Global Swine Fever Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Swine Fever Vaccine Market Foresight
Chinese veterinary biomanufacturing capacity is rebalancing toward higher-titer live attenuated output following successive African Swine Fever epizootics. Boehringer Ingelheim leverages its European R&D base to sustain premium recombinant vector development for export markets. Ceva Santé Animale anchors Mediterranean and Latin American distribution through regional production subsidiaries. Merck Animal Health competes in North American contract vaccination programs with specialized intradermal delivery platforms.
Swine fever vaccines are immunological preparations containing inactivated or attenuated viral antigens formulated to elicit protective neutralizing antibodies against classical or African swine fever viruses, typically stabilized with adjuvants and administered via intramuscular or intradermal routes. These products serve the primary commercial purpose of preventing catastrophic herd mortality in intensive pork production systems where single outbreaks can eliminate entire breeding populations. Live attenuated vaccines dominate volume consumption across East Asian commercial pig farming operations where cost sensitivity and established cold-chain logistics favor traditional formulations. Recombinant vector platforms capture expanding margin pools in European and North American breeding farms where marker-assisted differentiation of infected from vaccinated animals commands regulatory and export premiums. Subunit and DNA categories remain developmental with concentrated investment from research institutions seeking DIVA-compliant alternatives.
FDA and USDA regulate importation and licensure of veterinary biologics in the United States through the Center for Veterinary Biologics, while China's Ministry of Agriculture and Rural Affairs and its National Veterinary Drug Institute enforce mandatory vaccination protocols and production facility inspections. EMA guidelines under the EU Veterinary Medicines Regulation standardize quality, safety, and efficacy benchmarks for products circulating in European member states. Stakeholders must monitor divergence between national eradication strategies and vaccine approval pathways as classical swine fever-free status negotiations reshape cross-border product registration requirements.
Market Dynamics
China's National Veterinary Drug Institute is accelerating mandatory batch-release testing protocols, forcing manufacturers to reconfigure quality-control workflows around higher-titer live attenuated output standards. Cold-chain infrastructure gaps in secondary pork-producing provinces compound distribution friction as biosecurity mandates tighten.
Growth Catalysts
- EU Veterinary Medicines Regulation harmonization:Standardized DIVA-compliant labeling requirements across member states reduce cross-border registration friction for recombinant vector producers seeking multi-market entry.
- Intensive breeding operations:Large-scale sow farms in Guangdong and Sichuan provinces are consolidating vaccine procurement under centralized veterinary service contracts, creating volume anchors for high-throughput manufacturers.
- CRISPR-edited attenuation:Gene-edited viral backbone technologies are shortening development timelines for next-generation live vaccines while preserving immunogenicity profiles.
Market Restraints
- Biological input volatility:Porcine serum albumin and cell culture media supply concentrates in Danish and Dutch bioprocessing clusters, exposing formulation costs to single-source disruption risk.
- EMA cold-chain mandates:Stringent 2-8°C stability documentation requirements for live attenuated products block market entry for manufacturers lacking validated logistics partnerships in Southern Europe.
- Marker vaccine substitution:EMA-authorized recombinant platforms with DIVA compatibility are displacing traditional inactivated formulations in export-oriented breeding herds, compressing addressable volume for conventional suppliers.
Strategic Opportunities
- Vietnam commercialization gap:ASF endemic zones in northern provinces lack domestic high-titer production capacity, creating first-mover advantage for cold-chain-equipped foreign suppliers with MOU pathways through Vietnam's Department of Animal Health.
- Intradermal delivery convergence:Needle-free jet injector platforms combined with thermostable adjuvant formulations are opening subcutaneous administration alternatives for smallholder cooperatives lacking trained veterinary staff.
- USDA contract vaccination programs:Federal cost-share initiatives for regional ASF preparedness are channeling procurement toward specialized intradermal delivery systems with automated dosing verification.
Industry Challenges
- Viral seed stock authentication:Multi-laboratory confirmatory sequencing requirements for master seed viruses are extending pre-licensure timelines by 8-14 months, straining R&D capitalization.
- Legacy farm management system integration:Digital vaccination record modules from incumbent herd management software vendors resist API interoperability with third-party immunization tracking platforms, fragmenting data continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Swine Fever Vaccine Market |
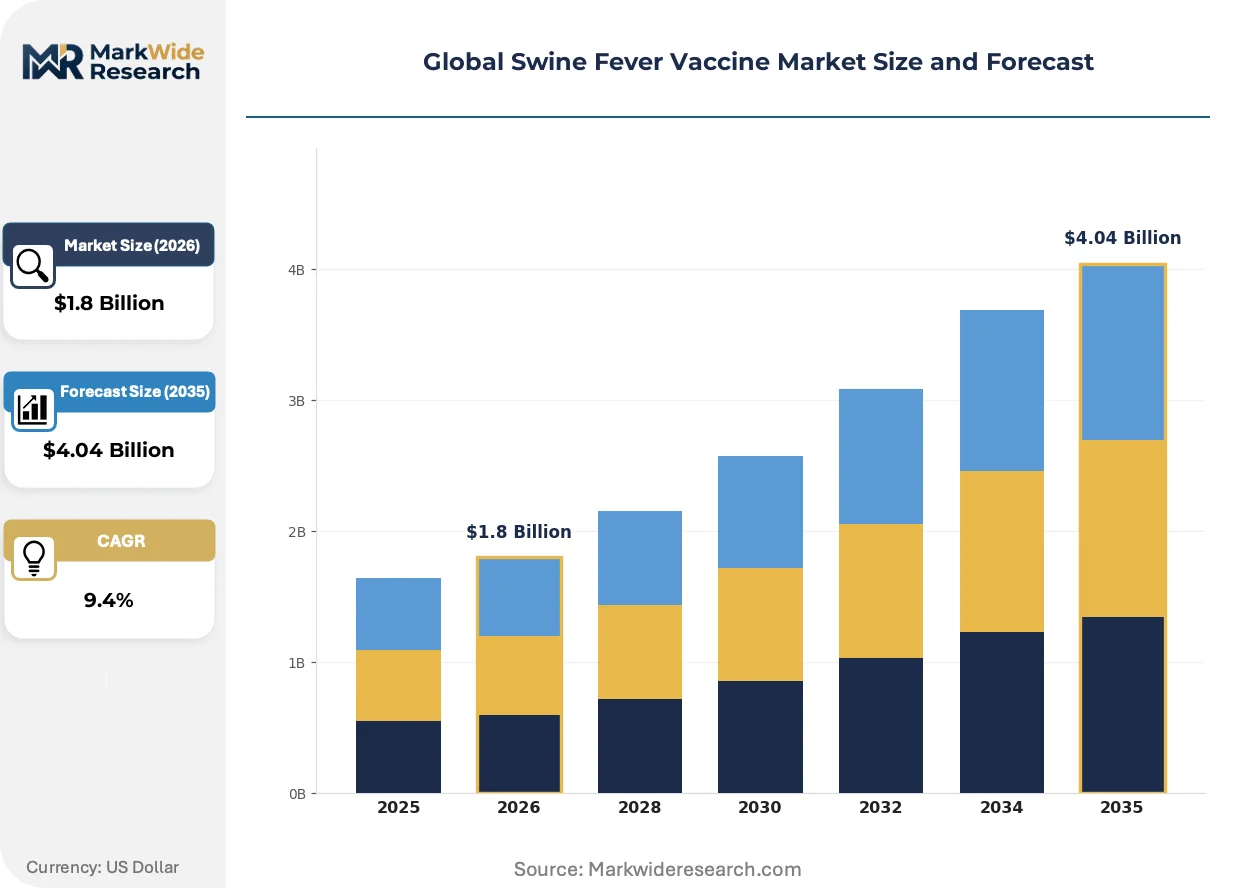
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Live Attenuated, Inactivated, Subunit, DNA, Recombinant Vector Application: Breeding Farms, Commercial Pig Farming, Backyard Production, Research Institutions Administration Method: Intramuscular Injection, Intradermal Injection, Oral, Nasal Spray End User: Veterinary Clinics, Diagnostic Laboratories, Animal Health Companies, Government Agencies |
| Companies Covered | CAHIC, Ceva Santé Animale, Boehringer Ingelheim, Ringpu Biology, Harbin Veterinary Research Institute, Merck Animal Health, Tecon Group, Qilu Animal Health, WINSUN Bio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Swine Fever Vaccine Market Shifts & Advancements
Gene-edited attenuation platforms are compressing development cycles while regulatory frameworks scramble to assess environmental release risks. Thermostable formulation chemistry and needle-free delivery systems are converging to decouple vaccine administration from cold-chain dependency.
CRISPR-Cas9 editing of viral virulence factors is absorbing regulatory scrutiny as China's National Veterinary Drug Institute develops gene-edited biologic classification guidelines distinct from transgenic organism protocols. Large-scale sow operations in Henan province are piloting these candidates under conditional use permits. The technology is absorbing market share from chemically attenuated predecessors by reducing reversion-to-virulence risk profiles.
EMA's 2024 revised environmental risk assessment guidelines for live veterinary vaccines are mandating extended shedding studies for candidates targeting notifiable diseases. Manufacturers must now submit 180-day horizontal transmission data for wild boar contact scenarios before centralized authorization. Recombinant vector platforms with documented host-restricted replication are capturing preference among Nordic breeding cooperatives supplying ASF-free export markets.
Consolidated procurement through veterinary service integrators is replacing direct farm-level purchasing in East Asian commercial operations. Large protein producers in Jiangsu province are outsourcing entire immunization programs to third-party animal health management firms with captive cold-chain fleets. This concentration is most visible in China's Yangtze River Delta, where single integrators now control vaccine logistics for 40,000-plus sow units.
Global Swine Fever Vaccine Market Segmentation
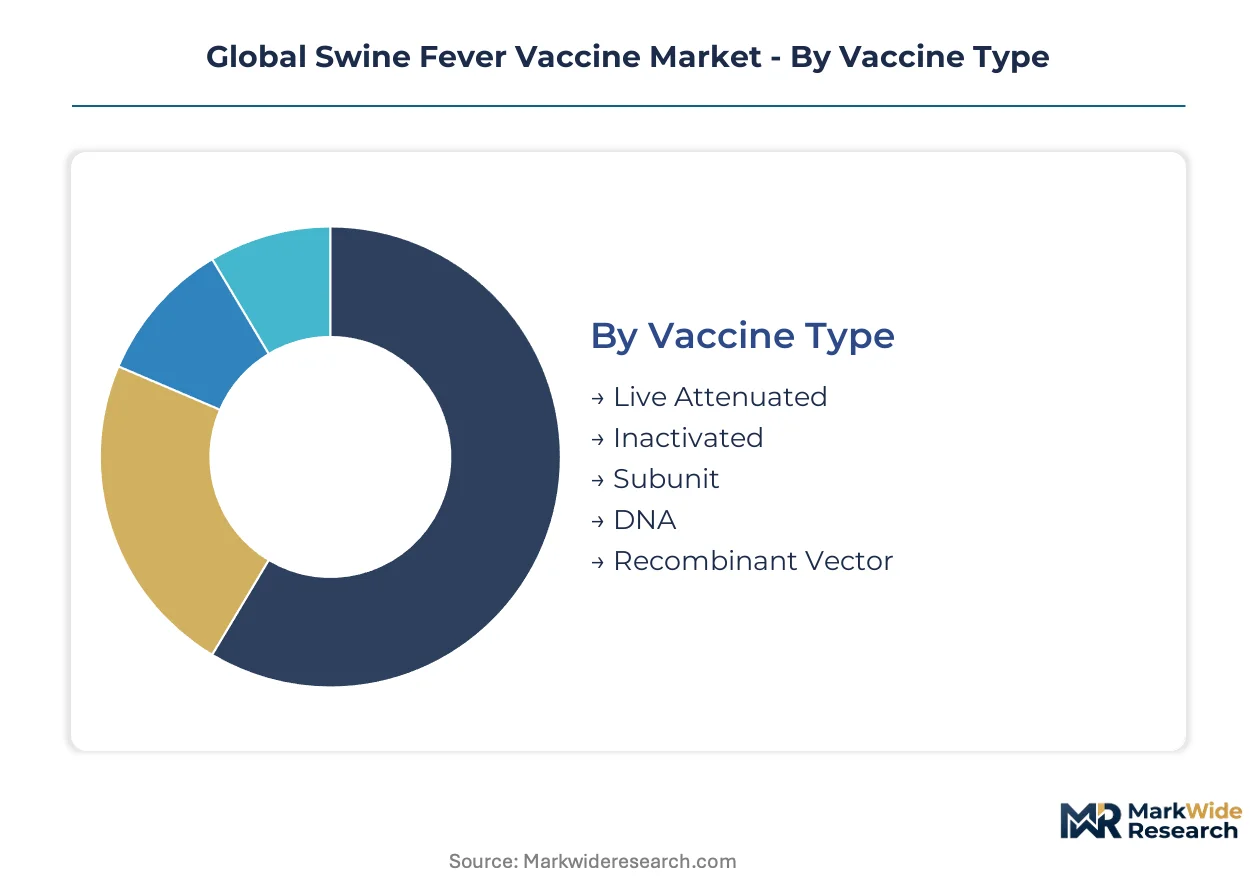
Vaccine type selection in swine fever prevention hinges on biosecurity tier, cold-chain maturity, and export eligibility requirements. Application context and administration feasibility further stratify procurement patterns across intensive versus smallholder production systems.
Vaccine Type:
Procurement decisions pivot on the trade-off between immunogenic robustness and DIVA compliance for international trade.
- Live Attenuated:Formulations contain chemically or genetically weakened viral particles that replicate transiently to stimulate cell-mediated immunity. Demand concentrates in China's Guangdong and Sichuan provinces where large sow units under government biosecurity mandates favor cost-effective herd-level protection despite cold-chain burdens.
- Recombinant Vector:Engineered viral backbones express swine fever antigens without productive replication, enabling serological differentiation of infected from vaccinated animals. European breeding cooperatives in Denmark and the Netherlands prioritize these platforms for ASF-free export certification under EMA guidelines.
- Inactivated:Chemically killed viral preparations stabilized with oil-based adjuvants require booster dosing but eliminate reversion risk. Southeast Asian smallholders lacking veterinary staff prefer these for simplified handling protocols.
- Subunit:Purified protein antigens formulated without viral genetic material offer theoretical safety advantages. Research institutions in Germany and the United States drive limited commercial offtake for experimental validation studies.
- DNA:Plasmid-based candidates encoding viral antigens remain developmental with no commercial licensure in major pork-producing jurisdictions.
Live attenuated leads on scale; recombinant vector leads on momentum.
Application:
Production system scale dictates vaccine specification, dosing frequency, and integration with herd health management software.
- Commercial Pig Farming:Intensive operations with 5,000-plus sow inventories demand high-throughput, multi-dose vial formats compatible with automated vaccination lines. China's Yangtze River Delta integrators now contract entire immunization programs to third-party animal health management firms with captive cold-chain fleets.
- Breeding Farms:Genetic nucleus and multiplier herds require DIVA-compliant platforms to preserve international semen and live animal export eligibility. Danish SPF cooperatives exclusively procure EMA-authorized recombinant vectors with documented marker compatibility.
- Backyard Production:Subsistence and smallholder operations across Vietnam's northern provinces and rural Philippines rely on government-subsidized live attenuated doses distributed through provincial veterinary stations.
- Research Institutions:Universities and national veterinary laboratories in the United States, Germany, and China purchase experimental formulations for challenge studies and regulatory dossier preparation.
Commercial pig farming commands procurement volume; breeding farms command specification premiums.
Administration Method:
Delivery route selection balances labor availability, equipment investment, and mucosal versus systemic immunity requirements.
- Intramuscular Injection:Standard deep-muscle delivery into the neck or ham region using 16-18 gauge needles remains the default for live attenuated and inactivated formulations. China's large-scale operations employ semi-automatic syringe systems with individual animal electronic identification linkage.
- Intradermal Injection:Needle-free jet injector platforms deposit antigen into the dermal layer, reducing tissue reaction and enabling lower dose volumes. USDA cost-share initiatives for regional ASF preparedness channel procurement toward these systems with automated dosing verification.
- Oral:Bait-delivered formulations target wild boar populations in European eradication zones and experimental domestic applications. EMA mandates 180-day horizontal transmission studies for environmental release authorization.
- Nasal Spray:Mucosal delivery mimics natural infection routes but requires specialized atomization equipment limiting adoption to research protocols.
Intramuscular injection retains infrastructure dominance; intradermal delivery gains share fastest among technology-adopting integrators.
End User:
Channel structure reflects regulatory custody, technical service bundling, and public versus private procurement authority.
- Animal Health Companies:Integrated manufacturers with captive R&D and production control formulation supply to distributor networks. Boehringer Ingelheim and Ceva Santé Animale leverage European bases for recombinant vector export while maintaining regional production subsidiaries.
- Veterinary Clinics:Private practitioners and corporate service chains administer vaccines under herd health contracts, particularly in North American and European markets with established veterinary service relationships.
- Government Agencies:China's Ministry of Agriculture and Rural Affairs, Vietnam's Department of Animal Health, and Brazil's Ministry of Agriculture coordinate centralized procurement for backyard producer subsidies and strategic reserves.
- Diagnostic Laboratories:Reference facilities validate vaccine efficacy through neutralizing antibody titration and PCR-based DIVA differentiation, supporting regulatory batch release.
Animal health companies anchor commercial volume; government agencies anchor price-sensitive procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting vaccine production toward jurisdictions with streamlined biologics approval pathways. Manufacturers now site high-titer live attenuated capacity in markets where batch-release testing burdens remain lighter than EMA-mandated protocols.
China
Guangdong and Sichuan provinces drive procurement volume through consolidated sow operations exceeding 40,000 head. The Ministry of Agriculture and Rural Affairs enforces mandatory vaccination protocols with facility inspections by the National Veterinary Drug Institute. Yangtze River Delta integrators now contract entire immunization programs to third-party animal health management firms with captive cold-chain fleets.
United States
Large-scale breeding cooperatives in Iowa and North Carolina prioritize DIVA-compliant platforms for export certification. FDA and USDA regulate importation through the Center for Veterinary Biologics, while federal cost-share initiatives channel procurement toward intradermal delivery systems. Midwestern contract vaccination programs now specify automated dosing verification as standard requirement.
Germany
Danish-border SPF cooperatives exclusively procure EMA-authorized recombinant vectors with documented marker compatibility. EMA guidelines under the EU Veterinary Medicines Regulation standardize quality benchmarks across member states. Lower Saxony bioprocessing clusters concentrate porcine serum albumin and cell culture media supply, exposing formulation costs to single-source disruption risk.
Vietnam
ASF endemic zones in northern provinces lack domestic high-titer production capacity, creating import dependency. The Department of Animal Health coordinates centralized procurement for backyard producer subsidies through provincial veterinary stations. Foreign suppliers with MOU pathways and cold-chain equipment capture first-mover advantage in commercial segments.
Brazil
Export-oriented breeding herds in Santa Catarina and Rio Grande do Sul states drive recombinant vector adoption for international trade eligibility. The Ministry of Agriculture enforces biosecurity mandates with production facility inspections. Southern cooperatives are consolidating vaccine procurement under centralized veterinary service contracts to secure volume pricing.
Global Swine Fever Vaccine Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue gene-edited attenuation platforms and thermostable formulations. The market structure consolidates around three strategic archetypes: European R&D-centric multinationals with recombinant vector specialization, Chinese state-linked manufacturers with live attenuated scale advantages, and regional distributors with captive cold-chain logistics. Dominant competitive moves include backward integration into viral seed stock production and strategic partnerships with veterinary service integrators replacing direct farm-level purchasing.
Within the multinational tier, Boehringer Ingelheim leverages its European base for recombinant vector export development while maintaining regional production subsidiaries. Ceva Santé Animale anchors Mediterranean and Latin American distribution networks through production subsidiaries. Merck Animal Health competes in North American contract vaccination programs with specialized delivery platforms. Chinese manufacturers CAHIC and Ringpu Biology exemplify the state-linked archetype with domestic high-throughput capacity serving government-mandated procurement programs.
| Leading Market Players |
|---|
| CAHIC |
| Ceva Santé Animale |
| Boehringer Ingelheim |
| Ringpu Biology |
| Harbin Veterinary Research Institute |
| Merck Animal Health |
| Tecon Group |
| Qilu Animal Health |
| WINSUN Bio |
| Others |
Supply & Pricing Matrix
Porcine serum albumin spot pricing volatility in Danish bioprocessing clusters cascades through formulation cost structures into three-tier pricing stratification across premium recombinant, standard live attenuated, and economy inactivated tiers. China's National Veterinary Drug Institute batch-release mandates compress margins on high-titer output while Vietnamese import dependency sustains premium capture for cold-chain-equipped foreign suppliers.
Pricing Analysis
Distributor margins of 18-25 percent separate manufacturer ex-works pricing from farm-gate procurement across East Asian markets. Three-tier pricing structure across premium recombinant vector, standard live attenuated, and economy inactivated levels reflects DIVA certification premiums and cold-chain service bundling. Pricing pressure stems from Chinese state-linked manufacturers scaling high-titer capacity under government procurement ceilings. Smallholder cooperatives in Vietnam's northern provinces exhibit highest price sensitivity; Danish SPF breeding cooperatives show lowest sensitivity due to export certification requirements.
Supply Chain Analysis
Specialized veterinary bioprocessing workforce availability concentrates in Lower Saxony's cell culture corridor, China's Yangtze River Delta biotech zones, and North Carolina's Research Triangle Park cluster. Viral seed stock production draws from porcine kidney cell lines, SPF-grade embryonated eggs, and chemically defined serum-free media. Single-source vulnerability pervades master seed virus repositories held at national veterinary institutes. Distribution runs through third-party animal health management integrators with captive cold-chain fleets replacing direct farm-level purchasing in consolidated procurement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in thermostable formulation chemistry and gene-edited attenuation platforms where R&D amortization spreads across widening addressable markets. Cost compression in cold-chain logistics from integrator consolidation amplifies premium-tier shift toward DIVA-compliant recombinant vectors.
For Market Incumbents: Lock in viral seed stock backward integration through exclusive licensing with national veterinary institutes to neutralize emerging CRISPR-edited platform threats. Secure capacity expansion in Vietnam through Department of Animal Health MOU pathways before regional cold-chain infrastructure matures. Certification investment in EMA environmental risk assessment documentation preserves Nordic breeding cooperative access against marker vaccine substitution pressure. For New Entrants and Emerging Players: Enter via needle-free intradermal delivery platform partnerships with USDA cost-share program administrators targeting Midwestern contract vaccination specifications. Vietnam's commercial pig farming segment offers the most penetrable white space given domestic high-titer production gaps and ASF endemic status. Go-to-market execution should anchor on provincial veterinary station relationships rather than direct large-integrator competition. For Investors and Strategic Acquirers: Asymmetric upside sits with gene-edited attenuation platform developers possessing conditional use permits from China's National Veterinary Drug Institute. Long-term viability over the projection horizon favors acquisition targets with thermostable formulation IP and validated wild boar horizontal transmission data under EMA guidelines. Monitor CRISPR-edited biologic classification guideline finalization as inflection signal for regulatory arbitrage repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Thermostable Formulation Development | Decouples vaccine distribution from cold-chain dependency in Southeast Asian smallholder markets. |
| Gene-Edited Attenuation Platform Advancement | Compresses development timelines while China's National Veterinary Drug Institute finalizes classification protocols. |
| Third-Party Integrator Partnership | Captures procurement concentration in China's Yangtze River Delta sow operations exceeding 40,000 head. |
| EMA Environmental Risk Assessment Submission | Unlocks Nordic breeding cooperative access through 180-day wild boar transmission documentation. |
| Provincial Veterinary Station Distribution Agreement | Secures government-subsidized channel access for backyard producer segments in Vietnam and Philippines. |
Research Methodology
Multiple input streams — veterinary biomanufacturing executives, regulatory affairs specialists at national drug institutes, herd health management integrators, and provincial veterinary officers — were reconciled against secondary validation from EMA centralized authorization procedures, USDA Center for Veterinary Biologics filings, and China's National Veterinary Drug Institute batch-release records. Bottom-up demand modeling across vaccine type, application, and administration method segments was triangulated with top-down market sizing from production capacity disclosures and procurement contract aggregations.
Data-stream reconciliation anchored volume and value outputs to segmentation dimensions spanning vaccine platform technology, production system scale, DIVA compliance tier, and regional regulatory cluster variations. CAGRs were derived from elasticity-adjusted penetration curves across the analysis window, incorporating veterinary service integrator consolidation rates and CRISPR-edited platform conditional use permit trajectories as industry-specific forecast inputs.
Inputs from national veterinary drug institutes and commercial integrators were available through the study window; gaps in pre-licensure viral seed stock sequencing timelines introduce uncertainty bands around gene-edited platform commercialization trajectories. Forecasts assume sustained EMA environmental risk assessment stringency and Chinese mandatory vaccination protocol continuity. Practitioners should monitor China's gene-edited biologic classification guideline publication and Vietnamese domestic production capacity announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Botanical and Plant Derived Drugs Market
Biopharmaceuticals
Glucagon Injectable Market
Biopharmaceuticals
Anti-Tumor Drugs Market
Biopharmaceuticals
Latin America Human Insulin Drugs Market
Biopharmaceuticals
Fenbendazole Market
Biopharmaceuticals
Iran Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Beta Interferon Market
Biopharmaceuticals
Benzbromarone API Market
Biopharmaceuticals
Biopharmaceutical CMO and CRO Market
Biopharmaceuticals
Global Upstream Bioprocessing Market
Biopharmaceuticals
Drug Resistant Pulmonary Tuberculosis Market
Biopharmaceuticals
Global Cytokine Market
Biopharmaceuticals
Plasma Protease C1-Inhibitor Market
Biopharmaceuticals
Human Combinatorial Antibody Libraries (Hucal) Market
Biopharmaceuticals
Global Anti-Infective Drugs Market
Biopharmaceuticals
Immunocytokines Market