
 Global Drug Discovery Technologies Market | 2026-2036
Global Drug Discovery Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Drug Discovery Technologies Market Analysis
China is fragmenting its drug discovery capacity through state-funded biotech parks in Shanghai and Suzhou. Thermo Fisher Scientific leverages its end-to-end reagent and instrument portfolio to dominate laboratory supply chains. Danaher Corporation sustains precision medicine workflows through its diagnostics and life sciences operating companies. Agilent Technologies specializes in analytical instrumentation for target validation and lead characterization.
Drug discovery technologies encompass the integrated platforms, computational tools, and laboratory methodologies used to identify, validate, and optimize therapeutic candidates from molecular targets through preclinical proof-of-concept. These systems employ assay miniaturization down to nanoliter volumes, CRISPR-based genetic perturbation, and machine-learning models trained on protein-ligand interaction databases to compress traditional ten-year development timelines. High-throughput screening retains the largest installed base but faces margin compression as commoditized plate readers proliferate. Bioinformatics captures expanding value pools as multi-omics data integration becomes essential for patient stratification. Genomics leads absolute spending among technology types, driven by plummeting sequencing costs and reference population databases.
The FDA's breakthrough therapy designation and the EMA's PRIME scheme compress regulatory review timelines, incentivizing investment in predictive toxicology and biomarker-qualified assays. China's NMPA reform of drug approval procedures and its inclusion in ICH guidelines are accelerating multinational trial placement in Shanghai and Beijing. Japan's PMDA sakigake designation further fragments Asia-Pacific regulatory competition for first-in-human studies. Stakeholders must monitor how AI-generated chemistry interacts with evolving intellectual property frameworks and whether emerging market regulators harmonize data integrity standards for algorithm-derived submissions.
Market Dynamics
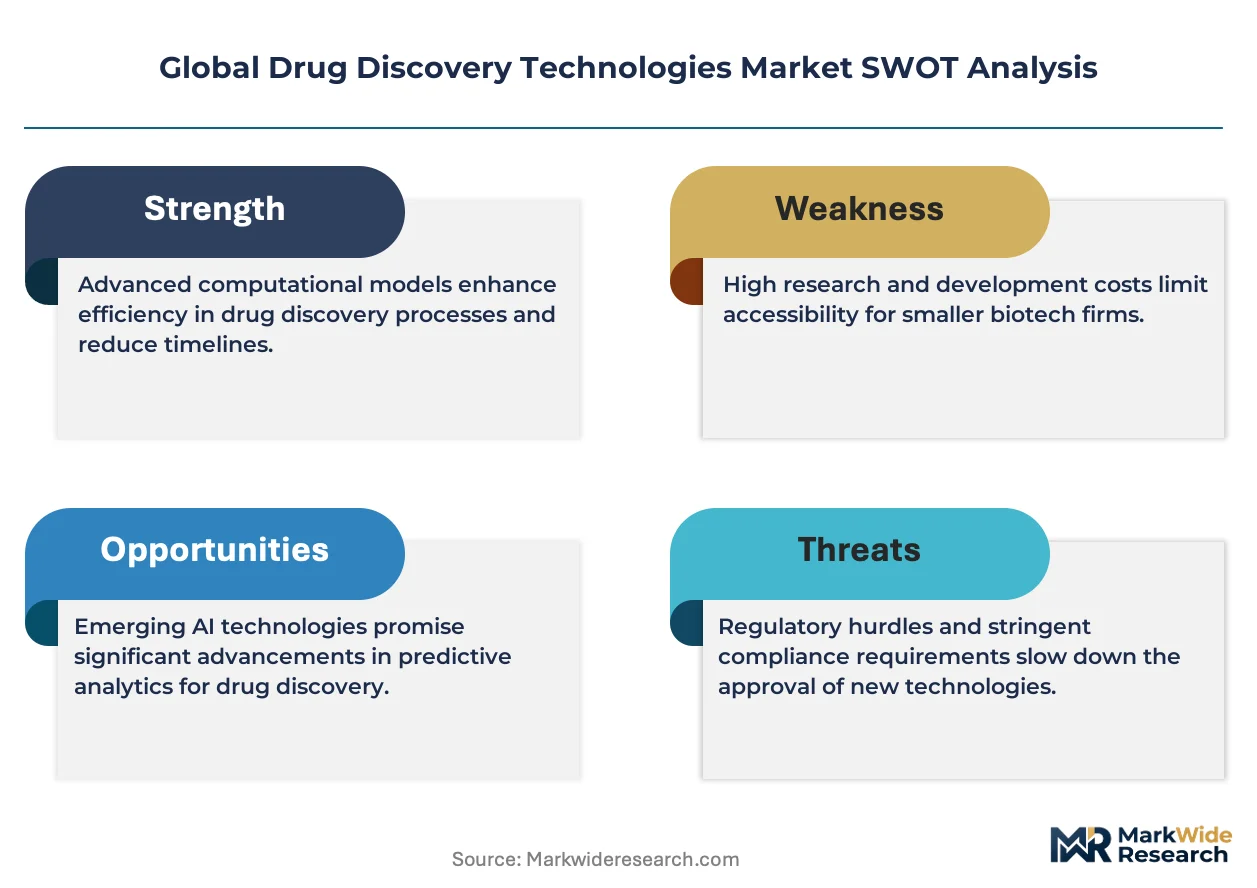
AI-driven screening platforms are compressing target-to-lead timelines from years to months, forcing contract research organizations to restructure fee-for-service models around milestone-based outcomes rather than full-time equivalent billing.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The pathway accelerates regulatory review for therapies addressing unmet medical needs, incentivizing biopharmaceutical firms to front-load investment in predictive toxicology assays.
- CRISPR-Based Genetic Perturbation:Functional genomics platforms enable rapid target validation across oncology and rare disease portfolios, displacing slower RNAi-based screening workflows in high-throughput environments.
- Shanghai-Suzhou Biotech Corridor:State-funded parks concentrate talent and capital infrastructure, drawing multinational placement of first-in-human studies away from traditional Western trial sites.
Market Restraints
- Sequencing Reagent Supply Concentration:Three suppliers control critical polymerase and flow-cell chemistries, exposing genome centers to price volatility and allocation rationing during demand surges.
- Algorithmic IP Uncertainty:Patent offices lack consistent frameworks for AI-generated molecular structures, chilling licensing negotiations and venture financing for computational chemistry startups.
- High-Content Imaging Capex Burden:Confocal screening systems require seven-figure capital commitments and specialized facilities, excluding mid-tier academic screening centers from competitive target validation.
Strategic Opportunities
- India's CDMO Expansion:The country's national pharmaceutical regulator harmonizes with ICH guidelines, enabling integrated discovery-to-manufacturing contracts for Western sponsors seeking cost arbitrage.
- Organ-on-Chip Convergence:Microfluidic tissue models merge with mass spectrometry readouts to replace animal efficacy studies, opening preclinical services revenue in jurisdictions tightening vivisection restrictions.
- Japan's Sakigake Designation:PMDA's priority review scheme for regenerative medicines attracts cell therapy developers to Tokyo-Osaka clinical trial networks ahead of Western regulatory submissions.
Industry Challenges
- Computational Biology Talent Scarcity:The intersection of cheminformatics and machine learning requires hybrid skill sets that traditional pharmaceutical training pipelines fail to produce at scale.
- Multi-Omics Data Integration Complexity:Harmonizing proteomic, metabolomic, and transcriptomic outputs across incompatible instrument platforms delays biomarker qualification for patient stratification.
- Legacy ELN Migration Friction:Electronic laboratory notebook vendors use proprietary data formats that obstruct AI training set assembly from historical assay archives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Drug Discovery Technologies Market |
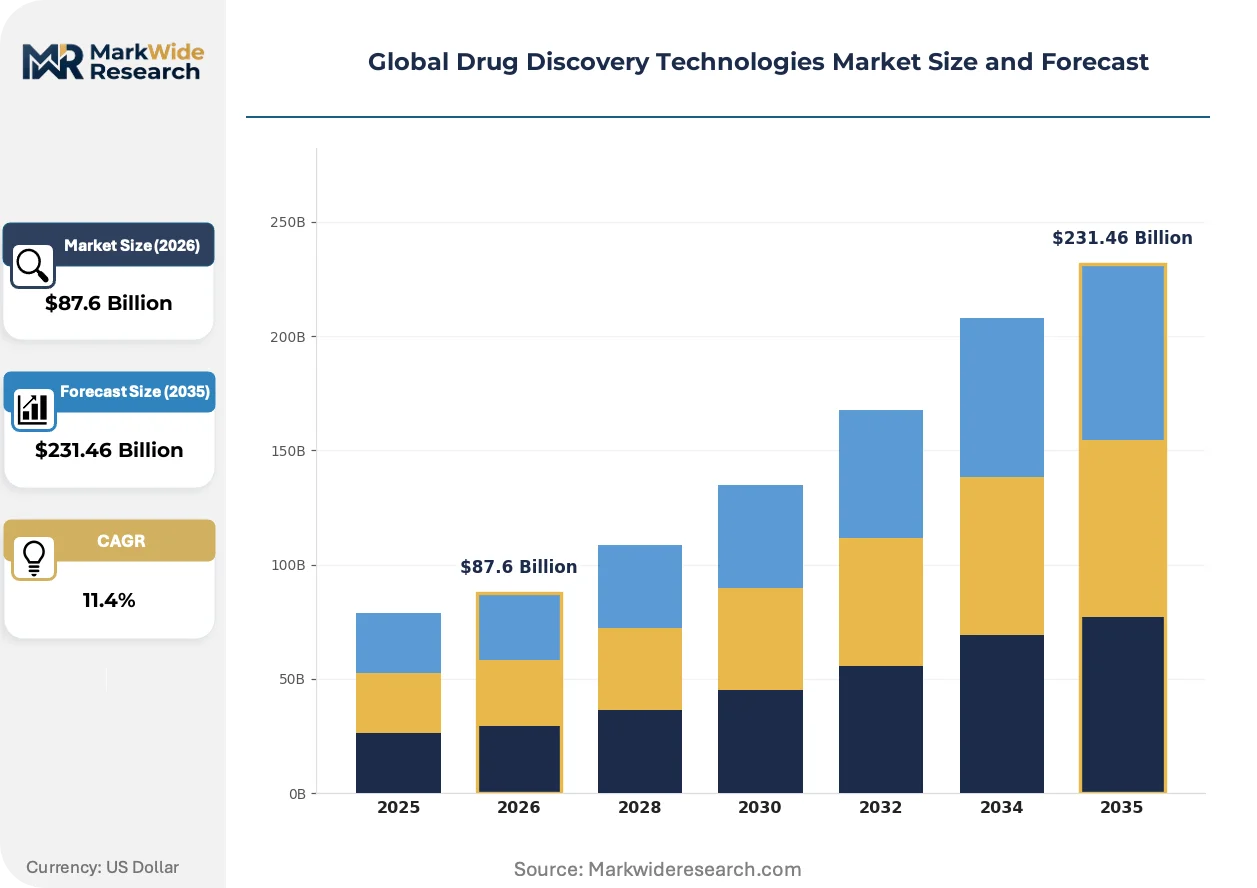
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Target Identification, Hit-to-Lead, Lead Optimization, Preclinical Development Technology Type: Genomics, Proteomics, Bioinformatics, High-Throughput Screening End User: Pharmaceutical Companies, Biotechnology Firms, Academic Research Institutes, Contract Research Organizations Solution: Software Tools, Lab Services, Data Analytics, Research Platforms |
| Companies Covered | Thermo Fisher Scientific Inc., Danaher Corporation, Agilent Technologies Inc., F. Hoffmann-La Roche Ltd, Merck KGAA, AstraZeneca PLC, Illumina Inc., Bio-Rad Laboratories Inc., QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Drug Discovery Technologies Market Emerging Trajectories
Discovery workflows are fragmenting into modular, cloud-accessible components that decouple data generation from analysis, enabling biotech startups to access enterprise-grade infrastructure without captive capital deployment.
AlphaFold-derived structural predictions are hybridizing with physics-based molecular dynamics simulations to prioritize compound libraries before wet-lab synthesis. Mid-cap biopharmaceutical firms in Boston and Basel are adopting these hybrid workflows within twelve-month implementation cycles. The compression of virtual screening cycles is displacing traditional high-throughput screening as the primary lead identification modality in kinase and GPCR target classes.
REACH registration requirements for novel chemical intermediates are extending supplier qualification timelines for European discovery chemistry operations. Contract manufacturers now demand eighteen-month advance commitments for custom synthesis of flagged molecular scaffolds. Biopharmaceutical procurement teams are responding by dual-sourcing critical intermediates from Swiss and North American suppliers to circumvent ECHA backlog.
Biotech venture capitalists now mandate that seed-stage companies demonstrate computational target validation before funding wet-lab operations, shifting risk allocation toward algorithmic proof-of-concept. This behavior change is most pronounced in San Francisco and Cambridge, where investors concentrate due diligence resources on machine-learning team quality rather than traditional medicinal chemistry credentials. The pivot is compressing founder backgrounds toward quantitative biology and away from classical pharmacology training.
Global Drug Discovery Technologies Market Segmentation
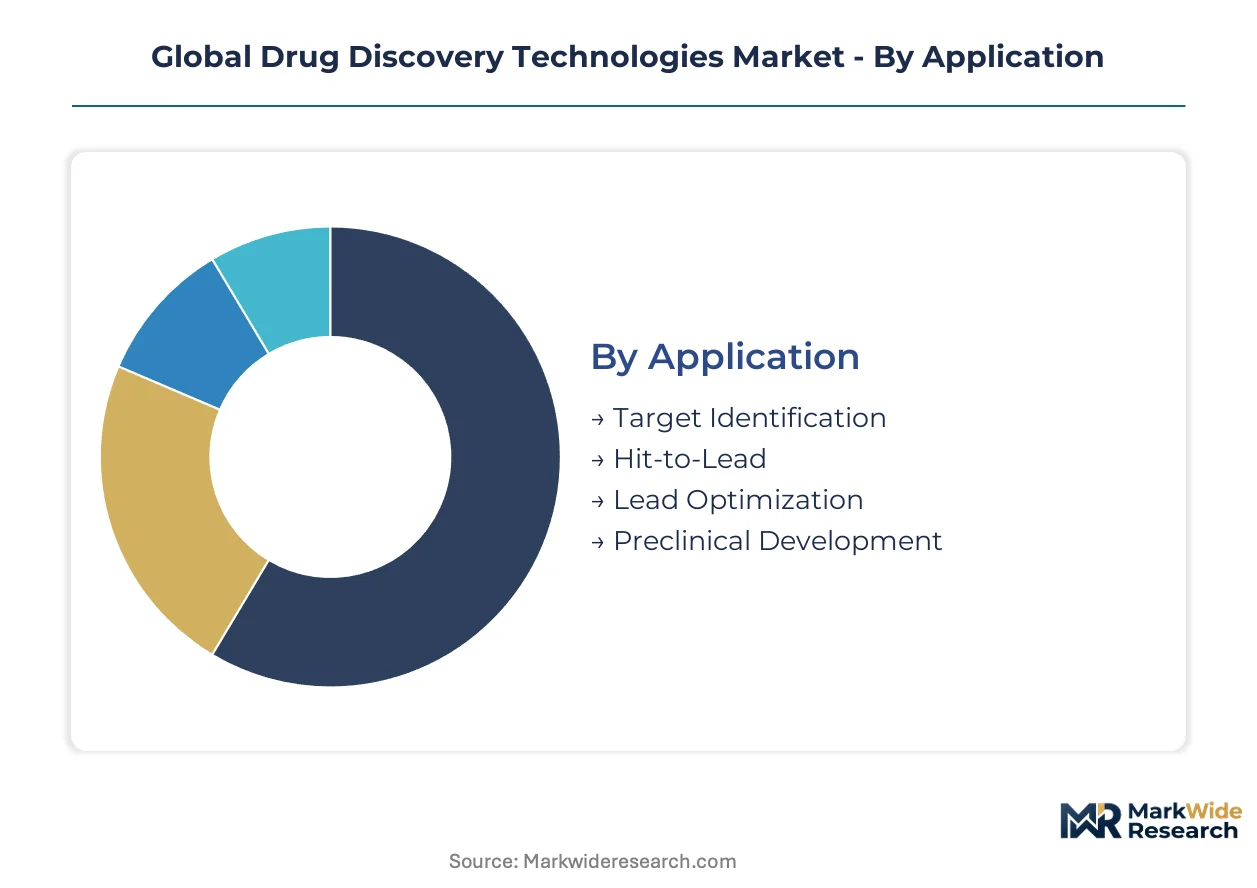
Drug discovery workflows fragment into specialized modules that match capital intensity to risk tolerance. Biopharmaceutical firms configure these segments differently across early-stage target validation versus late-stage candidate optimization.
Application:
Mature target identification workflows coexist with emerging AI-driven lead optimization protocols that compress traditional timelines.
- Target Identification:CRISPR-based functional genomics and RNA sequencing platforms validate disease mechanisms before chemical investment. Pharmaceutical companies in Boston and Basel concentrate spending here to derisk downstream portfolios. The FDA's breakthrough therapy designation accelerates timelines for validated oncology targets.
- Lead Optimization:Structure-guided medicinal chemistry and ADMET prediction models refine potency and safety profiles. China's NMPA reform incentivizes multinational sponsors to relocate optimization chemistry to Shanghai-Suzhou corridors for integrated IND-enabling packages.
- Hit-to-Lead:Fragment-based screening and biophysical characterization triage screening outputs.
- Preclinical Development:IND-enabling toxicology and pharmacokinetic studies bridge to human trials.
Target Identification handles the majority of throughput; Lead Optimization is climbing the fastest on share as AI tools mature.
Technology Type:
Cost tiers separate commodity instrumentation from premium analytics that command recurring revenue streams.
- Genomics:Next-generation sequencing and single-cell transcriptomics dominate absolute technology spending. Reference population databases in the United States and United Kingdom drive demand for variant interpretation pipelines. Plummeting per-base sequencing costs expand access to mid-tier biotechnology firms.
- High-Throughput Screening:Automated liquid handling and multimodal plate readers retain the largest installed base. Academic centers in Germany and Switzerland face margin compression as commoditized readers proliferate through Asian manufacturing.
- Bioinformatics:Multi-omics integration and machine-learning target prediction capture expanding value pools.
- Proteomics:Mass spectrometry-based protein quantification and interactome mapping enable mechanism validation.
High-Throughput Screening retains the largest installed footprint; Bioinformatics is expanding most quickly as data integration becomes essential.
End User:
Customer type determines procurement scale, with integrated pharmaceutical firms purchasing enterprise licenses versus project-based CRO engagements.
- Pharmaceutical Companies:Vertically integrated discovery operations span target validation through IND submission. San Francisco and Cambridge headquarters anchor the largest captive technology deployments. Internal AI teams displace external bioinformatics vendor relationships for core target classes.
- Contract Research Organizations:Fee-for-service models restructure around milestone-based outcomes as AI platforms compress timelines. India's CDMO expansion enables integrated discovery-to-manufacturing contracts for Western sponsors seeking cost arbitrage.
- Biotechnology Firms:Venture-backed startups access cloud-based screening infrastructure without captive capital.
- Academic Research Institutes:Grant-funded centers concentrate on target validation and mechanism studies.
Pharmaceutical Companies deploy the most capital-intensive infrastructure; Contract Research Organizations are gaining share fastest as outsourcing depth increases.
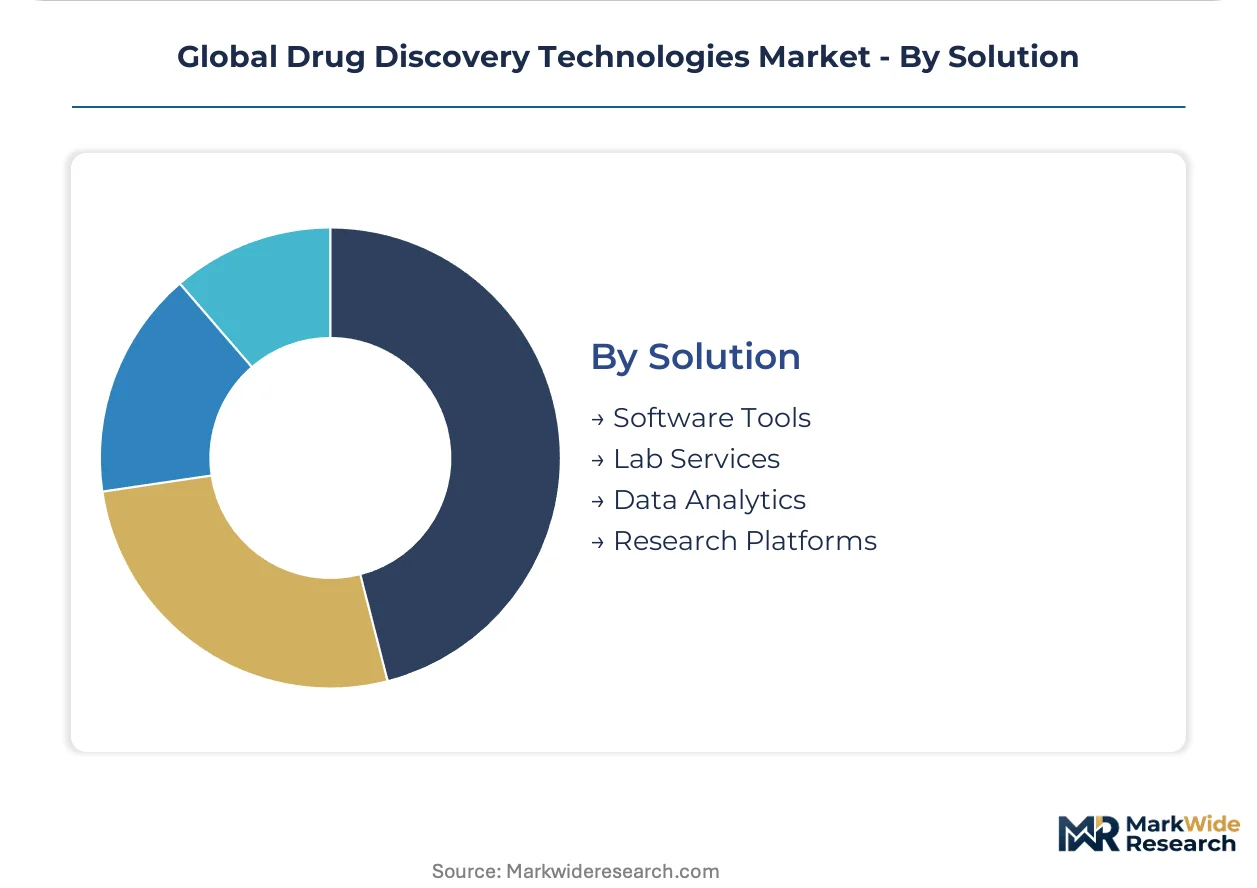
Solution:
Margin profiles diverge between recurring software subscriptions and project-based laboratory services.
- Software Tools:Computational chemistry suites and electronic laboratory notebooks command recurring revenue with high gross margins. Proprietary data formats from legacy ELN vendors obstruct AI training set assembly from historical archives.
- Lab Services:Custom synthesis and assay development generate project-based revenue with capital-intensive cost structures. REACH registration requirements extend supplier qualification timelines for European discovery chemistry operations.
- Data Analytics:Multi-omics integration and patient stratification algorithms monetize proprietary training sets.
- Research Platforms:Integrated hardware-software systems bundle instrumentation with analysis pipelines.
Lab Services handles the majority of transaction volume; Software Tools is the fastest mover on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates among three distinct national clusters. The United States, China, and Switzerland host the densest concentrations of discovery-stage infrastructure and regulatory innovation.
United States
FDA breakthrough therapy designations and accelerated approval pathways compress development timelines for oncology and rare disease programs. The agency's Center for Drug Evaluation and Research processes priority review vouchers within six-month windows. Boston and San Francisco anchor the largest clusters of venture-backed biotech firms, with Kendall Square alone housing over 120 discovery-stage companies.
China
State-funded biotech parks in Shanghai and Suzhou concentrate talent and capital infrastructure for integrated IND-enabling packages. NMPA reform of drug approval procedures and ICH guideline inclusion accelerate multinational trial placement. The Shanghai-Suzhou corridor now rivals Western sites for first-in-human study initiation.
Switzerland
Swissmedic's adaptive licensing frameworks and proximity to European reference markets attract precision medicine developers. Basel anchors cross-border discovery operations serving both EU and global trial networks. The country's dual-source chemical intermediate strategy circumvents REACH registration bottlenecks affecting continental European suppliers.
Germany
EMA centralized procedures and BfArM national scientific advice support complex biologic development programs. REACH registration requirements for novel chemical intermediates extend supplier qualification timelines, prompting procurement teams to dual-source from Swiss alternatives. Munich and Heidelberg concentrate mass spectrometry-based proteomics infrastructure for mechanism validation studies.
United Kingdom
MHRA's Innovative Licensing and Access Pathway maintains regulatory agility post-Brexit, preserving attractiveness for early-phase trials. The UK Biobank and Genomics England reference databases drive demand for variant interpretation pipelines. Cambridge and Oxford anchor AI-driven target prediction startups accessing cloud-based screening infrastructure.
Global Drug Discovery Technologies Market Vendor Landscape
Integrated life sciences conglomerates and specialized analytical instrument manufacturers split the market into distinct capability tiers. Thermo Fisher Scientific and Danaher Corporation anchor the consolidated upper tier through end-to-end reagent and workflow portfolios. Mid-tier players compete on modular bioinformatics subscriptions and niche assay technologies. Dominant competitive moves include strategic partnerships with AI-driven screening platforms and geographic expansion into China's state-funded biotech corridors.
Among integrated conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify the full-stack archetype spanning reagents through data analytics. Agilent Technologies Inc. occupies a specialized position within analytical instrumentation for target validation workflows. These three entities anchor distinct strategic positions without overlapping core competency claims.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Agilent Technologies Inc. |
| F. Hoffmann-La Roche Ltd |
| Merck KGAA |
| AstraZeneca PLC |
| Illumina Inc. |
| Bio-Rad Laboratories Inc. |
| QIAGEN |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on CRISPR reagent polymerases determines both tiered pricing spreads and supply chain resilience across discovery-stage operations. REACH registration bottlenecks for novel chemical intermediates force European sponsors toward dual-source strategies that widen price differentials between Swiss and continental suppliers.
Pricing Analysis
FDA breakthrough therapy designation dictates the pricing tier structure across predictive toxicology and biomarker-qualified assay portfolios. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified reagent bundles from research-grade consumables and open-source algorithmic tools. Cost compression in high-throughput screening plate readers is intensifying because Asian manufacturing commoditizes multimodal detection hardware. Mid-tier academic centers exhibit the highest price sensitivity, while integrated pharmaceutical firms in Boston and San Francisco absorb premium pricing for end-to-end workflow integration.
Supply Chain Analysis
Upstream feedstock concentration in Chinese polymerase manufacturing, Swiss fine chemical synthesis, and South Korean flow-cell fabrication creates structural vulnerabilities for Western genome centers. Critical inputs include CRISPR guide RNA chemistries, mass spectrometry ionization sources, and AI training-grade protein-ligand databases. Single-source vulnerability in sequencing reagent supply exposes buyers to allocation rationing during demand surges. Distribution runs through consolidated laboratory supply distributors serving pharmaceutical procurement teams and direct-to-academic e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in modular bioinformatics subscriptions as biotech startups demand cloud-accessible infrastructure without captive capital deployment. Algorithmic target validation is displacing traditional wet-lab proof-of-concept, creating niche entry points for computational chemistry specialists.
For Market Incumbents: Pre-empt displacement by CRISPR-based functional genomics platforms through captive supply of next-generation sequencing reagents and instrument portfolios. Deepen backward integration into flow-cell chemistries to secure allocation priority during demand surges. Lock in long-term service contracts with Boston and San Francisco biotech clusters before AI-driven screening platforms commoditize high-throughput screening workflows.
For New Entrants and Emerging Players: Build out organ-on-chip microfluidic tissue models for preclinical services revenue in jurisdictions tightening vivisection restrictions. White-space targets include India's CDMO corridor for integrated discovery-to-manufacturing contracts and cloud-based electronic laboratory notebook alternatives to legacy proprietary formats. Go-to-market angle centers on milestone-based outcome pricing that aligns with compressed AI-driven target-to-lead timelines.
For Investors and Strategic Acquirers: China's NMPA ICH harmonization reshapes the acquisition landscape by validating Shanghai-Suzhou infrastructure for multinational trial placement. Long-term viability favors computational biology startups with hybrid cheminformatics-machine learning teams over traditional medicinal chemistry houses. Target acquisition archetype: AI-driven target prediction platforms with validated training sets from UK Biobank or Genomics England reference databases. Signal to watch: FDA guidance on algorithm-derived submission data integrity standards.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Screening Platform Partnership | Thermo Fisher Scientific and Danaher Corporation anchor competitive positioning through computational chemistry integration. |
| Shanghai-Suzhou Biotech Corridor Expansion | State-funded parks attract multinational first-in-human study placement away from traditional Western trial sites. |
| Organ-on-Chip Preclinical Services Buildout | Microfluidic tissue models replace animal efficacy studies in jurisdictions with tightening vivisection restrictions. |
| Dual-Source Chemical Intermediate Strategy | Swiss and North American suppliers circumvent ECHA REACH registration bottlenecks affecting European discovery chemistry. |
| Cloud-Based ELN Migration | Proprietary data format obstruction of AI training set assembly creates replacement opportunity for interoperable alternatives. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with drug development executives, regulatory affairs leads at FDA and EMA, formulary directors at integrated delivery networks, and laboratory procurement managers at genome centers. Secondary validation drew from FDA breakthrough therapy designation filings, EMA PRIME scheme submissions, ClinicalTrials.gov protocol registries, and NMPA reform documentation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Calibration against historical regulatory approval timelines and technology adoption curves anchored the analytical framework. Segmentation dimensions modeled include application stage, technology type, end-user archetype, and solution delivery model across the projection horizon. CAGRs derived from regression analysis of installed base expansion and pricing trajectory assumptions. Industry-specific forecast inputs encompassed CRISPR reagent consumption patterns and AI-generated chemistry patent filing velocities.
Stress conditions across regulatory harmonization pace, sequencing reagent supply allocation, and algorithmic IP framework uncertainty were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about FDA breakthrough therapy pathway utilization and China ICH guideline adoption. Cross-checking against external benchmarks from OECD pharmaceutical R&D expenditure data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Nucleic Acid Aptamers Market
Biomedical Technology
Asia-Pacific Biomedical Sensors Market
Biomedical Technology
Global Cell Based Assays Market
Biomedical Technology
Vaccine Technology Market
Biomedical Technology
Fluorescent in Situ Hybridization Market
Biomedical Technology
Asia-Pacific Digital PCR Market
Biomedical Technology
Fluorescence-Activated Cell Sorting Market
Biomedical Technology
ST2 Biomarker Market
Biomedical Technology
PD L1 Biomarker Testing Market
Biomedical Technology
Bone Marrow Aspirate Concentrates (BMAC) Market
Biomedical Technology
Spine Biologics Market
Biomedical Technology
Neuro Immunoassay Market
Biomedical Technology
Lipid Transfer Proteins Market
Biomedical Technology
Ligases Enzyme Market
Biomedical Technology
Antibody Isotyping Kit Market
Biomedical Technology
US Liquid Biopsy Market