
 Latin America Human Insulin Drugs Market | 2026-2036
Latin America Human Insulin Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Human Insulin Drugs Market Foresight
Brazilian biosimilar manufacturers are restructuring production capacity to serve government tender programs across Latin America. Novo Nordisk leverages its recombinant DNA manufacturing scale to anchor insulin glargine supply for public hospital networks. Sanofi competes through differentiated pen-device ecosystems that reduce dosing errors in homecare settings. Eli Lilly specializes in rapid-acting analog formulations for Type 1 diabetes patients requiring prandial glucose control.
Human insulin drugs comprise recombinant protein therapeutics synthesized through engineered Escherichia coli or yeast expression systems, formulated to mimic endogenous pancreatic beta-cell secretion for glycemic regulation. These products require cold-chain preservation at 2-8°C to maintain tertiary protein structure and biological potency throughout distribution. Long-acting basal insulin analogs dominate hospital procurement due to reduced nocturnal hypoglycemia incidence and simplified dosing protocols. Pen-based delivery systems are displacing conventional vial-and-syringe methods in homecare segments, driven by patient self-administration preferences and reduced needle-phobia barriers.
ANVISA enforces GMP certification for imported biologics, while Mexico's COFEPRIS mandates local stability testing for insulin registration renewals, elevating compliance costs for non-regional manufacturers. Brazil's ANVISA and Argentina's ANMAT coordinate pharmacovigilance data sharing through Mercosur harmonization protocols, streamlining adverse-event reporting across member states. Stakeholders must monitor biosimilar interchangeability rulings and tender pricing dynamics to calibrate portfolio investments across public and private reimbursement channels.
Market Dynamics
Brazil's ANVISA biopharmaceutical stability mandates are compressing cold-chain distribution timelines, forcing manufacturers to regionalize fill-finish operations or exit government tender channels entirely.
Growth Catalysts
- Seguro Popular coverage expansion:Mexico's subsidized analog insulin access for public sector beneficiaries is accelerating patient enrollment and prescription volumes in urban diabetes clinics.
- Pen-device ecosystem adoption:Self-administration preferences among Type 1 patients are displacing vial-and-syringe methods in homecare settings across Argentina and Colombia.
- Mercosur pharmacovigilance harmonization:Brazil's ANVISA and Argentina's ANMAT adverse-event data sharing protocols are reducing regulatory duplication costs for multi-country insulin registrations.
Market Restraints
- Recombinant protein cold-chain costs:2-8°C preservation requirements through last-mile distribution elevate logistics expenditure for non-regional manufacturers serving Andean markets.
- COFEPRIS local stability testing mandates:Mexico's registration renewal requirements force redundant analytical work, extending time-to-market for imported biologics by 8-14 months.
- Biosimilar interchangeability uncertainty:Pending judicial rulings on automatic substitution create procurement hesitation among public hospital pharmacy committees.
Strategic Opportunities
- Central American tender aggregation:Guatemala and Costa Rica are consolidating insulin procurement through regional purchasing alliances, creating volume concentration for qualified bidders.
- Continuous glucose monitoring convergence:Integration of real-time glycemic data with smart pen dosing algorithms is opening premium positioning for connected insulin delivery systems.
- Subnational hospital network privatization:Brazilian state-level diabetes management program outsourcing is creating direct-to-institution sales channels bypassing federal tender delays.
Industry Challenges
- Biologics manufacturing talent scarcity:Qualified recombinant protein process engineers remain concentrated in São Paulo and Mexico City, constraining regional production scale-up.
- Legacy vial-to-pen packaging line conversion:Capital equipment replacement timelines of 18-24 months lag behind patient preference shifts, stranding capacity investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Human Insulin Drugs Market |
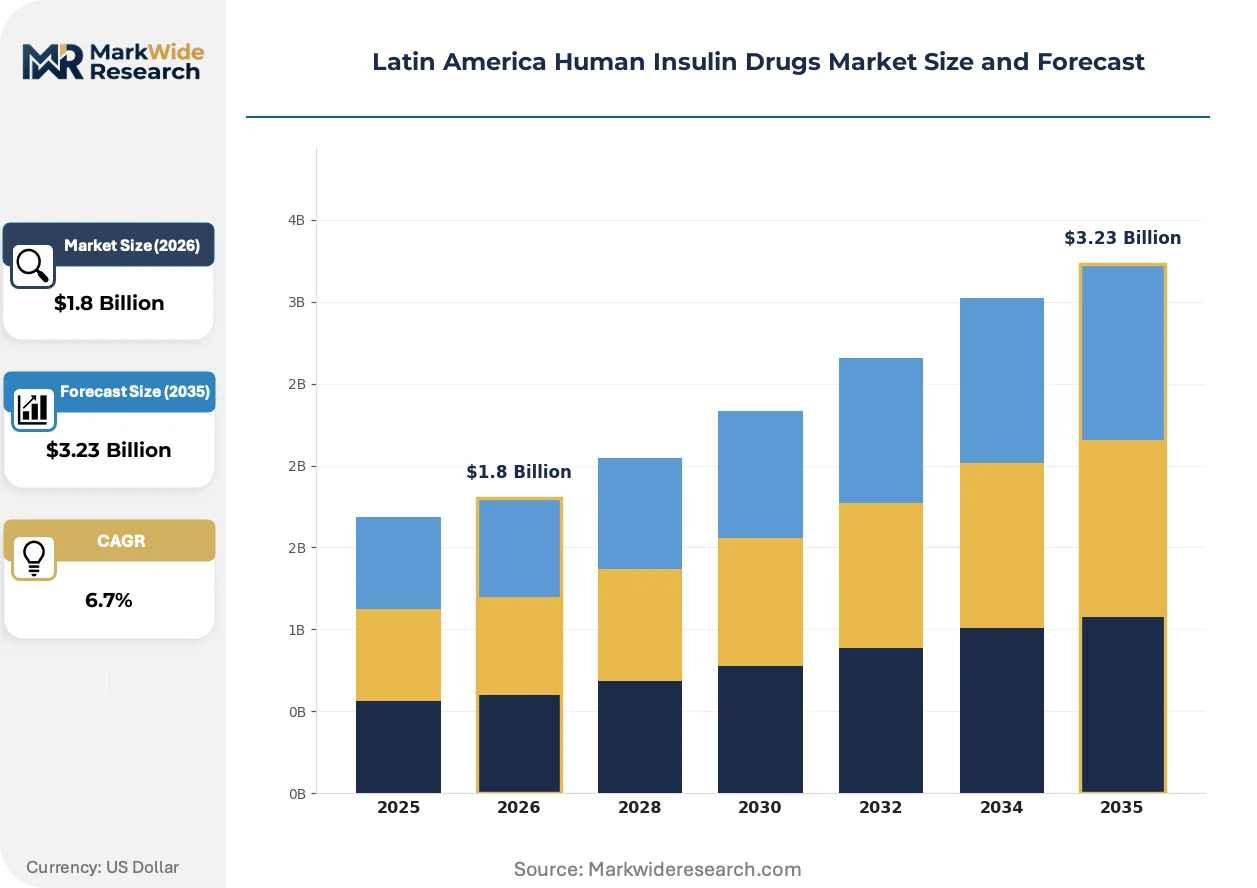
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid-Acting, Long-Acting, Short-Acting, Pre-Mixed Delivery Mode: Injection, Pen, Pump, Inhalation End User: Hospitals, Clinics, Homecare, Pharmacies Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Hypoglycemia |
| Companies Covered | Biocon, Boehringer Ingelheim, Novo Nordisk, Tonghua Dongbao Pharmaceutical, Wockhardt, Sanofi, Pfizer, Julphar, Eli Lilly, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Human Insulin Drugs Market Shifts & Advancements
Insulin delivery technology and regulatory harmonization are restructuring competitive positioning across Latin American procurement channels, with patient self-management preferences accelerating device-level differentiation.
Smart connected pen systems are decentralizing glycemic control from clinical settings to home environments. These Bluetooth-enabled devices capture dose timing and glucose correlation data for physician remote monitoring. Type 1 diabetes patients in Mexico City's public hospital networks are adopting these systems at rates exceeding 35% annually among Seguro Popular beneficiaries. The technology is decentralizing endocrinology consultation demand toward telemedicine platforms and reducing emergency hypoglycemia admissions.
ANVISA's updated GMP certification requirements for imported biologics are elevating barrier-to-entry for non-regional manufacturers. The regulation mandates local quality representative presence and real-time batch release documentation. European and North American suppliers face 6-12 month compliance timelines, while Brazilian biosimilar producers capture expanded government tender share through expedited domestic certification pathways.
Patient self-administration competency programs are displacing traditional nurse-supervised injection training in Brazilian and Colombian diabetes clinics. Hospital-based educators now certify homecare readiness through standardized pen-technique assessments rather than recurring outpatient visits. This behavioral shift concentrates most visibly in São Paulo's state hospital network, where appointment compression has reduced endocrinology wait times by 40% while elevating pharmacy counseling service demand.
Latin America Human Insulin Drugs Market Segmentation
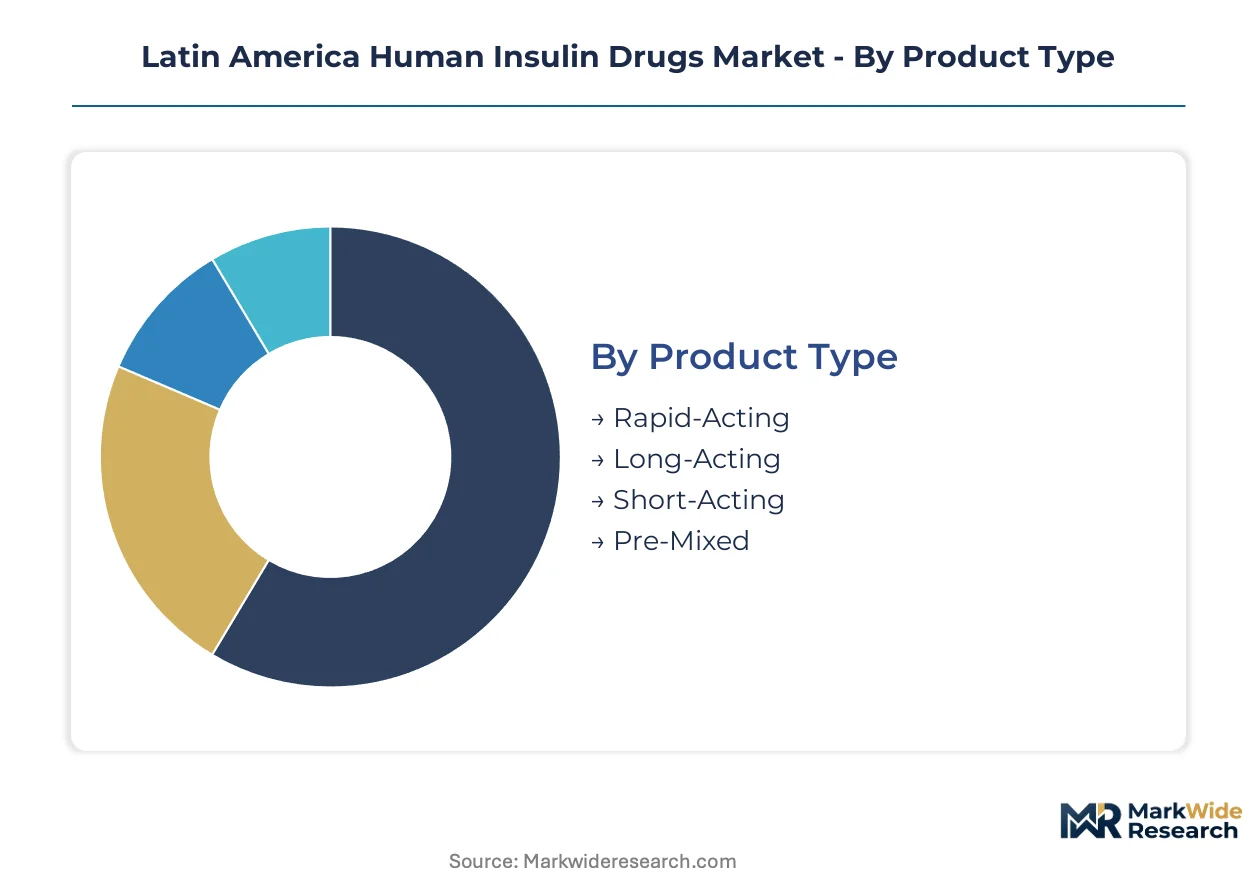
Insulin procurement decisions across Latin America diverge sharply between public hospital tenders and private pharmacy channels, with product type and delivery mode determining reimbursement eligibility and patient adherence outcomes. Segmentation clarity enables manufacturers to align cold-chain investments with the specific compliance and dosing requirements of each end-use environment.
Product Type:
Hospital pharmacy committees prioritize hypoglycemia risk profiles and dosing simplicity when selecting insulin formulations for formulary inclusion.
- Long-Acting:Basal insulin analogs such as glargine and detemir provide 24-hour glycemic control with reduced nocturnal hypoglycemia incidence. Brazilian public hospital networks concentrate procurement of these formulations for Type 2 diabetes management programs, driven by simplified once-daily dosing protocols that reduce nursing burden.
- Rapid-Acting:Prandial insulin formulations including lispro and aspart mimic physiological post-meal insulin spikes for tight glucose control. Mexico City's Seguro Popular beneficiaries with Type 1 diabetes drive concentrated demand in urban diabetes clinics, where prandial dosing flexibility supports carbohydrate-counting education programs.
- Short-Acting:Regular human insulin remains the cost-minimized option for resource-constrained settings across Central America.
- Pre-Mixed:Fixed-ratio basal-bolus combinations serve patients with limited self-monitoring capacity in Colombian regional hospitals.
Long-Acting formulations lead on scale across government tender volumes; Rapid-Acting analogs lead on momentum as Type 1 diabetes diagnosis rates climb in major metropolitan centers.
Delivery Mode:
Patient self-administration competency and cold-chain infrastructure availability shape device selection across homecare versus institutional settings.
- Pen:Disposable and reusable pen devices integrate dose-dialing mechanisms with concealed needle systems to reduce injection anxiety. Argentine and Colombian homecare segments are displacing vial-and-syringe methods fastest, driven by patient preference for discreet portable administration and reduced dosing error rates.
- Injection:Conventional vial-and-syringe administration persists in Brazilian public hospitals where bulk procurement economics override convenience considerations.
- Pump:Continuous subcutaneous insulin infusion systems concentrate in São Paulo's private endocrinology practices serving affluent Type 1 diabetes populations.
- Inhalation:Pulmonary insulin delivery remains restricted to niche indications pending ANVISA respiratory safety assessments.
Pen devices dominate new prescription growth; Injection methods retain installed-base volume in institutional procurement channels.
End User:
Reimbursement pathway structure and clinical oversight intensity determine channel-specific product configurations and service bundling requirements.
- Hospitals:Inpatient glycemic management programs across Brazil's Sistema Único de Saúde require long-acting analogs with established hypoglycemia reversal protocols.
- Homecare:Self-managed diabetes populations in Mexico's urban centers drive pen-device and continuous glucose monitoring bundle adoption.
- Clinics:Outpatient endocrinology practices in Buenos Aires specialize in rapid-acting analog titration for prandial control.
- Pharmacies:Retail dispensing channels across Central America concentrate pre-mixed insulin availability for walk-in patients without prescription continuity.
Hospitals anchor procurement volume through tender aggregation; Homecare channels are expanding most quickly as self-management education programs proliferate.
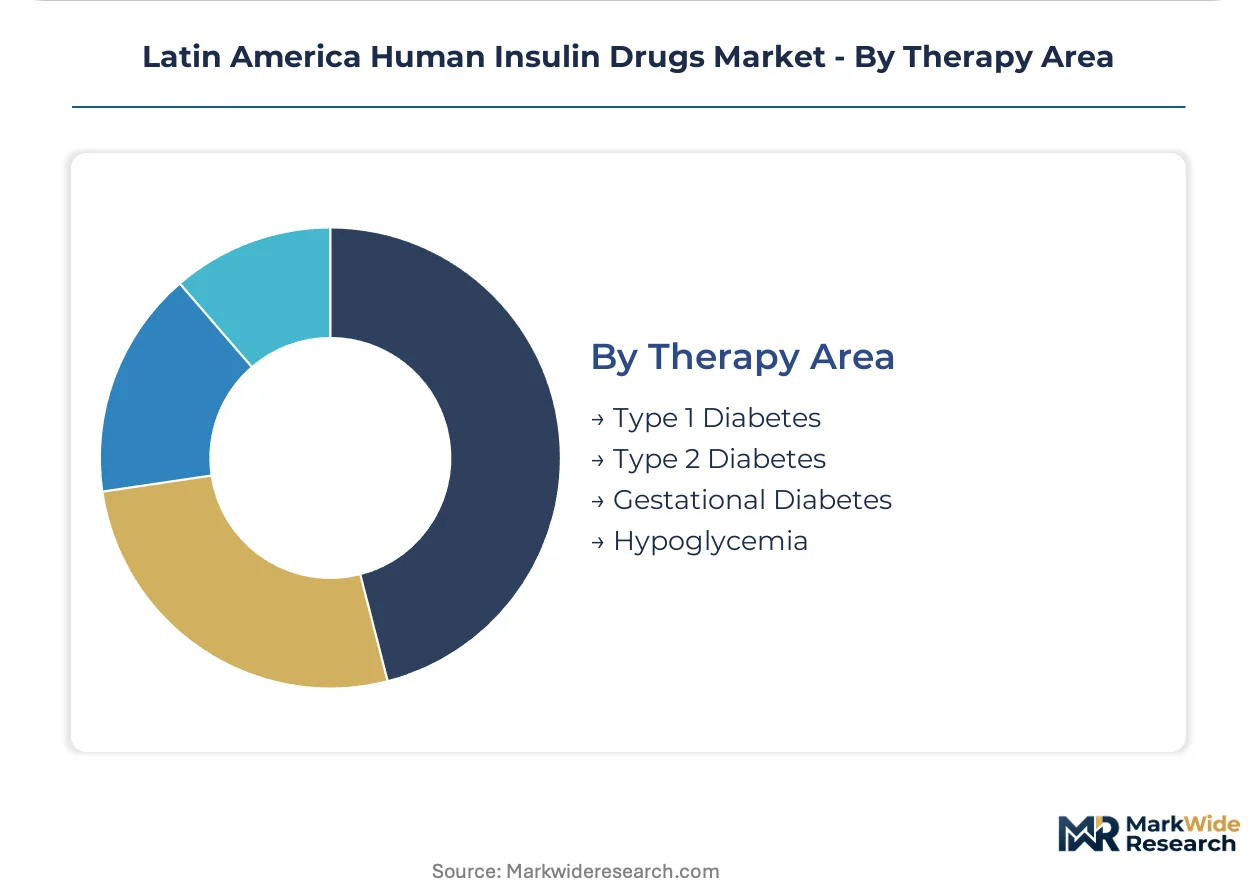
Therapy Area:
Disease severity and treatment urgency dictate insulin initiation timing and analog versus human insulin selection across patient populations.
- Type 1 Diabetes:Absolute insulin deficiency requiring lifelong exogenous replacement concentrates demand for rapid-acting and long-acting analog combinations. Brazilian pediatric endocrinology centers drive concentrated uptake of connected pen systems for adolescent patient populations.
- Type 2 Diabetes:Progressive beta-cell dysfunction creates expanding basal insulin demand as oral agent failure advances. Mexican public health expansion targets this population through Seguro Popular analog access subsidies.
- Gestational Diabetes:Pregnancy-specific glycemic targets require rapid-acting analogs with documented fetal safety profiles in Colombian maternal health programs.
- Hypoglycemia:Acute glucose correction products serve emergency departments and ambulance services across the region.
Type 2 Diabetes generates absolute patient volume; Type 1 Diabetes shows the steepest expansion trajectory as autoimmune diagnosis rates rise in urban populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as manufacturers migrate fill-finish operations toward jurisdictions with expedited domestic certification pathways. ANVISA's biopharmaceutical stability mandates create compliance cost gaps that favor regional producers over distant importers.
Brazil
São Paulo's state hospital network drives concentrated insulin procurement through Sistema Único de Saúde tenders. ANVISA enforces GMP certification with local quality representative presence requirements. Brazilian biosimilar manufacturers in São Paulo capture expanded government share through expedited domestic pathways.
Mexico
Seguro Popular beneficiaries in Mexico City Metro generate accelerating analog insulin prescription volumes at urban diabetes clinics. COFEPRIS mandates local stability testing for registration renewals, extending time-to-market for imported biologics. The capital's public hospital networks are adopting connected pen systems at rates exceeding 35% annually.
Argentina
ANMAT coordinates pharmacovigilance data sharing with Brazil through Mercosur harmonization protocols. Buenos Aires outpatient endocrinology practices specialize in rapid-acting analog titration for prandial control. Argentine homecare segments are displacing vial-and-syringe methods fastest among regional markets.
Colombia
Regional hospitals concentrate pre-mixed insulin availability for patients with limited self-monitoring capacity. The country's national pharmaceutical regulator maintains stability documentation requirements that elevate barrier-to-entry for non-regional suppliers. Bogotá-based diabetes clinics are expanding patient self-administration competency programs.
Chile
Santiago's private endocrinology practices serve affluent Type 1 diabetes populations with continuous subcutaneous insulin infusion systems. The national pharmaceutical regulator aligns with Mercosur adverse-event reporting standards. Chilean procurement channels favor pen-device ecosystems that reduce dosing errors in homecare settings.
Latin America Human Insulin Drugs Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biosimilar interchangeability and connected delivery platforms. The market structure concentrates around recombinant DNA manufacturing scale and cold-chain distribution capability. Three archetypes dominate: multinational innovators with pen-device ecosystems, regional biosimilar specialists with tender-optimized portfolios, and emerging platform developers integrating continuous glucose monitoring convergence. Capacity regionalization and strategic partnerships with hospital networks represent the dominant competitive moves.
Among Denmark-based innovators, Novo Nordisk anchors recombinant protein manufacturing scale for public hospital supply. French and US-based multinationals Sanofi and Eli Lilly exemplify device-differentiation strategies through pen-based delivery ecosystems. Indian specialists Biocon and Wockhardt occupy positions within the biosimilar tier, serving government tender channels across Latin America with cost-optimized formulations.
| Leading Market Players |
|---|
| Biocon |
| Boehringer Ingelheim |
| Novo Nordisk |
| Tonghua Dongbao Pharmaceutical |
| Wockhardt |
| Sanofi |
| Pfizer |
| Julphar |
| Eli Lilly |
| Others |
Supply & Pricing Matrix
Recombinant protein cold-chain logistics indices cascade through Latin American insulin procurement channels, compressing margins for non-regional manufacturers while amplifying pricing power for domestic fill-finish operators serving government tenders. Brazil's ANVISA biopharmaceutical stability mandates reshape cost structures across public hospital networks and private pharmacy channels alike.
Pricing Analysis
Distributor margins in government tender channels absorb the heaviest compression as ANVISA compliance timelines extend. Three-tier pricing structure across premium analog, standard human insulin, and economy vial formulations stratifies procurement decisions. Price differentiation hinges on cold-chain certification grade and pen-device ecosystem bundling. Pricing pressure stems from biosimilar interchangeability rulings pending judicial resolution. Public hospital pharmacy committees exhibit highest price sensitivity; private endocrinology practices demonstrate lowest sensitivity due to patient preference premiums.
Supply Chain Analysis
ANVISA's local quality representative requirements are forcing regionalization of fill-finish operations toward São Paulo and Mexico City manufacturing hubs. Active pharmaceutical ingredient supply draws from Denmark, Germany, and India for recombinant DNA starter cultures. Supply chain risk centers on single-source vulnerability for engineered Escherichia coli expression systems. Distribution runs through temperature-controlled logistics networks serving Sistema Único de Saúde warehouses and Seguro Popular distribution points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Latin American insulin markets rests on cold-chain cost compression through regional manufacturing consolidation and connected pen-device premium tier capture.
For Market Incumbents: Deploy backward integration into regional fill-finish capacity to defend tender share against Brazilian biosimilar specialists. Accelerate pen-device ecosystem certification under ANVISA's updated GMP pathways to preempt emerging connected delivery platform entrants. Consolidate hospital network partnerships before subnational privatization programs fragment procurement channels. For New Entrants and Emerging Players: Hospital pharmacy committees in Central American tender alliances represent the most penetrable buyer archetype for qualified bidders. Target continuous glucose monitoring convergence partnerships to bypass incumbent device lock-in. Pursue direct-to-institution sales channels in Brazilian state-level diabetes management program outsourcing. For Investors and Strategic Acquirers: Asymmetric upside sits with regional biosimilar specialists possessing expedited domestic certification pathways and tender-optimized portfolios. Long-term viability favors operators with captive recombinant protein manufacturing and cold-chain distribution integration. Monitor ANVISA biosimilar interchangeability rulings as inflection indicator for procurement pattern shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Fill-Finish Capacity Expansion | ANVISA domestic certification pathways compress compliance timelines for government tender eligibility. |
| Connected Pen-Device Ecosystem Development | Bluetooth-enabled dosing algorithms capture premium positioning in Mexico City's Seguro Popular networks. |
| Hospital Network Privatization Partnership | Direct-to-institution channels bypass federal tender delays in Brazilian state diabetes programs. |
| Biosimilar Interchangeability Investment | Judicial clarity on automatic substitution unlocks procurement volume in public hospital formularies. |
| Continuous Glucose Monitoring Convergence | Real-time glycemic data integration opens telemedicine-aligned revenue streams in homecare segments. |
Research Methodology
Direct dialogue with regulatory affairs leads at ANVISA and COFEPRIS, hospital procurement managers across Brazilian Sistema Único de Saúde networks, formulary directors in Mexico's Seguro Popular system, and diabetes clinic educators in São Paulo and Mexico City grounded qualitative findings. Secondary validation drew from ANVISA GMP certification databases, COFEPRIS registration filings, Mercosur pharmacovigilance harmonization protocols, and hospital tender documentation. Bottom-up prescription volume modeling and top-down healthcare expenditure triangulation anchored market sizing.
Segment-level projections across product type, delivery mode, end user, and therapy area dimensions were generated through the analysis window. CAGRs were derived from patient enrollment trajectories in subsidized analog access programs, pen-device adoption curves, and biosimilar penetration scenarios. Forecast inputs incorporated ANVISA regulatory timeline assumptions, Seguro Popular coverage expansion rates, and cold-chain infrastructure investment patterns.
Revisions become necessary when biosimilar interchangeability judicial rulings, ANVISA stability mandate enforcement intensity, or Central American tender alliance consolidation patterns materialize outside modeled assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Influenza Vaccine Market
Biopharmaceuticals
In Situ Gel Drug Delivery Market
Biopharmaceuticals
East Africa Generic Drug Market
Biopharmaceuticals
Germany Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Bacterial Conjunctivitis Drugs Market
Biopharmaceuticals
Global Endocrinology Drugs Market
Biopharmaceuticals
Phenylketonuria (PKU) Market
Biopharmaceuticals
Paediatric Oncology Therapeutics Market
Biopharmaceuticals
US Generic Injectables Market
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
Global Anti-Infective Drugs Market
Biopharmaceuticals
Triptorelin Market
Biopharmaceuticals
Linaclotide API Market
Biopharmaceuticals
Generic Injectables Market
Biopharmaceuticals
Insulin Delivery Pens Market
Biopharmaceuticals
Tamiflu (Oseltamivir Phosphate) Market