
 Global Mrna Vaccine Market | 2026-2036
Global Mrna Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mrna Vaccine Market Foresight
A shift from single-source lipid suppliers to multi-source feedstock agreements is rebalancing supply security across the mRNA vaccine industry. Moderna Inc. leverages in-house manufacturing scale to reduce dependency on external lipid producers. BioNTech anchors European production capacity through its Marburg facility network. Pfizer Inc. competes via integrated fill-finish operations that compress batch release timelines.
Messenger ribonucleic acid vaccines encode antigenic proteins through synthetic transcripts delivered via lipid nanoparticles, with particle size distribution typically engineered below 100 nanometers for optimal cellular uptake. The technology platform segment shows non-replicating mRNA occupying the dominant commercial position while self-amplifying formats capture developmental investment due to dose-sparing potential. Therapeutic applications, particularly in oncology indications, represent the fastest-growing demand pool as checkpoint inhibitors and personalized neoantigen programs advance through clinical pipelines.
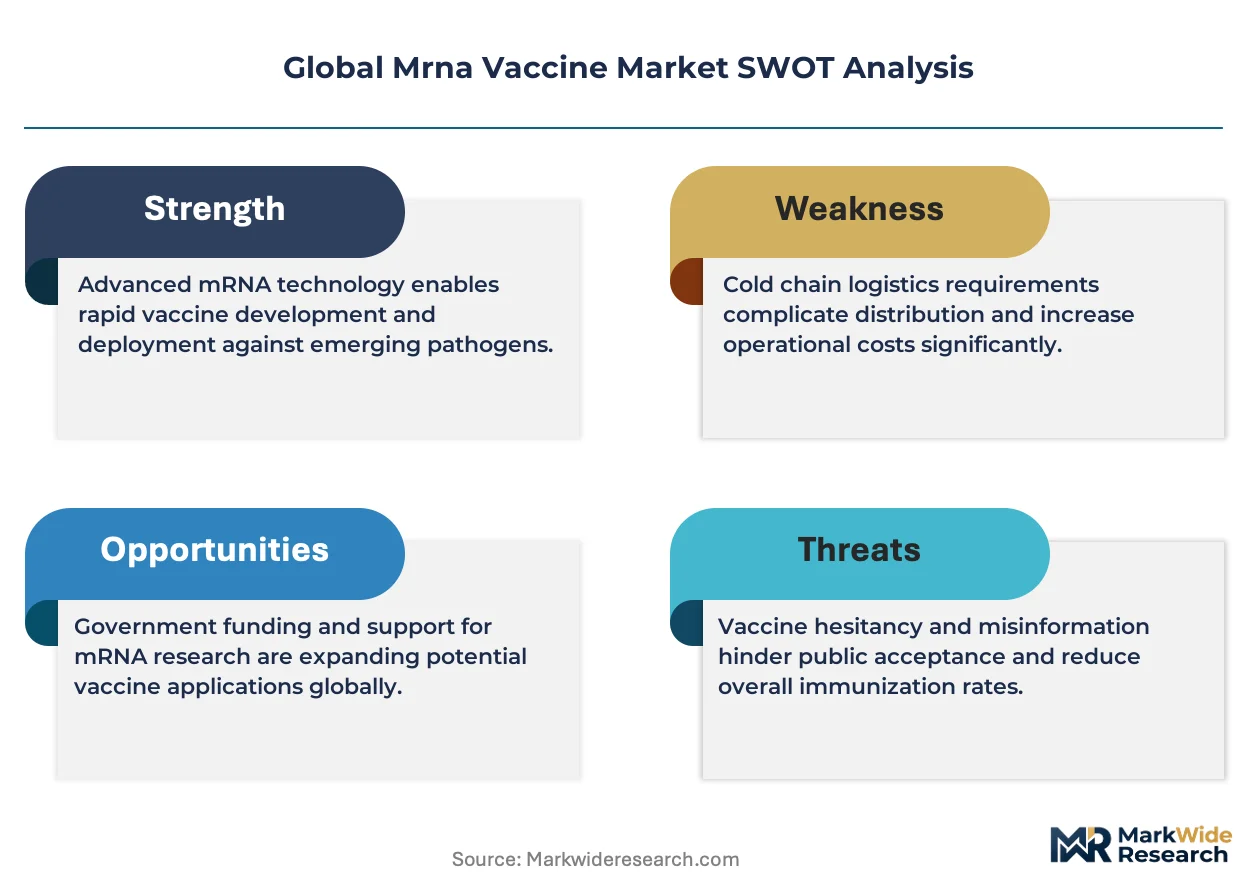
The FDA's Center for Biologics Evaluation and Research and the EMA's Committee for Medicinal Products for Human Use enforce divergent stability and potency standards that shape formulation requirements and cold-chain specifications. WHO prequalification pathways determine access to procurement programs across low-income country portfolios. Stakeholders must monitor regulatory convergence on lipid excipient characterization standards, as harmonization would unlock interchangeable sourcing across jurisdictions and compress qualification timelines for new manufacturing entrants.
Market Dynamics
The mRNA vaccine market is experiencing a fundamental reconfiguration as manufacturing capacity migrates from emergency-response scale to sustainable commercial infrastructure, with lipid nanoparticle supply security emerging as the decisive bottleneck determining which platforms achieve therapeutic breadth.
Growth Catalysts
- Adaptive licensing frameworks:The EMA's adaptive licensing pathways compress Phase III-to-approval timelines for oncology mRNA candidates, accelerating clinical translation.
- Hospital network expansion:Hospital and clinic networks in Germany, the United States, and Singapore are deploying mRNA protocols for seasonal influenza, broadening addressable patient populations.
- Lipid diversification:Multi-source feedstock agreements for ionizable lipids are rebalancing supply security and reducing single-source dependency risks.
Market Restraints
- Cold-chain infrastructure gaps:Ultra-low temperature storage requirements (-70°C for certain formulations) limit distribution reach in tropical and rural geographies lacking specialized logistics networks.
- Lipid supplier concentration:Four specialty chemical manufacturers control the majority of GMP-grade ionizable lipid production, creating input bottlenecks during demand surges.
- Stability duration limitations:Current formulation science achieves only 6-12 months refrigerated stability for most mRNA vaccines, constraining stockpiling strategies and emergency preparedness.
Strategic Opportunities
- Therapeutic oncology pivot:Personalized neoantigen programs and checkpoint inhibitor combinations represent unaddressed demand pools in immuno-oncology protocols.
- WHO prequalification access:Prequalification pathways unlock procurement programs across low-income country portfolios, expanding addressable markets beyond OECD boundaries.
- Self-amplifying mRNA convergence:Integration of self-amplifying formats with standard non-replicating platforms enables dose-sparing regimens and reduced manufacturing burden.
Industry Challenges
- Lipid excipient characterization standardization:Divergent FDA and EMA stability and potency standards create qualification friction for multi-jurisdictional product launches.
- Fill-finish capacity scarcity:Aseptic processing bottlenecks at contract manufacturing organizations extend batch release timelines and compress effective production yields.
- RNA synthesis specialist shortages:Limited pools of process development scientists with GMP oligonucleotide manufacturing experience constrain platform scaling velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mrna Vaccine Market |
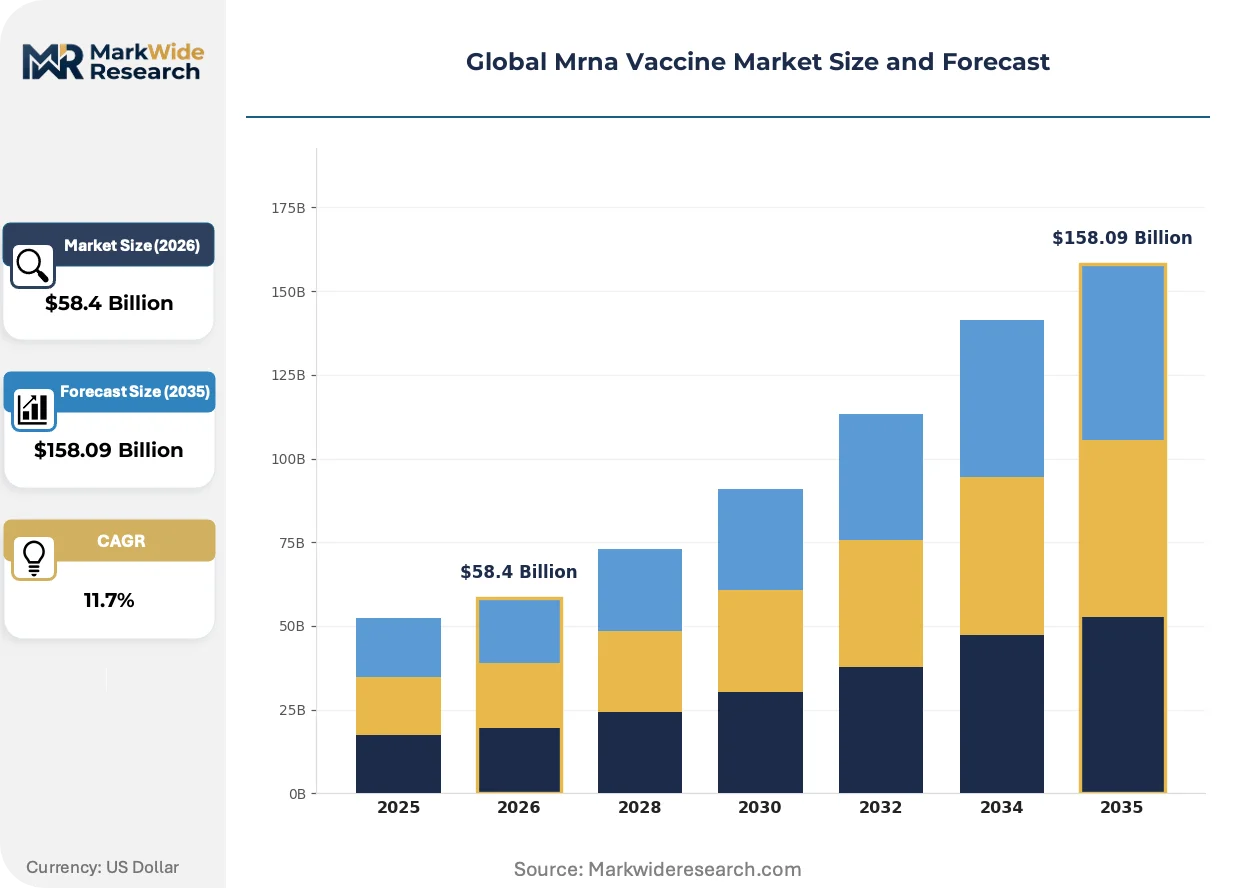
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $158.09 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Preventive, Therapeutic, Personalized, Cancer, Infectious Disease Technology Platform: Self-Amplifying mRNA, Non-Replicating mRNA, Lipid Nanoparticle, Polymer-Based Delivery, Peptide-Conjugated Indication: Respiratory Illnesses, Oncology, Cardiovascular Conditions, Rare Diseases, Immunological Disorders End User: Pharmaceutical Manufacturers, Contract Research Organizations, Biotech Firms, Academic Institutions, Public Health Agencies |
| Companies Covered | Moderna Inc., BioNTech, Pfizer Inc., CureVac SE, GSK plc, Sanofi, Arcturus Therapeutics, Gennova Biopharmaceuticals Limited, Walvax Biotechnology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mrna Vaccine Market Shifts & Advancements
Platform engineering is converging with supply chain restructuring to redefine competitive advantage in mRNA therapeutics, with manufacturing flexibility now rivaling clinical efficacy as a value determinant.
Microfluidic mixing technology for lipid nanoparticle formulation is modularizing production architectures, enabling single-batch flexibility across multiple mRNA sequences. Contract development and manufacturing organizations in Singapore and Germany are adopting these systems to serve fragmented oncology pipelines. The shift is compressing changeover timelines from weeks to days and reducing minimum viable batch sizes for personalized therapies.
REACH regulation updates in Europe are tightening characterization requirements for novel lipid excipients, forcing reformulation investments ahead of 2026 compliance deadlines. Manufacturers are responding by pre-qualifying alternative ionizable lipids through the EMA's scientific advice pathways. Synthetic lipid chemistry capabilities are becoming a regulated differentiator separating qualified suppliers from commodity producers.
Hospital procurement departments are consolidating mRNA vaccine sourcing through integrated delivery networks, displacing fragmented clinic-level purchasing. Large health systems in the United States are negotiating multi-year platform agreements covering COVID-19, influenza, and future respiratory indications. This concentration is visible most acutely in IDN-affiliated oncology centers, where formulary control over personalized neoantigen therapies is becoming a competitive weapon for patient recruitment.
Global Mrna Vaccine Market Segmentation
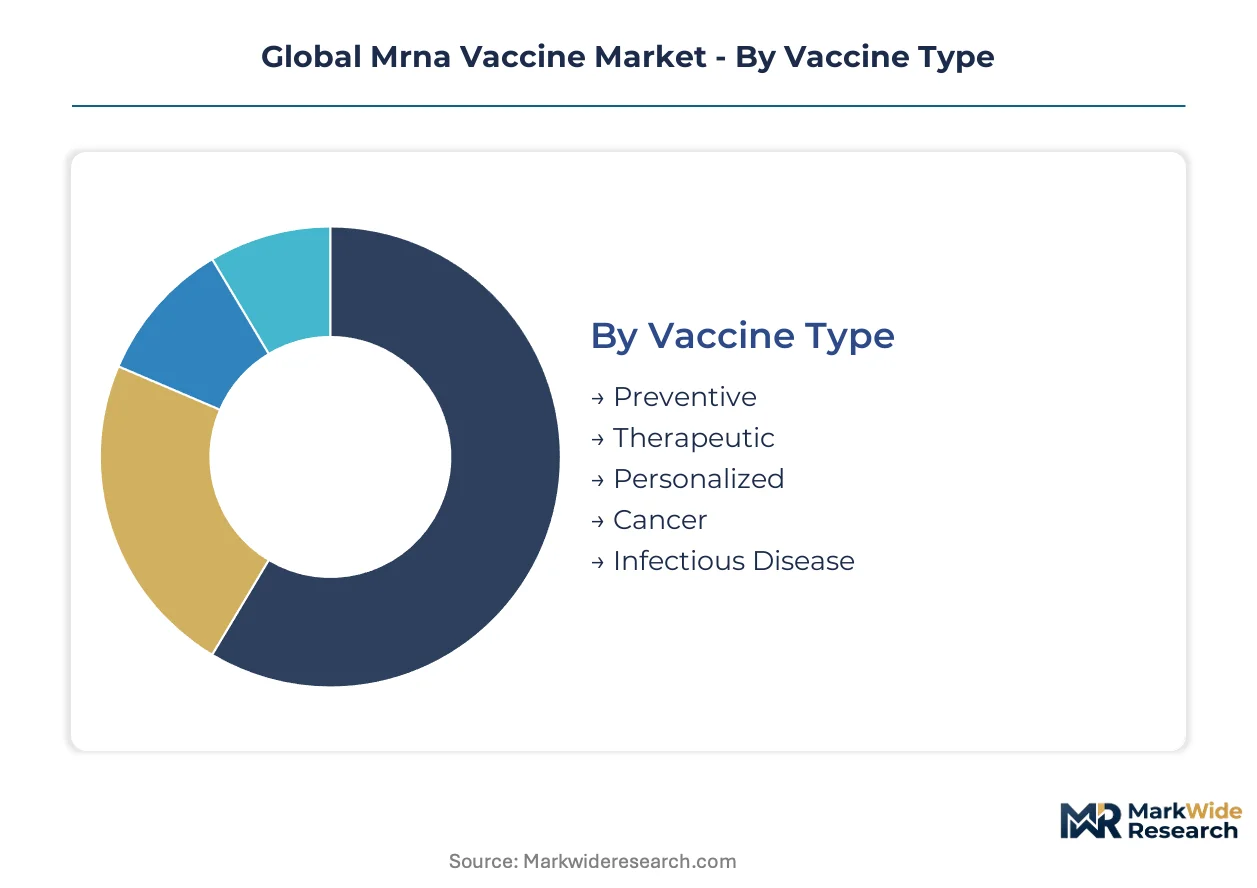
mRNA vaccine segmentation reveals how platform diversification creates distinct supply chain and regulatory requirements across therapeutic domains. Each category maps to specific manufacturing competencies, cold-chain specifications, and clinical development pathways that determine competitive positioning.
Vaccine Type:
Upgrade cycles in mRNA applications are accelerating as COVID-19-established infrastructure repurposes toward chronic and preventive indications, with each type demanding different stability profiles and dosing regimens.
- Preventive:Standard prophylactic formulations target population-scale immunization against respiratory pathogens. Demand clusters in Germany and Singapore where hospital networks are deploying seasonal influenza protocols; regulatory alignment between FDA and EMA on stability standards compresses multi-jurisdictional launch timelines.
- Therapeutic:Disease-modifying mRNA encodes functional proteins or cytokines for chronic conditions. Oncology centers in the United States are driving adoption of intratumoral delivery systems; manufacturing flexibility requirements favor modular microfluidic production architectures.
- Personalized:Patient-specific neoantigen vaccines require rapid turnaround from biopsy to administration. Academic medical centers with integrated GMP facilities capture this demand.
- Cancer:Tumor-associated antigen platforms target shared oncogenic mutations. Contract manufacturing organizations with dedicated oncology suites handle production scale.
- Infectious Disease:Broad-spectrum and variant-adapted vaccines address emerging pathogens. WHO prequalification pathways determine access to procurement programs across low-income country portfolios.
Volume placements concentrate in Preventive; the faster expansion belongs to Therapeutic.
Technology Platform:
Platform selection directly determines lipid supplier relationships, with ionizable lipid chemistry capabilities becoming the regulated differentiator separating qualified suppliers from commodity producers.
- Self-Amplifying mRNA:Replicase-encoding constructs enable intracellular amplification, reducing dose requirements. Developmental investment is concentrating in Singapore and Germany where CDMOs are adopting modular microfluidic systems; dose-sparing potential addresses manufacturing capacity constraints during demand surges.
- Non-Replicating mRNA:Standard synthetic transcripts without amplification machinery dominate current commercial production. Fill-finish operations in the United States compress batch release timelines; established regulatory pathways through FDA's Center for Biologics Evaluation and Research accelerate approval velocity.
- Lipid Nanoparticle:Ionizable lipid formulations encapsulate mRNA for cellular delivery. REACH regulation updates in Europe are tightening characterization requirements ahead of compliance deadlines.
- Polymer-Based Delivery:Cationic polymer alternatives to lipid systems offer distinct stability profiles. Academic partnerships drive early-stage development.
- Peptide-Conjugated:Targeting ligands direct mRNA to specific cell types. Oncology applications are gaining share fastest in immuno-oncology protocols.
Commercial scale favors Non-Replicating mRNA; the steepest expansion trajectory belongs to Self-Amplifying mRNA.
Indication:
Indication-specific development programs are fragmenting manufacturing demand, with oncology pipelines requiring smaller batch sizes and respiratory programs demanding surge capacity.
- Respiratory Illnesses:Seasonal and pandemic preparedness vaccines target influenza and coronavirus variants. Hospital network procurement in Germany is consolidating through integrated delivery networks; multi-year platform agreements covering COVID-19 and influenza are displacing fragmented clinic-level purchasing.
- Oncology:Personalized neoantigen and checkpoint inhibitor combination therapies represent unaddressed demand pools. IDN-affiliated cancer centers in the United States are using formulary control as competitive weapons for patient recruitment.
- Cardiovascular Conditions:mRNA-encoded regenerative proteins target ischemic tissue repair. Early-phase trials are evaluating delivery optimization.
- Rare Diseases:Orphan indications leverage mRNA's rapid program initiation for small populations. EMA's adaptive licensing pathways compress development timelines.
- Immunological Disorders:Tolerance-inducing mRNA approaches target autoimmune conditions. Preclinical investment is expanding in academic institutions.
Procurement volume clusters in Respiratory Illnesses; Oncology is climbing the fastest.
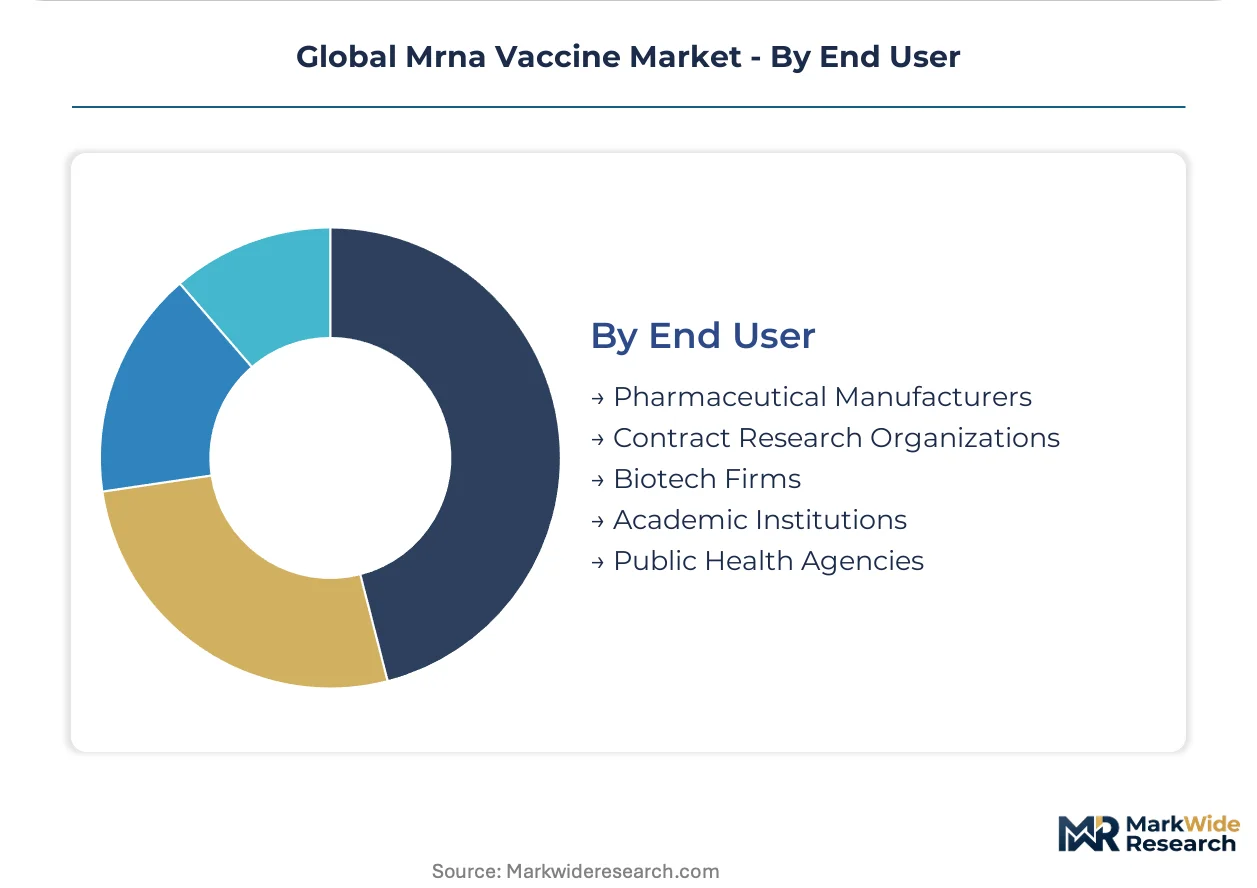
End User:
End-user concentration is reshaping supplier relationships, with large health systems and integrated manufacturers capturing margin through captive production or long-term CDMO agreements.
- Pharmaceutical Manufacturers:Vertically integrated developers control formulation and fill-finish operations. Multi-source feedstock agreements for ionizable lipids are rebalancing supply security.
- Contract Research Organizations:Development-stage service providers bridge discovery to GMP transition. Singapore-based CDMOs are adopting microfluidic mixing technology to serve fragmented oncology pipelines.
- Biotech Firms:Platform-technology developers without captive manufacturing rely on external partnerships. Lipid supplier concentration creates input bottlenecks during demand surges.
- Academic Institutions:Research hospitals and universities operate early-phase GMP facilities for personalized therapies. Minimum viable batch sizes are shrinking with modular production architectures.
- Public Health Agencies:Government procurement bodies determine access to national stockpiles and international distribution programs. WHO prequalification unlocks low-income country portfolios.
Contract volume concentrates in Pharmaceutical Manufacturers; the fastest share gain belongs to Contract Research Organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital and clinic networks in Germany, the United States, and Singapore currently absorb the highest mRNA vaccine procurement volumes, with manufacturing demand clustering where lipid nanoparticle production capacity scales fastest.
United States
FDA's Center for Biologics Evaluation and Research governs stability and potency standards that shape formulation requirements. The IRA provisions influence pharmaceutical procurement economics for hospital networks. Greater Boston and the San Francisco Bay Area host concentrated biotech clusters where personalized neoantigen programs advance through clinical pipelines.
Germany
EMA's adaptive licensing frameworks compress Phase III-to-approval timelines for oncology candidates. REACH regulation updates tighten characterization requirements for novel lipid excipients ahead of compliance deadlines. The Marburg facility network anchors European production capacity for ionizable lipid manufacturing.
Singapore
Contract development and manufacturing organizations adopt microfluidic mixing technology to serve fragmented oncology pipelines. The country's national pharmaceutical regulator aligns with WHO prequalification pathways for low-income country access. Biomedical manufacturing clusters scale lipid nanoparticle production capacity for regional supply security.
United Kingdom
Academic medical centers with integrated GMP facilities capture demand for patient-specific neoantigen therapies. The Medicines and Healthcare products Regulatory Agency enforces divergent standards from FDA on cold-chain specifications. London and Oxfordshire concentrations of RNA synthesis specialists constrain platform scaling velocity.
China
Walvax Biotechnology Co., Ltd. exemplifies domestic manufacturing scale for infectious disease applications. NMPA approval pathways determine access to national stockpiles and regional distribution programs. Yangtze River Delta biotech corridors attract investment in modular production architectures for dose-sparing regimens.
Global Mrna Vaccine Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturing migrates from emergency-response scale to sustainable commercial infrastructure. The vendor base concentrates around vertically integrated pharmaceutical developers, platform-technology biotech firms, and specialized contract manufacturing organizations. Three archetypes define positioning: captive manufacturers controlling formulation and fill-finish, technology licensors monetizing delivery platforms, and service providers enabling modular production. M&A activity and multi-source feedstock agreements constitute the primary competitive vectors reshaping supply security.
Within the captive manufacturing tier, Moderna Inc. and Pfizer Inc. exemplify scale-driven positions where in-house production reduces dependency on external inputs. BioNTech occupies a European-anchored position exemplifying integrated fill-finish operations that compress batch release timelines. Among platform-technology developers, CureVac SE and Arcturus Therapeutics represent archetypes pursuing dose-sparing formats through self-amplifying mRNA convergence.
| Leading Market Players |
|---|
| Moderna Inc. |
| BioNTech |
| Pfizer Inc. |
| CureVac SE |
| GSK plc |
| Sanofi |
| Arcturus Therapeutics |
| Gennova Biopharmaceuticals Limited |
| Walvax Biotechnology Co., Ltd. |
| Others |
Supply & Pricing Matrix
Ionizable lipid spot prices and GMP-grade cholesterol benchmarks cascade through mRNA vaccine manufacturing tiers, compressing margins at contract manufacturing organizations while vertically integrated pharmaceutical developers capture pricing power through captive supply agreements. REACH compliance costs and FDA stability testing requirements stratify procurement across premium-certified, standard-grade, and economy-tier supply channels.
Pricing Analysis
Volume procurement concentrates in preventive respiratory vaccines where per-dose margins compress under hospital network consolidation, while therapeutic oncology applications command premium pricing through personalized manufacturing protocols. Price differentiation rests on GMP certification tier and cold-chain reliability guarantees, with WHO-prequalified suppliers extracting measurable premiums over non-certified alternatives. Pricing pressure stems from lipid feedstock scarcity as multi-source agreements displace single-source contracts. Public health agencies exhibit highest price sensitivity due to budget-constrained procurement cycles; biotech firms with platform partnerships show lowest sensitivity due to pass-through arrangements.
Supply Chain Analysis
Single-source vulnerability sits with ionizable lipid production concentrated among German and United States specialty chemical manufacturers, with Singapore emerging as a diversification hub through CDMO microfluidic adoption. Raw material dependencies center on synthetic cholesterol, GMP-grade nucleotides, and proprietary cationic lipids. Supply chain risk manifests as regulatory restriction exposure under divergent FDA and EMA excipient characterization standards. Distribution runs through integrated delivery networks consolidating hospital procurement under multi-year platform agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as lipid supplier concentration and fill-finish capacity scarcity force sub-scale biotech firms toward acquisition or partnership exits.
For Market Incumbents: Anticipate margin compression from emerging self-amplifying mRNA platforms by securing multi-source ionizable lipid agreements before REACH compliance deadlines tighten supplier qualification windows. Prioritize backward integration into synthetic lipid chemistry capabilities to reduce dependency on the four dominant GMP-grade specialty chemical manufacturers. Channel control through integrated delivery network partnerships offers defensive positioning against CDMO price competition. For New Entrants and Emerging Players: Academic medical centers with captive GMP facilities represent the most penetrable channel for personalized neoantigen manufacturing partnerships, bypassing incumbent-dominated preventive vaccine procurement. White-space targets include rare disease indications where EMA adaptive licensing compresses development timelines and tropical geography distribution where cold-chain infrastructure gaps create demand for thermostable formulations. A go-to-market angle anchored in modular microfluidic production architectures enables minimum viable batch sizes below incumbent scale economics. For Investors and Strategic Acquirers: Distressed-cycle entries favor platform-technology biotech firms with validated lipid nanoparticle delivery systems in Germany or Singapore, where regulatory alignment with EMA or WHO pathways accelerates commercial translation. Long-term viability over a multi-year horizon hinges on therapeutic oncology pivot execution and self-amplifying mRNA convergence timing. The signal to watch is EMA scientific advice pathway utilization rates as an indicator of pipeline maturity and regulatory de-risking progress.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Lipid Feedstock Agreement | Reduces single-source vulnerability under REACH tightening and FDA stability divergence. |
| Modular Microfluidic Production Deployment | Enables personalized therapy batch flexibility at Singapore and Germany CDMO clusters. |
| EMA Adaptive Licensing Pathway Engagement | Compresses Phase III-to-approval timelines for oncology candidates in European markets. |
| WHO Prequalification Pursuit | Unlocks procurement programs across low-income country public health portfolios. |
| Self-Amplifying mRNA Platform Integration | Addresses dose-sparing demand surges through reduced manufacturing burden per dose. |
Research Methodology
FDA filings, EMA submission databases, and ClinicalTrials.gov records formed the secondary backbone, cross-referenced with customs data on lipid nanoparticle feedstock imports and hospital procurement contract disclosures. Primary interviews with regulatory affairs leads, formulary directors at integrated delivery networks, and GMP facility managers at contract manufacturing organizations validated demand assumptions and supply constraints. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored segmentation splits across preventive, therapeutic, and personalized vaccine categories.
Historical trendline analysis of COVID-19-established manufacturing capacity tracked migration toward sustainable commercial infrastructure across the projection horizon. Segmentation dimensions modeled include vaccine type, technology platform, indication, and end-user archetype, with regional regulatory clusters capturing FDA, EMA, and NMPA pathway divergence. CAGRs were derived from capacity utilization trajectories and hospital network procurement consolidation patterns, incorporating lipid supplier concentration indices and cold-chain infrastructure penetration as industry-specific forecast inputs.
Caveats apply where regulatory convergence on lipid excipient characterization standards or breakthrough thermostable formulation advances could materially shift the outlook. Forecasts reflect assumptions on manufacturing scale economics and adaptive licensing pathway utilization rates without guarantee of realization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Glioblastoma Multiforme (GBM) Market
Medical Biotechnology
Albendazole Drugs Market
Medical Biotechnology
Nanomedicine Market
Medical Biotechnology
Muscular Dystrophy Drugs Market
Medical Biotechnology
North America Bacteriophages Therapy Market
Medical Biotechnology
Mitochondrial Myopathies Market
Medical Biotechnology
T Cell-Specific Surface Glycoprotein CD28 Antibody Market
Medical Biotechnology
Mucormycosis Market
Medical Biotechnology
Global Red Biotechnology Market
Medical Biotechnology
Galectin Inhibitor Therapeutics Market
Medical Biotechnology
Global Antisense and Rnai Therapeutics Market
Medical Biotechnology
Global Stem Cells Market
Medical Biotechnology
Fetal Valproate Syndrome Market
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market
Medical Biotechnology
Cell and Tissue Preservation Market
Medical Biotechnology
Becker Muscular Dystrophy Market