
 EMEA Cancer Biological Therapy Market | 2026-2036
EMEA Cancer Biological Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
EMEA Cancer Biological Therapy Market Foresight
The EU Green Deal's pharmaceutical sustainability requirements is realigning biological therapy manufacturing standards across the EMEA region, compelling producers to reduce carbon intensity in cold-chain logistics and single-use bioreactor operations. Bristol-Myers Squibb Company anchors its European biological therapy network through advanced manufacturing facilities in Ireland and the Netherlands. Merck & Co. differentiates via deep R&D investment in immuno-oncology platforms targeting melanoma and lymphoma indications. F. Hoffmann-La Roche Ltd dominates the monoclonal antibody segment through sustained production scale and established hospital formulary relationships.
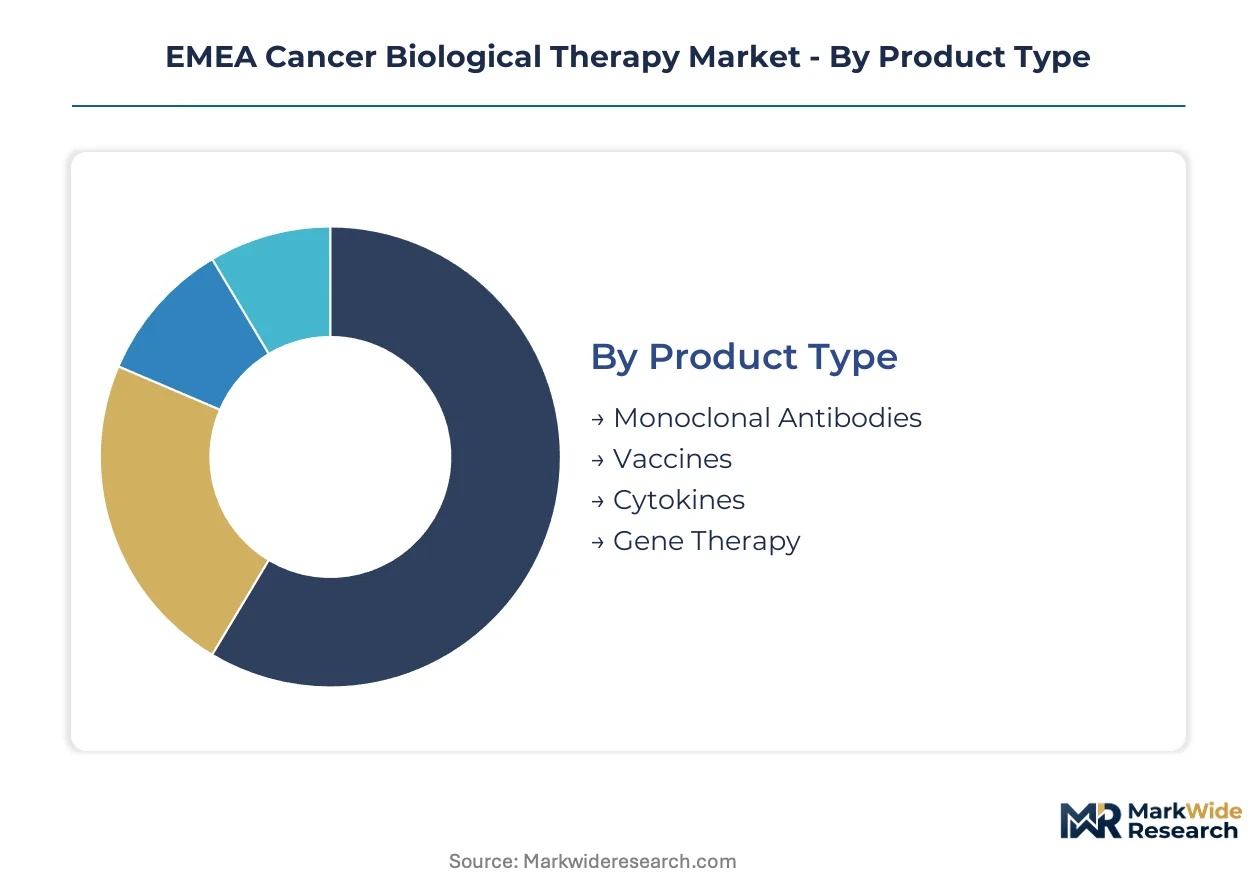
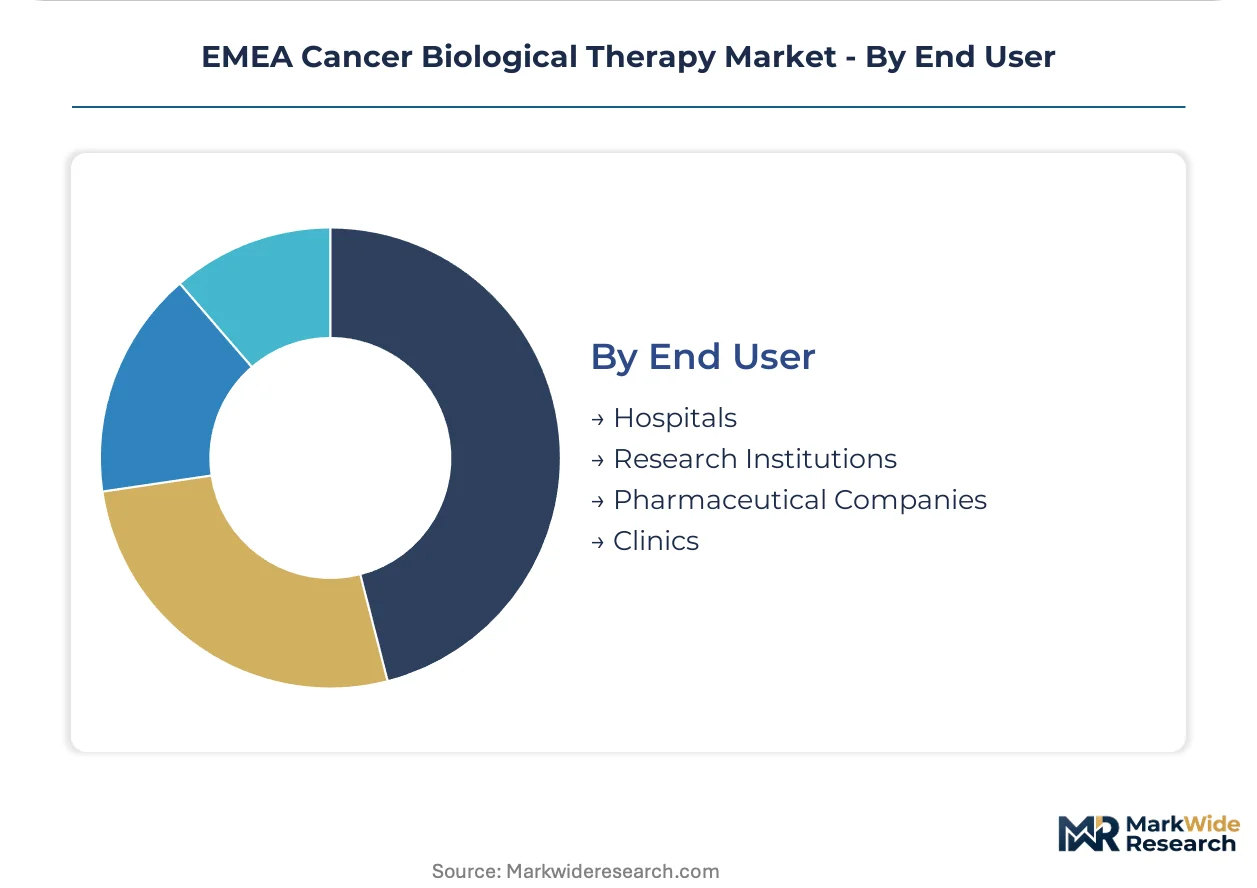
Cancer biological therapy encompasses therapeutic proteins, living cells, and genetically engineered agents designed to modulate immune responses or directly target malignant cell pathways, typically manufactured through mammalian cell culture in bioreactor systems with stringent purity thresholds exceeding 99% for injectable formulations. The primary commercial purpose centers on treating solid tumors and hematological malignancies with reduced systemic toxicity compared to conventional cytotoxic chemotherapy. Monoclonal antibodies occupy the largest revenue pool within product type segmentation, reflecting mature manufacturing infrastructure and broad label indications across breast cancer and lymphoma. Gene therapy represents the fastest-expanding category, driven by CAR-T cell approvals and personalized medicine protocols in hematology centers. Hospitals command the dominant end-user channel, though research institutions are capturing growing procurement volumes through early-phase clinical trial expansion.
EMA's centralized marketing authorization procedures govern biological therapy approval across EU member states, while REACH and the EU AI Act increasingly shape manufacturing material compliance and algorithm-driven diagnostic companion tools. The UK's MHRA operates parallel assessment pathways post-Brexit, creating dual regulatory navigation requirements for sponsors seeking EMEA-wide market access. Switzerland's Swissmedic maintains aligned but independent review standards, adding complexity for launches targeting the Alpine market. Stakeholders must monitor evolving EMA guidance on biosimilar interchangeability and national health technology assessment divergence between France, Germany, and Italy to optimize portfolio prioritization and pricing negotiations.
Market Dynamics
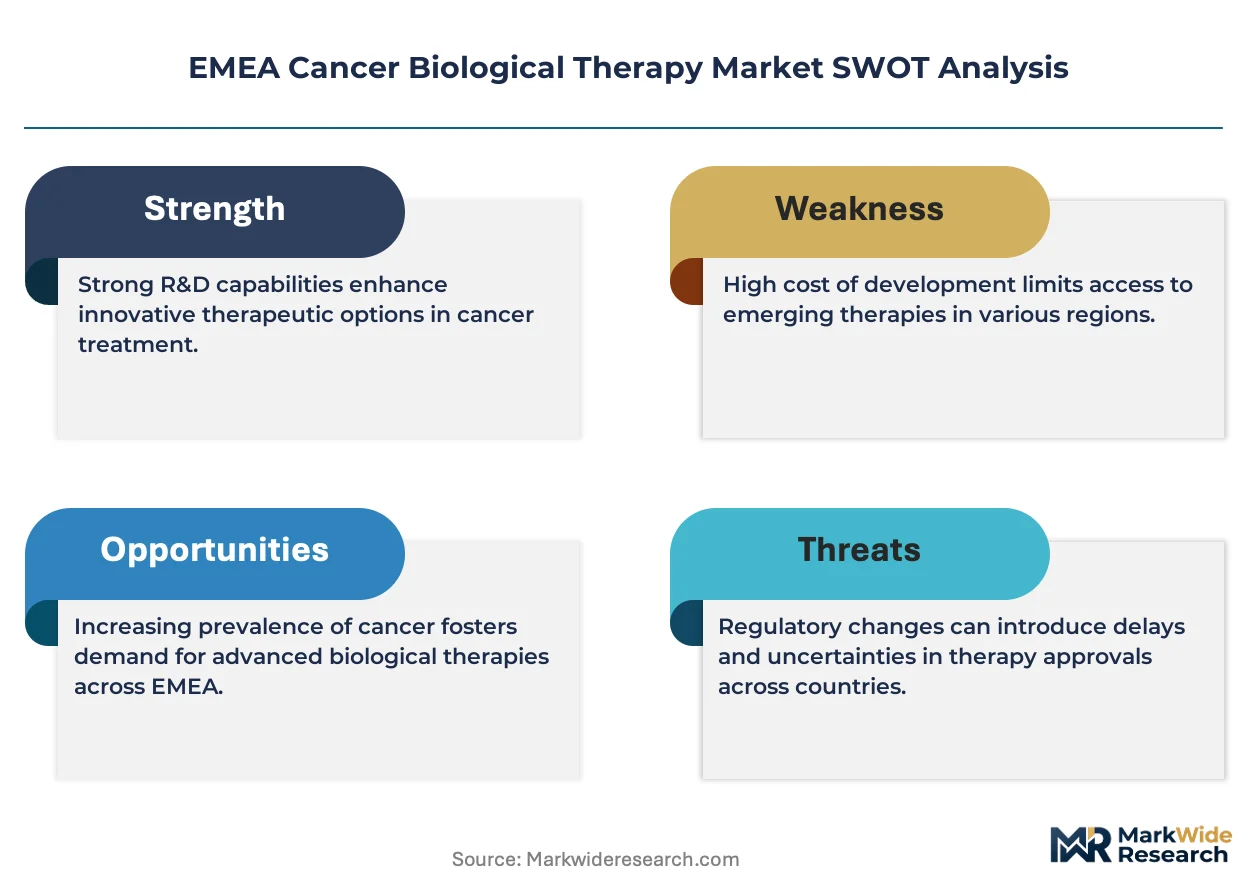
The EU Green Deal's pharmaceutical sustainability requirements are compressing manufacturing timelines and forcing cold-chain logistics redesign across EMEA biological therapy production networks. REACH compliance costs and carbon intensity benchmarks now filter supplier qualification decisions before clinical trial enrollment even begins.
Growth Catalysts
- EMA centralized authorization:Streamlined marketing procedures accelerate cross-border patient access and reduce redundant national filings for biological therapies.
- CAR-T manufacturing scale-up:Academic medical centers in Germany and Switzerland are expanding GMP-compliant cell processing capacity for personalized immuno-oncology protocols.
- Rhine-Main biotech corridor:Frankfurt-Heidelberg infusion center clustering creates patient concentration that justifies dedicated biological therapy distribution infrastructure.
Market Restraints
- Single-use bioreactor supply concentration:German and Irish manufacturing hubs depend on a narrow supplier base for sterile film assemblies and sensor technologies.
- Cold-chain energy cost volatility:Biological therapy logistics face electricity price swings that directly compress per-dose distribution margins.
- Biosimilar interchangeability uncertainty:Divergent EMA guidance and national HTA positions in France, Germany, and Italy create formulary access friction.
Strategic Opportunities
- Eastern European hospital networks:Poland and Czech Republic oncology centers are upgrading infusion infrastructure to handle biological therapy protocols previously limited to Western EU markets.
- EU AI Act diagnostic convergence:Algorithm-driven companion diagnostics for patient stratification open reimbursement pathways for precision biological therapies.
- Swissmedic-aligned launches:Switzerland's independent but harmonized review standards offer premium pricing potential for sponsors willing to navigate parallel regulatory tracks.
Industry Challenges
- GMP cell therapy technician scarcity:CAR-T and gene therapy manufacturing requires aseptic processing skills that outpace vocational training pipeline output in EMEA markets.
- Legacy EHR integration:Biological therapy patient monitoring systems must interface with hospital information architectures that vary across German Länder and NHS trusts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EMEA Cancer Biological Therapy Market |
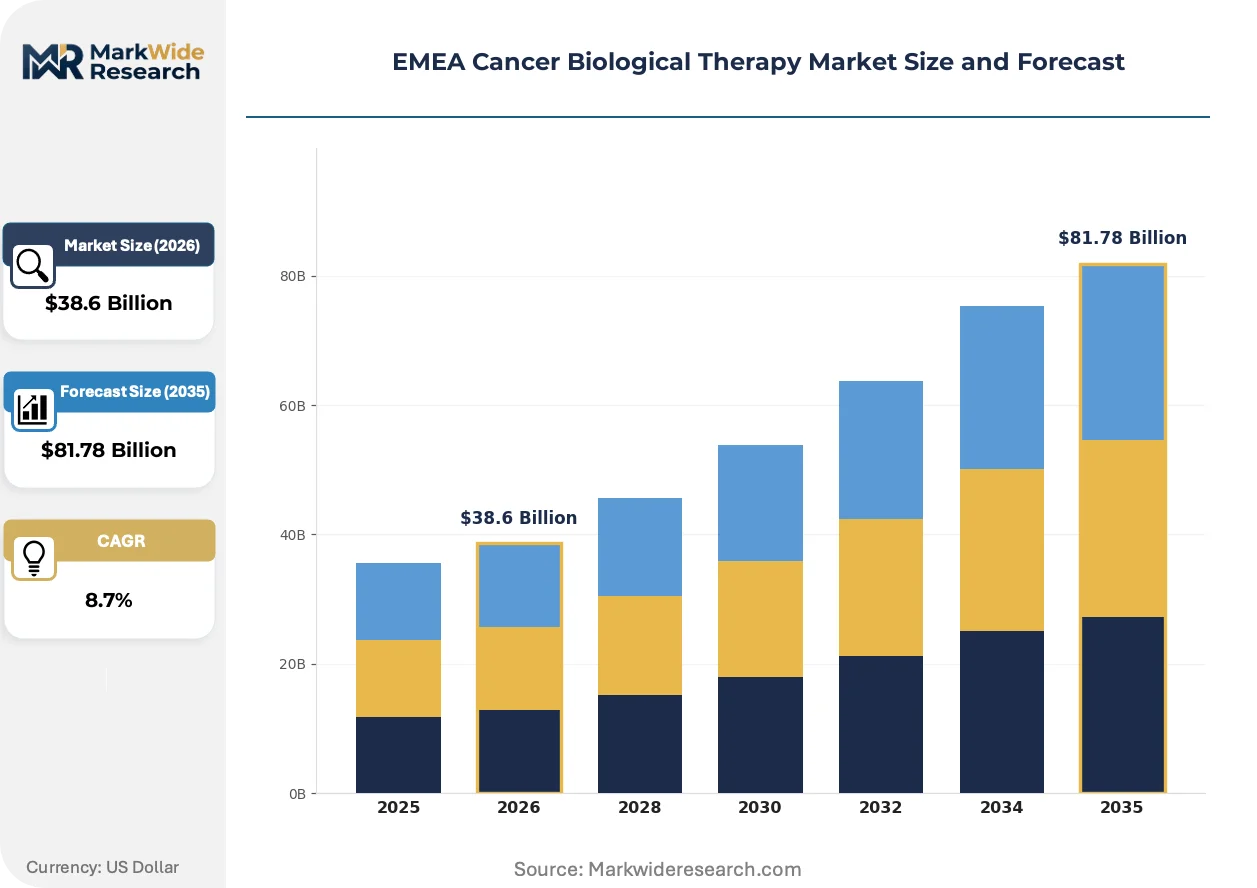
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Vaccines, Cytokines, Gene Therapy Therapy Area: Breast Cancer, Melanoma, Leukemia, Lymphoma Application: Oncology, Hematology, Diagnostics, Personalized Medicine End User: Hospitals, Research Institutions, Pharmaceutical Companies, Clinics |
| Companies Covered | Bristol-Myers Squibb Company, Merck & Co., F. Hoffmann-La Roche Ltd, Eli Lilly and Company, Pfizer Inc., Novartis International, Amgen Inc., Bayer AG, AstraZeneca PLC, Others |
| Regions Covered | EMEA: Germany, UK, France, Saudi Arabia, UAE, South Africa, Russia, Italy, Rest of EMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EMEA Cancer Biological Therapy Market Shifts & Advancements
Biological therapy manufacturing is pivoting from batch processing toward continuous bioproduction, while regulatory frameworks harden around algorithmic patient selection and supply chain carbon accounting. Three forces are restructuring competitive positioning.
Continuous manufacturing platforms are automating upstream cell culture and downstream purification steps that previously required multiple discrete batch holds. Dutch and Irish contract manufacturers are retrofitting existing stainless-steel facilities with perfusion bioreactor skids to compress production cycles. This shift is automating quality release timelines and reducing facility footprint requirements for high-volume monoclonal antibody output.
REACH and the EU AI Act are jointly tightening material traceability and algorithmic transparency requirements for biological therapy production. Manufacturers must now document chemical substance flows in single-use assemblies and validate machine-learning models used for batch release decisions. Hematology centers deploying CAR-T patient selection algorithms face the steepest compliance adaptation curves.
Hospital procurement consortia in Germany and France are consolidating biological therapy purchasing through tender mechanisms that bundle multiple indications and lock in multi-year volume commitments. Specialized infusion centers are displacing general oncology wards as the primary administration site for complex biological regimens. This concentration is most visible in the Rhine-Main corridor, where university hospital networks coordinate formulary decisions across Frankfurt, Heidelberg, and Mannheim sites.
EMEA Cancer Biological Therapy Market Segmentation
Biological therapy segmentation in EMEA reflects divergent manufacturing economics and clinical deployment patterns. Volume-driven monoclonal antibodies contrast with patient-specific gene therapies requiring distributed cell processing infrastructure. Procurement channels further stratify between centralized hospital formulary systems and fragmented research institution purchasing.
Product Type:
Volume concentration sits with established recombinant protein platforms, while premium pricing attaches to personalized cellular interventions requiring bespoke manufacturing workflows.
- Monoclonal Antibodies:These therapeutic proteins bind specific tumor-associated antigens to block growth signals or flag malignant cells for immune destruction. Manufacturing scales through fed-batch bioreactor operations in Irish and Dutch facilities serving EMEA hospital networks. Demand concentrates in Germany's Rhine-Main corridor where university hospitals maintain long-standing formulary relationships with established antibody suppliers.
- Gene Therapy:Genetically modified cellular products including CAR-T constructs require patient-specific ex vivo engineering in GMP-compliant cleanroom suites. Swiss and German academic medical centers are expanding decentralized manufacturing capacity to reduce vein-to-vein timelines for hematology indications. REACH compliance for viral vector raw materials adds qualification complexity before clinical release.
- Vaccines:Therapeutic cancer vaccines stimulate antigen-specific immune responses against tumor-associated proteins.
- Cytokines:Signaling proteins including interferons and interleukins modulate immune cell activation states.
Mature deployment sits with Monoclonal Antibodies. Newer deployment is concentrated in Gene Therapy.
Therapy Area:
Commercial gravity shifts between solid tumor indications with broad patient populations and hematological malignancies amenable to cellular engineering protocols.
- Breast Cancer:HER2-targeted biological therapies constitute the largest revenue pool within EMEA oncology, driven by adjuvant and metastatic treatment protocols. French and German hospital consortia negotiate centralized tenders bundling multiple antibody regimens across disease stages.
- Lymphoma:CD20-directed antibodies and emerging bispecific constructs address both indolent and aggressive B-cell subtypes. CAR-T manufacturing scale-up in Heidelberg and Zurich centers is expanding access beyond relapsed/refractory cases into earlier treatment lines.
- Melanoma:Checkpoint inhibitor combinations dominate first-line immunotherapy protocols.
- Leukemia:Acute lymphoblastic and myeloid subtypes drive demand for cellular engineering approaches.
Established protocols anchor Breast Cancer deployment. Lymphoma shows the steepest expansion trajectory as cellular manufacturing matures.
Application:
Clinical deployment separates curative-intent treatment from diagnostic and preventive modalities with divergent reimbursement pathways.
- Oncology:Solid tumor biological therapy administration concentrates in specialized infusion centers displacing general ward-based chemotherapy units. The Rhine-Main corridor's clustering of university hospitals creates patient density justifying dedicated cold-chain distribution infrastructure.
- Hematology:Blood malignancy treatment integrates cellular engineering with conventional stem cell transplantation protocols. German and Swiss centers lead EMEA in GMP-compliant patient-specific manufacturing capacity for CAR-T protocols.
- Diagnostics:Companion biomarker testing stratifies patient eligibility for targeted biological interventions.
- Personalized Medicine:Individualized treatment selection based on genomic profiling is gaining share fastest in academic medical center networks.
Current infrastructure favors Oncology deployment. Personalized Medicine is capturing growing procurement volumes through early-phase clinical trial expansion.
End User:
Purchasing authority concentrates in consolidated hospital systems, while research institutions capture growing volumes through investigator-initiated studies.
- Hospitals:University hospital networks in Germany, France, and Italy command dominant procurement volumes through formulary committees and tender mechanisms. EMA centralized authorization enables cross-border patient access that justifies multi-indication volume commitments.
- Research Institutions:Academic medical centers in Switzerland and the Netherlands are expanding early-phase biological therapy trial portfolios. EU AI Act compliance requirements for algorithmic patient stratification tools are reshaping procurement specifications for diagnostic companion technologies.
- Pharmaceutical Companies:Sponsor-funded clinical trial supply chains require dedicated manufacturing slots.
- Clinics:Community oncology practices handle selected biological therapy administrations with simplified cold-chain requirements.
Procurement scale sits with Hospitals. Research Institutions are expanding fastest as EMEA early-phase trial density increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main corridor anchors EMEA biological therapy demand through Frankfurt-Heidelberg-Mannheim university hospital clustering that justifies dedicated cold-chain infrastructure and specialized infusion center networks.
Germany
Bavaria and Baden-Württemberg drive manufacturing scale through GMP-compliant facilities serving CAR-T and monoclonal antibody production. The country's national pharmaceutical regulator enforces REACH compliance for single-use bioreactor materials. Heidelberg's university medical center anchors patient-specific cell processing capacity for hematology protocols.
Switzerland
Basel and Zurich academic medical centers concentrate gene therapy manufacturing for personalized immuno-oncology interventions. Swissmedic maintains independent but harmonized review standards that enable premium pricing pathways for sponsors navigating parallel EMA tracks. The Basel biotech cluster integrates pharmaceutical headquarters with specialized hematology treatment centers.
France
Paris and Lyon hospital consortia negotiate centralized tenders bundling biological therapies across breast cancer and lymphoma indications. ANSM oversees national pharmacovigilance requirements for biological therapy batch release. The Paris-Saclay research cluster connects academic medical centers with early-phase clinical trial infrastructure.
United Kingdom
London and Cambridge biotech corridors expand biological therapy R&D following MHRA's parallel assessment pathway post-Brexit. The national pharmaceutical regulator operates independent marketing authorization procedures that create dual navigation requirements for EMEA-wide access. The Cambridge cell therapy manufacturing cluster serves NHS trusts and commercial sponsors simultaneously.
Netherlands
Amsterdam and Rotterdam contract manufacturers retrofit stainless-steel facilities with continuous bioproduction platforms for monoclonal antibody output. The country's national pharmaceutical regulator aligns with EMA centralized procedures while maintaining distinct national health technology assessment processes. The Leiden biotech corridor hosts viral vector production for gene therapy supply chains.
EMEA Cancer Biological Therapy Market Competitive Landscape
The competitive structure tilts toward integrated pharmaceutical conglomerates with established biologics manufacturing networks. Market concentration reflects high capital barriers for GMP-compliant cell culture infrastructure and the dominance of hospital formulary relationships in procurement decisions. Two strategic archetypes predominate: diversified biopharmaceutical majors with cross-indication antibody portfolios, and specialized immuno-oncology developers focused on cellular engineering platforms. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as players secure manufacturing slots and distribution infrastructure across the Rhine-Main corridor and Swiss academic networks.
Within the diversified biopharmaceutical tier, Bristol-Myers Squibb Company and F. Hoffmann-La Roche Ltd occupy positions reflecting established European manufacturing footprints and long-standing hospital formulary relationships. Merck & Co. exemplifies the R&D-intensive archetype through its concentration on immuno-oncology platform development. These three entities represent the competitive core against which newer entrants and biosimilar developers benchmark manufacturing scale and regulatory navigation capabilities.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Merck & Co. |
| F. Hoffmann-La Roche Ltd |
| Eli Lilly and Company |
| Pfizer Inc. |
| Novartis International |
| Amgen Inc. |
| Bayer AG |
| AstraZeneca PLC |
| Others |
Supply & Pricing Matrix
Cold-chain energy costs cascade from German electricity markets through biological therapy distribution margins, compressing per-dose profitability as hospital consortia consolidate procurement leverage across the Rhine-Main corridor.
Pricing Analysis
Value-based pricing anchors on clinical outcome thresholds for CAR-T cell therapies, with German and Swiss hospital networks negotiating indication-specific reimbursement bundles. Price differentiation separates premium patient-specific cellular products from standard monoclonal antibody regimens based on manufacturing complexity and vein-to-vein timeline guarantees. Cost compression in the biosimilar tier intensifies as EMA interchangeability guidance remains unsettled, forcing originator sponsors to defend formulary position through service bundling. Research institutions exhibit highest price sensitivity due to grant-funded procurement constraints, while specialized infusion centers in Heidelberg and Zurich maintain lowest sensitivity given captive patient flows and premium positioning.
Supply Chain Analysis
Regional distribution centers in Frankfurt and Mannheim anchor hub-and-spoke cold-chain networks serving university hospital clusters across Baden-Württemberg and Bavaria. Manufacturing concentration rests on Ireland, the Netherlands, and Switzerland for GMP-compliant bioreactor operations, with German facilities handling patient-specific cell processing. Raw material dependencies center on single-use film assemblies, viral vector production media, and aseptic sensor technologies predominantly sourced from specialized chemical suppliers. Single-source vulnerability in sterile bioreactor component qualification creates exposure to REACH compliance delays. Distribution runs through dedicated pharmaceutical logistics operators with validated temperature-controlled infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GMP-compliant cell therapy technician scarcity props pricing power for sponsors with captive manufacturing capacity, constraining supply expansion despite demand acceleration across hematology indications.
For Market Incumbents: Acquire decentralized cell processing facilities in Swiss and German academic medical centers to secure CAR-T manufacturing slots before competitor capacity comes online. Consolidate formulary relationships through multi-indication tender participation with Rhine-Main hospital consortia. Backward integration into viral vector production reduces exposure to raw material qualification bottlenecks under REACH.
For New Entrants and Emerging Players: Digital-channel patient stratification tools offer the lowest-friction entry path, enabling algorithm-driven companion diagnostic partnerships that unlock reimbursement for precision biological therapies. Eastern European oncology networks in Poland and Czech Republic present the most penetrable geography, with upgrading infusion infrastructure creating first-mover opportunities in markets previously limited to Western EU protocols. Target investigator-initiated trial supply relationships with Dutch and Swiss research institutions.
For Investors and Strategic Acquirers: Distressed-cycle entries favor contract manufacturing organizations with validated continuous bioproduction platforms in Ireland and the Netherlands, where facility retrofitting costs have compressed asset valuations. Long-term viability hinges on securing manufacturing relationships with sponsors navigating dual EMA-MHRA regulatory tracks post-Brexit. Watch EMA biosimilar interchangeability guidance as the critical inflection signal for originator defense spending intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Expands GMP cell processing capacity in Heidelberg and Zurich academic centers to reduce vein-to-vein timelines. |
| Regulatory Approval Pathway | Navigates parallel EMA and Swissmedic tracks to capture premium pricing in Alpine markets. |
| Backward Integration | Captures viral vector production capacity to secure raw material flows under REACH compliance. |
| Hospital System Partnership | Locks multi-indication volume commitments through Rhine-Main corridor formulary consolidation. |
| Software Companion Development | Validates EU AI Act-compliant patient stratification algorithms for precision therapy reimbursement. |
Research Methodology
Document review covered EMA centralized authorization records, ClinicalTrials.gov entries, and hospital procurement databases, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers across the EMEA region. Secondary validation drew from REACH compliance filings, EU Green Deal pharmaceutical sustainability directives, and national health technology assessment positions in France, Germany, and Italy. Bottom-up segmentation modeling triangulated against top-down market sizing from biologics manufacturing capacity disclosures.
Cross-referencing historical approval timelines against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled included product type, therapy area, application, end user, and regional regulatory cluster. CAGRs were derived from capacity expansion trajectories and patient population epidemiology. Forecast inputs incorporated bioreactor utilization rates and cold-chain infrastructure investment pipelines.
Inputs from EMA and Swissmedic regulatory filings were available through the study window; gaps in real-time hospital tender outcome data introduce uncertainty bands around volume assumptions. Forecasts reflect documented assumptions regarding manufacturing scale-up timelines and reimbursement pathway convergence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Global Cell Based Immunotherapy Market
Cell & Gene Therapy
Viral Vector Production (Research-Use) Market
Cell & Gene Therapy
Hemophilia Gene Therapy Market
Cell & Gene Therapy
Oncolytic Adenovirus Market
Cell & Gene Therapy
Global Gene Therapy Market
Cell & Gene Therapy
Asia Pacific Cancer Biological Therapy Market
Cell & Gene Therapy
Europe Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Global Umbilical Cord Blood (UCB) Stem Cell Market
Cell & Gene Therapy
Rheumatoid Arthritis Stem Cell Therapy Market
Cell & Gene Therapy
Mrna Vaccines and Therapeutics Market
Cell & Gene Therapy
T Cell Therapy Market
Cell & Gene Therapy
Nucleic Acid Therapeutics CDMO Market
Cell & Gene Therapy
North America Stem Cell Therapy Market
Cell & Gene Therapy
Global Human DNA Vaccines Market
Cell & Gene Therapy
GMP Cell Banking Services Market
Cell & Gene Therapy
Stem Cell and Gene Therapy Biological Testing Market