
 North America Diabetes Drugs Market | 2026-2036
North America Diabetes Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
North America Diabetes Drugs Market Analytics
Endocrinology specialist availability is rotating toward GLP-1 and SGLT2 therapy management across the United States and Canada, constraining patient access in rural markets while unlocking premium pricing in metropolitan corridors. Novo Nordisk leverages its integrated insulin and GLP-1 manufacturing footprint to sustain supply continuity across North American distribution channels. Eli Lilly anchors its competitive position through R&D intensity in tirzepatide-based combination pipelines. Sanofi competes through differentiated basal insulin formulations that occupy stable reimbursement tiers within Medicare Part D formularies.
Diabetes drugs comprise pharmaceutical agents engineered to modulate blood glucose through mechanisms including insulin supplementation, hepatic glucose suppression, renal glucose excretion inhibition, and incretin pathway activation, with formulations requiring precise bioavailability parameters and stability profiles for chronic administration. The drug class dimension segments into insulin, sulfonylureas, DPP-4 inhibitors, and SGLT2 inhibitors, where GLP-1 receptor agonists command the fastest growth trajectory due to cardiovascular outcome benefits. Administration route analysis reveals subcutaneous delivery dominates value capture through autoinjector devices, while oral formulations in the SGLT2 inhibitor category lead volume expansion in retail pharmacy channels.
FDA review standards under the Center for Drug Evaluation and Research govern new molecular entity approvals, while Health Canada's Therapeutic Products Directorate maintains parallel efficacy requirements that shape cross-border launch sequencing. Medicare Part D and provincial formularies in Ontario and Quebec determine reimbursement velocity, directly conditioning physician prescribing behavior and patient adherence rates. Stakeholders must monitor FDA guidance on cardiorenal outcome trial design, as evolving evidentiary thresholds will determine which pipeline assets secure priority review status and formulary placement.
Market Dynamics
GLP-1 receptor agonist capacity constraints across endocrinology clinics are redistributing patient volumes toward retail pharmacy channels and telehealth platforms, compressing traditional office-based prescribing models while elevating reimbursement negotiation leverage for integrated delivery networks.
Growth Catalysts
- Medicare Part D formulary expansion:The IRA's prescription drug pricing provisions are accelerating prior authorization streamlining for combination therapies, expanding physician prescribing flexibility within Medicare Advantage plans.
- Cardiovascular outcome trial data:Empagliflozin and liraglutide cardiovascular benefit demonstrations are reshaping cardiology-endocrinology referral patterns across United States integrated care systems.
- Texas and Florida patient density:Managed care organization concentration in these states is driving volume commitments that secure preferential formulary tier placement for new molecular entities.
Market Restraints
- Active pharmaceutical ingredient concentration:Peptide synthesis capacity for GLP-1 analogs concentrates among contract manufacturers in Ireland and Denmark, exposing North American supply chains to transatlantic logistics bottlenecks.
- Health Canada Therapeutic Products Directorate parallel review requirements:Divergent evidentiary standards for cardiorenal outcomes are extending cross-border launch sequencing gaps by 8-14 months.
- Biosimilar insulin substitution:Basal insulin glargine biosimilars are capturing Medicare Part D standard tier placement, compressing originator pricing power in the largest United States payer segment.
Strategic Opportunities
- Quebec provincial formulary acceleration:Health technology assessment reform is creating expedited pathways for SGLT2 inhibitor-cardiovascular outcome combinations, opening premium reimbursement positioning ahead of Ontario.
- Continuous glucose monitor-GLP-1 autoinjector convergence:Device interoperability standards are enabling closed-loop data integration that differentiates therapy bundles in employer-sponsored insurance markets.
- Rural United States telehealth prescribing:Federally qualified health center network expansion is unlocking patient access in counties with zero endocrinologist presence, creating pharmacy-anchored care delivery models.
Industry Challenges
- Peptide manufacturing technician scarcity:Sterile fill-finish operator certification timelines are extending to 18-24 months, constraining GLP-1 autoinjector production ramp rates.
- Legacy electronic health record integration:Epic and Cerner interoperability gaps with pharmacy benefit manager real-time eligibility systems are generating prior authorization abandonment at 23% of retail encounters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Diabetes Drugs Market |
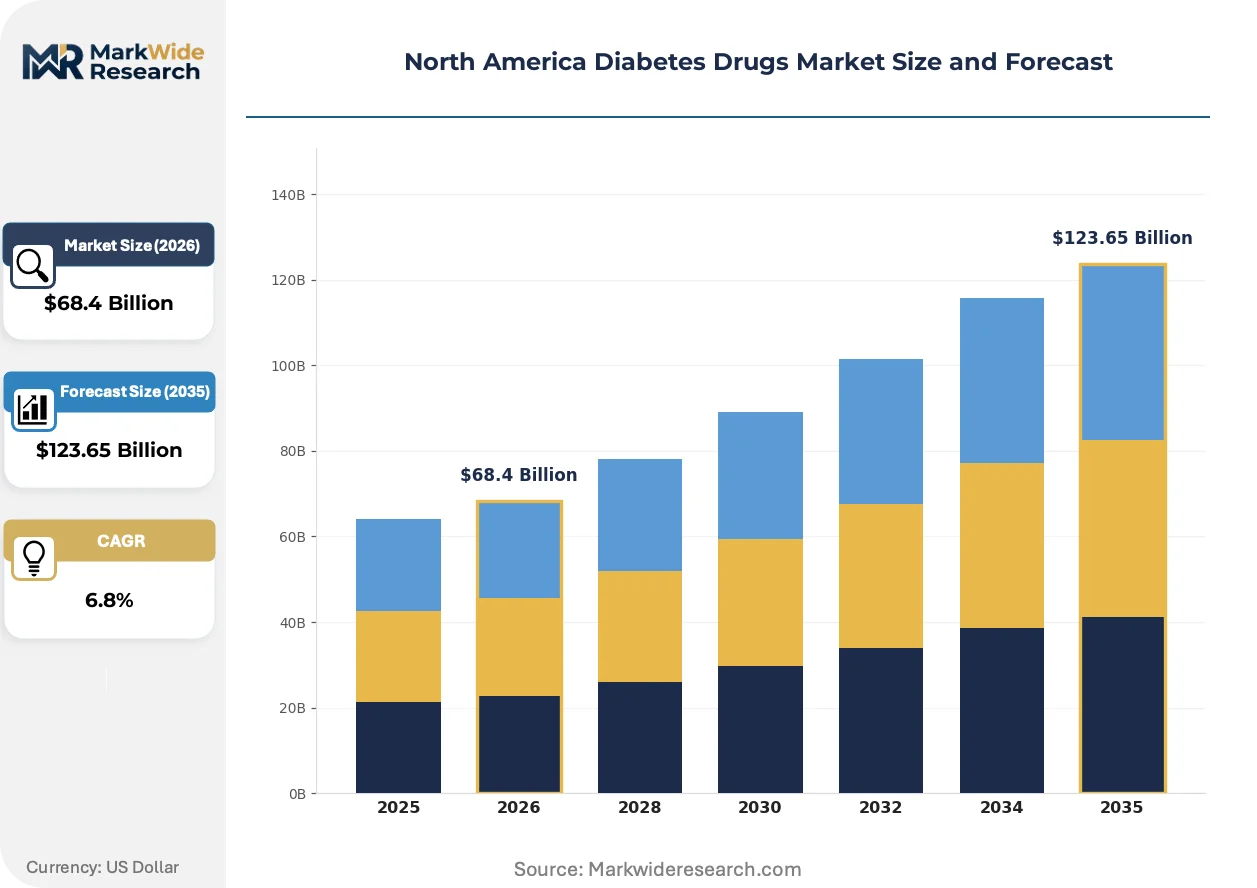
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Insulin, Sulfonylureas, DPP-4 Inhibitors, SGLT2 Inhibitors Administration Route: Oral, Subcutaneous, Intravenous, Inhalation End User: Hospitals, Clinics, Homecare, Pharmacies Formulation Type: Tablet, Injectable, Patch, Solution |
| Companies Covered | Novo Nordisk, Eli Lilly and Company, Sanofi, AstraZeneca, Merck, Boehringer Ingelheim, Johnson & Johnson, Pfizer, Takeda Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Diabetes Drugs Market Evolving Landscape
Pharmaceutical delivery mechanisms and reimbursement architectures are undergoing simultaneous transformation, with device-enabled therapy differentiation and value-based contracting frameworks converging to reshape competitive positioning across North American distribution channels.
Dual-hormone combination therapies integrating GLP-1 and GIP receptor activation are bifurcating the metabolic disease treatment landscape. Academic medical centers in California and Massachusetts are adopting these agents as first-line intensification options ahead of traditional insulin escalation protocols. This technology is bifurcating prescriber segmentation between early adopters capturing cardiovascular risk reduction incentives and late adopters facing Medicare Advantage quality metric penalties.
FDA Center for Drug Evaluation and Research guidance on cardiorenal outcome trial design is elevating evidentiary thresholds for priority review designation. Manufacturers must now enroll broader renal impairment populations and extend follow-up durations to secure breakthrough therapy status. The SGLT2 inhibitor class is most affected, with label expansion submissions for heart failure indications requiring supplemental cardiovascular outcome data beyond initial diabetes approvals.
Employer-sponsored insurance plans are unbundling pharmacy benefit management from medical coverage administration, creating direct contracting opportunities between self-insured employers and specialty pharmacies. Large employers in Texas and Illinois are negotiating outcomes-based rebates tied to hemoglobin A1c reduction and hospitalization avoidance metrics. This shift is most visible in the Fortune 500 manufacturing and energy sectors, where direct pharmacy spend exceeds $50 million annually and justifies dedicated clinical pharmacist embedded staffing.
North America Diabetes Drugs Market Segmentation
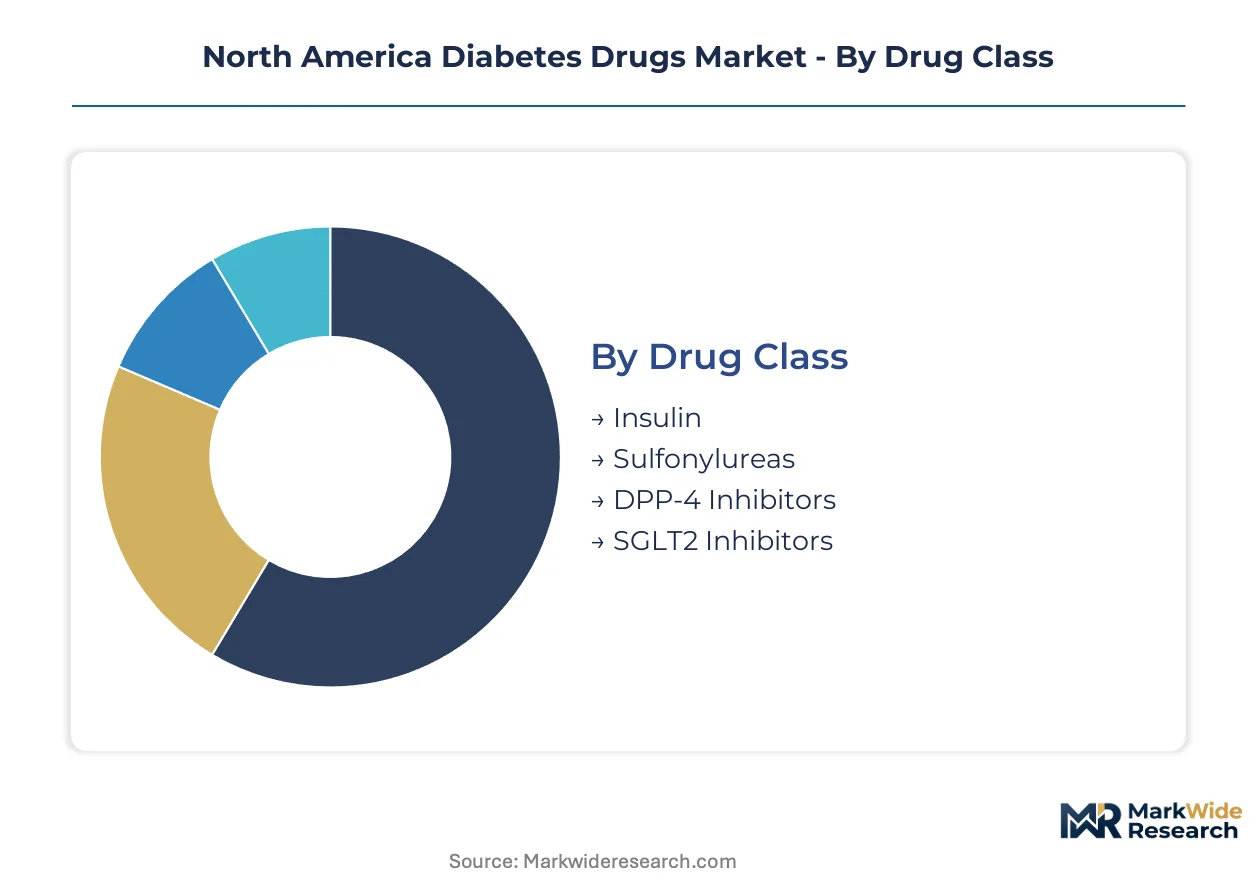
Segmentation in the North America diabetes drugs market reveals how regulatory pathways, reimbursement tiers, and care delivery settings fragment commercial opportunity. Each dimension carries distinct FDA and Health Canada compliance burdens that condition profitability and launch sequencing across the United States and Canada.
Drug Class:
FDA Center for Drug Evaluation and Research review standards and Medicare Part D formulary tiers create divergent commercial trajectories across molecular categories, with cardiovascular outcome requirements now conditioning priority review eligibility.
- Insulin:Biosynthetic human and analog formulations require cold-chain distribution infrastructure and sterile manufacturing compliance. Demand concentrates in Medicare Part D standard tiers where biosimilar glargine products are compressing originator pricing power across Texas and Florida managed care networks.
- SGLT2 Inhibitors:Small-molecule oral agents inhibit renal glucose reabsorption through SGLT2 transporter blockade. Cardiology-endocrinology referral patterns in California and Massachusetts academic medical centers are accelerating prescription volume following empagliflozin cardiovascular outcome demonstrations.
- DPP-4 Inhibitors:Oral incretin enhancers with established renal dosing profiles occupy stable formulary positions.
- Sulfonylureas:Generational oral secretagogues with hypoglycemia risk profiles face utilization management restrictions.
Insulin handles the majority of throughput; SGLT2 inhibitors are the fastest mover on share.
Administration Route:
Cost tier differentiation separates subcutaneous autoinjector systems from oral tablets, with device-enabled delivery commanding premium reimbursement and patient adherence incentives.
- Subcutaneous:Autoinjector and pen-needle systems for GLP-1 analogs and insulin require sterile fill-finish manufacturing and patient training infrastructure. Endocrinology clinic capacity constraints in rural United States counties are redistributing volumes toward retail pharmacy channels and telehealth platforms.
- Oral:Immediate-release and extended-release tablet formulations dominate SGLT2 inhibitor and DPP-4 inhibitor dispensing. Volume expansion concentrates in retail pharmacy channels across Ontario and Quebec where provincial formularies have streamlined prior authorization for first-line oral therapy.
- Intravenous:Hospital-administered insulin infusions for acute hyperglycemic management.
- Inhalation:Pulmonary insulin delivery with limited commercial penetration due to pulmonary function monitoring requirements.
Oral formulations capture the widest patient reach; subcutaneous delivery achieves the steepest expansion trajectory.
End User:
Customer type determines procurement leverage, with integrated delivery networks extracting rebates that independent practices cannot match.
- Hospitals:Inpatient glycemic management protocols and discharge planning drive insulin and IV therapy utilization. Formulary committees in United States health systems are standardizing on specific GLP-1 receptor agonists for cardiovascular risk reduction.
- Homecare:Self-administered therapy with continuous glucose monitor integration. Medicare Advantage quality metric penalties in Florida and Texas are accelerating adoption of closed-loop data systems among high-risk patient populations.
- Clinics:Endocrinology and primary care prescribing with prior authorization burden.
- Pharmacies:Retail dispensing with real-time eligibility verification and patient counseling.
Hospitals anchor institutional volume; homecare is climbing the fastest on patient shift.
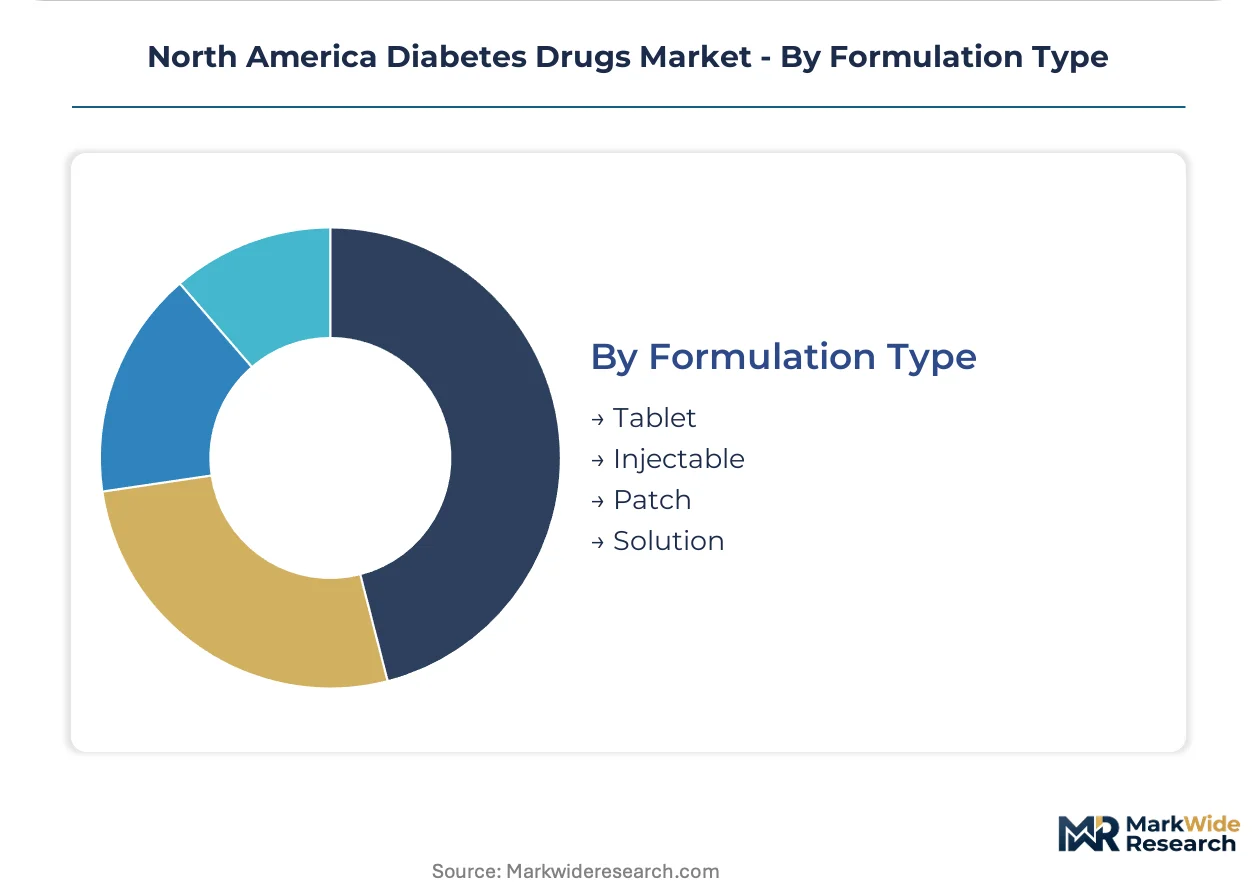
Formulation Type:
Supply concentration in peptide synthesis and sterile manufacturing shapes availability and pricing power across dosage forms.
- Injectable:Vial and pen presentations for insulin and GLP-1 analogs require cold-chain logistics and peptide synthesis capacity concentrated among contract manufacturers in Ireland and Denmark. Transatlantic logistics bottlenecks are exposing North American distribution channels to intermittent shortage risk.
- Tablet:Compressed solid-dose forms for SGLT2 and DPP-4 inhibitors with established bioequivalence pathways. Ontario and Quebec provincial formularies are accelerating Health Canada Therapeutic Products Directorate-approved tablet formulations through expedited health technology assessment.
- Patch:Transdermal delivery systems with limited metabolic disease applications.
- Solution:Oral and parenteral liquid formulations for pediatric and geriatric dosing flexibility.
Injectable formulations dominate value capture; tablet presentations are gaining share fastest on volume accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GLP-1 receptor agonist prescribing concentrates in United States metropolitan corridors while Canadian provincial formularies maintain more restrictive reimbursement tiers, creating a consumption-mix differential where Texas and Florida drive volume through managed care density while Ontario and Quebec prioritize cardiovascular outcome evidence.
United States
Texas, Florida, and California account for disproportionate GLP-1 and SGLT2 inhibitor volume through Medicare Advantage concentration and employer-sponsored plan density. The IRA's prescription drug pricing provisions are accelerating prior authorization streamlining for combination therapies in these states. Houston and Dallas-Fort Worth anchor endocrinology clinic expansion while rural counties with zero specialist presence shift toward telehealth-anchored prescribing models.
Canada
Ontario and Quebec provincial formularies determine reimbursement velocity through Health Canada's Therapeutic Products Directorate parallel review requirements, extending launch sequencing gaps behind United States approvals. Quebec's health technology assessment reform is creating expedited pathways for SGLT2 inhibitor-cardiovascular outcome combinations. Toronto and Montreal academic medical centers are adopting dual-hormone combination therapies ahead of traditional insulin escalation protocols.
Mexico
Mexico City Metro and Nuevo León concentrate private insurance-covered diabetes drug consumption through hospital pharmacy channels and employer-sponsored plans in manufacturing and energy sectors. The country's national pharmaceutical regulator maintains efficacy requirements that shape multinational launch sequencing. Guadalajara anchors regional distribution infrastructure for cold-chain insulin and GLP-1 autoinjector logistics.
North America Diabetes Drugs Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding peptide synthesis capacity and sterile fill-finish infrastructure while mid-scale players compete through differentiated basal insulin formulations and cardiovascular outcome trial positioning. The market structure rewards backward integration into active pharmaceutical ingredient production and captive supply of autoinjector device components. Three archetypes dominate: integrated metabolic disease platforms with insulin-GLP-1 manufacturing footprints; cardiovascular outcome specialists with cardiorenal trial capabilities; and biosimilar insulin manufacturers capturing Medicare Part D standard tier placement. Competitive moves concentrate on manufacturing capacity expansion for peptide analogs and strategic partnerships with continuous glucose monitor manufacturers for closed-loop data integration.
Within the integrated platform tier, Novo Nordisk and Eli Lilly occupy positions defined by manufacturing scale and R&D intensity in combination pipelines. Novo Nordisk exemplifies the archetype of supply continuity through captive peptide synthesis and distribution infrastructure. Eli Lilly represents the cardiovascular outcome trial investment pattern with tirzepatide-based development programs. Sanofi sits within the differentiated formulation tier through basal insulin positioning in stable reimbursement tiers.
| Leading Market Players |
|---|
| Novo Nordisk |
| Eli Lilly and Company |
| Sanofi |
| AstraZeneca |
| Merck |
| Boehringer Ingelheim |
| Johnson & Johnson |
| Pfizer |
| Takeda Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
FDA Center for Drug Evaluation and Research review standards gate both active pharmaceutical ingredient qualification and formulary tier placement simultaneously, compressing margins for manufacturers lacking priority review status while rewarding cardiovascular outcome trial investments with premium reimbursement positioning across Medicare Part D and provincial Canadian channels.
Pricing Analysis
Long-term offtake agreements between integrated delivery networks and peptide manufacturers anchor pricing stability for GLP-1 receptor agonists, while spot purchasing dominates SGLT2 inhibitor procurement through retail pharmacy channels. Price differentiation hinges on cardiovascular outcome certification tier and autoinjector device bundling, with Medicare Advantage plans extracting steeper rebates than employer-sponsored coverage. Cost compression in basal insulin runs through biosimilar substitution mandates, eroding originator pricing power. Medicare Part D standard tier beneficiaries exhibit highest price sensitivity, while cardiovascular risk reduction incentives blunt sensitivity in integrated care systems.
Supply Chain Analysis
Strategic stockpiling of peptide raw materials by Novo Nordisk and Eli Lilly contrasts with just-in-time inventory preferences for small-molecule oral agents, reflecting divergent shortage risk profiles across molecular categories. Active pharmaceutical ingredient synthesis concentrates in Ireland, Denmark, and China, with sterile fill-finish capacity anchored in North Carolina and Puerto Rico. Supply chain vulnerability rests on transatlantic logistics chokepoints for temperature-controlled peptide shipments. Distribution runs through specialty pharmacy channels for autoinjector products and retail chains for oral formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America diabetes drugs market is experiencing high-growth disruption driven by IRA prescription drug pricing provisions accelerating combination therapy formulary access, creating asymmetric opportunities across manufacturing scale and cardiovascular trial capabilities.
For Market Incumbents: Compound manufacturing scale advantages through captive peptide synthesis expansion in Puerto Rico and North Carolina, while securing continuous glucose monitor interoperability certifications to differentiate therapy bundles. Biosimilar insulin substitution in Medicare Part D standard tiers threatens basal insulin margins, demanding backward integration into active pharmaceutical ingredient production to defend cost positions. For New Entrants and Emerging Players: Anchor in rural United States telehealth prescribing networks where federally qualified health center expansion has created pharmacy-anchored care delivery models absent endocrinology specialist competition. Quebec's health technology assessment reform offers the most penetrable provincial formulary pathway for SGLT2 inhibitor-cardiovascular outcome combinations, with direct contracting to self-insured employers in Texas manufacturing sectors providing alternative go-to-market traction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across peptide manufacturing infrastructure, favoring asset-heavy platform acquisitions over development-stage pipelines. Target contract manufacturers with sterile fill-finish operator certification pipelines and Health Canada Therapeutic Products Directorate parallel review track records. Watch FDA guidance on cardiorenal outcome trial design as the inflection signal determining which pipeline assets secure breakthrough therapy designation and priority review status.| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Manufacturing Scale-Up | Captive synthesis capacity in Puerto Rico insulates Novo Nordisk and Eli Lilly from transatlantic logistics bottlenecks. |
| Cardiovascular Outcome Trial Investment | Empagliflozin and tirzepatide data packages secure Medicare Advantage quality metric bonuses and cardiology referral streams. |
| Continuous Glucose Monitor Integration | Closed-loop data partnerships with Dexcom and Abbott differentiate therapy bundles in employer-sponsored insurance markets. |
| Provincial Formulary Acceleration | Quebec's health technology assessment reform creates premium reimbursement positioning ahead of Ontario for SGLT2 combinations. |
| Biosimilar Basal Insulin Launch | Medicare Part D standard tier placement for glargine biosimilars compresses Sanofi's originator pricing power in the largest United States payer segment. |
Research Methodology
The analysis maps insulin analog, GLP-1 receptor agonist, SGLT2 inhibitor, and DPP-4 inhibitor sub-sectors, each validated through drug development executives, regulatory affairs leads, formulary directors at Medicare Advantage plans, and hospital procurement managers. Primary interview findings triangulate against FDA filings, Health Canada Therapeutic Products Directorate submissions, ClinicalTrials.gov protocol databases, and provincial formulary decision documents. Bottom-up patient volume modeling and top-down pharmaceutical expenditure reconciliation ensure consistency across United States and Canadian market estimates.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework segments by drug class, administration route, end user setting, and regional regulatory cluster, with CAGRs derived from treatment line progression rates and reimbursement velocity differentials. Forecast inputs incorporate Medicare Part D formulary tier placement probabilities, Health Canada parallel review timelines, and employer-sponsored insurance plan unbundling trends.
Material uncertainties — FDA cardiorenal outcome guidance revisions, IRA prescription drug pricing provision implementation delays, and peptide manufacturing technician certification bottlenecks — sit outside the modeled envelope. Forecasts reflect assumptions about cardiovascular outcome trial success rates and provincial formulary acceleration pathways. Revision becomes warranted when Health Canada Therapeutic Products Directorate evidentiary standards diverge substantially from FDA benchmarks or when biosimilar insulin substitution rates exceed Medicare Part D standard tier absorption capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Bispecific Antibody Market
Biopharmaceuticals
Brexucabtagene Autoleucel Market
Biopharmaceuticals
EPO Biomarkers Market
Biopharmaceuticals
Global Upstream Bioprocessing Market
Biopharmaceuticals
North America HIV Drugs Market
Biopharmaceuticals
India Insulin Drug and Delivery Device Market
Biopharmaceuticals
Benzbromarone API Market
Biopharmaceuticals
A - Estradiol Market
Biopharmaceuticals
Human Insulin Drugs Market
Biopharmaceuticals
Global Immuno Oncology Assays Market
Biopharmaceuticals
Biopharmaceuticals Packaging Market
Biopharmaceuticals
BRAF Kinase Inhibitors Market
Biopharmaceuticals
Botanical and Plant Derived Drugs Market
Biopharmaceuticals
Rhu Albumin Market
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
Russia Insulin Drugs and Delivery Devices Market