
 North America HIV Drugs Market | 2026-2036
North America HIV Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
North America HIV Drugs Market Intelligence
Specialty pharmacies is redrawing procurement patterns across the North America HIV drugs landscape as hospitals cede dispensing volume to outpatient-focused channels. Gilead Sciences leverages its integrated portfolio across oral and long-acting modalities to sustain formulary dominance. ViiV Healthcare anchors the injectable segment through concentrated R&D investment in cabotegravir-based regimens.
North America HIV drugs comprise antiretroviral pharmaceutical agents formulated as single or fixed-dose combinations targeting viral replication through inhibition of reverse transcriptase, protease, or integrase enzymes, with long-acting injectable suspensions now achieving therapeutic drug concentrations for one to two months per administration. Integrase inhibitors occupy the highest-margin position within the product type architecture due to superior resistance profiles and tolerability. The delivery mode dimension is bifurcating sharply between daily oral maintenance and long-acting injectable uptake, with subcutaneous administration gaining traction in adherence-challenged populations.
The FDA governs approval standards and post-market surveillance requirements for all novel antiretroviral entrants, while Health Canada and the Public Health Agency of Canada coordinate joint procurement and pricing negotiations for provincial formularies. The IRA's Medicare drug price negotiation provisions are reshaping reimbursement thresholds for legacy oral therapies. Stakeholders must monitor how long-acting formulation pipelines intersect with evolving payer prior-authorization criteria.
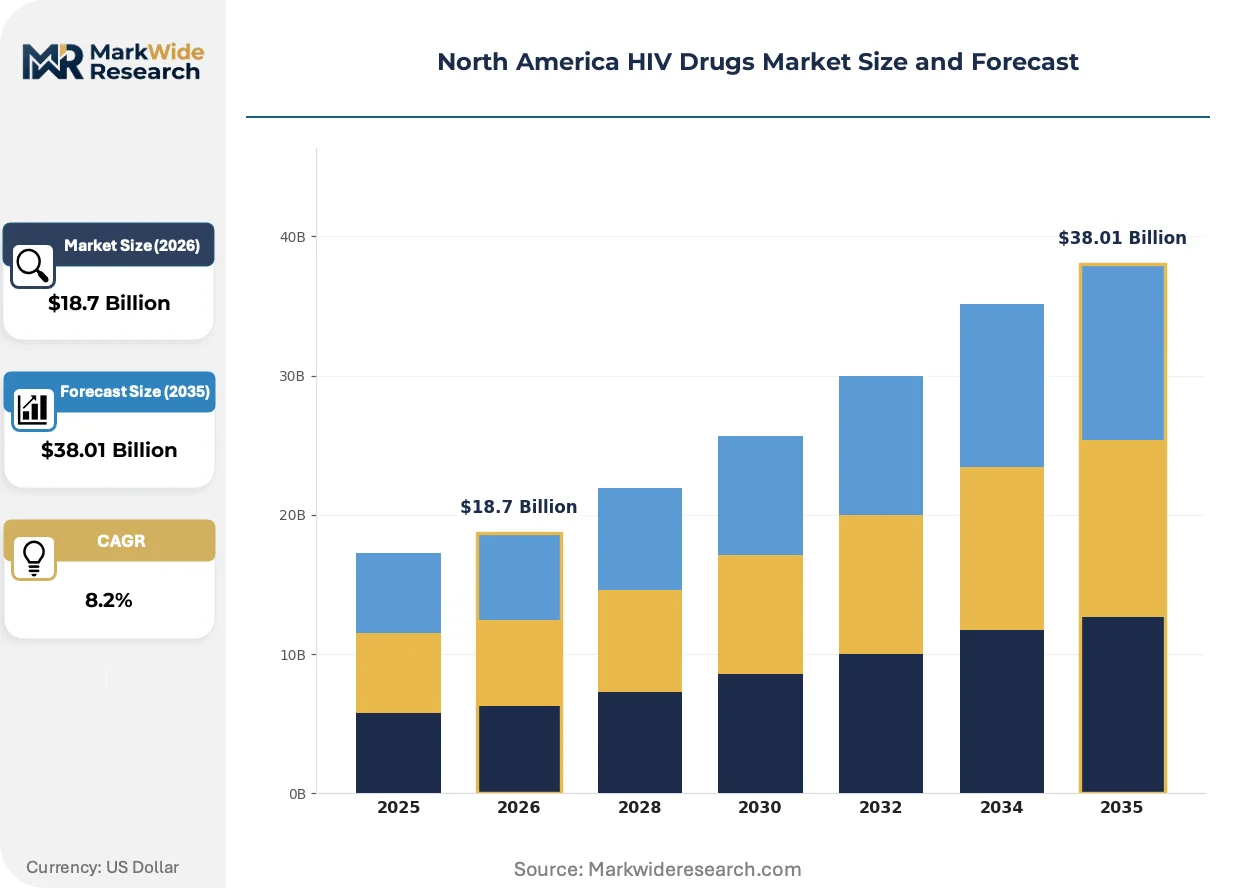
Market Dynamics
Long-acting injectable antiretroviral formulations are compressing patient visit frequencies and redistributing dispensing authority from hospital systems toward outpatient specialty pharmacy networks across the United States and Canada.
Growth Catalysts
- IRA Medicare Price Negotiation:The Inflation Reduction Act's drug pricing provisions are expanding patient access to legacy oral therapies through reduced out-of-pocket obligations at federally qualified health centers.
- Cabotegravir-Rilpivirine Long-Acting Regimens:Bimonthly subcutaneous administration is capturing adherence-challenged patient populations previously lost to daily oral discontinuation.
- Ryan White Program Funding Concentration:United States federal grants are channeling procurement volume toward integrated care clinics in urban corridors with elevated HIV prevalence.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Synthesis of integrase strand transfer inhibitors depends on limited contract manufacturers in India and China, exposing supply continuity to geopolitical friction.
- Cold Chain Infrastructure Gaps:Long-acting injectable suspensions require uninterrupted 2-8°C distribution, constraining reach into rural Canadian territories and remote US tribal health facilities.
- Prior Authorization Complexity:Payer formulary tiers for novel injectables impose multi-step approval protocols that delay therapy initiation by weeks in Medicaid-managed care plans.
Strategic Opportunities
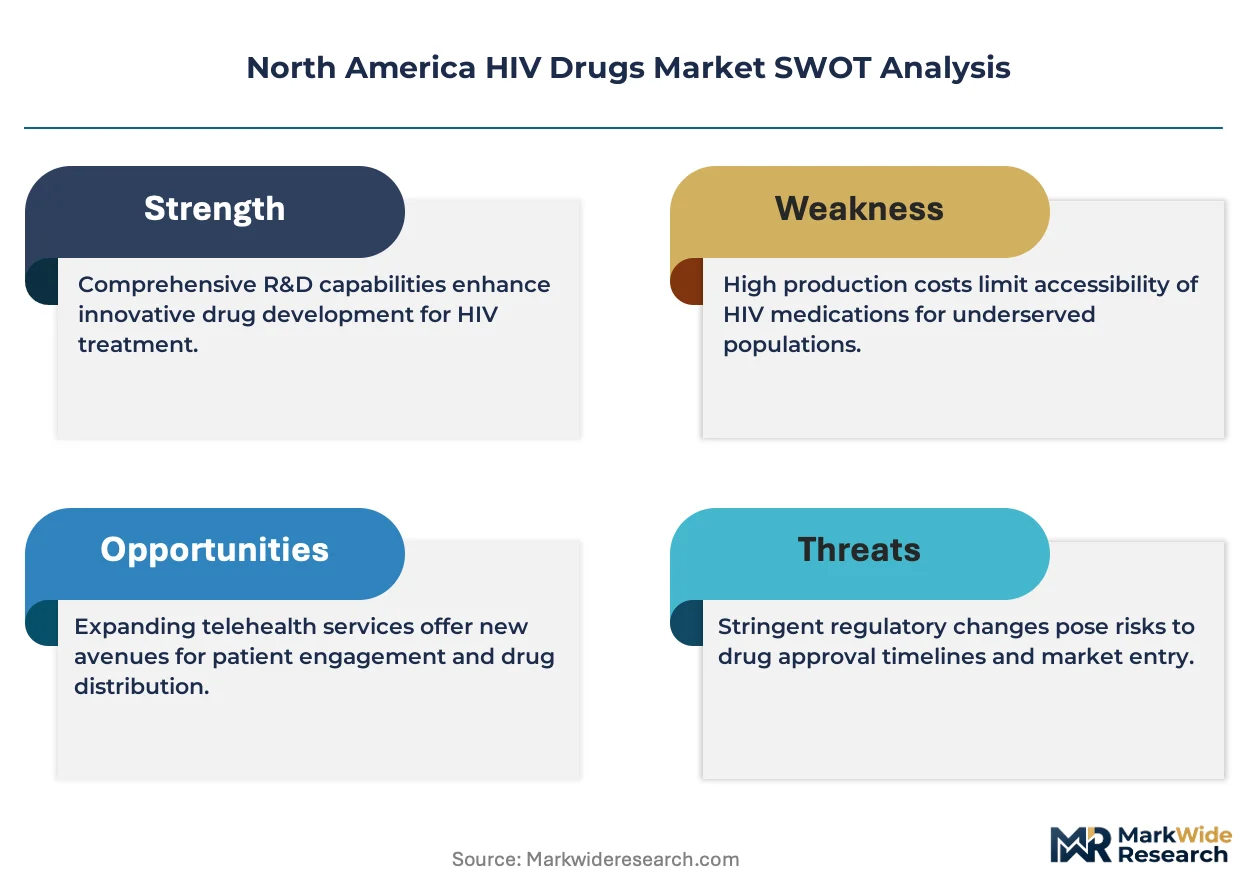
- 340B Drug Pricing Program Expansion:Eligible covered entities in the United States can capture margin spread between discounted acquisition and reimbursement rates to fund adherence support services.
- Telehealth-Integrated Dispensing:Virtual clinical consultations paired with mail-order specialty pharmacy fulfillment are penetrating rural Appalachian and Southwestern patient populations.
- Pre-Exposure Prophylaxis (PrEP) Protocol Broadening:Injectable cabotegravir for HIV prevention is gaining formulary inclusion among US commercial payers, opening demand beyond treatment-only indications.
Industry Challenges
- Pharmacovigilance Workforce Scarcity:FDA-mandated Risk Evaluation and Mitigation Strategies for long-acting formulations require specialized safety monitoring personnel that outpatient clinics struggle to recruit.
- Interoperable Health Record Fragmentation:Ryan White Program data reporting requirements conflict with state Medicaid management information systems, forcing duplicate documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America HIV Drugs Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.01 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NRTIs, NNRTIs, PIs, Integrase Inhibitors Therapy Area: Antiretroviral Therapy, Pre-Exposure Prophylaxis, Post-Exposure Prophylaxis, Combination Therapy Care Setting: Outpatient Clinics, Hospitals, Home Care, Specialty Pharmacies Delivery Mode: Oral, Injectable, Long-Acting, Subcutaneous |
| Companies Covered | Gilead Sciences, ViiV Healthcare, Merck & Co., Bristol-Myers Squibb Company, AbbVie, Janssen Pharmaceuticals, GlaxoSmithKline, Boehringer Ingelheim International GmbH, Theratechnologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America HIV Drugs Market Strategic Shifts & Innovations
Formulation science and reimbursement mechanics are jointly transforming how antiretroviral therapies reach patients, with administration frequency and site-of-care location becoming primary competitive variables.
Long-acting injectable nanosuspensions are supplanting daily oral combination tablets in maintenance therapy for virologically suppressed patients. Federally qualified health centers in the United States are accelerating adoption to reduce retention-in-care gaps. This modality shift is compressing pharmacy revenue per script while expanding total addressable patient years through improved persistence.
The FDA's accelerated approval pathway for antiretroviral therapies is truncating Phase III-to-launch intervals for novel integrase inhibitors. Sponsors are leveraging surrogate endpoint agreements to secure conditional authorization based on viral load suppression rather than clinical outcome data. Health Canada is harmonizing review timelines with FDA determinations, compressing North American regulatory lag.
Specialty pharmacies are capturing dispensing volume previously held by hospital outpatient departments through white-bagging arrangements with payers. PBM-owned pharmacies are integrating clinical counseling with automated adherence monitoring to justify preferred network status. This channel migration is most pronounced in California, Florida, and New York, where Medicaid managed care penetration exceeds national averages.
North America HIV Drugs Market Segmentation
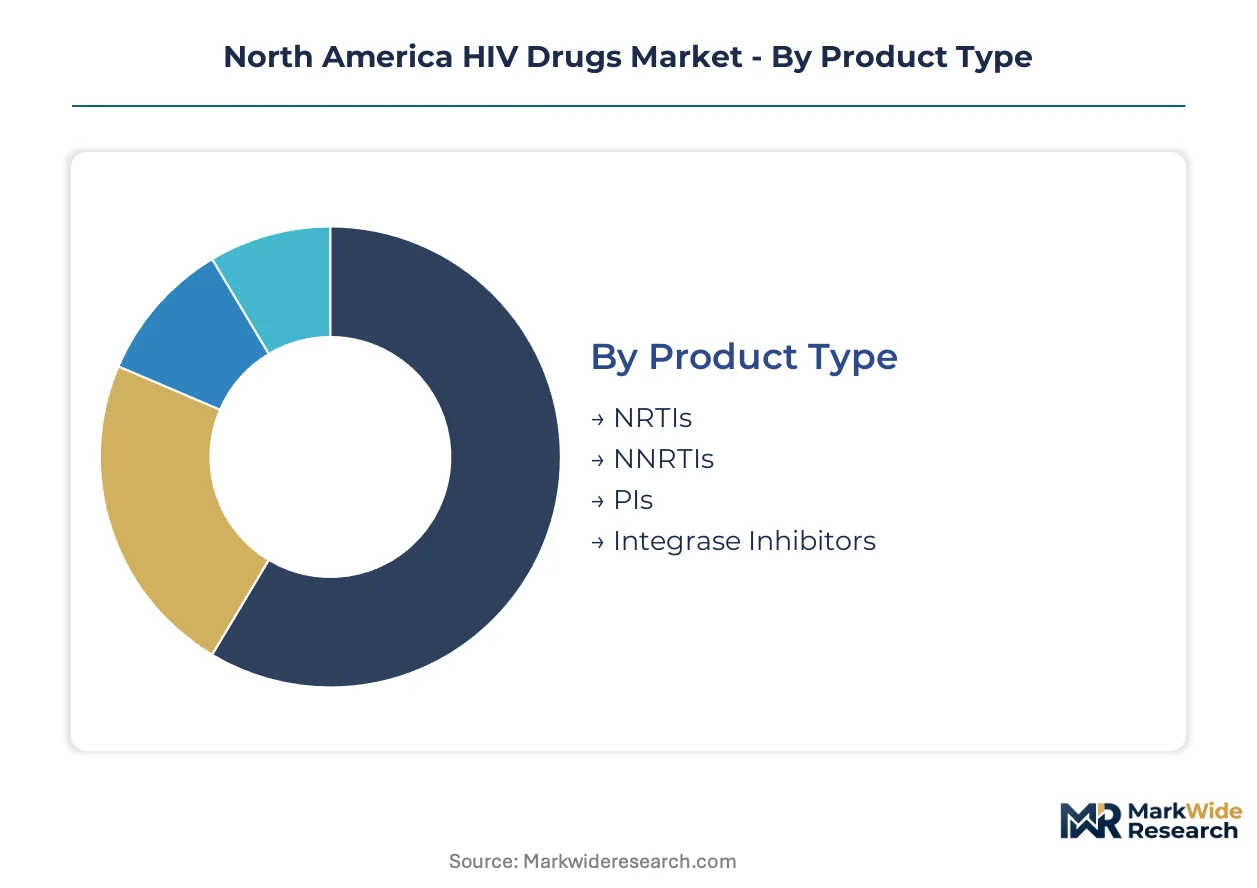
Segmentation reveals how regulatory pathways and reimbursement mechanics are concentrating procurement authority across distinct channels and formulations. Understanding these divides clarifies where formulary negotiations, cold-chain investments, and adherence programs deliver differential returns.
Product Type:
FDA approval standards and Health Canada review timelines create divergent commercial trajectories across mechanistic classes, with resistance profiles and tolerability thresholds determining payer tier placement.
- Integrase Inhibitors:These agents block viral DNA integration into host genomes through strand transfer inhibition, achieving rapid viral suppression with minimal metabolic side effects. Demand concentrates in Ryan White Program-funded clinics across California, Florida, and New York, driven by superior resistance barriers and streamlined prior authorization pathways.
- NRTIs:Nucleoside reverse transcriptase inhibitors function as chain terminators during viral RNA-to-DNA conversion, typically deployed as backbone components in combination regimens. Procurement volumes cluster at federally qualified health centers where the IRA's Medicare price negotiation provisions have compressed patient out-of-pocket obligations for these legacy molecules.
- NNRTIs:Non-nucleoside reverse transcriptase inhibitors bind allosterically to the viral enzyme, offering oral bioavailability advantages in resource-constrained settings.
- PIs:Protease inhibitors cleave viral polyproteins through active-site competition, requiring pharmacokinetic boosting that complicates metabolic monitoring.
Integrase Inhibitors handle the majority of throughput; Long-Acting formulations within this class are gaining share fastest.
Therapy Area:
Application scope determines site-of-care requirements and prescriber specialty, with prevention protocols demanding different distribution infrastructure than treatment maintenance.
- Antiretroviral Therapy:Chronic suppression regimens for HIV-positive patients require lifelong adherence support and resistance monitoring. Dispensing authority is migrating toward specialty pharmacy networks in Texas, Illinois, and Pennsylvania, propelled by white-bagging arrangements with Medicaid managed care plans.
- Pre-Exposure Prophylaxis:Preventive protocols for HIV-negative high-risk populations emphasize event-driven or continuous dosing strategies. Injectable cabotegravir is penetrating commercial payer formularies in urban corridors with elevated incidence rates, supported by telehealth-integrated dispensing models.
- Post-Exposure Prophylaxis:Emergency 28-day regimens initiated within 72 hours of potential exposure rely on emergency department and urgent care access.
- Combination Therapy:Fixed-dose single-tablet regimens simplify adherence but require complex API synthesis and bioequivalence demonstration.
Antiretroviral Therapy commands the dominant patient volume; Pre-Exposure Prophylaxis is climbing the fastest on enrollment expansion.
Care Setting:
Channel economics and 340B eligibility criteria are redistributing dispensing volume away from hospital systems toward outpatient-focused alternatives.
- Specialty Pharmacies:These entities combine clinical counseling with automated adherence monitoring, capturing scripts previously filled through hospital outpatient departments. Concentration is highest in states where Medicaid managed care penetration exceeds national benchmarks, with PBM-owned networks leveraging preferred status to justify clinical service investments.
- Outpatient Clinics:Federally qualified health centers and Ryan White-funded sites integrate medical and pharmacy services for underserved populations. Volume is concentrating in urban corridors across the Southeast and Southwest, where retention-in-care gaps have driven adoption of long-acting injectable modalities.
- Hospitals:Inpatient and outpatient departments retain acute initiation and resistance-testing functions but cede maintenance dispensing.
- Home Care:Infusion and nursing services support patients with complex comorbidities or mobility limitations.
Specialty Pharmacies handle the majority of throughput; Outpatient Clinics are expanding most quickly on 340B program participation.
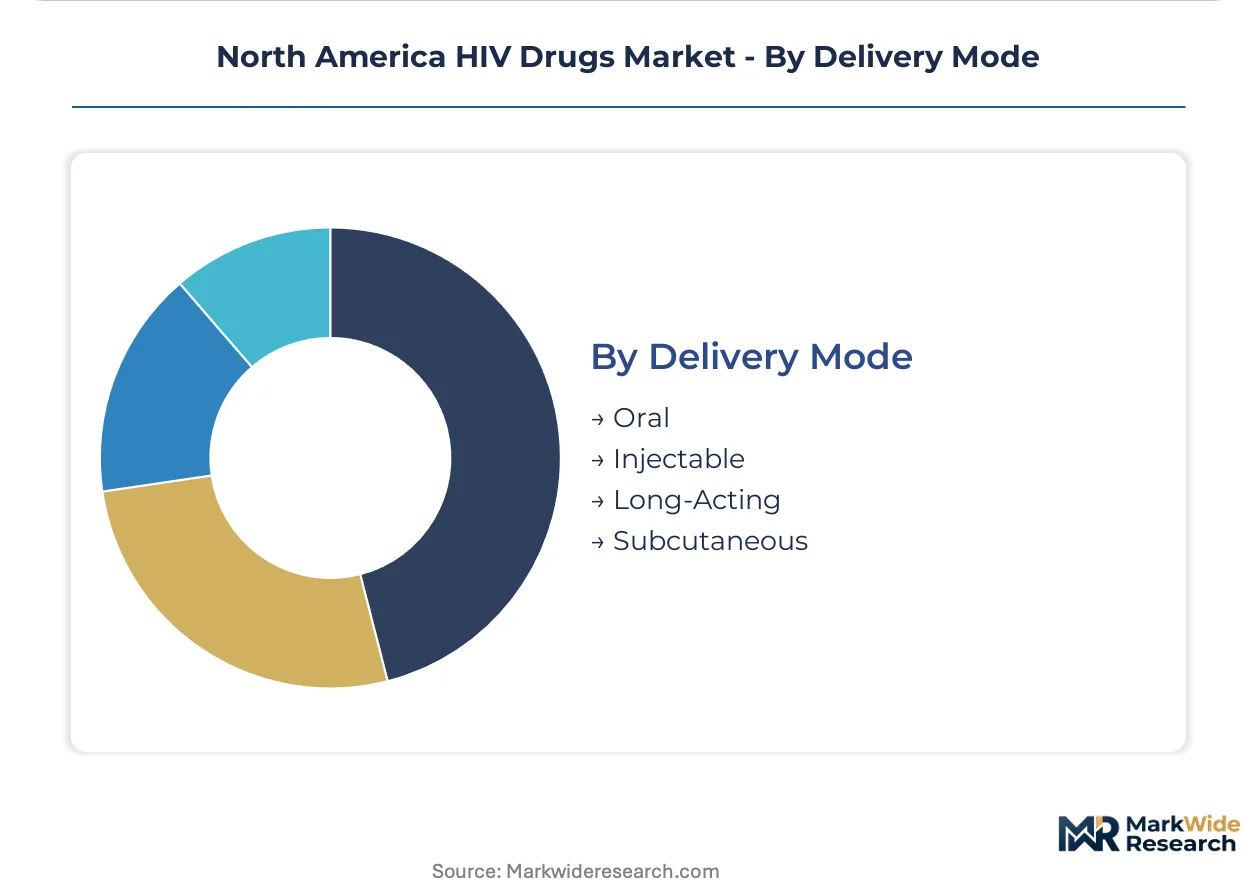
Delivery Mode:
Administration frequency has become the primary competitive variable, with formulation science enabling month-scale dosing intervals that reshape patient retention economics.
- Long-Acting:Injectable nanosuspensions achieve therapeutic drug concentrations for one to two months per administration through controlled-release matrix technology. Uptake is accelerating in adherence-challenged populations across the Midwest and Mountain West, where visit frequency reduction directly improves retention metrics.
- Injectable:Short-acting parenteral formulations serve acute initiation, treatment interruption recovery, and resistance-testing intervals.
- Oral:Daily combination tablets remain the default for treatment-naive patients and those preferring self-administration.
- Subcutaneous:Depot administration via abdominal or thigh injection sites enables patient self-management after clinical training.
Oral formulations handle the majority of throughput; Long-Acting delivery is gaining share fastest on persistence improvements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federally qualified health centers and Ryan White Program-funded clinics concentrate procurement authority across the United States, while Health Canada coordinates provincial formulary negotiations. Mexico's public health system expands access through Seguro Popular enrollment.
United States
Ryan White Program grants channel antiretroviral procurement toward integrated care clinics in California, Florida, and New York. The IRA's Medicare drug price negotiation provisions compress patient out-of-pocket obligations at federally qualified health centers. Specialty pharmacy networks in Texas and Illinois capture dispensing volume through white-bagging arrangements with Medicaid managed care plans.
Canada
Provincial formularies in Ontario and Quebec negotiate joint procurement through the pan-Canadian Pharmaceutical Alliance. Health Canada harmonizes review timelines with FDA determinations for novel integrase inhibitors. Cold chain infrastructure gaps constrain long-acting injectable distribution into rural territories and remote tribal health facilities.
Mexico
Seguro Popular enrollment expansion drives antiretroviral demand through Instituto Mexicano del Seguro Social clinics. The national pharmaceutical regulator oversees bioequivalence requirements for generic fixed-dose combinations. Mexico City anchors concentration of infectious disease specialists and reference laboratory capacity.
North America HIV Drugs Market Key Industry Players
Player mix skews toward vertically integrated pharmaceutical conglomerates with antiretroviral portfolios spanning oral and injectable modalities. The competitive structure concentrates around three archetypes: large-cap innovators with long-acting formulation pipelines, mid-tier generics manufacturers supplying fixed-dose combinations, and specialty-focused biotechs targeting adherence-challenged populations. Dominant competitive moves include strategic partnerships for nanosuspension delivery technology and geographic expansion of specialty pharmacy networks.
Within the large-cap innovator tier, Gilead Sciences and ViiV Healthcare exemplify portfolio breadth across daily oral maintenance and long-acting injectable regimens. Gilead Sciences occupies a position as a California-based integrated pharmaceutical developer, while ViiV Healthcare represents the concentrated R&D investment archetype in cabotegravir-based formulations. Merck & Co. anchors the mid-tier position with established reverse transcriptase inhibitor offerings.
| Leading Market Players |
|---|
| Gilead Sciences |
| ViiV Healthcare |
| Merck & Co. |
| Bristol-Myers Squibb Company |
| AbbVie |
| Janssen Pharmaceuticals |
| GlaxoSmithKline |
| Boehringer Ingelheim International GmbH |
| Theratechnologies |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between Ryan White Program-funded clinics and specialty pharmacy distributors lock in both antiretroviral supply access and price visibility across the United States. These contracts insulate federally qualified health centers from API cost volatility while compressing margins for intermediaries unable to secure preferred formulary tier placement.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate procurement for integrase strand transfer inhibitors. Three-tier pricing structure across innovator, authorized generic, and compulsory license tiers separates Gilead Sciences portfolio products from ViiV Healthcare cabotegravir formulations from Indian-sourced fixed-dose combinations. Price differentiation hinges on FDA approval tier and cold-chain certification level. Cost compression in the authorized generic tier is intensifying because the IRA's Medicare price negotiation provisions have reset reimbursement benchmarks for legacy oral therapies. Federally qualified health centers exhibit highest price sensitivity due to 340B margin dependency, while commercial payers demonstrate lowest sensitivity for long-acting injectable prior authorizations.
Supply Chain Analysis
Strategic stockpiling of cold-chain validated inventory buffers against distribution interruption for long-acting nanosuspensions, contrasting with just-in-time oral tablet replenishment preferred by high-volume specialty pharmacies. API synthesis concentrates in India and China for reverse transcriptase inhibitors, with Italy and Switzerland anchoring high-potency integrase inhibitor production. Raw material dependencies span acyclic nucleoside phosphonates, pyrimidine derivatives, and magnesium stearate excipients. Single-source vulnerability from Chinese contract manufacturers for cabotegravir intermediates exposes supply continuity to geopolitical friction. Distribution runs through PBM-owned specialty pharmacy networks with white-bagging arrangements displacing hospital outpatient department dispensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adherence support services and telehealth-integrated dispensing layers are expanding faster than antiretroviral molecule procurement across the North America HIV drugs landscape. Service-attach revenue now determines profitability for specialty pharmacy networks competing on patient retention metrics rather than script volume alone.
For Market Incumbents: Fortify formulary dominance through backward integration into long-acting nanosuspension manufacturing capacity in North Carolina and New Jersey. Expand 340B program participation across Ryan White-funded clinics in Texas and Florida to capture margin spread between discounted acquisition and reimbursement rates. Threat from ViiV Healthcare concentrated R&D investment in cabotegravir-based regimens demands accelerated Gilead Sciences pipeline diversification into bimonthly injectable modalities. For New Entrants and Emerging Players: Lead with telehealth-integrated dispensing models targeting rural Appalachian and Southwestern patient populations underserved by existing specialty pharmacy networks. White-space concentration exists in PrEP protocol adherence support for Medicaid managed care enrollees in Georgia and Arizona. Go-to-market angle should emphasize automated persistence monitoring paired with mail-order fulfillment to justify preferred network status with regional PBMs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty pharmacy networks with integrated clinical counseling capabilities and multi-year payer contracts. Long-term viability over the five-to-ten year horizon favors vertically integrated platforms spanning molecule development through patient adherence services. Acquisition target archetype: mid-cap specialty pharmacies with 340B eligibility and established Ryan White Program relationships. Signal to watch as inflection indicator: FDA approval velocity for quarterly versus bimonthly long-acting formulations shifting competitive persistence economics.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Formulation Pipeline Advancement | ViiV Healthcare cabotegravir investments compress patient visit frequency and improve retention metrics. |
| Specialty Pharmacy Network Expansion | PBM-owned platforms in California and New York displace hospital outpatient dispensing through white-bagging arrangements. |
| 340B Program Participation Deepening | Federally qualified health centers in Texas capture margin spread to fund adherence support infrastructure. |
| Telehealth-Integrated Dispensing Launch | Virtual clinical consultations paired with mail-order fulfillment penetrate rural patient populations previously lost to care. |
| PrEP Protocol Formulary Inclusion | Injectable cabotegravir for HIV prevention opens demand beyond treatment-only indications among commercial payers. |
Research Approach
A spread of perspectives from formulary directors at Medicaid managed care plans, regulatory affairs leads at large-cap pharmaceutical developers, procurement managers at federally qualified health centers, and payer access specialists converged on the working assumptions underpinning this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA approval databases, Health Canada submission records, Ryan White Program funding disbursement reports, and CMS Medicare Part D claims data. Bottom-up patient volume estimates triangulated against top-down pharmaceutical manufacturer revenue disclosures.
Segmentation dimensions modeled span product type across integrase inhibitors, NRTIs, NNRTIs, and protease inhibitors; therapy area across antiretroviral treatment, PrEP, and post-exposure prophylaxis; care setting across specialty pharmacies, outpatient clinics, hospitals, and home care; and delivery mode across long-acting injectable, oral, and subcutaneous depot formulations. CAGRs were derived from patient enrollment trajectories, formulation adoption curves, and reimbursement rate projections across the analysis window. Industry-specific forecast inputs include prior authorization approval velocity by payer type and cold-chain distribution capacity expansion timelines.
Forecasts assume regulatory continuity in FDA accelerated approval pathways and Health Canada harmonized review timelines; material policy shifts would require re-modeling. Specific risk factors include IRA Medicare price negotiation expansion to novel therapies, geopolitical disruption of API supply from Indian and Chinese contract manufacturers, and cold-chain infrastructure failure in rural Canadian territories. Revision becomes warranted when long-acting injectable prior authorization denial rates cross twenty-percent thresholds in Medicaid managed care plans.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Triptorelin Market
Biopharmaceuticals
Middle East and Africa Plasma Fractionation Market
Biopharmaceuticals
Cephalosporin Market
Biopharmaceuticals
Europe Plasma Fractionation Market
Biopharmaceuticals
Recombinant Human Serum Albumin Market
Biopharmaceuticals
Interleukin 1 Beta (IL-1β) ELISA Kit Market
Biopharmaceuticals
Chronic Phase Markers Market
Biopharmaceuticals
Global Vaccine Conjugate Market
Biopharmaceuticals
North America Contraceptives Market
Biopharmaceuticals
Non-Receptor Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Echinocandins Market
Biopharmaceuticals
Beta Interferon Market
Biopharmaceuticals
Gosling Plague Vaccine Market
Biopharmaceuticals
Germany Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Biologics Market
Biopharmaceuticals
Oligonucleotide API Market