
 Inflammatory Bowel Disease Treatment Market | 2026-2036
Inflammatory Bowel Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Inflammatory Bowel Disease Treatment Market Analysis
Buyer concentration among hospital systems is decoupling from traditional specialty pharmacy distribution, forcing manufacturers to restructure account management and contracting protocols. AbbVie leverages its immunology infrastructure to sustain direct hospital partnerships. Takeda Pharmaceutical Company Limited anchors its position through integrated patient-support programs that bypass fragmented retail channels. Johnson & Johnson Services, Inc competes by controlling infusion-site networks and capturing site-of-care economics.
Inflammatory bowel disease treatment encompasses pharmacological interventions targeting chronic intestinal inflammation, including monoclonal antibodies engineered against TNF-alpha, interleukin-12/23, and integrin receptors, formulated for subcutaneous or intravenous delivery to induce and maintain mucosal healing. The biologics segment dominates value generation due to premium positioning and patent-protected moats, while the oral administration route captures volume leadership through aminosalicylate generics and emerging small-molecule JAK inhibitors. Injectable and intravenous channels concentrate margin pools where cold-chain logistics and infusion infrastructure create service-layer differentiation.
FDA, EMA, and WHO prequalification standards govern clinical trial endpoints, biosimilar interchangeability, and manufacturing consistency for biologic IBD therapies. These frameworks shape demand by determining which products gain formulary access and which face step-therapy restrictions. Stakeholders must monitor pipeline shifts toward oral biologics and non-steroidal mechanisms that could redraw therapeutic hierarchies without warning.
Market Dynamics
Hospital procurement consolidation is decoupling from specialty pharmacy networks, forcing manufacturers to rebuild account management around integrated delivery systems rather than fragmented retail channels. This structural shift compresses margin pools and redefines site-of-care economics across the therapeutic landscape.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses clinical-to-commercial timelines for biologics targeting refractory ulcerative colitis, enabling earlier formulary placement and reducing development risk exposure.
- Subcutaneous formulation expansion:Self-administered delivery formats reduce infusion center dependency and expand addressable patient populations beyond urban hospital catchments.
- Japan's reimbursement framework:Premium pricing for biologics with demonstrated mucosal healing endpoints sustains manufacturer investment in IBD-specific clinical programs.
Market Restraints
- Cold-chain logistics concentration:Biologic stability requirements limit distribution to certified third-party logistics providers, creating single-point vulnerability in temperature-controlled networks.
- Biosimilar interchangeability friction:EMA guidance on automatic substitution remains inconsistent across member states, delaying pharmacy-level adoption and perpetuating originator volume retention.
- Small-molecule JAK inhibitors:Oral alternatives with comparable efficacy endpoints threaten to compress biologic pricing power in moderate disease segments.
Strategic Opportunities
- Germany's DiGA pathway:Digital therapeutics for disease monitoring and medication adherence qualify for statutory reimbursement, opening parallel revenue streams beyond pharmaceutical products.
- Oral biologic convergence:Antibody fragment engineering and permeation enhancer co-formulation promise to bridge the efficacy-convenience gap that currently segments injectable and oral markets.
- Direct-to-patient pharmacy models:Specialty distributors bypass hospital markup structures and capture adherence data that supports outcome-based contracting with payers.
Industry Challenges
- Gastroenterology infusion nursing shortage:Biologic administration requires certified personnel that health systems struggle to retain against competing specialties, constraining site expansion.
- Legacy EHR integration:Patient support programs require real-time data exchange with hospital systems running disparate Epic, Cerner, and Meditech architectures, fragmenting care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inflammatory Bowel Disease Treatment Market |
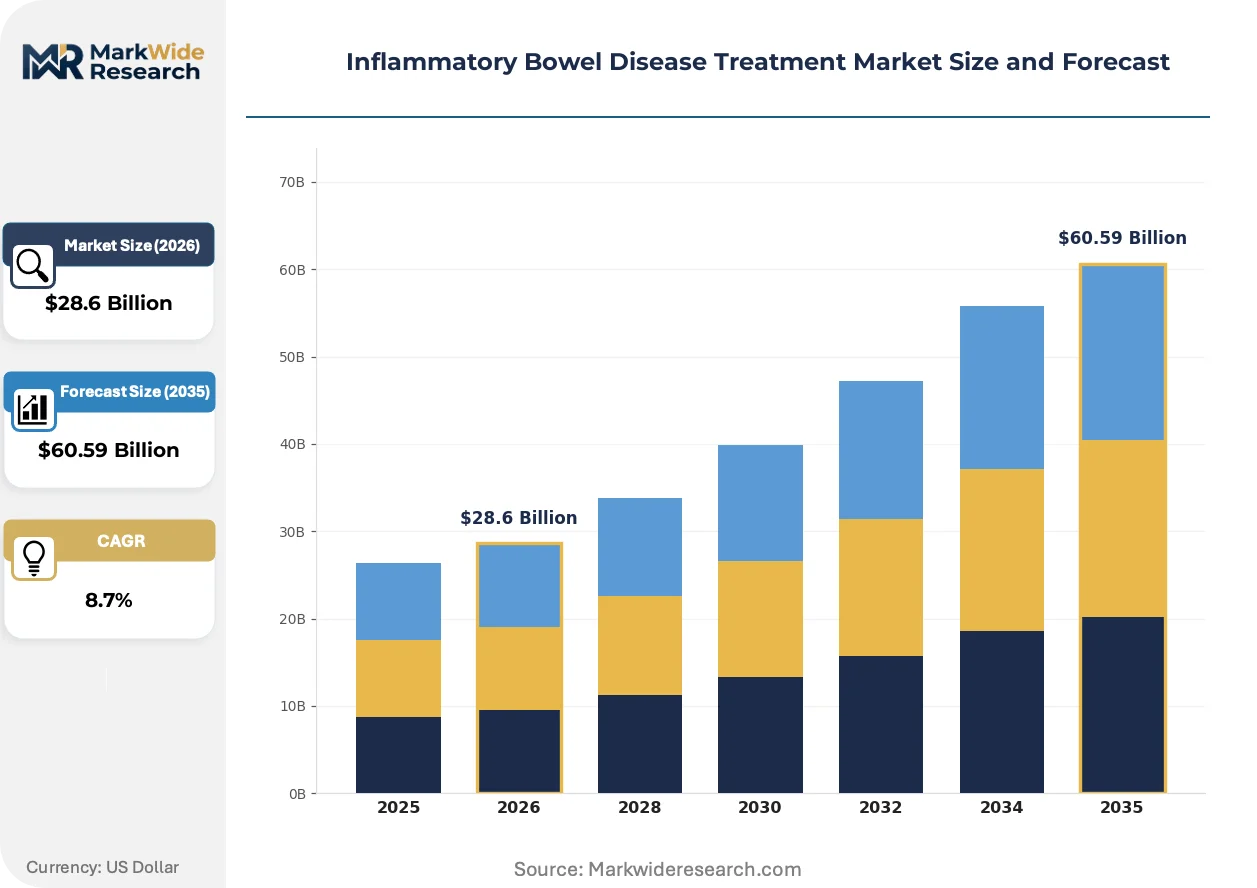
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Aminosalicylates, Corticosteroids, Immunomodulators Administration Route: Oral, Injectable, Intravenous, Topical End User: Hospitals, Outpatient Clinics, Homecare, Specialty Pharmacies Therapeutic Area: Ulcerative Colitis, Crohn's Disease, Indeterminate Colitis, Others |
| Companies Covered | AbbVie, Takeda Pharmaceutical Company Limited, Johnson & Johnson Services, Inc, Pfizer Inc., UCB S.A., Biogen, Novartis AG, Amgen Inc., Celltrion Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inflammatory Bowel Disease Treatment Market Emerging Trajectories
Biologic delivery formats and regulatory science are converging to redraw competitive boundaries, with mucosal healing endpoints replacing symptomatic response as the decisive clinical benchmark.
Antibody engineering platforms producing subcutaneous-compatible high-concentration formulations are rewriting site-of-care requirements for anti-integrin and anti-interleukin therapies. Community gastroenterology practices in the United States are adopting these formats faster than hospital-based infusion centers anticipated, compressing the infrastructure advantage that academic medical centers previously held. The shift enables geographic expansion into secondary markets without capital-intensive infusion suite construction.
EMA's revised biosimilar extrapolation guidelines now require indication-specific clinical data for IBD approvals rather than relying on mechanistic class assumptions. Manufacturers must run dedicated ulcerative colitis and Crohn's disease trials to secure full label claims, extending development timelines and raising capital requirements for follow-on entrants. European reference product sponsors are responding by tightening tender specifications and building real-world evidence registries that demonstrate switching risk.
Hospital system pharmacy and therapeutics committees are consolidating biologic purchasing through single-source agreements that bundle multiple immunology indications. Integrated delivery networks in the United States now negotiate enterprise-wide contracts spanning rheumatology, dermatology, and gastroenterology, replacing specialty-specific procurement. This concentration rewards manufacturers with broad immunology portfolios and disadvantages single-indication players dependent on fragmented account access.
Inflammatory Bowel Disease Treatment Market Segmentation
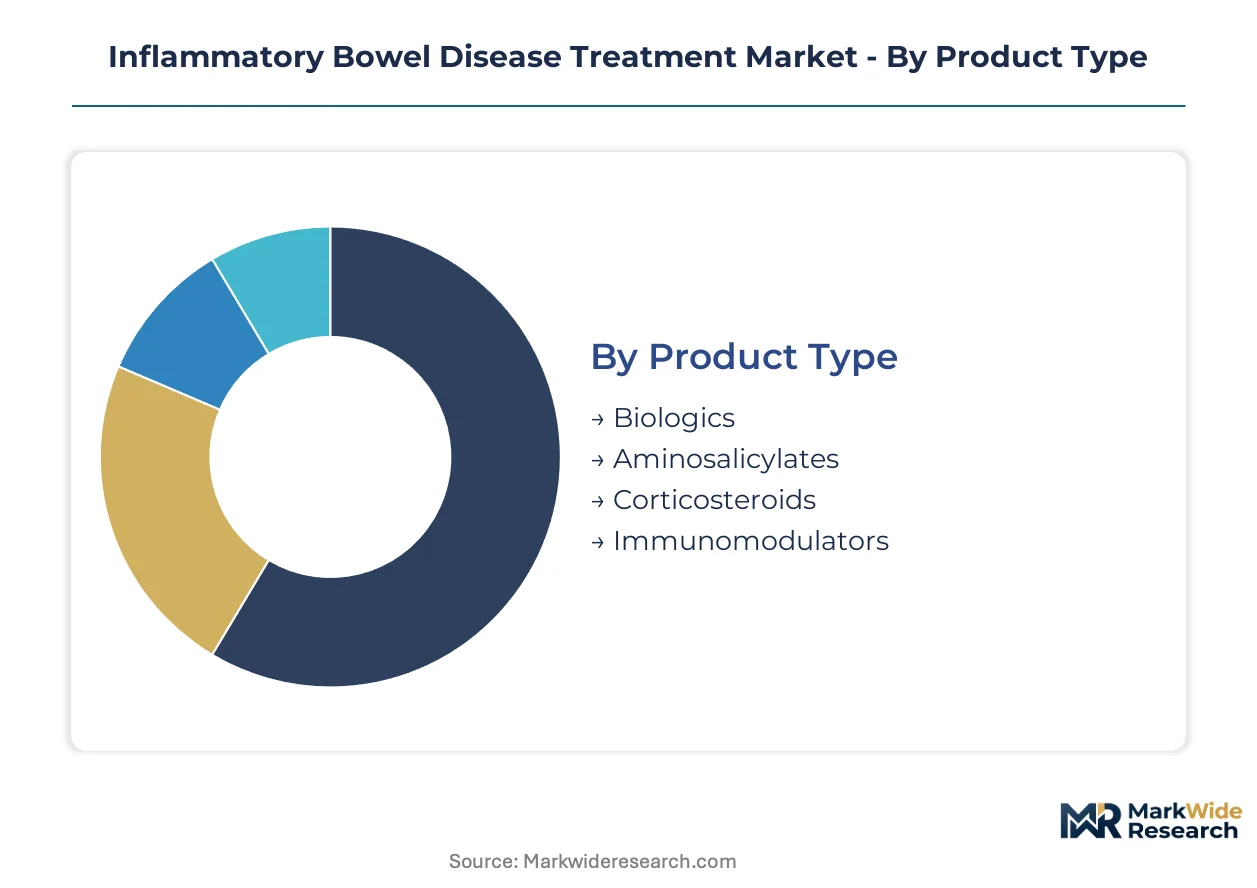
Therapeutic modality and delivery format choices determine reimbursement pathways, site-of-care economics, and competitive moat durability in IBD treatment. Segmentation clarity reveals where manufacturers must rebuild commercial infrastructure as procurement consolidates around integrated delivery systems.
Product Type:
Upgrade cycles from conventional immunosuppression to targeted biologics are shortening as mucosal healing endpoints displace symptomatic control in clinical protocols.
- Biologics:Engineered monoclonal antibodies and antibody fragments targeting TNF-alpha, interleukin-12/23, and integrin receptors command premium positioning through demonstrable mucosal healing outcomes. Demand concentrates in United States academic medical centers and German statutory health insurance formularies where step-therapy restrictions favor agents with sustained remission data.
- Aminosalicylates:Oral 5-ASA formulations remain first-line for mild-to-moderate ulcerative colitis with established safety profiles and generic availability constraining pricing power. Volume leadership sits with retail pharmacy dispensing in Japan and community gastroenterology practices across the United States.
- Corticosteroids:Systemic and topical glucocorticoids serve acute flare management with rapid symptom suppression but limited maintenance utility due to toxicity profiles.
- Immunomodulators:Thiopurines and methotrexate occupy bridging roles between conventional and biologic therapy with established immunogenicity monitoring requirements.
Volume placements concentrate in Aminosalicylates; the faster expansion belongs to Biologics.
Administration Route:
Cost tier stratification separates hospital-based infusion economics from self-administered subcutaneous alternatives that bypass facility fees.
- Injectable:Subcutaneous pen and syringe formats for anti-interleukin and anti-integrin therapies eliminate infusion center dependency and expand geographic reach. United States community gastroenterology practices are adopting these formats faster than hospital systems anticipated.
- Intravenous:Infusion-delivered anti-TNF agents retain indication breadth but concentrate margin capture in hospital-owned ambulatory infusion centers where site-of-care differentials apply.
- Oral:Small-molecule JAK inhibitors and conventional aminosalicylates offer patient convenience but face compressed reimbursement in moderate disease segments where biologics demonstrate superior mucosal healing.
- Topical:Rectal formulations target distal colitis with localized delivery minimizing systemic exposure.
Margin pools concentrate in Intravenous; the steepest expansion trajectory belongs to Injectable formats.
End User:
Customer type fragmentation is collapsing as hospital systems consolidate procurement authority across previously independent specialty pharmacy channels.
- Hospitals:Integrated delivery networks in the United States now negotiate enterprise-wide immunology contracts spanning rheumatology, dermatology, and gastroenterology. German hospital pharmacies leverage DiGA pathway integration for digital therapeutic bundling.
- Outpatient Clinics:Community gastroenterology practices in Japan and the United States are capitalizing on subcutaneous format availability to capture patients previously referred to hospital infusion centers.
- Homecare:Nurse-administered subcutaneous delivery models are emerging in markets with established specialty nursing infrastructure.
- Specialty Pharmacies:Fragmented retail channels face margin compression as direct-to-patient distribution models bypass traditional markup structures.
Procurement authority concentrates in Hospitals; the fastest share gain belongs to Outpatient Clinics.
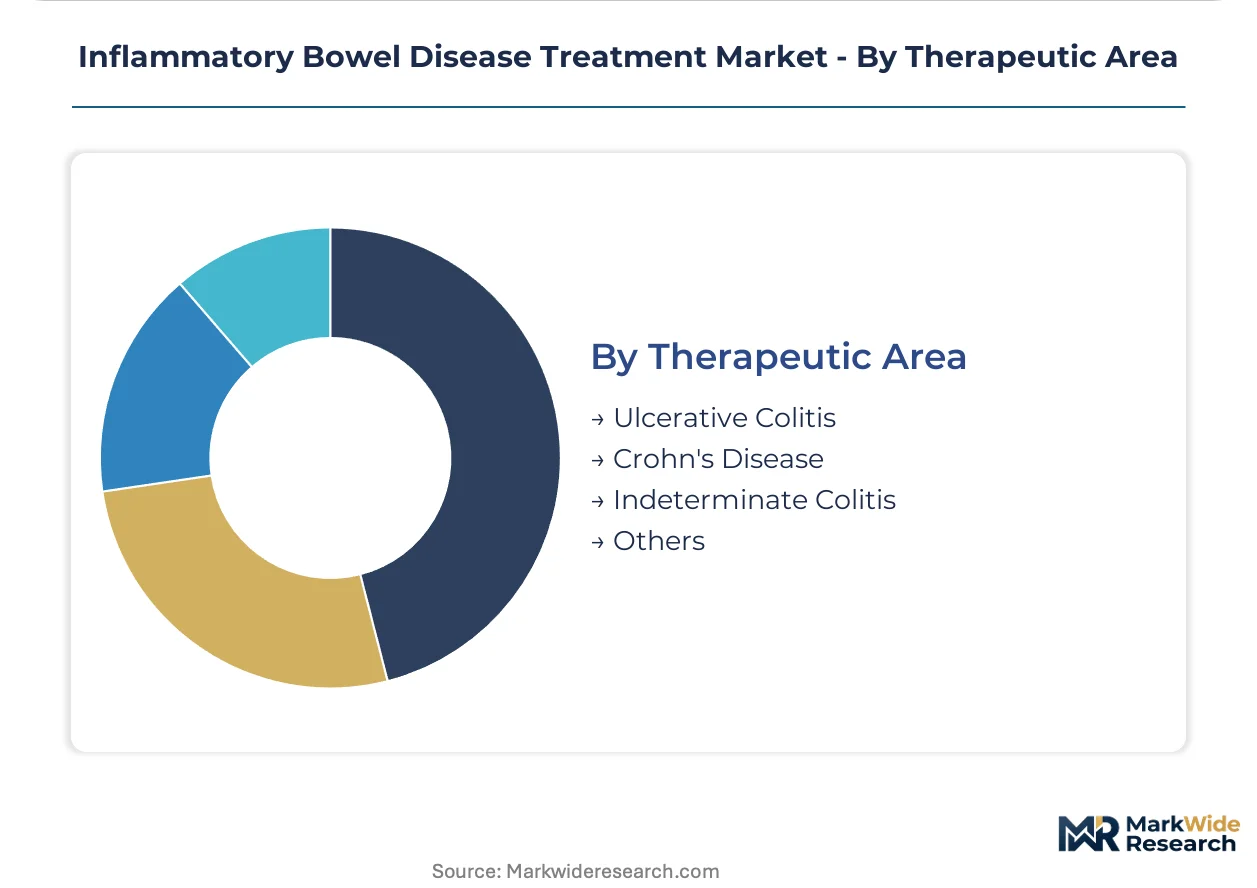
Therapeutic Area:
Application-specific clinical trial requirements under revised EMA guidance are extending development timelines and raising capital barriers for indication expansion.
- Ulcerative Colitis:Continuous mucosal inflammation limited to the colon enables more uniform treatment response assessment and faster regulatory pathways. Japanese reimbursement frameworks specifically reward demonstrated mucosal healing endpoints in this indication.
- Crohn's Disease:Transmural inflammation with skip lesions creates more heterogeneous treatment responses and complex surgical intervention patterns. Demand concentrates in United States tertiary referral centers with established intestinal ultrasound and capsule endoscopy capabilities.
- Indeterminate Colitis:Diagnostic uncertainty category captures patients with overlapping features pending definitive classification.
- Others:Microscopic colitis and unclassified inflammatory bowel conditions represent emerging research targets with limited approved therapeutic options.
Clinical trial investment concentrates in Ulcerative Colitis; the expanding addressable population belongs to Crohn's Disease.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for inflammatory bowel disease treatments concentrates in health systems with favorable reimbursement for biologic immunomodulators. The United States, Germany, and Japan anchor volume due to structured access pathways for advanced therapies. Each market presents distinct regulatory and procurement dynamics that shape manufacturer commercial strategies.
United States
Academic medical centers in Boston and the Research Triangle drive biologic adoption through integrated delivery network contracts. FDA accelerated approval pathways compress development timelines for ulcerative colitis therapies. Hospital procurement consolidation across the Midwest and Southeast is replacing fragmented specialty pharmacy distribution with enterprise-wide immunology agreements.
Germany
Statutory health insurance formularies prioritize agents with demonstrated mucosal healing endpoints in ulcerative colitis. EMA revised biosimilar extrapolation guidelines now require indication-specific clinical data, extending development timelines for follow-on entrants. The Rhine-Ruhr and Bavarian hospital clusters leverage DiGA pathway integration for digital therapeutic bundling with pharmaceutical products.
Japan
PMDA premium pricing frameworks specifically reward biologics achieving mucosal healing endpoints in clinical trials. Subcutaneous formulation adoption is expanding beyond Tokyo and Osaka into secondary markets without infusion infrastructure. The country's aging population and established gastroenterology specialist network sustain investment in IBD-specific clinical programs.
United Kingdom
NICE technology appraisals enforce step-therapy restrictions that favor originator biologics with sustained remission data. London and Manchester academic centers anchor clinical trial recruitment for novel anti-interleukin therapies. NHS England's specialized commissioning framework concentrates high-cost biologic prescribing in designated intestinal failure units.
Switzerland
Swissmedic approval standards align with EMA guidance while permitting earlier patient access through temporary authorization schemes. Basel and Zurich hospital pharmacies negotiate indication-bundled contracts spanning immunology portfolios. The country's reference pricing system for biologics creates downward pressure on originator premiums as biosimilar portfolios expand.
Inflammatory Bowel Disease Treatment Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue oral biologic and biosimilar specialization. The vendor base stratifies across three maturity tiers: diversified immunology incumbents with hospital system contracts, mid-scale biologic specialists with single-indication focus, and emerging biosimilar manufacturers leveraging regulatory science capabilities. Market structure rewards portfolio breadth over single-product concentration. Dominant competitive moves include indication-bundled procurement negotiations and subcutaneous formulation engineering to bypass infusion center dependency.
Within the diversified immunology tier, AbbVie and Takeda Pharmaceutical Company Limited exemplify archetypes of hospital-direct partnership models. Johnson & Johnson Services, Inc occupies a position emphasizing site-of-care network control. These three entities anchor competitive dynamics through distinct channel strategies rather than product-specific differentiation.
| Leading Market Players |
|---|
| AbbVie |
| Takeda Pharmaceutical Company Limited |
| Johnson & Johnson Services, Inc |
| Pfizer Inc. |
| UCB S.A. |
| Biogen |
| Novartis AG |
| Amgen Inc. |
| Celltrion Inc. |
| Others |
Supply Flow & Price Mechanics
Subcutaneous formulation engineering simultaneously compresses cold-chain distribution costs and redistributes margin capture toward outpatient channels, decoupling biologic pricing from hospital infusion economics. This shift enables manufacturers to bypass facility fee markups while forcing traditional intravenous suppliers to defend site-of-care premiums through nursing retention investments.
Pricing Analysis
Volume placements concentrate in oral aminosalicylates with thin margins; margin pools cluster in intravenous biologics commanding facility fee premiums. Three-tier pricing structure across originator biologics, biosimilars, and conventional immunomodulators reflects mucosal healing endpoint differentiation and patent exclusivity status. Cost compression in the biosimilar tier intensifies as EMA indication-specific requirements extend development timelines and concentrate supply among capitalized entrants. Community gastroenterology practices exhibit highest price sensitivity due to reimbursement rate compression, while academic medical centers prioritize clinical outcome data over acquisition cost.
Supply Chain Analysis
Cold-chain logistics costs anchor distribution economics for biologic stability requirements, limiting qualified third-party logistics providers to certified networks in the United States, Germany, and Switzerland. Manufacturing draws from mammalian cell culture platforms, single-use bioreactor systems, and permeation enhancer chemical inputs. Single-source vulnerability concentrates in temperature-controlled last-mile networks where certified infusion nursing availability constrains site expansion. Distribution runs through integrated delivery network pharmacies consolidating procurement across immunology indications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified infusion nursing scarcity props biologic pricing by constraining site-of-care expansion and preserving hospital markup structures. This bottleneck sustains originator premiums even as biosimilar portfolios mature.
For Market Incumbents:Anchored hospital-direct contracts through enterprise-wide immunology bundling defends against biosimilar tender erosion. Incumbents should deepen backward integration into subcutaneous formulation manufacturing to capture outpatient channel migration, while building real-world evidence registries that demonstrate switching risk to formulary committees facing automatic substitution pressure.
For New Entrants and Emerging Players:The mid-tier pricing gap between originator anti-integrin therapies and conventional immunomodulators offers white-space entry for oral biologic candidates with mucosal healing endpoints. Japan's secondary markets and United States community gastroenterology practices represent the most penetrable geographies due to subcutaneous format readiness. A direct-to-patient pharmacy model bypassing hospital markup structures provides the optimal go-to-market angle.
For Investors and Strategic Acquirers:Exit pathways concentrate in mid-scale biologic specialists with single-indication focus and regulatory science capabilities. Long-term viability hinges on pipeline optionality across ulcerative colitis and Crohn's disease rather than single-product concentration. The inflection signal to monitor is EMA biosimilar extrapolation guidance tightening, which extends development timelines and raises capital barriers for follow-on entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Engineering | Anti-integrin and anti-interleukin therapies bypass hospital infusion dependency, expanding geographic reach into secondary United States markets. |
| Real-World Evidence Registry Development | Originator sponsors demonstrate switching risk to European formulary committees under revised EMA extrapolation guidelines. |
| Enterprise Immunology Contracting | Integrated delivery networks bundle rheumatology, dermatology, and gastroenterology procurement, rewarding portfolio breadth. |
| DiGA Pathway Integration | German hospital pharmacies bundle digital therapeutics for disease monitoring with biologic prescriptions, opening parallel revenue streams. |
| Direct-to-Patient Pharmacy Models | Specialty distributors bypass hospital markup structures and capture adherence data supporting outcome-based payer contracting. |
Methodological Framework
Multi-period observation of formulary placement timelines, biosimilar tender outcomes, and subcutaneous adoption rates anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation cross-checked segment-level outputs.
Input-output matrices mapped biologic volume assumptions across administration route, therapeutic area, and regional regulatory cluster to generate value forecasts over the projection horizon. CAGRs were derived from indication-specific prevalence trajectories, treatment line escalation patterns, and biosimilar penetration curves. Modeled inputs included mucosal healing endpoint achievement rates and step-therapy restriction stringency by payer type.
Inputs from clinical trial disclosure databases and procurement contract registries were available through the study window; gaps in real-world switching data and long-term biosimilar immunogenicity tracking introduce uncertainty bands around persistence assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Gallstone Market
Gastroenterology
High Definition Ultrasound Gastroscope Market
Gastroenterology
Acute Pancreatitis Market
Gastroenterology
Gastrointestinal Drugs Market
Gastroenterology
Malignant Ascites Market
Gastroenterology
Necrotic Enteritis Treatment Market
Gastroenterology
Gastroesophageal Reflux Disease Therapeutics Market
Gastroenterology
Gastric Cancer Market
Gastroenterology
Fecal Incontinence Market
Gastroenterology
Global Gastrointestinal Bleeding Treatment Market
Gastroenterology
Zollinger Ellison Syndrome Treatment Market
Gastroenterology
Diverticular Disease Therapeutics Market
Gastroenterology
Intestinal Pseudo-Obstruction Treatment Market
Gastroenterology
Colon Hydrotherapy Market
Gastroenterology
Hirschsprung Disease Treatment Market
Gastroenterology
Intestinal Fistula Treatment Market