
 AL Amyloidosis Therapeutics Market | 2026-2036
AL Amyloidosis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
AL Amyloidosis Therapeutics Market Outlook
Aftermarket patient support and compliance monitoring is reconfiguring how manufacturers capture lifetime value per treated individual. Alnylam Pharmaceuticals anchors its position through RNA interference platform specialization in transthyretin and light chain amyloidosis. Janssen Pharmaceuticals leverages daratumumab's hematology franchise to extend into AL amyloidosis combinations. Bristol-Myers Squibb competes via its immunomodulatory portfolio depth across plasma cell disorders.
AL amyloidosis therapeutics comprise pharmacological interventions targeting clonal plasma cells and pathogenic light chain deposition, with daratumumab-based regimens demonstrating hematologic response rates exceeding standard chemotherapy in frontline settings. These therapies serve to halt organ dysfunction progression and prolong survival in patients with cardiac, renal, or hepatic involvement. The product type dimension shows daratumumab and bortezomib occupying dominant positions due to established efficacy data, while subcutaneous administration routes gain traction through reduced infusion center burden and patient preference. End user concentration tilts toward hospitals and specialty pharmacies where multidisciplinary amyloidosis programs manage complex comorbidities.
FDA orphan drug designations and EMA conditional marketing authorizations shape development incentives and post-approval evidence requirements for novel AL amyloidosis agents. ISO 14155 clinical investigation standards and ICH E6 Good Clinical Practice guidelines govern trial conduct across jurisdictions, influencing site selection and data package robustness. Stakeholders must monitor evolving biomarker-based response criteria and their integration into payer value frameworks to anticipate reimbursement dynamics.
Market Dynamics
FDA accelerated approval pathways for orphan indications are compressing clinical trial timelines and rewiring commercialization economics for AL amyloidosis developers. This regulatory velocity is pulling antibody-directed therapies into frontline treatment algorithms faster than historical plasma cell disorder benchmarks.
Growth Catalysts
- Medicare reimbursement frameworks:Specialized amyloidosis treatment centers in the United States secure favorable reimbursement for daratumumab-based regimens, expanding patient access beyond academic medical centers.
- EMA conditional marketing authorizations:European regulators grant early access to novel agents targeting transthyretin and light chain amyloidosis, reducing time-to-market for RNA interference platforms.
- Subcutaneous administration routes:Reduced infusion center burden and patient preference for home-based delivery are accelerating adoption of injectable formulations in hematology-oncology clinics.
Market Restraints
- Biomarker validation costs:ISO 14155 clinical investigation standards demand extensive cardiac and renal biomarker documentation, inflating per-patient trial expenditures.
- Plasma cell clonality heterogeneity:Variable light chain deposition patterns complicate standardized response criteria across cardiac, hepatic, and renal involvement subtypes.
- Specialized site concentration:Qualified amyloidosis treatment programs cluster in major metropolitan academic centers, limiting rural and community hospital participation.
Strategic Opportunities
- ICH E6 Good Clinical Practice harmonization:Unified trial conduct standards across FDA and EMA jurisdictions enable single-protocol global studies, reducing redundant site activation.
- Home infusion nursing networks:Channel innovation in subcutaneous administration is bypassing traditional hospital-based infusion centers for maintenance therapy delivery.
- Post-approval evidence frameworks:Regulators are accepting real-world cardiac biomarker data to supplement registrational trials, opening pathways for label expansion.
Industry Challenges
- Amyloidosis specialist workforce scarcity:Multidisciplinary program coordination demands cardiologists, nephrologists, and hematologists with rare disease expertise, creating recruitment bottlenecks.
- Legacy EHR integration:Specialized amyloidosis registries require custom data pipelines to capture organ-specific response metrics within hospital IT systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AL Amyloidosis Therapeutics Market |
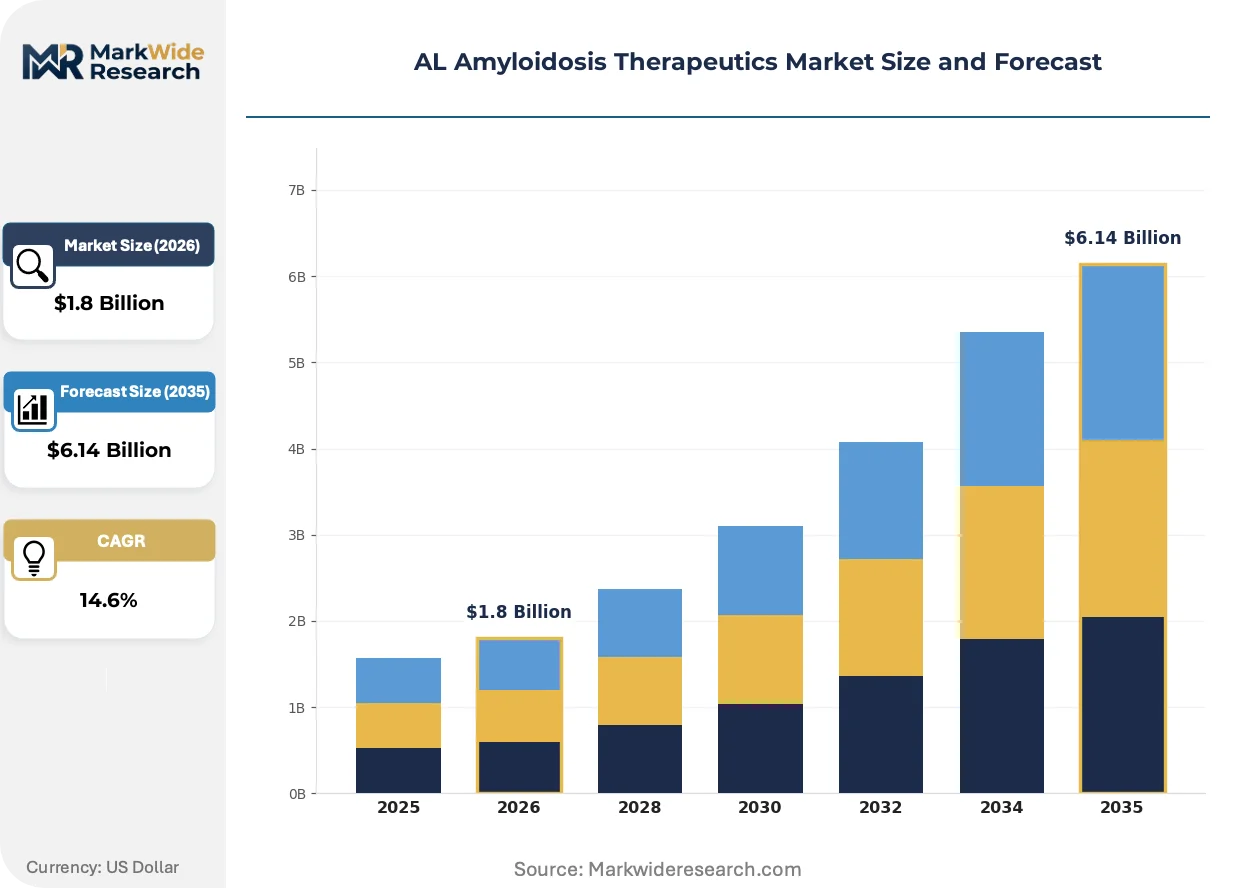
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Daratumumab, Pomalidomide, Bortezomib, Lenalidomide Administration Route: Intravenous, Subcutaneous, Oral, Injectable End User: Hospitals, Clinics, Homecare, Specialty Pharmacies Distribution Channel: Direct Sales, Retail Pharmacies, Wholesalers, Online Pharmacies |
| Companies Covered | Janssen Pharmaceuticals, Alnylam Pharmaceuticals, Bristol-Myers Squibb Company, Pfizer Inc., Johnson & Johnson Services, Inc., GSK plc, Takeda Pharmaceutical Company Limited, AstraZeneca, Prothena Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AL Amyloidosis Therapeutics Market Strategic Shifts
RNA interference platforms are penetrating AL amyloidosis treatment algorithms, compressing development timelines for agents targeting pathogenic light chain production. This technological shift is forcing established plasma cell disorder franchises to defend position through combination regimen innovation.
CRISPR-based gene editing for transthyretin amyloidosis is rendering obsolete lifelong chronic infusion models in hereditary disease subsets. Academic medical centers with advanced cell therapy infrastructure are piloting these curative-intent approaches in cardiac involvement patients. The structural consequence is a bifurcation between episodic intervention and sustained pharmacologic suppression business models.
EMA's orphan drug incentives are reshaping evidence generation requirements for AL amyloidosis agents, permitting smaller registrational cohorts with post-marketing cardiac outcome commitments. Manufacturers are responding by front-loading biomarker surrogate endpoints to secure conditional authorizations. Cardiac involvement subpopulations face the steepest evidentiary demands under this framework.
Hospital procurement committees are consolidating antibody-directed therapy purchasing through specialty pharmacy networks, disintermediating traditional wholesale distribution for high-cost oncology agents. Integrated delivery networks in the United States are extracting value-based rebates tied to hematologic response rates. This concentration is visible most acutely in Medicare Advantage–dominated regions where total cost of care contracts predominate.
AL Amyloidosis Therapeutics Market Segmentation
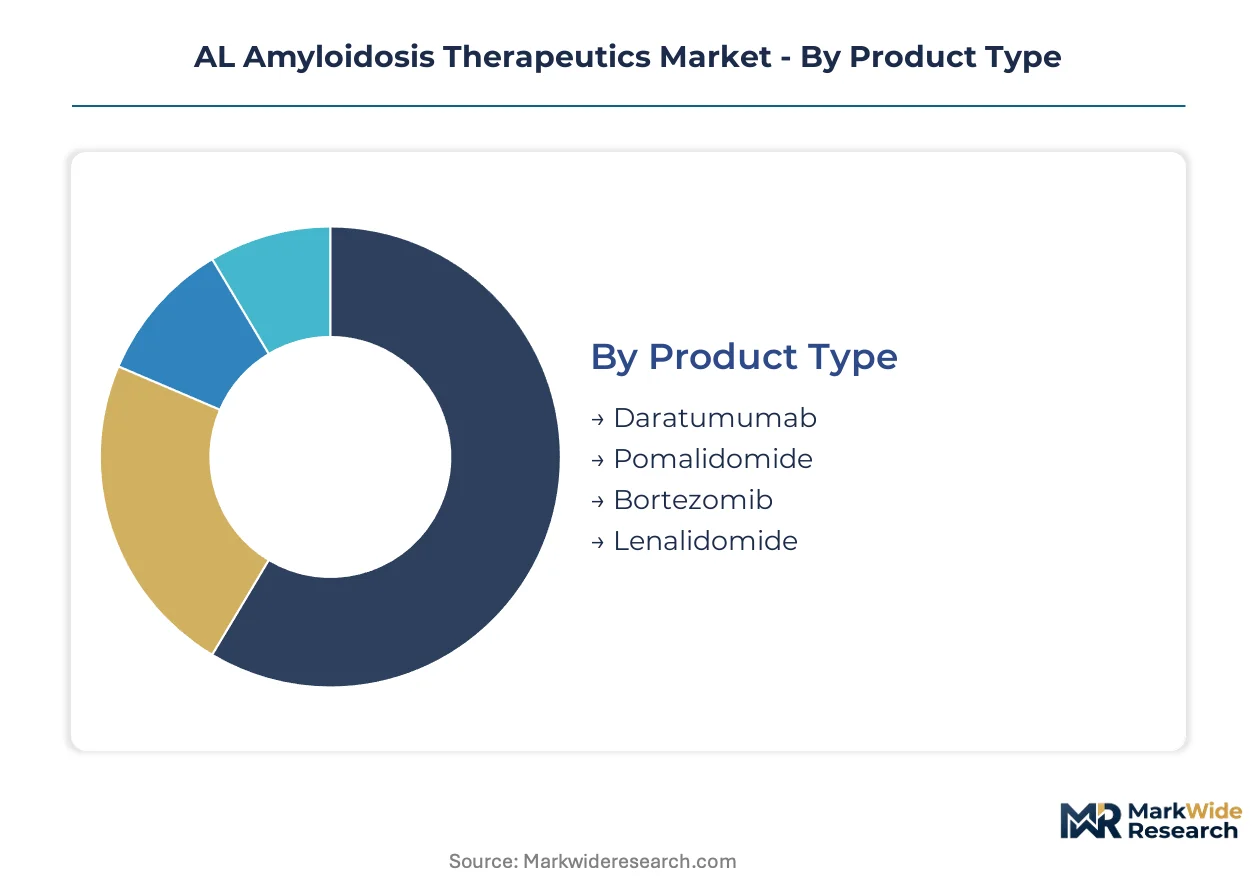
AL amyloidosis therapeutics demand stratifies across product mechanisms, delivery modes, and care settings. Each segmentation dimension carries distinct reimbursement, compliance, and patient journey implications that reshape manufacturer channel strategies.
Product Type:
After-sales-service intensity varies sharply across this category, with infusion-dependent therapies requiring nursing networks and biomarker monitoring infrastructure that oral agents bypass entirely.
- Daratumumab:Anti-CD38 monoclonal antibody administered via extended infusion protocols with mandatory pre-medication regimens. Demand concentrates in United States Medicare-reimbursed amyloidosis treatment centers where subcutaneous formulations reduce infusion center burden.
- Bortezomib:Proteasome inhibitor available in both intravenous and subcutaneous presentations with established cardiac response data in AL amyloidosis populations. United States hematology-oncology clinics favor this agent for frontline combinations given reimbursement familiarity and organ-specific response tracking.
- Pomalidomide:Immunomodulatory agent with oral administration advantage for relapsed/refractory settings.
- Lenalidomide:Thalidomide analogue deployed in maintenance protocols following stem cell transplantation.
By volume, bortezomib leads. By growth pace, daratumumab is ahead.
Administration Route:
Cost tier stratification separates hospital-based infusion models from home-delivered alternatives, with reimbursement differentials driving site-of-care migration.
- Subcutaneous:Reduced administration time and elimination of infusion center capacity constraints. United States specialty pharmacy networks capture this volume through home nursing arrangements that bypass hospital outpatient departments.
- Intravenous:Established route for proteasome inhibitors and monoclonal antibodies requiring controlled infusion environments. United States academic medical centers retain this volume for cardiac-monitored induction therapy.
- Oral:Immunomodulatory agents enable patient-managed dosing with pharmacy benefit manager reimbursement pathways.
- Injectable:Depot formulations and pre-filled syringes for maintenance protocols in ambulatory settings.
By volume, intravenous leads. By growth pace, subcutaneous is expanding most quickly.
End User:
Customer type concentration reflects disease complexity, with multidisciplinary coordination requirements filtering patients toward integrated programs.
- Hospitals:Academic medical centers with dedicated amyloidosis programs manage cardiac, renal, and hepatic involvement through coordinated specialist teams. United States hospital systems in Boston, New York, and Rochester anchor this segment.
- Specialty Pharmacies:Limited distribution networks handle high-cost antibody therapies with REMS compliance and patient assistance program administration. United States specialty pharmacy concentration in Philadelphia and Chicago metropolitan areas dominates daratumumab dispensing.
- Clinics:Community hematology-oncology practices with plasma cell disorder expertise.
- Homecare:Nursing-supported subcutaneous administration for maintenance therapy.
By volume, hospitals lead. By growth pace, specialty pharmacies are gaining share fastest.
Distribution Channel:
Supply concentration in specialty networks is displacing traditional wholesale models for high-value oncology agents.
- Direct Sales:Manufacturer-to-provider arrangements for daratumumab with integrated patient support services. United States integrated delivery networks in California and Texas extract value-based rebates through direct contracting.
- Wholesalers:Traditional distribution for oral agents and supportive care medications with inventory management services.
- Retail Pharmacies:Limited role given restricted distribution requirements for novel therapies.
- Online Pharmacies:Emerging channel for oral immunomodulatory agents with mail-order pharmacy benefit integration.
By volume, direct sales leads. By growth pace, online pharmacies show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
AL amyloidosis therapeutics consumption varies sharply by geography, with the United States deploying antibody-directed therapies in frontline settings while European markets emphasize conditional authorizations for novel platforms and Japan concentrates specialist expertise in academic medical centers.
United States
Medicare reimbursement frameworks and specialized amyloidosis treatment centers in Boston, New York, and Rochester drive patient access to daratumumab-based regimens. FDA accelerated approval pathways compress clinical trial timelines for orphan indications. Integrated delivery networks in California and Texas extract value-based rebates tied to hematologic response rates.
Germany
EMA conditional marketing authorizations enable early access to RNA interference platforms targeting transthyretin and light chain amyloidosis. The country's national pharmaceutical regulator accepts post-marketing cardiac biomarker data for label expansion. Heidelberg and Munich academic medical centers anchor multidisciplinary amyloidosis programs with coordinated cardiologist-nephrologist-hematologist teams.
United Kingdom
NHS specialized commissioning frameworks concentrate AL amyloidosis care in London, Cambridge, and Birmingham referral centers. NICE technology appraisals shape access to novel antibody therapies through incremental cost-effectiveness thresholds. The country's national pharmaceutical regulator aligns with EMA orphan drug incentives to accelerate rare disease agent availability.
Japan
PMDA sakigake designation system fast-tracks innovative therapies for diseases with high unmet need, including cardiac amyloidosis subtypes. Tokyo and Osaka university hospitals maintain national amyloidosis registries with custom data pipelines for organ-specific response metrics. METI biomedical innovation programs support domestic clinical trial infrastructure for plasma cell disorder franchises.
Switzerland
Swissmedic marketing authorizations for orphan indications leverage EMA assessments while maintaining independent pricing negotiations. Basel and Zurich pharmaceutical clusters host headquarters operations for major plasma cell disorder developers. The country's specialized hematology networks coordinate cross-border patient referral with neighboring EU member states.
AL Amyloidosis Therapeutics Market Competitive Environment
Capability concentration sits with RNA interference specialists and antibody engineering platforms; scale advantage sits with established hematology-oncology franchises with existing plasma cell disorder infrastructure. The market structure tiers into three archetypes: platform-technology developers with novel mechanism intellectual property, combination regimen innovators extending legacy franchise positions, and emerging gene therapy curative-intent programs. Dominant competitive moves include strategic partnerships for biomarker validation infrastructure and geographic expansion through specialty pharmacy network consolidation.
Within the platform-technology tier, Alnylam Pharmaceuticals and Prothena Corporation occupy positions exemplifying RNA interference and immunotherapy specialization respectively. Among established hematology franchises, Janssen Pharmaceuticals and Bristol-Myers Squibb represent archetypes of antibody-directed therapy extension from multiple myeloma into AL amyloidosis indications. Johnson & Johnson Services, Inc. anchors the diversified healthcare conglomerate position with cross-subsidized rare disease development capabilities. These three named entities collectively illustrate the competitive tension between novel mechanism validation and incumbent franchise defense.
| Leading Market Players |
|---|
| Janssen Pharmaceuticals |
| Alnylam Pharmaceuticals |
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| Johnson & Johnson Services, Inc. |
| GSK plc |
| Takeda Pharmaceutical Company Limited |
| AstraZeneca |
| Prothena Corporation |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on FDA-certified plasma cell disorder manufacturing facilities in the United States and Ireland determines both the premium-to-standard pricing spread across daratumumab-based regimens and the hub-and-spoke distribution architecture that feeds specialty pharmacy networks. This concentration amplifies reimbursement negotiation leverage for integrated delivery networks while constraining rural hospital access to value-based contracting tiers.
Pricing Analysis
Long-term offtake agreements between Janssen Pharmaceuticals and Medicare Advantage plans anchor daratumumab pricing, while spot purchasing for bortezomib induction cycles creates tiered spreads based on hematologic response guarantees and biomarker monitoring bundling. Price differentiation rests on cardiac involvement severity grading and subcutaneous formulation certification status, with cost compression in frontline combination therapy intensifying due to biosimilar proteasome inhibitor entry. Community hematology-oncology clinics exhibit highest price sensitivity; academic medical centers with amyloidosis specialist programs demonstrate lowest.
Supply Chain Analysis
Contract manufacturing concentration at Lonza and Catalent facilities in Switzerland and Singapore governs monoclonal antibody drug substance capacity for anti-CD38 therapies. Active pharmaceutical ingredient sourcing draws from Chinese and Indian chemical synthesis hubs, with fill-finish operations tethered to Pennsylvania and North Carolina sterile manufacturing sites. Single-source vulnerability in lipid nanoparticle formulation for RNA interference platforms threatens Alnylam's patisiran supply continuity. Distribution runs through limited specialty pharmacy networks with REMS compliance infrastructure rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multidisciplinary amyloidosis program coordination demands cardiologist-nephrologist-hematologist teams that fewer than forty United States medical centers currently field, creating a credentialing bottleneck that constrains market expansion regardless of therapeutic innovation pace.
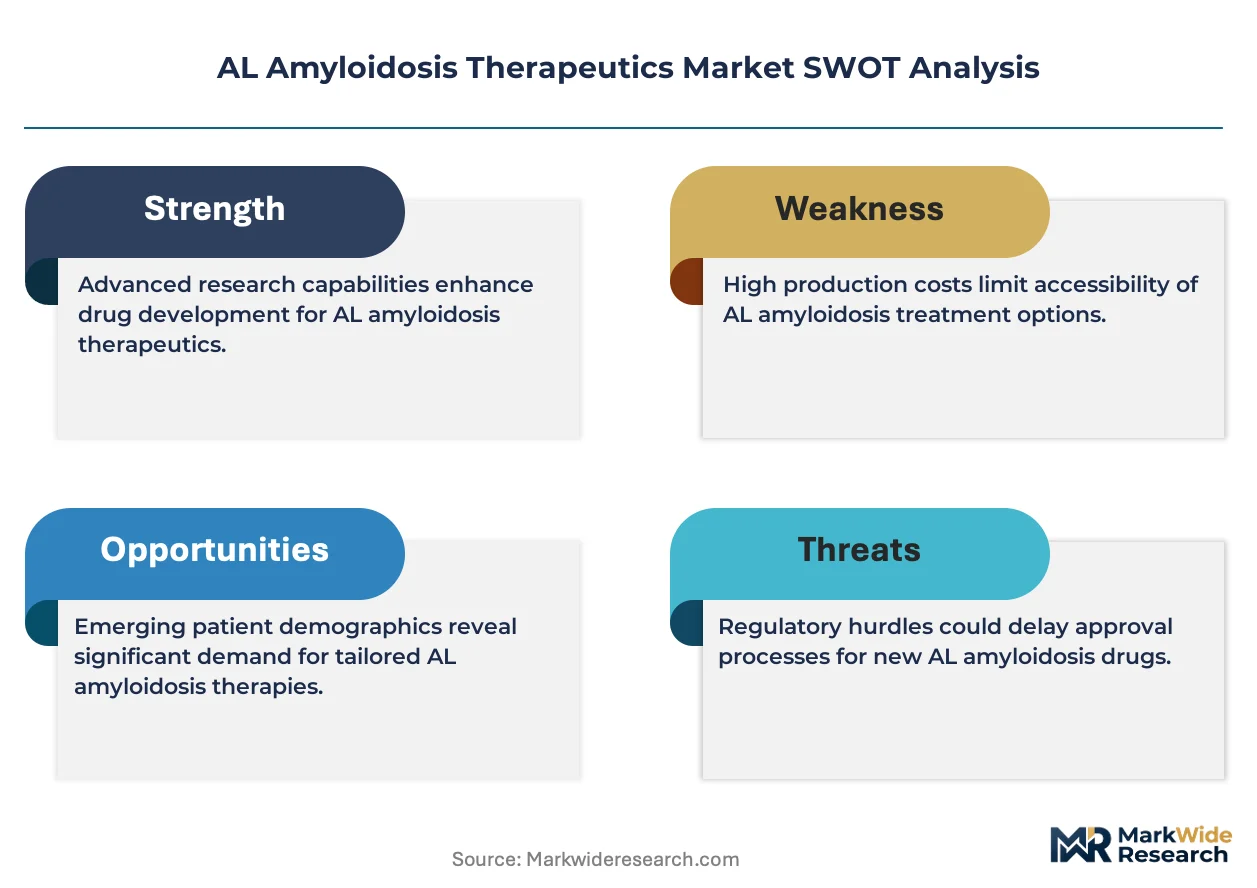
For Market Incumbents: Build biomarker validation infrastructure moats through exclusive partnerships with Mayo Clinic and Boston University amyloidosis registries to preempt RNA interference platform displacement. Secure backward integration into diagnostic assay manufacturing to capture organ-specific response tracking revenue streams. Defend against CRISPR gene therapy curative-intent programs by front-loading combination regimen cardiac outcome data. For New Entrants and Emerging Players: Establish a beachhead in home infusion nursing networks for subcutaneous maintenance therapy delivery, bypassing hospital outpatient department concentration. Target European markets with EMA conditional marketing authorization pathways that permit smaller registrational cohorts than FDA requirements. Pursue licensing agreements with established plasma cell disorder franchises for daratumumab combination rights rather than de novo development. For Investors and Strategic Acquirers: The market sits at a platform-transition phase that favors RNA interference specialists with validated delivery technology over legacy small-molecule incumbents. Long-term viability hinges on curative-intent pipeline optionality rather than chronic administration models. Monitor PMDA sakigake designations and FDA breakthrough therapy grants as inflection indicators for platform validation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker-Guided Trial Design | FDA acceptance of cardiac troponin and NT-proBNP surrogates compresses registrational timelines for novel agents. |
| Subcutaneous Formulation Development | Reduced infusion center burden shifts site-of-care economics toward specialty pharmacy networks. |
| Specialty Pharmacy Network Consolidation | Limited distribution with REMS compliance extracts value-based rebates from Medicare Advantage plans. |
| RNA Interference Platform Expansion | EMA conditional authorizations for transthyretin amyloidosis validate light chain-targeting mechanism extension. |
| Academic Medical Center Partnership | Mayo Clinic and Boston University registry access secures post-approval evidence generation infrastructure. |
Study Parameters
Cross-validation between formulary director interviews at United States integrated delivery networks and EMA conditional marketing authorization documentation anchors the qualitative findings. Primary fieldwork encompassed discussions with amyloidosis specialist hematologists, cardiac biomarker laboratory directors, specialty pharmacy reimbursement managers, and hospital procurement committee chairs. Secondary validation drew from FDA orphan drug designation filings, ClinicalTrials.gov protocol registries, Medicare Part B claims data, and ISO 14155 investigation standards. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation were reconciled across segmentation dimensions.
Calibration against historical daratumumab and bortezomib adoption curves in multiple myeloma informed the AL amyloidosis indication expansion trajectory across the analysis window. The analytical framework modeled treatment line positioning, administration route migration, patient population cardiac involvement severity, and regional regulatory cluster dynamics. CAGRs were derived from log-linear trend fitting to adjusted prevalence estimates and therapy penetration scenarios. Forecast inputs incorporated Medicare reimbursement rate revisions and EMA post-marketing commitment timelines.
Sensitivities concentrate around biomarker validation standardization and RNA interference manufacturing scale-up. Forecasts reflect assumptions regarding specialist workforce expansion and conditional authorization conversion rates. Quarterly review of FDA accelerated approval conversion status and cardiac outcome study readouts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Hemoglobin Analyzer Market
Hematology
Thrombocytopenia Treatment Market
Hematology
Graft Versus Host Disease (Gvhd) Treatment Market
Hematology
Allogeneic Stem Cell Therapy Market
Hematology
Global Non-Hodgkin Lymphoma Therapeutics Market
Hematology
Warm Autoimmune Hemolytic Anemia Market
Hematology
Idiopathic Thrombocytopenic Purpura Market
Hematology
Small Lymphocytic Lymphoma Market
Hematology
Follicular Lymphoma Treatment Market
Hematology
Febrile Neutropenia Market
Hematology
Chemotherapy-Induced Myelosuppression Treatment Market
Hematology
Acute Myeloid Leukemia Treatment Market
Hematology
Global Sickle Cell Disease Treatment Market
Hematology
Hematologic Malignancies Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Lymphopenia Therapeutics Market