
 Diverticular Disease Therapeutics Market | 2026-2036
Diverticular Disease Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Diverticular Disease Therapeutics Market Analytics
Project finance structures for specialty pharmaceutical manufacturing is reconfiguring competitive entry barriers across the diverticular disease landscape. AbbVie Inc. leverages its immunology infrastructure to sustain development pipelines targeting inflammatory complications of diverticulosis. Pfizer Inc. anchors its position through manufacturing scale in oral antibiotic production, while Novartis AG differentiates via geographic dominance in European hospital formulary placement.
Diverticular disease therapeutics encompass pharmacological and procedural interventions designed to manage inflammation, infection, bleeding, and obstruction arising from colonic diverticula, with antibiotic regimens typically spanning seven to ten days for uncomplicated acute diverticulitis. These treatments serve primary commercial purposes in reducing hospitalization duration, preventing perforation, and managing recurrent symptomatic episodes in outpatient and inpatient settings. The therapy area dimension shows acute diverticulitis commanding the largest patient volume pool, while probiotics represents the fastest-growing product type as gastroenterology practices integrate microbiome modulation into recurrence prevention protocols. Oral delivery mode retains dominant share in ambulatory settings, though intravenous administration captures higher per-treatment margins in emergency department-to-inpatient transitions.
The FDA's 505(b)(2) regulatory pathway shapes generic antibiotic entry timelines for diverticulitis therapies, while the EMA's centralized marketing authorization procedure governs pan-European access for novel anti-inflammatory formulations. The EU MDR elevates clinical evidence requirements for surgical intervention devices used in complicated cases, directly influencing product development budgets and commercialization timelines. Stakeholders must monitor evolving microbiome-targeted therapy classifications as regulators grapple with probiotic oversight frameworks that could either accelerate or constrain segment expansion.
Market Dynamics
The FDA's 505(b)(2) pathway accelerates generic antibiotic entry while hospital systems compress diverticulitis treatment into ambulatory protocols, fundamentally altering where and how therapeutic value is captured across the patient journey.
Growth Catalysts
- Ambulatory Protocol Expansion:Hospital systems in the United States are standardizing same-day discharge pathways for uncomplicated acute diverticulitis, expanding addressable prescription volumes into outpatient settings.
- Microbiome Modulation Integration:Gastroenterology practices are incorporating targeted probiotics into recurrence prevention protocols, creating new chronic therapy revenue streams beyond acute antibiotic courses.
- EMA Centralized Authorization:The European Medicines Agency's streamlined marketing authorization procedure accelerates pan-European formulary placement for novel anti-inflammatory formulations.
Market Restraints
- Generic Antibiotic Price Compression:The 505(b)(2) pathway enables rapid generic entry for fluoroquinolone and cephalosporin regimens, eroding branded pricing power in first-line therapy.
- European Device Evidence Burden:The EU MDR elevates clinical trial requirements for surgical intervention devices used in complicated diverticulitis, extending development timelines and capital lock-up periods.
- Diagnostic Substitution Risk:Advanced CT imaging protocols reduce unnecessary antibiotic prescriptions by distinguishing uncomplicated from complicated presentations at the point of emergency department admission.
Strategic Opportunities
- Probiotic Regulatory Clarity:Emerging FDA and EMA frameworks for live biotherapeutic product classification could unlock accelerated approval pathways for microbiome-targeted recurrence prevention therapies.
- Chronic Maintenance Positioning:Pharmaceutical developers can reposition select anti-inflammatory agents for long-term diverticulosis management, mirroring strategies deployed in inflammatory bowel disease maintenance therapy.
- Telehealth Integration:Virtual gastroenterology consults enable remote monitoring of post-acute patients, creating subscription-based adherence programs for chronic probiotic regimens.
Industry Challenges
- Microbiome Trial Design Complexity:Establishing clinically meaningful endpoints for probiotic efficacy in recurrence prevention requires novel biomarker validation and extended observation windows that strain study budgets.
- Hospital-Physician Alignment Friction:Divergent incentive structures between emergency department physicians favoring admission and gastroenterologists promoting outpatient management complicate protocol standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diverticular Disease Therapeutics Market |
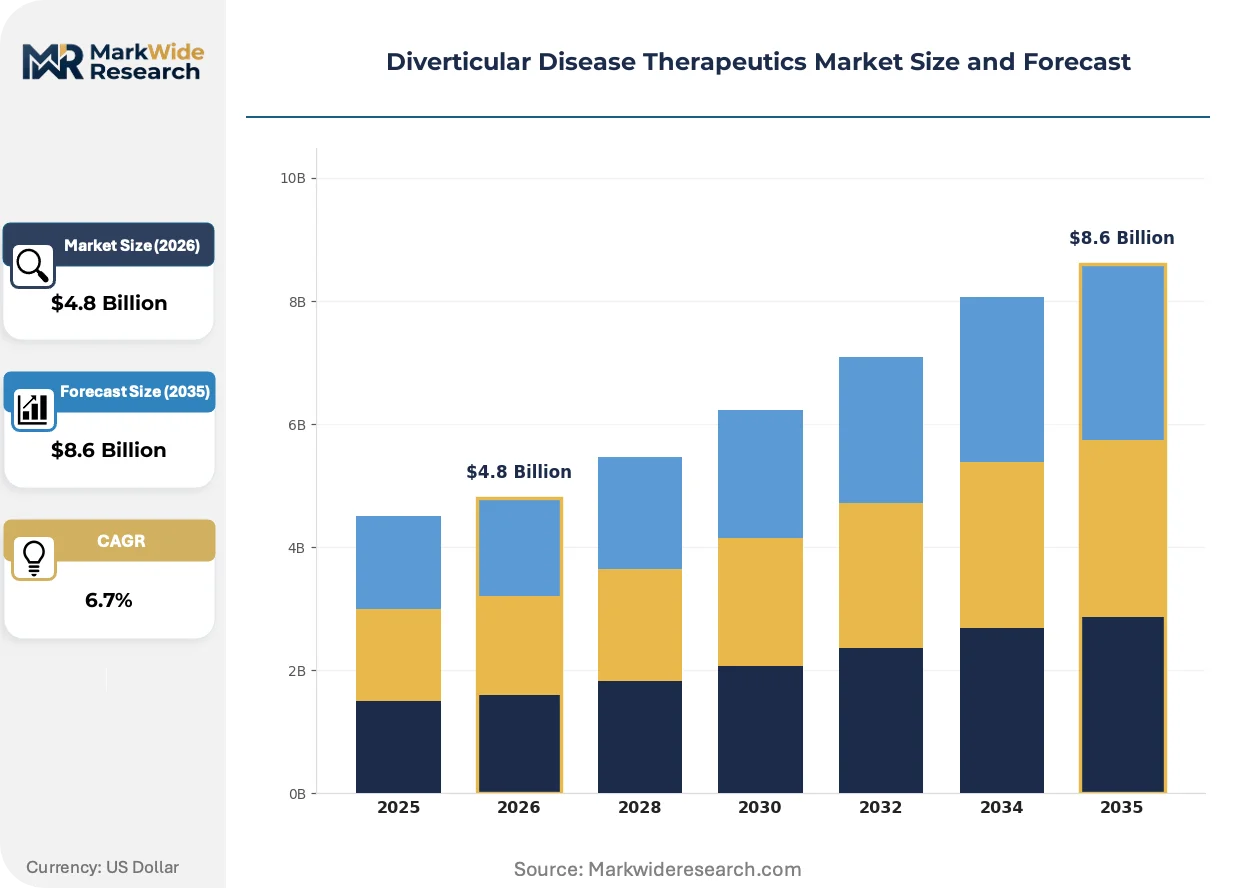
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Anti-Inflammatory Drugs, Probiotics, Surgical Interventions Therapy Area: Acute Diverticulitis, Chronic Diverticular Disease, Colonic Obstruction, Diverticular Bleeding End User: Hospitals, Clinics, Homecare Settings, Long-Term Care Facilities Delivery Mode: Oral, Intravenous, Rectal, Topical |
| Companies Covered | Pfizer Inc., Novartis AG, Johnson & Johnson, AbbVie Inc., Bayer AG, AstraZeneca plc, Abbott Laboratories, Teva Pharmaceutical Industries Ltd., GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diverticular Disease Therapeutics Market Evolving Landscape
Digital health infrastructure is digitizing patient monitoring and treatment adherence across the diverticular disease care continuum, compressing traditional site-of-care boundaries and enabling new data-driven intervention models.
Remote patient monitoring platforms using connected wearable devices are digitizing post-acute surveillance for diverticulitis patients, enabling early detection of recurrence signs. Gastroenterology practices in the United States are piloting these systems for high-risk patients with prior complicated presentations. This capability is digitizing the traditional emergency department gatekeeper role, allowing preemptive outpatient intervention before acute decompensation.
The FDA's evolving framework for live biotherapeutic products is reshaping development pathways for microbiome-targeted therapies, creating distinct regulatory tracks separate from traditional pharmaceuticals or dietary supplements. European developers are navigating parallel EMA qualification pathways for novel probiotic entities. Manufacturers with early engagement experience are securing competitive positioning in a category where regulatory precedent remains sparse.
Hospital-at-home programs are displacing traditional inpatient observation for select uncomplicated diverticulitis cases, altering antibiotic administration patterns and site-of-revenue capture. United States health systems with established hospital-at-home infrastructure are contracting directly with infusion services for IV-to-oral step-down therapy. This channel shift concentrates volume in integrated delivery networks with capital-intensive home-based care capabilities.
Diverticular Disease Therapeutics Market Segmentation
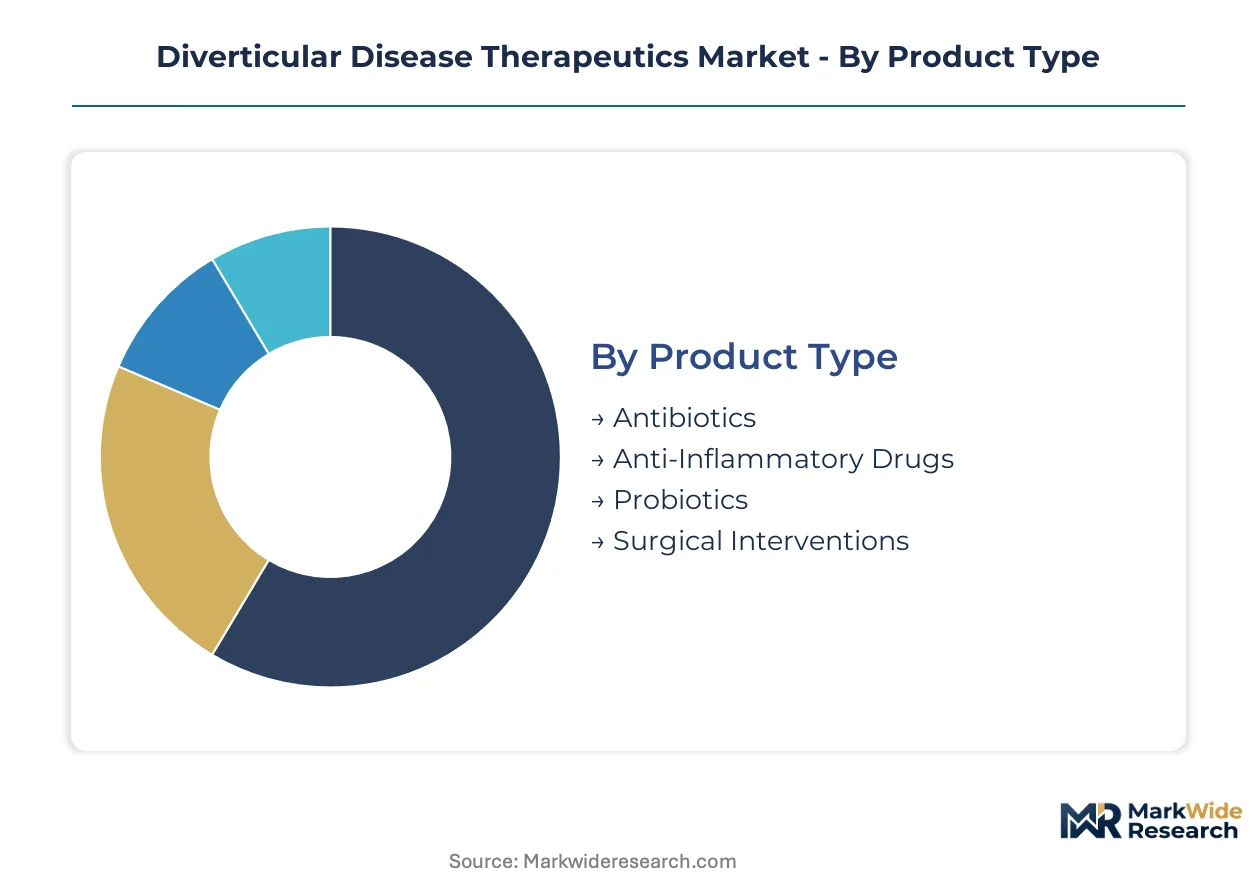
Segmentation in diverticular disease therapeutics reveals distinct commercial rhythms across acute intervention versus chronic management cycles. Prescription turnover velocity varies dramatically between emergency antibiotic courses and maintenance probiotic regimens, reshaping inventory and marketing investment priorities for manufacturers.
Product Type:
Antibiotic courses cycle through patients in seven-to-ten-day windows, while surgical interventions lock capital for months and probiotics sustain recurring revenue over years.
- Antibiotics:Fluoroquinolone and cephalosporin combinations dominate first-line empiric therapy for uncomplicated acute presentations. United States emergency departments generate the highest prescription velocity, though the FDA's 505(b)(2) pathway accelerates generic entry that compresses branded pricing.
- Probiotics:Live biotherapeutic formulations targeting microbiome modulation command premium positioning in recurrence prevention protocols. Gastroenterology practices in Germany and France are integrating these into chronic management pathways faster than other European markets.
- Anti-Inflammatory Drugs:Systemic corticosteroids and targeted immunomodulators address inflammatory complications in select complicated cases.
- Surgical Interventions:Resection procedures and laparoscopic interventions manage perforation, abscess, or refractory disease.
Antibiotics anchors the volume base while probiotics gains share at the steepest rate.
Therapy Area:
Cost tier stratification separates emergency interventions from elective chronic management, with reimbursement intensity tracking complication severity.
- Acute Diverticulitis:Uncomplicated presentations drive the largest addressable patient pool through outpatient antibiotic courses. United States hospital systems are compressing these into same-day discharge pathways that expand prescription capture outside traditional inpatient settings.
- Diverticular Bleeding:Interventional colonoscopy and transfusion-dependent cases generate the highest per-episode costs across the therapeutic spectrum. Japanese tertiary centers have developed specialized bleeding management protocols that reduce surgical conversion rates.
- Chronic Diverticular Disease:Recurrent symptomatic episodes without acute inflammation require maintenance-focused therapeutic approaches.
- Colonic Obstruction:Mechanical complications from diverticular strictures necessitate procedural intervention alongside pharmacological support.
Acute diverticulitis captures the highest prescription frequency while diverticular bleeding commands the premium reimbursement tier.
End User:
Site-of-care migration is concentrating volume in settings with integrated infusion and remote monitoring capabilities.
- Hospitals:Inpatient units manage complicated presentations requiring IV antibiotic initiation and surgical backup. United States health systems with established hospital-at-home infrastructure are contracting directly with infusion services for step-down therapy.
- Homecare Settings:IV-to-oral transition and chronic probiotic adherence programs are shifting revenue capture outside traditional facilities. Medicare reimbursement changes in the United States are accelerating this channel expansion.
- Clinics:Outpatient gastroenterology practices handle uncomplicated diagnosis and maintenance therapy initiation.
- Long-Term Care Facilities:Elderly populations with recurrent disease receive chronic management in residential settings.
Hospitals retain the highest acute intervention margin while homecare settings expand most quickly as a revenue channel.
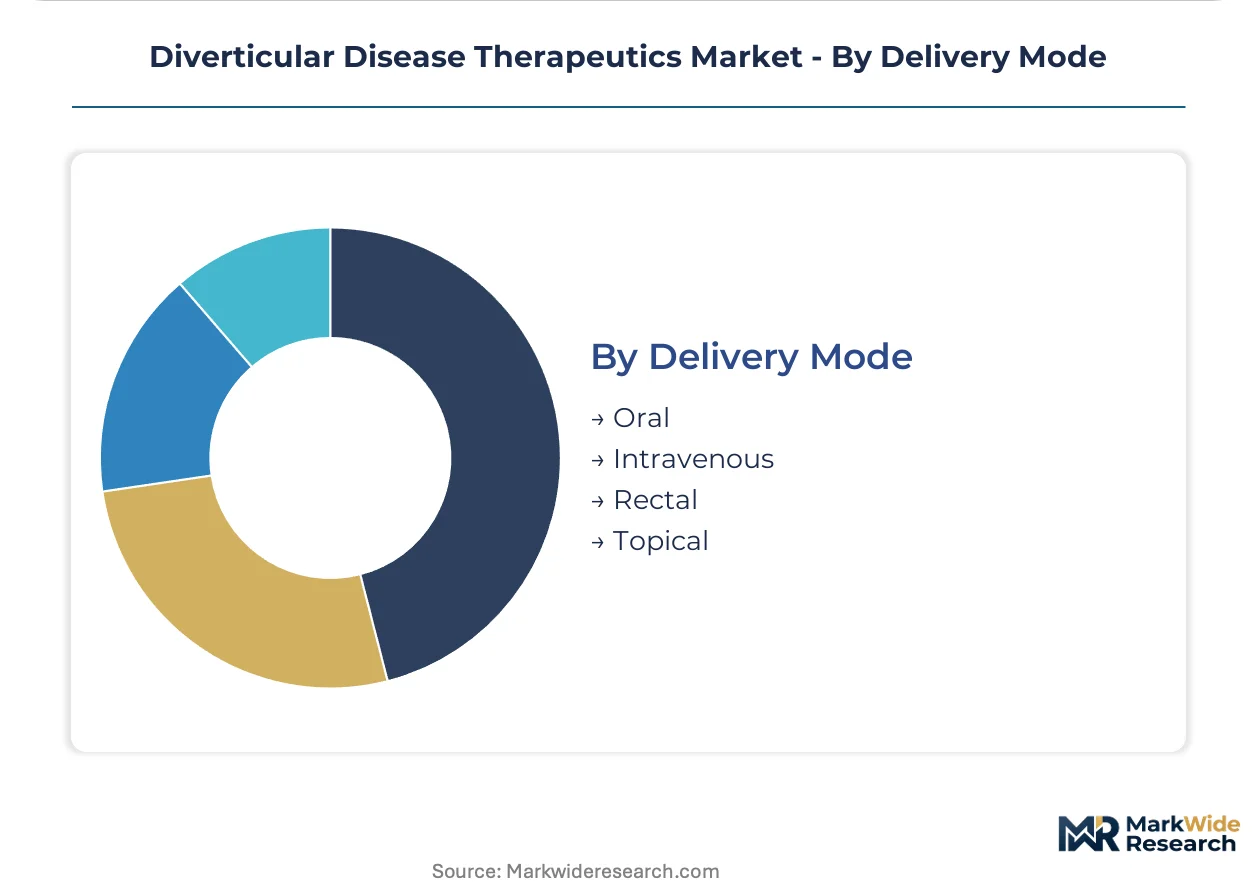
Delivery Mode:
Margin structure inverts between high-volume oral ambulatory prescriptions and lower-volume intravenous inpatient capture.
- Oral:Tablet and capsule formulations dominate ambulatory antibiotic completion and probiotic maintenance regimens. Retail pharmacy chains in the United States negotiate volume-based contracts that determine generic substitution rates.
- Intravenous:Hospital and infusion center administration captures higher per-treatment revenue in emergency-to-inpatient transitions. European hospital formulary placement governed by EMA centralized authorization shapes competitive access.
- Rectal:Localized delivery options address select distal colonic presentations.
- Topical:Limited applications in perianal complication management.
Oral delivery commands the prescription volume base while intravenous administration secures the highest per-treatment margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's 505(b)(2) pathway and Medicare reimbursement shifts are accelerating site-of-care migration for diverticulitis management, while European regulators elevate clinical evidence standards for surgical devices. Hospital systems in mature markets are contracting directly with home infusion services, compressing traditional inpatient revenue capture.
United States
Aging demographics and elevated outpatient surgical volumes sustain prescription volumes for acute and chronic presentations. The FDA's streamlined 505(b)(2) pathway accelerates generic antibiotic approvals, eroding branded pricing power in first-line therapy. Hospital systems in Texas and Florida are expanding hospital-at-home infrastructure for IV-to-oral step-down therapy.
Germany
Gastroenterology practices are integrating targeted probiotics into recurrence prevention protocols faster than other European markets. The EU MDR elevates clinical evidence requirements for surgical intervention devices, extending development timelines. The Rhine-Ruhr metropolitan region hosts concentrated hospital formulary placement negotiations for novel anti-inflammatory formulations.
France
Specialized bleeding management protocols in tertiary centers reduce surgical conversion rates for diverticular hemorrhage. ANSM oversight of live biotherapeutic products shapes probiotic classification frameworks. The Paris-Saclay cluster anchors pharmaceutical development pipelines targeting inflammatory complications of diverticulosis.
Japan
PMDA marketing authorization procedures govern access for systemic corticosteroids and immunomodulators in complicated cases. METI industrial policy supports microbiome modulation research consortia. Tokyo's tertiary hospital networks pilot remote patient monitoring platforms for high-risk post-acute surveillance.
United Kingdom
NHS England's ambulatory care transformation program compresses uncomplicated diverticulitis into same-day discharge pathways. MHRA post-Brexit regulatory autonomy enables tailored approval timelines for novel formulations. The Cambridge-London corridor concentrates biotech investment in chronic maintenance positioning strategies.
Diverticular Disease Therapeutics Market Competitive Landscape
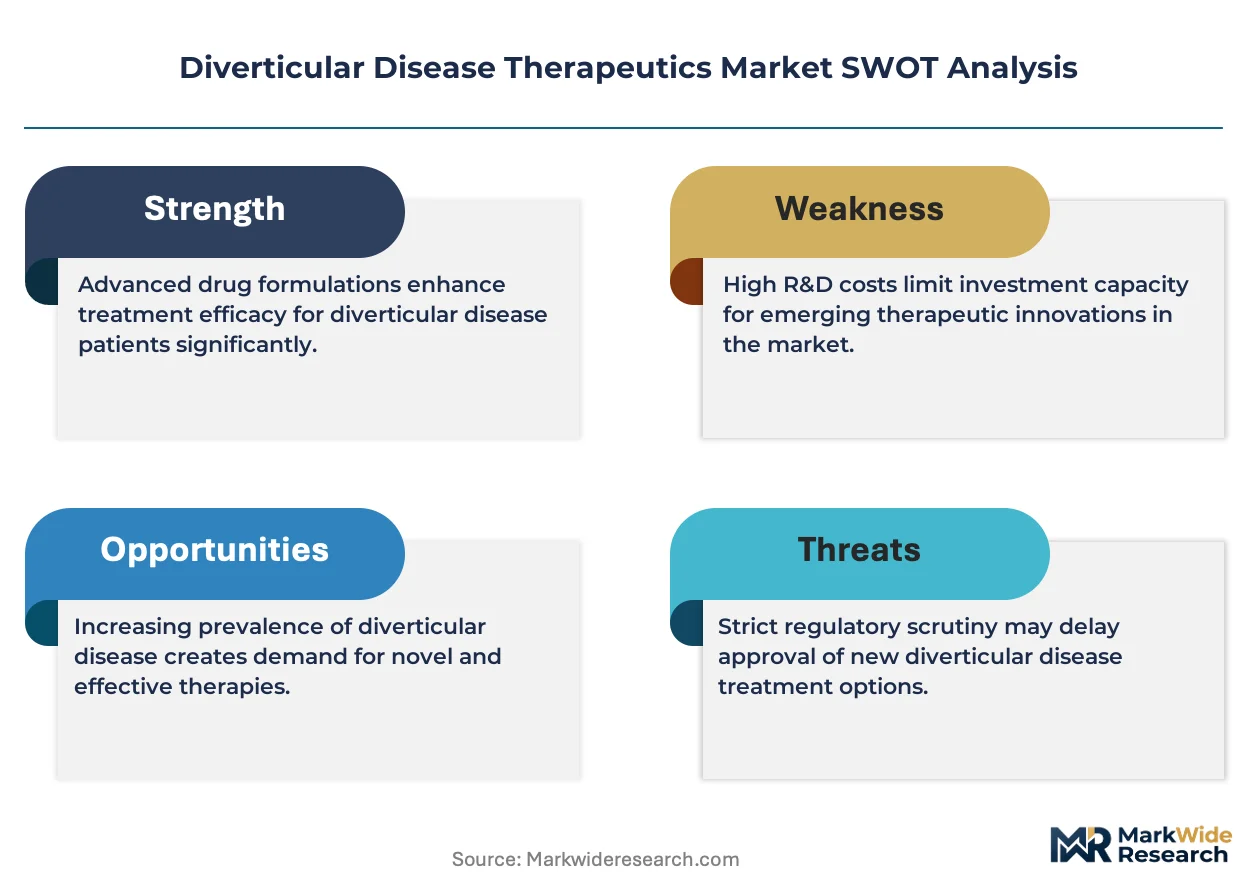
On the supply side, the industry is consolidating around immunology infrastructure holders and generic manufacturing scale players, with mid-tier specialists occupying microbiome modulation niches. Three strategic archetypes dominate: diversified pharmaceutical conglomerates with hospital formulary leverage, generic manufacturers exploiting 505(b)(2) acceleration, and biotech developers pursuing live biotherapeutic regulatory first-mover status. Competitive moves concentrate on strategic partnerships for hospital-at-home channel access and portfolio diversification into chronic maintenance indications.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Novartis AG exemplify scale-driven positions, with the former anchoring oral antibiotic production capacity and the latter occupying European hospital formulary placement networks. AbbVie Inc. represents the immunology infrastructure archetype, leveraging existing development pipelines. These three entities illustrate how regulatory pathway expertise and site-of-care channel control are separating winners from challengers.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Johnson & Johnson |
| AbbVie Inc. |
| Bayer AG |
| AstraZeneca plc |
| Abbott Laboratories |
| Teva Pharmaceutical Industries Ltd. |
| GlaxoSmithKline plc |
| Others |
Value Network & Pricing Analysis
The Rhine-Ruhr metropolitan region anchors European pharmaceutical manufacturing capacity for oral antibiotic production, with its concentrated formulation facilities translating directly into pricing leverage for fluoroquinolone and cephalosporin suppliers serving hospital formulary networks across Germany, France, and the Netherlands.
Pricing Analysis
Certification level creates the primary spread between branded and generic antibiotic tiers, with FDA 505(b)(2) approvals and EMA centralized authorizations commanding premium positioning against unapproved alternatives. Volume-based contracting through United States retail pharmacy chains and European hospital procurement consortia drives price differentiation, while generic entry via accelerated pathways compresses margins in first-line therapy. Cost compression in oral antibiotic segments intensifies because of rapid bioequivalence approvals, though intravenous formulations retain pricing power in emergency-to-inpatient transitions. Acute care settings demonstrate highest price sensitivity due to formulary budget constraints, while chronic probiotic maintenance programs show lowest sensitivity among gastroenterology practices integrating microbiome modulation protocols.
Supply Chain Analysis
Export-control regimes for live biotherapeutic products limit cross-border flows of microbiome-targeted therapies between United States and European development facilities, constraining capacity allocation decisions. Active pharmaceutical ingredient production draws from India, China, and the United States, with fermentation-derived probiotic strains and synthetic antibiotic compounds as critical inputs. Single-source vulnerability persists in specialized immunomodulator manufacturing for complicated diverticulitis cases. Distribution runs through integrated delivery networks with hospital-at-home capabilities, bypassing traditional wholesale channels for IV-to-oral step-down therapy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the diverticular disease therapeutics landscape creates multiple entry niches, as site-of-care migration splits patient volume between acute antibiotic prescriptions and chronic probiotic maintenance programs with divergent margin profiles.
For Market Incumbents: Harden formulary positioning through backward integration into live biotherapeutic manufacturing capacity, securing supply continuity for microbiome-targeted recurrence prevention therapies. Expand hospital-at-home channel partnerships to capture IV-to-oral step-down revenue outside traditional inpatient settings, defending against generic antibiotic price erosion through chronic maintenance indication expansion. For New Entrants and Emerging Players: Build out telehealth-integrated adherence platforms for high-risk post-acute patients, targeting the underpenetrated homecare monitoring segment where Medicare reimbursement changes are accelerating channel expansion. Focus initial commercialization on German and French gastroenterology practices with fastest probiotic integration rates, leveraging direct-to-physician education on microbiome modulation protocols. For Investors and Strategic Acquirers: Long-term, this sits as a chronic disease management play because diverticulosis maintenance therapy mirrors inflammatory bowel disease repositioning strategies with recurring revenue potential. Target acquisition profiles should emphasize biotech developers with early FDA live biotherapeutic product engagement experience and established hospital system partnerships. The signal to watch is regulatory clarity on probiotic classification frameworks that would unlock accelerated approval pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Live Biotherapeutic Product Regulatory Engagement | Early FDA and EMA qualification pathways secure competitive positioning in microbiome-targeted recurrence prevention. |
| Hospital-at-Home Infrastructure Partnership | Direct contracting with infusion services captures IV-to-oral step-down revenue outside traditional inpatient facilities. |
| Chronic Maintenance Indication Expansion | Repositioning anti-inflammatory agents for long-term diverticulosis management mirrors IBD maintenance strategies. |
| Telehealth Platform Integration | Remote monitoring capabilities enable subscription-based adherence programs for chronic probiotic regimens. |
| Manufacturing Scale-Up for Oral Antibiotics | Expanded production capacity addresses volume demands from ambulatory protocol expansion in United States health systems. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists and refined through secondary validation across FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up prescription volume modeling triangulated with top-down pharmaceutical market sizing across therapy area and delivery mode dimensions.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation modeling across treatment line, dosage form, administration route, and regional regulatory cluster. CAGRs were derived from patient epidemiology trends, pricing trajectory assumptions, and site-of-care migration patterns, incorporating antibiotic resistance surveillance data and probiotic clinical pipeline advancement as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by microbiome-focused biotech entrants or accelerated regulatory shifts for live biotherapeutic products would shift outcomes. Material shifts in FDA probiotic classification frameworks or EU MDR surgical device evidence requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Helicobacter Pylori Infections Treatment Market
Gastroenterology
Hirschsprung Disease Treatment Market
Gastroenterology
Gastrointestinal Drugs Market
Gastroenterology
Fecal Incontinence Market
Gastroenterology
Gastritis Treatment Market
Gastroenterology
Necrotic Enteritis Treatment Market
Gastroenterology
Gastroesophageal Junction Adenocarcinoma Therapeutics Market
Gastroenterology
Duodenal Ulcer Treatment Market
Gastroenterology
Inflammatory Bowel Disease Treatment Market
Gastroenterology
Pouchitis Treatment Market
Gastroenterology
High Definition Ultrasound Gastroscope Market
Gastroenterology
Colon Hydrotherapy Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market
Gastroenterology
US Inflammatory Bowel Disease Treatment Market
Gastroenterology
Malignant Ascites Market
Gastroenterology
Chile Gastric Cancer Treatment Market