
 Inflammatory Bowel Disease Market | 2026-2036
Inflammatory Bowel Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Inflammatory Bowel Disease Market Intelligence
The biologics segment is repositioning away from originator monoclonal antibodies toward lower-cost biosimilar alternatives, splitting the market into premium innovator tiers and commoditized interchangeable products. AbbVie Inc. leverages its entrenched adalimumab franchise to sustain pricing power in branded maintenance therapy. CELLTRION INC. competes aggressively on manufacturing scale to anchor biosimilar supply contracts with European and Asian hospital systems.
Inflammatory bowel disease encompasses chronic, relapsing immune-mediated disorders of the gastrointestinal tract—principally ulcerative colitis and Crohn's disease—characterized by transmural or mucosal inflammation, fibrosis, and epithelial barrier dysfunction; treatment aims to induce and maintain remission while preventing structural damage and surgical intervention. Biologics command the dominant value share due to targeted cytokine inhibition and superior mucosal healing rates compared to conventional immunomodulators. Injectable and infusion delivery modes capture concentrated margins as clinic-administered anti-TNF and anti-integrin therapies require specialized handling and monitoring infrastructure.
FDA maintains stringent requirements for biosimilar interchangeability designation, while EMA's centralized marketing authorization shapes access across EU member states and REACH-related manufacturing standards govern biologic production inputs. Japan's PMDA imposes additional local clinical bridging study requirements that delay biosimilar entry and protect innovator revenue streams. Stakeholders must monitor evolving interchangeability legislation at the US state level and EMA's emerging guidance on complex biologic extrapolation to anticipate where margin compression will strike first.
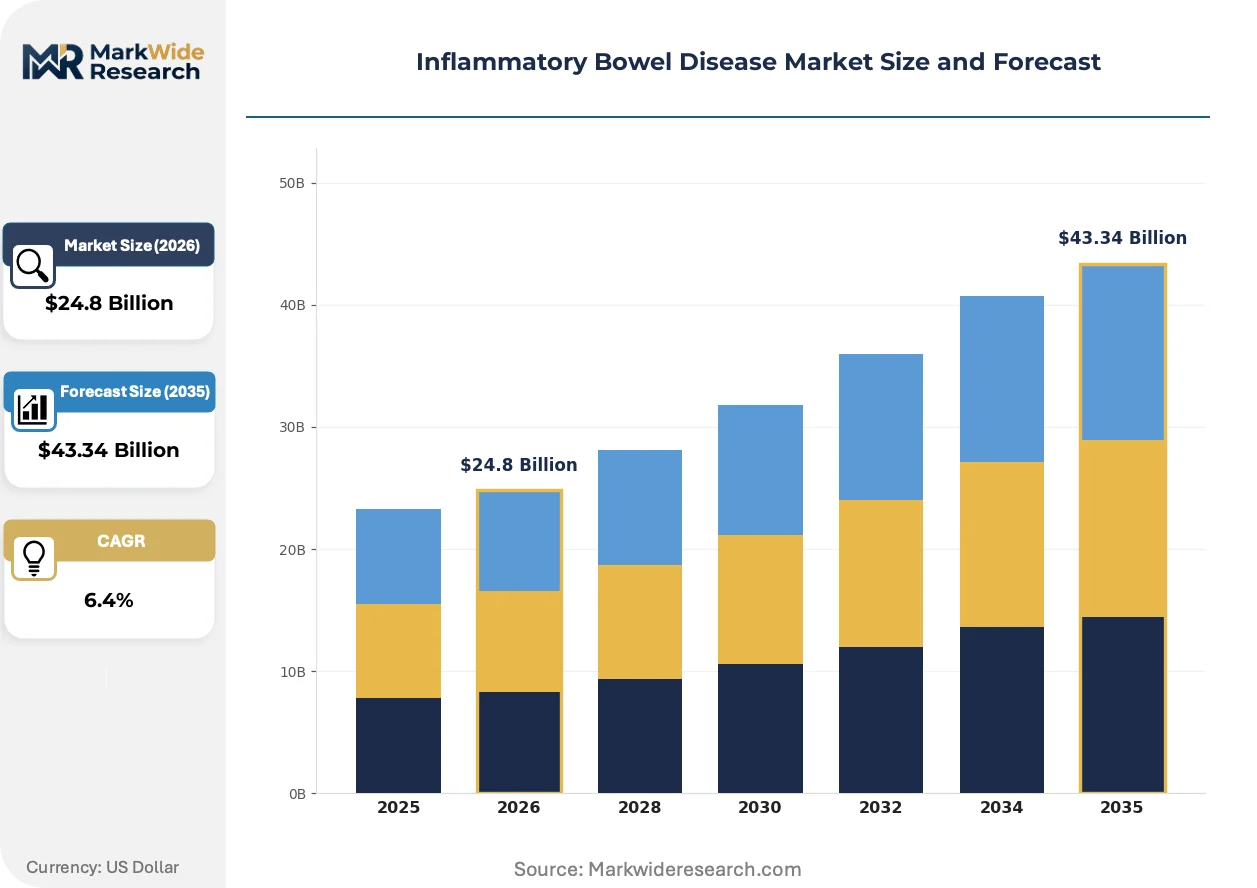
Market Dynamics
Biosimilar interchangeability pathways at FDA and EMA are fragmenting the biologics value chain, compressing originator margins while expanding patient access to anti-TNF and anti-integrin therapies across hospital systems.
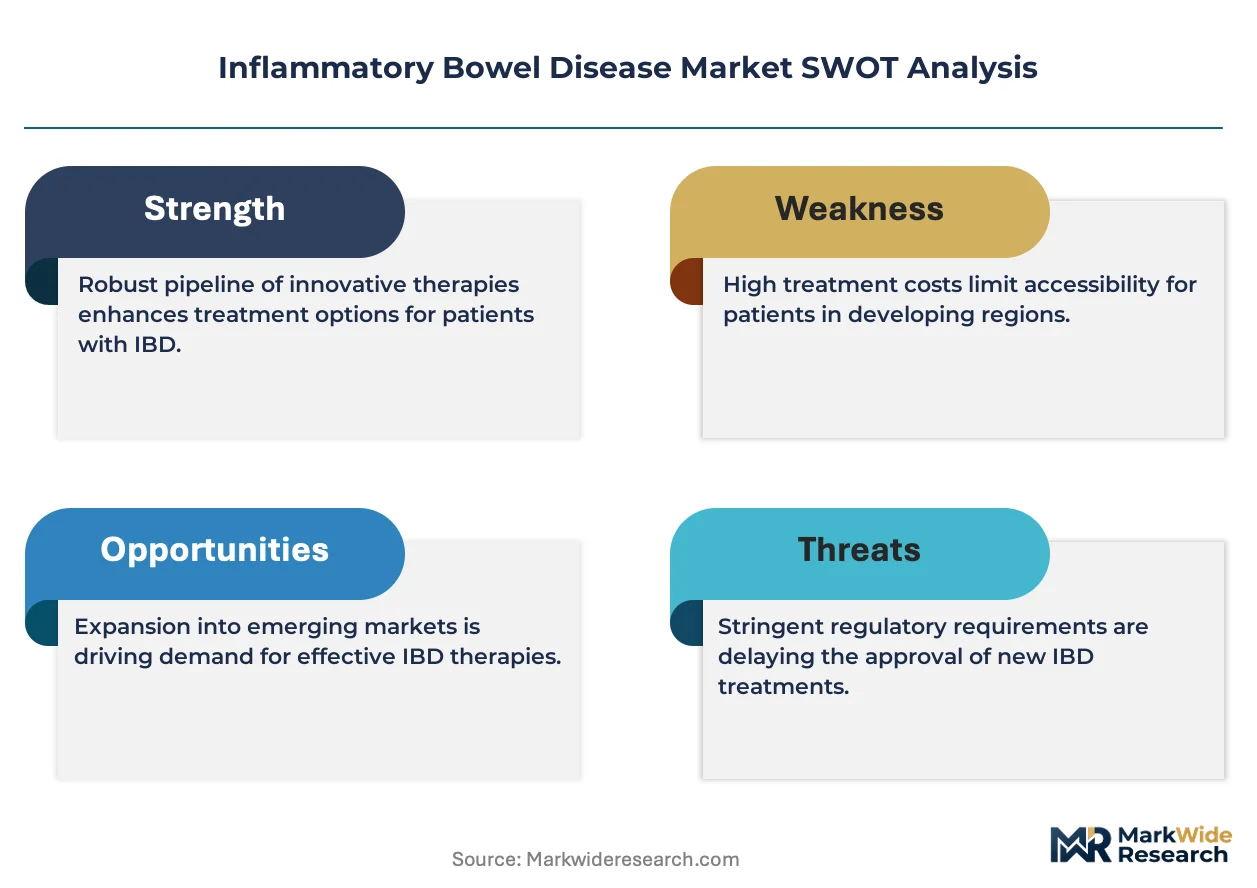
Growth Catalysts
- EMA Accelerated Assessment:Centralized marketing authorization for complex biologics reduces time-to-market for biosimilar developers targeting ulcerative colitis indications.
- Japan's Specialist Gastroenterology Infrastructure:Concentrated academic medical centers in Tokyo and Osaka facilitate rapid adoption of clinic-administered infusion therapies.
- Anti-Integrin Mechanism Expansion:Gut-selective biologics addressing refractory Crohn's disease are capturing share from systemic immunosuppressants in tertiary care settings.
Market Restraints
- Cold Chain Infrastructure Requirements:Injectable biologics demand continuous temperature-controlled logistics, limiting distribution reach in secondary hospital networks.
- PMDA Bridging Study Mandates:Japan's regulator imposes additional local clinical trials that extend biosimilar approval timelines and protect originator revenue.
- Originator Patent Thickets:Process patents on cell-line development and purification methods create legal barriers around adalimumab and infliximab formulations.
Strategic Opportunities
- Subcutaneous Formulation Switching:Self-administered maintenance dosing reduces clinic burden and expands addressable patient populations beyond infusion centers.
- US State-Level Interchangeability Legislation:Automatic substitution laws in California and New York create first-mover advantages for designated interchangeable biosimilars.
- Mucosal Healing Endpoints:Biomarker-driven trial designs are shortening development cycles for novel JAK inhibitors and S1P modulators.
Industry Challenges
- Specialized Infusion Nursing Shortages:Anti-TNF administration requires certified personnel for hypersensitivity monitoring, constraining clinic throughput.
- Legacy Electronic Health Record Integration:Biologic therapy tracking modules lack standardization across Epic and Cerner deployments, complicating outcomes data capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inflammatory Bowel Disease Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Immunomodulators, Corticosteroids, Aminosalicylates Therapy Area: Ulcerative Colitis, Crohn's Disease, Indeterminate Colitis, Others End User: Hospitals, Clinics, Homecare, Research Institutes Delivery Mode: Oral, Injectable, Infusion, Transdermal |
| Companies Covered | AbbVie Inc., Takeda Pharmaceutical Company Limited, Johnson & Johnson Services, Inc., Pfizer Inc., UCB S.A., Novartis AG, CELLTRION INC., Merck & Co., Inc., Biogen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inflammatory Bowel Disease Market Strategic Shifts & Innovations
Oral small-molecule therapies are eroding the injectable biologics monopoly in maintenance therapy, while real-world evidence platforms reshape how payers evaluate mucosal healing outcomes.
Subcutaneous drug-device combination products are modularizing the administration experience for anti-TNF and anti-IL-23 therapies. Rheumatology and gastroenterology practices in Germany and the United States are adopting these systems to reduce chair time and staff burden. The technology is modularizing site-of-care economics, enabling therapy migration from hospital infusion suites to home settings.
EMA's emerging guidance on complex biologic extrapolation is tightening evidentiary standards for biosimilar indication expansion. Developers must now submit separate immunogenicity datasets for ulcerative colitis versus Crohn's disease approvals. European hospital formularies are responding by segmenting procurement across originator, biosimilar, and designated-interchangeable tiers.
Hospital pharmacy committees are consolidating biologic purchasing through centralized tenders that bundle multiple autoimmune indications. This aggregation is displacing physician-level prescribing autonomy in favor of protocol-driven therapy selection. The shift is most pronounced in integrated delivery networks across the United States and university hospital systems in France.
Inflammatory Bowel Disease Market Segmentation
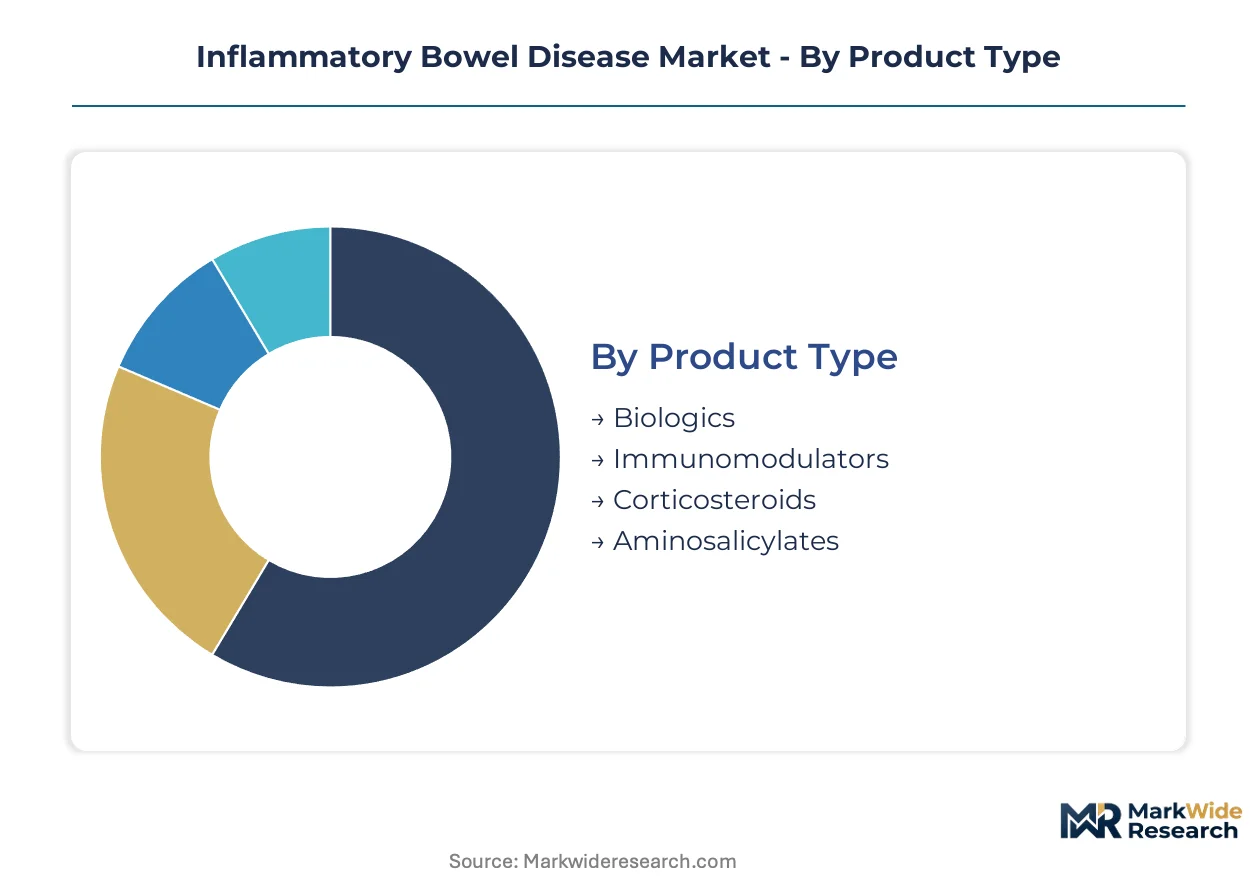
Segmentation in inflammatory bowel disease therapy reveals how treatment selection cascades from disease severity through delivery logistics to site-of-care economics. Understanding these intersecting dimensions clarifies where biologic manufacturers capture margin versus where commoditization pressures concentrate.
Product Type:
Standalone biologic therapies command premium positioning through specialized cold-chain infrastructure, while small-molecule immunomodulators embed into broader autoimmune protocols with simpler distribution requirements.
- Biologics:Monoclonal antibodies targeting TNF-alpha, integrins, and interleukins deliver targeted cytokine inhibition with superior mucosal healing rates. Demand clusters in tertiary hospital systems across the United States, Germany, and Japan where infusion nursing capacity and reimbursement frameworks support clinic-administered maintenance regimens.
- Immunomodulators:Thiopurines and methotrexate function as steroid-sparing bridge therapies with established oral bioavailability profiles. Prescription volume concentrates in European ambulatory settings where EMA guidelines favor step-up treatment algorithms before biologic escalation.
- Corticosteroids:Acute flare management via prednisone and budesonide retains front-line positioning despite long-term toxicity limitations.
- Aminosalicylates:Mesalazine formulations dominate mild-to-moderate ulcerative colitis maintenance with generic manufacturing eroding originator pricing power.
Volume placements concentrate in biologics; the faster expansion belongs to immunomodulators as biosimilar competition compresses anti-TNF pricing and expands access thresholds.
Therapy Area:
Disease-specific segmentation tracks how Crohn's transmural pathology demands more aggressive surgical and biologic intervention compared to ulcerative colitis mucosal disease patterns.
- Ulcerative Colitis:Continuous mucosal inflammation limited to the colon enables topical aminosalicylate therapy and proctocolectomy as curative surgical exit. Biologic adoption accelerates fastest in California and New York integrated delivery networks where state-level interchangeability legislation streamlines biosimilar substitution.
- Crohn's Disease:Transmural skip lesions with fibrostenotic and fistulizing complications require anti-TNF or anti-integrin biologics for structural damage prevention. German university hospitals in Berlin and Munich anchor demand concentration due to specialized interventional gastroenterology and intestinal surgery capabilities.
- Indeterminate Colitis:Diagnostic uncertainty between ulcerative colitis and Crohn's phenotypes delays definitive therapy selection.
- Others:Microscopic colitis and pouchitis represent niche indications with limited dedicated trial infrastructure.
Ulcerative Colitis generates the highest absolute prescription volumes; Crohn's Disease is climbing the fastest as refractory case identification improves and anti-integrin mechanisms expand indication breadth.
End User:
Site-of-care segmentation reflects how infusion nursing shortages and reimbursement differentials push biologic administration away from hospitals toward ambulatory alternatives.
- Hospitals:Academic medical centers in Tokyo and Osaka maintain dominant biologic infusion capacity with specialized hypersensitivity monitoring protocols. Japanese PMDA bridging study requirements protect hospital formulary originator preferences against rapid biosimilar conversion.
- Clinics:Rheumatology-gastroenterology multispecialty practices in Germany adopt subcutaneous drug-device combinations to reduce chair time. Outpatient reimbursement parity with hospital settings accelerates this migration.
- Homecare:Self-administered maintenance dosing expands addressable populations beyond geographic constraints of infusion center density.
- Research Institutes:Academic centers anchor biomarker-driven trial recruitment for novel JAK inhibitors and S1P modulators.
Hospital systems retain the largest installed base; homecare channels are expanding most quickly as subcutaneous formulations modularize administration economics.
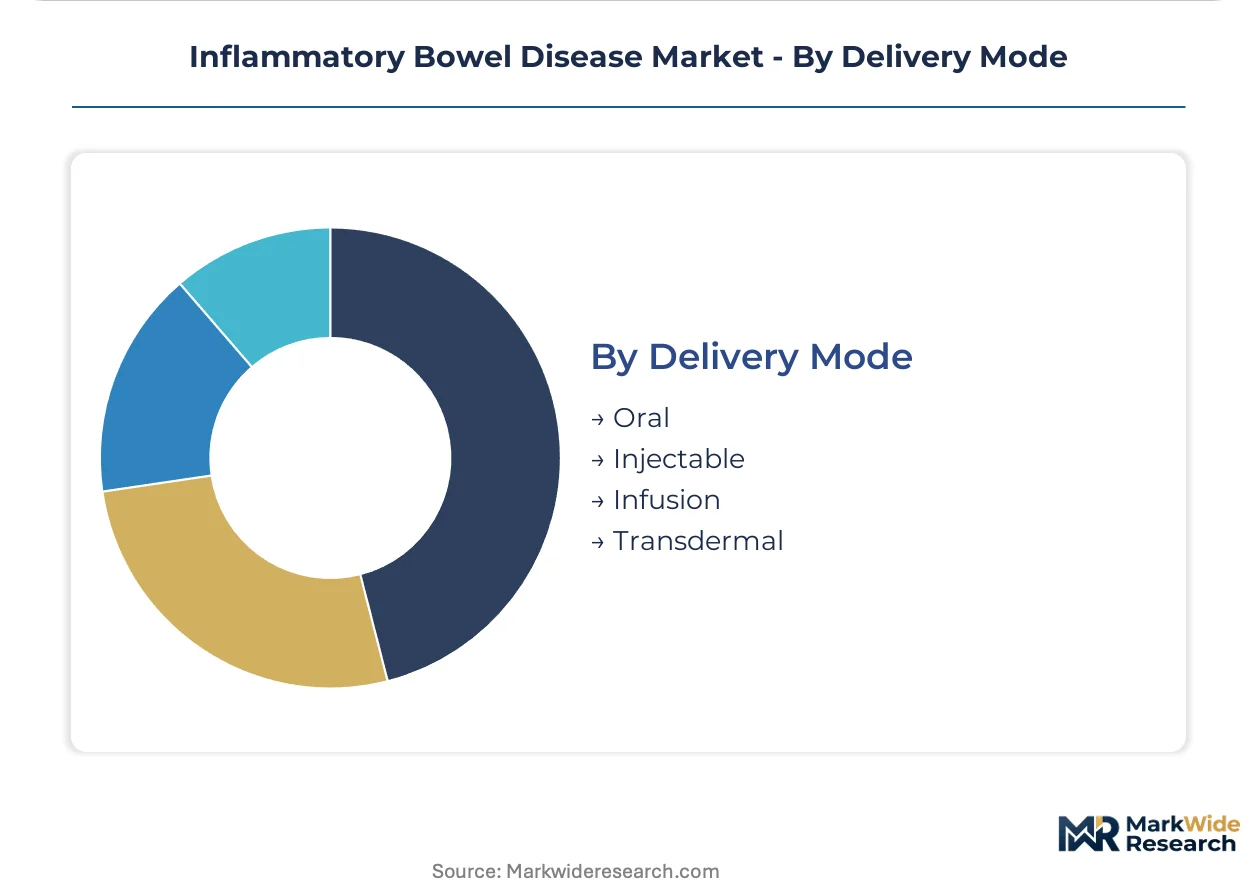
Delivery Mode:
Route-of-administration segmentation tracks the competitive tension between patient convenience preferences and pharmacokinetic requirements for large-molecule biologic stability.
- Injectable:Prefilled syringes and auto-injectors for adalimumab and golimumab enable self-administered maintenance without clinic dependency. FDA interchangeability designation creates automatic substitution pathways in California and New York that accelerate biosimilar volume capture.
- Infusion:Intravenous infliximab and vedolizumab require continuous temperature-controlled logistics and certified nursing oversight. Cold chain infrastructure limitations constrain distribution reach in secondary hospital networks across the United States and European periphery.
- Oral:Small-molecule JAK inhibitors and S1P modulators erode injectable biologic monopoly in maintenance therapy.
- Transdermal:Limited current application for IBD therapeutics due to molecular size barriers and colonic targeting requirements.
Infusion retains the highest value per dose; oral formulations are gaining share fastest as patient preference and payer cost pressure align behind small-molecule alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors biologic therapy demand concentration, with academic medical centers in the Kanto region administering the highest per-capita infusion volumes for anti-TNF and anti-integrin therapies.
United States
Integrated delivery networks in California and New York drive biosimilar substitution through state-level interchangeability legislation. FDA interchangeability designation creates automatic substitution pathways that accelerate volume capture for designated products. The Cleveland Clinic and Mayo Clinic anchor tertiary care demand for refractory Crohn's disease management.
Germany
University hospital systems in Berlin and Munich specialize in interventional gastroenterology for transmural Crohn's complications. EMA centralized marketing authorization streamlines biosimilar access across federal states. North Rhine-Westphalia's hospital pharmacy committees consolidate biologic purchasing through centralized tenders bundling multiple autoimmune indications.
Japan
PMDA bridging study mandates delay biosimilar entry and protect originator revenue streams in hospital formularies. Specialist gastroenterology infrastructure concentrates in Osaka and Nagoya academic centers. METI reimbursement frameworks sustain premium pricing for clinic-administered maintenance regimens.
United Kingdom
NHS England's biosimilar adoption targets compress originator margins while expanding patient access thresholds. NICE technology appraisals prioritize mucosal healing endpoints in formulary decisions. The Manchester and Birmingham hospital networks anchor inflammatory bowel disease biologic utilization in secondary care settings.
France
ANSM pharmacovigilance requirements shape post-market surveillance obligations for biologic manufacturers. Hospital pharmacy committees in Paris and Lyon academic centers segment procurement across originator, biosimilar, and designated-interchangeable tiers. HAS reimbursement decisions concentrate demand in tertiary referral networks.
Inflammatory Bowel Disease Market Key Industry Players
Premium-margin players sit above commodity-margin players across the biologics value chain, with originator monoclonal antibodies commanding pricing power against interchangeable biosimilar alternatives. The market structure consolidates around entrenched anti-TNF franchises and emerging gut-selective mechanisms. Three archetypes dominate: large-cap pharmaceutical conglomerates with diversified immunology portfolios, mid-cap biotech specialists focused on novel cytokine targets, and biosimilar manufacturers competing on manufacturing scale and supply security. Dominant competitive moves include subcutaneous formulation development to enable site-of-care migration and real-world evidence platform construction to support payer negotiations.
Among large-cap immunology incumbents, AbbVie Inc. and Takeda Pharmaceutical Company Limited exemplify the premium-tier archetype through entrenched adalimumab and vedolizumab franchises. CELLTRION INC. occupies a distinct position as a scale-driven biosimilar specialist competing on manufacturing capacity and European hospital supply contracts.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Takeda Pharmaceutical Company Limited |
| Johnson & Johnson Services, Inc. |
| Pfizer Inc. |
| UCB S.A. |
| Novartis AG |
| CELLTRION INC. |
| Merck & Co., Inc. |
| Biogen Inc. |
| Others |
Cost & Logistics Intelligence
CHO cell culture media costs and single-use bioreactor consumables anchor manufacturing economics for monoclonal antibody production, cascading through three distinct pricing tiers that separate originator biologics from designated-interchangeable biosimilars and commodity immunomodulators.
Pricing Analysis
Mucosal healing rates serve as the value-based pricing anchor for anti-TNF and anti-integrin therapies in hospital formularies. Three-tier pricing structure across premium, standard, and economy levels segments originator vedolizumab from EMA-authorized biosimilars and generic thiopurines. Cost compression in the biosimilar tier intensifies because FDA interchangeability designations enable automatic substitution in California and New York. Integrated delivery networks exhibit highest price sensitivity; academic medical centers in Japan remain least sensitive due to PMDA bridging study protections.
Supply Chain Analysis
Cell-line development and purification resin supply rests on specialized biotechnology manufacturing clusters in the United States, Germany, and South Korea. Chinese contract manufacturing organizations feed active pharmaceutical ingredient production for small-molecule JAK inhibitors. Single-source vulnerability concentrates in affinity chromatography resin suppliers for monoclonal antibody capture steps. Distribution runs through cold-chain logistics networks anchored by tertiary hospital pharmacy hubs in Tokyo, Berlin, and Cleveland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Inflammatory bowel disease therapy manufacturing is consolidating around scale-driven biologics producers and vertically integrated pharmaceutical conglomerates, with biosimilar interchangeability legislation forcing sub-scale developers toward exit or acquisition.
For Market Incumbents: Deploy subcutaneous formulation switching to capture site-of-care migration from infusion centers toward home administration. Secure hospital pharmacy committee contracts through bundled autoimmune indication tenders before European centralized procurement consolidates further. AbbVie's adalimumab franchise faces erosion from FDA-designated interchangeable biosimilars; counter through real-world evidence platforms demonstrating sustained mucosal healing differentiation. For New Entrants and Emerging Players: Capture oral small-molecule maintenance therapy segments where patient preference and payer cost pressure align behind JAK inhibitor and S1P modulator alternatives. Target German rheumatology-gastroenterology multispecialty practices adopting drug-device combination products for chair-time reduction. Pursue licensing agreements with academic medical centers in Osaka and Nagoya for biomarker-driven trial recruitment infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap biotech specialists with novel cytokine targets in late-stage development across the United States and European Union. Long-term viability hinges on regulatory exclusivity duration and formulary placement durability. Watch EMA guidance on complex biologic extrapolation as the inflection indicator for biosimilar indication expansion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Enables therapy migration from hospital infusion suites to home settings, expanding addressable populations. |
| EMA Centralized Marketing Authorization | Streamlines biosimilar access across EU member states, compressing originator pricing power. |
| Real-World Evidence Platform Construction | Supports payer negotiations by demonstrating mucosal healing outcomes beyond clinical trial endpoints. |
| Hospital Pharmacy Committee Consolidation | Displaces physician prescribing autonomy through protocol-driven therapy selection in integrated networks. |
| Biomarker-Driven Trial Design | Shortens development cycles for novel mechanisms by using objective response endpoints favored by FDA. |
Research Approach
Document review covered FDA filings, EMA centralized marketing authorization records, ClinicalTrials.gov protocols, and hospital formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Bottom-up patient-volume modeling and top-down revenue triangulation validated segmentation outputs across therapy area, delivery mode, and site-of-care dimensions.
Historical prescription volume trajectories were cross-referenced against expert panel input on biosimilar substitution rates and interchangeability legislation timelines. Segmentation modeling tracked product type, therapy area, end user, and delivery mode across the projection horizon. CAGRs were derived from patient prevalence projections, treatment escalation algorithms, and pricing elasticity assumptions for originator versus biosimilar tiers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA interchangeability designation timelines, EMA complex biologic extrapolation guidance, and PMDA bridging study requirement modifications. A small set of regulatory triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Gastroesophageal Reflux Disease Therapeutics Market
Gastroenterology
Acute Pancreatitis Market
Gastroenterology
Chile Gastric Cancer Treatment Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market
Gastroenterology
Malabsorption Syndrome Treatment Market
Gastroenterology
Stomach Cancer Market
Gastroenterology
Inflammatory Bowel Disease Treatment Market
Gastroenterology
Diverticular Disease Therapeutics Market
Gastroenterology
Chronic Liver Diseases Therapeutics Market
Gastroenterology
Peptic Ulcer Market
Gastroenterology
Gastroretentive Drug Delivery Systems Outsourcing Market
Gastroenterology
Digestive Health Market
Gastroenterology
Hyperemesis Gravidarum Treatment Market
Gastroenterology
Digestive Health Products Market
Gastroenterology
Duodenal Ulcer Treatment Market
Gastroenterology
Crohns Disease Therapeutics Market