
 Gastroesophageal Reflux Disease Therapeutics Market | 2026-2036
Gastroesophageal Reflux Disease Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Gastroesophageal Reflux Disease Therapeutics Market Analysis
Generic omeprazole is recalibrating cost structures across the proton pump inhibitor category, compressing branded margins while expanding patient access. AstraZeneca leverages its biologics pipeline to sustain differentiation in refractory GERD segments. Takeda Pharmaceutical Company anchors volume leadership through its established histamine antagonist franchise. Johnson & Johnson Services competes via channel control across retail pharmacy and direct-to-patient platforms.
Gastroesophageal reflux disease therapeutics encompass pharmaceutical agents that modulate gastric acid secretion, mucosal protection, or esophageal motility, with proton pump inhibitors achieving intragastric pH above four for twelve to sixteen hours through irreversible hydrogen-potassium ATPase inhibition. These agents serve the primary commercial purpose of healing erosive esophagitis, managing chronic heartburn, and preventing Barrett's esophagus progression. Proton pump inhibitors dominate current revenue pools due to entrenched prescribing habits and broad formulary coverage, while H2-receptor antagonists occupy a shrinking but defensible niche in mild intermittent cases and renal-impaired populations. The coating agents segment is gaining traction among pediatric care specialists seeking alternatives to systemic acid suppression.
The FDA maintains stringent requirements for long-term safety documentation in acid-suppression therapies, while the EMA's pharmacovigilance framework shapes European market access timelines for novel mechanisms. Health Canada and the TGA enforce bioequivalence standards that govern generic substitution rates across their respective jurisdictions. Stakeholders must monitor regulatory signals on potassium-competitive acid blocker pathways and prepare for reimbursement negotiations as these agents advance through clinical validation.
Market Dynamics
The FDA's evolving guidance on long-term proton pump inhibitor safety is forcing integrated delivery networks to recalibrate prescribing protocols and formulary placement decisions across acute and ambulatory settings.
Growth Catalysts
- Hospital pharmacy formulary expansion:Institutional buyers are widening access to novel acid-suppression therapies through centralized procurement committees, accelerating adoption of potassium-competitive acid blockers in refractory patient populations.
- EMA pharmacovigilance framework:European regulatory clarity on long-term safety documentation is compressing market access timelines for innovative mechanisms, enabling faster patient access to next-generation therapies.
- Integrated delivery network consolidation:United States purchasing decisions are concentrating in fewer hands, creating volume incentives for therapeutic innovation and streamlined supply contracts.
Market Restraints
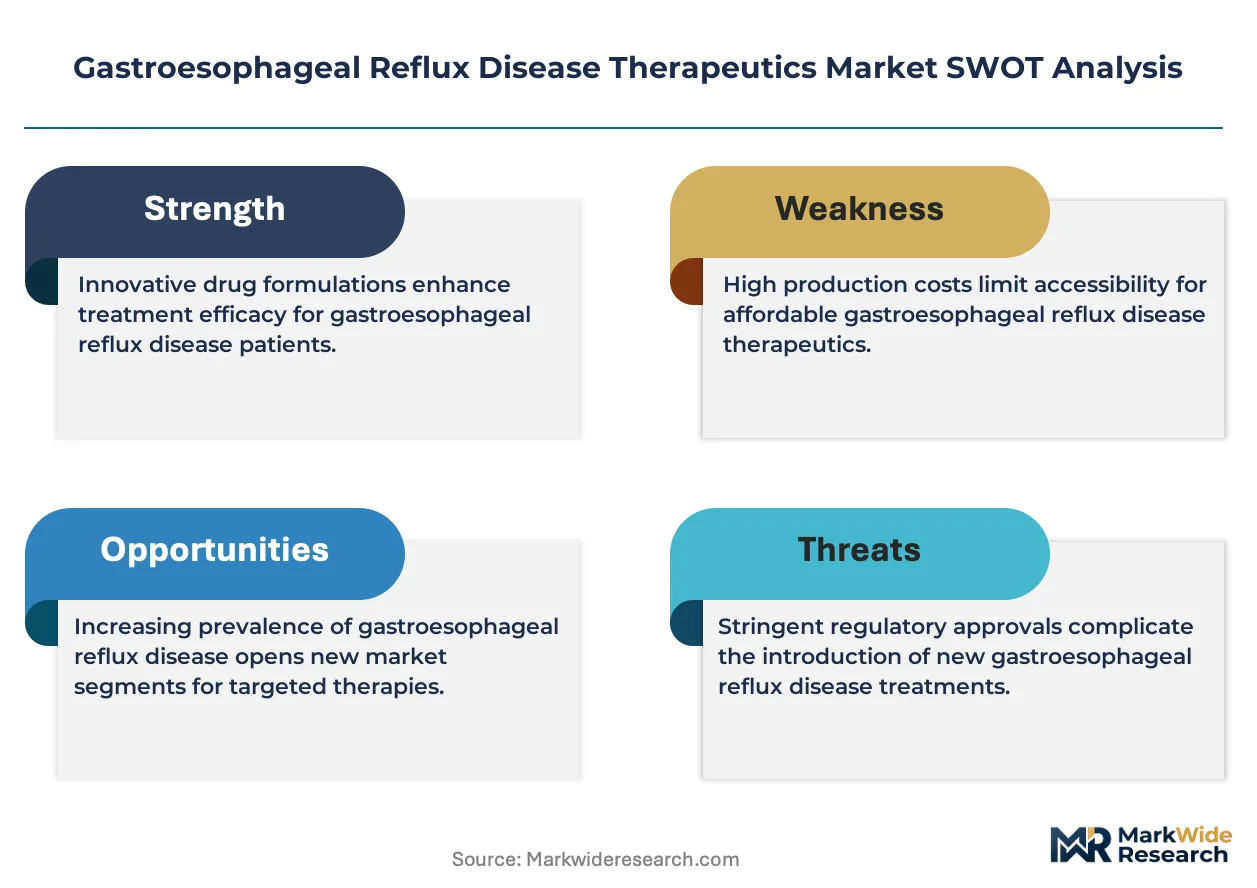
- Generic omeprazole saturation:Commoditization of first-generation proton pump inhibitors is compressing branded pricing power and eroding margin structures across the acid-suppression category.
- API supply concentration:Active pharmaceutical ingredient manufacturing for hydrogen-potassium ATPase inhibitors clusters in specific Asian manufacturing hubs, exposing formulators to single-source dependencies and geopolitical transit risks.
- Renal impairment limitations:Systemic acid suppression carries constrained utility in chronic kidney disease populations, restricting addressable patient pools for standard-of-care therapies.
Strategic Opportunities
- Pediatric coating agent segments:Mucosal protection formulations are gaining traction among pediatric care specialists seeking alternatives to systemic pharmacologic intervention in developing esophageal systems.
- Direct-to-patient platform expansion:Digital pharmacy channels are enabling manufacturer-patient relationships that bypass traditional retail intermediaries, capturing adherence data and improving refill economics.
- Health Canada bioequivalence pathways:Streamlined generic substitution standards are creating expedited entry routes for differentiated formulations with improved pharmacokinetic profiles.
Industry Challenges
- Clinical pharmacology talent scarcity:Specialized expertise in gastric pH modulation and esophageal motility disorders remains concentrated in academic medical centers, constraining commercial team expansion.
- Long-term cardiovascular safety documentation:Extended outcome studies required for chronic acid suppression therapies demand substantial capital deployment with uncertain regulatory reception timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gastroesophageal Reflux Disease Therapeutics Market |
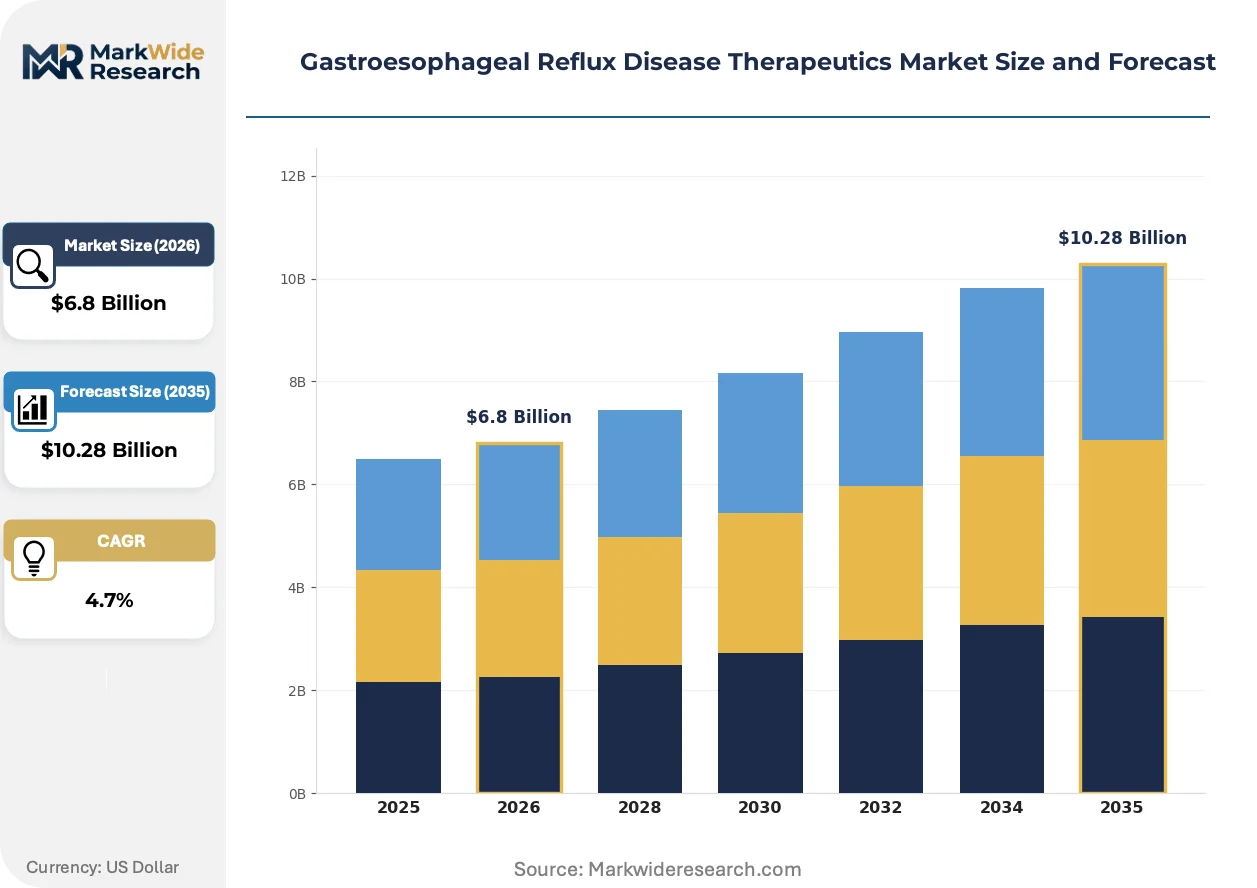
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Pump Inhibitors, H2-Receptor Antagonists, Antacids, Coating Agents Therapy Area: Chronic Condition, Pediatric Care, Post-Surgical Recovery, Over-the-Counter Remedies Delivery Mode: Oral, Injectable, Topical, Transdermal End User: Clinics, Hospitals, Home Care, Pharmacies |
| Companies Covered | AstraZeneca, Takeda Pharmaceutical Company, Johnson & Johnson Services, Eisai Co., GlaxoSmithKline plc, Novartis AG, Phathom Pharmaceuticals, Ironwood Pharmaceuticals, Sun Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gastroesophageal Reflux Disease Therapeutics Market Emerging Trajectories
Potassium-competitive acid blockers are disrupting entrenched proton pump inhibitor protocols through faster onset and reversible binding mechanics, while regulatory scrutiny on chronic therapy safety intensifies documentation requirements.
Reversible hydrogen-potassium ATPase inhibition is consolidating clinical positioning in refractory GERD segments where irreversible proton pump inhibitors demonstrate inadequate symptom control. Gastroenterology practices in tertiary referral centers are adopting these agents for rapid pH normalization. The technology is consolidating market share in non-erosive disease populations previously managed through step-down protocols.
The FDA's long-term safety documentation requirements for acid-suppression therapies are extending clinical validation timelines and inflating development costs for novel mechanisms. Sponsors must now demonstrate cardiovascular and renal outcomes across multi-year exposure cohorts. Biopharmaceutical developers are responding by prioritizing potassium-competitive acid blockers with shorter half-lives and reduced systemic accumulation profiles.
Integrated delivery networks are unbundling pharmacy benefit management from medical benefit administration, creating direct contracting opportunities for manufacturers with proven adherence outcomes. Hospital systems are replacing traditional wholesale distribution with self-distribution models and 340B program optimization. This restructuring is most visible in United States metropolitan markets where vertically consolidated health systems control both prescribing and dispensing decisions.
Gastroesophageal Reflux Disease Therapeutics Market Segmentation
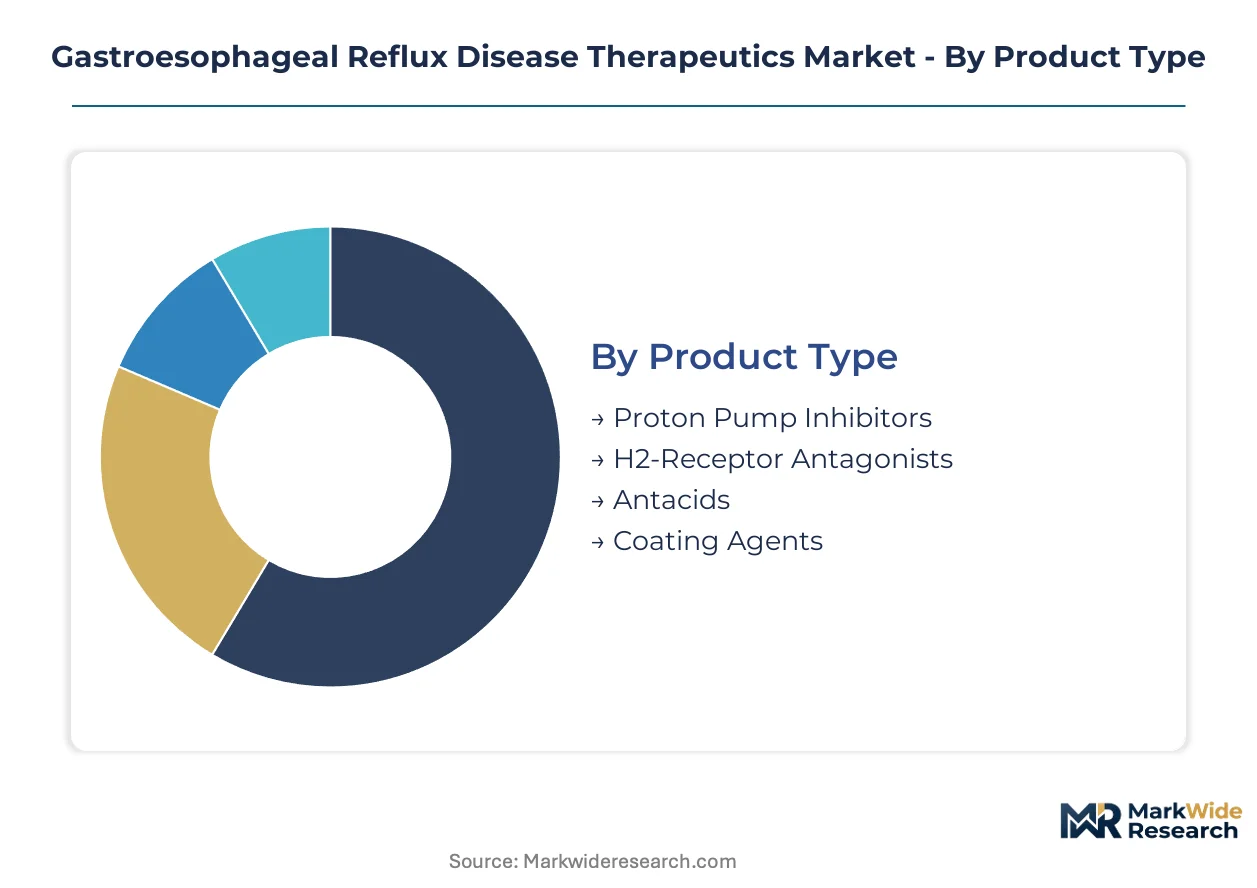
Therapeutic modality determines reimbursement pathways and prescribing authority across GERD management. Product innovation cycles and safety documentation requirements vary sharply by segment, creating divergent competitive economics.
Product Type:
Upgrade dynamics center on reversible acid suppression mechanisms displacing entrenched irreversible protocols in refractory patient populations.
- Proton Pump Inhibitors:Irreversible hydrogen-potassium ATPase inhibition sustains intragastric pH above four for twelve to sixteen hours through covalent proton pump binding. Hospital formularies in the United States retain these agents as first-line erosive esophagitis therapy despite generic omeprazole saturation eroding branded economics.
- H2-Receptor Antagonists:Competitive histamine receptor blockade reduces basal and stimulated acid secretion through reversible parietal cell inhibition. Renal-impaired populations and mild intermittent symptom cases in European ambulatory settings sustain residual demand where systemic PPI exposure carries documented risks.
- Antacids:Rapid-onset neutralization chemistry addresses breakthrough symptoms without pharmacologic half-life constraints.
- Coating Agents:Mucosal barrier formulations protect esophageal epithelium through physical rather than pharmacologic mechanisms.
Volume placements concentrate in proton pump inhibitors; the faster expansion belongs to coating agents.
Therapy Area:
Cost tier stratification separates chronic maintenance prescriptions from acute episodic purchases.
- Chronic Condition:Long-term acid suppression protocols for erosive esophagitis and Barrett's esophagus prevention require sustained therapeutic coverage with documented safety surveillance. Integrated delivery networks in the United States negotiate outcomes-based contracts for these high-lifetime-value patient cohorts.
- Pediatric Care:Developing esophageal systems demand modified dosing regimens and alternative delivery formulations with reduced systemic exposure profiles. European pediatric gastroenterology societies are restricting PPI exposure duration in favor of behavioral modification and coating agent adjuncts.
- Post-Surgical Recovery:Temporary acid suppression supports healing following fundoplication or bariatric intervention.
- Over-the-Counter Remedies:Self-directed symptom management bypasses prescription gatekeeping entirely.
Revenue concentration sits with chronic condition management; pediatric care is gaining share fastest.
Delivery Mode:
Application context dictates route selection across acute intervention versus maintenance scenarios.
- Oral:Enteric-coated tablets and delayed-release capsules dominate outpatient prescribing through established bioavailability profiles and patient self-administration convenience. Retail pharmacy channels in the United States capture the majority of dispensed volume through ninety-day maintenance supplies.
- Injectable:Intravenous proton pump inhibition enables rapid pH normalization in hospitalized bleeding ulcer or severe erosive disease cases where oral intake is contraindicated.
- Topical:Mucosal application formats address localized esophageal protection without systemic absorption.
- Transdermal:Absorption through dermal layers remains investigational for acid suppression therapeutics.
Oral formulations anchor volume; injectable applications show steepest expansion trajectory in acute care settings.
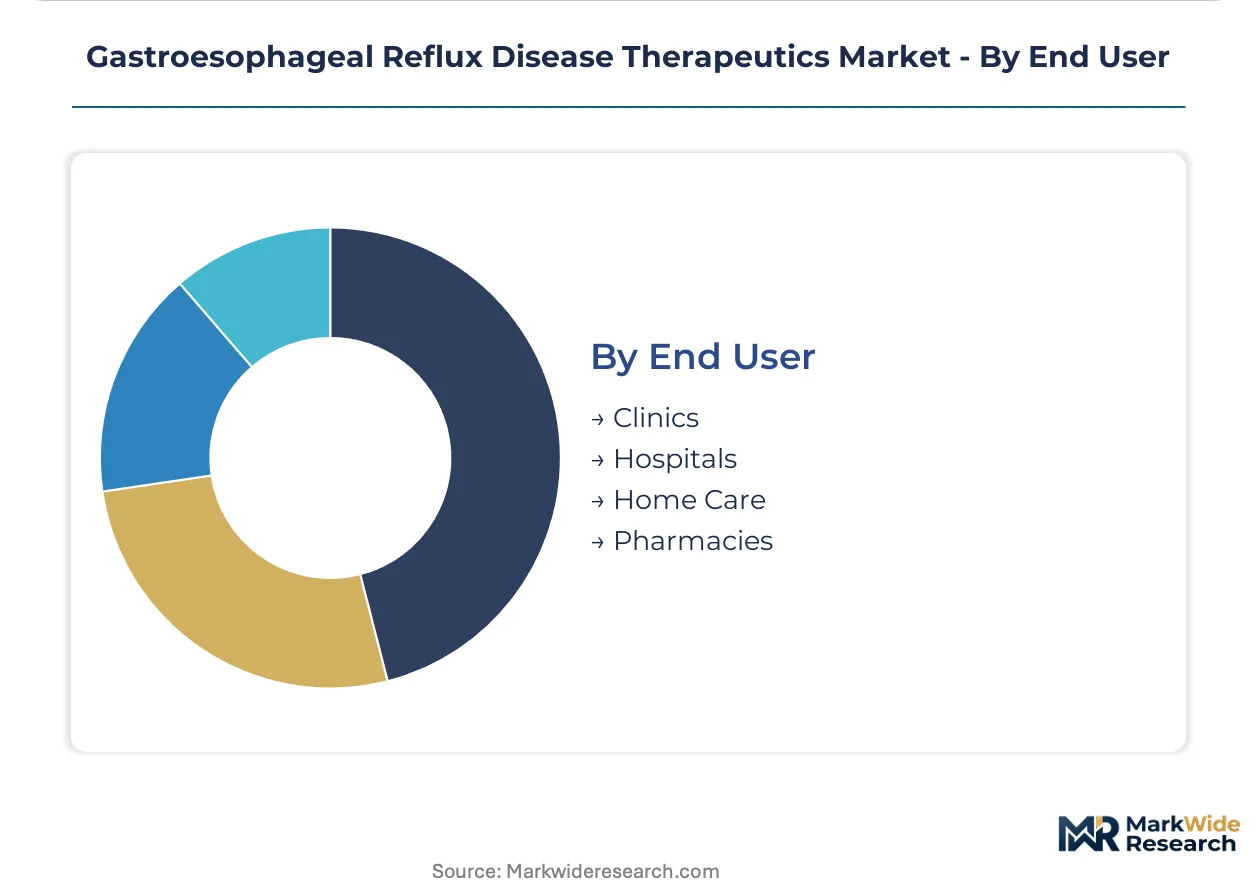
End User:
Customer type determines purchasing authority and formulary access tier.
- Hospitals:Centralized pharmacy and therapeutics committees control acid-suppression protocol selection across emergency, inpatient, and discharge prescribing. 340B program participation in the United States creates pricing differentiation between covered and non-covered entity purchases.
- Clinics:Gastroenterology specialty practices manage refractory case referrals and therapeutic escalation decisions.
- Home Care:Infusion services and visiting nurse protocols extend parenteral acid suppression into residential settings.
- Pharmacies:Community and mail-order dispensing intermediaries capture prescription fulfillment and over-the-counter substitution economics.
Hospital procurement concentrates volume; direct-to-patient platform expansion is climbing the fastest among channel configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special pharmaceutical economic zones in Hyderabad and the Research Triangle Park have concentrated clinical trial infrastructure and API manufacturing for acid-suppression therapies. These zones attract contract research organizations and active pharmaceutical ingredient producers through tax holidays and accelerated regulatory pathways.
United States
Integrated delivery networks in Texas and California are consolidating formulary decisions for proton pump inhibitors and potassium-competitive acid blockers. The FDA's evolving guidance on long-term acid suppression safety is forcing hospital pharmacy committees to document cardiovascular outcomes. Boston's biomedical corridor anchors post-market surveillance studies for chronic GERD populations.
Germany
Statutory health insurance funds in Bavaria and North Rhine-Westphalia negotiate reference pricing for generic omeprazole while maintaining premium reimbursement for innovative mechanisms. The EMA pharmacovigilance framework compresses market access timelines for novel acid-suppression therapies. Frankfurt's pharmaceutical distribution hub coordinates parallel trade flows across European Union member states.
Japan
Aging demographics in Tokyo and Osaka are expanding the addressable patient pool for maintenance acid-suppression therapy. The PMDA's streamlined review pathways for gastroenterology drugs are accelerating approvals for potassium-competitive acid blockers. Kansai's pharmaceutical manufacturing belt hosts formulation facilities serving domestic and export markets.
India
Domestic pharmaceutical consumption in Maharashtra and Gujarat is rising as urbanization drives dietary shifts associated with GERD prevalence. CDSCO bioequivalence standards govern generic substitution rates for proton pump inhibitor exports. Hyderabad's bulk drug parks supply hydrogen-potassium ATPase inhibitor APIs to formulators in Andhra Pradesh and Telangana.
Switzerland
Specialist gastroenterology practices in Zurich and Geneva manage refractory GERD referrals from across Alpine regions. Swissmedic maintains stringent documentation requirements for long-term acid suppression therapies. Basel's pharmaceutical research cluster generates clinical pharmacology expertise in gastric pH modulation.
Gastroesophageal Reflux Disease Therapeutics Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with originator companies defending margin in refractory populations while generic producers capture volume in maintenance therapy. The proton pump inhibitor category shows tiered concentration: three multinational pharmas anchor branded segments, while Indian and Chinese API suppliers feed formulation networks. Strategic archetypes include biologics-led differentiation specialists, histamine antagonist volume leaders, and channel-integrated retail platform operators. Competitive moves center on M&A for potassium-competitive acid blocker pipelines and capacity expansion in pediatric coating agent manufacturing.
Among Anglo-Swedish and Japanese pharmaceutical majors, AstraZeneca and Takeda Pharmaceutical Company exemplify contrasting archetypes in acid-suppression strategy. AstraZeneca occupies a position within biologics-forward portfolios targeting refractory GERD segments, while Takeda anchors volume leadership through established histamine antagonist franchises. Johnson & Johnson Services represents the channel-control archetype, leveraging retail pharmacy and direct-to-patient platforms to capture adherence economics.
| Leading Market Players |
|---|
| AstraZeneca |
| Takeda Pharmaceutical Company |
| Johnson & Johnson Services |
| Eisai Co. |
| GlaxoSmithKline plc |
| Novartis AG |
| Phathom Pharmaceuticals |
| Ironwood Pharmaceuticals |
| Sun Pharmaceutical Industries |
| Others |
Supply Flow & Price Mechanics
Clinical pharmacology expertise concentrated in Basel and Boston generates labor-cost differentials that widen pricing spreads between premium branded formulations and economy-tier generics. The scarcity of gastric pH modulation specialists forces sponsors to pay substantial premiums for development talent, compressing margins on mid-tier products while sustaining elevated price points for differentiated mechanisms.
Pricing Analysis
Volume-margin splits separate commodity proton pump inhibitors from premium potassium-competitive acid blockers. Three-tier pricing structure across premium, standard, and economy levels stratifies by therapeutic mechanism and regulatory documentation depth. Price differentiation rests on FDA approval tier and cardiovascular safety data package completeness. Cost compression in the standard tier intensifies because generic omeprazole saturation erodes branded pricing power. Retail pharmacy channels exhibit highest price sensitivity; hospital formularies demonstrate lowest sensitivity due to outcomes-based contracting frameworks.
Supply Chain Analysis
Direct-to-patient digital channels handle chronic maintenance prescriptions while hospital self-distribution manages acute care parenteral formulations. Active pharmaceutical ingredient manufacturing clusters in India, China, and select European hubs. Hydrogen-potassium ATPase inhibitor production draws from concentrated Asian manufacturing centers. Potassium-competitive acid blocker intermediates and enteric coating polymers constitute critical input dependencies. Single-source API vulnerability exposes formulators to geopolitical transit disruptions. Distribution runs through vertically integrated hospital systems in the United States and wholesale networks in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized manufacturing capacity for pediatric coating agents and potassium-competitive acid blocker APIs operates below demand growth, propping pricing premiums for qualified suppliers. This supply-constrained structure favors incumbents with captive production assets.
For Market Incumbents: Extend formulary control through outcomes-based contracts with integrated delivery networks, anchoring volume in refractory GERD populations where generic substitution fails. Deepen backward integration into API manufacturing for hydrogen-potassium ATPase inhibitors to offset single-source concentration risk. Prioritize certification investment in FDA long-term safety documentation to defend margin position against emerging potassium-competitive acid blocker entrants. For New Entrants and Emerging Players: The premium-economy price-point gap in coating agent segments creates entry opportunity for mucosal protection formulations targeting pediatric care specialists. White-space concentration sits with direct-to-patient platform expansion for chronic maintenance populations bypassing traditional retail pharmacy intermediaries. European ambulatory settings present most penetrable geography given EMA pharmacovigilance framework clarity. Pursue licensing agreements with established API suppliers to accelerate market access without capital-intensive manufacturing buildout. For Investors and Strategic Acquirers: Re-rating potential sits with potassium-competitive acid blocker developers given FDA pathway clarity on reversible binding mechanisms. Long-term viability across the projection horizon favors sponsors with differentiated pharmacokinetic profiles and reduced systemic accumulation. Target acquisition archetype includes clinical-stage developers with completed Phase II refractory GERD data. Watch potassium-competitive acid blocker formulary adoption rates in United States hospital systems as inflection indicator for category shift timing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III cardiovascular outcomes studies satisfy FDA long-term safety documentation requirements for chronic acid suppression. |
| Regulatory Approval Pathway | PMDA streamlined review accelerates potassium-competitive acid blocker market access in Japanese aging demographics. |
| Manufacturing Scale-Up | Pediatric coating agent capacity expansion captures fastest-growing segment among alternatives to systemic PPI exposure. |
| Pipeline Diversification | Mucosal protection formulations reduce reliance on proton pump inhibitor commoditization pressures. |
| Licensing Agreement | API supply partnerships with Hyderabad bulk drug parks mitigate single-source concentration risk for formulators. |
Methodological Framework
Document review covered FDA guidance documents, EMA pharmacovigilance frameworks, ClinicalTrials.gov entries, and hospital formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from SEC 10-K pharmaceutical filings, CDSCO bioequivalence standards, and GPO contract disclosures. Bottom-up patient population modeling and top-down therapeutic category sizing enabled triangulation across data sources.
Market size outputs and growth trajectories across the analysis window reflect segmentation by therapeutic modality, therapy area, delivery mode, and end-user channel. The analytical framework incorporated patient epidemiology, treatment line progression, and reimbursement pathway evolution. CAGRs were derived from regression-based trend extrapolation adjusted for regulatory timeline uncertainty. Forecast inputs included generic substitution rates, potassium-competitive acid blocker clinical validation milestones, and integrated delivery network consolidation patterns.
Inputs from FDA advisory committee minutes and EMA assessment reports were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around volume estimates. Forecasts reflect assumptions regarding regulatory approval timelines and formulary placement velocity. Periodic stress-testing of base assumptions is recommended given potential for FDA safety guidance revision and API supply disruption scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Digestive Health Products Market
Gastroenterology
Digestive Health Market
Gastroenterology
Gastroretentive Drug Delivery Systems Outsourcing Market
Gastroenterology
Intestinal Pseudo-Obstruction Treatment Market
Gastroenterology
Duodenal Ulcer Treatment Market
Gastroenterology
Malabsorption Syndrome Treatment Market
Gastroenterology
Global Gastrointestinal Bleeding Treatment Market
Gastroenterology
US Inflammatory Bowel Disease Treatment Market
Gastroenterology
Necrotic Enteritis Treatment Market
Gastroenterology
Global Gastrointestinal Stent Market
Gastroenterology
Fecal Incontinence Market
Gastroenterology
Stomach Cancer Market
Gastroenterology
Peptic Ulcer Market
Gastroenterology
Gluten Intolerance Treatment Market
Gastroenterology
Pouchitis Treatment Market
Gastroenterology
Crohns Disease Therapeutics Market