
 Fibroblast Activation Protein Inhibitors Market | 2026-2036
Fibroblast Activation Protein Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Fibroblast Activation Protein Inhibitors Market Foresight
Modular radiopharmaceutical kit formats are realigning procurement patterns across nuclear medicine departments. Bayer AG leverages its integrated cyclotron network to secure isotope supply chains for FAP-directed imaging agents. AstraZeneca sustains broad oncology infrastructure that supports companion diagnostic development alongside therapeutic pipelines. Novartis AG anchors its position through radioligand therapy platforms that extend into fibroblast activation protein targeting.
Fibroblast activation protein inhibitors comprise synthetic and biologic compounds designed to block FAP enzymatic activity, a membrane-bound serine protease overexpressed on cancer-associated fibroblasts in desmoplastic stromal microenvironments; these agents functionally disrupt tumor-stromal signaling cascades and enable selective radiotracer accumulation for diagnostic imaging. Small molecules and monoclonal antibodies represent the dominant modality categories, with peptides gaining traction in radiopharmaceutical applications due to favorable pharmacokinetics and rapid renal clearance profiles. Intravenous delivery maintains primacy in clinical settings, while subcutaneous formulations attract development investment for outpatient administration models.
The FDA oversees investigational new drug applications and breakthrough therapy designations for FAP inhibitor candidates, while the EMA's centralized marketing authorization procedure governs European commercialization pathways for radiopharmaceutical conjugates. ISO 13485 quality management standards and GMP radiochemistry guidelines constrain manufacturing scale-up for clinical-grade FAP ligands. Stakeholders must monitor reimbursement negotiations for novel PET tracers across national health technology assessment bodies.
Market Dynamics
Breakthrough therapy designations from the FDA are compressing clinical validation timelines for FAP-targeted radiopharmaceuticals, pulling forward revenue realization windows and intensifying R&D resource competition among developers.
Growth Catalysts
- EMA Centralized Authorization:The European Medicines Agency's unified marketing pathway for radiopharmaceutical conjugates eliminates fragmented national approvals, accelerating cross-border commercialization for FAP imaging agents.
- Oncology Department Expansion:Academic medical centers in Germany are scaling PET imaging protocols using FAP-targeted tracers, creating installed-base demand for companion inhibitor therapeutics.
- Modular Kit Formats:Standardized radiopharmaceutical preparation systems are reducing per-dose production complexity, enabling same-day synthesis in hospital-based cyclotron facilities.
Market Restraints
- Isotope Supply Concentration:Cyclotron-produced gallium-68 and lutetium-177 depend on a limited network of regional production facilities, creating geographic supply vulnerability for FAP ligand manufacturers.
- GMP Radiochemistry Standards:ISO 13485 quality management requirements and good manufacturing practice guidelines impose capital-intensive facility validation burdens that constrain manufacturing scale-up.
- Reimbursement Negotiation Friction:National health technology assessment bodies in Europe apply divergent cost-effectiveness thresholds for novel PET tracers, fragmenting market access timelines.
Strategic Opportunities
- Subcutaneous Formulation Development:Outpatient administration models for FAP inhibitors could displace intravenous delivery dominance, expanding addressable patient populations beyond infusion-capable centers.
- Peptide Radiopharmaceutical Expansion:Favorable pharmacokinetics and rapid renal clearance profiles position peptide-based FAP ligands to capture share from antibody modalities in diagnostic applications.
- Multicenter Trial Coordination:Helmholtz centers and German university hospitals are establishing imaging trial infrastructure that could serve as a template for standardized clinical validation across European markets.
Industry Challenges
- Radiochemistry Talent Scarcity:The specialized skill set combining PET tracer synthesis with GMP compliance faces supply constraints, limiting manufacturing expansion at contract development organizations.
- Companion Diagnostic Integration:Therapeutic pipeline developers must synchronize FAP inhibitor clinical trials with imaging agent regulatory approvals, creating complex program management dependencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fibroblast Activation Protein Inhibitors Market |
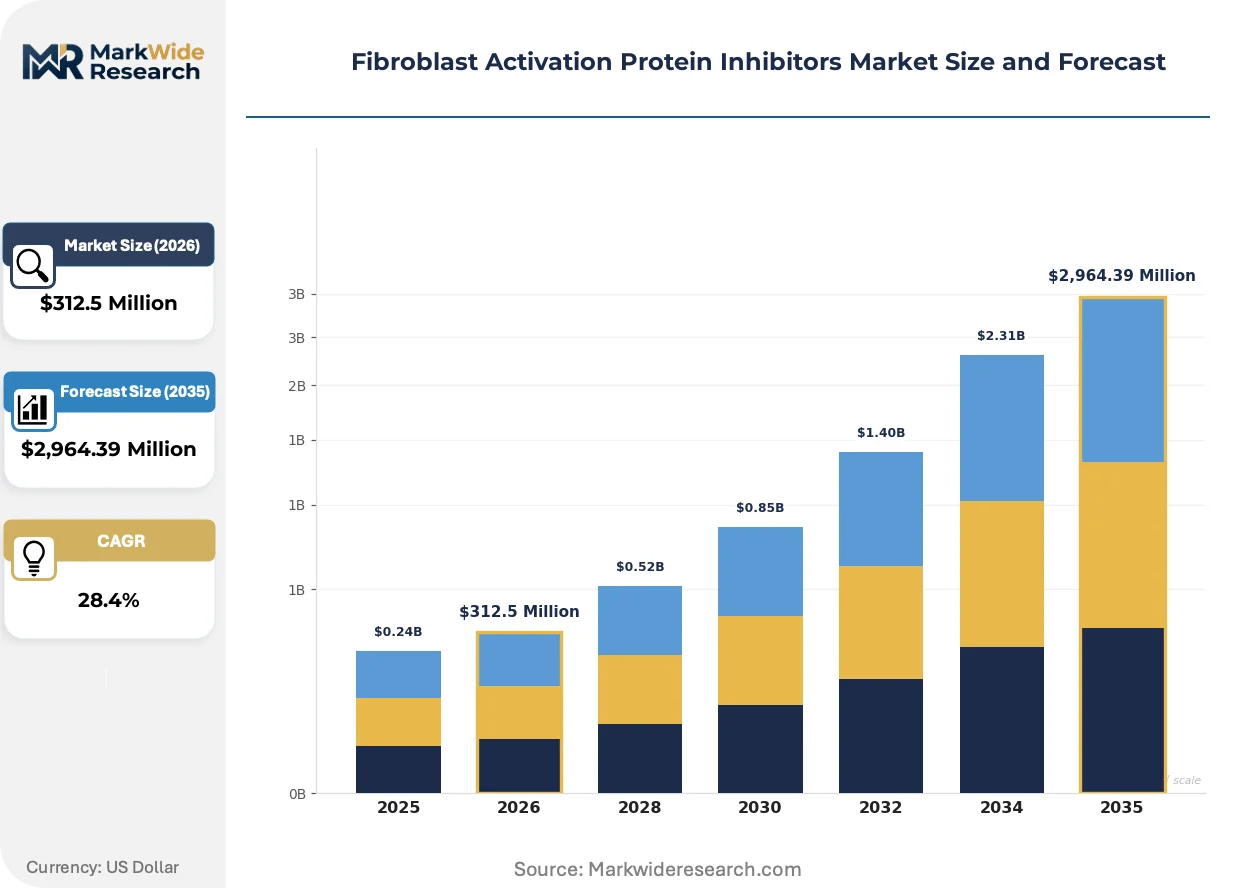
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $2,964.39 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Monoclonal Antibodies, Peptides, RNA Interference Therapy Area: Oncology, Autoimmune Diseases, Cardiovascular Disorders, Fibrotic Conditions Delivery Mode: Intravenous, Subcutaneous, Oral, Topical End User: Hospitals, Clinics, Research Laboratories, Pharmacies |
| Companies Covered | SOFIE, AstraZeneca, Novartis AG, BioXcel/OnkosXcel, Isotopia Molecular Imaging, Bayer AG, Lantheus Holdings, Avacta Life Science, GE HealthCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fibroblast Activation Protein Inhibitors Market Shifts & Advancements
Radioligand therapy platforms are extending into fibroblast activation protein targeting, blurring historical boundaries between diagnostic imaging and therapeutic delivery in nuclear medicine departments.
Peptide-based FAP ligands are converging with chelator technology advances to enable stable radiometal labeling for both imaging and therapeutic applications. Nuclear medicine departments in German academic centers are adopting these conjugates at accelerating pace for desmoplastic tumor characterization. The structural consequence is converging with radiopharmaceutical vendor strategies, compressing development timelines for theranostic product pairs.
The FDA's breakthrough therapy designation pathway is restructuring clinical validation economics for FAP inhibitor candidates by enabling rolling review and accelerated approval eligibility. This regulatory mechanism reduces capital requirements for late-stage development programs while intensifying competition for scarce investigator sites. Oncology-focused biopharmaceutical developers with existing radioligand infrastructure are responding most aggressively, filing integrated imaging-therapy development plans.
Academic medical center procurement is consolidating radiopharmaceutical sourcing around integrated cyclotron network operators capable of same-day isotope delivery. Hospital pharmacy departments are displacing external compounding arrangements with in-house kit-based preparation systems, particularly in German and Swiss markets where reimbursement favors site-of-care production economics. This channel restructuring is most visible in university hospital systems coordinating multicenter imaging trials.
Fibroblast Activation Protein Inhibitors Market Segmentation
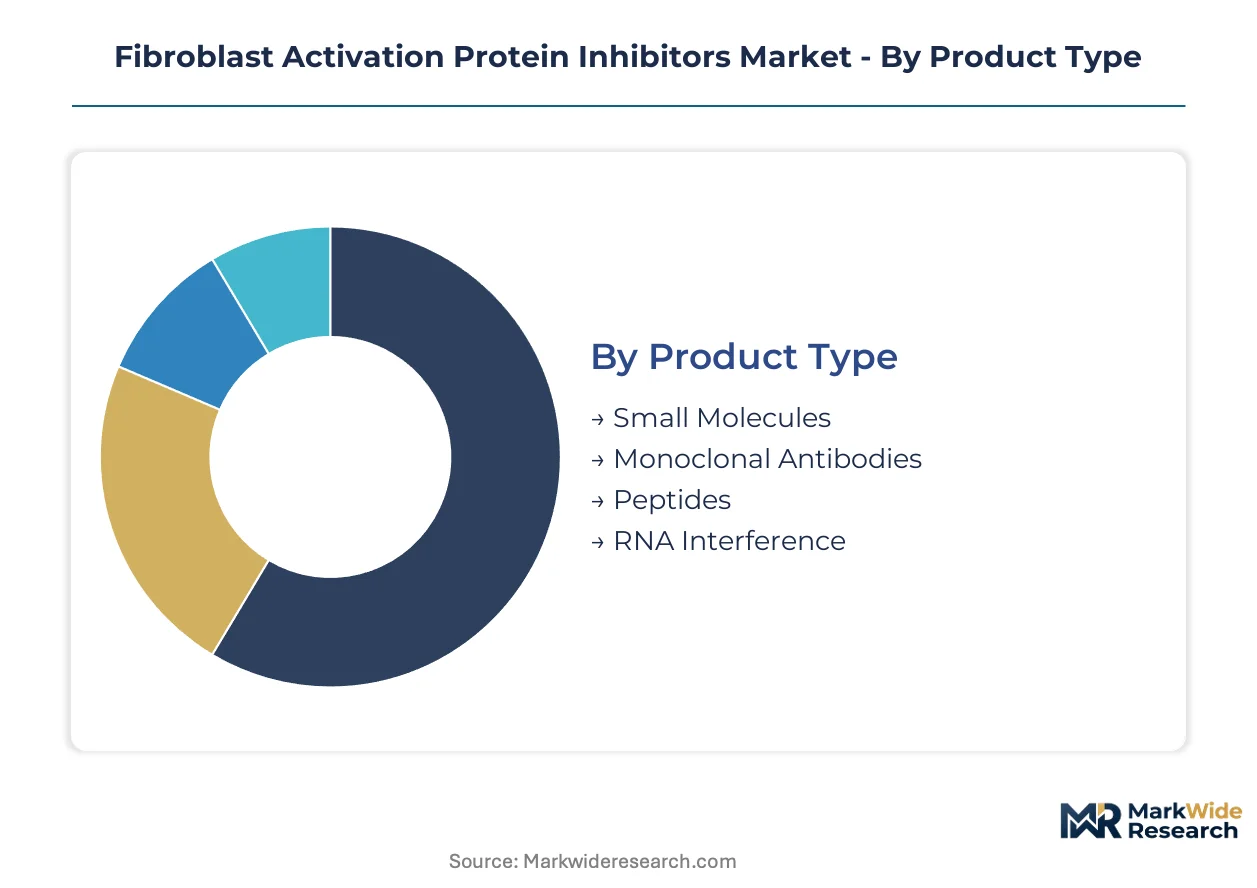
Segmentation in the FAP inhibitor market reveals how supply chain configuration and clinical infrastructure shape competitive positioning across modalities. Developers must align product formats with cyclotron network coverage, reimbursement pathways, and hospital pharmacy capabilities.
Product Type:
Supply concentration among cyclotron network operators favors formats with stable isotope coupling and same-day synthesis feasibility.
- Small Molecules:Synthetic compounds with defined molecular weights enable rapid renal clearance and reproducible GMP manufacturing. Demand concentrates in German university hospitals scaling PET imaging protocols, driven by compatibility with kit-based radiopharmaceutical preparation systems.
- Monoclonal Antibodies:Large biologic constructs offer extended circulating half-lives but require complex mammalian cell production infrastructure. Academic medical centers in Switzerland leverage existing oncology infusion networks for these modalities, constrained by cold-chain distribution requirements.
- Peptides:Favorable pharmacokinetics support rapid tumor penetration and renal excretion profiles suited to theranostic applications.
- RNA Interference:Emerging nucleic acid modalities face delivery formulation challenges and limited clinical validation infrastructure.
Today's leader: Small Molecules. Tomorrow's challenger: Peptides.
Therapy Area:
Cost tier differentiation separates imaging-only applications from theranostic pairs requiring dual regulatory pathways.
- Oncology:Desmoplastic tumor microenvironments in pancreatic, gastric, and colorectal malignancies drive the dominant share of clinical development. Helmholtz centers coordinate multicenter trials across Germany, with FDA breakthrough therapy designations compressing validation timelines for radiopharmaceutical conjugates.
- Fibrotic Conditions:Idiopathic pulmonary fibrosis and hepatic fibrosis represent expanding indications where FAP expression on activated fibroblasts enables stromal targeting. Swiss and Austrian academic hospitals pilot imaging protocols for interstitial lung disease characterization.
- Autoimmune Diseases:Rheumatoid arthritis and inflammatory bowel disease applications remain preclinical, constrained by biomarker validation requirements.
- Cardiovascular Disorders:Atherosclerotic plaque imaging attracts development investment but faces reimbursement uncertainty across European health technology assessment bodies.
Oncology commands current revenue concentration. Fibrotic Conditions are gaining share fastest as diagnostic protocols expand beyond cancer centers.
Delivery Mode:
Volume concentration in infusion-capable centers preserves intravenous dominance while outpatient economics drive formulation innovation.
- Intravenous:Maintains clinical primacy through established oncology nursing infrastructure and controlled biodistribution for radiotracer administration. German hospital pharmacies favor this route for FAP-directed gallium-68 and lutetium-177 conjugates.
- Subcutaneous:Outpatient administration models attract investment from developers seeking to expand beyond academic medical center catchments. Austrian and Swiss clinics pilot depot formulations for therapeutic antibodies.
- Oral:Small molecule inhibitors enable community pharmacy dispensing but face bioavailability challenges for targeted delivery.
- Topical:Limited to dermatologic fibrotic conditions with minimal current clinical infrastructure.
Intravenous retains installed-base advantage. Subcutaneous climbs the fastest as reimbursement shifts toward site-of-care economics.
End User:
Customer type fragmentation reflects divergent procurement authority between centralized hospital pharmacies and distributed clinical settings.
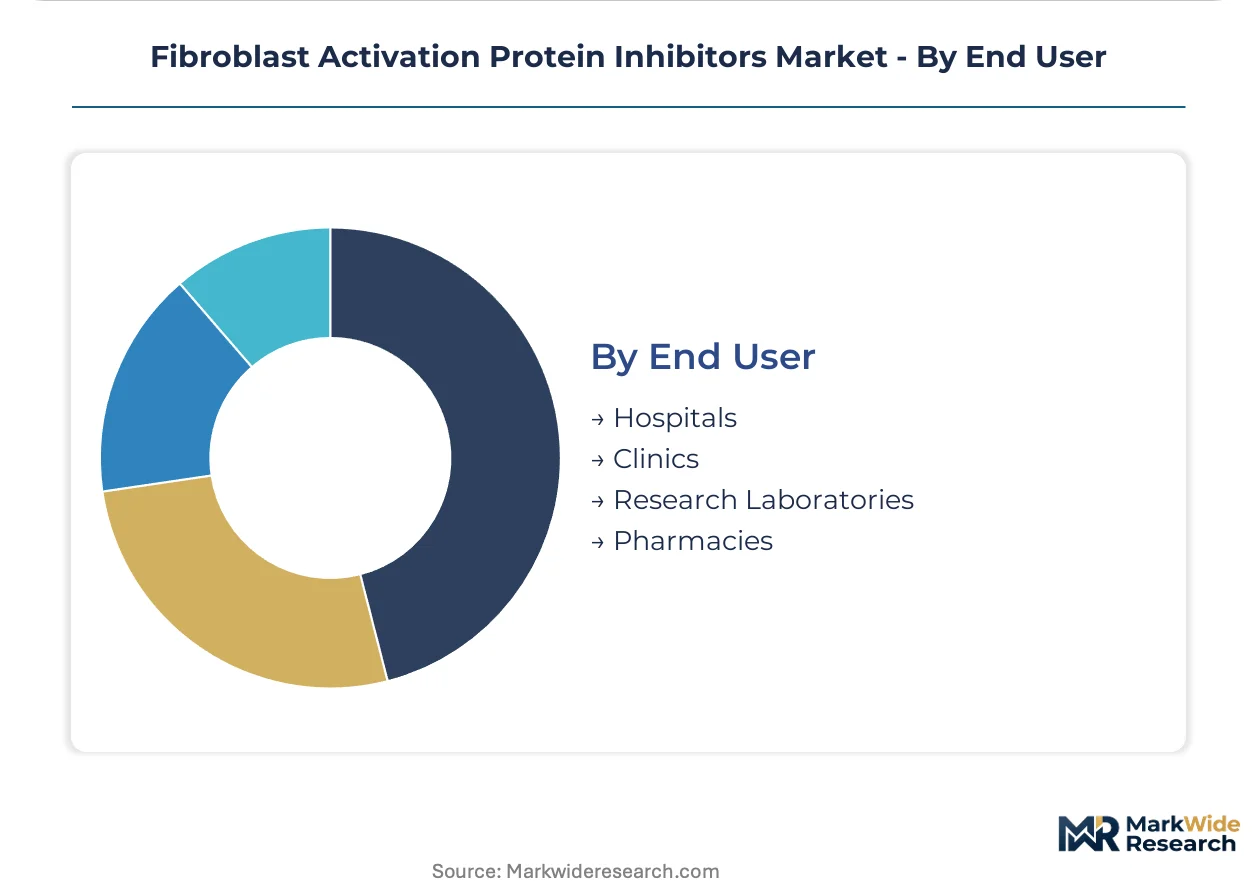
- Hospitals:Academic medical centers with integrated cyclotron facilities control radiopharmaceutical preparation and theranostic protocol development. German university hospital systems coordinate multicenter imaging trials that establish clinical validation standards.
- Research Laboratories:Helmholtz centers and university institutes drive preclinical candidate selection and tracer optimization. Swiss Federal Institutes of Technology anchor radiochemistry talent pipelines for the sector.
- Clinics:Community oncology practices depend on external isotope supply chains and compounding arrangements.
- Pharmacies:Retail and specialty pharmacy channels remain underdeveloped for radiopharmaceutical distribution.
Hospitals anchor current demand. Research Laboratories shape tomorrow's pipeline through tracer development partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fibroblast activation protein inhibitor development traces its clinical lineage to German academic medical centers, where Helmholtz institutes pioneered FAP-targeted radiotracer protocols in the early 2010s. This foundation established diagnostic imaging infrastructure that now anchors multicenter trial coordination across Europe and North America.
Germany
Helmholtz centers in Munich and Berlin coordinate multicenter imaging trials that validate FAP-directed PET tracers for pancreatic and gastric malignancies. The country's national pharmaceutical regulator, the Federal Institute for Drugs and Medical Devices, aligns with EMA centralized procedures to accelerate radiopharmaceutical approvals. University hospital systems in Heidelberg and Tübingen operate integrated cyclotron networks that enable same-day isotope production for clinical-grade ligand synthesis.
United States
FDA breakthrough therapy designations compress clinical validation timelines for FAP inhibitor candidates, pulling forward revenue windows for developers with existing radioligand infrastructure. The agency's rolling review mechanism reduces capital requirements for late-stage programs while intensifying competition for investigator sites. Academic medical centers in Boston and Houston anchor theranostic protocol development, with MD Anderson and Dana-Farber scaling PET imaging departments for desmoplastic tumor characterization.
Switzerland
Swiss Federal Institutes of Technology in Zurich and Lausanne anchor radiochemistry talent pipelines that supply specialized synthesis expertise to European contract development organizations. Swissmedic maintains stringent GMP radiochemistry guidelines that constrain manufacturing scale-up but ensure clinical-grade quality for export markets. University hospitals in Basel and Geneva pilot imaging protocols for interstitial lung disease, expanding FAP-targeted applications beyond oncology into fibrotic conditions.
United Kingdom
The Medicines and Healthcare products Regulatory Agency oversees marketing authorization applications for FAP-directed radiopharmaceuticals through national procedures that parallel EMA centralized pathways. London's Royal Marsden Hospital and Manchester's Christie NHS Foundation Trust coordinate imaging trial networks that validate companion diagnostic integration for therapeutic pipelines. The concentration of contract research organizations in Cambridge and Oxford accelerates preclinical candidate optimization for peptide-based ligands.
Japan
PMDA consultations for radiopharmaceutical development are restructuring clinical validation economics for FAP inhibitor candidates seeking Asian market entry. The Pharmaceuticals and Medical Devices Agency's priority review vouchers incentivize novel diagnostic imaging agents for desmoplastic malignancies. University hospitals in Tokyo and Osaka establish imaging protocol standards that influence regulatory acceptance across Asia-Pacific markets, with National Cancer Center Japan leading multicenter coordination.
Fibroblast Activation Protein Inhibitors Market Competitive Landscape
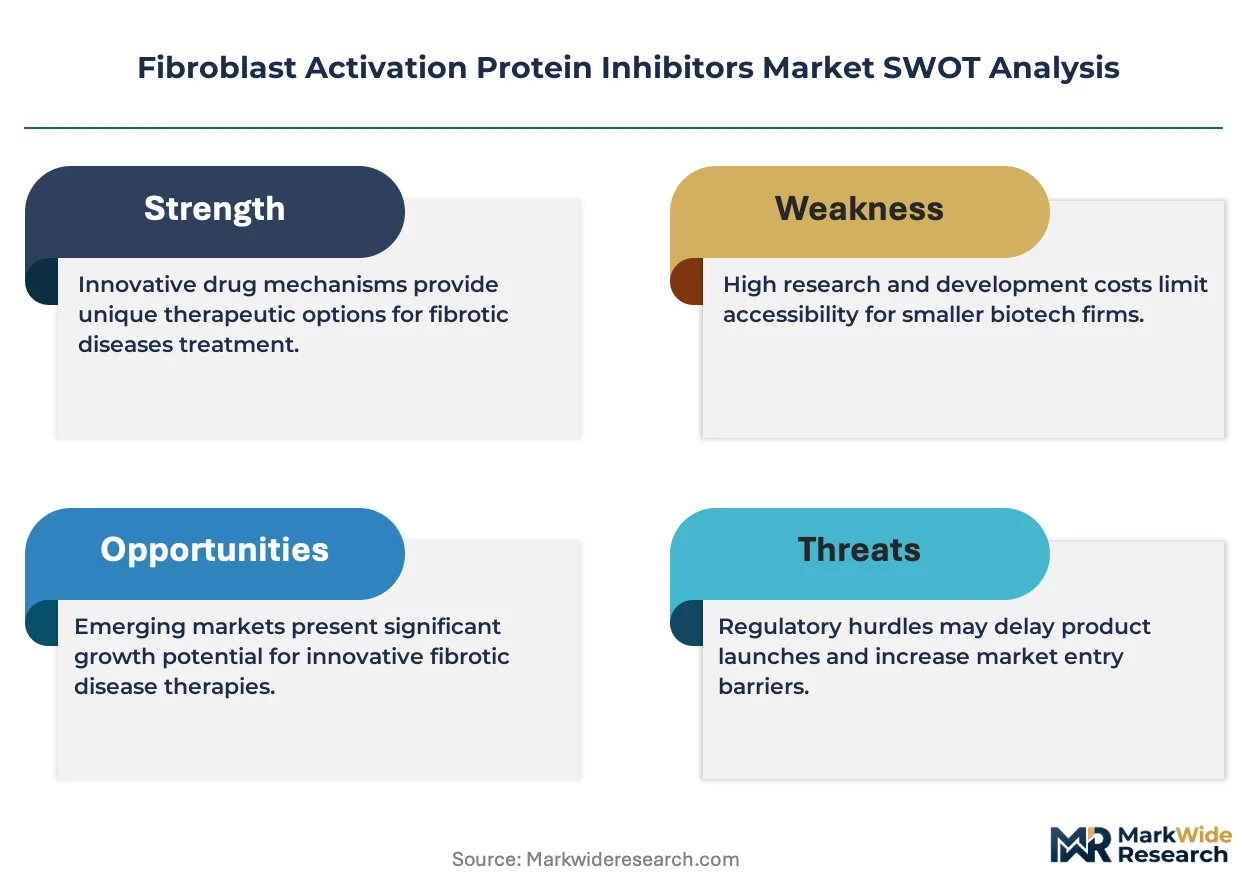
The competitive structure tilts toward integrated radiopharmaceutical platform operators with captive cyclotron networks and established oncology infrastructure. Market concentration reflects significant capital barriers to GMP radiochemistry facility validation and isotope supply chain security. Three archetypes dominate: diversified pharmaceutical conglomerates with radioligand therapy divisions, specialized molecular imaging companies with tracer development expertise, and academic spin-outs commercializing institutional research. Dominant competitive moves include strategic partnerships between diagnostic developers and therapeutic pipeline sponsors, plus backward integration into cyclotron network operation to secure isotope supply.
Among diversified pharmaceutical conglomerates, Bayer AG and Novartis AG occupy positions that exemplify platform-centric strategies, leveraging integrated infrastructure to span diagnostic imaging and therapeutic delivery. AstraZeneca represents the oncology-focused archetype, sustaining broad infrastructure that supports companion diagnostic development alongside therapeutic pipelines. These three companies anchor the competitive landscape through distinct but overlapping approaches to FAP-targeted modality development.
| Leading Market Players |
|---|
| SOFIE |
| AstraZeneca |
| Novartis AG |
| BioXcel/OnkosXcel |
| Isotopia Molecular Imaging |
| Bayer AG |
| Lantheus Holdings |
| Avacta Life Science |
| GE HealthCare |
| Others |
Supply & Pricing Matrix
Radiochemistry specialists concentrated in German and Swiss academic centers command wage premiums that compress margin spreads between economy-tier kit formulations and premium-grade theranostic conjugates. Labor-cost differentials between GMP-certified facility operators and hospital-based compounding sites drive pricing-tier stratification across European nuclear medicine departments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates cyclotron-network-integrated theranostic pairs from kit-based diagnostic agents and outsourced compounding arrangements. Price differentiation rests on GMP certification tier and same-day synthesis capability, with ISO 13485-validated facilities capturing premiums. Cost compression in economy-tier diagnostic kits is intensifying because hospital pharmacies are displacing external suppliers with in-house preparation systems. Academic medical centers with captive cyclotron infrastructure exhibit lowest price sensitivity, while community oncology clinics dependent on external isotope supply chains face acute budget constraints.
Supply Chain Analysis
Refurbishment flows for used cyclotron components and recycled radiometal sources create secondary supply channels that supplement primary isotope production networks. Geographic supply concentration centers on Germany, Belgium, and the Netherlands for gallium-68 generator manufacturing, with lutetium-177 production anchored in Germany and Poland. Raw material dependencies draw from enriched stable isotope feedstocks, specialized chelator chemicals, and clinical-grade peptide precursors. Single-source vulnerability pervades the gallium-68 generator segment where three European suppliers control installed base. Distribution runs through integrated cyclotron network operators capable of same-day isotope delivery to hospital pharmacy departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market is achievable through kit-format standardization that reduces per-dose labor content and shifts production economics toward outpatient-capable administration models.
For Market Incumbents: Extend cyclotron network coverage into underserved Central European markets to preempt competitor site-of-care capture. Deepen backward integration into isotope enrichment capabilities to offset supply concentration risk from Belgian and Dutch generator suppliers. Lock in long-term GMP radiochemistry talent pipelines through Swiss Federal Institutes of Technology partnerships. Prioritize FDA breakthrough therapy designation maintenance to preserve accelerated approval timelines against emerging radioligand competitors. For New Entrants and Emerging Players: The premium-to-economy pricing gap in diagnostic kit formulations offers white-space entry for modular preparation systems compatible with existing hospital cyclotron infrastructure. Target Austrian and Swiss community oncology clinics currently dependent on external compounding arrangements. Pursue subcutaneous formulation development to displace intravenous delivery dominance in outpatient settings. Establish go-to-market positioning through Helmholtz center research partnerships that validate tracer performance for multicenter trial inclusion. For Investors and Strategic Acquirers: Diversified pharmaceutical conglomerates with radioligand therapy divisions are the most active acquirers in this space, seeking tracer development expertise to complete theranostic platform integration. Long-term viability over the coming decade hinges on successful companion diagnostic synchronization with therapeutic pipelines. Acquisition targets should display GMP radiochemistry facility validation and established cyclotron network access rather than early-stage candidate libraries. Monitor FDA breakthrough therapy designation grants as inflection indicators for revenue realization window compression.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Helmholtz center coordination accelerates multicenter imaging validation across German university hospitals. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses validation timelines for novel FAP inhibitor candidates. |
| Manufacturing Scale-Up | GMP radiochemistry facility expansion addresses talent scarcity constraining contract development organization capacity. |
| Backward Integration | Cyclotron network operation secures isotope supply chains against gallium-68 generator concentration risk. |
| Pipeline Diversification | Fibrotic condition indications expand addressable market beyond oncology into interstitial lung disease imaging. |
Research Methodology
Direct dialogue with nuclear medicine department heads, hospital pharmacy directors, radiochemistry facility operators, and regulatory affairs specialists at EMA and FDA combined with secondary validation. Primary fieldwork drew from FDA investigational new drug filings, EMA centralized marketing authorization procedures, ClinicalTrials.gov protocol registries, and German Federal Institute for Drugs and Medical Devices approval databases. Secondary sources encompassed ISO 13485 quality management standards documentation, GMP radiochemistry guidelines, and hospital procurement records from German university hospital systems. Bottom-up demand modeling from installed cyclotron base and top-down market sizing from radiopharmaceutical revenue flows underwent iterative triangulation.
Segmentation outputs across product type, therapy area, delivery mode, and end user categories structured the analytical framework throughout the projection horizon. Modeled dimensions included kit-based versus centralized manufacturing formats, oncology versus fibrotic condition applications, intravenous versus subcutaneous administration routes, and academic medical center versus community clinic demand clusters. CAGRs derived from patient volume projections tied to PET imaging protocol expansion rates and reimbursement pathway maturation across national health technology assessment bodies. Forecast inputs incorporated cyclotron network capacity buildout schedules and radiochemistry workforce pipeline data from Swiss and German technical universities.
Caveats apply where EMA centralized authorization timelines or FDA rolling review eligibility shifts could materially shift the outlook for revenue realization windows. Forecasts reflect assumptions regarding isotope supply chain stability and reimbursement negotiation outcomes across European markets. Practitioners should monitor FDA breakthrough therapy designation grants and Helmholtz center trial coordination announcements for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Canada Specialty Pharmacy Market
Pharmaceuticals
MRSA Antibiotic Preparations Market
Pharmaceuticals
Global Non-Small Cell Lung Cancer Drugs Market
Pharmaceuticals
Depression and Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Glioblastoma Treatment Drugs Market
Pharmaceuticals
Isotretinoin Drugs Market
Pharmaceuticals
Fusion Inhibitors Market
Pharmaceuticals
Liver Fibrosis Drugs Market
Pharmaceuticals
Global Monoclonal Antibody Therapeutics Market
Pharmaceuticals
Over-The-Counter (OTC) Analgesics Market
Pharmaceuticals
Global Prophylactic HIV Drugs Market
Pharmaceuticals
Finland Pharmaceutical Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis Drugs Pipeline Market
Pharmaceuticals
Flunarizine Hydrochloride Market
Pharmaceuticals
OTC Analgesic Market
Pharmaceuticals
Monkeypox Vaccine and Treatment Market