
 Intestinal Pseudo-Obstruction Treatment Market | 2026-2036
Intestinal Pseudo-Obstruction Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Intestinal Pseudo-Obstruction Treatment Market Foresight
Specialized gastrointestinal pharmaceutical manufacturing in North America is pivoting toward orphan and niche motility indications. Teva Pharmaceutical Industries Ltd. leverages its generic formulation expertise to supply cost-accessible prokinetic therapies across hospital systems. GlaxoSmithKline plc sustains a research footprint in neurogastroenterology that anchors its presence in prescription motility agents. Pfizer Inc. competes through established urology-gastroenterology crossover portfolios that extend into off-label prescriptive patterns for pseudo-obstruction management.
Intestinal pseudo-obstruction treatment encompasses pharmacological, surgical, nutritional, and rehabilitative interventions targeting impaired bowel motility without mechanical obstruction, typically involving prokinetic agents such as metoclopramide or erythromycin that stimulate cholinergic or motilin receptor pathways to restore peristaltic coordination. The primary purpose is to prevent intestinal failure, reduce parenteral nutrition dependency, and avert surgical resection in chronic or idiopathic presentations. Medication categories dominate current prescription volumes, though nutritional support segments command durable margin pools due to long-term home parenteral and enteral supply contracts. Hospital end users concentrate the highest acuity cases, while homecare channels represent the fastest-growing delivery setting as payors push for post-stabilization outpatient management.
The FDA orphan drug program and EMA's incentives for rare disease therapeutics shape trial design and market access pathways for novel prokinetic compounds. Health Canada's PMRA and the TGA impose distinct bioequivalence and manufacturing standards that fragment regulatory submission strategies across developed markets. Stakeholders must monitor pipeline progression in ghrelin agonists and interstitial cell-targeted therapies while calibrating reimbursement negotiations against evolving parenteral nutrition cost benchmarks.
Market Dynamics
Hospital-based gastroenterology departments are consolidating chronic intestinal motility disorder care into integrated pathways, concentrating patient volumes at tertiary referral centers and reshaping how prokinetic therapies are prescribed, reimbursed, and monitored across acute and post-acute settings.
Growth Catalysts
- FDA Orphan Drug Incentives:The FDA's breakthrough therapy and orphan drug designations accelerate clinical trial investment for rare gastrointestinal conditions, compressing development timelines for novel prokinetic compounds.
- Home Parenteral Nutrition Expansion:Payors in the United States are pushing post-stabilization management into homecare channels, creating durable demand for long-term nutritional support contracts and remote monitoring infrastructure.
- Ghrelin Agonist Pipeline Activity:Pharmaceutical developers are advancing interstitial cell-targeted therapies through late-stage trials, promising mechanistic alternatives to existing cholinergic and motilin receptor approaches.
Market Restraints
- Specialized Manufacturing Concentration:North American contract manufacturers dominate sterile prokinetic formulation capacity, creating geographic supply vulnerability and limited second-source options for hospital systems.
- Bioequivalence Fragmentation:Health Canada's PMRA and Australia's TGA impose distinct dissolution and impurity standards that force redundant regulatory submissions, inflating market access costs for multinational sponsors.
- Long-Term Erythromycin Limitations:Antibiotic prokinetics face diminishing efficacy and resistance concerns with extended use, constraining chronic therapy options without adequate mechanistic substitutes.
Strategic Opportunities
- EMA Rare Disease Incentives:The European Medicines Agency's PRIME designation and pediatric investigation plans offer expedited assessment pathways for novel motility agents targeting pediatric pseudo-obstruction subtypes.
- Neurogastroenterology Convergence:Integration of high-resolution manometry with ambulatory wireless motility capsule systems enables personalized therapy selection based on regional transit patterns rather than empirical protocols.
- Rehabilitative Channel Development:Specialized intestinal rehabilitation centers in Germany and the Netherlands demonstrate scalable models for multidisciplinary chronic care that reduce parenteral nutrition dependency.
Industry Challenges
- Neurogastroenterology Specialist Scarcity:Fellowship-trained motility specialists remain concentrated at academic medical centers, creating diagnostic bottlenecks and delayed care access for refractory cases.
- Legacy EHR Integration Friction:Ambulatory motility monitoring data lacks standardized interoperability with hospital electronic health record systems, complicating longitudinal care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intestinal Pseudo-Obstruction Treatment Market |
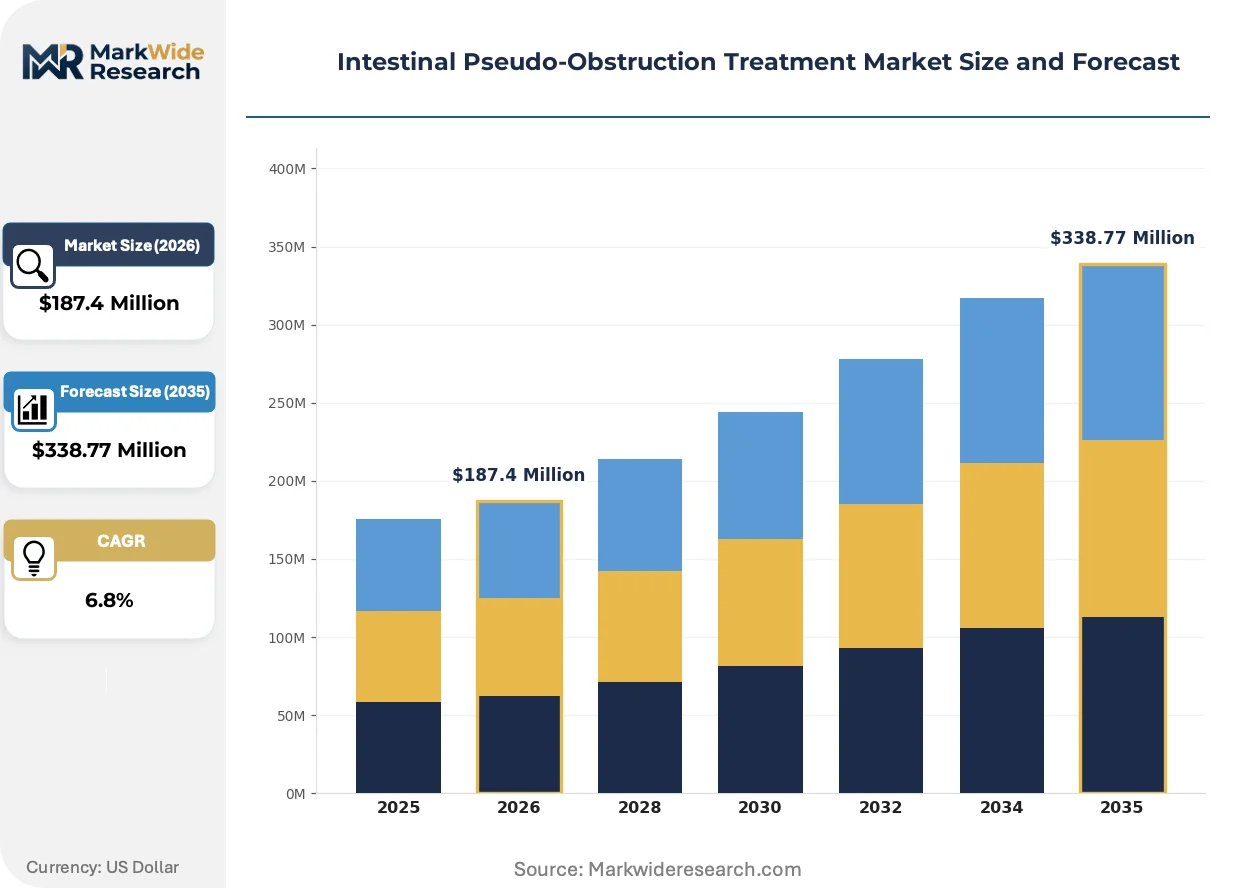
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication, Surgery, Nutritional Support, Physical Therapy Application: Symptomatic Relief, Long-term Management, Diagnostic Procedures, Postoperative Care End User: Hospitals, Homecare, Outpatient Clinics, Rehabilitation Centers Treatment Strategy: Pharmacological, Surgical Intervention, Dietary Modification, Integrated Care |
| Companies Covered | Dr. Reddy's Laboratories Ltd., Teva Pharmaceutical Industries Ltd., GlaxoSmithKline plc, Abbott Laboratories, Pfizer Inc., Johnson & Johnson, Takeda Pharmaceutical Company Limited, Ironwood Pharmaceuticals, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intestinal Pseudo-Obstruction Treatment Market Shifts & Advancements
Novel prokinetic mechanisms and digital biomarker platforms are displacing empirical prescribing patterns, while regulatory incentives and reimbursement redesign accelerate the shift from acute intervention toward chronic disease management infrastructure.
Wireless motility capsule systems that measure regional and whole-gut transit times are overtaking traditional radiopaque marker studies in tertiary referral centers. Gastroenterology departments at academic medical centers in the United States and Germany are adopting these devices for pre-treatment phenotyping and therapy monitoring. The technology is overtaking functional assessment protocols by enabling objective, ambulatory measurement that aligns reimbursement with documented physiological response rather than symptom reporting alone.
The FDA's breakthrough therapy designation pathway for serious rare diseases is compressing Phase 2-to-approval timelines for ghrelin receptor agonists and 5-HT4 selective compounds. Sponsors receiving this designation gain intensive agency guidance and rolling review privileges that reduce regulatory risk capital. Hospital pharmacy and therapeutics committees in the United States are responding by establishing early access protocols and budget impact models ahead of formal launch.
Site-of-care contracting is consolidating purchasing authority for high-cost nutritional therapies at the integrated delivery network level rather than individual hospital pharmacy departments. Large US health systems including Kaiser Permanente and Mayo Clinic are centralizing parenteral nutrition formulary decisions with mandatory home infusion network participation. This concentration is most visible in Medicare Advantage populations where total cost of care contracts incentivize outpatient stabilization and readmission avoidance.
Intestinal Pseudo-Obstruction Treatment Market Segmentation
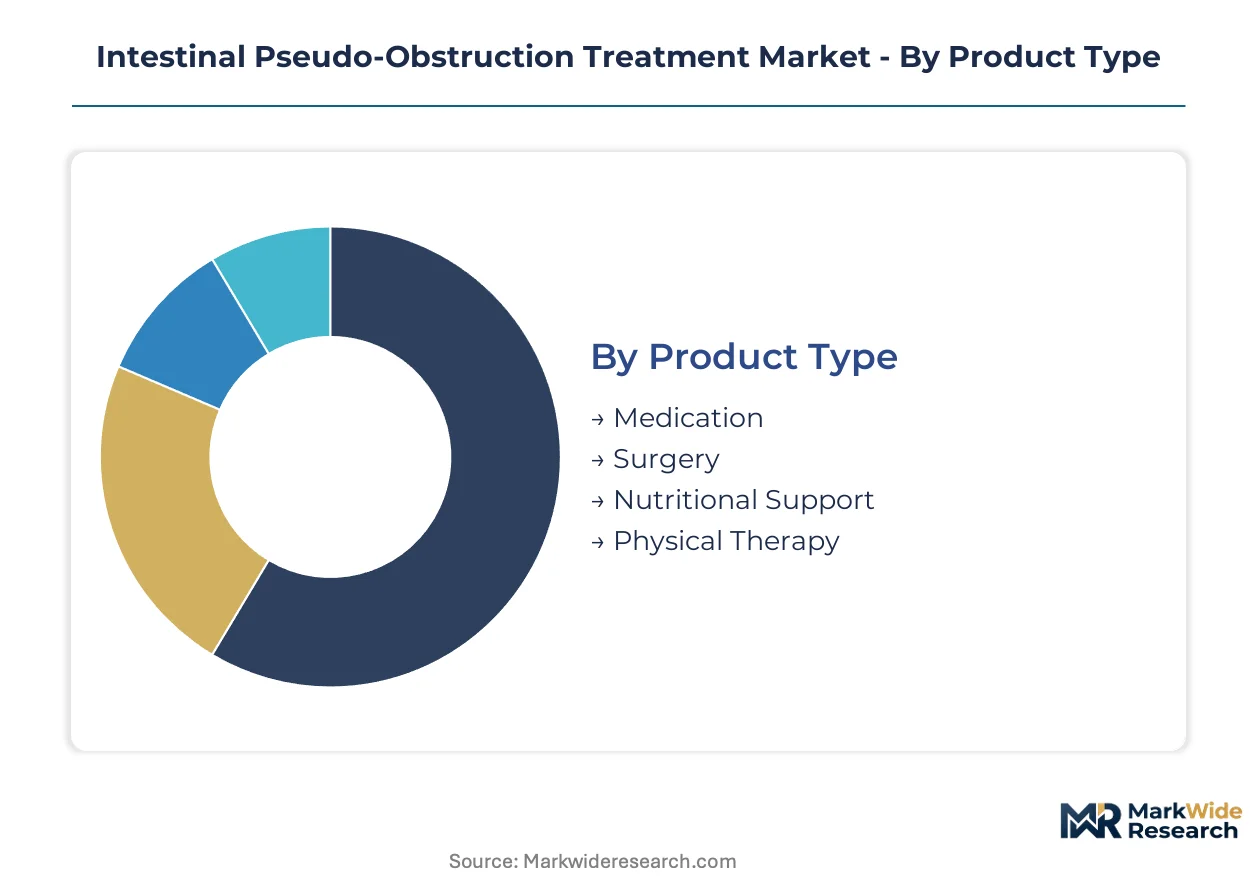
Treatment pathways for intestinal pseudo-obstruction fragment across intervention modalities, care settings, and therapeutic objectives. Segmentation clarity enables stakeholders to align R&D investment, reimbursement negotiation, and distribution infrastructure with specific patient trajectories and acuity levels.
Product Type:
Replacement cycles vary sharply across intervention categories, with pharmaceutical formulations turning over faster than surgical implants or durable nutritional delivery systems.
- Medication:Prokinetic agents including metoclopramide, erythromycin, and emerging ghrelin agonists dominate prescription volumes through oral and intravenous formulations. Hospital formularies in the United States prioritize generic-accessible cholinergic stimulants for acute decompensation episodes, though resistance limitations with macrolide prokinetics constrain chronic deployment.
- Nutritional Support:Parenteral nutrition formulations and enteral feeding systems address intestinal failure in refractory cases, with home infusion contracts creating durable revenue streams. Medicare Advantage payors in the United States are consolidating purchasing authority at integrated delivery network levels, centralizing formulary decisions and mandatory network participation.
- Surgery:Decompression procedures, stoma creation, and intestinal transplantation reserve for pharmacologically refractory presentations requiring anatomical intervention.
- Physical Therapy:Abdominal wall rehabilitation and neuromuscular electrical stimulation protocols support motility recovery in postoperative and chronic ambulatory populations.
Volume placements concentrate in Medication; the faster expansion belongs to Nutritional Support.
Application:
Margin profiles diverge by clinical objective, with acute symptomatic interventions commanding premium pricing against subscription-like long-term management contracts.
- Long-term Management:Chronic therapy protocols combine rotating prokinetic regimens with nutritional support to prevent intestinal failure and reduce parenteral nutrition dependency. Tertiary referral centers in Germany and the Netherlands have developed scalable rehabilitation models that demonstrate reduced dependency through multidisciplinary care coordination.
- Symptomatic Relief:Acute decompression and nausea control address episodic exacerbations, typically in emergency department or inpatient gastroenterology settings. The FDA's breakthrough therapy designation pathway is compressing Phase 2-to-approval timelines for novel agents targeting acute motility restoration.
- Diagnostic Procedures:Wireless motility capsule systems and high-resolution manometry enable phenotyping prior to therapy selection, displacing empirical protocols in academic medical centers.
- Postoperative Care:Ileus prevention and motility restoration following abdominal surgery represent a crossover indication where pseudo-obstruction therapies see off-label utilization.
Revenue concentration sits with Long-term Management; Diagnostic Procedures are climbing the fastest as phenotyping becomes prerequisite to reimbursement.
End User:
Site-of-care migration is redistributing patient volumes from inpatient beds toward ambulatory and domestic settings, reshaping supply chain and service delivery requirements.
- Hospitals:Tertiary academic medical centers concentrate the highest-acuity refractory cases requiring multimodal intervention and surgical consultation. Fellowship-trained neurogastroenterology specialists remain scarce outside these institutions, creating diagnostic bottlenecks.
- Homecare:Post-stabilization parenteral nutrition and remote motility monitoring represent the steepest expansion trajectory as payors push cost avoidance through readmission prevention. Large US health systems including Kaiser Permanente and Mayo Clinic are mandating home infusion network participation.
- Outpatient Clinics:Community gastroenterology practices manage stable chronic cases with periodic prokinetic adjustment and nutritional monitoring.
- Rehabilitation Centers:Specialized intestinal rehabilitation facilities in Germany and the Netherlands demonstrate multidisciplinary models for reducing parenteral nutrition dependency through coordinated medical, nutritional, and physical therapy intervention.
Patient volumes still anchor in Hospitals; Homecare channels are gaining share fastest through payor-mandated site-of-care migration.
Treatment Strategy:
Integration intensity separates competitive approaches, with single-modality protocols yielding to coordinated care pathways that align pharmaceutical, nutritional, and rehabilitative interventions.
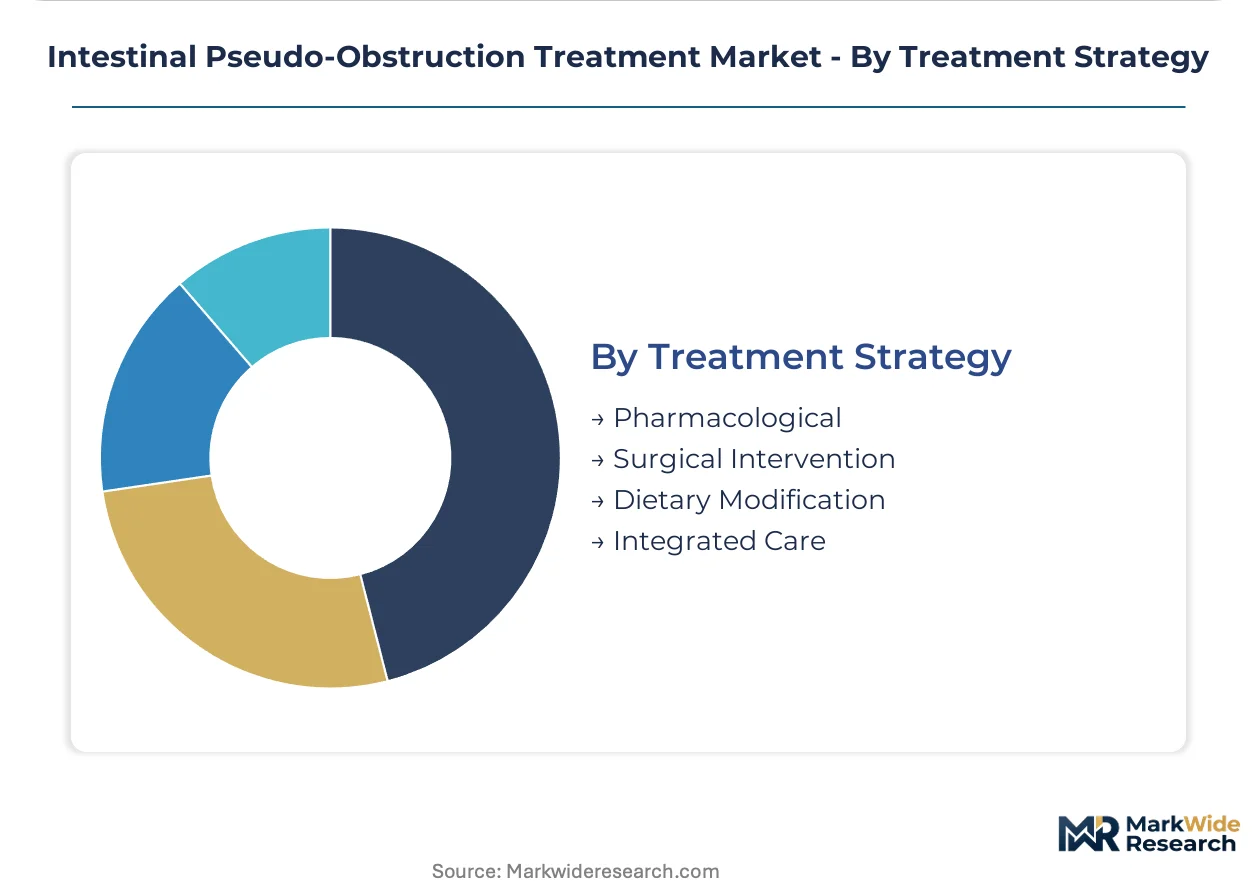
- Pharmacological:Cholinergic agonists, motilin receptor agonists, and emerging ghrelin receptor-targeted compounds form the intervention backbone, though long-term erythromycin efficacy erosion creates unmet need for mechanistic alternatives.
- Integrated Care:Multidisciplinary protocols combining medical, nutritional, surgical, and rehabilitative expertise demonstrate superior outcomes in reducing parenteral nutrition dependency and delaying transplantation. EMA rare disease incentives including PRIME designation and pediatric investigation plans are accelerating assessment pathways for novel agents targeting pediatric pseudo-obstruction subtypes.
- Surgical Intervention:Decompression, bypass, and transplantation reserve for intestinal failure refractory to conservative management.
- Dietary Modification:Enteral nutrition optimization and specialized formula selection support motility preservation in partial obstruction presentations.
Clinical investment concentrates in Pharmacological approaches; Integrated Care is expanding most quickly as outcome-based reimbursement rewards coordination.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing for prokinetic therapies clusters in the United States, Germany, India, Japan, and Switzerland. These countries concentrate sterile formulation capacity, regulatory expertise, and tertiary referral infrastructure for rare motility disorders.
United States
Tertiary academic medical centers in Boston and Houston manage the highest volumes of refractory intestinal pseudo-obstruction cases requiring multimodal intervention. The FDA's orphan drug incentives and breakthrough therapy designations accelerate clinical trial investment for novel ghrelin agonists. Philadelphia-area contract manufacturers dominate sterile prokinetic formulation capacity serving hospital systems nationwide.
Germany
Specialized intestinal rehabilitation centers in Munich and Hamburg demonstrate scalable multidisciplinary models reducing parenteral nutrition dependency. The EMA's PRIME designation offers expedited assessment pathways for pediatric pseudo-struction subtypes. Baden-Württemberg hosts concentrated neurogastroenterology research clusters advancing interstitial cell-targeted therapies.
India
Hyderabad and Ahmedabad-based API manufacturers supply cost-accessible generic prokinetic intermediates to multinational formulation facilities. CDSCO's accelerated approval pathways for orphan indications are attracting contract research investment from European sponsors. Maharashtra's sterile injectable manufacturing corridor is expanding capacity for complex peptide-based motility agents.
Japan
PMDA's sakigake designation system compresses review timelines for first-in-class prokinetic mechanisms addressing unmet motility needs. Tokyo and Osaka academic hospitals lead Asia-Pacific adoption of wireless motility capsule systems for pre-treatment phenotyping. Kansai-region pharmaceutical clusters maintain active research footprints in 5-HT4 selective compounds.
Switzerland
Basel-area biopharma operations anchor European development of ghrelin receptor agonists through late-stage clinical programs. Swissmedic's streamlined rare disease approval pathways facilitate early market access for novel motility therapeutics. The country's specialized logistics infrastructure supports temperature-sensitive parenteral nutrition distribution across Alpine markets.
Intestinal Pseudo-Obstruction Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue interstitial cell-targeted mechanisms and digital motility diagnostics. The market structure reflects moderate consolidation around diversified pharmaceutical conglomerates with orphan disease capabilities. Three archetypes dominate: generic prokinetic suppliers with hospital formulary penetration, integrated nutrition therapy providers with home infusion networks, and specialty biopharma developers advancing mechanistically novel compounds. Competitive intensity centers on M&A activity targeting motility-focused biotech assets and strategic partnerships securing site-of-care contracting authority.
Within the generic-accessible tier, Teva Pharmaceutical Industries Ltd. and Dr. Reddy's Laboratories Ltd. exemplify manufacturers leveraging formulation expertise to supply cost-sensitive prokinetic therapies across hospital systems. GlaxoSmithKline plc occupies a position among research-anchored conglomerates sustaining neurogastroenterology capabilities that inform prescription motility agent development. Pfizer Inc. sits within the diversified therapeutic portfolio archetype, with established urology-gastroenterology crossover assets extending into off-label prescriptive patterns for pseudo-obstruction management.
| Leading Market Players |
|---|
| Dr. Reddy's Laboratories Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| GlaxoSmithKline plc |
| Abbott Laboratories |
| Pfizer Inc. |
| Johnson & Johnson |
| Takeda Pharmaceutical Company Limited |
| Ironwood Pharmaceuticals |
| Novartis AG |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up hospital infusion networks in the United States have consolidated purchasing authority for parenteral nutrition therapies, compressing formulary margins while creating captive demand pools that insulate contracted suppliers from spot-market volatility. This ownership pattern concentrates downstream pricing power within integrated delivery networks while fragmenting upstream API sourcing across multiple regulatory jurisdictions.
Pricing Analysis
Warranty and service bundling separates premium-tier prokinetic suppliers from commodity competitors, with comprehensive home monitoring and 24-hour nursing support commanding substantial markups over unbundled pharmaceutical-only contracts. Three-tier pricing structure across premium, standard, and economy levels reflects FDA breakthrough designation status, generic bioequivalence certification, and volume commitment scale. Cost compression in the standard tier is intensifying because Medicare Advantage payors are mandating mandatory home infusion network participation. Hospital pharmacy and therapeutics committees demonstrate lowest price sensitivity for acute inpatient prokinetic formulations, while homecare channels exhibit highest sensitivity due to total cost of care contract structures.
Supply Chain Analysis
Direct-to-hospital channels handle acute inpatient demand for sterile prokinetic formulations, while home infusion networks manage post-stabilization nutritional therapy distribution. Active pharmaceutical ingredient manufacturing concentrates in India, Switzerland, and the United States, with sterile formulation capacity clustering in Pennsylvania and Baden-Württemberg. Peptide-based motility agents and specialized enteral nutrition substrates draw from biologics manufacturing corridors with limited second-source alternatives. Single-source vulnerability pervades the sterile injectable segment because FDA validation timelines for alternative suppliers extend across multi-year horizons. Distribution runs through integrated delivery network central warehouses rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sterile formulation capacity scarcity props pricing discipline across the prokinetic therapy landscape, with validated manufacturing slots commanding premium allocations from sponsors seeking accelerated regulatory pathways.
For Market Incumbents: Acquire late-stage ghrelin agonist pipelines to secure mechanistic differentiation against emerging interstitial cell-targeted competitors. Expand backward integration into peptide API manufacturing through partnerships with Hyderabad and Ahmedabad-based suppliers to reduce exposure to CDSCO regulatory delays. Lock in exclusive site-of-care contracting with Kaiser Permanente and Mayo Clinic-tier health systems before reimbursement consolidation hardens. For New Entrants and Emerging Players: Begin with wireless motility capsule distribution partnerships in German and Dutch intestinal rehabilitation centers, where phenotyping infrastructure investment outpaces supply. Target pediatric pseudo-obstruction subtypes eligible for EMA PRIME designation, a white-space segment with expedited assessment pathways and limited incumbent presence. Pursue direct-to-specialist commercial models bypassing hospital pharmacy and therapeutics committee gatekeeping through ambulatory clinic relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap biopharma developers with FDA breakthrough therapy designations in neurogastroenterology but constrained commercial infrastructure in the United States. Long-term viability across the analysis window hinges on pipeline progression toward interstitial cell-targeted mechanisms that displace legacy cholinergic approaches. Watch FDA orphan drug grant awards as the inflection signal indicating agency prioritization of specific motility indications.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Designation Pursuit | Compresses Phase 2-to-approval timelines for ghrelin receptor agonists through intensive agency guidance. |
| Home Infusion Network Partnership | Secures mandatory participation status within Medicare Advantage total cost of care contracts. |
| EMA PRIME Designation Application | Unlocks expedited assessment pathways for pediatric pseudo-obstruction subtypes with unmet need. |
| Wireless Motility Capsule Integration | Enables objective phenotyping that aligns reimbursement with documented physiological response. |
| Sterile Manufacturing Scale-Up | Addresses single-source vulnerability in peptide-based prokinetic formulation capacity. |
Research Methodology
Multi-period observation of FDA orphan drug grant awards, EMA PRIME designations, and Medicare Advantage formulary consolidations anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, ClinicalTrials.gov protocol registries, EMA submission databases, and integrated delivery network annual reports. Bottom-up prescription volume modeling and top-down reimbursement expenditure analysis were triangulated against sterile manufacturing capacity disclosures.
Segment-weighting across product type, application, end user, and treatment strategy dimensions informed the analytical framework over the projection horizon. CAGRs were derived from fitted growth curves applied to patient prevalence estimates, therapy penetration rates, and pricing trajectory assumptions. Forecast inputs incorporated orphan drug incentive utilization rates, home parenteral nutrition expansion patterns, and neurogastroenterology specialist fellowship graduation volumes.
Underlying measurement precision varies by segment; hospital-based medication volumes carry tighter precision than emerging homecare channel estimates due to claims data availability differences. Forecasts reflect assumptions regarding regulatory pathway efficiency, reimbursement stability, and manufacturing capacity expansion timelines. Periodic stress-testing of base assumptions against FDA approval velocity and payor policy shifts is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Acute Pancreatitis Market
Gastroenterology
Gastroesophageal Junction Adenocarcinoma Therapeutics Market
Gastroenterology
Biliary Tract Cancers (Btcs) Treatment Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market
Gastroenterology
Chronic Liver Diseases Therapeutics Market
Gastroenterology
Gastric Cancer Market
Gastroenterology
Gluten Intolerance Treatment Market
Gastroenterology
Malabsorption Syndrome Treatment Market
Gastroenterology
Intestinal Fistula Treatment Market
Gastroenterology
Polyps Market
Gastroenterology
Inflammatory Bowel Disease Market
Gastroenterology
Ultrasound Gastroscopes Market
Gastroenterology
Colon Hydrotherapy Market
Gastroenterology
Necrotic Enteritis Treatment Market
Gastroenterology
Fecal Incontinence Market
Gastroenterology
Inflammatory Bowel Disease Treatment Market