
 Acute Pancreatitis Market | 2026-2036
Acute Pancreatitis Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Pancreatitis Market Analysis
Precision biologic manufacturing is fragmenting traditional small-molecule dominance in acute pancreatitis therapeutics. AbbVie Inc. leverages its immunology infrastructure to develop cytokine-modulating approaches for severe cases. Baxter International Inc. anchors the critical-care segment through parenteral nutrition and fluid resuscitation portfolios. CalciMedica Inc. differentiates by specializing in calcium-channel antagonists targeting early-phase inflammatory cascades.
Acute pancreatitis constitutes a sudden inflammatory condition of the pancreas characterized by autodigestion from prematurely activated proteolytic enzymes, with severity graded by the Revised Atlanta Criteria based on organ failure duration and local complications. The condition serves industrial purpose by driving pharmaceutical development across anti-inflammatory, anti-secretory, and supportive therapeutic categories. Medications dominate current revenue pools through broad-spectrum applicability across severity grades, while Enzymes represent the fastest-expanding segment as pancreatic replacement therapies gain protocol integration. Intravenous delivery mode commands the highest clinical utilization in hospital settings where nil-per-os status mandates parenteral administration.
The FDA governs new drug approvals and post-market surveillance for pancreatitis therapeutics through its Center for Drug Evaluation and Research, while the EMA's Committee for Medicinal Products for Human Use establishes parallel standards across European markets. The EU's Medical Device Regulation and GDPR-compliant clinical data frameworks shape diagnostic kit commercialization and multi-center trial conduct. Japan's PMDA accelerates reviews for severe acute pancreatitis therapies under its Sakigake designation system. Stakeholders must monitor evolving biomarker-qualified surrogate endpoints that could compress trial durations and reshape competitive entry sequencing.
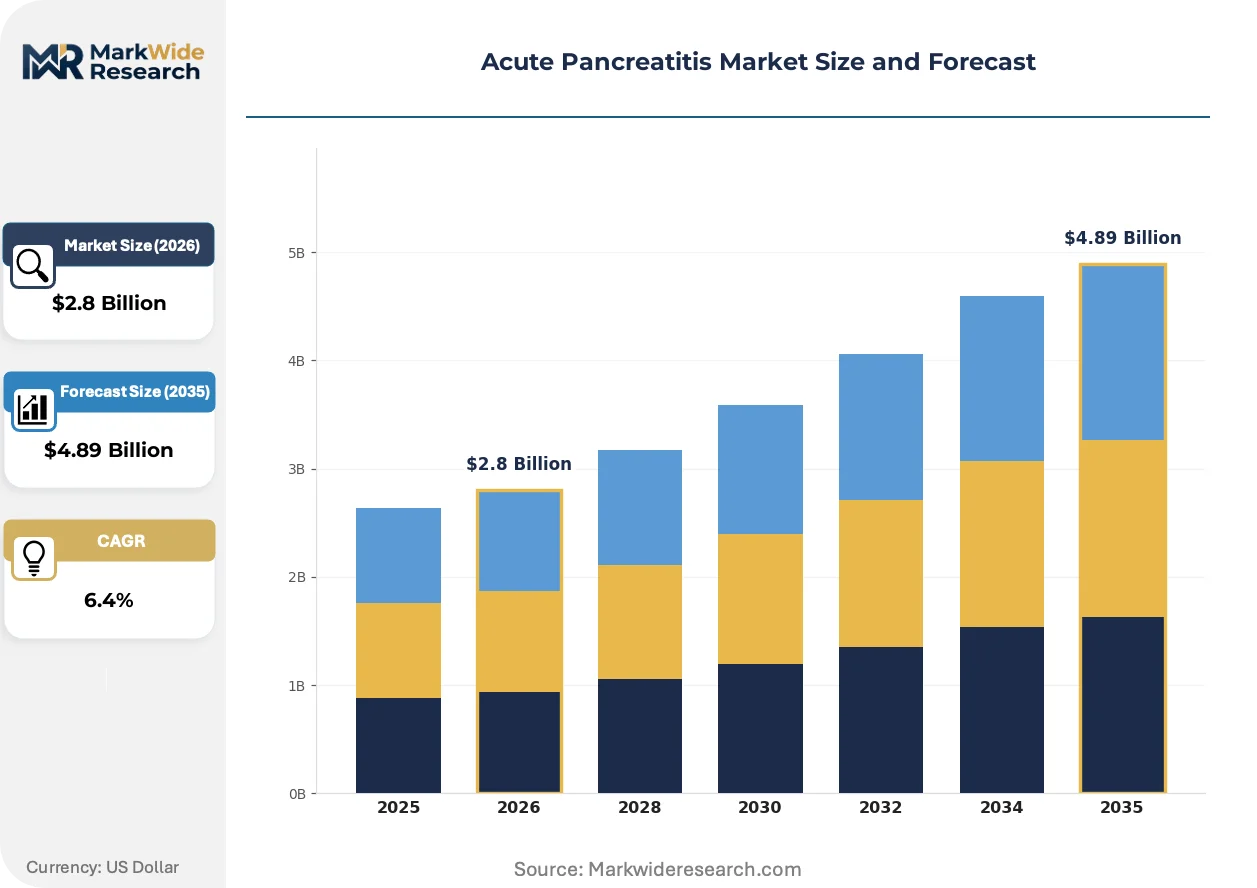
Market Dynamics
FDA accelerated approval pathways for critical-care biologics are compressing development timelines and fragmenting traditional small-molecule dominance in acute pancreatitis therapeutics. Hospital-based gastroenterology departments drive protocol integration of targeted enzyme therapies.
Growth Catalysts
- PMDA Sakigake designation:Japan's priority review system for severe acute pancreatitis therapies is shortening regulatory timelines and attracting biologic developers to file first in Tokyo.
- Tertiary care infrastructure expansion:Hospital construction in Germany and the United States is adding dedicated pancreatitis units with integrated critical-care biologic administration capabilities.
- Biomarker-qualified surrogate endpoints:Evolving FDA guidance on inflammatory markers is enabling smaller, faster Phase III trials for novel anti-cytokine approaches.
Market Restraints
- Plasma-derived enzyme input costs:Volatility in porcine pancreas sourcing and fractionation capacity constraints are squeezing margins for pancreatic replacement therapy manufacturers.
- Single-source parenteral nutrition lipids:Concentration of intravenous lipid emulsion supply among three European contract manufacturers creates vulnerability for fluid resuscitation protocols.
- Revised Atlanta Criteria diagnostic heterogeneity:Inconsistent severity grading across emergency departments complicates trial enrollment and label expansion for targeted therapies.
Strategic Opportunities
- Underpenetrated Indian tertiary sector:CDSCO's streamlined approval for critical-care biologics is opening private hospital chains in Mumbai and Delhi to advanced pancreatitis management.
- Home-infusion channel development:Post-acute enzyme replacement therapy is shifting from hospital discharge to specialty pharmacy home delivery models in the United States.
- Calcium-channel antagonist convergence:CalciMedica's early-phase inflammatory cascade approach is creating white space for combination protocols with existing anti-secretory agents.
Industry Challenges
- Critical-care trial recruitment:Severe acute pancreatitis patient identification and consent within narrow therapeutic windows requires specialized site networks.
- Legacy EMR integration:Hospital IT systems struggle to incorporate real-time severity scoring algorithms into existing pancreatitis order sets.
- Biologic cold-chain integrity:Temperature excursion risks during intravenous administration in busy emergency departments compromise cytokine-modulating drug stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Pancreatitis Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Enzymes, Nutritional Supplements, Diagnostic Kits End User: Hospitals, Outpatient Clinics, Homecare Settings, Rehabilitation Centers Therapy Area: Gastroenterology, Pain Management, Emergency Medicine, Nutritional Therapy Delivery Mode: Oral, Injectable, Intravenous, Topical |
| Companies Covered | AbbVie Inc., Amgen Inc., Merck & Co., Inc., Johnson & Johnson, Pfizer Inc., Novartis AG, Baxter International Inc., CalciMedica Inc., Fresenius SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Pancreatitis Market Emerging Trajectories
Precision biologic manufacturing is fragmenting traditional small-molecule dominance across acute pancreatitis therapeutics. Three distinct shifts are reshaping competitive positioning and clinical protocol design.
Targeted enzyme replacement therapies are migrating from post-acute oral supplementation to intra-hospital parenteral administration during nil-per-os status. Gastroenterology departments at tertiary centers in the United States and Germany are adopting these protocols within 48 hours of admission. This migration from delayed replacement to early intervention is compressing the window for competitor small-molecule anti-secretory agents.
REACH-compliant biomarker frameworks are harmonizing inflammatory endpoint qualification across European multi-center trials. EMA's Committee for Medicinal Products for Human Use is accepting C-reactive protein and procalcitonin trajectories as surrogate efficacy measures. Severe acute pancreatitis biologic developers targeting EU market access are restructuring Phase II programs around these qualified endpoints.
Hospital procurement committees are consolidating vendor relationships for critical-care pancreatitis bundles. Integrated parenteral nutrition, fluid resuscitation, and enzyme therapy contracts are displacing single-product purchasing at large health systems in Japan and the United States. This concentration is most visible in Tokyo's metropolitan hospital alliance, where three-year sole-source agreements now dominate category management.
Acute Pancreatitis Market Segmentation
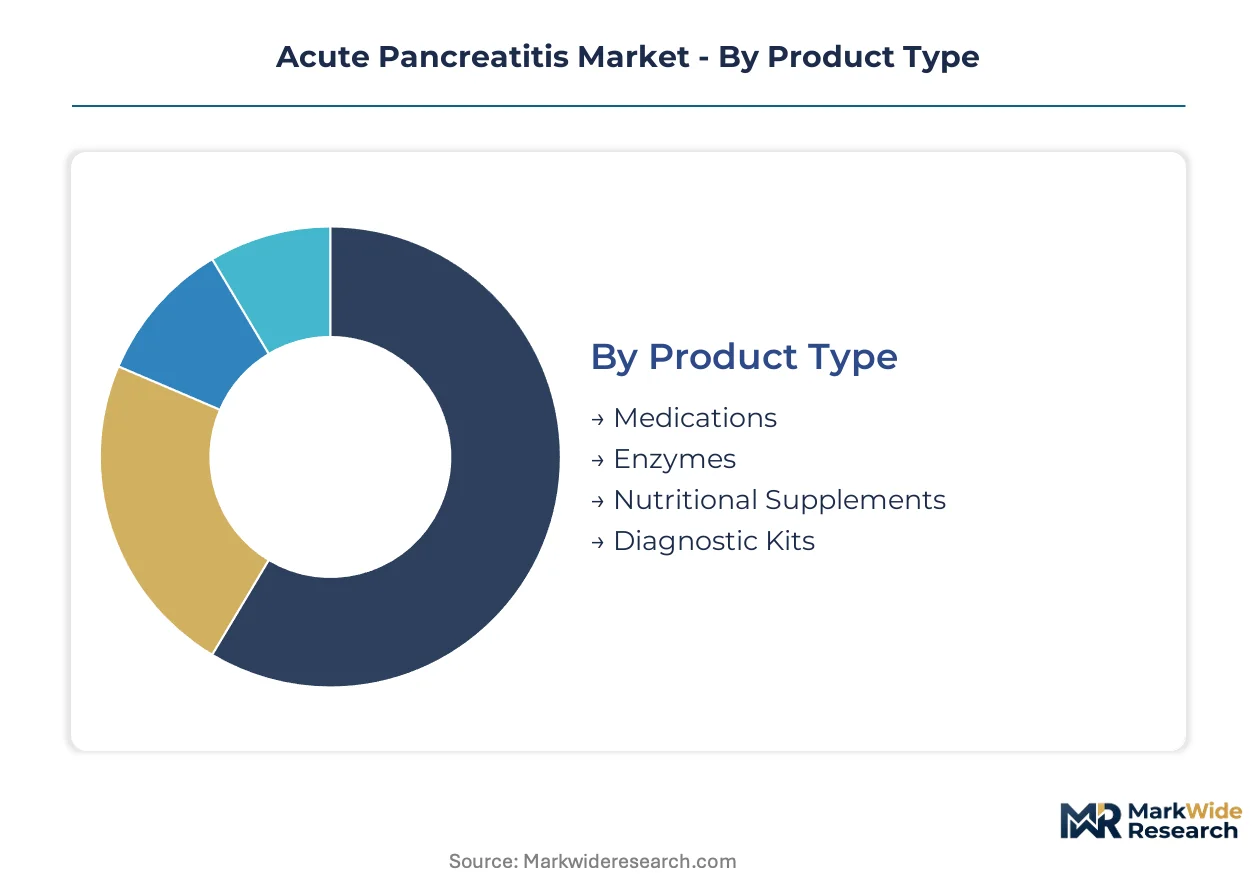
Acute pancreatitis therapeutics fragment across therapeutic intent, care setting, and administration route. Each dimension shapes procurement patterns and protocol integration differently across tertiary hospital networks.
Product Type:
Use-case spectrum spans immediate symptom control through long-term metabolic restoration, with each tier demanding distinct manufacturing scale and regulatory pathway.
- Medications:Broad-spectrum anti-inflammatory and anti-secretory agents address proteolytic enzyme activation across all severity grades. Hospital formularies in the United States and Germany stock these for first-line emergency intervention, though generic erosion compresses margins for small-molecule developers.
- Enzymes:Pancreatic replacement therapies shift from post-acute oral supplementation to early parenteral administration during nil-per-os status. Tertiary gastroenterology departments in Japan and the United States are adopting these protocols within 48 hours of admission, displacing delayed replacement models.
- Nutritional Supplements:Enteral and parenteral formulations support metabolic recovery in prolonged cases.
- Diagnostic Kits:Serum amylase, lipase, and imaging biomarker assays enable rapid severity stratification.
Established volume favors Medications; emerging adoption favors Enzymes.
End User:
Care setting concentration determines reimbursement pathway and product configuration, with acute-phase intervention concentrating in institutional settings while recovery phases migrate outward.
- Hospitals:Tertiary centers command critical-care biologic administration, parenteral nutrition delivery, and 24-hour severity monitoring. Japan's metropolitan hospital alliances and German university hospitals anchor demand through dedicated pancreatitis units with integrated intensive care.
- Outpatient Clinics:Post-acute monitoring and enzyme titration occur in gastroenterology specialty practices. United States ambulatory surgery centers are expanding same-day diagnostic capabilities for mild cases.
- Homecare Settings:Specialty pharmacy networks deliver post-discharge enzyme replacement and nutritional support.
- Rehabilitation Centers:Extended metabolic recovery programs address alcohol-related recurrence prevention.
Revenue concentration sits with Hospitals; patient volume expansion is climbing the fastest in Homecare Settings.
Therapy Area:
Specialist ownership of the patient journey creates siloed procurement with limited cross-departmental coordination.
- Gastroenterology:Departmental protocols govern endoscopic intervention, enzyme replacement timing, and severity scoring. Academic medical centers in the United States and Germany drive adoption of early parenteral enzyme therapy.
- Pain Management:Opioid-sparing multimodal approaches are gaining protocol integration in severe cases.
- Emergency Medicine:Rapid diagnostic triage and fluid resuscitation initiation occur before specialist consultation.
- Nutritional Therapy:Clinical dietitians manage enteral feeding advancement and parenteral lipid composition.
Therapeutic control concentrates in Gastroenterology; protocol innovation is expanding most quickly in Pain Management.
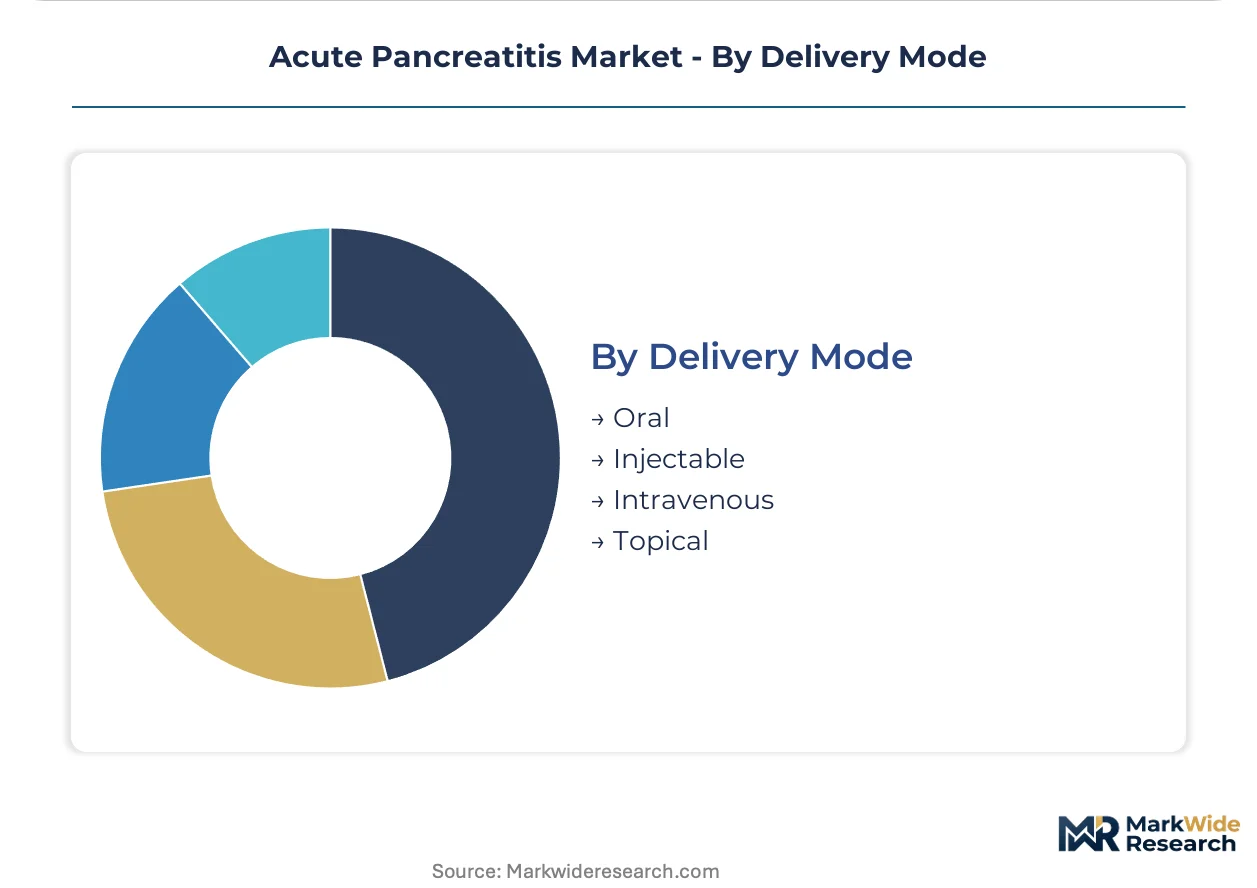
Delivery Mode:
Route selection tracks disease severity and gastrointestinal functional status, with nil-per-os mandates driving parenteral dominance in acute phases.
- Intravenous:Fluid resuscitation, parenteral nutrition, and critical-care biologics require vascular access in hospitalized severe cases. Emergency departments in the United States and Japan utilize this route exclusively during initial 48-72 hour nil-per-os protocols.
- Injectable:Subcutaneous enzyme preparations and anti-cytokine agents bridge hospital and home settings.
- Oral:Enteric-coated enzyme replacement and anti-secretory agents resume post-acute.
- Topical:Limited application for skin complications in necrotizing cases.
Clinical utilization peaks with Intravenous; post-acute transition is gaining share fastest in Oral delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for critical-care biologics and parenteral nutrition concentrates shapes acute pancreatitis therapeutic access across major markets. The United States maintains a net importer position for plasma-derived enzyme inputs, while Germany and Japan balance domestic manufacturing with specialized European and Asian sourcing networks.
United States
Tertiary hospital construction in Houston and Phoenix expands dedicated pancreatitis unit capacity. FDA accelerated approval pathways compress development timelines for cytokine-modulating biologics. The Mayo Clinic Rochester anchors protocol innovation for early parenteral enzyme administration within 48-hour admission windows.
Germany
University hospital alliances in Bavaria and North Rhine-Westphalia drive adoption of REACH-compliant biomarker frameworks. EMA's Committee for Medicinal Products for Human Use accepts C-reactive protein trajectories as surrogate efficacy endpoints. Berlin's Charité university hospital network standardizes integrated critical-care bundle procurement across metropolitan systems.
Japan
Metropolitan hospital alliances in Tokyo consolidate three-year sole-source agreements for pancreatitis therapeutic bundles. PMDA's Sakigake designation system shortens regulatory review timelines for severe acute pancreatitis biologics. Osaka's Kansai Medical University anchors adoption of early-phase inflammatory cascade interventions.
India
Private hospital chains in Mumbai and Delhi expand tertiary pancreatitis management capacity. CDSCO streamlined approval pathways for critical-care biologics reduce market entry barriers. Apollo Hospitals' Chennai network pilots home-infusion channel development for post-acute enzyme replacement therapy.
United Kingdom
NHS England's specialized commissioning frameworks concentrate severe acute pancreatitis care in designated tertiary centers. MHRA post-Brexit regulatory autonomy enables parallel review pathways with FDA and EMA. London's Royal Free Hospital anchors multi-center biomarker qualification trials for novel anti-inflammatory approaches.
Acute Pancreatitis Market Vendor Landscape
On the supply side, the industry is consolidating around integrated critical-care bundles that combine parenteral nutrition, fluid resuscitation, and enzyme replacement protocols. Large-cap pharmaceutical developers and specialized biologic manufacturers occupy distinct tier positions. Three archetypes dominate: immunology-platform multinationals, critical-care infrastructure suppliers, and calcium-channel antagonist specialists. Competitive moves center on hospital procurement committee consolidation and biomarker-qualified trial restructuring.
Within the immunology-platform tier, AbbVie Inc. and Amgen Inc. represent established developers leveraging existing inflammatory disease infrastructure. Baxter International Inc. anchors the critical-care infrastructure segment through parenteral nutrition and fluid resuscitation positioning. CalciMedica Inc. exemplifies the specialist archetype focused on early-phase inflammatory cascade modulation.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Amgen Inc. |
| Merck & Co., Inc. |
| Johnson & Johnson |
| Pfizer Inc. |
| Novartis AG |
| Baxter International Inc. |
| CalciMedica Inc. |
| Fresenius SE & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
Bavarian university hospital clusters anchor European enzyme therapy manufacturing, and their fractionation capacity constraints translate directly into downstream pricing power for parenteral nutrition and pancreatic replacement therapy suppliers. This geographic concentration of specialized biologic production creates asymmetric leverage in contract negotiations with hospital procurement committees across Germany, Japan, and the United States.
Pricing Analysis
Next-generation cytokine-modulating biologics command substantial premiums over legacy small-molecule anti-secretory agents, while prior-generation oral enzyme supplements face commoditization pressure. Three-tier pricing structure across premium biologics, standard parenteral formulations, and economy oral generics dominates hospital formularies. Price differentiation hinges on FDA accelerated approval tier and cold-chain logistics bundling. Cost compression in the oral enzyme tier intensifies because of Indian manufacturer entry, though tertiary centers show low price sensitivity for critical-care biologics.
Supply Chain Analysis
Porcine pancreas sourcing draws from Denmark, the Netherlands, and select United States agricultural processors as primary feedstock inputs. Plasma-derived enzyme concentrates, intravenous lipid emulsions, and specialized biologic cold-chain packaging constitute critical component dependencies. Single-source vulnerability concentrates in European contract manufacturing for parenteral nutrition lipids. Distribution runs through hospital procurement committees consolidating sole-source agreements for integrated critical-care bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized manufacturing assets for biologic cold-chain integrity represent the binding constraint in this market, with limited qualified capacity for cytokine-modulating drug production creating acquisition premiums for capable facilities.
For Market Incumbents: Pre-empt biosimilar encroachment by securing multi-year porcine pancreas offtake agreements with Danish and Dutch agricultural processors. Add dedicated pancreatitis biologic fill-finish capacity in Singapore or Switzerland to diversify beyond European contract manufacturing concentration. FDA accelerated approval pathway expertise constitutes the critical defensive moat. For New Entrants and Emerging Players: Pursue CDSCO streamlined approval for Mumbai and Delhi private hospital chains where tertiary pancreatitis management remains underpenetrated. Target home-infusion channel partnerships with United States specialty pharmacy networks as the most penetrable post-acute segment. Position around calcium-channel antagonist combination protocols with existing anti-secretory agents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors immunology-platform multinationals with existing cytokine infrastructure over de novo biologic developers. Long-term viability over the next decade rests on biomarker-qualified surrogate endpoint capabilities that compress Phase III timelines. Acquisition target archetype: specialized biologic manufacturers with REACH-compliant European manufacturing and existing hospital GPO contracts. The signal to watch is PMDA Sakigake designation awards as inflection indicator for regulatory timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker-Qualified Trial Design | EMA acceptance of C-reactive protein trajectories accelerates European market entry timelines. |
| Critical-Care Bundle Consolidation | Tokyo metropolitan hospital alliances favor sole-source agreements spanning parenteral nutrition and enzyme therapy. |
| Home-Infusion Channel Development | Apollo Hospitals' Chennai network pilots specialty pharmacy delivery for post-acute enzyme replacement. |
| Porcine Pancreas Supply Security | Backward integration into Danish agricultural sourcing mitigates fractionation capacity constraints. |
| Sakigake Designation Pursuit | PMDA priority review system attracts biologic developers to file first in Tokyo for severe acute pancreatitis therapies. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across hospital gastroenterology departments, critical-care procurement committees, and biologic manufacturing facilities. Primary interviews captured protocol integration timelines, formulary placement criteria, and cold-chain logistics requirements. Secondary validation drew from FDA accelerated approval filings, EMA Committee for Medicinal Products for Human Use opinions, PMDA Sakigake designation records, and hospital GPO contract databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Calibration against historical biologic launch trajectories and regulatory timeline data refined projection parameters across the modeling period. Segmentation dimensions included therapeutic intent, care setting, administration route, and regional regulatory cluster. CAGRs were derived from severity-grade-specific adoption curves and hospital construction pipeline analysis. Forecast inputs incorporated PMDA review duration trends and tertiary care infrastructure expansion schedules in target markets.
Sensitivities concentrate around biomarker endpoint qualification timelines, porcine pancreas sourcing disruptions, and hospital procurement committee consolidation patterns. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and critical-care biologic stability standards. Material shifts in FDA guidance on inflammatory surrogate endpoints or European fractionation capacity constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Global Gastrointestinal Stent Market
Gastroenterology
Stomach Cancer Market
Gastroenterology
Chronic Liver Diseases Therapeutics Market
Gastroenterology
Malignant Ascites Market
Gastroenterology
US Inflammatory Bowel Disease Treatment Market
Gastroenterology
Chile Gastric Cancer Treatment Market
Gastroenterology
Inflammatory Bowel Disease Market
Gastroenterology
Global Gastrointestinal Bleeding Treatment Market
Gastroenterology
Peptic Ulcer Market
Gastroenterology
Inflammatory Bowel Disease Treatment Market
Gastroenterology
Gluten Intolerance Treatment Market
Gastroenterology
Hirschsprung Disease Treatment Market
Gastroenterology
Intestinal Pseudo-Obstruction Treatment Market
Gastroenterology
Intestinal Fistula Treatment Market
Gastroenterology
Diverticular Disease Therapeutics Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market