
 Zollinger Ellison Syndrome Treatment Market | 2026-2036
Zollinger Ellison Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Zollinger Ellison Syndrome Treatment Market Analytics
Aftermarket patient monitoring and long-term acid suppression management is reconfiguring how pharmaceutical firms capture lifetime value from rare disease cohorts. Takeda Pharmaceutical Company Limited leverages its heritage in gastrointestinal therapeutics to sustain deep relationships with academic medical centers. Pfizer Inc. competes through manufacturing scale that anchors supply security for proton pump inhibitor formulations. Novartis AG specializes in somatostatin analog development, positioning its portfolio around tumor burden reduction alongside symptomatic control.
Zollinger Ellison Syndrome constitutes a rare neuroendocrine disorder driven by gastrin-secreting tumors that provoke pathologic gastric acid hypersecretion, typically requiring sustained pharmacologic acid suppression below pH 3.0 to prevent peptic complications and esophageal injury. The condition demands lifelong therapeutic intervention, creating durable prescription volume concentrated among gastroenterology and oncology specialists. Proton pump inhibitors command the dominant share of pharmacologic intervention due to irreversible H+/K+ ATPase blockade and superior acid suppression depth versus H2-receptor antagonists. Somatostatin analogs represent the fastest-expanding segment as tumor-directed therapy gains priority in multidisciplinary neuroendocrine tumor protocols, with injectable delivery modes capturing preference in hospital and outpatient clinic settings where clinical oversight ensures proper administration.
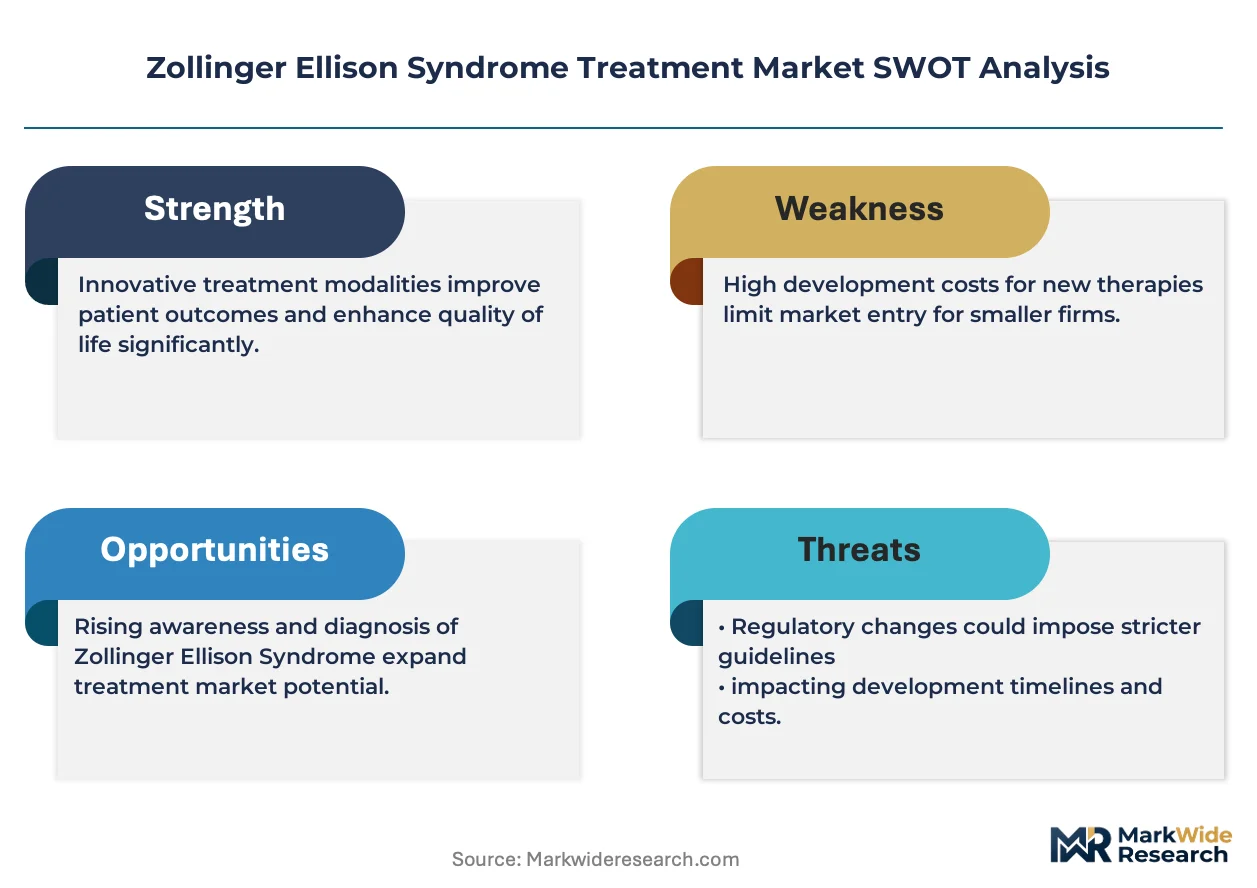
FDA orphan drug designation frameworks and EMA's Committee for Orphan Medicinal Products incentivize development investment through protocol assistance and fee reductions, directly shaping which sponsors advance candidates into Phase II trials. Japan's PMDA operates a comparable priority review scheme for rare diseases that accelerates market entry for qualifying acid suppression and tumor-targeted therapies. Stakeholders must monitor how regulatory convergence on real-world evidence requirements for rare disease approvals reshapes post-market commitment burdens and lifecycle management strategies.
Market Dynamics
Multidisciplinary neuroendocrine tumor centers are consolidating patient referral networks, concentrating prescription authority among hospital-based gastroenterologists and oncologists who coordinate acid suppression protocols with tumor-directed therapy.
Growth Catalysts
- FDA Orphan Drug Designation:Accelerated review pathways and protocol assistance reduce Phase II trial costs, incentivizing sponsors to advance somatostatin analog candidates into clinical development.
- Japan's PMDA Priority Review Scheme:Rare disease fast-track mechanisms compress approval timelines for acid suppression therapies, drawing investment toward localized clinical programs.
- Injectable Delivery Modes:Long-acting depot formulations capture preference in outpatient clinic settings where clinical oversight ensures proper somatostatin analog administration.
Market Restraints
- API Supply Concentration:Proton pump inhibitor active pharmaceutical ingredients depend on a limited supplier base in India and China, exposing formulation manufacturers to import disruption risk.
- Diagnostic Delay:Average time to Zollinger Ellison Syndrome confirmation exceeds five years due to nonspecific symptom presentation, compressing addressable patient pools in any given treatment year.
- Substitution Pressure from H2 Antagonists:Generic ranitidine and famotidine formulations retain formulary position in cost-constrained health systems despite inferior acid suppression depth.
Strategic Opportunities
- Real-World Evidence Pathways:FDA and EMA convergence on post-market commitment frameworks allows sponsors to substitute registry data for controlled trials, reducing lifecycle management costs.
- Biomarker-Guided Patient Stratification:Gastrin level monitoring technologies enable precision dosing protocols that differentiate premium somatostatin analog positioning from standard acid suppression.
- Telemedicine Integration:Remote gastroenterology consultation models extend specialist reach into underserved U.S. states and rural German regions lacking neuroendocrine tumor centers.
Industry Challenges
- Specialist Workforce Scarcity:Fellowship-trained neuroendocrine tumor physicians concentrate at academic medical centers, limiting patient access in community hospital settings.
- Cross-Border Regulatory Divergence:EMA's Committee for Orphan Medicinal Products and FDA's Office of Orphan Products Development maintain non-harmonized evidentiary standards, forcing duplicate submission strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zollinger Ellison Syndrome Treatment Market |
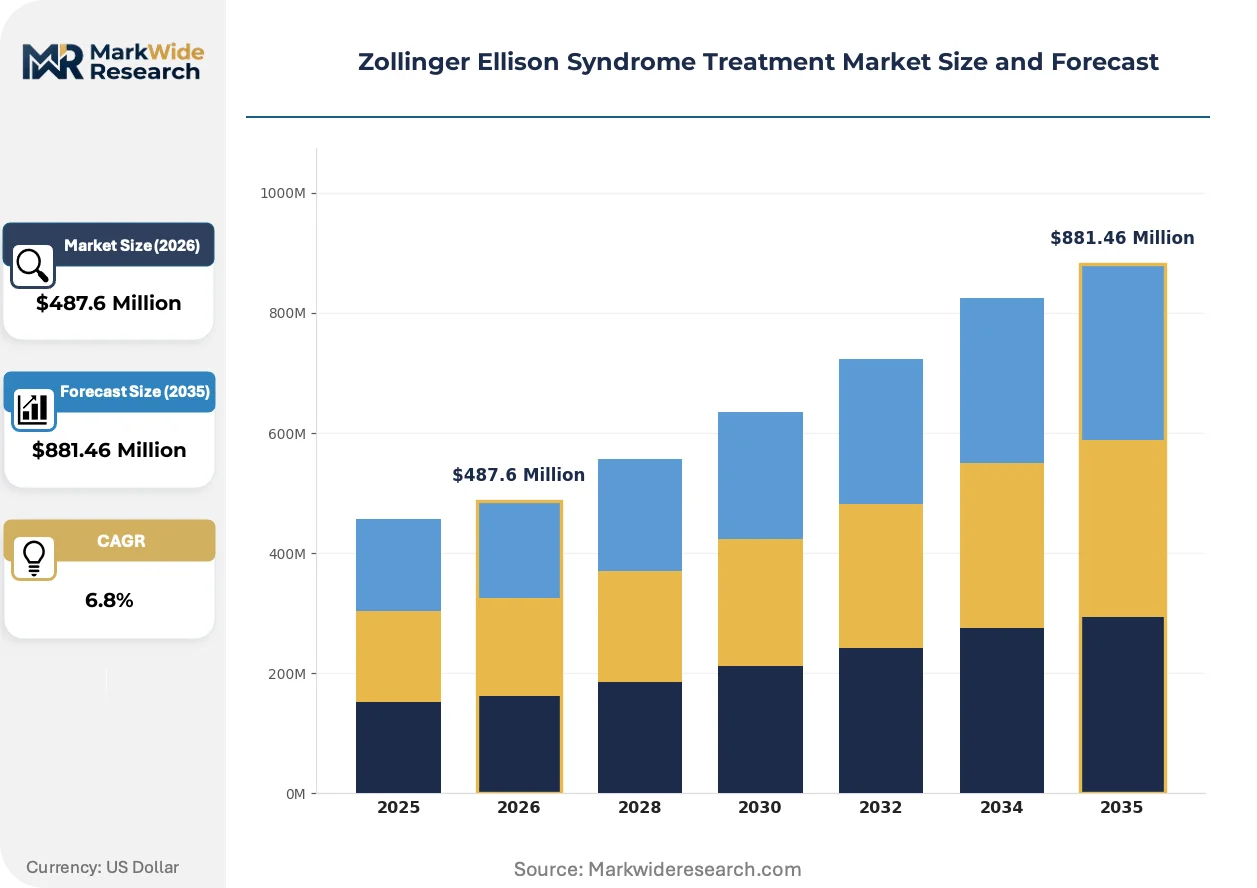
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Pump Inhibitors, Antacids, H2-Receptor Antagonists, Somatostatin Analogs Delivery Mode: Oral, Injectable, Intravenous, Transdermal Indication: Cancer-Related Hypersecretion, Peptic Ulcer Disease, Gastroesophageal Reflux Disease, Zollinger-Ellison Syndrome End User: Hospitals, Outpatient Clinics, Home Healthcare, Pharmacies |
| Companies Covered | Bayer AG, Sanofi, GSK Plc, AstraZeneca plc, Takeda Pharmaceutical Company Limited, Pfizer Inc., F. Hoffmann-La Roche Ltd, Bristol Myers Squibb Company, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zollinger Ellison Syndrome Treatment Market Evolving Landscape
Acid suppression technology is bifurcating between incremental proton pump inhibitor formulation improvements and disruptive somatostatin analog delivery systems that merge tumor control with symptomatic management.
Continuous intragastric pH monitoring devices are rendering obsolete empiric dose escalation protocols that relied on symptom reporting rather than objective acid exposure metrics. Tertiary care centers in the United States and Germany are integrating these sensors into standard-of-care pathways for refractory cases. This instrumentation shift is compressing the window between therapeutic failure and protocol adjustment, reducing esophageal complication rates.
EMA's expanded access programs for rare disease therapies are creating regulatory precedents that permit pre-approval compassionate use of somatostatin analogs in life-threatening gastrinoma progression. Sponsors are leveraging these frameworks to generate natural history data that supports marketing authorization submissions. Hospital pharmacies across France, Italy, and Spain are now structuring inventory systems around anticipatory stocking for named-patient programs.
Academic medical centers are unbundling long-term acid suppression management from initial tumor staging, creating discrete revenue streams for pharmaceutical firms. Gastroenterology departments at Mayo Clinic, MD Anderson, and Karolinska Institute are establishing dedicated Zollinger Ellison Syndrome monitoring clinics. This service model concentrates prescription loyalty among patients requiring lifelong pharmacologic intervention.
Zollinger Ellison Syndrome Treatment Market Segmentation
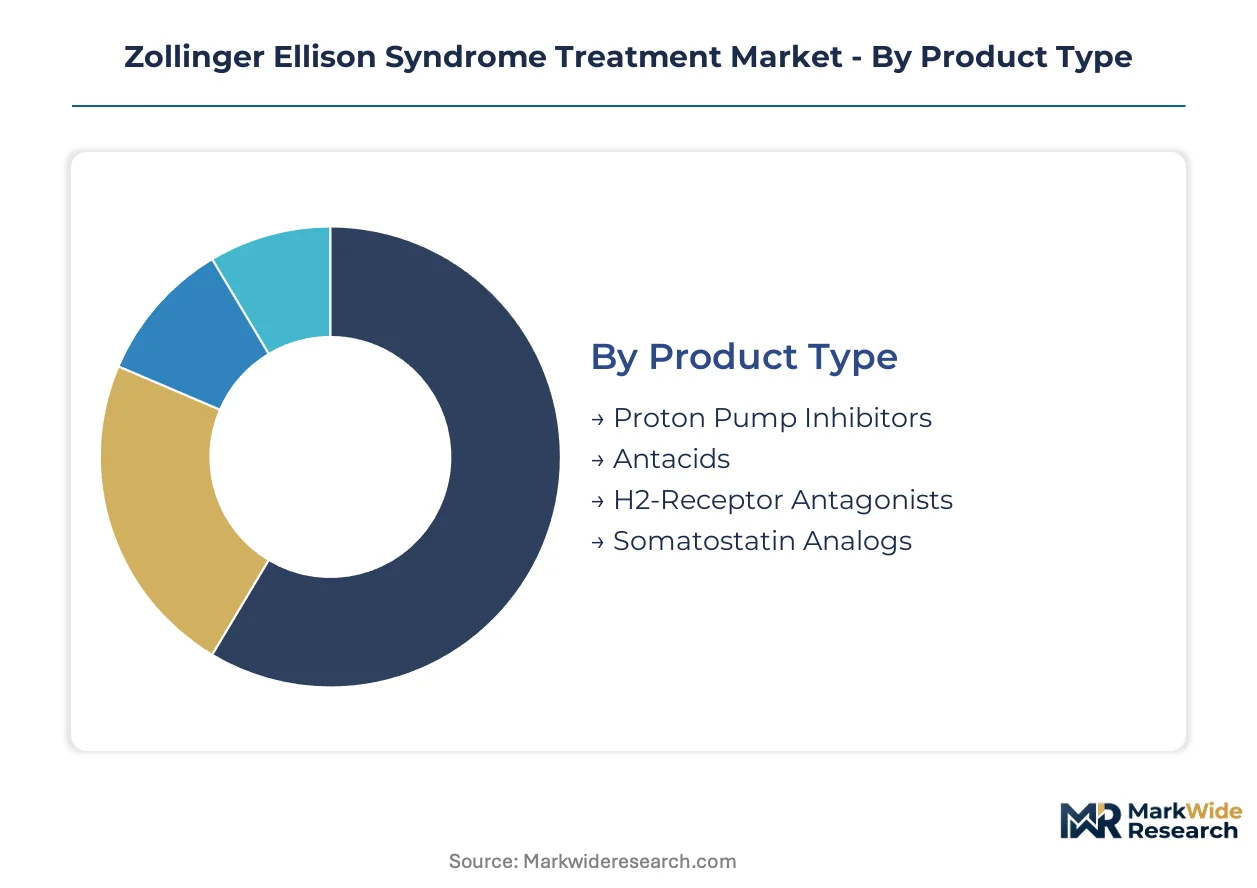
Segmentation in Zollinger Ellison Syndrome treatment reveals how prescription patterns concentrate among specialists managing lifelong acid suppression protocols. Patient lifetime value varies dramatically across delivery modes and care settings, reshaping how pharmaceutical firms allocate commercial resources.
Product Type:
After-sales service intensity peaks with somatostatin analogs requiring clinical oversight for depot administration and dose titration monitoring.
- Proton Pump Inhibitors:Irreversible H+/K+ ATPase blockade delivers sustained acid suppression below pH 3.0 through once-daily oral dosing. Demand concentrates in United States academic medical centers where gastroenterology departments coordinate tumor-directed therapy with symptomatic control.
- Somatostatin Analogs:Long-acting octreotide and lanreotide formulations suppress gastrinoma hormone secretion while reducing tumor burden. Injectable delivery modes capture preference in German and Japanese neuroendocrine tumor centers where multidisciplinary protocols prioritize disease modification alongside acid control.
- Antacids:Calcium carbonate and magnesium hydroxide formulations provide on-demand symptomatic relief for breakthrough acid episodes.
- H2-Receptor Antagonists:Ranitidine and famotidine compete on cost in formulary negotiations despite inferior acid suppression depth versus proton pump inhibitors.
Proton pump inhibitors hold the largest share; momentum sits with somatostatin analogs.
Delivery Mode:
Cost tier stratification separates premium injectable depot formulations from commoditized oral generics.
- Injectable:Long-acting somatostatin analog depots require refrigeration, cold-chain logistics, and trained clinical administration. United States outpatient clinics and hospital infusion centers capture the highest prescription volumes where reimbursement supports specialty pharmacy dispensing.
- Oral:Proton pump inhibitor capsules and tablets dominate maintenance therapy for ambulatory patients with controlled gastrinoma progression.
- Intravenous:Pantoprazole and esomeprazole infusions address acute bleeding episodes and preoperative acid suppression in hospitalized patients.
- Transdermal:Experimental delivery systems remain confined to early-phase clinical trials with limited commercial penetration.
Oral formulations maintain volume leadership; injectable delivery modes are gaining share fastest.
Indication:
Application severity determines pricing power, with cancer-related hypersecretion commanding premium positioning.
- Zollinger-Ellison Syndrome:The index indication demands lifelong pharmacologic intervention with acid suppression targets below pH 3.0 to prevent esophageal stricture and peptic perforation. German and Japanese tertiary centers concentrate the highest patient volumes where diagnostic protocols have shortened time-to-confirmation.
- Cancer-Related Hypersecretion:Gastrinoma and other neuroendocrine tumors drive somatostatin analog adoption through tumor-directed therapy protocols. United States comprehensive cancer centers at Mayo Clinic and MD Anderson anchor clinical trial enrollment and off-label utilization.
- Peptic Ulcer Disease:Secondary acid suppression indications support proton pump inhibitor volume but face generic substitution pressure.
- Gastroesophageal Reflux Disease:Overlap prescriptions expand addressable pools though reimbursement coding separates GERD from orphan indication pathways.
Zollinger-Ellison Syndrome holds the largest share; momentum sits with cancer-related hypersecretion.
End User:
Customer type dictates procurement sophistication, with hospital pharmacies negotiating formulary placement through tender processes.
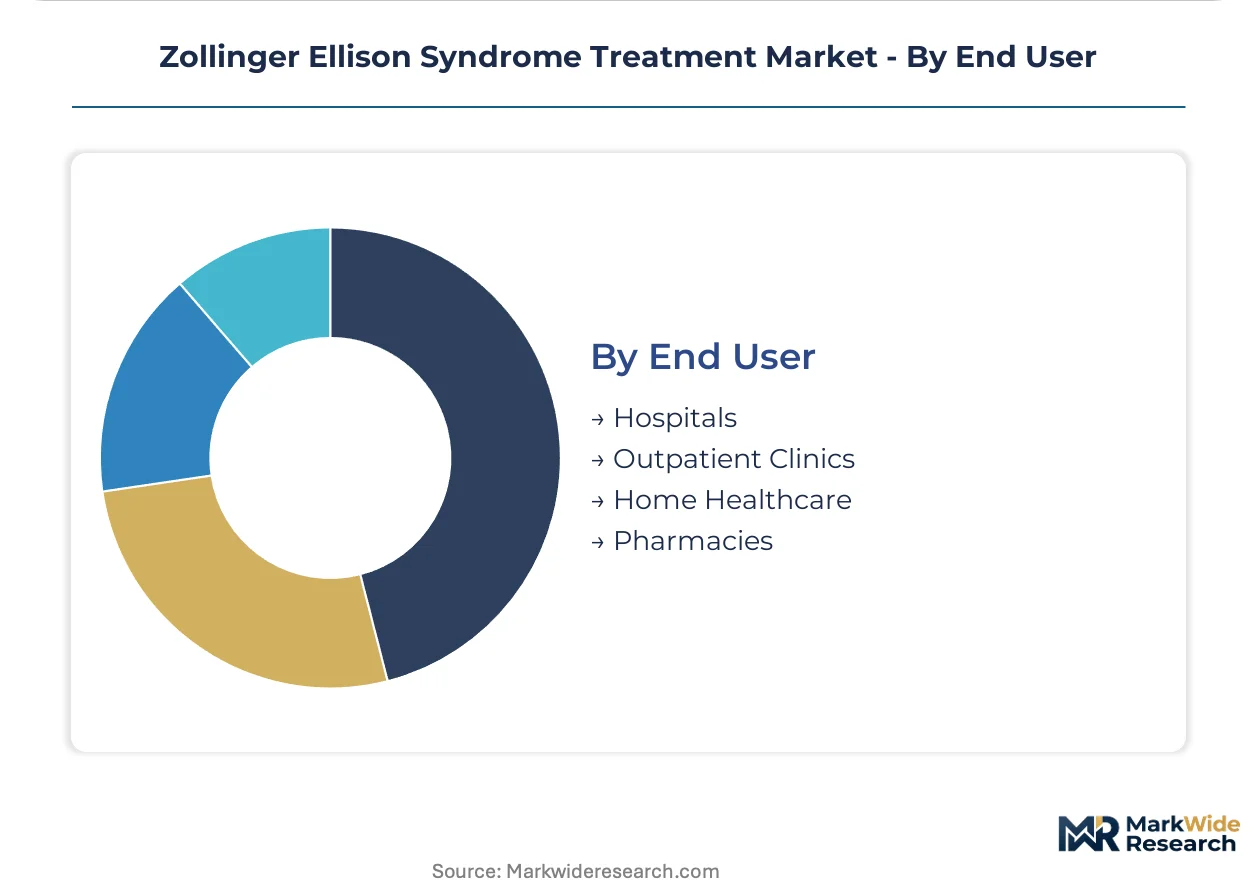
- Hospitals:Tertiary care centers in the United States, Germany, and Japan concentrate somatostatin analog purchasing through centralized pharmacy and therapeutics committees. Academic medical centers maintain dedicated neuroendocrine tumor protocols that standardize acid suppression algorithms.
- Outpatient Clinics:Gastroenterology and oncology practices manage long-term depot administration and gastrin level monitoring.
- Home Healthcare:Specialty nursing services support patient self-administration training for selected somatostatin analog formulations.
- Pharmacies:Retail and mail-order channels dispense oral proton pump inhibitors for maintenance therapy with limited clinical oversight.
Hospitals hold the largest share; momentum sits with outpatient clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies, with cost-constrained health systems in Southern Europe favoring generic proton pump inhibitors while Japanese and German tertiary centers absorb premium somatostatin analog pricing without volume erosion.
United States
Mayo Clinic, MD Anderson, and Cleveland Clinic anchor the highest patient volumes through dedicated neuroendocrine tumor centers. FDA orphan drug designation frameworks compress approval timelines for somatostatin analog candidates, incentivizing sponsors to prioritize U.S. clinical programs. Academic medical centers in Rochester, Houston, and Boston standardize acid suppression protocols that integrate continuous intragastric pH monitoring.
Germany
Charité Berlin and Heidelberg University Hospital concentrate gastrinoma referral networks through multidisciplinary tumor boards. EMA's Committee for Orphan Medicinal Products provides protocol assistance and fee reductions that accelerate somatostatin analog development investment. The Baden-Württemberg and Bavaria regions host specialized gastroenterology departments that shortened diagnostic confirmation timelines below the five-year global average.
Japan
PMDA priority review schemes for rare diseases compress market entry timelines for acid suppression and tumor-targeted therapies. National Cancer Center Hospital and Keio University Hospital anchor clinical trial enrollment for long-acting depot formulations. The Kanto region around Tokyo concentrates outpatient clinic infrastructure where trained clinical staff administer injectable somatostatin analogs.
United Kingdom
NHS England's specialized commissioning framework concentrates Zollinger Ellison Syndrome care at Royal Free London and Oxford University Hospitals. NICE technology appraisals determine reimbursement eligibility for premium somatostatin analogs against cost-effectiveness thresholds. The Greater London and Thames Valley clusters maintain dedicated neuroendocrine tumor nursing services that support long-term depot administration.
France
EMA expanded access programs permit pre-approval compassionate use of somatostatin analogs in life-threatening gastrinoma progression. Hôpital Européen Georges Pompidou and Gustave Roussy generate natural history data that supports marketing authorization submissions. The Île-de-France region structures hospital pharmacy inventory systems around anticipatory stocking for named-patient programs.
Zollinger Ellison Syndrome Treatment Market Competitive Landscape
Specialized gastroenterology incumbents and diversified oncology portfolios split the market into distinct competitive spheres. The vendor base concentrates among pharmaceutical firms with heritage in acid suppression science and those pivoting toward tumor-directed neuroendocrine protocols. Three archetypes dominate: heritage gastrointestinal specialists, diversified oncology platform players, and manufacturing-scale generic formulators. Competitive moves center on somatostatin analog pipeline advancement and proton pump inhibitor supply security arrangements.
Within the heritage gastrointestinal tier, Takeda Pharmaceutical Company Limited occupies a position anchored by decades of acid suppression research and deep academic medical center relationships. Pfizer Inc. exemplifies the manufacturing-scale archetype, leveraging formulation capacity to secure supply continuity for proton pump inhibitor portfolios. Novartis AG represents the oncology-pivot archetype, positioning around somatostatin analog development that merges tumor burden reduction with symptomatic management protocols.
| Leading Market Players |
|---|
| Bayer AG |
| Sanofi |
| GSK Plc |
| AstraZeneca plc |
| Takeda Pharmaceutical Company Limited |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd |
| Bristol Myers Squibb Company |
| Novartis AG |
| Others |
Value Network & Pricing Analysis
Single-source API dependency in proton pump inhibitor manufacturing determines both margin compression in oral generic tiers and the premium pricing power retained by injectable somatostatin analog producers. This concentration dynamic forces formulation sponsors to secure dual-source agreements or absorb tariff exposure while tiering price structures around clinical oversight requirements.
Pricing Analysis
After-sales service contracts for depot administration and gastrin monitoring drive lifetime value capture across the somatostatin analog segment. Three-tier pricing structure across premium depot formulations, standard oral maintenance therapies, and economy generic proton pump inhibitors reflects after-sales bundling intensity. Pricing pressure stems from formulary substitution toward H2-receptor antagonists in cost-constrained health systems. Hospital pharmacies exhibit lowest price sensitivity due to dedicated neuroendocrine tumor protocol budgets, while retail channels face highest substitution elasticity.
Supply Chain Analysis
Upstream active pharmaceutical ingredient production for proton pump inhibitors centers on manufacturing facilities in India and China. Pantoprazole and esomeprazole intermediates draw from specialized chemical synthesis clusters, while octreotide and lanreotide peptide production rests on biologics capabilities concentrated in Switzerland and Ireland. Single-source vulnerability in Indian API supply exposes formulation manufacturers to import disruption risk. Distribution runs through hospital pharmacy and therapeutics committees at academic medical centers, with specialty pharmacy channels handling outpatient depot logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hospital-based gastroenterology departments that coordinate multidisciplinary neuroendocrine tumor protocols, consolidating prescription authority away from dispersed community practitioners.
For Market Incumbents: Harden supply security through backward integration into proton pump inhibitor API production or captive sourcing agreements with Indian and Chinese manufacturers. Defend somatostatin analog positioning by embedding continuous intragastric pH monitoring technologies into bundled service contracts that raise switching costs for academic medical centers. For New Entrants and Emerging Players: Establish a beachhead in telemedicine-enabled gastroenterology consultation models that extend specialist reach into underserved U.S. states and rural German regions lacking neuroendocrine tumor centers. Target outpatient clinic infrastructure for long-acting depot administration where reimbursement supports premium pricing and clinical oversight requirements create natural barriers to generic substitution. For Investors and Strategic Acquirers: FDA orphan drug designation pathway convergence with EMA real-world evidence frameworks reshapes the acquisition landscape toward somatostatin analog pipeline assets with Phase II-ready candidates. Long-term viability hinges on tumor-directed therapy protocols displacing pure acid suppression approaches. Target acquisition archetypes include biotech firms with depot formulation expertise and biomarker-guided dosing platforms. The signal to watch is gastrin level monitoring technology adoption rates at Mayo Clinic, MD Anderson, and Karolinska Institute as indicators of precision medicine inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II somatostatin analog candidates attract FDA orphan drug designation fee reductions and protocol assistance. |
| Regulatory Approval Pathway | EMA expanded access programs permit pre-approval compassionate use generating natural history data for submissions. |
| Manufacturing Scale-Up | Long-acting depot formulation capacity anchors supply security for hospital infusion center and outpatient clinic networks. |
| Pipeline Diversification | Biomarker-guided patient stratification platforms differentiate premium positioning from standard acid suppression protocols. |
| Strategic Partnership | Academic medical center alliances at Charité Berlin and Heidelberg University Hospital concentrate referral network control. |
Research Methodology
The analysis maps proton pump inhibitor formulations, somatostatin analog delivery systems, and diagnostic monitoring technologies, each validated through gastroenterology department heads, hospital pharmacy and therapeutics committee chairs, regulatory affairs specialists, and payer access managers. Primary interview intelligence combined with FDA orphan drug designation filings, EMA Committee for Orphan Medicinal Products submissions, ClinicalTrials.gov protocol records, and hospital procurement database extracts. Bottom-up prescription volume modeling and top-down epidemiological prevalence estimates were triangulated to anchor market sizing.
Assumptions held fixed include regulatory pathway timelines for orphan indications and diagnostic confirmation rates at tertiary centers, while variables included somatostatin analog adoption curves and telemedicine penetration in specialist-deprived regions. Segmentation dimensions spanned product type, delivery mode, indication severity, and end-user procurement sophistication. CAGRs were derived from patient lifetime value modeling across acid suppression maintenance protocols. Forecast inputs incorporated gastrinoma incidence trajectories and multidisciplinary neuroendocrine tumor center expansion rates.
Stress conditions across API supply disruption scenarios, diagnostic delay compression, and H2-receptor antagonist substitution elasticity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions, with revision triggers including PMDA priority review scheme modifications, EMA real-world evidence requirement shifts, and proton pump inhibitor API sourcing concentration changes. Cross-checking against hospital pharmacy procurement records and specialty pharmacy dispensing data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Digestive Health Market
Gastroenterology
Gallstone Market
Gastroenterology
Peptic Ulcer Market
Gastroenterology
Polyps Market
Gastroenterology
Malignant Ascites Market
Gastroenterology
Gastrointestinal Drugs Market
Gastroenterology
High Definition Ultrasound Gastroscope Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market
Gastroenterology
Gastric Cancer Market
Gastroenterology
Stomach Cancer Market
Gastroenterology
Hyperemesis Gravidarum Treatment Market
Gastroenterology
Diverticular Disease Therapeutics Market
Gastroenterology
Fecal Incontinence Market
Gastroenterology
Global Gastrointestinal Stent Market
Gastroenterology
Chile Gastric Cancer Treatment Market
Gastroenterology
Digestive Health Products Market