
 Japan Endoscopy Devices Market | 2026-2036
Japan Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Endoscopy Devices Market Foresight
A capital-intensity divergence between domestic incumbents and multinational entrants is unwinding competitive stability in Japan's endoscopy sector. Olympus Corporation leverages decades of optical engineering heritage to sustain dominance in flexible gastrointestinal systems. Fujifilm Holdings Corporation anchors its position through digital imaging platforms that compete directly with legacy video architectures.
Endoscopy devices encompass instrumented visualization systems—typically 2–10 mm diameter insertion tubes with fiber-optic or CMOS sensor arrays—engineered for minimally invasive diagnostic and therapeutic access to hollow organs and body cavities. These systems transmit real-time imagery to surgical teams, enabling tissue biopsy, polypectomy, and stent deployment without open incision. Flexible endoscopes command premium positioning due to articulation complexity and sterilization durability requirements, while digital imaging technology is displacing optical platforms as hospitals prioritize 4K resolution and AI-enhanced polyp detection. Ultrasonic endoscopes represent a concentrated margin pool where EUS-guided fine-needle aspiration drives procedural expansion in pancreatic and biliary diagnostics.
PMDA enforces Japan-specific revalidation protocols for reusable endoscope sterilization cycles, elevating compliance costs for manufacturers without in-house biocompatibility testing. METI's medical device pricing reforms periodically compress reimbursement ceilings, forcing vendors to demonstrate measurable clinical outcome improvements for premium tier placement. Stakeholders must monitor how JIS standards for electromagnetic compatibility evolve alongside software-as-medical-device classifications that could reshape regulatory pathways for AI-integrated imaging systems.
Market Dynamics
PMDA's sterilization revalidation mandates are compressing vendor margins while metropolitan hospital clusters in Tokyo, Osaka, and Nagoya concentrate purchasing power around AI-integrated imaging platforms.
Growth Catalysts
- Metropolitan Healthcare Concentration:Tokyo, Osaka, and Nagoya clusters drive procedural volume expansion through centralized gastroenterology departments and tertiary referral networks.
- PMDA Reprocessing Standards:Tightened biocompatibility testing requirements for reusable device cycles elevate barriers for non-compliant manufacturers and favor established sterilization infrastructure.
- CMOS Sensor Migration:Digital imaging arrays are displacing fiber-optic architectures as hospitals prioritize 4K resolution and real-time AI-enhanced polyp detection capabilities.
Market Restraints
- Input Cost Volatility:Specialized optical glass and precision articulation cable assemblies face supply concentration from German and Swiss precision component suppliers.
- Technical Limitation:Flexible endoscope durability constraints limit sterilization cycle counts, accelerating capital replacement schedules and total cost of ownership.
- Regulatory Friction:METI medical device pricing reforms compress reimbursement ceilings without commensurate cost recognition for AI-integrated system upgrades.
Strategic Opportunities
- Rural Hospital Penetration:Secondary cities in Hokkaido and Kyushu remain underpenetrated for EUS-guided diagnostic procedures and advanced therapeutic endoscopy.
- Software-as-Medical-Device Pathway:PMDA's evolving classification framework for AI-integrated imaging creates regulatory tailwinds for algorithm-native vendors.
- Ultrasonic Endoscope Expansion:EUS-guided fine-needle aspiration represents concentrated margin pools in pancreatic and biliary diagnostic applications.
Industry Challenges
- Specialized Technician Scarcity:Biomedical engineering programs produce insufficient graduates trained in CMOS sensor calibration and AI-integrated system maintenance.
- Legacy System Integration:Digital platform deployment requires costly retrofitting of hospital IT infrastructure and PACS compatibility verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Endoscopy Devices Market |
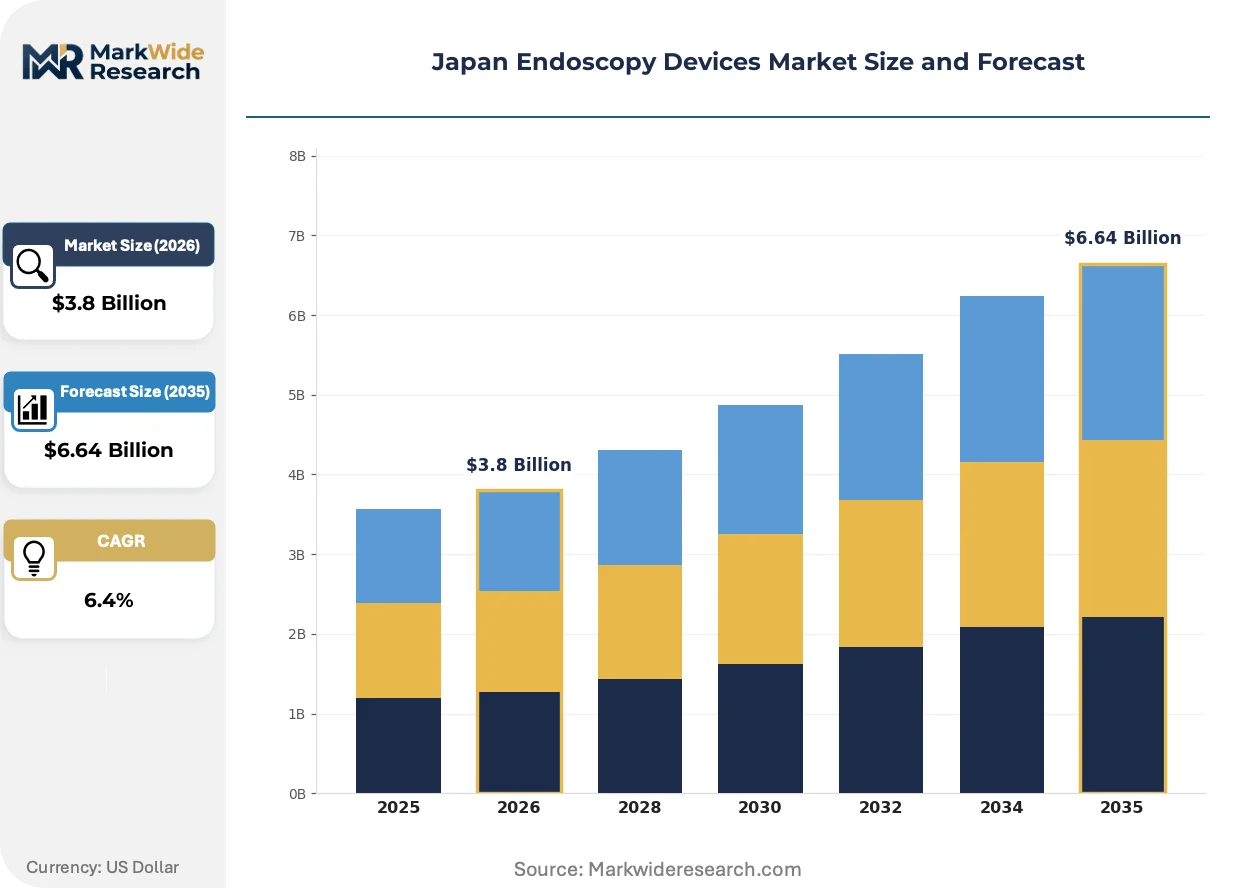
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Endoscopes, Rigid Endoscopes, Flexible Endoscopes, Ultrasonic Endoscopes Technology: Optical Imaging, Digital Imaging, Laser Imaging, Ultrasound End User: Hospitals, Clinics, Surgical Centers, Diagnostic Laboratories Application: Gastroenterology, Pulmonology, Urology, ENT |
| Companies Covered | Olympus Corporation, Fujifilm Holdings Corporation, Pentax Medical (HOYA Corporation), Medtronic plc, Boston Scientific Corporation, Stryker Corporation, Karl Storz SE & Co. KG, Conmed Corporation, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Endoscopy Devices Market Shifts & Advancements
AI-enhanced imaging is rewiring competitive advantage around algorithmic detection accuracy rather than optical hardware specifications alone.
CMOS sensor arrays are fragmenting the traditional duopoly in flexible gastrointestinal systems. Regional hospital networks in Kansai and Chubu are adopting digital platforms at accelerated replacement cycles. The technology is fragmenting vendor revenue concentration by enabling software-native entrants to compete on detection metrics without legacy optical manufacturing assets.
PMDA's software-as-medical-device classification pathway is restructuring regulatory economics for AI-integrated systems. Manufacturers must now submit algorithm training datasets and validation protocols alongside hardware biocompatibility documentation. Endoscopy vendors with captive AI development capabilities are consolidating clinical evidence generation to accelerate approval timelines.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases. Metropolitan clusters in Tokyo are negotiating direct maintenance agreements with third-party biomedical service providers. This pattern is most visible in Kanto region academic medical centers where internal engineering departments absorb routine calibration and preventive maintenance functions.
Japan Endoscopy Devices Market Segmentation
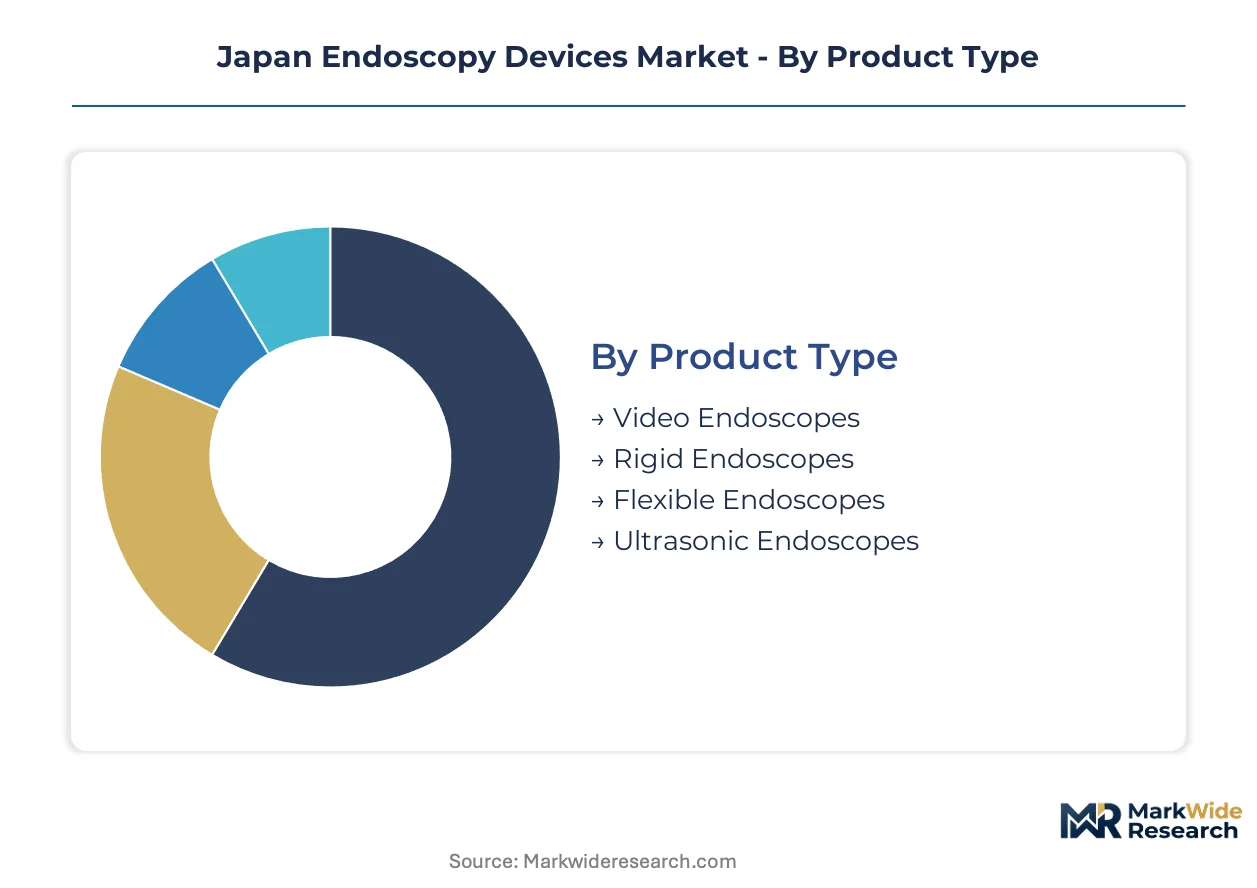
Segmentation in Japan's endoscopy market reveals how PMDA regulatory pathways and metropolitan procurement concentration reshape competitive positioning across hardware and software categories. Understanding substitution dynamics between optical and digital platforms enables vendors to calibrate R&D allocation and pricing architecture.
Product Type:
Flexible endoscopes face intensifying substitution pressure from CMOS-enabled video platforms as Tokyo academic centers accelerate replacement cycles.
- Flexible Endoscopes:Articulated insertion tubes with fiber-optic or digital sensor arrays enable minimally invasive access to gastrointestinal and pulmonary tracts. Demand concentrates in Tokyo and Osaka tertiary hospitals where sterilization durability requirements elevate total cost of ownership calculations.
- Video Endoscopes:Integrated CMOS sensor platforms transmit 4K resolution imagery with AI-enhanced polyp detection capabilities. Procurement committees in Nagoya metropolitan clusters prioritize these systems for compatibility with PACS infrastructure and real-time diagnostic workflows.
- Ultrasonic Endoscopes:EUS-guided systems combine endoscopic visualization with high-frequency ultrasound for pancreatic and biliary diagnostics.
- Rigid Endoscopes:Stainless steel sheathed optical systems serve arthroscopic and laparoscopic procedures with limited articulation requirements.
Flexible endoscopes anchor the volume base while video endoscopes gain share at the steepest rate.
Technology:
Cost tier stratification separates legacy optical installations from premium digital deployments across Japan's hospital reimbursement bands.
- Digital Imaging:CMOS sensor arrays capture high-resolution imagery with computational enhancement capabilities. Adoption accelerates in Kanto region hospitals seeking AI-integrated detection workflows and streamlined sterilization protocols.
- Optical Imaging:Fiber-optic bundles transmit illumination and imagery through flexible glass filament architectures. Remaining demand concentrates in rural Hokkaido and Kyushu facilities with constrained capital budgets and legacy maintenance infrastructure.
- Ultrasound:High-frequency transducer integration enables subsurface tissue characterization and guided needle aspiration.
- Laser Imaging:Confocal and fluorescence modalities provide cellular-level resolution for specialized oncological screening.
Optical imaging retains installed base dominance while digital imaging expands most quickly through metropolitan replacement cycles.
End User:
Customer type determines procurement authority scope and service contract bundling preferences across Japan's healthcare delivery tiers.
- Hospitals:Tertiary and secondary acute care facilities with centralized gastroenterology departments drive procedural volume and capital equipment purchasing. Tokyo, Osaka, and Nagoya clusters concentrate demand for AI-integrated platforms with comprehensive maintenance agreements.
- Clinics:Outpatient specialty practices perform screening endoscopies with lower throughput requirements and compressed reimbursement schedules.
- Surgical Centers:Ambulatory facilities focus on same-day therapeutic procedures with streamlined sterilization workflows.
- Diagnostic Laboratories:Independent pathology services utilize endoscopic retrieval for tissue specimen processing.
Hospitals command the capital expenditure pool while clinics represent the volume expansion frontier.
Application:
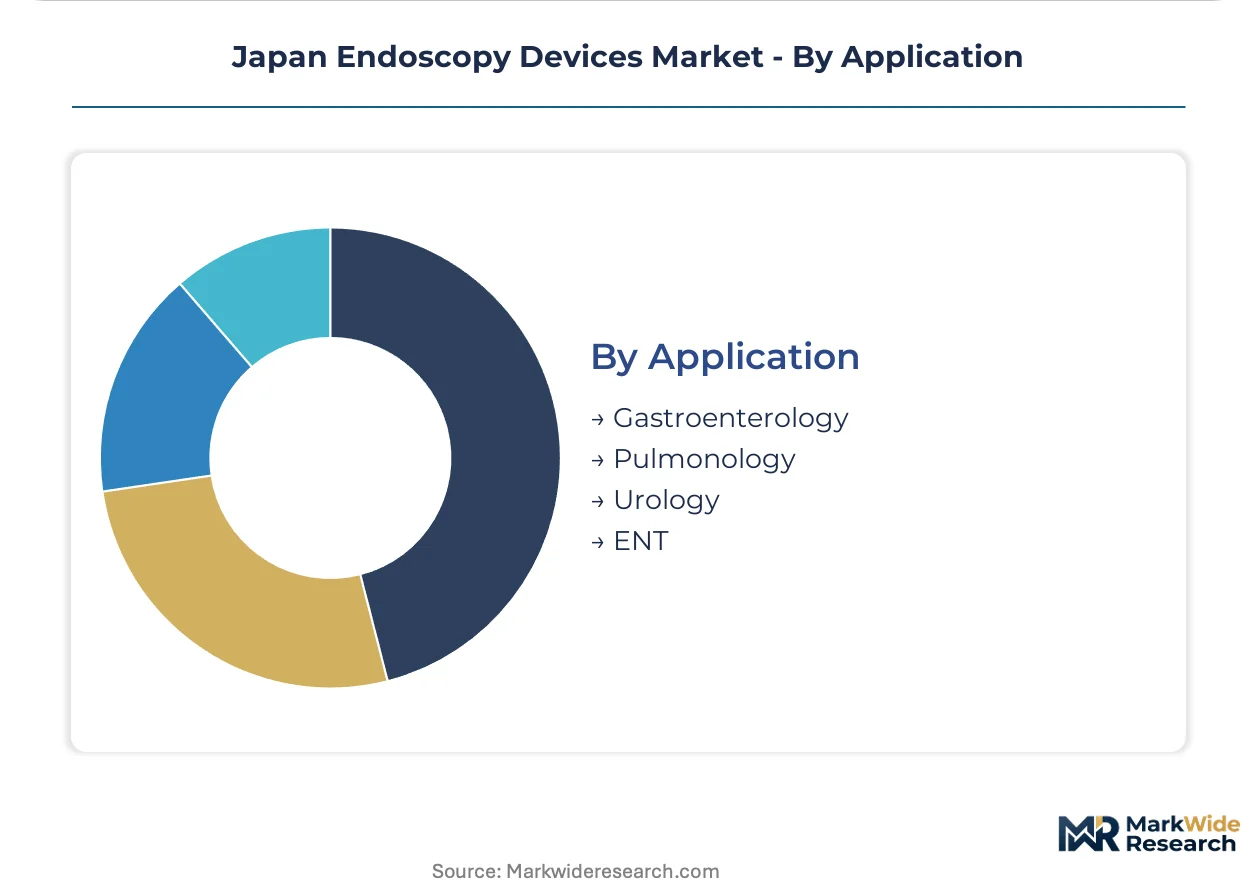
Procedure reimbursement rates and screening program mandates shape application-level demand concentration across Japan's prefectural health systems.
- Gastroenterology:Colonoscopy and esophagogastroduodenoscopy procedures dominate procedural volumes with national colorectal cancer screening program support. Demand concentrates in metropolitan clusters with aging demographic concentration and centralized referral networks.
- Pulmonology:Bronchoscopic procedures serve lung cancer staging and interventional airway management.
- Urology:Cystoscopic and ureteroscopic interventions address urolithiasis and bladder pathology.
- ENT:Sinonasal and laryngeal endoscopy supports otolaryngological diagnostics and surgical planning.
Gastroenterology sustains the procedural volume base while pulmonology climbs the fastest on lung cancer screening expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Tokyo's metropolitan hospital clusters while rural prefectures absorb compressed reimbursement schedules. Kanto region academic medical centers negotiate direct service contracts that bypass traditional vendor bundling. This asymmetry shapes procurement patterns across Japan's prefectural healthcare systems.
Kanto/Tokyo
Tokyo's tertiary hospitals drive demand for AI-integrated video endoscopes with 4K resolution capabilities. METI's medical device pricing reforms force vendors to demonstrate clinical outcome improvements for premium tier placement. The Tokyo metropolitan cluster concentrates purchasing authority through centralized gastroenterology departments at Keio University Hospital and Tokyo Medical University Hospital.
Kansai/Osaka
Osaka's hospital networks prioritize CMOS sensor platforms compatible with existing PACS infrastructure. PMDA's software-as-medical-device classification pathway accelerates regulatory timelines for algorithm-native vendors submitting to Kansai region academic centers. Osaka University Hospital and Kobe University Hospital anchor procedural volume expansion in pancreatic and biliary diagnostics.
Chubu/Nagoya
Nagoya metropolitan clusters exhibit accelerated replacement cycles for digital imaging systems. JIS standards for electromagnetic compatibility shape procurement specifications for integrated operating room deployments. Nagoya University Hospital and Fujita Health University Hospital concentrate EUS-guided fine-needle aspiration procedures.
Kyushu
Kyushu's secondary cities remain underpenetrated for advanced therapeutic endoscopy and ultrasonic diagnostic procedures. PMDA's tightened reprocessing standards elevate compliance costs for rural facilities lacking in-house biocompatibility testing infrastructure. Fukuoka City Hospital and Kumamoto University Hospital represent emerging demand centers for EUS-guided interventions.
Hokkaido
Hokkaido's rural facilities retain legacy optical imaging systems due to constrained capital budgets and limited maintenance infrastructure. METI's reimbursement ceiling compressions disproportionately impact equipment upgrade schedules in northern prefectures. Sapporo Medical University Hospital concentrates specialty procedural referrals from across the island.
Japan Endoscopy Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in Japan's endoscopy sector. Domestic incumbents leverage decades of optical engineering heritage while multinational entrants compete on digital platform integration. The market structure separates into heritage manufacturers with captive sterilization infrastructure, software-native specialists exploiting PMDA's evolving classification pathways, and diversified medical technology conglomerates with service network scale. Competitive moves concentrate on AI development partnerships and unbundled maintenance contract negotiations.
Among Japan-based heritage manufacturers, Olympus Corporation and Fujifilm Holdings Corporation occupy positions defined by optical engineering lineage and digital imaging platform development respectively. HOYA Corporation's Pentax Medical subsidiary represents the diversified conglomerate archetype with integrated healthcare portfolio scale. Medtronic plc and Boston Scientific Corporation exemplify multinational entrants competing through service network breadth and algorithmic detection capabilities. These five entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Olympus Corporation |
| Fujifilm Holdings Corporation |
| Pentax Medical (HOYA Corporation) |
| Medtronic plc |
| Boston Scientific Corporation |
| Stryker Corporation |
| Karl Storz SE & Co. KG |
| Conmed Corporation |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Capacity utilization at Japanese precision component foundries shapes both supply concentration and price floors for endoscopy device manufacturing. Scale economies in CMOS sensor packaging and optical glass polishing create tiered procurement power, with metropolitan hospital clusters capturing volume discounts while rural facilities absorb standard list pricing.
Pricing Analysis
The customization-premium spread between standard flexible endoscope configurations and AI-integrated video platforms exceeds threefold in Tokyo academic centers. Pricing stratifies across premium, standard, and economy tiers based on CMOS resolution grade and PMDA software-as-medical-device certification status. Cost compression in standard optical systems is intensifying because METI reimbursement ceiling reforms compress vendor margins without recognizing AI upgrade investments. Rural Hokkaido clinics exhibit highest price sensitivity due to constrained capital budgets, while Kanto region tertiary hospitals prioritize outcome metrics over acquisition cost.
Supply Chain Analysis
Germany and Switzerland anchor precision optical glass and articulation cable assembly production for Japanese endoscope manufacturers. CMOS sensor arrays draw from Taiwanese foundry capacity and South Korean packaging operations. Single-source vulnerability concentrates in specialized illumination fiber bundles where Schott AG maintains dominant supply position. Distribution runs through authorized dealer networks with direct service contracts increasingly unbundled in metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's endoscopy sector sits at a platform-economics inflection where AI-integrated imaging platforms are displacing standalone hardware value capture. Interoperability demands from hospital PACS infrastructure are consolidating procurement decisions around software-native vendors with algorithmic detection capabilities.
For Market Incumbents: Secure captive sterilization infrastructure investments to defend against PMDA revalidation margin compression. Deepen backward integration into CMOS sensor calibration capabilities to offset software-native entrant disruption in AI-enhanced detection workflows. Prioritize JIS electromagnetic compatibility certification to maintain integrated operating room specification compliance. For New Entrants and Emerging Players: Rural hospital maintenance service gaps present immediate white-space opportunity where Olympus and Fujifilm service networks under-penetrate. Kyushu and Hokkaido secondary cities offer most penetrable geography for EUS-guided diagnostic procedure expansion. Pursue third-party biomedical service provider partnerships as primary go-to-market channel to bypass incumbent capital equipment bundling. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors algorithm-native specialists with PMDA software-as-medical-device approval momentum over legacy optical hardware manufacturers. Long-term viability in the 5-10 year window hinges on clinical evidence generation scale for AI training dataset validation. Watch PMDA algorithm validation protocol publication timelines as inflection indicator for regulatory pathway acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Software-as-Medical-Device Submission | Accelerates regulatory timelines for AI-integrated imaging platforms in Kansai academic centers. |
| Hospital System Partnership | Direct maintenance agreements with Tokyo metropolitan clusters bypass traditional vendor bundling structures. |
| Backward Integration into CMOS Calibration | Captures sensor optimization margin and reduces dependence on Taiwanese foundry service tiers. |
| Rural Service Network Expansion | Addresses Hokkaido and Kyushu maintenance gaps where incumbent coverage remains sparse. |
| Reimbursement Strategy Development | Demonstrates clinical outcome improvements to METI for premium tier placement under pricing reforms. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across hospital purchasing committees, biomedical engineering departments, and GPO contracts managers. Primary interviews with clinicians performing EUS-guided procedures and sterilization technicians at Tokyo and Osaka tertiary facilities combined with secondary validation from PMDA device registration databases, METI medical device pricing bulletins, and hospital procurement contract disclosures. Bottom-up procedural volume estimates and top-down equipment replacement cycle analysis were triangulated to calibrate market sizing.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product type flexibility, technology architecture migration, end-user tier concentration, and application-specific reimbursement bands. CAGRs were derived from replacement cycle acceleration patterns and metropolitan cluster adoption curves. Forecast inputs incorporated PMDA regulatory pathway timelines and METI pricing reform implementation phases.
Forecasts assume regulatory continuity in PMDA software-as-medical-device classification and METI reimbursement frameworks; material policy shifts would require re-modeling. Specific risks include JIS standards evolution for electromagnetic compatibility and algorithm validation protocol changes. Recalibration cycles align with material shifts in PMDA guidance publication and METI pricing reform announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endorectal Balloon Market
Endoscopy
Global Endoscopy Ultrasound Market
Endoscopy
Veterinary Video Endoscopy Market
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
China Arthroscopy Market
Endoscopy
Saudi Arabia Endoscopy Devices Market
Endoscopy
Endoscopic Stricture Management Market
Endoscopy
Endoscopy Fluid Management Systems Market
Endoscopy
Global Endoscopic Ultrasound Needles Market
Endoscopy
Nasopharyngoscope Market
Endoscopy
Netherlands Endoscopy Devices Market
Endoscopy
United States Endoscopy Devices Market
Endoscopy
Global Endoscopic Vessel Harvesting Systems Market
Endoscopy
Argentina Endoscopy Devices Market
Endoscopy
Hysteroscopic Endometrial Resection Procedures Market
Endoscopy
Global Endoscope Leak Detection Device Market