
 Global Gastrointestinal Bleeding Treatment Market | 2026-2036
Global Gastrointestinal Bleeding Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gastrointestinal Bleeding Treatment Market Intelligence
Software-enabled diagnostic modules integrated into endoscopic systems is broadening the scope of treatment beyond simple hemorrhage control. Olympus Corporation leverages its dominance in core endoscopy to integrate these advanced features. Boston Scientific Corporation competes through its portfolio of specialized mechanical clips and thermal coagulation devices. Medtronic Plc positions its offerings to serve high-volume hospital networks requiring standardized, effective solutions for common bleeding etiologies.
Gastrointestinal bleeding treatment encompasses medical interventions designed to stop hemorrhage within the digestive tract. These procedures often employ endoscopic devices, such as thermal probes that deliver argon plasma coagulation to cauterize bleeding sites. Endoscopic devices and hemostatic agents constitute the core product segments for managing acute bleeds. While hospitals remain the largest end user, ambulatory surgery centers represent the fastest-growing segment for elective and follow-up procedures.
Device and agent approval pathways are governed by bodies like the US FDA, which requires extensive clinical data. In Europe, CE marking under the Medical Device Regulation (MDR) is mandatory, while China's NMPA sets its own standards for market access. The critical decision for providers now centers on balancing the higher cost of novel topical agents against their potential for reduced re-bleeding rates.
Market Dynamics
The procedural shift from inpatient hospital settings to ambulatory surgery centers is the central force shaping the market. This migration demands devices optimized for faster turnaround times and procedural efficiency, influencing product design and purchasing criteria across health systems.
Growth Catalysts
- Aging Demographics:The rising incidence of gastrointestinal conditions in aging populations, particularly in Japan and Germany, directly stimulates demand for endoscopic bleeding management procedures and associated devices.
- Ambulatory Surgery Center Expansion:Growth in outpatient procedures within the United States health system creates a specific need for effective, easy-to-use hemostatic agents and single-use devices that facilitate quicker patient discharge.
- Advanced Topical Agents:The development of novel hemostatic powders and gels that demonstrate superior efficacy in reducing re-bleeding rates is encouraging adoption by clinicians seeking better patient outcomes.
Market Restraints
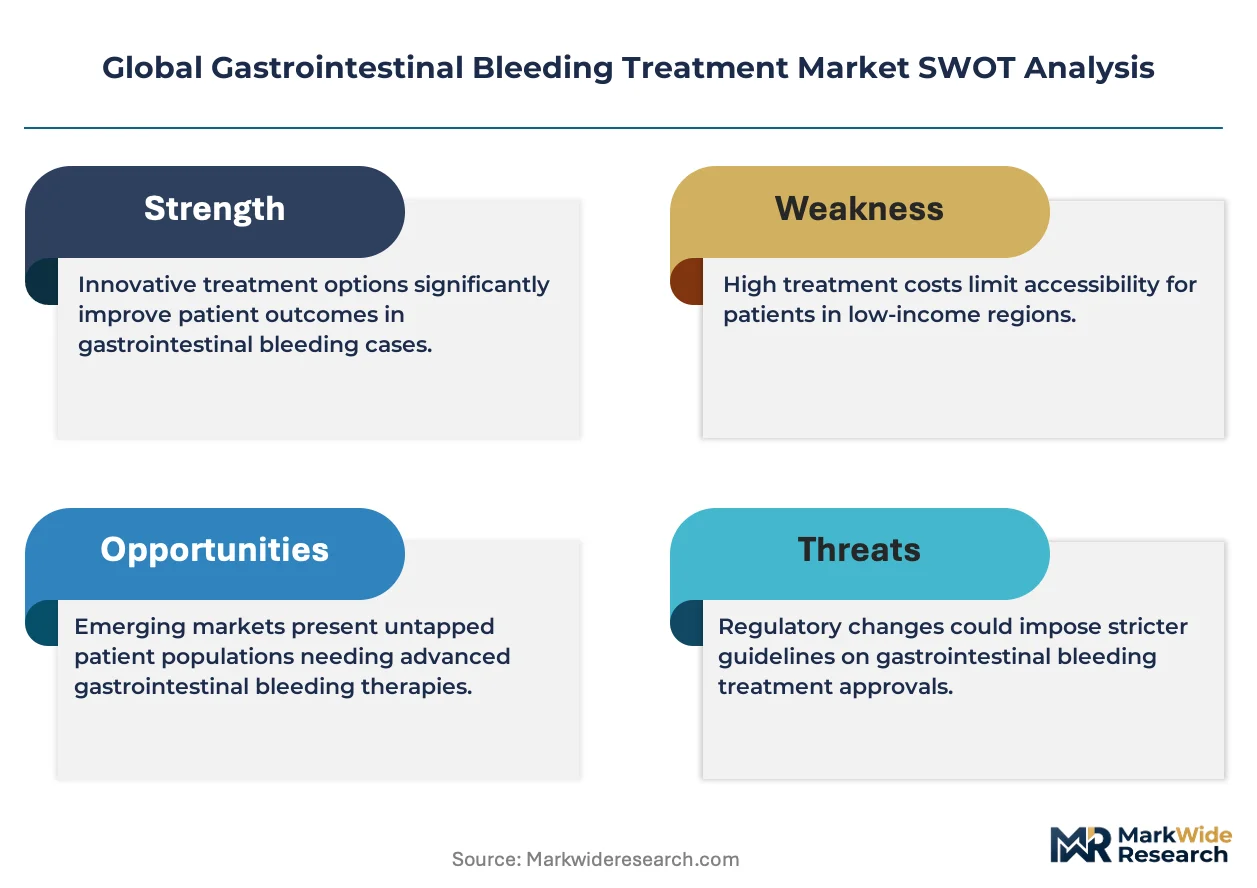
- High Device Costs:The significant upfront cost of advanced devices, such as over-the-scope clips and sophisticated thermal coagulation systems, acts as a barrier to adoption for budget-constrained hospitals.
- Stringent Regulatory Pathways:The rigorous clinical evidence required for market approval from bodies like the US FDA and for CE marking under the EU MDR prolongs product development timelines.
- Reimbursement Uncertainty:Inconsistent reimbursement policies for newer, more expensive topical hemostatic agents across different healthcare payers limits predictable access for providers and patients.
Strategic Opportunities
- AI-Powered Diagnostics:Integrating artificial intelligence software into endoscopic platforms to automatically detect and characterize bleeding lesions presents a significant opportunity to improve diagnostic accuracy and guide treatment.
- Biodegradable Implants:Developing bioresorbable mechanical clips that securely stop bleeding and then safely dissolve over time would eliminate the need for subsequent removal procedures, enhancing patient convenience.
- Emerging Market Penetration:Expanding the availability of foundational endoscopic hemostasis technologies in healthcare systems across Southeast Asia and Latin America addresses a large, underserved patient population.
Industry Challenges
- Specialized Clinician Training:The effective use of advanced endoscopic hemostasis techniques requires specialized training and continuous education for gastroenterologists, creating an implementation bottleneck for new technologies.
- Cold Chain Logistics:Certain biologic-based hemostatic agents require an uninterrupted cold chain from manufacture to the endoscopy suite, introducing logistical complexity and potential for product spoilage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gastrointestinal Bleeding Treatment Market |
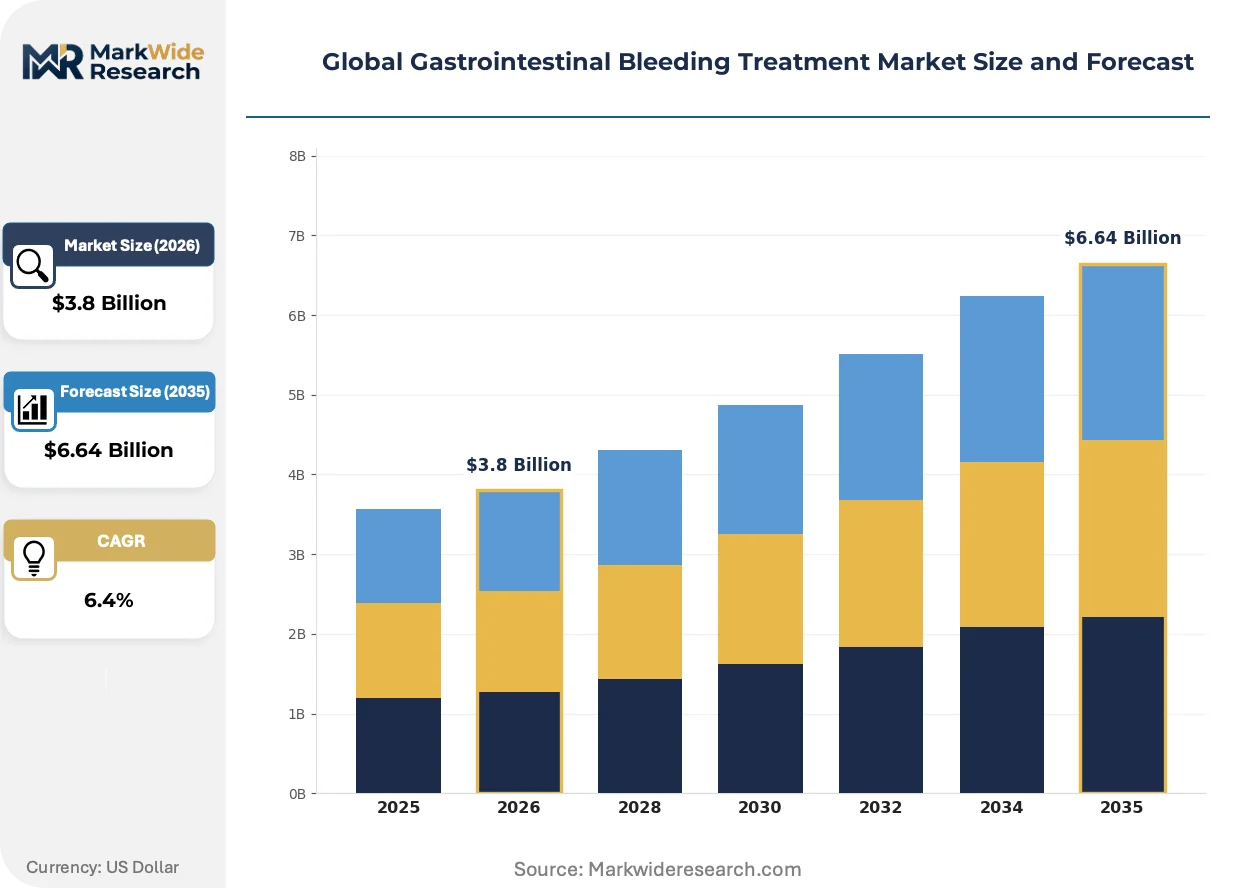
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopic Devices, Hemostatic Agents, Thermal Coagulation Devices, Mechanical Clips, Topical Agents, Banding Systems Therapy Area: Peptic Ulcer Bleeding, Esophageal Varices, Mallory-Weiss Tear, Angiodysplasia, Diverticular Bleeding, Dieulafoy Lesion End User: Hospitals, Ambulatory Surgery Centers, Gastroenterology Clinics, Emergency Care Units Delivery Mode: Invasive Procedures, Minimally Invasive Techniques, Pharmacological Treatment, Endoscopic Intervention |
| Companies Covered | Boston Scientific Corporation, CONMED Corporation, Cook Group, Erbe Elektromedizin GmbH, Ovesco Endoscopy AG, Olympus Corporation, STERIS plc, Medtronic Plc, EndoClot Plus Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gastrointestinal Bleeding Treatment Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of material science innovations and software intelligence. These forces are creating a new generation of tools that enhance precision and improve patient safety during hemostatic procedures.
Topical hemostatic powders are designed for endoscopic application over broad, oozing bleeding surfaces that are difficult to treat with focal therapies. Gastroenterology departments in high-volume hospitals are rapidly adopting these agents for managing diffuse non-variceal bleeds. This powder-based approach is overtaking traditional injection sclerotherapy for specific etiologies due to its ease of use and ability to cover large areas quickly.
Regulatory frameworks are mandating higher standards for clinical evidence and post-market surveillance. Europe's Medical Device Regulation (MDR) requires manufacturers to provide more extensive data on the long-term safety and performance of devices. This affects hemostatic clips and thermal probes, forcing companies to invest heavily in clinical studies to maintain or gain market access in the EU.
A notable shift in purchasing behavior involves hospital systems prioritizing total cost of care over individual device price. Large integrated delivery networks in the United States are evaluating products based on their ability to reduce re-bleeding rates, shorten hospital stays, and minimize repeat procedures. This value-based procurement model favors devices with strong clinical evidence supporting superior patient outcomes.
Global Gastrointestinal Bleeding Treatment Market Segmentation
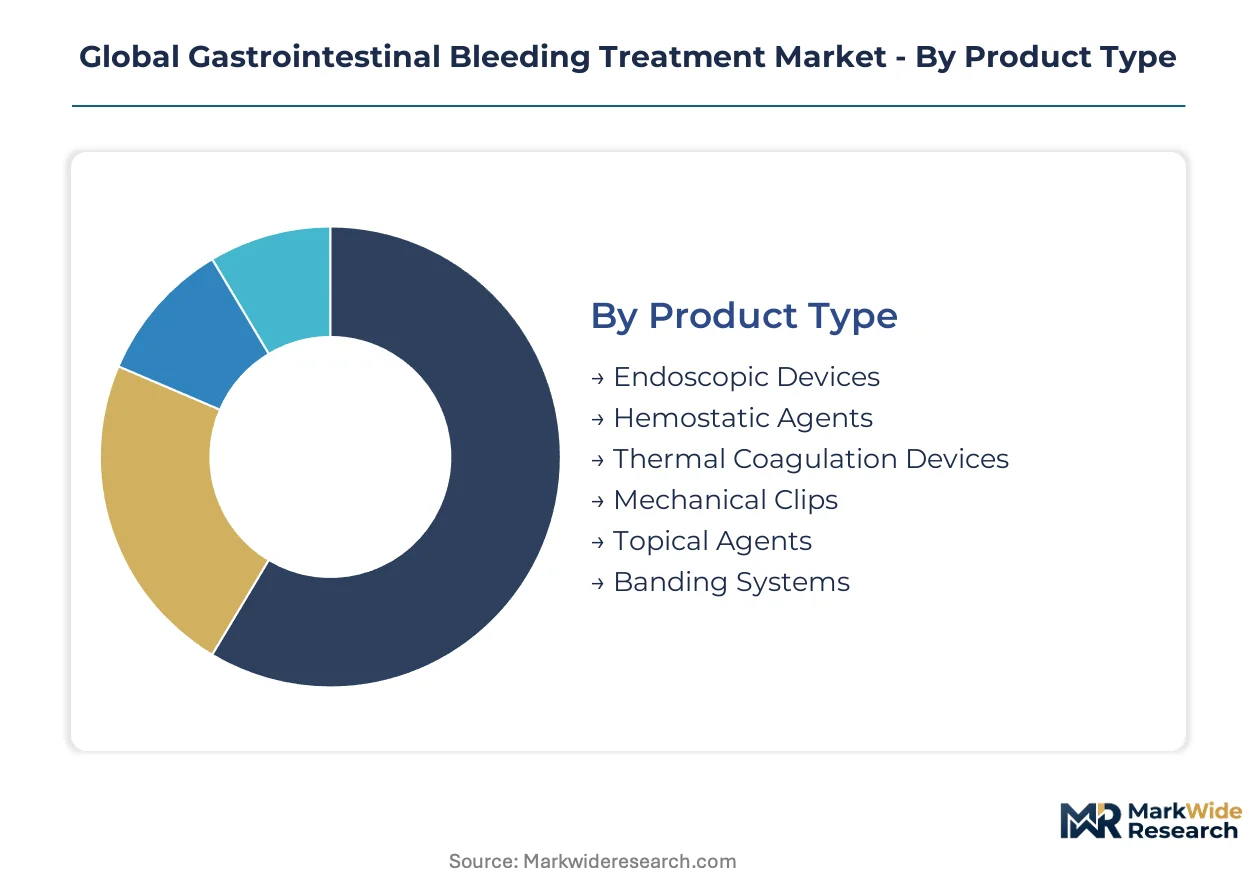
Understanding the varied segments within the global gastrointestinal bleeding treatment market is critical for stakeholders to align product development and market strategies. This segmentation highlights the distinct product types, therapy areas, end-user profiles, and delivery modes that define the competitive landscape and demand drivers for effective hemorrhage control.
Product Type:
The choice of gastrointestinal bleeding treatment products often hinges on clinical efficacy and procedural efficiency for specific bleeding etiologies.
- Endoscopic Devices:These instruments, including endoscopes and accessory tools, visualize the bleeding site and facilitate intervention. Demand concentrates in hospital systems across the United States and Germany due to established infrastructure and high procedural volumes.
- Topical Agents:These include powders and gels applied directly to bleeding surfaces to promote hemostasis. Gastroenterology departments in high-volume hospitals are rapidly adopting these agents for managing diffuse non-variceal bleeds, driven by their ease of use and ability to cover large areas quickly.
- Hemostatic Agents:This broad category encompasses various substances, including injectables and sprays, designed to stop bleeding.
- Thermal Coagulation Devices:These devices use heat, such as argon plasma coagulation, to cauterize bleeding vessels.
- Mechanical Clips:These are metal clips deployed endoscopically to close bleeding vessels or perforations.
- Banding Systems:Primarily used for esophageal varices, these systems apply elastic bands to ligate bleeding vessels.
Endoscopic Devices lead on scale; Topical Agents lead on momentum.
Therapy Area:
Application-specific requirements significantly influence the selection of appropriate treatment modalities for gastrointestinal hemorrhage.
- Peptic Ulcer Bleeding:This common condition involves bleeding from ulcers in the stomach or duodenum, frequently managed with endoscopic clips or thermal therapy. Demand for these interventions is consistently high across all major healthcare systems, including Japan and the United States.
- Esophageal Varices:Caused by portal hypertension, these are enlarged veins in the esophagus prone to severe bleeding, often treated with banding systems or sclerotherapy. Management of these complex cases drives demand for specialized endoscopic techniques in tertiary care centers.
- Mallory-Weiss Tear:This involves a tear in the esophageal lining, typically due to forceful vomiting, often requiring endoscopic hemostasis.
- Angiodysplasia:Characterized by fragile blood vessels in the gastrointestinal tract, this condition causes chronic or recurrent bleeding.
- Diverticular Bleeding:Bleeding from small pouches in the colon, often managed endoscopically or through angiography.
- Dieulafoy Lesion:A rare vascular anomaly causing recurrent, severe gastrointestinal bleeding, requiring precise endoscopic intervention.
Peptic Ulcer Bleeding cases constitute the largest patient volume, while Esophageal Varices demand highly specialized interventions.
End User:
The operational model and patient volume of a healthcare facility determine its procurement needs for GI bleeding solutions.
- Hospitals:These facilities manage the majority of acute and complex gastrointestinal bleeding cases, requiring a comprehensive range of devices and agents. Hospitals in Germany and the United States represent significant purchasing power due to their large patient populations and established reimbursement frameworks.
- Ambulatory Surgery Centers:These outpatient facilities increasingly handle elective and follow-up endoscopic procedures for GI bleeding, prioritizing devices optimized for faster turnaround times. The expansion of these centers in the United States creates specific demand for efficient, easy-to-use hemostatic agents.
- Gastroenterology Clinics:These specialized clinics focus on diagnostic endoscopy and less severe bleeding interventions.
- Emergency Care Units:These units provide immediate stabilization for acute GI bleeding patients before transfer to specialized departments.
Hospitals manage the vast majority of acute GI bleeds, whereas Ambulatory Surgery Centers are expanding most quickly for elective procedures.
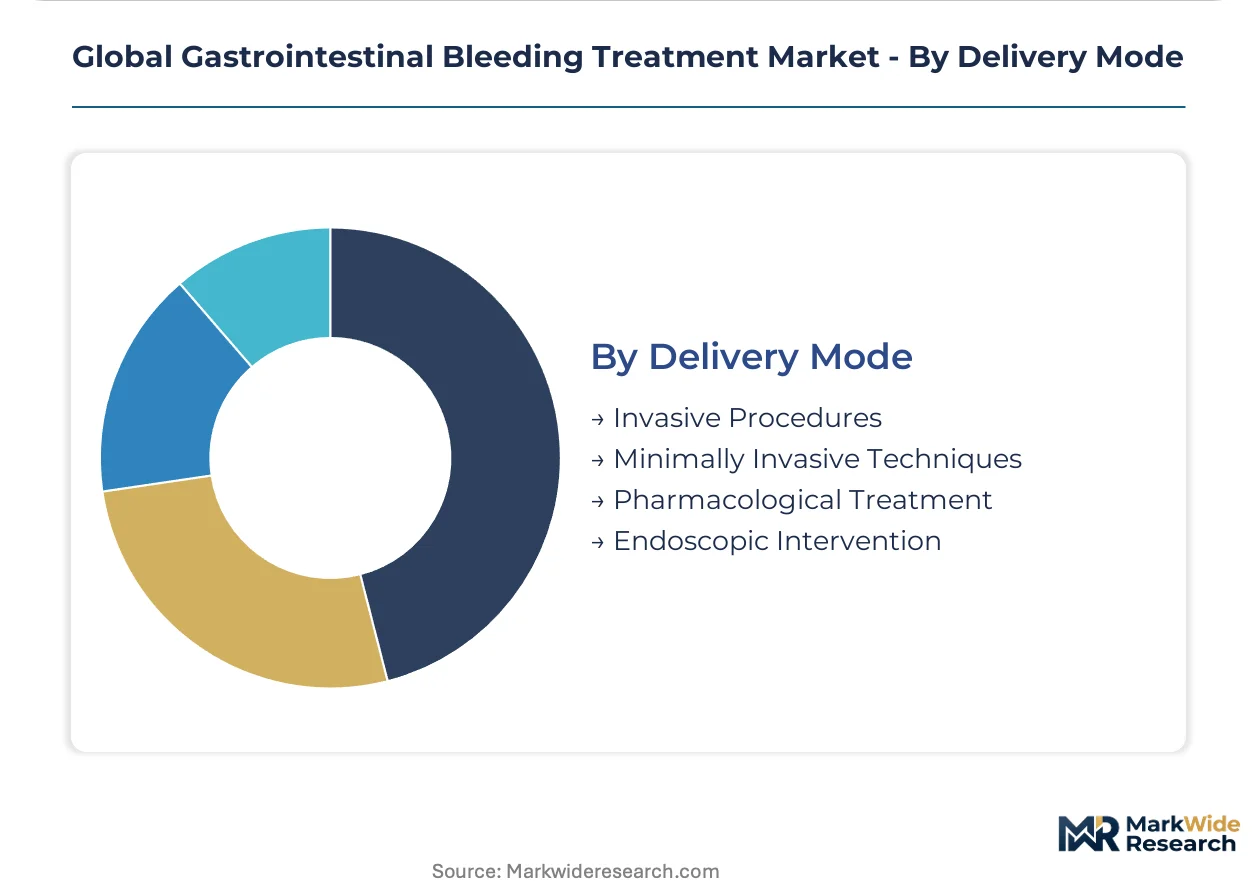
Delivery Mode:
Technological advancements and patient comfort drive the evolution of delivery modes in gastrointestinal bleeding management.
- Endoscopic Intervention:This minimally invasive approach uses an endoscope to visualize and treat bleeding sites directly, forming the cornerstone of acute GI bleeding management. Hospitals in Japan and the United States extensively utilize endoscopic techniques due to their effectiveness and established procedural guidelines.
- Minimally Invasive Techniques:This category encompasses endoscopic and other less invasive methods designed to reduce patient recovery time and improve outcomes. These techniques are gaining preference across various healthcare settings, including ambulatory surgery centers, for their efficiency.
- Invasive Procedures:These include surgical interventions reserved for severe cases where endoscopic methods fail or are not feasible.
- Pharmacological Treatment:This involves the use of medications to control bleeding, often as an adjunct to other therapies or for specific etiologies.
Endoscopic Intervention remains the cornerstone of acute GI bleeding management, supported by a shift towards less invasive approaches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States drives innovation in gastrointestinal bleeding treatment through its extensive ambulatory surgery center network, Germany's demand is shaped by an aging population requiring frequent endoscopic interventions. Japan also exhibits high demand for advanced endoscopic solutions due to similar demographic pressures. Emerging markets in Asia present significant growth opportunities for foundational technologies.
United States
The United States market for GI bleeding treatment is propelled by the expansion of ambulatory surgery centers and a strong emphasis on reducing re-bleeding rates. The US FDA's stringent approval process for novel devices ensures high standards of clinical efficacy. Major healthcare systems in metropolitan areas like New York and Los Angeles are prioritizing devices that offer faster turnaround times and improved patient outcomes.
Germany
Germany's demand for gastrointestinal bleeding treatments stems from its aging demographic and established healthcare infrastructure. CE marking under the Medical Device Regulation (MDR) is mandatory for market access, influencing product development. Specialist clinics in regions such as Bavaria and North Rhine-Westphalia are adopting advanced thermal coagulation systems to manage complex cases efficiently.
Japan
Japan's market is characterized by a high incidence of gastrointestinal conditions in its elderly population, leading to consistent demand for endoscopic interventions. The PMDA regulates medical device approvals, emphasizing safety and clinical performance. Hospitals in major urban centers like Tokyo and Osaka are key adopters of sophisticated endoscopic devices and specialized hemostatic agents.
China
China presents a large, underserved patient population for gastrointestinal bleeding treatments, with increasing access to modern medical technologies. The NMPA sets national standards for medical device registration and market entry. Major hospital networks in the Yangtze River Delta and Pearl River Delta regions are expanding their endoscopy capabilities, driving demand for both devices and topical agents.
India
India's market for GI bleeding treatment is growing due to improving healthcare access and an increasing prevalence of lifestyle-related gastrointestinal disorders. The CDSCO regulates medical devices, focusing on both local manufacturing and imported products. Tertiary care centers in cities such as Mumbai and Delhi are investing in endoscopic devices to manage acute bleeding episodes.
Global Gastrointestinal Bleeding Treatment Market Key Industry Players
Top-tier vendors anchor the premium segment, while a diverse array of specialized manufacturers competes in niche areas and cost-effective solutions. The market exhibits a tiered structure, with global players dominating comprehensive offerings and regional companies focusing on specific product lines. Strategic archetypes include integrated solution providers, specialized device manufacturers, and topical agent innovators. Dominant competitive moves include portfolio diversification into related endoscopic accessories and strategic partnerships for geographic expansion.
Integrated solution providers like Olympus Corporation exemplify comprehensive offerings across endoscopic systems and accessory tools. Boston Scientific Corporation represents a specialized device manufacturer, focusing on mechanical clips and thermal coagulation devices. Medtronic Plc occupies a position as a provider of standardized, effective solutions for high-volume hospital networks, emphasizing reliability and broad utility.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| CONMED Corporation |
| Cook Group |
| Erbe Elektromedizin GmbH |
| Ovesco Endoscopy AG |
| Olympus Corporation |
| STERIS plc |
| Medtronic Plc |
| EndoClot Plus Inc. |
| Others |
Cost & Logistics Intelligence
Hospital systems' value-based procurement models are reshaping product design and purchasing criteria for gastrointestinal bleeding treatments. This demand-side pressure requires suppliers to optimize devices for procedural efficiency and superior patient outcomes, influencing pricing structures across the market.
Pricing Analysis
Capacity additions in specialized manufacturing hubs are reshaping price floors for certain endoscopic devices. The dominant pricing model reflects value-based procurement, where clinical efficacy in reducing re-bleeding rates and procedural efficiency are key differentiation drivers. Cost compression for advanced devices intensifies due to budget-constrained hospitals and inconsistent reimbursement policies. Large integrated delivery networks, however, prioritize devices with strong clinical evidence, making them less price-sensitive than smaller, budget-focused facilities.
Supply Chain Analysis
Workforce availability in key manufacturing geographies, particularly across China and Europe, impacts the production of advanced medical devices and topical agents. The supply chain for gastrointestinal bleeding treatments draws from specialized metals for mechanical clips and complex biologic compounds for hemostatic agents. Cold chain logistics for biologic-based hemostatic agents represent a significant structural risk, introducing potential for spoilage. Distribution runs through established hospital networks and rapidly expanding ambulatory surgery centers, often requiring direct sales or specialized medical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gastrointestinal bleeding treatment market is transitioning into a late-cycle quality story. Hospital systems' focus on superior patient outcomes, especially reduced re-bleeding rates, drives demand for premium, clinically validated solutions.
For Market Incumbents: Deploy advanced software integration into existing endoscopic platforms to enhance diagnostic accuracy and treatment guidance. Strengthen clinical evidence for novel hemostatic agents to justify higher costs against potential re-bleeding reductions, addressing reimbursement uncertainty. Expand training programs for gastroenterologists to overcome implementation bottlenecks for new technologies, countering specialized clinician training challenges.
For New Entrants and Emerging Players: Ambulatory surgery centers represent a penetrable segment for new entrants, prioritizing efficient, easy-to-use hemostatic agents and single-use devices. Partner with regional distributors specializing in outpatient facilities to establish rapid market presence. Focus on developing biodegradable mechanical clips that dissolve naturally, offering enhanced patient convenience and differentiating from established competitors.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized device manufacturers and topical agent innovators demonstrating superior clinical outcomes. Long-term viability over a five to ten-year window favors companies with strong intellectual property in AI-powered diagnostics and bioresorbable implants. The signal to watch is the adoption rate of novel topical hemostatic agents in high-volume hospital networks, indicating a shift towards value-based procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Integrate AI for automated lesion detection, improving diagnostic precision. |
| CE Marking Pathway | Ensure compliance with EU Medical Device Regulation, securing market access in Europe. |
| Hospital System Partnership | Secure adoption in high-volume networks, fostering standardized treatment protocols. |
| Product Launch (Biodegradable Clips) | Introduce novel dissolving hemostatic devices, enhancing patient convenience and safety. |
| Reimbursement Strategy | Advocate for coverage of high-value topical agents, expanding patient access. |
Research Approach
Multiple input streams — primary interviews with gastroenterologists, hospital procurement managers, and regulatory affairs specialists, alongside secondary data from medical device databases, clinical trial registries, and government health reports — were reconciled. This approach ensured comprehensive data collection from both demand and supply sides. Bottom-up and top-down triangulation validated market size and growth projections.
Data-stream reconciliation established an analytical framework to project market trends across the analysis window. Segmentation dimensions modeled included product type, therapy area, end-user, delivery mode, and regional regulatory frameworks. Compound annual growth rates were derived from historical data analysis and future market drivers. Key forecast inputs included aging population statistics and ambulatory surgery center expansion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving regulatory pathways and novel technology adoption. Forecasts reflect assumptions regarding clinical evidence requirements and reimbursement policy shifts. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Peptic Ulcer Market
Gastroenterology
Chronic Liver Diseases Therapeutics Market
Gastroenterology
Gastritis Treatment Market
Gastroenterology
US Inflammatory Bowel Disease Treatment Market
Gastroenterology
High Definition Ultrasound Gastroscope Market
Gastroenterology
Diverticular Disease Therapeutics Market
Gastroenterology
Chile Gastric Cancer Treatment Market
Gastroenterology
Colon Hydrotherapy Market
Gastroenterology
Stomach Cancer Market
Gastroenterology
Gastroretentive Drug Delivery Systems Outsourcing Market
Gastroenterology
Inflammatory Bowel Disease Treatment Market
Gastroenterology
Intestinal Fistula Treatment Market
Gastroenterology
Gastric Cancer Market
Gastroenterology
Polyps Market
Gastroenterology
Gluten Intolerance Treatment Market
Gastroenterology
Digestive Health Products Market