
 Malignant Ascites Market | 2026-2036
Malignant Ascites Market Size, Share, and Industry Trends Forecast 2026-2036
Malignant Ascites Market Foresight
Minimally invasive fluid evacuation technology is tilting malignant ascites management away from repeated paracentesis toward indwelling catheter systems. Fresenius leverages its dialysis infrastructure to anchor peritoneal access device distribution across European hospital networks. Becton Dickinson competes through specialized interventional radiology portfolios that dominate inpatient drainage procedures.
Malignant ascites denotes pathological accumulation of protein-rich fluid in the peritoneal cavity secondary to metastatic cancer, typically exceeding 500 mL in volume and requiring therapeutic drainage to relieve abdominal pressure and respiratory compromise. Catheters and drainage devices occupy the largest revenue pool within product types due to recurring replacement cycles and infection-control protocols, while intraperitoneal port systems represent the fastest-growing segment as interventional oncology expands catheter-directed drug delivery. Among therapy areas, palliative care sustains the deepest penetration since curative options remain limited for refractory ascites, though surgical intervention generates premium pricing for specialized drainage hardware.
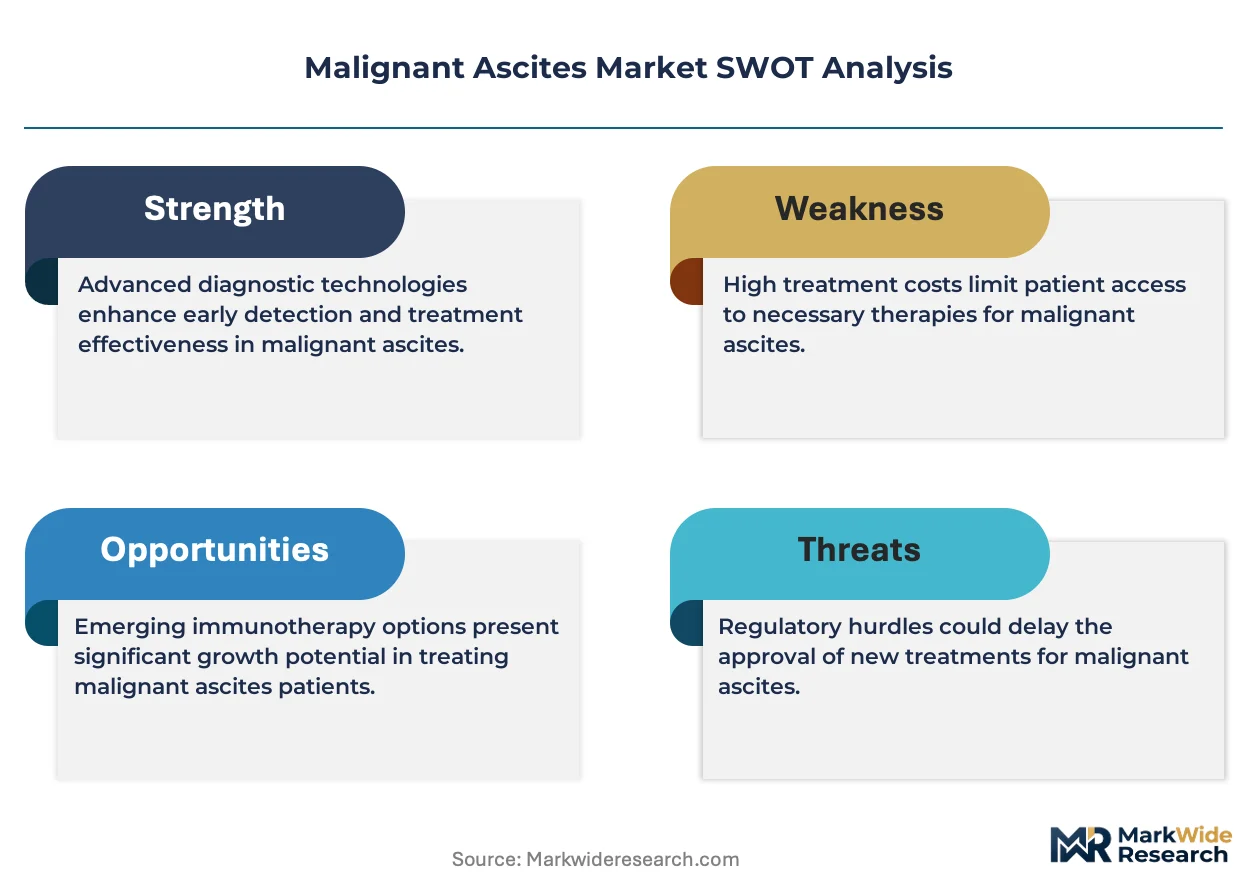
FDA 510(k) clearance pathways and EMA medical device regulations shape product development timelines and sterilization standards for implantable ascites hardware. ISO 13485 quality management systems and HIPAA data protocols further govern manufacturers serving connected drainage monitoring platforms. Stakeholders must weigh reimbursement volatility against the shift toward outpatient and home healthcare delivery models when allocating R&D resources across catheter portfolios.
Market Dynamics
The transition from repeated paracentesis to indwelling catheter systems is compressing procedure volumes while expanding hardware replacement cycles and infection-control service revenue across oncology departments.
Growth Catalysts
- Hospital palliative care expansion:Oncology departments in the United States, Germany, and Japan are building dedicated ascites management units that standardize catheter-based drainage protocols.
- MDR sterility benchmarks:The EU Medical Device Regulation is accelerating hospital procurement of single-use drainage sets with validated biocompatibility certification.
- Interventional radiology growth:Image-guided catheter placement is displacing surgical port installation in academic medical centers, reducing recovery times and enabling same-day discharge.
Market Restraints
- Silicone and polyurethane feedstock volatility:Medical-grade polymer prices fluctuate with petrochemical markets, squeezing margins on catheter manufacturing.
- Single-supplier concentration for implantable ports:European hospital networks depend on a narrow base of contract manufacturers for titanium-reinforced intraperitoneal hardware.
- Reimbursement compression in Medicare:The Centers for Medicare & Medicaid Services has narrowed coverage criteria for outpatient drainage procedures, limiting home healthcare expansion.
Strategic Opportunities
- Home healthcare penetration in Japan:METI incentives for aging-in-place infrastructure are creating demand for patient-managed drainage systems with telemedicine integration.
- Intraperitoneal chemotherapy delivery:Catheter-directed regional therapy for ovarian and gastric malignancies is opening parallel revenue streams beyond palliative fluid evacuation.
- ISO 13485-certified contract manufacturing:Outsourced sterilization and packaging services are enabling mid-size device firms to enter European markets without captive cleanroom investment.
Industry Challenges
- Interventional radiology training pipeline:Academic medical centers report insufficient fellowship slots to meet demand for image-guided ascites management specialists.
- FDA 510(k) pathway compression:Substantial equivalence determinations for next-generation drainage catheters are extending review timelines, delaying commercial launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malignant Ascites Market |
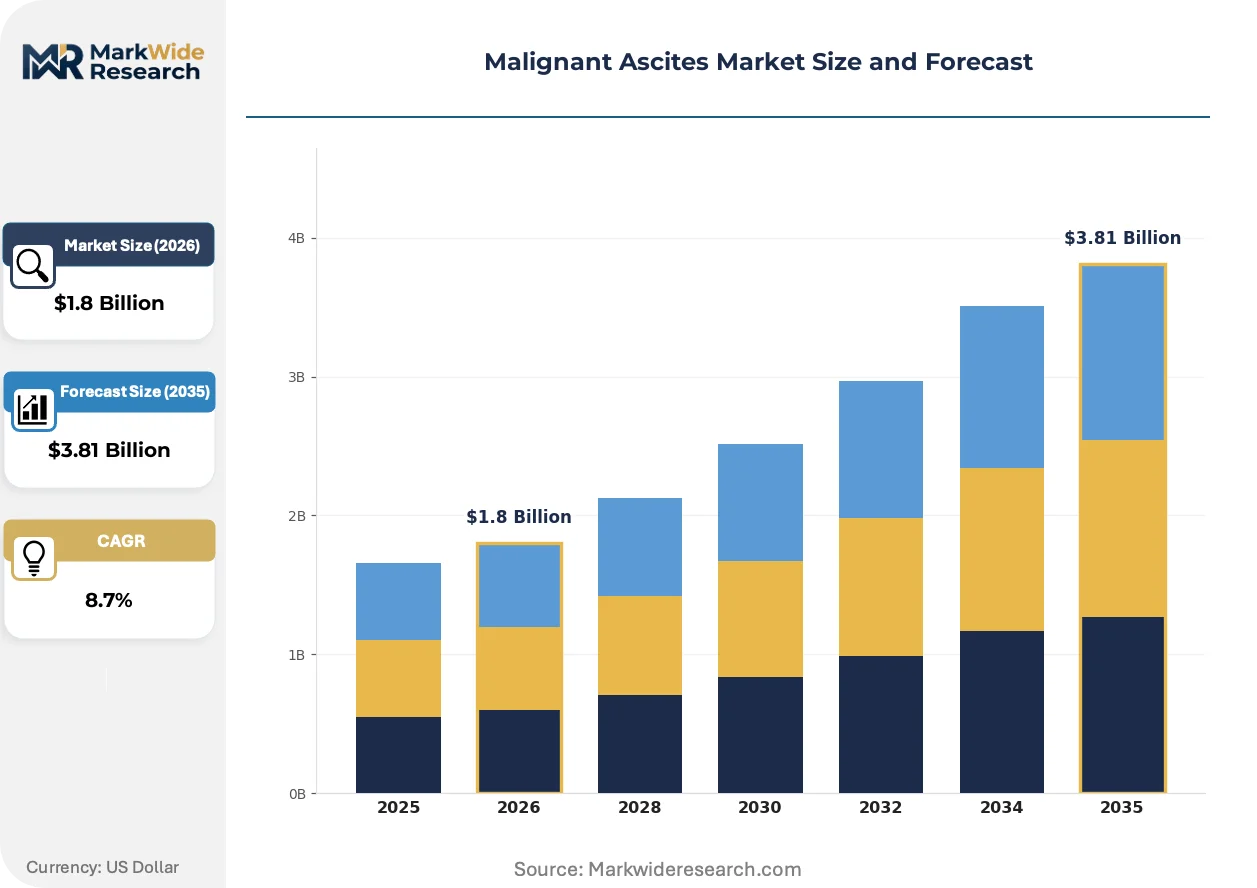
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Drainage Devices, Intraperitoneal Port Systems, Ascitic Fluid Pumps Therapy Area: Oncology, Palliative Care, Surgical Intervention, Symptom Management Delivery Mode: Inpatient Care, Outpatient Care, Home Healthcare, Telehealth Services End User: Hospitals, Specialty Clinics, Long-term Care Facilities, Homecare Providers |
| Companies Covered | Medtronic, Fresenius, Pfizer, Clover Biopharmaceuticals, BioVie, Becton Dickinson, Merit Medical Systems, Sequana Medical, B. Braun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malignant Ascites Market Shifts & Advancements
Device connectivity and closed-system drainage architecture are converging to reshape how clinicians monitor fluid output and detect infection. These shifts favor manufacturers with integrated software-hardware capabilities.
Programmable vacuum-assisted drainage is migrating from surgical recovery units to outpatient oncology clinics. Interventional radiologists at tertiary centers in Germany and the United States are adopting these systems for refractory ascites cases. The technology is migrating from inpatient reimbursement codes toward ambulatory surgical center billing, compressing per-procedure revenue while extending patient monitoring contracts.
The FDA's updated biocompatibility guidance for permanent implant devices is tightening cytotoxicity and sensitization testing requirements for silicone-based catheters. Manufacturers must now submit extended rabbit intracutaneous reactivity data and genotoxicity screening. Intraperitoneal port systems face the steepest compliance burden, with several submissions receiving additional information requests that extend clearance timelines by six to nine months.
Oncology procurement committees are consolidating vendor relationships around full-service drainage contracts that bundle hardware, replacement schedules, and infection surveillance. Hospital purchasing in Japan and Germany favors single-source agreements with defined per-patient cost caps over transactional device orders. This concentration is visible most acutely in university hospital networks, where standardization committees now mandate interoperable connection standards across catheter and port portfolios.
Malignant Ascites Market Segmentation
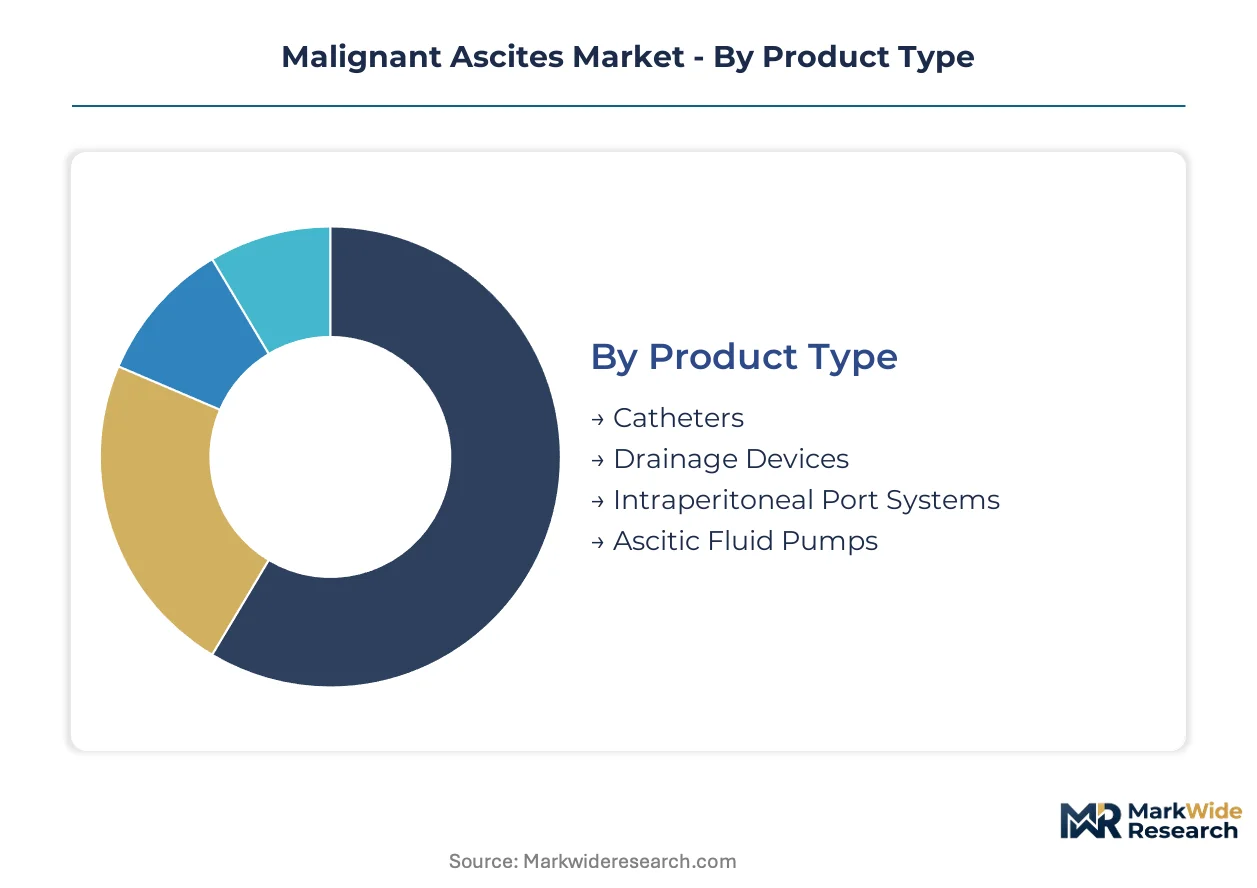
Segmentation in malignant ascites management reveals how reimbursement pathways, clinical setting infrastructure, and patient acuity reshape procurement priorities across hardware categories. Understanding these divisions exposes where catheter replacement cycles concentrate versus where emerging delivery modes disrupt established revenue pools.
Product Type:
Cost tier differentiation separates commodity drainage hardware from premium implantable systems with extended biocompatibility certification cycles.
- Catheters:Silicone and polyurethane construction dominates, with tunneled designs reducing peritonitis rates in long-term indwelling applications. United States hospital networks standardize on antimicrobial-impregnated variants to satisfy Joint Commission infection benchmarks, though polymer feedstock volatility squeezes contract manufacturer margins.
- Drainage Devices:Vacuum-assisted and gravity-fed systems comprise this mid-tier category, with closed-system architecture becoming mandatory under EU MDR sterility protocols. German university hospitals drive specification tightening through centralized procurement consortia that mandate validated biofilm resistance testing.
- Intraperitoneal Port Systems:Titanium-reinforced implantable ports with dual-lumen designs enable concurrent fluid evacuation and chemotherapy delivery.
- Ascitic Fluid Pumps:Programmable implantable pumps remain limited to specialized interventional oncology centers in Japan and the United States.
Catheters command the established base. The steepest expansion runs through intraperitoneal port systems.
Therapy Area:
Application focus determines whether procurement prioritizes disposable volume or durable hardware with premium service contracts.
- Oncology:Interventional radiology departments at tertiary centers in Germany and Japan anchor demand for catheter-directed regional therapy, with intraperitoneal chemotherapy protocols requiring specialized port systems that withstand cytotoxic agent exposure.
- Palliative Care:Hospice and hospital-based palliative units across the United States generate recurring revenue through scheduled drainage procedures and infection surveillance protocols. Medicare reimbursement compression is narrowing coverage for repeated paracentesis, accelerating shift toward indwelling catheter management.
- Surgical Intervention:Peritoneovenous shunt placement has retreated to salvage cases after catheter technology improved.
- Symptom Management:Respiratory compromise and abdominal pressure relief drive acute care utilization.
Palliative care captures volume concentration. Oncology applications are climbing the fastest.
Delivery Mode:
Patient acuity and reimbursement site-of-service rules determine where fluid evacuation procedures migrate across care settings.
- Inpatient Care:Acute decompensation and initial catheter placement remain concentrated at academic medical centers with interventional radiology coverage. United States hospital systems are compressing length-of-stay through same-day discharge protocols that shift monitoring burden to outpatient infrastructure.
- Outpatient Care:Ambulatory surgical centers in Germany and Japan are capturing scheduled drainage procedures through bundled payment contracts that reward efficiency. PMDA and EMA pathway convergence on biocompatibility standards enables cross-border device sourcing for these settings.
- Home Healthcare:Patient-managed drainage with telemedicine oversight is expanding fastest in Japan under METI aging-in-place incentives.
- Telehealth Services:Remote monitoring of fluid output and infection markers supports home-based management.
Inpatient care retains the procedural base. Home healthcare shows the steepest trajectory.
End User:
Customer type segmentation exposes how purchasing authority concentrates in integrated delivery networks versus fragments across independent providers.
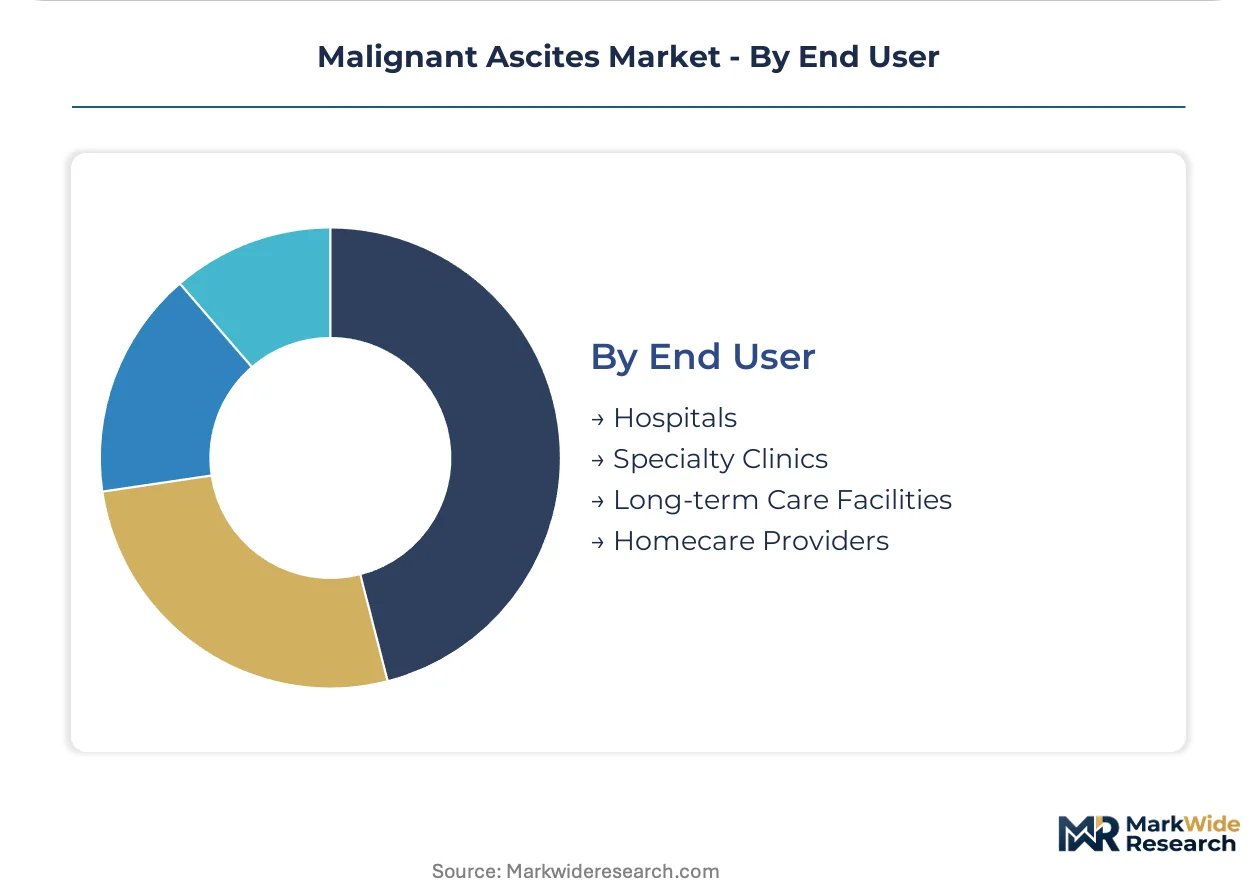
- Hospitals:Oncology and interventional radiology departments at university-affiliated centers in the United States, Germany, and Japan dominate capital equipment procurement. Standardization committees now mandate interoperable connection standards that lock in vendor relationships across replacement cycles.
- Specialty Clinics:Interventional radiology free-standing centers in Germany are capturing outpatient drainage volume through focused procedure efficiency.
- Long-term Care Facilities:Skilled nursing facilities face reimbursement barriers to advanced ascites management.
- Homecare Providers:Durable medical equipment suppliers with nursing oversight capabilities are expanding into drainage system rental and maintenance.
Hospitals command the established base. Specialty clinics are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German medical device manufacturers export catheter systems to United States hospital networks, while Japanese suppliers feed intra-Asian distribution channels for home healthcare drainage equipment.
United States
Oncology departments at Johns Hopkins and MD Anderson anchor catheter placement volumes for refractory ascites. CMS reimbursement compression under Medicare Part B narrows outpatient drainage coverage, pushing academic medical centers toward bundled payment contracts. Interventional radiology clusters in Houston and Boston standardize image-guided port installation protocols.
Germany
University hospital consortia in Baden-Württemberg and Bavaria drive centralized procurement of MDR-compliant drainage sets. The EU Medical Device Regulation accelerates validation requirements for silicone-based implantable hardware. Freiburg and Heidelberg medical technology corridors concentrate contract manufacturing for titanium-reinforced intraperitoneal ports.
Japan
METI aging-in-place incentives expand patient-managed drainage with telemedicine oversight in Kanto and Kansai regions. PMDA biocompatibility pathways converge with EMA standards, enabling cross-border device sourcing for ambulatory surgical centers. Tokyo and Osaka interventional oncology units pioneer programmable pump integration for intraperitoneal chemotherapy delivery.
United Kingdom
NHS England specialized commissioning frameworks concentrate ascites management at designated cancer centers in London and Manchester. MHRA post-Brexit device regulations maintain alignment with MDR sterility benchmarks for implantable ports. The Cambridge-Oxford-London golden triangle anchors clinical trial recruitment for next-generation catheter systems.
Switzerland
Swissmedic certification requirements for permanent implant devices attract premium catheter manufacturers to Basel and Zurich medical technology clusters. University Hospital Zurich and Geneva University Hospitals serve as reference centers for European interventional radiology training. Swiss hospital procurement favors single-source agreements with defined per-patient cost caps over transactional orders.
Malignant Ascites Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement environments. Hospital purchasing committees consolidate vendor relationships around full-service drainage contracts that bundle hardware, replacement schedules, and infection surveillance. Three archetypes dominate: diversified medical technology conglomerates with dialysis or interventional radiology infrastructure, mid-size device firms leveraging ISO 13485-certified contract manufacturing, and biopharmaceutical developers pursuing catheter-directed drug delivery platforms. Competitive moves center on M&A to capture interventional oncology capabilities and strategic partnerships to secure polymer feedstock supply.
Among diversified medical technology conglomerates, Medtronic, Fresenius, and Becton Dickinson exemplify channel-controlling archetypes. Medtronic represents the implantable hardware specialist tier with established cardiovascular device infrastructure applicable to peritoneal access systems. Fresenius occupies a position anchored by dialysis network distribution reach across European hospital systems. Becton Dickinson sits within the interventional radiology supply tier, with product portfolios aligned to inpatient drainage procedure workflows. These three companies illustrate how scale and channel access shape competitive positioning without requiring equivalent technological specialization.
| Leading Market Players |
|---|
| Medtronic |
| Fresenius |
| Pfizer |
| Clover Biopharmaceuticals |
| BioVie |
| Becton Dickinson |
| Merit Medical Systems |
| Sequana Medical |
| B. Braun |
| Others |
Supply & Pricing Matrix
Freiburg and Heidelberg medical technology corridors concentrate contract manufacturing capacity for titanium-reinforced intraperitoneal ports, creating asymmetric pricing power for German suppliers serving United States hospital networks facing silicone feedstock volatility.
Pricing Analysis
Current-generation programmable vacuum-assisted drainage systems command premium positioning against prior-generation gravity-fed hardware and next-generation closed-system architectures still awaiting FDA biocompatibility validation. Pricing stratifies across premium implantable ports with extended certification cycles, standard antimicrobial-impregnated catheters, and economy drainage sets for single-use applications. Cost compression in the economy tier is intensifying because polymer feedstock volatility squeezes contract manufacturer margins. Hospital procurement committees demonstrate lowest price sensitivity for dual-lumen port systems enabling concurrent chemotherapy delivery, while skilled nursing facilities face acute budget constraints on basic drainage hardware.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates supply chain risk planning for titanium-reinforced intraperitoneal hardware. Manufacturing concentrates in Germany, Japan, and Switzerland for medical-grade polymer processing and precision machining of implantable components. Raw material dependencies center on medical-grade silicone, polyurethane resins, and titanium alloys. Single-source vulnerability persists for ISO 13485-certified sterilization services. Distribution runs through hospital procurement consortia and specialized interventional radiology supply networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from infection surveillance protocols and scheduled replacement cycles is expanding faster than hardware sales, making after-sales contracting the priority capability for sustainable positioning.
For Market Incumbents: Build switching-cost moats through interoperable connection standards that lock hospital networks into multi-year replacement schedules. Consolidate vendor relationships around full-service drainage contracts bundling hardware, infection monitoring, and telemedicine oversight. Defend against mid-size device firms leveraging ISO 13485-certified contract manufacturing by deepening direct hospital system partnerships. Prioritize certification investment in MDR-compliant biocompatibility documentation to accelerate European procurement cycles. For New Entrants and Emerging Players: Build out patient-managed drainage capabilities with telemedicine integration targeting Japanese home healthcare expansion under METI aging-in-place incentives. White-space opportunity concentrates in ambulatory surgical center billing for scheduled drainage procedures. The most penetrable segment is outpatient interventional radiology clinics in Germany seeking efficiency-focused procedure bundles. Go-to-market execution should anchor on ISO 13485-certified contract manufacturing partnerships to bypass captive cleanroom capital requirements. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because catheter replacement cycles and infection-control service contracts generate predictable cash flows detached from acute hardware procurement volatility. Acquisition targets should screen for interventional oncology capabilities and software-hardware integration competence. The signal to watch is FDA 510(k) clearance velocity for next-generation closed-system drainage architectures, as extended review timelines compress valuation multiples for pre-revenue device firms.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | 510(k) clearance for silicone-based catheters unlocks United States hospital procurement channels. |
| CE Marking Pathway | MDR compliance certification enables access to German university hospital consortia. |
| Hospital System Partnership | Single-source agreements with defined per-patient cost caps lock in replacement cycle revenue. |
| Software Companion Development | Connected drainage monitoring platforms satisfy HIPAA protocols and enable telemedicine billing. |
| Reimbursement Strategy | Bundled payment contracts with CMS align acute care and outpatient site-of-service economics. |
Research Methodology
Cross-validation between hospital procurement databases and GPO contract filings anchors the qualitative findings on purchasing committee decision criteria. Primary interviews with interventional radiologists, biomedical engineers, hospital purchasing committees, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EMA medical device registrations, CMS Medicare reimbursement data, and hospital procurement databases. Bottom-up procedure volume estimates and top-down market sizing triangulate to constrain forecast variance.
Calibration against historical catheter placement volumes and replacement cycle frequencies across academic medical centers informs the analytical framework across the analysis window. Segmentation dimensions modeled include product type, therapy area, delivery mode, and end user, with regional regulatory clusters as an additional dimension. CAGRs were derived from fitted growth curves applied to procedure volume projections and hardware replacement frequencies. Industry-specific inputs include interventional radiology fellowship pipeline capacity and FDA review timeline data.
Sensitivities concentrate around FDA 510(k) review duration, polymer feedstock price volatility, and Medicare reimbursement compression for outpatient drainage procedures. Forecasts reflect documented assumptions on procedure migration from inpatient to ambulatory settings. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
High Definition Ultrasound Gastroscope Market
Gastroenterology
Malabsorption Syndrome Treatment Market
Gastroenterology
Biliary Tract Cancers (Btcs) Treatment Market
Gastroenterology
Global Gastrointestinal Bleeding Treatment Market
Gastroenterology
Duodenal Ulcer Treatment Market
Gastroenterology
Gastric Cancer Market
Gastroenterology
Peptic Ulcer Market
Gastroenterology
Gallstone Market
Gastroenterology
Chronic Liver Diseases Therapeutics Market
Gastroenterology
Ultrasound Gastroscopes Market
Gastroenterology
Gastroesophageal Junction Adenocarcinoma Therapeutics Market
Gastroenterology
Disposable Intestinal Wash Bags Market
Gastroenterology
Crohns Disease Therapeutics Market
Gastroenterology
Colon Hydrotherapy Market
Gastroenterology
Inflammatory Bowel Disease Treatment Market
Gastroenterology
Polyps Market