
 Gallstone Market | 2026-2036
Gallstone Market Size, Share, and Industry Trends Forecast 2026-2036
Gallstone Market Analysis
Ambulatory surgical centers is reorganizing demand within the gallstone treatment landscape as payers and health systems redirect low-acuity procedures away from inpatient settings. Boston Scientific Corporation leverages its endoscopic retrieval portfolio to capture outpatient procedural volume. Medtronic anchors its position through integrated laparoscopic visualization and energy platforms. Cook Medical LLC specializes in ERCP-directed stone management devices for complex biliary anatomy.
Gallstones are hardened deposits of cholesterol or bilirubin that form in the gallbladder, typically measuring 0.5 to 5.0 centimeters, and require intervention when symptomatic or complicated by cholecystitis or pancreatitis. Cholecystectomy dominates product-type revenue as the definitive surgical standard, while lithotripsy occupies a narrower niche for patients contraindicated for anesthesia. Laparoscopic technology leads procedural volume due to established reimbursement and shorter recovery profiles, though magnetic resonance imaging gains ground in preoperative biliary mapping for atypical anatomy.
FDA 510(k) clearance requirements govern laparoscopic instrument commercialization in the United States, while the EU Medical Device Regulation imposes enhanced clinical evidence standards for endoscopic accessories entering European markets. Japan's PMDA maintains distinct quality management system inspections that extend approval timelines for foreign manufacturers. Stakeholders must monitor site-of-care reimbursement shifts and evolving sterilization validation standards as outpatient volumes reshape capital equipment deployment strategies.
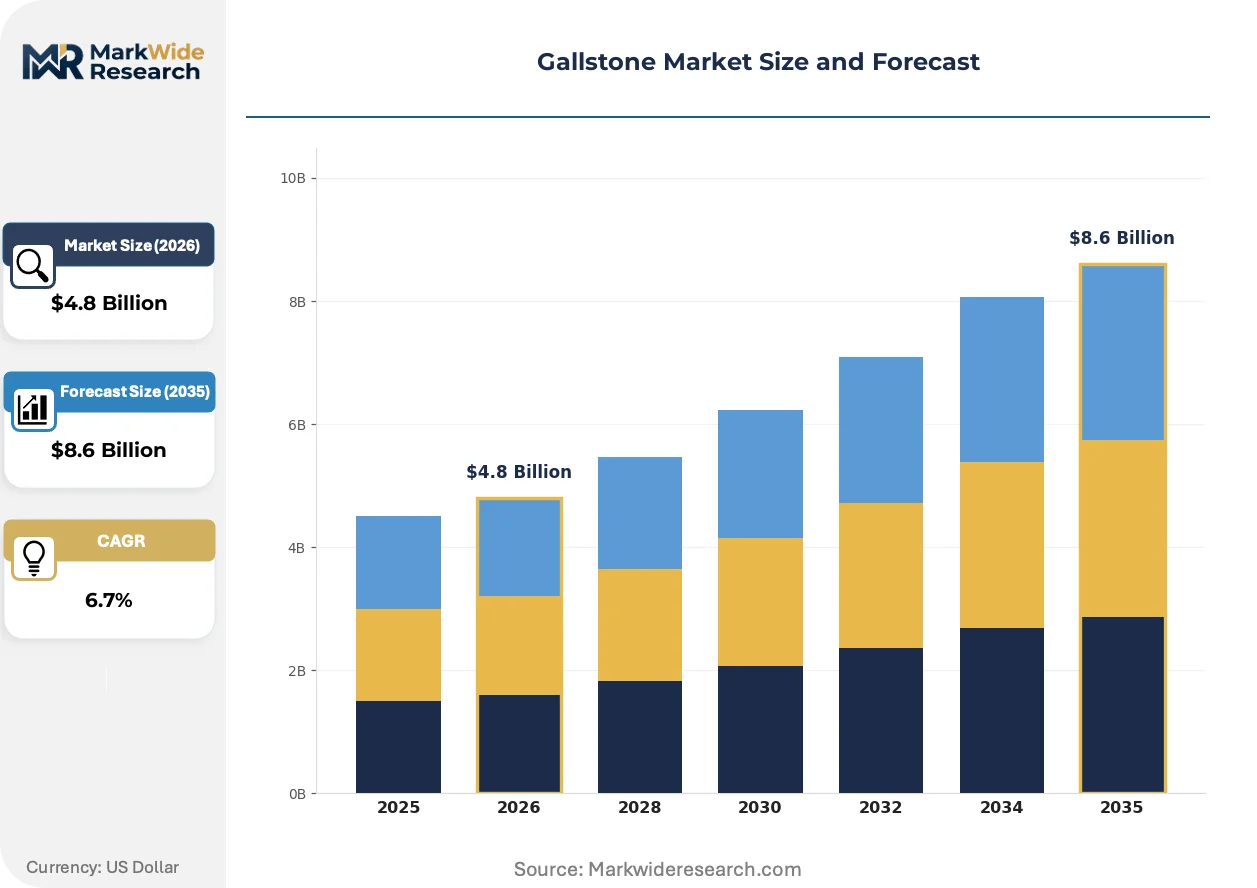
Market Dynamics
Site-of-care migration toward ambulatory surgical centers is compressing inpatient cholecystectomy volumes and forcing device manufacturers to recalibrate capital deployment toward outpatient-compatible instrumentation. Payer reimbursement differentials between hospital and ambulatory settings now dictate procurement patterns for laparoscopic platforms.
Growth Catalysts
- Aging Demographics:Population cohorts over 65 in the United States and Japan generate disproportionate gallstone incidence, sustaining procedural demand for cholecystectomy and ERCP interventions.
- Obesity Prevalence:Metabolic syndrome expansion correlates directly with cholesterol stone formation, expanding the addressable patient pool for surgical and endoscopic management across North American and European health systems.
- MDR Harmonization:The EU Medical Device Regulation's standardized clinical evidence requirements streamline market access for endoscopic retrieval devices, reducing fragmentation in European commercialization pathways.
Market Restraints
- Supply Concentration:Single-source dependence for high-grade surgical stainless steel from German and Japanese metallurgical suppliers exposes instrument manufacturers to input volatility and allocation constraints.
- Technical Limitation:Percutaneous cholecystostomy catheter durability failures in obese patients restrict non-surgical management options, capping lithotripsy market penetration.
- Regulatory Friction:Japan's PMDA quality management system inspections impose 18-24 month approval extensions for foreign manufacturers, delaying product launches versus domestic competitors.
Strategic Opportunities
- Underpenetrated Geography:India's tier-2 and tier-3 cities present unserved demand for laparoscopic cholecystectomy, with CDSCO streamlined pathways enabling faster device registration than historical norms.
- Technology Convergence:Integration of intraoperative fluorescence cholangiography with standard laparoscopic platforms enables real-time biliary anatomy visualization, differentiating premium system offerings.
- Regulatory Tailwind:The United States IRA hospital outpatient prospective payment system adjustments favor ASC-based procedures, accelerating capital equipment purchases by independent surgical centers.
Industry Challenges
- Specialized Workforce Scarcity:Advanced laparoscopic suturing and bile duct injury repair skills concentrate among aging surgeon cohorts, constraining training pipeline throughput for complex cases.
- Sterilization Validation:Reprocessed endoscopic accessory compliance with FDA 510(k) biocompatibility standards requires extended validation timelines, compressing margin structures for single-use alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gallstone Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cholecystectomy, Lithotripsy, Medication, Endoscopic Procedures Technology: Laparoscopic, Ultrasound, Magnetic Resonance Imaging, Computed Tomography End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Home Care Application: Diagnostic Procedures, Surgical Treatment, Preventive Care, Follow-up Care |
| Companies Covered | Boston Scientific Corporation, Intuitive Surgical, Medtronic, ConMed, Cook Medical LLC, Stryker Corporation, Olympus Corporation, Endo-Flex, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gallstone Market Emerging Trajectories
Digital surgical platforms and advanced energy modalities are restructuring how cholecystectomy procedures are performed, monitored, and reimbursed. Device manufacturers now compete on intraoperative data capture and connectivity rather than instrument mechanics alone.
Single-port robotic access systems are decomposing the traditional multi-trocar laparoscopic paradigm by enabling gallbladder extraction through umbilical incision alone. Academic medical centers in South Korea and the United States pilot these platforms for reduced postoperative pain and improved cosmesis. The technology is decomposing established trocar and insufflator markets as integrated robotic consoles subsume discrete instrument functions.
The EU Medical Device Regulation's post-market surveillance requirements mandate systematic clinical follow-up for Class IIb laparoscopic instruments, elevating data infrastructure investments. Manufacturers must deploy registry connectivity and adverse event tracking systems to maintain CE marking. High-volume cholecystectomy centers in Germany and France face disproportionate documentation burdens, favoring suppliers with pre-integrated compliance architectures.
Hospital purchasing coalitions now consolidate laparoscopic platform procurement across multi-facility networks, unbundling historical surgeon preference item autonomy. Integrated delivery networks in Texas and Florida negotiate system-wide contracts for visualization and energy devices, displacing individual hospital negotiations. This concentration is most visible in the southeastern United States, where Baptist and HCA networks standardize instrumentation to capture volume-based pricing.
Gallstone Market Segmentation
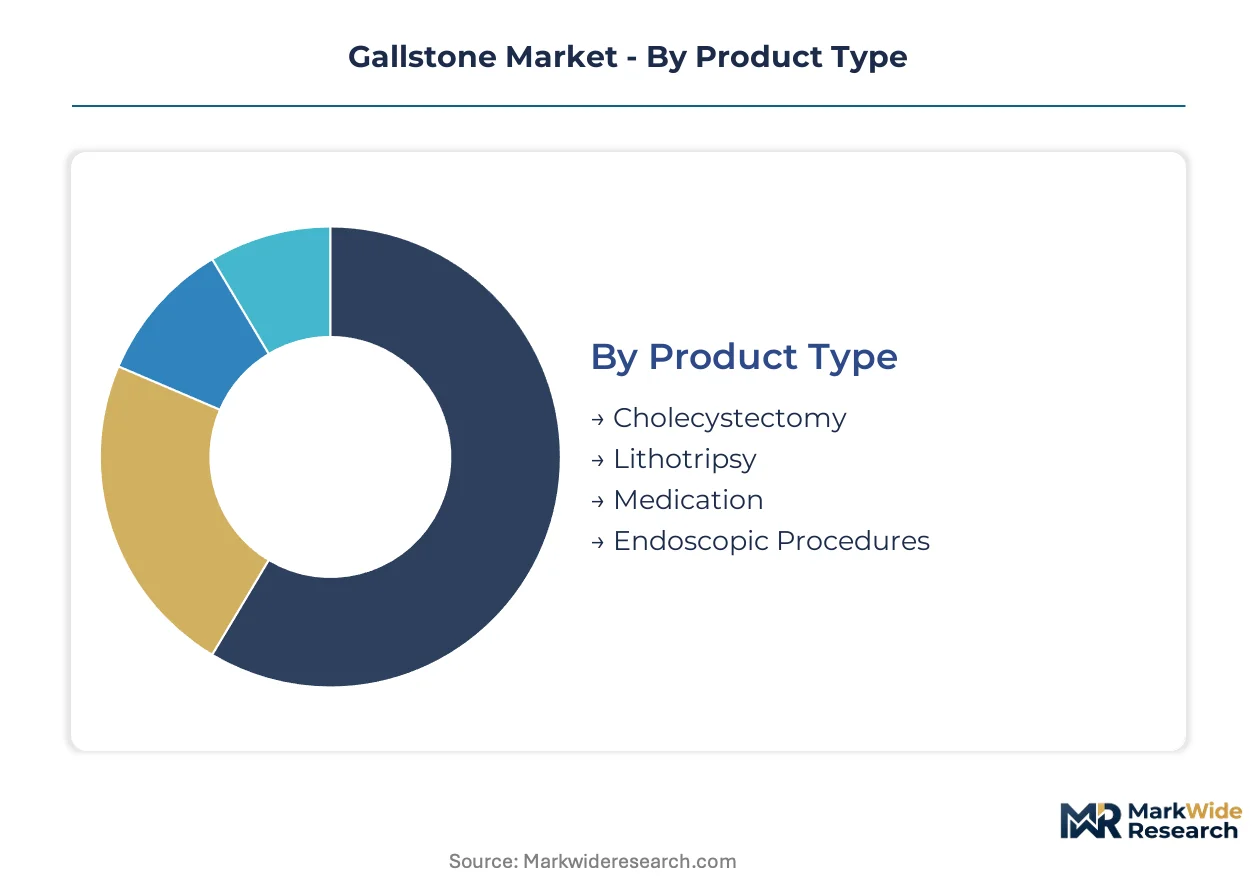
Gallstone treatment pathways fragment across intervention intensity, imaging modality, and care setting. Each segment carries distinct regulatory requirements, reimbursement profiles, and capital intensity that shape manufacturer strategy and provider procurement decisions.
Product Type:
FDA 510(k) pathways differentiate clearance timelines between surgical and pharmacological interventions, with device categories facing biocompatibility validation that drug submissions bypass.
- Cholecystectomy:Definitive surgical removal of the gallbladder through laparoscopic or open approaches. Demand concentrates in United States ambulatory surgical centers where Medicare reimbursement differentials favor same-day discharge protocols.
- Lithotripsy:Non-invasive fragmentation of stones using shock wave or laser energy for patients contraindicated for anesthesia. Adoption remains constrained by stone composition variability and retreatment rates in German and Japanese tertiary centers.
- Medication:Ursodeoxycholic acid dissolution therapy for cholesterol-dominant stones. Prescription volumes track obesity prevalence in Mediterranean health systems.
- Endoscopic Procedures:ERCP-directed stone extraction and sphincterotomy. Technical complexity limits procedure volume to specialized biliary centers in Seoul and Singapore.
Established volume favors Cholecystectomy; emerging adoption favors Endoscopic Procedures.
Technology:
Capital equipment depreciation schedules and disposable revenue streams create divergent margin structures across imaging and surgical platforms.
- Laparoscopic:Minimally invasive visualization and instrumentation systems enabling peritoneal access. Procurement in Texas and Florida integrated delivery networks now bundles insufflators, cameras, and energy devices under single-source contracts.
- Ultrasound:First-line diagnostic imaging for stone detection and biliary dilation assessment. Point-of-care adoption is accelerating in Indian tier-2 cities where device portability outweighs resolution limitations.
- Magnetic Resonance Imaging:MRCP sequences for preoperative biliary mapping in atypical anatomy. Reimbursement authorization requirements restrict utilization to academic medical centers.
- Computed Tomography:Cross-sectional imaging for complicated cholecystitis and pancreatitis staging. Radiation dose concerns limit serial monitoring applications.
Installed base concentration favors Laparoscopic; steepest expansion trajectory favors Ultrasound.
End User:
Site-of-care economics and staffing models determine device specification requirements across facility types.
- Hospitals:Inpatient and emergency departments managing complicated presentations. Volume is compressing as payers redirect uncomplicated cases to outpatient settings.
- Specialty Clinics:Gastroenterology-focused facilities performing diagnostic workup and ERCP interventions. Concentration in urban Japan reflects specialist density.
- Ambulatory Surgical Centers:Same-day cholecystectomy facilities with streamlined anesthesia protocols. United States IRA outpatient payment adjustments are accelerating capital purchases by independent operators.
- Home Care:Post-discharge monitoring and pain management following elective procedures. Remote patient tracking adoption is climbing fastest in South Korean metropolitan areas.
Historical volume anchors Hospitals; reimbursement tailwinds favor Ambulatory Surgical Centers.
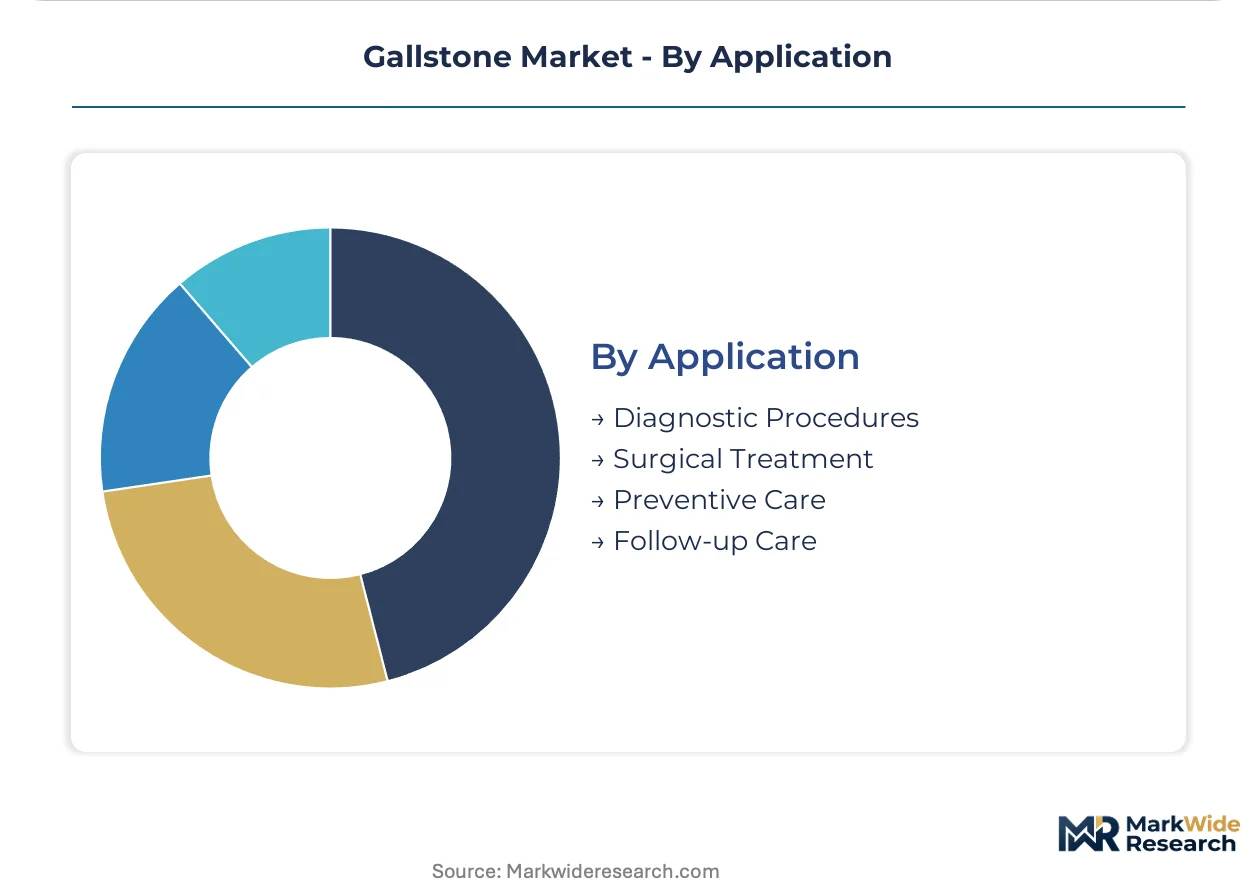
Application:
Episode-of-care bundling and quality metrics reshape revenue allocation across the treatment continuum.
- Diagnostic Procedures:Initial imaging and laboratory confirmation of symptomatic stones. Ultrasound-first protocols dominate in United Kingdom primary care networks.
- Surgical Treatment:Definitive intervention through cholecystectomy or stone extraction. Robotic platform integration is gaining share in Seoul academic centers.
- Preventive Care:Dietary counseling and metabolic management for high-risk cohorts. Pharmacological prophylaxis remains underpenetrated outside Nordic health systems.
- Follow-up Care:Post-procedural monitoring for retained stones or duct injury. Registry-linked surveillance requirements under EU MDR elevate documentation infrastructure needs.
Revenue concentration favors Surgical Treatment; quality incentive alignment favors Follow-up Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for laparoscopic instrumentation, while the Trans-Siberian rail corridor enables Central Asian medical device transit. These infrastructure assets determine how cholecystectomy equipment reaches surgical centers across high-incidence markets.
United States
Aging demographics and obesity prevalence sustain procedural volumes for cholecystectomy across the Southeast and Midwest. Medicare outpatient payment adjustments under the IRA favor ambulatory surgical center site-of-care migration. The Texas Medical Center in Houston concentrates high-volume biliary surgery training and robotic platform adoption.
Germany
Specialized biliary centers in Munich and Heidelberg drive ERCP-directed stone extraction demand for complex anatomy cases. The EU Medical Device Regulation's post-market surveillance requirements elevate documentation infrastructure investments for Class IIb laparoscopic instruments. The Stuttgart industrial cluster supplies high-grade surgical stainless steel for instrument manufacturing.
Japan
Specialist density in Tokyo and Osaka generates concentrated demand for advanced endoscopic retrieval devices. PMDA quality management system inspections impose extended approval timelines for foreign manufacturers, delaying product launches versus domestic competitors. The Kobe medical device manufacturing corridor anchors regional production capacity.
India
Tier-2 and tier-3 cities present unserved demand for laparoscopic cholecystectomy as surgical infrastructure expands. CDSCO streamlined pathways enable faster device registration than historical norms for imported instrumentation. The Delhi-NCR corridor concentrates private hospital chains investing in same-day surgery capacity.
South Korea
Academic medical centers in Seoul pilot single-port robotic access systems for reduced postoperative pain and improved cosmesis. MFDS regulatory frameworks align with international standards, accelerating foreign device market entry versus Japanese timelines. The Songdo biomedical cluster supports digital surgical platform development.
Gallstone Market Vendor Landscape
Listed leaders compete with private specialists across capital equipment and disposable accessory segments. The vendor base concentrates around integrated visualization platforms and specialized retrieval devices, with tiered positioning between full-system suppliers and component specialists. Three archetypes dominate: diversified medtech conglomerates with laparoscopic portfolios, pure-play endoscopic device manufacturers, and robotic platform entrants decomposing traditional instrumentation markets. Competitive moves center on hospital purchasing coalition penetration and site-of-care reimbursement capture.
Within the diversified medtech tier, Boston Scientific Corporation and Medtronic occupy positions anchoring endoscopic retrieval and integrated visualization platforms respectively. Cook Medical LLC exemplifies the specialized manufacturer archetype with focused ERCP-directed stone management positioning. Intuitive Surgical represents the robotic platform entrant, with its single-port systems decomposing established multi-trocar paradigms in academic centers.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Intuitive Surgical |
| Medtronic |
| ConMed |
| Cook Medical LLC |
| Stryker Corporation |
| Olympus Corporation |
| Endo-Flex |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Ninety-day surgical stainless steel inventory buffers at German metallurgical suppliers translate directly into pricing power asymmetry between instrument manufacturers and raw material providers. Payer-mandated site-of-care migration toward ambulatory surgical centers compresses capital equipment procurement cycles, forcing device vendors to absorb input volatility rather than pass through cost increases.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs laparoscopic platform procurement, with FDA 510(k) clearance tier and integrated software capability serving as the primary differentiation drivers. Pricing pressure stems from hospital purchasing coalition consolidation across Texas and Florida integrated delivery networks, which unbundle historical surgeon preference item autonomy. Ambulatory surgical centers exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize premium tiers for training and research requirements.
Supply Chain Analysis
Germany and Japan anchor high-grade surgical stainless steel production for laparoscopic instrumentation, with Stuttgart and Kobe industrial clusters feeding precision forging operations. Instrument manufacturing draws from nickel-titanium alloys, optical fiber bundles, and ceramic insulator components. Single-source metallurgical concentration exposes the supply chain to allocation constraints during demand spikes. Distribution runs through hospital purchasing coalitions and GPO contracts rather than direct manufacturer-to-facility relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
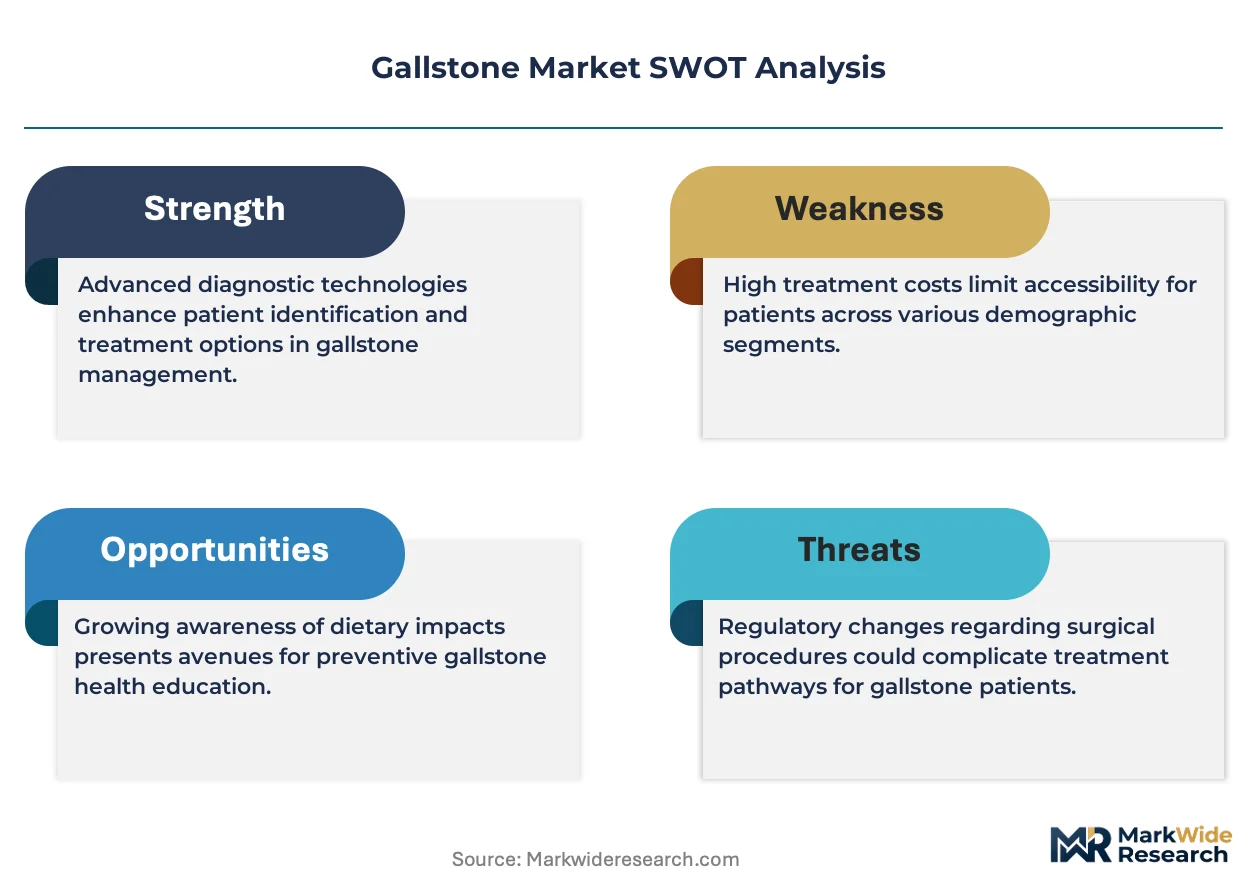
Platform economics now govern competitive outcomes as integrated visualization-energy systems displace discrete instrument sales, with interoperability between robotic consoles and legacy laparoscopic towers determining procurement decisions.
For Market Incumbents: Shield installed base erosion by deepening software companion development for fluorescence cholangiography integration, countering single-port robotic entrants decomposing multi-trocar paradigms. Secure backward integration into German surgical stainless steel supply through long-term offtake agreements with Stuttgart metallurgical suppliers. Prioritize CE marking pathway investments ahead of EU MDR post-market surveillance mandate expansion.
For New Entrants and Emerging Players: Differentiate on intraoperative data capture and connectivity architecture rather than instrument mechanics, targeting India's tier-2 and tier-3 cities where CDSCO streamlined registration enables faster market access than saturated United States and European channels. Pursue white-label OEM partnerships with established distributors in the Delhi-NCR corridor to bypass capital-intensive direct sales infrastructure.
For Investors and Strategic Acquirers: Long-term, this sits as a site-of-care arbitrage play because reimbursement differentials between hospital and ambulatory settings will continue reshaping capital deployment for cholecystectomy equipment. Target acquisition profiles center on ERCP-directed stone management specialists with established biliary center relationships in Seoul and Singapore. Monitor IRA outpatient payment system adjustment announcements as the primary inflection signal for independent surgical center capital expenditure cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Fluorescence cholangiography integration differentiates premium laparoscopic platforms in academic medical centers. |
| CE Marking Pathway Investment | EU MDR post-market surveillance compliance elevates data infrastructure requirements for Class IIb instruments. |
| Hospital System Partnership | Integrated delivery network standardization in Texas and Florida displaces individual hospital negotiations. |
| Backward Integration | Captive supply of German surgical stainless steel mitigates allocation risk during demand spikes. |
| Reimbursement Strategy | IRA outpatient payment adjustments accelerate ambulatory surgical center capital equipment purchases. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with laparoscopic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR technical documentation. Bottom-up procedural volume estimates triangulated against top-down capital equipment depreciation schedules across the analysis window.
Across the modeling period, segmentation dimensions included intervention intensity, imaging modality, care setting, and regulatory pathway cluster. CAGRs were derived from installed base growth projections and replacement cycle dynamics. Forecast inputs incorporated obesity prevalence trajectories, aging demographic shifts, and site-of-care reimbursement elasticity parameters.
Material uncertainties — PMDA approval timeline extensions, surgical stainless steel allocation constraints, and IRA payment system reversals — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding laparoscopic platform adoption curves and ambulatory surgical center penetration rates. Recalibration cycles align with material shifts in Medicare reimbursement policy and EU MDR enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
US Gastroenterology Ambulatory Surgery Center Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market
Gastroenterology
Chronic Liver Diseases Therapeutics Market
Gastroenterology
Helicobacter Pylori Infections Treatment Market
Gastroenterology
Intestinal Pseudo-Obstruction Treatment Market
Gastroenterology
Peptic Ulcer Market
Gastroenterology
Malignant Ascites Market
Gastroenterology
Colon Hydrotherapy Market
Gastroenterology
Polyps Market
Gastroenterology
Hyperemesis Gravidarum Treatment Market
Gastroenterology
Acute Pancreatitis Market
Gastroenterology
Intestinal Fistula Treatment Market
Gastroenterology
Anal Fissure Treatment Market
Gastroenterology
High Definition Ultrasound Gastroscope Market
Gastroenterology
Inflammatory Bowel Disease Market
Gastroenterology
Malabsorption Syndrome Treatment Market