
 Fecal Incontinence Market | 2026-2036
Fecal Incontinence Market Size, Share, and Industry Trends Forecast 2026-2036
Fecal Incontinence Market Analysis
Silicone is shifting toward advanced hydrogel composites in anal plug and barrier device manufacturing, reducing skin irritation rates while extending wear time. Coloplast A/S anchors its portfolio in premium skin-friendly adhesives for ostomy and continence care. Medtronic plc dominates neuromodulation systems for fecal incontinence, leveraging its sacral nerve stimulation platform across urology and pelvic floor indications. Hollister Incorporated competes through specialized distribution channels targeting long-term care facilities.
Fecal incontinence encompasses the involuntary loss of bowel control, treated through pharmacological agents such as loperamide and diphenoxylate, implantable neuromodulation devices delivering sacral nerve stimulation at 10-14 Hz frequency, surgical sphincter repair, and structured pelvic floor behavioral protocols. The devices segment leads value generation due to recurring battery replacement cycles and proprietary catheter ecosystems, while behavioral therapy represents the fastest-expanding category as payers mandate conservative treatment prior to device authorization. Medications retain volume dominance in primary care but face margin compression from generic substitution.
FDA 510(k) clearance requirements govern implantable neuromodulation devices, mandating clinical evidence for safety and efficacy prior to commercialization, while the EU Medical Device Regulation imposes stricter post-market surveillance and unique device identification on continence products sold in Europe. Reimbursement coding by Medicare in the United States directly determines patient access to sacral nerve stimulation procedures and associated device costs. Stakeholders must monitor evolving payer criteria for step-therapy requirements and real-world evidence demands that could redirect investment between pharmaceutical and interventional device portfolios.
Market Dynamics
Reimbursement gatekeeping by Medicare and private payers is forcing device manufacturers to generate real-world evidence for sacral nerve stimulation prior to authorization, compressing commercialization timelines and redirecting R&D budgets toward conservative therapy adjacencies.
Growth Catalysts
- Aging demographics:The United States, Japan, and Germany face expanding elderly populations requiring chronic continence management. Long-term care facilities in these markets drive recurring demand for barrier devices and behavioral therapy protocols.
- FDA 510(k) streamlining:The FDA's abbreviated pathway for neuromodulation device iterations accelerates incremental improvements to sacral nerve stimulators. Manufacturers leverage predicate device claims to reduce clinical trial burdens.
- Hydrogel composite materials:Advanced silicone-hydrogel blends in anal plugs reduce dermatitis incidence and extend wear duration. Home care patients and institutional buyers prioritize these skin-friendly formulations despite premium pricing.
Market Restraints
- Silicone supply concentration:Medical-grade silicone production clusters in Germany and the United States. Any disruption to Wacker Chemie or Dow Corning output cascades through barrier device manufacturing.
- Reimbursement complexity:Medicare's step-therapy mandates require documented behavioral therapy failure before sacral nerve stimulation authorization. This creates multi-month delays between diagnosis and device implantation.
- Generic pharmaceutical substitution:Loperamide and diphenoxylate face commoditization as patent protections expire. Primary care prescribing shifts to low-cost alternatives, eroding branded medication margins.
Strategic Opportunities
- Underpenetrated home care channels:Remote patient monitoring platforms enable pelvic floor therapy delivery outside clinical settings. Telehealth reimbursement expansion in the United States supports this channel development.
- EU MDR compliance differentiation:Stricter post-market surveillance requirements under the EU Medical Device Regulation favor manufacturers with robust clinical data infrastructure. CE-marked devices gain preferential positioning in European tenders.
- AI-powered diagnostic triage:Machine learning algorithms analyzing patient-reported outcomes and biomarker data improve fecal incontinence severity classification. This technology convergence supports personalized treatment pathway selection.
Industry Challenges
- Specialized urogynecology workforce gaps:Sacral nerve stimulation implantation requires fellowship-trained surgeons. Training program capacity constraints limit procedure volume expansion in secondary markets.
- Battery replacement logistics:Implantable neuromodulation devices require surgical battery exchanges every 4-6 years. Coordinating revision procedures strains hospital scheduling and patient compliance.
- Behavioral therapy standardization:Pelvic floor physical therapy protocols lack consistent outcome metrics across provider networks. Payer skepticism about efficacy documentation delays authorization for advanced interventions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fecal Incontinence Market |
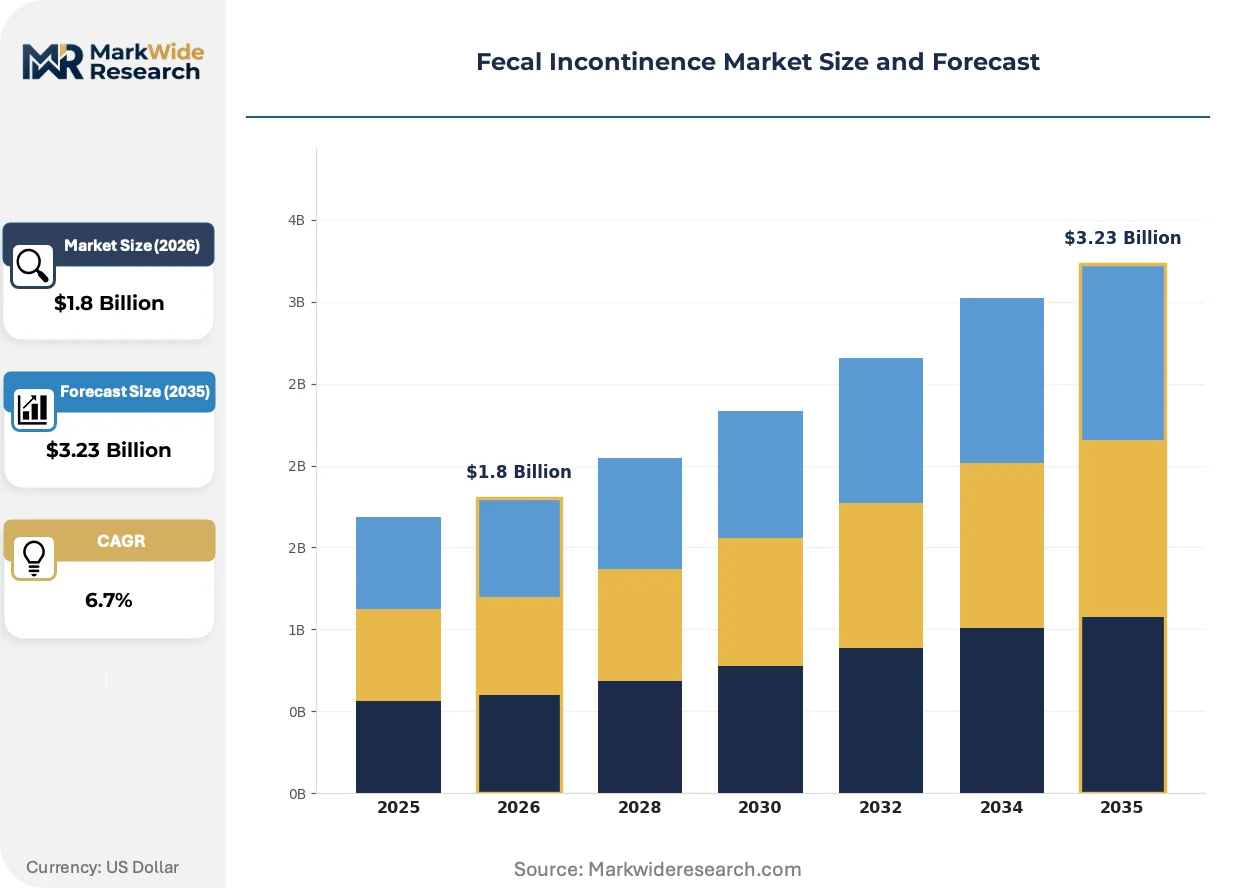
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Devices, Surgery, Behavioral Therapy Therapy Area: Neurological Disorders, Gastrointestinal Conditions, Muscle Weakness, Post-Surgery Recovery End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Age Group: Adults, Seniors, Children, Adolescents |
| Companies Covered | Medtronic plc, Coloplast A/S, Boston Scientific Corporation, Axonics Inc., Hollister Incorporated, ConvaTec Group plc, B. Braun Melsungen AG, Kimberly-Clark Corporation, Procter & Gamble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fecal Incontinence Market Emerging Trajectories
Digital health integration and material science advances are restructuring how fecal incontinence is diagnosed, managed, and reimbursed across acute and ambulatory settings.
Closed-loop adaptive neuromodulation is consolidating market positioning among high-complexity patients. These implantable systems automatically adjust stimulation parameters based on real-time physiological feedback. Academic medical centers in the United States and Germany are piloting these devices for refractory cases. The technology is consolidating sacral nerve stimulation's role as a last-line intervention, compressing demand for repeat surgical sphincter repairs.
Post-market surveillance obligations under the EU Medical Device Regulation are reshaping competitive economics for continence product manufacturers. The MDR mandates unique device identification, periodic safety updates, and enhanced clinical follow-up for Class IIa and above devices. Barrier device and neuromodulation system suppliers serving European markets must rebuild quality management systems. Smaller manufacturers lacking regulatory affairs infrastructure are withdrawing from EU distribution, concentrating supply among multinational device firms.
Patient-directed care pathways are fragmenting traditional referral networks. Direct-to-consumer pelvic floor training applications and wearable biofeedback devices enable symptom self-management prior to specialist consultation. United States employer-sponsored health plans increasingly cover these digital therapeutics as first-line interventions. Gastroenterology practices in competitive metropolitan markets are responding by unbundling diagnostic and therapeutic services to capture patients earlier in their search process.
Fecal Incontinence Market Segmentation
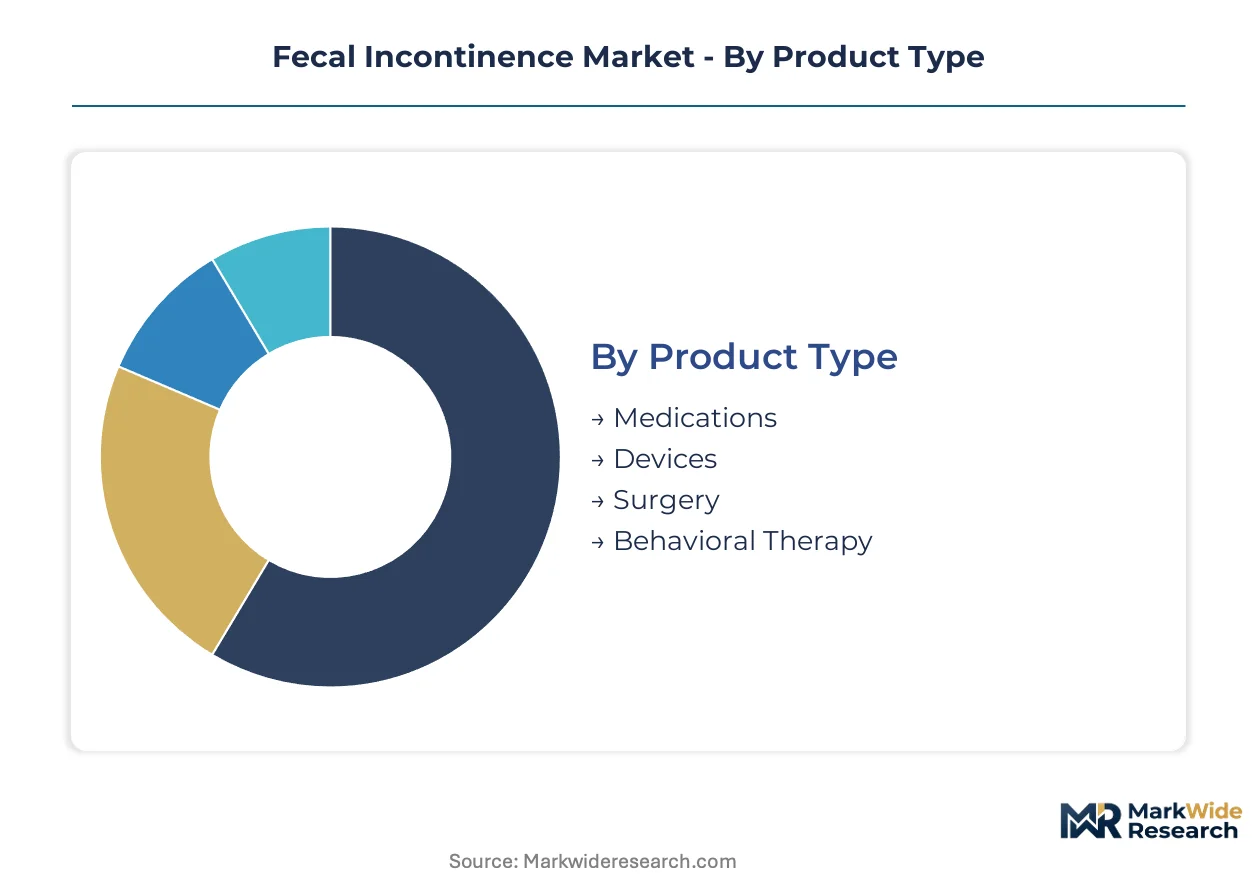
Segmentation in fecal incontinence treatment reveals distinct reimbursement pathways and clinical decision hierarchies. Device manufacturers, pharmaceutical suppliers, and service providers each navigate different regulatory gatekeepers and patient access timelines based on how offerings are categorized.
Product Type:
Technology sophistication determines pricing power and replacement revenue cycles across the four product categories.
- Medications:Oral agents including loperamide and diphenoxylate modulate intestinal motility through opioid receptor agonism. Primary care prescribing in the United States concentrates volume here, though generic substitution erodes branded margins and limits R&D recovery.
- Devices:Implantable neuromodulation systems deliver sacral nerve stimulation at calibrated frequencies, while barrier products incorporate silicone-hydrogel composites for extended wear. Medicare reimbursement coding for these systems requires documented behavioral therapy failure, creating authorization delays that manufacturers address through real-world evidence generation.
- Surgery:Sphincter repair procedures and artificial bowel sphincter implantation address structural defects in select candidates. Academic medical centers in Germany and the United States perform the majority of these interventions, constrained by fellowship-trained surgeon availability.
- Behavioral Therapy:Pelvic floor muscle training and biofeedback protocols constitute first-line intervention under most payer step-therapy requirements. Telehealth expansion enables home-based delivery, though outcome standardization gaps persist across provider networks.
Devices lead on scale through recurring battery replacement cycles; behavioral therapy leads on momentum through payer mandate expansion.
Therapy Area:
Underlying etiology shapes treatment selection criteria and expected durability of intervention outcomes.
- Neurological Disorders:Multiple sclerosis, spinal cord injury, and diabetic neuropathy disrupt autonomic bowel control. Sacral nerve stimulation demonstrates particular efficacy in this population, driving device adoption at tertiary referral centers.
- Gastrointestinal Conditions:Inflammatory bowel disease, irritable bowel syndrome, and radiation proctitis produce urgency-predominant symptoms. Pharmacological management with antidiarrheal agents dominates initial therapy in gastroenterology practice.
- Muscle Weakness:Obstetric trauma and age-related sphincter degeneration respond variably to surgical repair. Pelvic floor physical therapy serves as bridge intervention when surgical candidacy is uncertain.
- Post-Surgery Recovery:Iatrogenic injury following colorectal resection or prostatectomy creates temporary or persistent incontinence. Rehabilitation centers coordinate multidisciplinary recovery protocols for this segment.
Gastrointestinal conditions anchor volume through broad diagnostic prevalence; neurological disorders concentrate value through device-intensive intervention.
End User:
Care setting determines product form factor requirements and purchasing authority structures.
- Hospitals:Inpatient units manage acute exacerbations and coordinate surgical interventions. Device implantation procedures generate procedural revenue that cross-subsidizes conservative therapy programs.
- Clinics:Outpatient gastroenterology and urogynecology practices serve as gatekeepers to advanced interventions. These settings conduct behavioral therapy trials required for neuromodulation preauthorization.
- Home Care:Long-term care facilities and domiciliary nursing support chronic barrier device utilization. Aging demographics in Japan and the United States expand addressable population in this channel.
- Rehabilitation Centers:Post-acute facilities specialize in pelvic floor retraining following neurological injury or surgical recovery. Bundled payment models incentivize outcome-focused protocol standardization.
Hospitals retain surgical case concentration; home care gains share fastest through demographic shift and telehealth enablement.
Age Group:
Physiological reserve and comorbidity burden modify risk tolerance for invasive interventions.
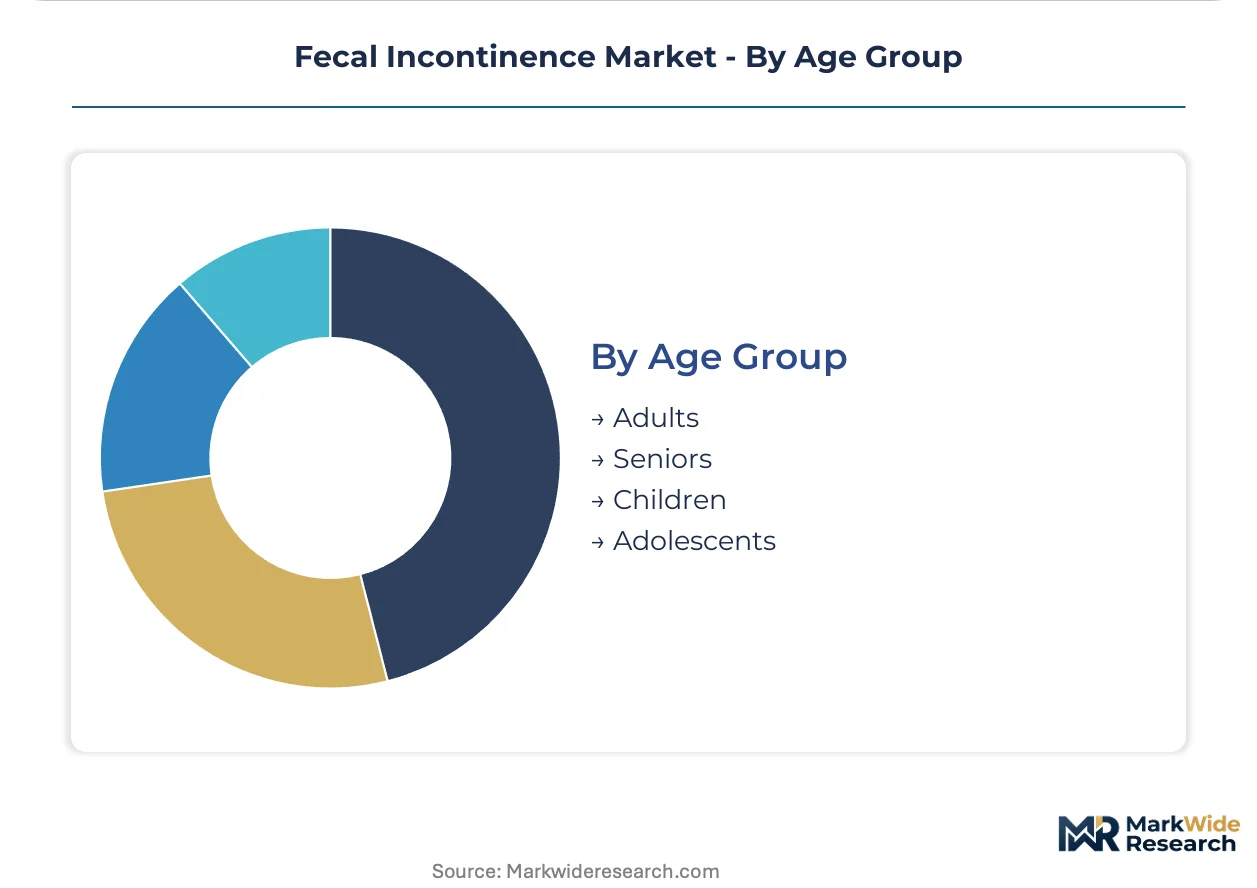
- Adults:Working-age patients prioritize discrete, minimally disruptive management options. Employer-sponsored health plans in the United States increasingly cover digital therapeutic interventions for this demographic.
- Seniors:Polypharmacy interactions and frailty limit medication options, elevating device and barrier product relevance. Medicare coverage determinations disproportionately shape product development priorities for this segment.
- Children:Congenital anorectal malformations and functional defecation disorders require specialized pediatric surgical and behavioral protocols. Tertiary children's hospitals concentrate relevant clinical expertise.
- Adolescents:Transition-age patients with childhood-onset conditions face care coordination gaps between pediatric and adult services. Developmental considerations modify behavioral therapy engagement strategies.
Seniors dominate absolute utilization through prevalence concentration; adults show steepest expansion trajectory through digital health adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors neuromodulation device development, with its corporate headquarters concentration shaping regulatory strategy and reimbursement lobbying across North American and European markets.
United States
Medicare reimbursement coding for sacral nerve stimulation procedures determines patient access timelines and device manufacturer revenue recognition. FDA 510(k) clearance pathways for neuromodulation iterations compress clinical trial burdens through predicate device claims. The Twin Cities corridor concentrates Medtronic's pelvic floor therapeutic development alongside University of Minnesota academic partnerships.
Germany
Medical-grade silicone production clusters around Wacker Chemie's Burghausen facilities, supplying barrier device manufacturers continent-wide. EU Medical Device Regulation post-market surveillance obligations impose unique device identification and periodic safety reporting requirements. Bavarian medical technology firms rebuild quality management systems to retain CE-marked distribution access.
Japan
Aging demographics expand home care demand for barrier devices and pelvic floor behavioral protocols in long-term care facilities. PMDA consultation pathways guide neuromodulation device manufacturers through pre-market approval requirements. Tokyo metropolitan academic medical centers pilot closed-loop adaptive stimulation systems for refractory fecal incontinence cases.
United Kingdom
NICE technology appraisals determine National Health Service commissioning for sacral nerve stimulation against behavioral therapy benchmarks. MHRA post-Brexit regulatory divergence creates parallel conformity assessment requirements for continence product suppliers. London teaching hospitals concentrate fellowship-trained urogynecology surgical capacity for sphincter repair procedures.
France
ANSM vigilance reporting obligations govern adverse event documentation for implantable continence devices distributed domestically. HAS evaluation of clinical benefit determines reimbursement levels for advanced therapeutic interventions. Parisian pelvic floor referral networks coordinate multidisciplinary management across gastroenterology, urogynecology, and colorectal surgery specialties.
Fecal Incontinence Market Vendor Landscape
Global majors compete with regional champions across reimbursement navigation and regulatory compliance capabilities. The vendor base separates into three tiers: multinational device conglomerates with sacral nerve stimulation platforms, specialized continence care suppliers with barrier product portfolios, and diversified consumer health corporations with retail-absorbent offerings. Strategic moves concentrate on real-world evidence generation for payer authorization and EU MDR compliance infrastructure consolidation.
Among the neuromodulation-focused tier, Medtronic plc and Axonics Inc. exemplify scale-driven and emerging-platform archetypes respectively. Coloplast A/S and Hollister Incorporated occupy positions within specialized continence care, with the former representing premium skin-friendly adhesive positioning and the latter exemplifying long-term care facility distribution channel specialization. ConvaTec Group plc anchors the diversified medical technology archetype with ostomy and continence care portfolio breadth.
| Leading Market Players |
|---|
| Medtronic plc |
| Coloplast A/S |
| Boston Scientific Corporation |
| Axonics Inc. |
| Hollister Incorporated |
| ConvaTec Group plc |
| B. Braun Melsungen AG |
| Kimberly-Clark Corporation |
| Procter & Gamble |
| Others |
Supply Flow & Price Mechanics
Captive silicone-hydrogel manufacturing in Germany and the United States anchors both supply security and premium pricing power for barrier device manufacturers. Medical-grade silicone production clusters around Wacker Chemie's Burghausen facilities and Dow Corning's Midland operations, creating upstream control that supports margin defense against generic substitution pressure in pharmaceutical adjacencies.
Pricing Analysis
Input-cost pass-through from medical-grade silicone and battery components shapes pricing stratification across premium, standard, and economy tiers. FDA 510(k) certification tier and skin-friendly adhesive formulation quality drive price differentiation between Coloplast's premium positioning and Hollister's long-term care channel focus. Cost compression in the medication segment intensifies due to loperamide generic substitution, while device manufacturers face downward pressure from Medicare step-therapy documentation requirements. Long-term care facilities exhibit highest price sensitivity due to bulk procurement mandates; tertiary academic medical centers show lowest sensitivity given bundled reimbursement for sacral nerve stimulation procedures.
Supply Chain Analysis
ISO 13485 and FDA Quality System Regulation certification gating constrains supplier pools for implantable neuromodulation components. Manufacturing concentrates in the United States, Germany, and Japan, with Minnesota anchoring Medtronic's sacral nerve stimulator production and Bavarian medical technology firms serving European barrier device demand. Raw material dependencies rest on lithium-ion battery cells, medical-grade silicone, and biocompatible catheter polymers. Single-source vulnerability in specialized urogynecology surgical training programs limits procedure volume scaling. Distribution runs through hospital purchasing committees, GPO contracts, and direct-to-facility logistics for long-term care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in fecal incontinence treatment hinges on hydrogel composite material cost-down curves and the shift toward recurring-revenue neuromodulation battery replacement cycles.
For Market Incumbents: Anticipate reimbursement compression from Medicare step-therapy expansion by building real-world evidence infrastructure for behavioral therapy adjacencies. Defend sacral nerve stimulation positioning through backward integration into battery cell supply and captive silicone-hydrogel formulation capacity. Counter Axonics' emerging platform threat by deepening hospital system partnership density in the Twin Cities corridor and Bavarian academic medical centers. For New Entrants and Emerging Players: Launch via telehealth-enabled pelvic floor therapy platforms targeting employer-sponsored health plans in competitive United States metropolitan markets. Home care channels in Japan's long-term care facilities represent the most penetrable geography given aging demographics and reimbursement expansion for remote patient monitoring. Pursue EU MDR compliance differentiation as a go-to-market angle, capturing share from smaller manufacturers withdrawing from European distribution. For Investors and Strategic Acquirers: Roll-up economics work for specialized continence care suppliers because EU MDR compliance infrastructure requirements are concentrating supply among multinational device firms with robust clinical data systems. The five-to-ten year viability window favors platforms with sacral nerve stimulation predicate device claims and established GPO contract access. Watch for inflection in CMS reimbursement coding decisions for closed-loop adaptive neuromodulation as a signal for next-generation device platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Predicate device claims compress clinical trial burdens for sacral nerve stimulator iterations. |
| CE Marking Pathway | EU MDR post-market surveillance obligations favor manufacturers with robust quality management systems. |
| Hospital System Partnership | Academic medical center density in Minneapolis and Munich anchors procedure volume and training pipeline. |
| Software Companion Development | AI-powered diagnostic triage algorithms improve severity classification and treatment pathway selection. |
| Reimbursement Strategy | Medicare coding determinations directly shape patient access timelines for device implantation procedures. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with urogynecology fellowship directors, hospital purchasing committee members, biomedical engineers at neuromodulation device firms, GPO contracts managers, and CMS reimbursement policy specialists with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, hospital procurement records, and trade data for medical-grade silicone. Bottom-up unit economics for sacral nerve stimulation procedures and top-down epidemiological prevalence modeling triangulated market sizing.
Comparable-period anchoring used historical neuromodulation implantation volumes and behavioral therapy authorization rates to calibrate projection assumptions across the analysis window. Segmentation dimensions modeled include product type, underlying etiology, care setting, and age-related risk tolerance. CAGRs derived from procedure volume trajectories, device replacement cycles, and telehealth reimbursement expansion patterns. Forecast inputs incorporated Medicare coverage determination timelines and EU MDR transition compliance rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt CMS step-therapy mandate expansion or Wacker Chemie supply disruption scenarios. Forecasts reflect documented assumptions about aging demographic trajectories and neuromodulation battery longevity improvements. A model refresh is warranted upon material change in sacral nerve stimulation reimbursement coding or EU MDR enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Helicobacter Pylori Infections Treatment Market
Gastroenterology
Intestinal Pseudo-Obstruction Treatment Market
Gastroenterology
Chronic Liver Diseases Therapeutics Market
Gastroenterology
Digestive Health Products Market
Gastroenterology
Inflammatory Bowel Disease Market
Gastroenterology
Zollinger Ellison Syndrome Treatment Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market
Gastroenterology
Duodenal Ulcer Treatment Market
Gastroenterology
US Inflammatory Bowel Disease Treatment Market
Gastroenterology
Digestive Health Market
Gastroenterology
Colon Hydrotherapy Market
Gastroenterology
Gastritis Treatment Market
Gastroenterology
Malabsorption Syndrome Treatment Market
Gastroenterology
Crohns Disease Therapeutics Market
Gastroenterology
Inflammatory Bowel Disease Treatment Market
Gastroenterology
Ultrasound Gastroscopes Market