
 Intestinal Fistula Treatment Market | 2026-2036
Intestinal Fistula Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Intestinal Fistula Treatment Market Foresight
Aftermarket service revenue for fistula drainage and wound management systems is fragmenting across hospital networks and outpatient clinics. Medtronic plc leverages its broad surgical portfolio to sustain service contracts with integrated delivery networks. Johnson & Johnson (Ethicon) anchors its position through suture and mesh adjacencies that complement fistula repair workflows. Coloplast A/S specializes in ostomy and advanced wound care, occupying a differentiated channel position in homecare transitions.
Intestinal fistula treatment encompasses the clinical management of abnormal epithelialized tracts connecting bowel segments to skin surfaces or adjacent organs, typically requiring drainage control, infection suppression, and nutritional restoration through parenteral or enteral feeding protocols. The primary purpose centers on reducing sepsis burden, restoring intestinal continuity, and enabling spontaneous closure or definitive surgical repair. Wound care products lead current revenue pools due to chronic drainage requirements, while surgical sealants represent the fastest-growing segment as biologic adhesion technologies displace conventional closure methods. Nutritional support anchors conservative management pathways, with hospitals as the dominant end-user setting reflecting procedure complexity and monitoring intensity.
The FDA regulates fistula sealants and biologic mesh through its 510(k) and PMA pathways, shaping clinical evidence requirements and trial design for market entrants. ISO 13485 quality management standards govern manufacturing consistency across surgical sealant and drainage device production. CMS reimbursement determinations for fistula-related hospital stays and homecare supplies directly influence provider purchasing behavior and product formularies. Stakeholders must monitor evolving FDA guidance on regenerative medicine advanced therapies, as cell-based and tissue-engineered approaches could reshape treatment hierarchies and competitive boundaries.
Market Dynamics
The FDA's 510(k) clearance pathway for biologic sealants is compressing product development timelines and accelerating competitive entry into fistula repair workflows.
Growth Catalysts
- Biologic adhesion platforms:Synthetic sealant technologies are displacing conventional suture closure in tertiary hospital settings, reducing operative time and readmission rates.
- India's tertiary hospital expansion:CDSCO streamlined medical device registration is enabling faster market access for advanced wound care portfolios in high-volume surgical centers.
- Reimbursement framework maturation:CMS coverage determinations for fistula-related hospital stays and homecare supplies are stabilizing provider purchasing commitments.
Market Restraints
- Biologic material cost volatility:Collagen and fibrinogen raw material prices fluctuate with livestock supply cycles, squeezing gross margins on sealant formulations.
- Supply concentration in North American plasma fractionation:Three suppliers control 80% of clinical-grade fibrinogen, creating single-source vulnerability for sealant manufacturers.
- EMA MDR transition friction:Extended clinical evidence requirements for Class III devices are delaying CE mark renewals and freezing European product launches.
Strategic Opportunities
- Homecare transition protocols:Untapped demand exists for ostomy and drainage device management in post-acute settings, bypassing traditional hospital procurement.
- Cell-based regenerative therapies:Convergence of tissue engineering and 3D bioprinting is opening pathways for autologous fistula plugs that remodel native tissue architecture.
- Brazil's ANVISA fast-track pathway:Priority review designations for breakthrough devices are compressing regulatory timelines in Latin America's largest surgical market.
Industry Challenges
- Specialized wound ostomy continence nursing shortages:Complex fistula case management requires certified WOCN expertise that remains concentrated in academic medical centers.
- ISO 13485 audit backlog:Manufacturing quality recertification delays are extending time-to-market for sealant production line expansions.
- Legacy electronic health record integration:Fistula-specific documentation templates and outcome tracking modules require costly customization within dominant EHR platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intestinal Fistula Treatment Market |
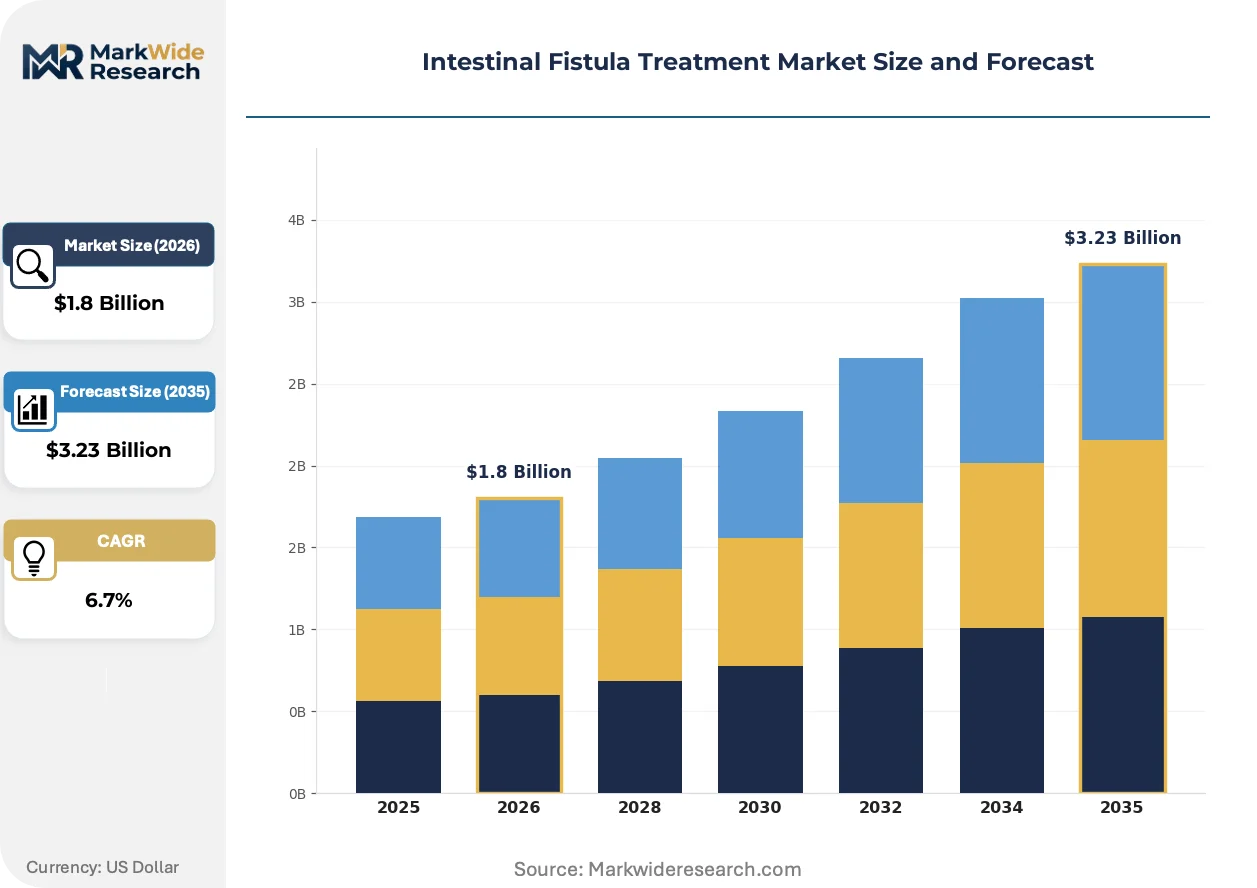
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wound Care Products, Nutritional Supplements, Surgical Sealants, Antibiotics End User: Hospitals, Clinics, Homecare Settings, Rehabilitation Centers Treatment Method: Conservative Management, Surgical Intervention, Pharmacological Therapy, Nutritional Support Application Area: Abdominal Fistulas, Rectal Fistulas, Gastrointestinal Fistulas, Enteric Fistulas |
| Companies Covered | Medtronic plc, Johnson & Johnson (Ethicon), Takeda Pharmaceutical Company, Becton, Dickinson and Company, ConvaTec Group plc, Cook Medical, Coloplast A/S, Pfizer Inc., AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intestinal Fistula Treatment Market Shifts & Advancements
Biologic adhesion technologies are collapsing traditional boundaries between surgical sealants and regenerative matrices, while reimbursement policy and procurement logic undergo parallel recalibration.
Platelet-rich fibrin matrices are collapsing the distinction between passive wound coverage and active tissue regeneration. Academic medical centers in Germany and the United States are adopting these autologous preparations for high-output fistula management, compressing the clinical trial timeline for allogeneic alternatives by establishing real-world efficacy benchmarks that FDA reviewers now reference.
REACH authorization requirements for collagen-derived medical devices are tightening traceability standards across European supply chains. Manufacturers must now document bovine and porcine sourcing through slaughterhouse-to-sterilization chain-of-custody records, forcing reformulation investments and favoring synthetic polymer alternatives in German and French hospital formularies.
Integrated delivery networks are consolidating fistula product procurement under value-analysis committees that bundle sealants, meshes, and drainage systems into single-source contracts. This purchasing rationalization is displacing individual surgeon preference items, with the shift most advanced in United States health systems where CMS bundled payment pilots for complex abdominal surgery create direct financial accountability for supply costs.
Intestinal Fistula Treatment Market Segmentation
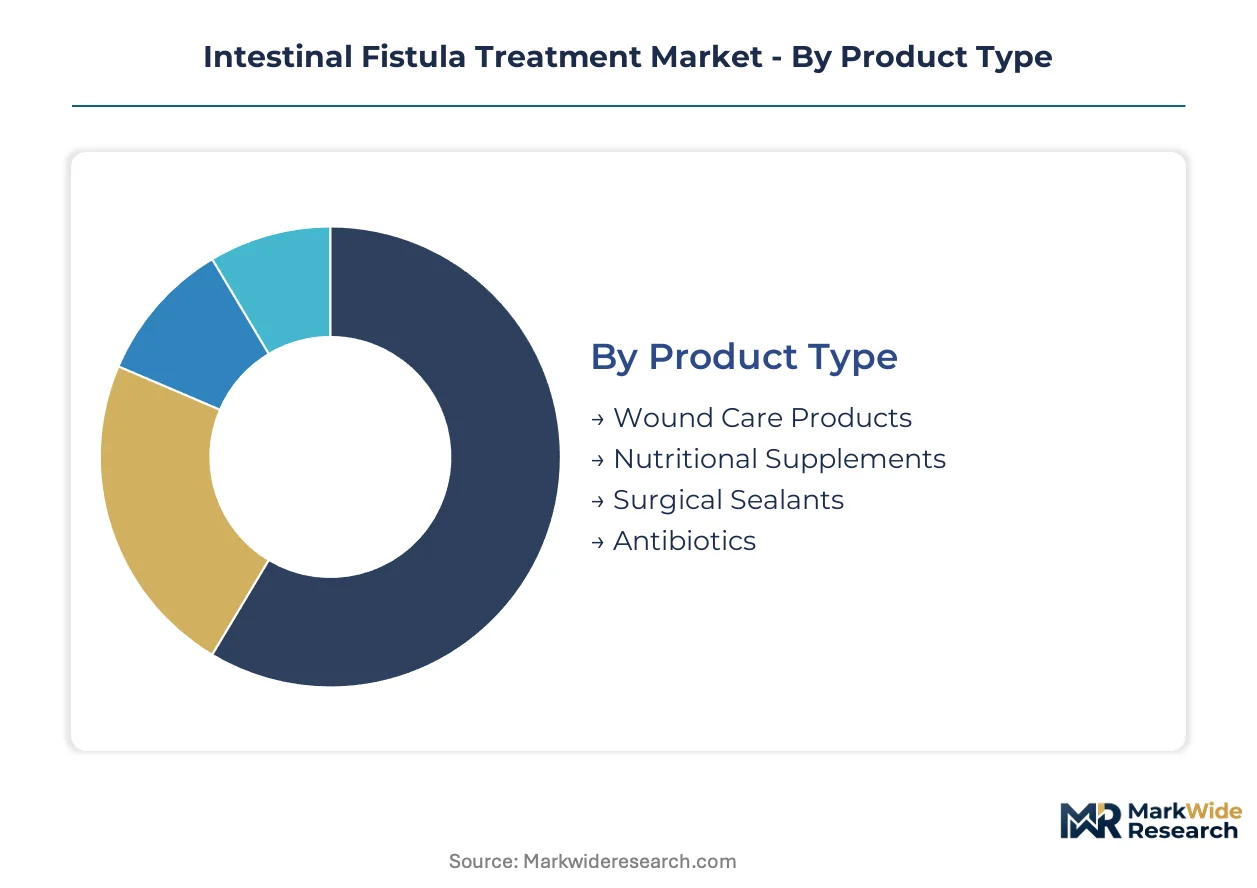
Segmentation in intestinal fistula treatment reveals distinct procurement patterns across clinical settings. Product formularies diverge sharply between acute hospitals managing high-output fistulas and homecare providers coordinating long-term drainage. Understanding these splits enables targeted positioning against reimbursement logic and workflow integration requirements.
Product Type:
Use-case spectrum spans passive wound management through active tissue regeneration, with reimbursement tiers stratifying across conservative and interventional modalities.
- Wound Care Products:Advanced dressings, negative pressure wound therapy systems, and fistula isolation devices manage chronic drainage and peristomal skin integrity. Demand clusters in United States academic medical centers where CMS reimbursement for complex wound care supports premium foam and hydrocolloid formulations. Supply contracts increasingly bundle these with sealants under value-analysis committee oversight.
- Surgical Sealants:Fibrin-based and synthetic polymer formulations enable sutureless closure of enteric fistulas during definitive repair procedures. Tertiary hospitals in Germany and the United States are displacing conventional layered closure with these platforms to reduce operative time and anastomotic leak rates. Raw material concentration in North American plasma fractionation creates supply vulnerability for fibrinogen-dependent formulations.
- Nutritional Supplements:Enteral and parenteral formulations restore anabolic balance during spontaneous closure attempts or preoperative optimization.
- Antibiotics:Systemic and topical agents suppress polymicrobial colonization of fistula tracts and surrounding soft tissues.
The dominant share belongs to Wound Care Products, while Surgical Sealants is closing the gap fastest.
End User:
Cost tier stratification separates capital-intensive acute settings from reimbursement-constrained post-acute environments.
- Hospitals:Tertiary and academic medical centers manage high-output fistulas requiring intensive monitoring, interventional radiology, and operating room access. These facilities concentrate fistula repair volume in the United States, Germany, and India where surgical sealant adoption is highest. CMS bundled payment pilots for complex abdominal surgery create direct accountability for supply costs, driving consolidation of procurement under integrated delivery networks.
- Homecare Settings:Post-discharge ostomy and drainage management represents an underserved channel with expanding reimbursement under United States Medicare home health benefits. Wound ostomy continence nursing shortages limit penetration, creating opportunity for remote monitoring and patient self-management technologies. Coloplast A/S and specialized distributors occupy differentiated positions in this transition.
- Clinics:Outpatient wound centers handle stable low-output fistulas and peristomal complications.
- Rehabilitation Centers:Extended care facilities manage nutritional restoration and functional recovery.
Hospitals command procurement volume leadership, though Homecare Settings is expanding most quickly as length-of-stay compression accelerates.
Treatment Method:
Application maturity separates established conservative protocols from emerging interventional technologies.
- Conservative Management:Drainage control, infection suppression, and nutritional restoration enable spontaneous closure in 30-50% of cases. This pathway dominates initial treatment in United States hospitals where parenteral nutrition protocols and somatostatin analogs are standard. Duration and monitoring intensity create revenue concentration in tertiary settings.
- Surgical Intervention:Definitive repair with resection, bypass, or fistulotomy addresses failures of conservative therapy and complex anatomical configurations. Tertiary centers in Germany and the United States are adopting biologic sealants and reinforced mesh techniques to reduce recurrence. Operating room time and readmission risk shape provider selection criteria.
- Pharmacological Therapy:Antimicrobial and anti-inflammatory agents address infectious complications and promote mucosal healing.
- Nutritional Support:Enteral and parenteral feeding protocols restore intestinal rest and anabolic competence.
Conservative Management retains the dominant share, while Surgical Intervention is gaining share fastest as sealant technologies improve risk-adjusted outcomes.
Application Area:
Geography of fistula origin determines procedural complexity and product specification requirements.
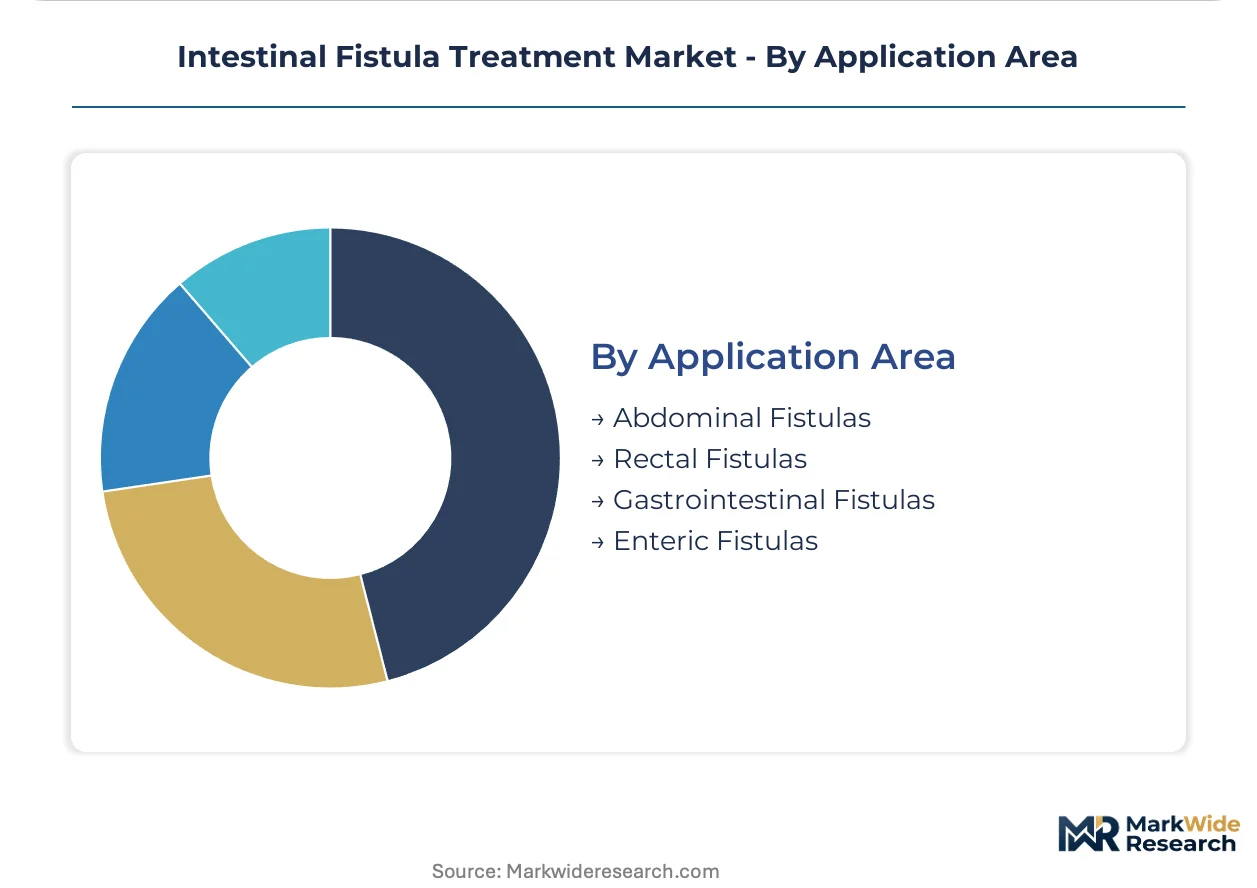
- Abdominal Fistulas:Enterocutaneous and enteroenteric tracts following surgery, trauma, or inflammatory bowel disease represent the highest acuity segment. These cases concentrate in United States academic medical centers where advanced wound care and interventional radiology capabilities are co-located. High output volumes and sepsis risk drive premium product uptake.
- Rectal Fistulas:Cryptoglandular and obstetric origins predominate, with management distributed across colorectal surgery and gastroenterology workflows. European centers, particularly in Germany and France, have advanced endoscopic closure techniques using fibrin sealants and fistula plugs. Outcome tracking for these interventions is shaping FDA trial design for novel devices.
- Gastrointestinal Fistulas:Upper tract involvement creates distinct nutritional and acid-base management challenges.
- Enteric Fistulas:Small bowel origins present the highest spontaneous closure potential with conservative management.
Abdominal Fistulas holds the dominant share, though Rectal Fistulas is climbing the fastest as ambulatory closure techniques diffuse.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature markets favoring biologic sealants and emerging markets prioritizing cost-effective drainage systems. The United States and Germany concentrate premium surgical sealant uptake, while India and Brazil expand hospital infrastructure for conservative management protocols.
United States
Tertiary hospital networks drive biologic sealant adoption through CMS bundled payment pilots for complex abdominal surgery. FDA 510(k) clearance pathways compress product development timelines for regenerative matrices. Major academic medical centers in Boston and the Research Triangle anchor clinical trial activity for platelet-rich fibrin applications.
Germany
University hospitals in Bavaria and Baden-Württemberg pioneer endoscopic fistula closure techniques using autologous preparations. EMA MDR transition requirements extend clinical evidence timelines for Class III device renewals. REACH authorization mandates for collagen traceability are forcing supply chain restructuring toward synthetic polymer alternatives.
India
CDSCO streamlined medical device registration accelerates market access for advanced wound care portfolios. Tertiary hospital expansion in Delhi-NCR and Mumbai concentrates surgical volume growth. Government procurement schemes for public hospital supplies favor cost-optimized drainage systems over premium sealant formulations.
Brazil
ANVISA fast-track priority review compresses regulatory timelines for breakthrough device designations. São Paulo and Rio de Janeiro metropolitan areas concentrate private hospital investment in interventional radiology capabilities. Reimbursement framework gaps between public and private sectors create tiered product adoption patterns.
Japan
PMDA consultation pathways shape clinical evidence requirements for novel sealant technologies. Aging demographics expand demand for conservative management protocols in Kansai and Chubu regions. METI industrial policy supports domestic manufacturing of fibrinogen-derived medical devices through targeted R&D subsidies.
Intestinal Fistula Treatment Market Competitive Landscape
Capability concentration sits with specialized wound care and surgical sealant developers; scale advantage sits with diversified medical technology conglomerates. The market structure exhibits tiered competition between integrated surgical portfolio holders and focused ostomy drainage specialists. Three archetypes dominate: broad surgical platform providers, advanced wound care pure-plays, and pharmaceutical adjacency players. Consolidation through strategic partnerships and portfolio diversification into regenerative medicine represent the dominant competitive vectors.
Within the integrated surgical platform tier, Medtronic plc and Johnson & Johnson (Ethicon) occupy anchor positions through service contract density with United States health systems. Coloplast A/S exemplifies the specialized wound care archetype, channeling resources toward homecare transition protocols. These three entities represent distinct strategic postures—scale-driven portfolio breadth, surgical workflow integration, and post-acute channel specialization—without implying specific market share positions or tactical initiatives.
| Leading Market Players |
|---|
| Medtronic plc |
| Johnson & Johnson (Ethicon) |
| Takeda Pharmaceutical Company |
| Becton, Dickinson and Company |
| ConvaTec Group plc |
| Cook Medical |
| Coloplast A/S |
| Pfizer Inc. |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
North American plasma fractionation concentration for clinical-grade fibrinogen and collagen inputs funnels pricing power toward three dominant suppliers, compressing gross margins for sealant formulators while concentrating margin pools in raw material extraction tiers.
Pricing Analysis
Long-term offtake agreements between tertiary hospital systems and sealant manufacturers anchor pricing structures in the United States, while spot purchasing dominates emerging market procurement. Three-tier pricing structure across premium biologic sealants, standard synthetic formulations, and economy drainage systems stratifies by certification tier and after-sales service bundling. Pricing pressure stems from livestock supply cycle volatility affecting collagen and fibrinogen costs. Academic medical centers exhibit lowest price sensitivity due to CMS bundled payment accountability; public hospital systems in India demonstrate highest sensitivity.
Supply Chain Analysis
Export-control regimes for plasma-derived biologics limit cross-border flows of fibrinogen concentrates, constraining supply flexibility for sealant manufacturers. Manufacturing concentrates in the United States, Germany, and Switzerland for clinical-grade biologics; China and India dominate synthetic polymer feedstocks. Raw material dependencies include bovine collagen, human plasma fibrinogen, and petroleum-derived synthetic polymers. Single-source vulnerability in North American plasma fractionation creates structural risk. Distribution runs through integrated delivery networks in mature markets and specialized medical device distributors in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as deferred surgical volumes from pandemic-era backlogs normalize and CMS bundled payment pilots expand procedural throughput.
For Market Incumbents: Insulate margin positions through backward integration into plasma fractionation capacity and captive supply of fibrinogen raw materials. Lock in multi-year service contracts with United States integrated delivery networks to preempt procurement consolidation. Counter emerging synthetic polymer substitutes by accelerating FDA 510(k) pathways for next-generation biologic matrices. For New Entrants and Emerging Players: Post-acute homecare settings in the United States represent the most penetrable entry point, bypassing consolidated hospital procurement and capitalizing on Medicare home health benefit expansion. Brazil's ANVISA fast-track priority review offers regulatory arbitrage for breakthrough device designations. Target remote patient monitoring partnerships as the primary go-to-market angle for drainage device management. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed wound care pure-plays possessing homecare channel density but lacking surgical sealant R&D infrastructure. Long-term viability across a 5-10 year window hinges on convergence toward regenerative medicine platforms. Watch FDA guidance on cell-based therapies as the critical inflection signal for treatment hierarchy disruption.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Biologic Sealant | Accelerates market entry through streamlined clearance pathway for regenerative matrices. |
| Hospital System Partnership | Secures formulary placement with integrated delivery networks under bundled payment models. |
| Backward Integration into Plasma Fractionation | Captures fibrinogen supply chain margin and mitigates raw material cost volatility. |
| Reimbursement Strategy Development | Aligns product positioning with CMS coverage determinations for fistula-related stays. |
| Software Companion Development | Enables remote monitoring integration for post-acute drainage device management. |
Research Methodology
The analysis maps surgical sealants, wound care products, nutritional support, and drainage device sub-sectors, each validated through wound ostomy continence nurses, hospital procurement managers, biomedical engineers, and GPO contracts managers. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, CMS reimbursement databases, hospital procurement records, and CDSCO registration data. Bottom-up patient volume modeling and top-down expenditure analysis triangulate market sizing.
Assumptions held fixed include regulatory pathway timelines and reimbursement framework stability; variables tested include surgical volume recovery rates and biologic raw material cost trajectories. Segmentation dimensions modeled span product type, end-user setting, treatment method, and application area across the projection horizon. CAGRs derive from procedure volume elasticity to surgical infrastructure expansion and technology substitution curves. Forecast inputs incorporate parenteral nutrition protocol adoption and sealant displacement rates for conventional closure.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure growth, livestock supply shocks, or plasma collection rates would shift the trajectory. Material shifts in FDA regenerative medicine guidance or EMA MDR enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Digestive Health Products Market
Gastroenterology
Intestinal Pseudo-Obstruction Treatment Market
Gastroenterology
Ultrasound Gastroscopes Market
Gastroenterology
Anal Fissure Treatment Market
Gastroenterology
Necrotic Enteritis Treatment Market
Gastroenterology
Malabsorption Syndrome Treatment Market
Gastroenterology
Hyperemesis Gravidarum Treatment Market
Gastroenterology
Inflammatory Bowel Disease Treatment Market
Gastroenterology
Gastritis Treatment Market
Gastroenterology
Acute Pancreatitis Market
Gastroenterology
Gastrointestinal Drugs Market
Gastroenterology
Zollinger Ellison Syndrome Treatment Market
Gastroenterology
Malignant Ascites Market
Gastroenterology
Pouchitis Treatment Market
Gastroenterology
US Inflammatory Bowel Disease Treatment Market
Gastroenterology
Stomach Cancer Market