
 Global Interleukin Inhibitors Market | 2026-2036
Global Interleukin Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Interleukin Inhibitors Market Foresight
Biologics are restructuring competitive economics in the interleukin inhibitor space as recombinant proteins and monoclonal antibodies displace older small-molecule immunosuppressants. Novartis AG leverages its deep manufacturing scale in biologics production to anchor supply security for high-volume autoimmune therapies. AbbVie Inc. differentiates through vertical control over its Humira-related immunology infrastructure and sustained R&D intensity in next-generation IL inhibitors.
Interleukin inhibitors comprise engineered proteins and antibodies that block pro-inflammatory cytokines—principally IL-1, IL-6, IL-12, IL-17, and IL-23—through high-affinity binding at picomolar concentrations, thereby interrupting autoimmune signaling cascades. These therapeutics serve primary commercial purpose in chronic inflammatory diseases where T-cell dysregulation drives tissue destruction. Monoclonal antibodies dominate current revenue pools given their established efficacy in psoriasis and rheumatoid arthritis, while small molecule inhibitors represent the fastest-expanding segment as oral bioavailability reduces patient burden versus injectable biologics. Delivery mode segmentation reveals subcutaneous injection as the mature volume leader, though intravenous infusion retains premium positioning for hospital-administered induction regimens in inflammatory bowel disease.
FDA's Breakthrough Therapy designation and EMA's PRIME scheme are accelerating development timelines for novel interleukin targets, while Japan's PMDA maintains stringent immunogenicity standards that shape formulation requirements for Asia-Pacific entry. The EU's MDR and forthcoming HTA convergence under EUnetHTA are raising evidentiary bars for comparative effectiveness, directly influencing trial design and market access negotiations. Stakeholders must monitor evolving biosimilar substitution policies and payer risk-sharing arrangements as these mechanisms determine brand longevity and pricing power across major reimbursement markets.
Market Dynamics
The interleukin inhibitor market is reconfiguring around biosimilar entry pressure and the migration from hospital-based infusion to self-administered subcutaneous delivery, compressing service revenue while expanding volume addressability.
Growth Catalysts
- FDA Breakthrough Therapy designation:The accelerated pathway compresses development timelines for novel IL-23 and IL-17 targeting antibodies, pulling forward commercialization by 12-18 months versus standard review.
- Specialty clinic expansion in the United States:Dedicated immunology treatment centers are building biologic administration capacity, creating pull-through demand for maintenance dosing regimens.
- Japan's biosimilar uptake framework:METI's pricing and reimbursement incentives for follow-on biologics are expanding patient access to IL-6 pathway inhibitors previously restricted by cost barriers.
Market Restraints
- Cold chain complexity:Monoclonal antibody formulations require continuous 2-8°C distribution, constraining reach into markets with fragmented logistics infrastructure.
- Immunogenicity surveillance burden:EMA's post-authorization safety study requirements for novel biologics extend regulatory compliance costs across the product lifecycle.
- Small-molecule JAK inhibitor substitution:Oral immunosuppressants are capturing price-sensitive segments in rheumatoid arthritis, eroding biologic volume in mild-to-moderate disease.
Strategic Opportunities
- Germany's outpatient biologic reimbursement expansion:The G-BA's 2024 framework shift enables community-based administration, unlocking capacity constraints in hospital-centric delivery.
- Oral IL-17 small molecule development:Convergence of peptide engineering and formulation science is enabling non-injectable alternatives to capture injection-averse patient populations.
- India's autoimmune diagnosis infrastructure:Underpenetrated rheumatology screening in tier-2 cities creates first-mover positioning for biosimilar IL-6 inhibitors as diagnostic rates improve.
Industry Challenges
- Cell line development expertise scarcity:Mammalian expression system optimization for high-yield IL inhibitor production requires specialized bioprocess engineering talent concentrated in Boston and Basel clusters.
- Comparative effectiveness evidence generation:EUnetHTA convergence demands head-to-head trial data against standard-of-care biologics, extending clinical development timelines and investment requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Interleukin Inhibitors Market |
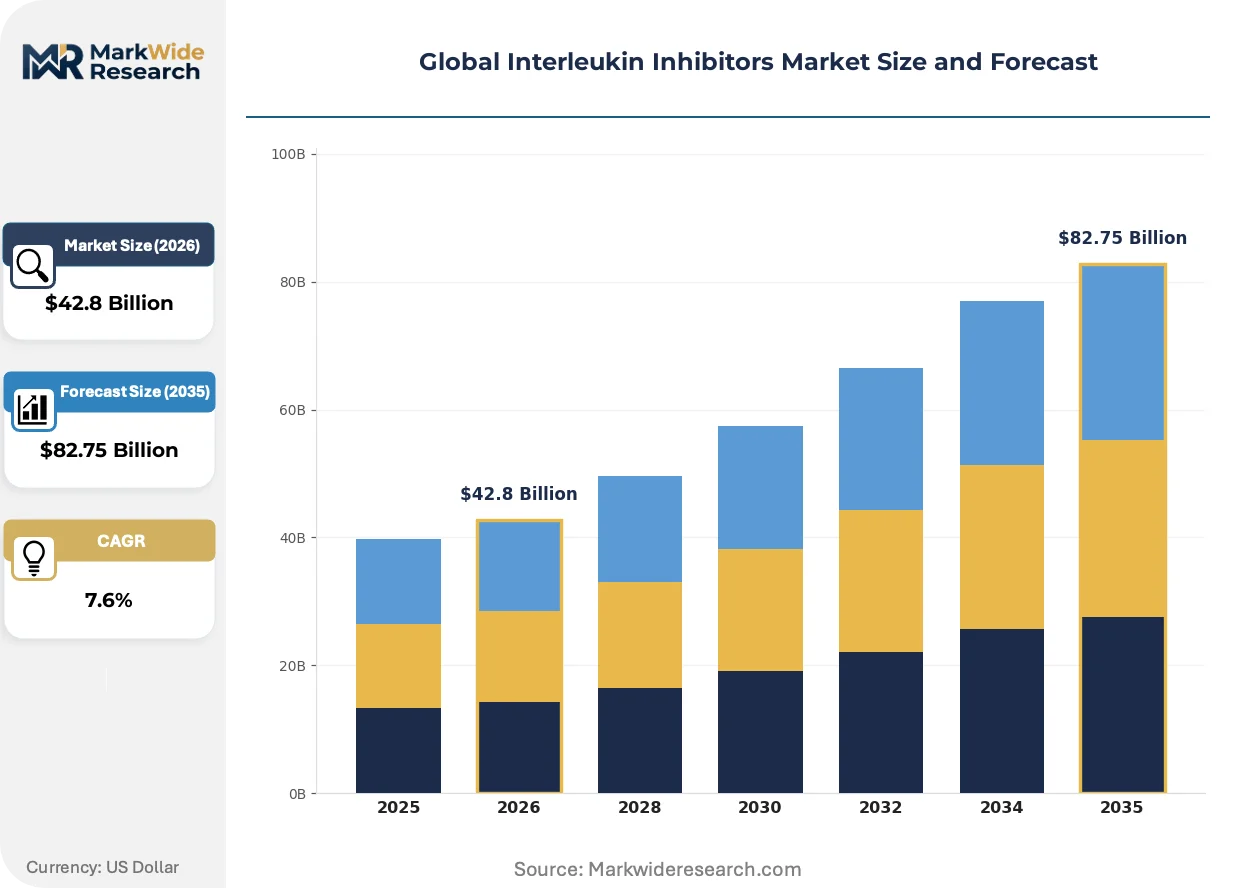
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $82.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Small Molecule Inhibitors, Recombinant Proteins, Fusion Proteins Therapy Area: Rheumatoid Arthritis, Psoriasis, Inflammatory Bowel Disease, Asthma, Systemic Lupus Erythematosus End User: Specialty Clinics, Research Laboratories, Pharmaceutical Companies, Contract Research Organizations Delivery Mode: Subcutaneous Injection, Intravenous Infusion, Oral Administration, Transdermal Patch |
| Companies Covered | Novartis AG, AbbVie Inc., Johnson & Johnson Services, Inc., Eli Lilly and Company, Regeneron Pharmaceuticals Inc., F. Hoffmann-La Roche Ltd, AstraZeneca, GlaxoSmithKline plc, Teva Pharmaceutical Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Interleukin Inhibitors Market Shifts & Advancements
Biologic manufacturing and delivery modalities are undergoing parallel transformation as developers pursue patient convenience and payer cost containment simultaneously.
Half-life extended monoclonal antibodies are absorbing dosing frequency reduction as the central competitive variable in psoriasis and psoriatic arthritis maintenance therapy. Specialty pharmacies in the United States are prioritizing quarterly and semi-annual subcutaneous options, compressing the market for legacy monthly injection regimens. This absorption is forcing reformulation investments across established IL-12/23 and IL-17 portfolios.
EMA's MDR implementation is elevating clinical evidence requirements for Class III implantable drug-device combination products used in biologic delivery. Manufacturers must now submit post-market clinical follow-up data as a condition of continued CE marking, extending compliance obligations for autoinjector systems. The German and French notified body ecosystems are responding with specialized biologics-device convergence assessment pathways.
Patients with inflammatory bowel disease are consolidating purchasing decisions through integrated specialty pharmacy networks that bundle drug, device, and adherence monitoring services. This channel consolidation is displacing traditional wholesale distribution in the United States, concentrating volume with CVS Specialty, Accredo, and Walgreens Specialty Pharmacy. The shift is most visible in Crohn's disease induction regimens where prior authorization complexity drives demand for full-service coordination.
Global Interleukin Inhibitors Market Segmentation
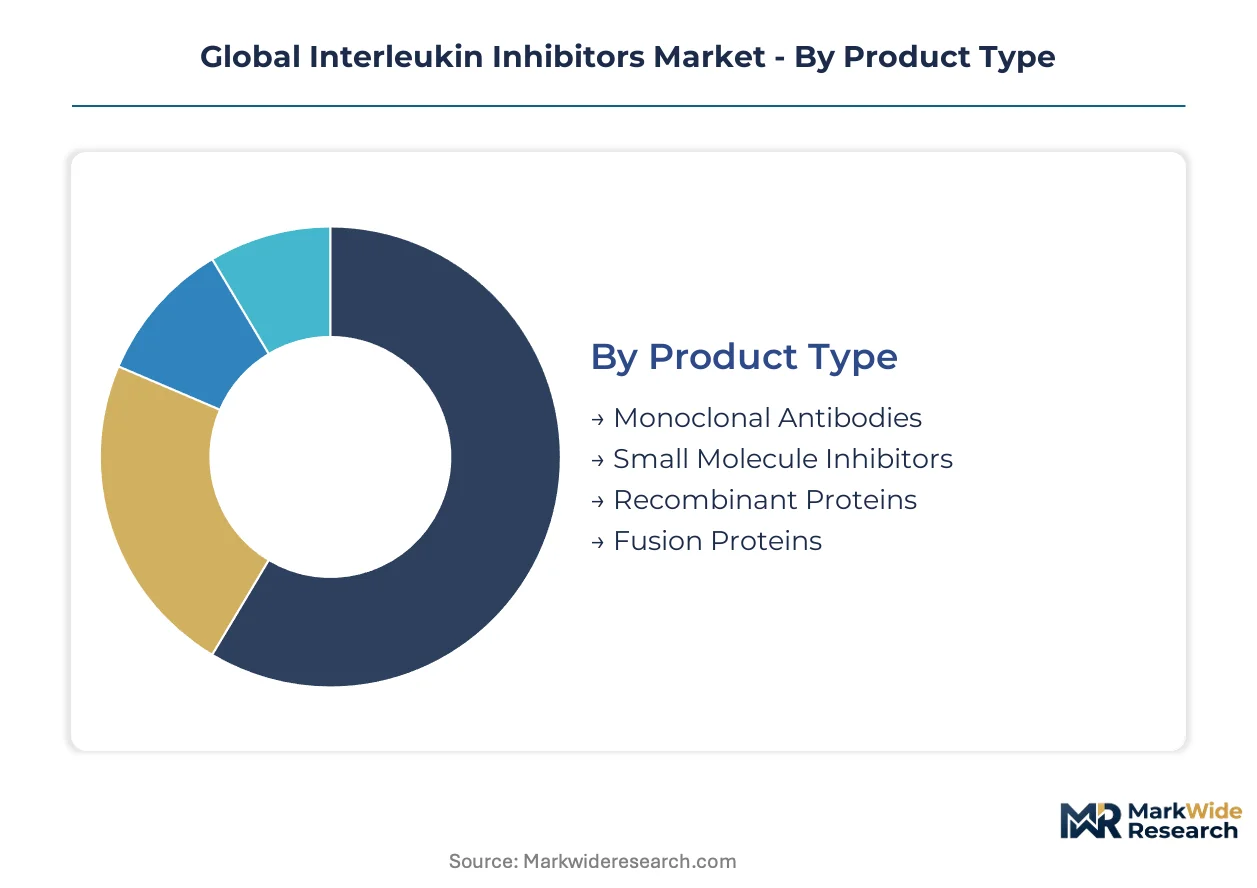
Interleukin inhibitor segmentation reveals divergent commercial strategies across molecular platforms and care settings. Product type and delivery mode choices determine manufacturing investment, reimbursement pathways, and competitive moat durability.
Product Type:
Monoclonal antibodies command premium pricing and hospital anchoring, while small molecules expand through outpatient convenience and oral bioavailability advantages.
- Monoclonal Antibodies:Engineered immunoglobulins bind IL-17 and IL-23 with picomolar affinity, delivering sustained cytokine blockade in psoriasis and psoriatic arthritis. Demand concentrates in United States specialty dermatology clinics where prior authorization infrastructure supports biologic reimbursement. FDA Breakthrough Therapy designations for novel IL-23 inhibitors accelerate development timelines and reinforce hospital formulary placement.
- Small Molecule Inhibitors:Oral agents targeting intracellular JAK-STAT pathways downstream of interleukin receptors offer patient-administered alternatives to injection regimens. Germany's outpatient biologic reimbursement expansion creates pull-through for oral IL-6 pathway modulators in rheumatoid arthritis, capturing price-sensitive segments from injectable biologics.
- Recombinant Proteins:Engineered cytokine traps and receptor antagonists provide IL-1 blockade in autoinflammatory syndromes with established manufacturing platforms.
- Fusion Proteins:Chimeric constructs combining receptor domains with antibody Fc regions extend half-life in chronic inflammatory conditions.
Mature deployment sits with monoclonal antibodies. Newer deployment is concentrated in small molecule inhibitors.
Therapy Area:
Autoimmune disease severity and tissue involvement pattern dictate interleukin target selection and dosing intensity across patient populations.
- Psoriasis:IL-17 and IL-23 pathway dominance in skin inflammation drives highest-volume biologic utilization, with United States dermatology practices standardizing quarterly maintenance regimens.
- Inflammatory Bowel Disease:IL-12/23 and IL-23 blockade in Crohn's disease requires intravenous induction followed by subcutaneous maintenance, creating complex care coordination demands in Japan's hospital-centric delivery system.
- Rheumatoid Arthritis:IL-6 receptor antagonists and IL-1 inhibitors compete with JAK inhibitors for moderate disease segments.
- Asthma:Type 2 inflammation biomarker stratification limits IL-4/IL-13 inhibitor penetration to eosinophilic phenotypes.
- Systemic Lupus Erythematosus:Interferon pathway overlap with interleukin signaling complicates targeted therapy development and regulatory endpoints.
Volume leadership resides in psoriasis. Steepest expansion trajectory appears in inflammatory bowel disease as diagnostic rates improve.
End User:
Site of care determines reimbursement mechanics, cold chain requirements, and patient adherence monitoring infrastructure.
- Specialty Clinics:Dedicated immunology centers in the United States administer subcutaneous maintenance doses with integrated pharmacy services and adherence tracking.
- Research Laboratories:Academic medical centers in Basel and Boston clusters conduct biomarker-stratified trials for novel IL-23 and IL-17 targets under FDA and EMA accelerated pathways.
- Pharmaceutical Companies:In-house development groups and externalized discovery partnerships drive candidate progression from cell line development to Phase I.
- Contract Research Organizations:Full-service providers manage multi-regional trials spanning PMDA immunogenicity requirements and EUnetHTA comparative effectiveness demands.
Commercial volume concentrates in specialty clinics. Capability investment is shifting toward contract research organizations as trial complexity escalates.
Delivery Mode:
Route of administration shapes patient adherence, healthcare resource utilization, and competitive differentiation in maintenance therapy.
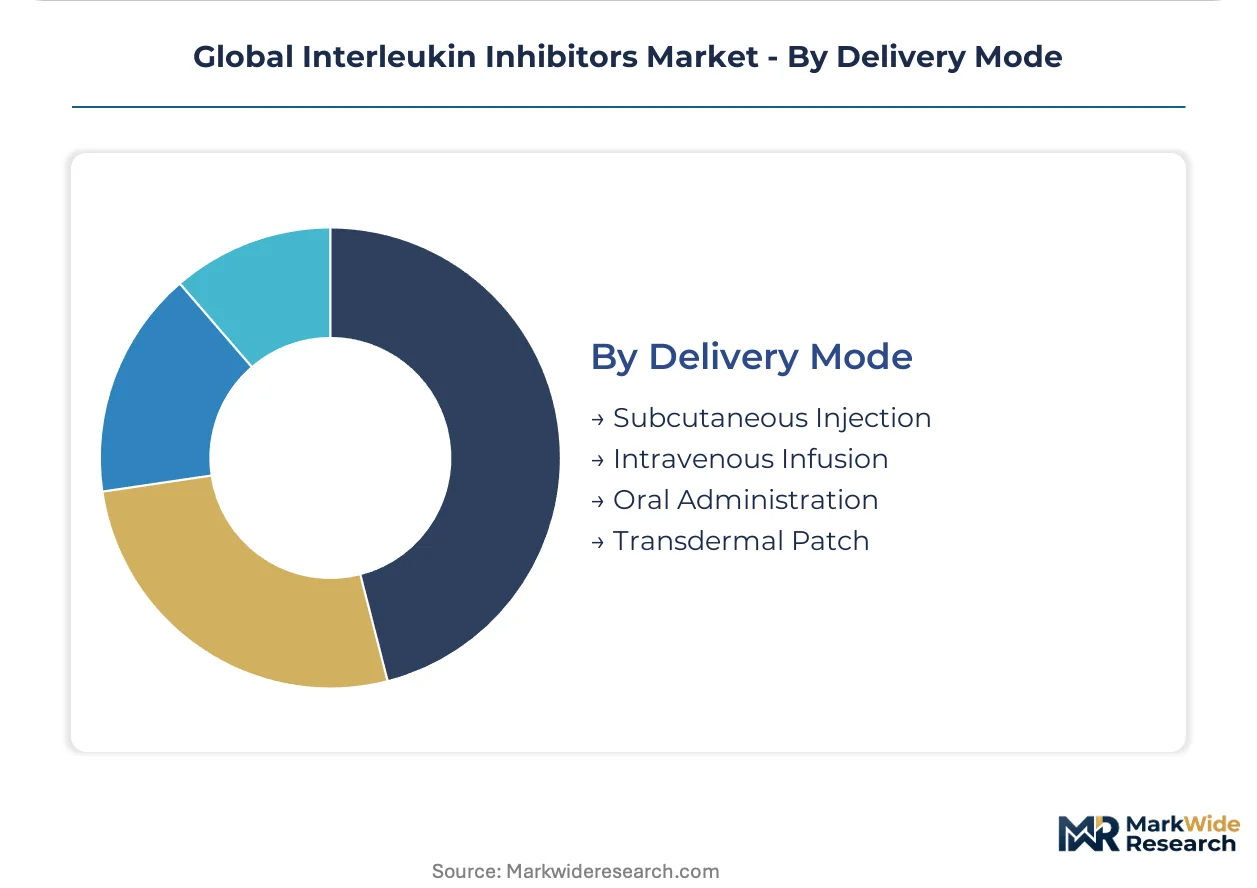
- Subcutaneous Injection:Prefilled syringes and autoinjector devices enable home administration, with half-life extended formulations compressing dosing frequency to quarterly intervals in United States specialty pharmacy networks.
- Intravenous Infusion:Hospital-administered induction regimens in inflammatory bowel disease retain premium positioning through controlled bioavailability and acute monitoring capacity.
- Oral Administration:Small molecule permeability and formulation stability challenges constrain IL-17 pathway targeting, though peptide engineering advances are narrowing the gap.
- Transdermal Patch:Microneedle array technologies for biologic delivery remain preclinical, with EMA MDR device classification uncertainties extending development timelines.
Established volume flows through subcutaneous injection. Innovation investment targets oral administration to capture injection-averse patient segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan as specialized immunology treatment centers expand biologic administration capacity and reimbursement frameworks mature. Regulatory acceleration through FDA Breakthrough Therapy designations and EMA adaptive licensing frameworks pulls forward commercialization timelines across these markets.
United States
Specialty dermatology clinics in the United States standardize quarterly maintenance regimens for IL-17 and IL-23 pathway inhibitors, creating pull-through demand for half-life extended formulations. FDA's accelerated approval pathways compress development timelines by 12-18 months versus standard review. The Greater Boston biopharma cluster anchors cell line development expertise for high-yield monoclonal antibody production.
Germany
Germany's outpatient biologic reimbursement expansion through G-BA's 2024 framework shift unlocks capacity constraints from hospital-centric delivery, enabling community-based administration. EMA's MDR implementation elevates clinical evidence requirements for Class III drug-device combination products. The Basel-Strasbourg biopharma corridor concentrates mammalian expression system optimization capabilities.
Japan
Japan's hospital-centric delivery system for inflammatory bowel disease creates complex care coordination demands for intravenous induction regimens. METI's pricing and reimbursement incentives for follow-on biologics expand patient access to IL-6 pathway inhibitors. PMDA maintains stringent immunogenicity standards that shape formulation requirements for Asia-Pacific market entry.
India
Underpenetrated rheumatology screening in India's tier-2 cities creates first-mover positioning for biosimilar IL-6 inhibitors as diagnostic infrastructure improves. CDSCO's evolving biosimilar guidelines shape local manufacturing investment decisions. The Hyderabad-Bengaluru pharmaceutical corridor concentrates contract research capabilities for multi-regional immunogenicity trials.
United Kingdom
The United Kingdom's integrated specialty pharmacy networks bundle drug, device, and adherence monitoring services, consolidating purchasing decisions for inflammatory bowel disease therapies. MHRA's post-Brexit regulatory alignment with EMA standards maintains CE marking continuity for autoinjector systems. The London-Cambridge life sciences cluster anchors biomarker-stratified trial design for novel IL-23 targets.
Global Interleukin Inhibitors Market Competitive Landscape
Portfolio diversification dominates the current landscape as established biopharma groups extend immunology franchises through next-generation IL pathway targeting. The market structure consolidates around large-cap integrated pharmaceutical companies with captive biologics manufacturing infrastructure. Three archetypes define competitive positioning: vertically integrated biologics manufacturers with global supply networks, specialty immunology players with deep clinical development expertise, and emerging biosimilar specialists with cost-optimized production platforms. M&A activity and strategic licensing partnerships constitute the primary competitive moves, with particular intensity around IL-23 and IL-17 targeting assets.
Within the integrated biopharma tier, Novartis AG and AbbVie Inc. exemplify contrasting supply security strategies. Novartis leverages deep manufacturing scale in biologics production to anchor high-volume autoimmune therapy supply chains. AbbVie occupies a position defined by sustained R&D intensity in next-generation IL inhibitors and control over legacy immunology infrastructure. Johnson & Johnson Services, Inc. represents the diversified healthcare conglomerate archetype, with immunology assets nested within broader pharmaceutical and medical device portfolios.
| Leading Market Players |
|---|
| Novartis AG |
| AbbVie Inc. |
| Johnson & Johnson Services, Inc. |
| Eli Lilly and Company |
| Regeneron Pharmaceuticals Inc. |
| F. Hoffmann-La Roche Ltd |
| AstraZeneca |
| GlaxoSmithKline plc |
| Teva Pharmaceutical Industries Ltd |
| Others |
Supply & Pricing Matrix
Large-cap integrated pharmaceutical groups with captive biologics manufacturing anchor pricing discipline through in-house production of high-yield monoclonal antibodies, insulating premium tiers from spot-market API volatility while compressing margins for outsourced competitors dependent on contract manufacturing organizations.
Pricing Analysis
Volume leadership concentrates in quarterly and semi-annual subcutaneous maintenance regimens, while premium positioning attaches to intravenous induction protocols in hospital settings. Pricing stratifies across originator biologics, authorized biosimilars, and emerging small-molecule alternatives, with differentiation driven by FDA Breakthrough Therapy designation status and cold-chain service bundling. Cost compression in the biosimilar tier is intensifying because Japan's METI pricing incentives expand patient access to IL-6 pathway inhibitors. Price-sensitive segments in rheumatoid arthritis exhibit highest elasticity, shifting toward oral JAK inhibitors, whereas psoriasis patients in United States specialty dermatology clinics demonstrate lowest sensitivity due to prior authorization infrastructure locking in biologic reimbursement.
Supply Chain Analysis
EMA MDR certification and FDA current good manufacturing practice qualification gate entry for autoinjector systems and drug-device combination products, extending compliance timelines for novel delivery technologies. Mammalian cell line development concentrates in the United States, Switzerland, and Germany, with the Boston and Basel clusters anchoring high-yield expression system optimization. Production draws from Chinese hamster ovary cell banks, single-use bioreactor systems, and affinity chromatography resins. Single-source vulnerability in specialty enzyme supply creates concentration risk for half-life extension technologies. Distribution runs through integrated United States specialty pharmacy networks that bundle drug, device, and adherence monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The interleukin inhibitor market is becoming a vertical-integration race as players pursue captive cell line development capabilities to secure supply continuity for high-volume autoimmune therapies and defend against biosimilar price erosion.
For Market Incumbents: Lock in supply security through backward integration into mammalian expression system optimization, concentrating investment in the Boston and Basel bioprocess engineering clusters. Prioritize half-life extended formulation development to compress dosing frequency and defend against small-molecule JAK inhibitor substitution in rheumatoid arthritis. Channel control through specialty pharmacy network partnerships protects prior authorization infrastructure from disintermediation. For New Entrants and Emerging Players: Contract research organizations with multi-regional immunogenicity trial capabilities offer the most accessible entry vector, enabling service-based participation before asset ownership. India's tier-2 rheumatology screening expansion presents the most penetrable geography for biosimilar IL-6 inhibitors as diagnostic infrastructure improves. A go-to-market angle anchored in cost-optimized production platforms targets price-sensitive segments eroding from originator biologics. For Investors and Strategic Acquirers: Distressed-cycle entries favor emerging biosimilar specialists with cost-optimized production platforms in India and South Korea as patent cliffs accelerate for legacy IL-12/23 inhibitors. Long-term viability across the analysis window hinges on positioning within oral small-molecule development pipelines targeting IL-17 pathways. The signal to watch is EUnetHTA comparative effectiveness evidence requirements, which will determine which development-stage assets can secure premium reimbursement in European markets.| Strategic Initiative | Industry Significance |
|---|---|
| Cell Line Development Scale-Up | Captive mammalian expression systems in Basel and Boston clusters secure supply continuity for high-volume IL-23 inhibitors. |
| Half-Life Extension Formulation | Quarterly and semi-annual dosing regimens compress competitive pressure from monthly injection legacy products in United States specialty pharmacy networks. |
| Oral Small-Molecule Pipeline | Peptide engineering advances targeting IL-17 pathways capture injection-averse patient populations from subcutaneous biologics. |
| Biosimilar Manufacturing Investment | Cost-optimized production platforms in India and South Korea exploit patent cliffs for IL-12/23 inhibitors in price-sensitive segments. |
| Specialty Pharmacy Integration | Full-service coordination with CVS Specialty and Accredo bundles adherence monitoring and prior authorization management for inflammatory bowel disease therapies. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists across the United States, Germany, and Japan. FDA Breakthrough Therapy designation databases, EMA adaptive pathway submissions, ClinicalTrials.gov entries, and Japan PMDA consultation minutes provided structured secondary validation. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Granularity-level modeling operated at the interleukin target-by-therapy area intersection, with separate projections for IL-17, IL-23, IL-6, and IL-1 pathway inhibitors across psoriasis, inflammatory bowel disease, rheumatoid arthritis, and asthma indications. Administration route, patient treatment line, and regional regulatory cluster dimensions shaped volume and value outputs over the projection horizon. CAGRs derived from patent expiry schedules, biosimilar entry assumptions, and diagnostic rate improvement curves in underpenetrated geographies.
Caveats apply where FDA accelerated approval pathway modifications, EUnetHTA comparative effectiveness convergence, or Japan PMDA immunogenicity standard revisions could materially shift the outlook. Forecasts reflect assumptions regarding biosimilar substitution rates and specialty clinic expansion trajectories. A model refresh is warranted upon material change in G-BA outpatient biologic reimbursement implementation or IL-17 small-molecule clinical trial readouts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Istradefylline API Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
BRAF-MEK Inhibitors Market
Pharmaceuticals
Global Vaccine Contract Manufacturing Market
Pharmaceuticals
Intranasal Migraine Drugs Market
Pharmaceuticals
Japan Diabetes Drugs Market
Pharmaceuticals
Antidiuretic Drugs Market
Pharmaceuticals
Critical Care Antiarrhythmic Drugs Market
Pharmaceuticals
Global Travel Vaccines Market
Pharmaceuticals
Global PD-1 and PD-L1 Inhibitors Market
Pharmaceuticals
Immunoglobulin Market
Pharmaceuticals
Europe Pharmaceutical Contract Sales Outsourcing (CSO) Market
Pharmaceuticals
AI in Pharma Market
Pharmaceuticals
North America Anticoccidial Drugs Market
Pharmaceuticals
Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market