
 G Protein Coupled Receptors (Gpcrs) Market | 2026-2036
G Protein Coupled Receptors (Gpcrs) Market Size, Share, and Industry Trends Forecast 2026-2036
G Protein Coupled Receptors (Gpcrs) Market Intelligence
High-resolution structural characterization is rotating toward cryo-EM and X-ray crystallography standards that command premium pricing. Thermo Fisher Scientific leverages its integrated instrument-reagent workflow to dominate structural biology service contracts. WuXi AppTec anchors global CRO capacity through captive GPCR expression platforms. Promega Corporation differentiates with proprietary luminescence assay formats that reduce false-positive rates in screening campaigns.
G protein coupled receptors constitute a superfamily of seven-transmembrane domain receptors that transduce extracellular signals through intracellular G-protein and arrestin pathways, with structural topology defined by extracellular N-termini, seven alpha-helical transmembrane segments, and intracellular C-terminal tails. These receptors mediate cellular responses to hormones, neurotransmitters, and sensory stimuli, making them the most targeted protein class in approved pharmaceuticals. Drug development applications capture the largest value pool given the historical success of GPCR-targeted therapeutics in cardiovascular and central nervous system indications. CRISPR-enabled knockout and knock-in cell lines represent the fastest-expanding technology segment as sponsors demand genetically validated assay systems. Research applications retain stable funding through NIH and Wellcome Trust grants, though margin compression persists in commoditized binding assays.
FDA orphan drug designations and EMA PRIME eligibility reshape investment priorities toward rare GPCR-linked diseases. China's NMPA innovation pathway and revised drug registration rules accelerate local sponsor entry into GPCR modulator development. ISO 13485 and GLP compliance requirements for diagnostic GPCR biomarker assays create certification barriers that filter smaller reagent suppliers. Stakeholders must monitor how AI-driven structure prediction tools alter the economics of de novo GPCR ligand design versus traditional high-throughput screening infrastructure.
Market Dynamics
Cryo-EM structural determination is compressing timelines for GPCR ligand optimization, displacing traditional NMR-based approaches and forcing CROs to retool capital equipment portfolios.
Growth Catalysts
- FDA Accelerated Approval:Orphan GPCR indications gain priority review vouchers that compress development timelines for rare disease sponsors.
- CRISPR Cell Engineering:Knockout and knock-in lines deliver genetically validated screening systems that reduce target validation failure rates.
- China NMPA Innovation Pathway:Revised drug registration rules fast-track domestic GPCR modulator candidates into Phase I trials.
Market Restraints
- Helium Supply Concentration:Cryo-EM instrument cooling depends on Qatar and US helium reserves, creating input cost volatility for structural biology service providers.
- Transmembrane Expression Bottlenecks:Mammalian cell systems yield insufficient GPCR protein for crystallography, constraining high-throughput structure pipelines.
- ISO 13485 Certification Barriers:Diagnostic GPCR biomarker assays require quality management compliance that filters smaller reagent suppliers from clinical markets.
Strategic Opportunities
- Allosteric Modulator Design:AI-driven structure prediction converges with cryo-EM density maps to unlock druggable sites beyond orthosteric pockets.
- India CDMO Expansion:Contract development capacity for GPCR-targeted biologics remains underdeveloped relative to small-molecule chemistry services.
- Sensor GPCR Applications:Olfactory and taste receptor platforms migrate into food safety and environmental monitoring diagnostics.
Industry Challenges
- Membrane Protein Crystallography Expertise:Academic training pipelines produce fewer specialists capable of lipidic cubic phase methods.
- Cross-Reactivity Liability:GPCR subfamily homology generates off-target pharmacology that complicates IND-enabling safety packages.
- Legacy Assay Integration:Radioligand binding formats persist in regulatory submissions despite luminescence replacement, forcing dual-platform validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | G Protein Coupled Receptors (Gpcrs) Market |
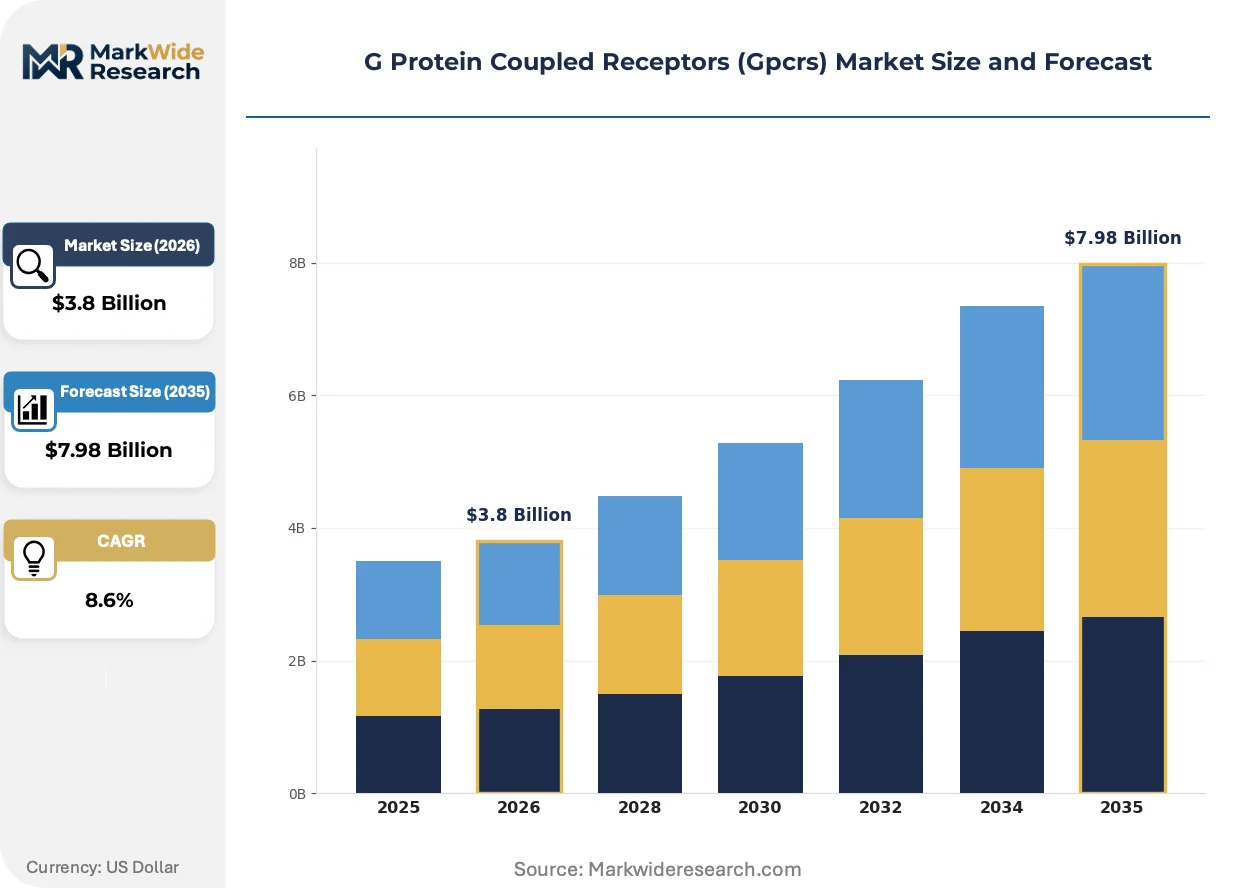
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agonists, Antagonists, Modulators, Inhibitors Application: Drug Development, Diagnostics, Research, Therapeutics End User: Pharmaceutical Companies, Research Institutions, Biotechnology Firms, Hospitals Technology: High-Throughput Screening, CRISPR, Molecular Imaging, Bioinformatics |
| Companies Covered | Thermo Fisher Scientific, Promega Corporation, Abcam plc, Eurofins Scientific, QIAGEN, Merck KGaA, WuXi AppTec, Enzo Biochem, Becton Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
G Protein Coupled Receptors (Gpcrs) Market Strategic Shifts & Innovations
Structural biology workflows are fragmenting into specialized nodes as resolution requirements diverge between drug discovery and mechanistic research applications.
Cryo-electron microscopy is decomposing the monopoly of X-ray crystallography for GPCR structure determination. Mid-size biotech sponsors now specify cryo-EM deliverables in CRO contracts that previously demanded crystal structures. This instrument shift is decomposing the pricing power of established structural biology facilities that lack electron microscopy capacity.
EMA PRIME eligibility is redirecting capital toward rare GPCR-linked indications with unmet medical need. Designated products receive enhanced regulatory dialogue and accelerated assessment timelines. European sponsors with PRIME-designated GPCR programs are reallocating manufacturing investment toward single-product facilities.
Biopharma procurement teams are unbundling structural biology contracts from integrated discovery alliances. Stand-alone cryo-EM service agreements now compete with captive platform access at WuXi AppTec and Thermo Fisher Scientific. This purchasing pattern is most visible among Boston and San Francisco headquartered sponsors with internal medicinal chemistry capabilities.
G Protein Coupled Receptors (Gpcrs) Market Segmentation
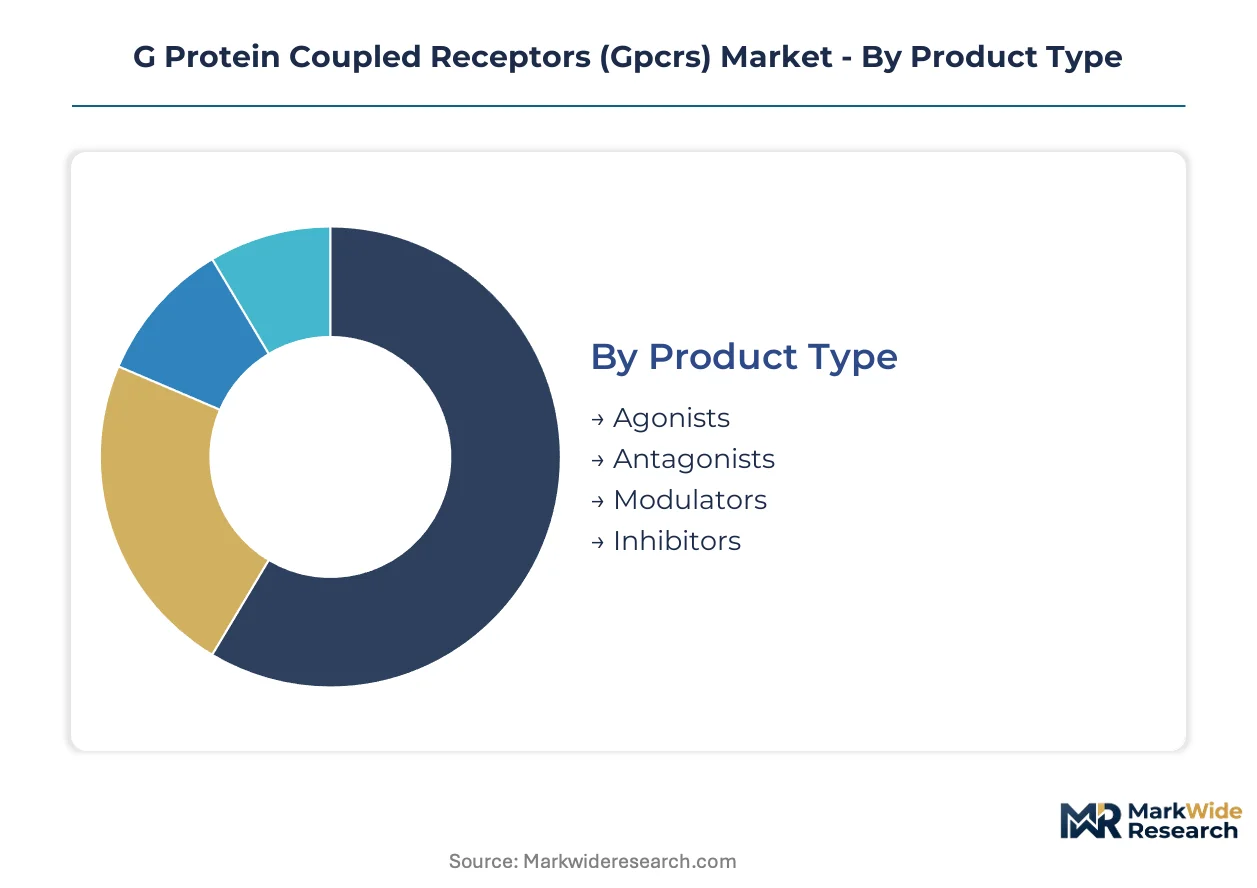
GPCR market segmentation reveals how value pools concentrate around therapeutic modality and target validation technology. Product type and application dimensions capture the largest margin differentials, while end-user and technology splits expose procurement power and capability gaps.
Product Type:
Margin pools concentrate in differentiated pharmacology rather than commodity antagonism, with mechanism complexity commanding pricing premiums.
- Agonists:Full and partial agonists activate GPCR signaling through G-protein or arrestin pathways, with biased agonism emerging as a precision mechanism. Demand clusters in cardiovascular and metabolic indications where receptor activation drives therapeutic effect, though selectivity engineering against subfamily homology remains a formulation challenge.
- Antagonists:Competitive and non-competitive blockers occupy orthosteric or allosteric sites to silence constitutive receptor activity. United States and German sponsors dominate procurement for CNS-targeted antagonists, where blood-brain barrier penetration specifications filter supplier capabilities.
- Modulators:Allosteric and bitopic modulators tune receptor sensitivity without direct activation, enabling pathway-selective pharmacology.
- Inhibitors:Small-molecule and peptide inhibitors target GPCR kinases or downstream effectors, extending druggable space beyond receptor orthosteric pockets.
The dominant share belongs to Antagonists, while Modulators is closing the gap fastest.
Application:
Application value splits along regulatory validation depth, with clinically translatable segments capturing premium pricing over exploratory research.
- Drug Development:Lead optimization through IND-enabling studies consumes the largest GPCR reagent and service expenditure, with cryo-EM structural packages and CRISPR-validated cell lines now standard in sponsor contracts. China's NMPA innovation pathway is accelerating local investment in GPCR modulator pipelines.
- Therapeutics:Approved and late-clinical GPCR-targeted drugs drive manufacturing demand for active pharmaceutical ingredients and formulation development. FDA accelerated approval for orphan indications is reshaping investment toward rare disease GPCR targets.
- Research:Academic and pre-competitive exploration of GPCR biology maintains stable funding through NIH and Wellcome Trust mechanisms.
- Diagnostics:GPCR biomarker assays for receptor occupancy and disease stratification face ISO 13485 certification barriers that filter smaller reagent suppliers from clinical markets.
Drug Development commands the largest value pool, while Diagnostics is expanding most quickly as companion diagnostic requirements tighten.
End User:
Procurement concentration reflects R&D scale and vertical integration strategies across the biopharma value chain.
- Pharmaceutical Companies:Large-cap sponsors with internal medicinal chemistry capabilities are unbundling structural biology contracts, procuring stand-alone cryo-EM services separately from integrated discovery alliances.
- Biotechnology Firms:Mid-size sponsors specify cryo-EM deliverables in CRO contracts that previously demanded crystal structures, fragmenting purchasing patterns.
- Research Institutions:Academic centers face capital equipment constraints as cryo-EM displaces NMR, forcing core facility consolidation.
- Hospitals:Clinical translation of GPCR diagnostics remains limited by reimbursement uncertainty and biomarker validation timelines.
Pharmaceutical Companies retain dominant procurement volume, though Biotechnology Firms is gaining share fastest through venture-backed GPCR platform companies.
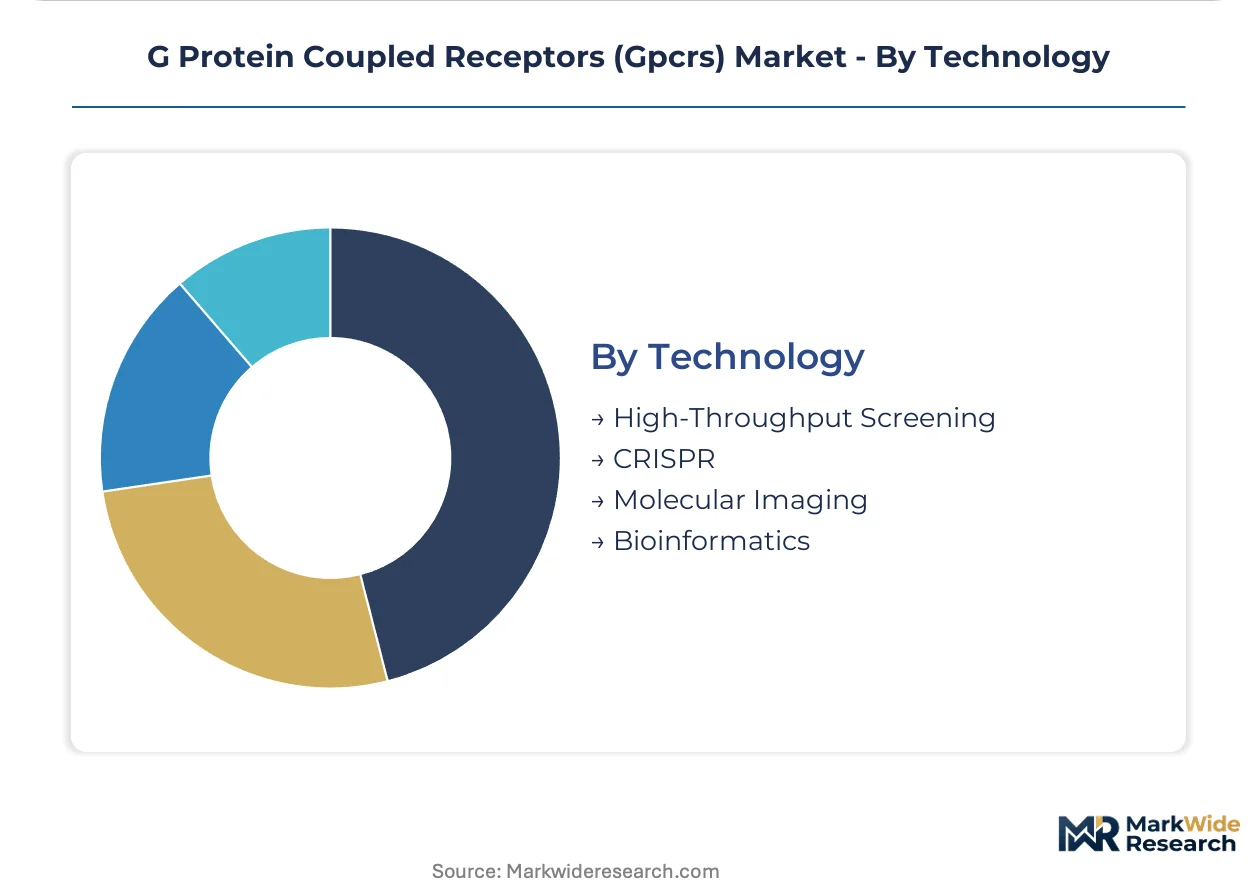
Technology:
Technology segmentation tracks the displacement of legacy formats by genetically validated and structurally resolved systems.
- CRISPR:Knockout and knock-in cell lines deliver genetically validated screening systems that reduce target validation failure rates, representing the steepest expansion trajectory as sponsors demand orthogonal confirmation.
- High-Throughput Screening:Automated ligand binding and functional assays persist in lead generation, though luminescence formats are displacing radioligand methods.
- Molecular Imaging:Cryo-EM and advanced fluorescence techniques resolve GPCR conformational states and protein-protein interactions.
- Bioinformatics:AI-driven structure prediction tools are altering the economics of de novo ligand design versus traditional screening infrastructure.
High-Throughput Screening maintains installed base dominance, while CRISPR is climbing the fastest as genetically defined assay systems become standard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract research capacity clusters around established biopharma hubs where GPCR structural biology and screening infrastructure concentrate. The United States, China, and Germany anchor service demand, with regulatory pathways in each jurisdiction reshaping investment timing and facility location decisions.
United States
FDA accelerated approval pathways for orphan GPCR indications compress development timelines and concentrate sponsor investment in rare disease targets. Priority review vouchers reward sponsors addressing unmet needs in GPCR-linked conditions. Greater Boston and San Francisco Bay Area biotech clusters house the largest concentration of mid-size sponsors specifying cryo-EM deliverables in CRO contracts.
China
NMPA innovation pathway and revised drug registration rules fast-track domestic GPCR modulator candidates into Phase I trials. Local sponsors now procure CRISPR-validated cell lines and structural biology packages previously sourced from Western CROs. Shanghai and Suzhou industrial parks host expanding captive GPCR expression platforms serving both domestic and multinational sponsors.
Germany
EMA PRIME eligibility redirects capital toward rare GPCR-linked diseases, with designated products receiving enhanced regulatory dialogue and accelerated assessment timelines. Heidelberg and Munich academic centers train specialists in lipidic cubic phase crystallography methods. Bavarian CROs compete on integrated instrument-reagent workflows for structural biology service contracts.
Switzerland
Swissmedic alignment with EMA procedures enables synchronized European market entry for GPCR-targeted therapeutics. Basel and Zurich host precision medicine consortia exploring GPCR biomarker stratification. The country's diagnostic reagent suppliers face ISO 13485 certification barriers that filter smaller players from clinical assay markets.
United Kingdom
Wellcome Trust funding mechanisms sustain academic exploration of GPCR biology despite margin compression in commoditized binding assays. MHRA post-Brexit regulatory autonomy creates parallel submission requirements for sponsors seeking UK market access. London and Cambridge research institutions consolidate core facilities as cryo-EM displaces NMR capital equipment.
G Protein Coupled Receptors (Gpcrs) Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the GPCR reagent and service landscape. Integrated instrument-reagent workflows command premium pricing in structural biology, while commoditized assay formats face procurement pressure from large-cap pharmaceutical sponsors. Three archetypes dominate: diversified life science conglomerates with captive platform access, specialized CROs with regional scale advantages, and niche reagent suppliers with proprietary detection formats. Competitive moves center on unbundling service contracts and retooling capital equipment portfolios toward cryo-EM capacity.
Within the diversified conglomerate tier, Thermo Fisher Scientific anchors integrated workflow offerings, while WuXi AppTec represents captive platform access models. Among specialized reagent developers, Promega Corporation occupies a position defined by proprietary luminescence formats. These three exemplify how technology differentiation and geographic reach segment competitive positioning in GPCR-targeted drug discovery infrastructure.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Promega Corporation |
| Abcam plc |
| Eurofins Scientific |
| QIAGEN |
| Merck KGaA |
| WuXi AppTec |
| Enzo Biochem |
| Becton Dickinson and Company |
| Others |
Cost & Logistics Intelligence
Cryo-EM instrument procurement replacing legacy NMR infrastructure simultaneously redistributes supplier leverage toward Qatar and US helium reserve holders while compressing service pricing for structural biology packages across United States, China, and Germany. This substitution dynamic concentrates input cost volatility in cooling-dependent workflows while fragmenting buyer power as mid-size sponsors unbundle contracts from integrated discovery alliances.
Pricing Analysis
ISO 13485 dictates the pricing tier structure for diagnostic GPCR biomarker assays, separating GLP-certified premium structural biology packages from standard research-grade reagents and economy luminescence assay formats. Price differentiation rests on certification level and volume scale, with large-cap pharmaceutical sponsors extracting concessions on commoditized binding assays while CRISPR-validated cell lines command sustained premiums. Cost compression in standard-tier reagents is intensifying because Chinese domestic suppliers are expanding NMPA-compliant production capacity. Biotechnology firms with venture-backed platform architectures exhibit highest price sensitivity, whereas orphan disease sponsors with FDA priority review vouchers demonstrate lowest sensitivity to structural biology service costs.
Supply Chain Analysis
Strategic helium stockpiling dominates inventory strategy for cryo-EM-dependent structural biology service providers, contrasting with just-in-time reagent replenishment for luminescence assay manufacturers. Geographic supply concentration centers on the United States for electron microscopy instrumentation, China for CRISPR cell engineering consumables, and Germany for lipidic cubic phase crystallography reagents. Raw material dependencies include helium cooling reserves, recombinant GPCR expression vectors, and synthetic lipid matrices for membrane protein stabilization. Single-source vulnerability in Qatar helium exports creates structural supply risk for cryo-EM cooling systems. Distribution runs through captive platform access at integrated conglomerates and unbundled service agreements with specialized CROs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized cryo-EM operator capacity constitutes the critical scarce asset in this market, with academic training pipelines producing fewer lipidic cubic phase crystallography specialists than sponsor demand requires. This capability gap concentrates margin capture among integrated instrument-reagent workflow providers while fragmenting competitive positioning for pure-play reagent suppliers.
For Market Incumbents: Fortify structural biology service contracts by embedding CRISPR-validated cell line offerings into integrated discovery alliances, countering sponsor tendencies toward unbundled procurement. Expand captive helium reserve partnerships or alternative cooling technology R&D to mitigate Qatar supply concentration risk. Prioritize GLP certification investments for diagnostic GPCR biomarker assays to defend premium pricing tiers against ISO 13485-compliant entrants.
For New Entrants and Emerging Players: Stand-alone cryo-EM service capacity represents the most penetrable white-space target, as established structural biology facilities lacking electron microscopy capacity face pricing erosion. India's underdeveloped contract development capacity for GPCR-targeted biologics offers geographic expansion opportunity absent dominant incumbent presence. Pursue sensor GPCR diagnostic applications in food safety and environmental monitoring, where reimbursement uncertainty filters large-cap pharmaceutical sponsors and regulatory pathways remain less congested than therapeutic indications.
For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors platform consolidators with integrated instrument-reagent workflows over point-solution reagent developers. Long-term viability over the next decade hinges on structural biology service providers achieving scale in cryo-EM capacity before academic training pipelines replenish specialist supply. Acquisition targets should display proprietary luminescence detection formats or captive GPCR expression platforms. The signal to watch is FDA orphan drug designation velocity for rare GPCR-linked diseases, which indicates sponsor R&D budget allocation toward premium service procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryo-EM Capacity Expansion | Captures sponsor contracts shifting from X-ray crystallography structural deliverables. |
| CRISPR Cell Engineering Platform | Delivers genetically validated screening systems reducing target validation failure rates. |
| Helium Supply Partnership | Secures cooling input for electron microscopy against Qatar reserve volatility. |
| ISO 13485 Certification Pathway | Enables diagnostic GPCR biomarker assay entry into clinical markets. |
| India CDMO Geographic Expansion | Addresses underdeveloped contract development capacity for GPCR-targeted biologics. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA orphan drug filings, EMA PRIME designation records, NMPA innovation pathway submissions, and ClinicalTrials.gov protocol registries. Primary interviews engaged drug development executives at mid-size biotechnology sponsors, regulatory affairs leads navigating accelerated approval pathways, CRO procurement managers specifying cryo-EM deliverables, and academic core facility directors consolidating capital equipment. Secondary validation drew from SEC 10-K disclosures of diversified life science conglomerates, NIH grant funding databases, and ISO certification registries. Bottom-up triangulation across sponsor R&D expenditure patterns converges with top-down market sizing across structural biology service contracts and reagent procurement volumes.
Segmentation dimensions modeled span product type, application, end user, and technology across the projection horizon. The analytical framework incorporates therapeutic modality complexity, regulatory validation depth, and procurement concentration patterns. CAGRs derive from sponsor pipeline expansion rates, CRO capacity utilization trends, and instrument replacement cycles. Industry-specific forecast inputs include CRISPR cell line adoption velocity and cryo-EM instrument installation rates at academic and commercial facilities.
Material uncertainties — helium supply disruption, transmembrane expression yield breakthroughs, AI-driven structure prediction accuracy thresholds — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained FDA and EMA accelerated approval pathway utilization and NMPA innovation pathway throughput. Revision becomes warranted when cryo-EM resolution capabilities or AI structure prediction accuracy cross thresholds that displace traditional high-throughput screening infrastructure economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
US Generic Injectables Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Performance Enhancing Drugs Market
Pharmaceuticals
Disease-Modifying Agents Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Non-Sterile Compounding Pharmacy Market
Pharmaceuticals
Gastrointestinal OTC Drugs Market
Pharmaceuticals
Cardiometabolic Drugs Market
Pharmaceuticals
Rheumatology Therapeutics Market
Pharmaceuticals
Global Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
MRSA Antibiotic Preparations Market
Pharmaceuticals
Nikethamide Injection Market
Pharmaceuticals
North America Over the Counter Drugs Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
H2-Receptor Antagonists Market
Pharmaceuticals
Antiretroviral (ARV) Agents Market
Pharmaceuticals
Optic Nerve Disorders Drugs Market