
 Hirschsprung Disease Treatment Market | 2026-2036
Hirschsprung Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hirschsprung Disease Treatment Market Analysis
The gap between premium surgical platforms and commodity supportive care is realigning how capital flows across the Hirschsprung disease treatment landscape. Medtronic plc leverages its minimally invasive instrumentation portfolio to dominate advanced pull-through procedures in tertiary pediatric centers. Johnson & Johnson anchors its position through broad enteral nutrition and wound closure portfolios that sustain recurring revenue in postoperative care.
Hirschsprung disease treatment encompasses surgical correction of aganglionic bowel segments, pharmacologic management of enterocolitis, and nutritional support for intestinal dysmotility, with pull-through procedures typically requiring anastomosis within one centimeter of the dentate line to preserve continence. Surgery commands the largest share of intervention value while enteral nutrition represents the fastest-growing segment as home-based feeding protocols reduce hospital readmission burdens. Neonatal and pediatric patient age groups concentrate procedure volume, whereas adult presentations—often delayed diagnoses—generate higher per-case expenditure due to complex secondary complications.
FDA PMA oversight governs novel surgical devices and biologics in the United States, while EMA orphan drug incentives shape European development priorities for aganglionosis therapies. Pediatric device consortia in both jurisdictions are streamlining trial design for small-population indications, directly affecting how manufacturers allocate R&D budgets and clinical evidence investments. Stakeholders must monitor evolving reimbursement thresholds for transition-of-care protocols as payers scrutinize long-term outcomes data across surgical and medical management pathways.
Market Dynamics
Minimally invasive surgical platforms are compressing the traditional three-stage pull-through protocol into single-intervention neonatal procedures, forcing equipment manufacturers to recalibrate their revenue models around disposable instrument volumes rather than capital equipment sales.
Growth Catalysts
- FDA PMA Pathway Streamlining:Pediatric device consortia in the United States have collapsed trial enrollment timelines for aganglionosis interventions. Device sponsors now access accelerated review through the Humanitarian Device Exemption track.
- Home-Based Enteral Nutrition Protocols:Tertiary pediatric centers in Germany are discharging postoperative patients with remote monitoring capabilities. This shift extends the therapeutic revenue window beyond acute surgical episodes.
- EMA Orphan Drug Incentives:European developers of neural crest cell therapies receive protocol assistance and fee waivers. These incentives redirect venture capital toward congenital enteric neuropathy targets.
Market Restraints
- Pediatric Surgical Workforce Concentration:Qualified pediatric colorectal surgeons cluster in fewer than forty academic medical centers across the United States. This geographic scarcity limits procedure volume expansion regardless of device availability.
- Biologic Cold Chain Requirements:Experimental aganglionic cell therapies require continuous cryogenic logistics. Distribution infrastructure gaps in secondary markets constrain clinical trial site selection.
- Reimbursement Compression for Supportive Care:Enteral formula and stoma supplies face utilization review by Medicaid programs. Prior authorization requirements extend payment cycles and elevate administrative costs for home health providers.
Strategic Opportunities
- Adult Delayed Diagnosis Segment:Patients presenting beyond childhood with Hirschsprung disease generate per-case expenditures threefold above neonatal indices. Specialized centers in Japan are developing dedicated adult transition clinics.
- Neural Stem Cell Convergence:Advances in induced pluripotent stem cell differentiation are intersecting with enteric nervous system biology. This convergence enables autologous cell sourcing for pull-through augmentation.
- Direct-to-Home Distribution Channels:Enteral nutrition manufacturers are bypassing durable medical equipment intermediaries. Direct shipment models capture margin previously allocated to regional distributors.
Industry Challenges
- Pediatric Surgical Training Pipeline Constraints:Fellowship positions in pediatric colorectal surgery have stagnated for fifteen years. Academic medical centers compete for a fixed pool of qualified candidates.
- Multicenter Trial Coordination Complexity:Aganglionosis indications require coordinated neonatal enrollment across dispersed surgical sites. Regulatory variance between institutional review boards fragments protocol execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hirschsprung Disease Treatment Market |
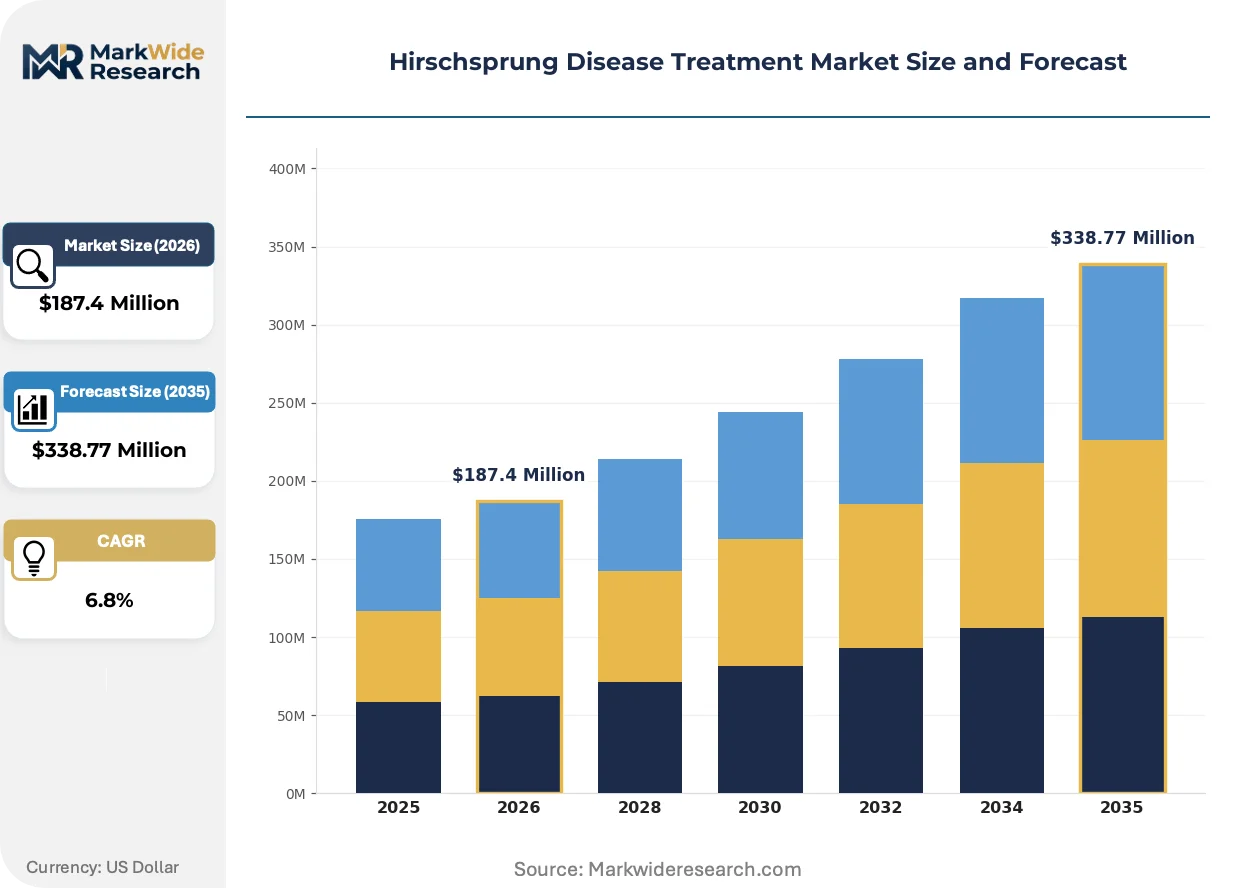
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Surgery, Medication, Enteral Nutrition, Supportive Care Indication: Long Segment, Short Segment, Intermediate Segment, Total Colonic Aganglionosis Patient Age Group: Pediatric, Neonatal, Adolescent, Adult Healthcare Setting: Hospital, Outpatient Clinic, Home Care, Specialty Center |
| Companies Covered | Medtronic plc, Johnson & Johnson, Pfizer Inc., Sanofi, Boston Scientific Corporation, B. Braun Melsungen AG, Novartis AG, Cook Medical, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hirschsprung Disease Treatment Market Emerging Trajectories
Robotic surgical platforms are reconfiguring the technical requirements for pull-through procedures, while regulatory frameworks for rare disease interventions accelerate biologic development timelines.
Laparoscopic and robotic-assisted transanal pull-through techniques are decentralizing the geographic distribution of complex pediatric colorectal surgery. Community hospitals with general pediatric surgeons are adopting these platforms to retain patients who previously transferred to quaternary centers. This diffusion is compressing referral network hierarchies and redistributing procedure volumes across health system tiers.
The FDA's Pediatric Device Consortia program has established standardized endpoints for aganglionosis device trials. This framework reduces protocol development costs for surgical instrument sponsors. European developers are aligning their clinical evidence packages with these FDA precedents to enable simultaneous transatlantic submissions.
Parental demand for single-stage neonatal repair is displacing traditional multi-stage protocols in United States referral centers. Families are selecting surgical programs based on published continence outcomes rather than institutional reputation alone. This behavioral shift is forcing centers to publish longitudinal functional data and invest in specialized pelvic floor rehabilitation services.
Hirschsprung Disease Treatment Market Segmentation
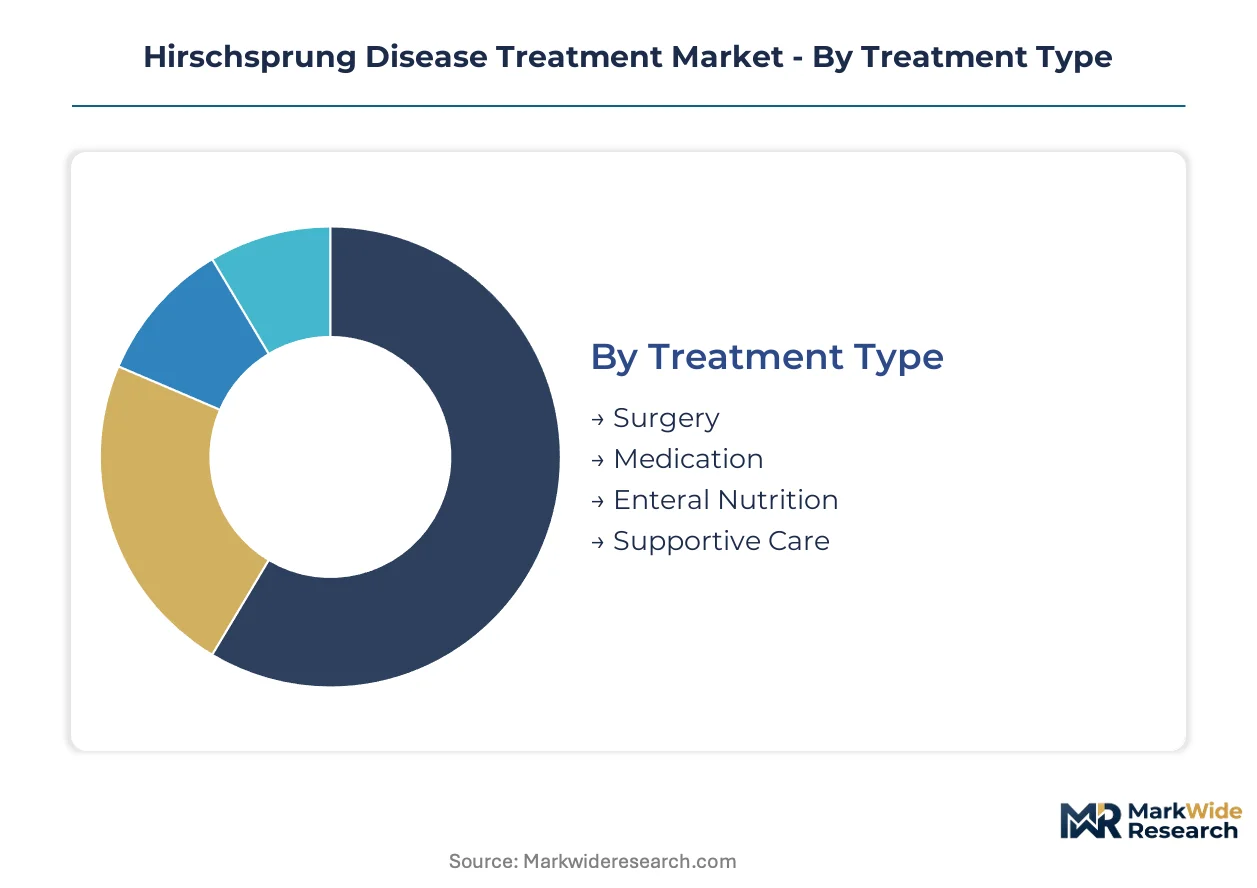
Surgical intervention dominates value capture in Hirschsprung disease treatment, while enteral nutrition and home-based protocols are redistributing revenue streams across acute and chronic care episodes. Segment boundaries blur as minimally invasive platforms compress traditional staging and shift procedure economics toward disposable instrumentation.
Treatment Type:
Surgical technique sophistication determines reimbursement tiering and capital equipment allocation across pediatric centers.
- Surgery:Pull-through procedures—transanal, laparoscopic, and robotic-assisted—require anastomosis within one centimeter of the dentate line to preserve continence. United States tertiary centers concentrate demand for single-stage neonatal repair as families select programs based on published functional outcomes.
- Enteral Nutrition:Home-based feeding protocols reduce hospital readmission burdens and extend therapeutic revenue windows beyond acute surgical episodes. Germany leads adoption of remote monitoring capabilities for postoperative discharge.
- Medication:Pharmacologic management targets enterocolitis prevention and intestinal dysmotility, with antibiotic prophylaxis and laxative regimens forming the standard of care.
- Supportive Care:Stoma management, wound closure, and pelvic floor rehabilitation services sustain recurring revenue in postoperative pathways.
Surgery leads on scale; enteral nutrition leads on momentum.
Indication:
Anatomical extent of aganglionosis dictates surgical complexity, operative duration, and long-term functional prognosis.
- Short Segment:Limited rectosigmoid involvement permits transanal pull-through without laparoscopic assistance. Community hospitals with general pediatric surgeons increasingly retain these cases that previously transferred to quaternary centers.
- Long Segment:Extends proximal to splenic flexure, requiring multi-stage protocols with diverting colostomy. Japan's specialized adult transition clinics report threefold higher per-case expenditure due to secondary complications.
- Intermediate Segment:Descending colon involvement presents technical variability in pull-through approach selection.
- Total Colonic Aganglionosis:Rare presentation requiring extensive bowel resection and lifelong nutritional management.
Short segment dominates procedural volume; long segment commands premium reimbursement.
Patient Age Group:
Diagnostic timing shapes intervention complexity, with delayed presentations generating substantially higher resource utilization.
- Neonatal:Newborn diagnosis enables single-stage repair and optimal functional outcomes. Parental demand for immediate definitive repair is displacing traditional multi-stage protocols in United States referral centers.
- Pediatric:Infant and childhood presentations concentrate the majority of annual procedure volume across academic medical centers.
- Adult:Delayed diagnosis—often misattributed to chronic constipation—generates complex secondary complications including megacolon and enterocolitis. Specialized centers in Japan are developing dedicated adult transition clinics to capture this high-expenditure segment.
- Adolescent:Transition-age patients require coordinated handoff from pediatric to adult colorectal services.
Pediatric captures volume concentration; adult delivers margin expansion.
Healthcare Setting:
Site-of-care migration reflects pressure to reduce inpatient utilization while maintaining specialized surgical expertise.
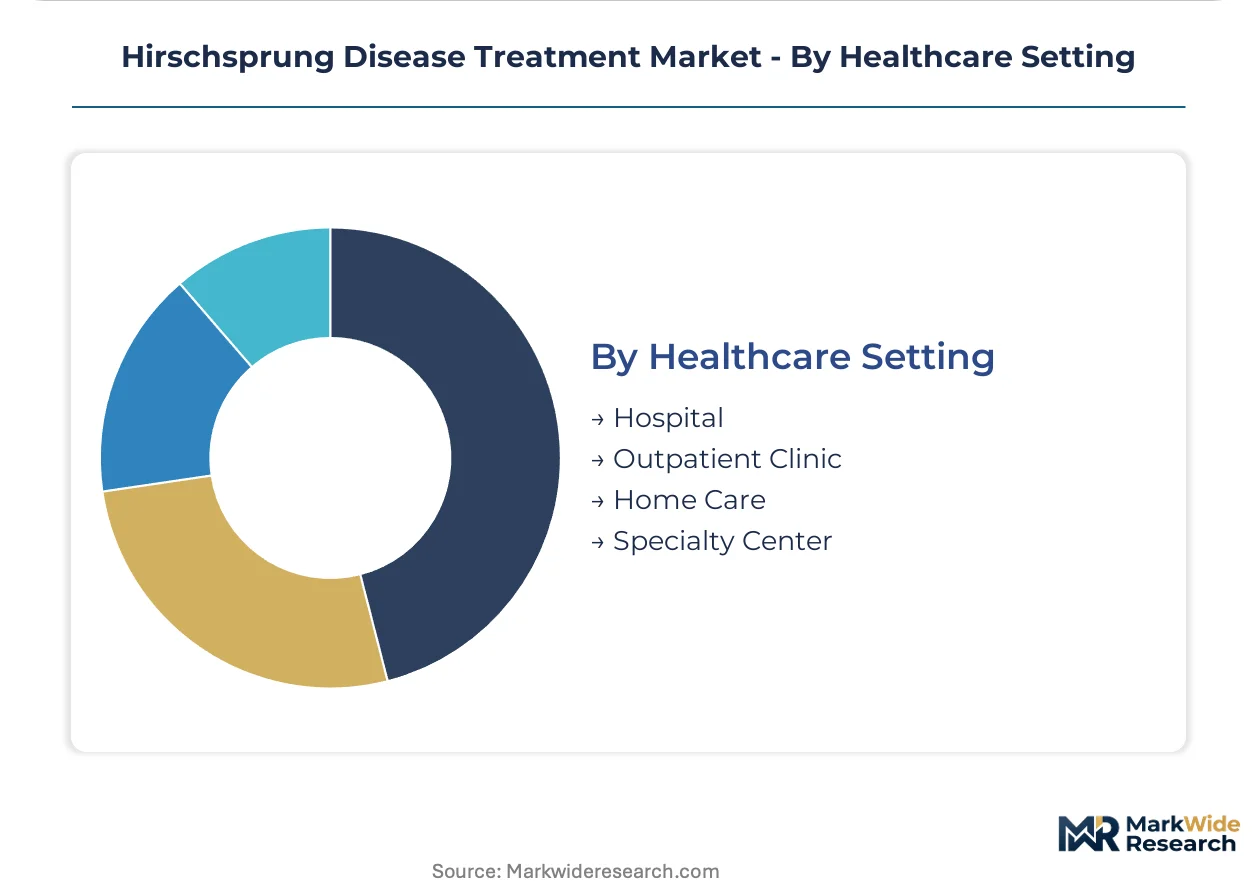
- Hospital:Inpatient surgical suites handle complex pull-through procedures, enterocolitis emergencies, and staged protocol completions. Fewer than forty academic medical centers across the United States concentrate qualified pediatric colorectal surgical capacity.
- Home Care:Direct-to-home enteral nutrition distribution bypasses durable medical equipment intermediaries, capturing margin previously allocated to regional distributors.
- Specialty Center:Dedicated pediatric colorectal programs publish longitudinal continence data to attract family selection based on outcomes rather than institutional reputation alone.
- Outpatient Clinic:Preoperative evaluation and postoperative surveillance visits sustain referral network relationships.
Hospital anchors intervention value; home care is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric colorectal surgical expertise clusters in fewer than forty academic medical centers across the United States, with similar workforce concentrations shaping treatment access in Germany and Japan. This geographic scarcity of qualified specialists directly determines where complex pull-through procedures concentrate and how referral networks organize patient flows.
United States
FDA Pediatric Device Consortia have standardized endpoints for aganglionosis trials, collapsing enrollment timelines for surgical instrument sponsors. The Humanitarian Device Exemption track accelerates review for rare disease interventions. Tertiary centers in Boston and Philadelphia publish longitudinal continence data to attract family selection based on outcomes.
Germany
EMA orphan drug incentives redirect venture capital toward congenital enteric neuropathy targets, with protocol assistance and fee waivers supporting neural crest cell therapy development. Home-based enteral nutrition protocols with remote monitoring capabilities extend therapeutic revenue windows beyond acute surgical episodes. Heidelberg and Berlin anchor specialized pediatric colorectal surgical capacity.
Japan
METI funding for rare disease infrastructure supports dedicated adult transition clinics capturing high-expenditure delayed diagnosis cases. PMDA streamlined review pathways for pediatric surgical devices align with FDA precedents to enable simultaneous transatlantic submissions. Tokyo and Osaka concentrate the nation's qualified pediatric colorectal surgical workforce.
United Kingdom
NHS specialized commissioning for congenital anomalies concentrates complex pull-through procedures in designated supraregional centers. MHRA alignment with FDA Pediatric Device Consortia endpoints reduces protocol development costs for surgical instrument sponsors. London and Manchester anchor the national referral network for aganglionosis interventions.
Canada
Health Canada priority review for pediatric medical devices accelerates market access for minimally invasive surgical platforms. Provincial health authority funding for home enteral nutrition programs reduces hospital readmission burdens post-surgery. Toronto and Vancouver concentrate pediatric colorectal surgical expertise and clinical trial site selection.
Hirschsprung Disease Treatment Market Vendor Landscape
Top-tier vendors anchor premium surgical instrumentation, while mid-tier nutrition and supportive care suppliers capture recurring revenue in postoperative pathways. The market structure reflects a bifurcation between capital-intensive device platforms and consumable-driven chronic care models. Strategic archetypes include integrated surgical conglomerates with broad minimally invasive portfolios, specialized pediatric nutrition providers with direct-to-home distribution capabilities, and regional medical device manufacturers with focused colorectal instrument lines. Dominant competitive moves center on portfolio diversification into adjacent chronic care segments and strategic partnerships with pediatric academic medical centers for clinical evidence generation.
Among diversified medical technology conglomerates, Medtronic plc and Johnson & Johnson occupy positions exemplifying contrasting strategic archetypes. Medtronic represents the premium surgical instrumentation vector, anchoring advanced pull-through procedure platforms in tertiary pediatric centers. Johnson & Johnson exemplifies the broad supportive care model, sustaining recurring revenue through enteral nutrition and wound closure portfolios. Stryker Corporation sits within the orthopedic-to-surgical expansion archetype, leveraging its hospital capital equipment relationships to access pediatric colorectal suites.
| Leading Market Players |
|---|
| Medtronic plc |
| Johnson & Johnson |
| Pfizer Inc. |
| Sanofi |
| Boston Scientific Corporation |
| B. Braun Melsungen AG |
| Novartis AG |
| Cook Medical |
| Stryker Corporation |
| Others |
Supply Flow & Price Mechanics
EMA orphan drug sustainability mandates gate both qualified biologic supply and premium-tier pricing access for neural crest cell therapies, compressing margins for manufacturers unable to demonstrate cryogenic logistics compliance or longitudinal clinical efficacy data.
Pricing Analysis
Bundled pull-through procedure packages command premium reimbursement at United States tertiary centers, while unbundled enteral nutrition and stoma supplies face utilization review and extended payment cycles. Three-tier pricing structure across premium single-stage neonatal repair, standard multi-stage protocols, and economy supportive care segments reflects certification by pediatric device consortia and published continence outcomes. Cost compression in commodity enteral formula runs through Medicaid prior authorization requirements. Family payers demonstrate highest price sensitivity for recurring home-based supplies, whereas hospital systems absorb premium surgical platform costs.
Supply Chain Analysis
Cryogenic freight costs for experimental aganglionic cell therapies constrain clinical trial site selection to major metropolitan corridors with validated cold chain infrastructure. Biologic manufacturing concentrates in Germany, the United States, and Japan where EMA and FDA pediatric device consortia streamline protocol development. Distribution runs through tertiary pediatric surgical centers and direct-to-home enteral nutrition channels. Single-source vulnerability persists for specialized pediatric colorectal instrumentation, with qualified surgeons clustering in fewer than forty academic medical centers across the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hirschsprung disease treatment functions as a stable compounder, with congenital anomaly incidence providing non-cyclical procedure volume and home-based care protocols extending revenue visibility beyond acute surgical episodes.
For Market Incumbents: Anchor market position through exclusive supply agreements with designated pediatric colorectal centers and backward integration into cryogenic biologic logistics. Defend against emerging robotic surgical platforms by embedding disposable instrument contracts within capital equipment leases. Invest in FDA Humanitarian Device Exclusion pathway expertise to accelerate competitor entry barriers. For New Entrants and Emerging Players: Launch via direct-to-home enteral nutrition distribution models bypassing durable medical equipment intermediaries. Target adult delayed diagnosis segments in Japan where METI-funded transition clinics concentrate high-expenditure cases underserved by pediatric-focused incumbents. Prioritize neural stem cell convergence partnerships with academic medical centers possessing enteric nervous system biology research programs. For Investors and Strategic Acquirers: Roll-up economics work for regional enteral nutrition providers because fragmented home health supplier bases lack national direct-shipment capabilities and reimbursement navigation expertise. Five-to-ten year viability rests on capturing Medicaid managed care contract concentration. Monitor FDA Pediatric Device Consortia endpoint standardization as signal for accelerated surgical instrument sponsor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Tertiary center alliances secure pull-through procedure volume and longitudinal outcome data publication rights. |
| FDA Humanitarian Device Exemption Submission | Accelerated review timelines compress competitor entry windows for rare disease surgical platforms. |
| Direct-to-Home Distribution Buildout | Bypassing durable medical equipment intermediaries captures margin from enteral nutrition and stoma supply segments. |
| Neural Crest Cell Therapy Pipeline Advancement | EMA orphan drug incentives redirect venture capital toward autologous cell sourcing for pull-through augmentation. |
| Pediatric Surgical Training Consortium Investment | Fellowship pipeline expansion addresses workforce concentration constraints limiting procedure volume growth. |
Methodological Framework
Multiple input streams — pediatric surgical registry data, hospital procurement databases, and regulatory filing repositories — were reconciled through bottom-up and top-down triangulation. Primary interviews with pediatric colorectal surgeons, biomedical engineers, GPO contracts managers, and home health reimbursement specialists were validated against secondary sources including FDA PMA filings, EMA orphan drug designations, ClinicalTrials.gov entries, and CMS Medicare cost reports.
Data-stream reconciliation across the projection horizon applied segmentation modeling by treatment type, patient age group, anatomical indication extent, and healthcare setting. CAGRs were derived from procedure volume trajectories, reimbursement rate evolution, and technology adoption S-curves. Forecast inputs incorporated neural stem cell therapy development timelines and pediatric surgical workforce pipeline projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory pathway delays or biologic cold chain infrastructure failures. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Inflammatory Bowel Disease Treatment Market
Gastroenterology
Zollinger Ellison Syndrome Treatment Market
Gastroenterology
Fecal Incontinence Market
Gastroenterology
Gastroretentive Drug Delivery Systems Outsourcing Market
Gastroenterology
Necrotic Enteritis Treatment Market
Gastroenterology
Gastric Cancer Market
Gastroenterology
Pouchitis Treatment Market
Gastroenterology
Disposable Intestinal Wash Bags Market
Gastroenterology
Gastritis Treatment Market
Gastroenterology
Inflammatory Bowel Disease Market
Gastroenterology
Intestinal Fistula Treatment Market
Gastroenterology
Stomach Cancer Market
Gastroenterology
Gluten Intolerance Treatment Market
Gastroenterology
Colon Hydrotherapy Market
Gastroenterology
US Gastroenterology Ambulatory Surgery Center Market
Gastroenterology
Biliary Tract Cancers (Btcs) Treatment Market