
 High Definition Ultrasound Gastroscope Market | 2026-2036
High Definition Ultrasound Gastroscope Market Size, Share, and Industry Trends Forecast 2026-2036
High Definition Ultrasound Gastroscope Market Insights
Multi-source procurement of ultrasonic transducer arrays is recalibrating supply economics for endoscope manufacturers. Olympus Corporation leverages captive ceramic foundry capacity to protect margin on high-frequency probes. Fujifilm Holdings Corporation anchors its position through backward integration into video processing chipsets. Boston Scientific Corporation competes via specialized therapeutic delivery channels in North American hospital systems.
A high definition ultrasound gastroscope combines an optical imaging channel with an integrated ultrasonic transducer operating at frequencies between 5 and 20 MHz, enabling simultaneous mucosal visualization and submucosal tissue characterization for oncologic staging and interventional guidance. The device requires precision-machined bending sections, miniaturized phased arrays, and dedicated processors to generate real-time cross-sectional images during endoscopic procedures. Flexible gastroscopy platforms command the largest installed base due to their versatility across diagnostic and therapeutic applications, while AI Integration represents the fastest-expanding technology segment as computer-assisted polyp detection and automated layer recognition reduce operator variability. Ultrasonic Device hardware captures the deepest margin pools because transducer miniaturization and frequency tuning demand proprietary materials expertise that few suppliers replicate.
FDA premarket notification requirements and EMA Medical Device Regulation conformity assessments govern acoustic output limits, biocompatibility of patient-contacting materials, and electromagnetic compatibility for processor units. ISO 13485 quality management standards and IEC 60601-1-2 ed. 4.1 collateral specifications further constrain design validation cycles for manufacturers targeting multiple regulatory jurisdictions. Stakeholders must monitor how FDA's evolving software-as-a-medical-device guidance applies to AI-enabled image enhancement features already embedded in next-generation platforms.
Market Dynamics
AI-enabled image enhancement is compressing operator training cycles and expanding addressable procedure volumes beyond specialist-only settings, fundamentally altering how hospitals justify capital investment in integrated endoscopic ultrasound suites.
Growth Catalysts
- Pancreatic oncology staging protocols:National cancer institutes in Germany, Japan, and the United States have elevated endoscopic ultrasound to mandatory staging modality for resectability assessment, creating procedural volume floors.
- FDA software-as-a-medical-device guidance:Clarified pathways for AI-assisted polyp detection accelerate regulatory clearance for computer-vision modules embedded in next-generation processors.
- Ceramic transducer miniaturization:Advances in piezoelectric material processing enable 20 MHz phased arrays within 2.4 mm diameter probes, expanding diagnostic resolution for submucosal layer assessment.
Market Restraints
- Single-source ceramic supply:High-purity lead zirconate titanate substrates concentrate among Japanese and German specialty chemical suppliers, exposing manufacturers to input volatility and allocation risk.
- Electromagnetic compatibility validation:IEC 60601-1-2 ed. 4.1 collateral specifications impose extended testing cycles for processor units, delaying multi-jurisdiction product launches.
- Capital equipment replacement cycles:Tertiary hospitals operate 7-10 year depreciation schedules for endoscope platforms, constraining upgrade velocity despite feature differentiation.
Strategic Opportunities
- Community hospital penetration:United States ambulatory surgical centers and secondary hospitals remain underpenetrated for therapeutic EUS, presenting volume expansion potential through leasing and service bundling models.
- EU Medical Device Regulation harmonization:MDR Article 120 transition timelines create temporary competitive windows for manufacturers with notified body relationships established ahead of 2027-2028 deadlines.
- Convergence of optical coherence tomography and ultrasound:Hybrid imaging platforms combining OCT mucosal detail with EUS depth penetration enable single-procedure comprehensive staging, commanding premium positioning.
Industry Challenges
- Specialized technician scarcity:Endoscope reprocessing and transducer calibration require certified biomedical engineering staff, with training programs lagging installed base expansion in high-volume markets.
- Legacy system integration friction:AI-enhanced processors must interface with hospital PACS infrastructure spanning multiple vendor generations, complicating deployment and support economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Definition Ultrasound Gastroscope Market |
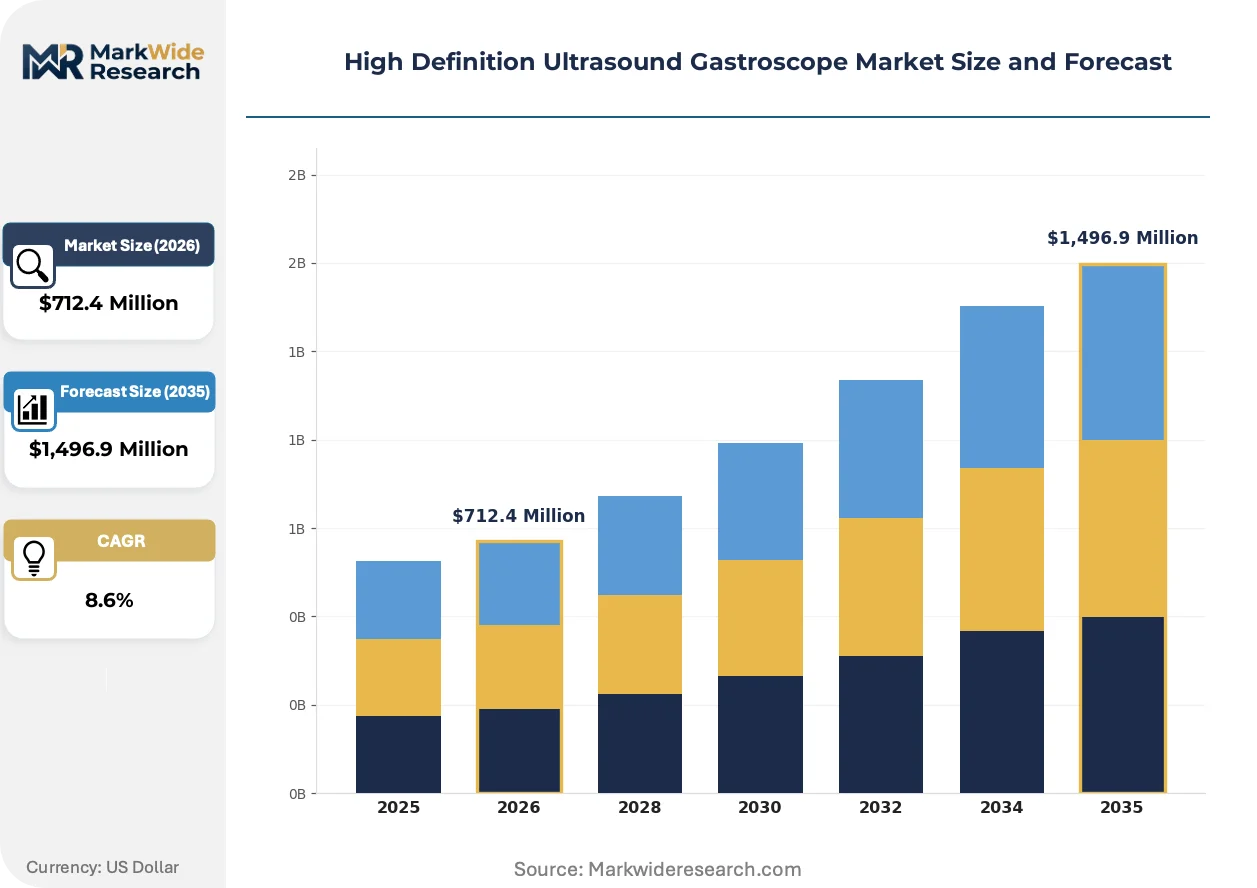
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,496.9 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Gastroscopy, Rigid Gastroscopy, Capsule Endoscopy, Ultrasonic Device End User: Hospitals, Diagnostic Centers, Research Laboratories, Outpatient Facilities Technology: Ultrasonic Imaging, Digital Imaging, Video Processing, AI Integration Application: Disease Diagnosis, Therapeutic Procedures, Biopsy, Surgical Interventions |
| Companies Covered | Olympus Corporation, Fujifilm Holdings Corporation, Boston Scientific Corporation, Medtronic, PENTAX Medical, CONMED Corporation, Stryker Corporation, Ethicon Endo-Surgery, KARL STORZ SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Definition Ultrasound Gastroscope Market Trends and Innovations
Real-time computational analysis is displacing interpretive dependence on operator experience, compressing the skill gradient between academic medical centers and community practice settings while creating new value capture opportunities for software-enabled hardware platforms.
Computer-assisted polyp detection algorithms embedded in video processing units are automating mucosal lesion identification during routine surveillance endoscopy. Gastroenterology departments at United States academic medical centers are deploying these modules at scale, with adoption curves steepening following 2023-2024 reimbursement clarifications. The technology is automating preliminary screening workflows and reallocating specialist attention toward therapeutic intervention decisions.
EMA Medical Device Regulation notified body capacity constraints are extending conformity assessment timelines for ultrasonic device platforms seeking CE marking. Manufacturers with established European Authorized Representative structures and quality management systems certified under ISO 13485:2016 are securing priority queue positioning. High-frequency probe categories with novel piezoelectric materials face the most pronounced delays as clinical evaluation requirements tighten.
Hospital procurement departments are consolidating endoscopic ultrasound program investments through multi-year managed equipment service agreements rather than capital purchase models. Original equipment manufacturers are responding with performance-guaranteed contracts bundling device, maintenance, and disposable supply commitments. This transition is most visible in United States integrated delivery networks where standardization across affiliated facilities reduces total cost of ownership negotiation complexity.
High Definition Ultrasound Gastroscope Market Segmentation
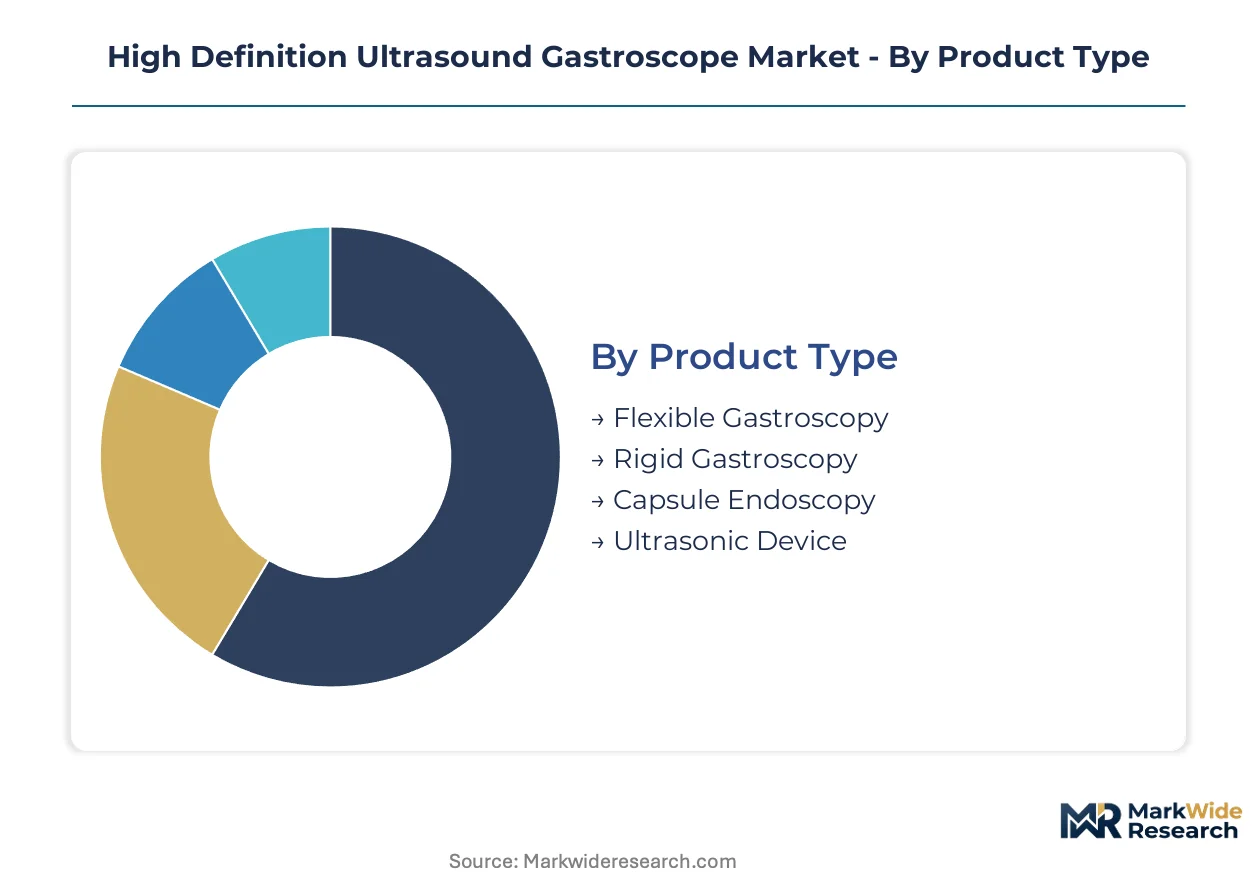
High definition ultrasound gastroscope procurement decisions split across device architecture, clinical setting, imaging modality, and procedural intent. Each segmentation axis carries distinct margin profiles and regulatory validation burdens that reshape vendor go-to-market economics.
Product Type:
Capital allocation cycles and procedural volume thresholds determine platform selection across healthcare systems.
- Flexible Gastroscopy:Articulating insertion tubes with 4-way angulation dominate installed bases due to versatility across diagnostic and therapeutic applications. Demand concentrates in tertiary hospitals across Germany, Japan, and the United States where integrated imaging suites justify capital investment.
- Ultrasonic Device:Integrated transducer-probe assemblies operating at 5-20 MHz enable real-time submucosal tissue characterization. Procurement concentrates in academic medical centers pursuing pancreatic oncology staging protocols where resectability assessment drives mandatory EUS adoption.
- Rigid Gastroscopy:Stainless steel shaft designs serve specialized therapeutic interventions requiring instrument stability. Adoption remains limited to surgical endoscopy suites.
- Capsule Endoscopy:Wireless ingestible platforms with ultrasonic transducer miniaturization remain experimental. Research laboratories evaluate prototypes for small bowel applications.
Volume sits with Flexible Gastroscopy; growth tilts toward Ultrasonic Device.
End User:
Reimbursement infrastructure and procedure complexity filter addressable demand across care delivery settings.
- Hospitals:Tertiary centers with dedicated gastroenterology departments command the deepest installed bases. North American and Western European institutions are expanding endoscopic ultrasound programs for pancreatic and biliary staging.
- Diagnostic Centers:Ambulatory facilities concentrate on routine surveillance endoscopy with AI-assisted polyp detection. United States ambulatory surgical centers represent underpenetrated expansion territory.
- Outpatient Facilities:Community-based clinics with limited reprocessing infrastructure favor leasing models over capital purchase.
- Research Laboratories:Academic institutions evaluate next-generation piezoelectric materials and hybrid imaging platforms prior to commercial translation.
Procurement value concentrates in Hospitals; addressable volume is expanding fastest in Diagnostic Centers.
Technology:
Intellectual property ownership and software validation timelines differentiate competitive positioning.
- AI Integration:Computer-assisted polyp detection and automated layer recognition algorithms compress operator training cycles. FDA software-as-a-medical-device guidance is accelerating regulatory clearance for embedded computer-vision modules.
- Ultrasonic Imaging:Phased array transducers with frequency-tuned ceramic substrates generate cross-sectional tissue maps. Miniaturization of 20 MHz arrays within 2.4 mm probes is expanding diagnostic resolution.
- Digital Imaging:CMOS sensor arrays and high-definition video chipsets enable mucosal surface visualization. Backward integration into video processing hardware protects margin pools.
- Video Processing:Dedicated processors for real-time image reconstruction require electromagnetic compatibility validation under IEC 60601-1-2 ed. 4.1 specifications.
Revenue contribution is deepest in Ultrasonic Imaging; capability investment is climbing fastest in AI Integration.
Application:
Clinical outcome requirements and reimbursement coding determine technology configuration and pricing tolerance.
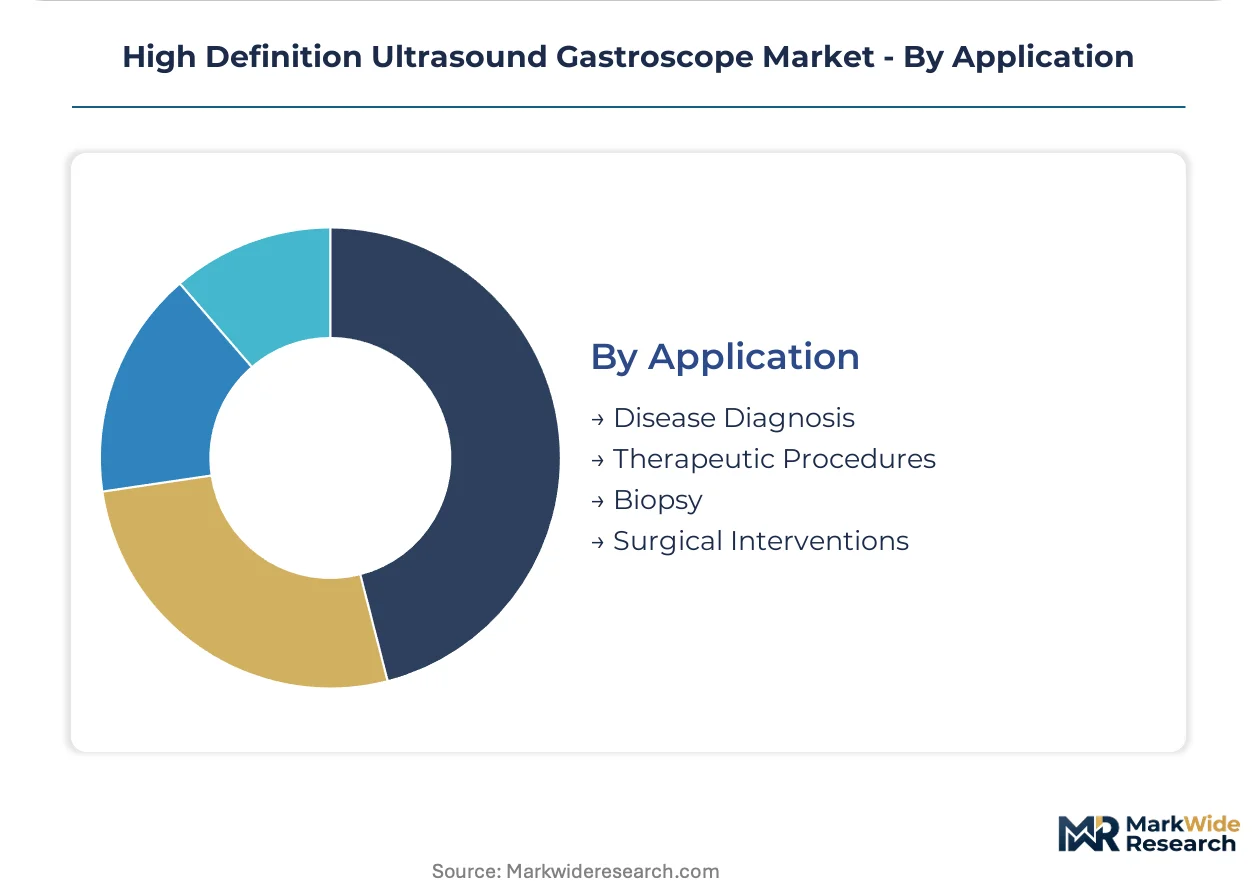
- Disease Diagnosis:Oncologic staging protocols for pancreatic, biliary, and gastrointestinal malignancies mandate EUS tissue characterization. National cancer institutes have elevated endoscopic ultrasound to mandatory resectability assessment.
- Therapeutic Procedures:Fine-needle aspiration and celiac plexus neurolysis require dedicated therapeutic delivery channels. Boston Scientific Corporation competes via specialized hospital system relationships.
- Biopsy:Tissue acquisition with real-time ultrasound guidance demands precision-machined instrument channels. Olympus Corporation leverages captive manufacturing for high-frequency probe compatibility.
- Surgical Interventions:Peroral endoscopic myotomy and submucosal dissection procedures require hybrid optical-ultrasonic platforms with advanced electrosurgical integration.
Procedure volume concentrates in Disease Diagnosis; reimbursement expansion is steepest for Therapeutic Procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tertiary hospitals in Germany, Japan, and the United States command the deepest installed bases for high definition ultrasound gastroscope systems, with national cancer institutes in these markets mandating endoscopic ultrasound for pancreatic oncology staging protocols.
United States
FDA premarket notification pathways for ultrasonic device platforms are compressing development timelines for manufacturers targeting integrated imaging suites. The agency's evolving software-as-a-medical-device guidance applies directly to AI-enabled image enhancement features embedded in next-generation processors. Academic medical centers in Boston and the Research Triangle are expanding endoscopic ultrasound programs for pancreatic and biliary staging.
Germany
EMA Medical Device Regulation conformity assessments govern acoustic output limits and biocompatibility requirements for patient-contacting materials in ultrasonic transducer arrays. ISO 13485 quality management standards constrain design validation cycles for manufacturers targeting multiple regulatory jurisdictions. Industrial clusters in Baden-Württemberg and Bavaria concentrate precision-machined bending section manufacturing for flexible gastroscopy platforms.
Japan
METI industrial policy supports ceramic transducer miniaturization through advanced piezoelectric material processing programs. PMDA regulatory frameworks align with international IEC 60601-1-2 ed. 4.1 collateral specifications for electromagnetic compatibility validation. Tokyo and Osaka metropolitan areas host captive ceramic foundry capacity protecting margin on high-frequency probes for integrated endoscope manufacturers.
United Kingdom
NHS England procurement frameworks are consolidating endoscopic ultrasound program investments through multi-year managed equipment service agreements. MHRA post-market surveillance requirements align with EU MDR transition timelines for notified body relationships. London and Manchester tertiary centers are deploying AI-assisted polyp detection modules at scale following 2023-2024 reimbursement clarifications.
India
CDSCO medical device registration pathways are streamlining for ultrasonic device platforms as domestic manufacturing expands under production-linked incentive schemes. BIS standards for electromagnetic compatibility are converging with IEC specifications for processor units. Hyderabad and Bengaluru research laboratories evaluate next-generation piezoelectric materials and hybrid imaging platforms prior to commercial translation.
High Definition Ultrasound Gastroscope Market Competitive Landscape
Backward integration into critical component supply dominates the current landscape for high definition ultrasound gastroscope manufacturing. The vendor base concentrates among diversified medical technology conglomerates with captive production capabilities across ceramic transducers, video processing chipsets, and precision-machined insertion tubes. Three strategic archetypes define positioning: integrated imaging suite providers, specialized therapeutic delivery channel operators, and component technology specialists. M&A activity and strategic partnerships represent the dominant competitive moves as manufacturers secure ceramic supply agreements and AI software licensing arrangements.
Among Japan-based medical technology conglomerates, Olympus Corporation and Fujifilm Holdings Corporation occupy positions anchored by captive manufacturing capabilities across the value chain. Olympus exemplifies the integrated imaging suite archetype through its ceramic foundry capacity for high-frequency probe production. Fujifilm represents backward integration into video processing hardware, protecting margin pools in digital imaging components. Boston Scientific Corporation, a United States-based diversified medical device company, sits within the specialized therapeutic delivery channel operator archetype, competing through hospital system relationships in North American markets.
| Leading Market Players |
|---|
| Olympus Corporation |
| Fujifilm Holdings Corporation |
| Boston Scientific Corporation |
| Medtronic |
| PENTAX Medical |
| CONMED Corporation |
| Stryker Corporation |
| Ethicon Endo-Surgery |
| KARL STORZ SE & Co. KG |
| Others |
Pricing and Supply Chain Analysis
High-purity lead zirconate titanate substrate pricing indices cascade through ultrasonic transducer manufacturing into three-tier equipment economics, with Japanese and German ceramic foundry premiums compressing margins for non-integrated endoscope assemblers.
Pricing Analysis
Volume concentrates in flexible gastroscopy platforms while margin pools sit with ultrasonic device hardware. Three-tier pricing structure across premium, standard, and economy levels differentiates by transducer frequency capability and AI module certification grade. Pricing pressure stems from hospital procurement consolidation into multi-year managed service agreements. Community hospitals and ambulatory surgical centers exhibit highest price sensitivity, while academic medical centers prioritize diagnostic resolution over acquisition cost.
Supply Chain Analysis
ISO 13485 certification and FDA quality system regulation gating constrain supplier qualification for patient-contacting transducer arrays. Ceramic substrate fabrication concentrates in Japan and Germany, with precision-machined bending sections sourcing from Baden-Württemberg industrial clusters. High-frequency probe assembly depends on captive piezoelectric material processing and miniaturized phased array fabrication. Single-source ceramic supply creates allocation vulnerability during foundry capacity constraints. Distribution runs through original equipment manufacturer direct sales and specialized therapeutic delivery channel operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EMA Medical Device Regulation notified body capacity constraints and FDA software-as-a-medical-device validation requirements erect barrier-to-entry moats favoring manufacturers with established quality management systems.
For Market Incumbents: Cement defensive positioning through backward integration into ceramic transducer supply and AI-enabled image enhancement software stacks. Threats emerge from specialized therapeutic delivery channel operators capturing hospital system relationships. Priority levers include captive foundry capacity expansion in Tokyo-Osaka corridors and ISO 13485:2016 certification maintenance for MDR Article 120 transition priority queuing. For New Entrants and Emerging Players: AI-assisted polyp detection algorithms offer technology-first wedge positioning against legacy video processing incumbents. White-space targets include United States ambulatory surgical centers and secondary hospitals with underpenetrated therapeutic EUS programs. Community hospital leasing models with service bundling represent the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor component technology specialists with novel piezoelectric material patents in German industrial clusters. Long-term viability over a multi-year horizon hinges on regulatory clearance velocity and ceramic supply security. Watch FDA software-as-a-medical-device guidance evolution as inflection indicator for AI-enabled platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Relationship Establishment | EMA MDR Article 120 transition timelines create temporary competitive windows for CE marking priority. |
| Ceramic Foundry Capacity Expansion | Captive lead zirconate titanate substrate production protects margin on 20 MHz high-frequency probe categories. |
| AI Software Companion Development | FDA software-as-a-medical-device guidance accelerates regulatory clearance for computer-vision embedded processors. |
| Hospital System Partnership | Multi-year managed equipment service agreements consolidate procurement across United States integrated delivery networks. |
| Hybrid Imaging Platform Launch | OCT-EUS convergence enables single-procedure comprehensive staging commanding premium positioning in academic centers. |
Research Methodology
Independent corroboration across primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists, combined with secondary validation through FDA 510(k) filings, EMA CE marking databases, hospital procurement records, and ISO 13485 certification registries, underwrites the qualitative findings. Bottom-up installed base modeling and top-down procedure volume estimates triangulate market sizing.
Comparable-period anchoring to historical EUS procedure volumes and capital equipment replacement cycles structures the projection horizon. Segmentation dimensions modeled include product architecture, clinical setting, imaging modality, and procedural intent. CAGRs derive from regression analysis against pancreatic oncology staging protocol adoption curves and ceramic transducer miniaturization trajectories. Forecast inputs incorporate reimbursement clarification timelines and AI module regulatory clearance velocity.
Several conditions sit outside the modeled scope, including unforeseen electromagnetic compatibility specification revisions and acute ceramic supply disruptions. Forecasts reflect assumptions about EMA notified body capacity normalization and FDA software guidance stability. A model refresh is warranted upon material change in MDR transition timeline enforcement or AI-enabled feature reimbursement coding.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Digestive Health Products Market
Gastroenterology
Fecal Incontinence Market
Gastroenterology
Gastroesophageal Junction Adenocarcinoma Therapeutics Market
Gastroenterology
Crohns Disease Therapeutics Market
Gastroenterology
US Inflammatory Bowel Disease Treatment Market
Gastroenterology
US Gastroenterology Ambulatory Surgery Center Market
Gastroenterology
Intestinal Pseudo-Obstruction Treatment Market
Gastroenterology
Chronic Liver Diseases Therapeutics Market
Gastroenterology
Intestinal Fistula Treatment Market
Gastroenterology
Duodenal Ulcer Treatment Market
Gastroenterology
Malabsorption Syndrome Treatment Market
Gastroenterology
Zollinger Ellison Syndrome Treatment Market
Gastroenterology
Disposable Intestinal Wash Bags Market
Gastroenterology
Inflammatory Bowel Disease Market
Gastroenterology
Biliary Tract Cancers (Btcs) Treatment Market
Gastroenterology
Polyps Market