
 Necrotic Enteritis Treatment Market | 2026-2036
Necrotic Enteritis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Necrotic Enteritis Treatment Market Foresight
The Veterinary Feed Directive is pivoting how pharmaceutical firms approach feed-additive formulations in the United States. Merck & Co. leverages its veterinary vaccine infrastructure to sustain research pipelines against clostridial pathogens. Kemin Industries anchors its position through specialized nutritional additives that reduce pathogen load in broiler gut environments. Bayer competes via integrated animal health portfolios spanning therapeutics and preventive care.
Necrotic enteritis treatment encompasses antimicrobial and non-antimicrobial interventions targeting Clostridium perfringens-induced intestinal necrosis in avian species, typically administered through feed or water systems at concentrations calibrated to bird weight and infection severity. The primary purpose centers on mortality reduction and feed conversion ratio preservation in intensive poultry production systems. Antibiotics and probiotics command the largest current revenue pools, though nutritional supplements represent the fastest-expanding category as producers seek growth-promoter alternatives. Oral delivery dominates volume due to feed-mixing economies, while injectable routes capture premium positioning for acute outbreak management in high-value breeding flocks.
The FDA enforces prescription requirements for medically important antibiotics in animal feed, while the EPA monitors environmental discharge from poultry operations using therapeutic agents. Brazil's national agricultural regulator and the EU's EMA veterinary medicines framework both intensify residue-testing protocols, reshaping export eligibility for treated flocks. Stakeholders must weigh antimicrobial restriction trajectories against the performance gap of alternative therapeutics when allocating development resources.
Market Dynamics
Antimicrobial stewardship programs are compressing the addressable market for conventional antibiotics while simultaneously expanding the competitive arena for non-antimicrobial alternatives in intensive poultry operations.
Growth Catalysts
- Brazil's integrated processing corridors:Consolidated broiler operations in São Paulo and Paraná states are standardizing preventive treatment protocols across captive feed mills, creating concentrated procurement volumes for therapeutic suppliers.
- REACH residue protocols:The EU's intensified monitoring of poultry imports is forcing export-oriented producers in Thailand and Vietnam to adopt veterinary-grade treatment documentation, expanding the premium product tier.
- Precision fermentation:Recombinant protein production methods are reducing unit costs for novel antimicrobial peptides, enabling cost-competitive substitution against legacy ionophores in starter rations.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for clostridial therapeutics clusters in eastern China, exposing formulators to logistics disruptions and import licensing volatility.
- Veterinary Feed Directive friction:The FDA's prescription requirements for medically important antibiotics in feed have extended procurement cycles by 14-21 days for US broiler operations, compressing emergency response windows.
- Probiotic efficacy variance:Strain-specific performance inconsistency in competitive exclusion products limits reliable feed conversion guarantees, constraining producer willingness to fully displace antibiotics.
Strategic Opportunities
- Vietnam's Mekong Delta expansion:Greenfield broiler complexes in Đồng Tháp and An Giang provinces lack established supplier relationships, creating first-mover positioning for integrated health solution providers.
- Water-soluble delivery innovation:Precision dosing systems for drinking water administration are capturing share from conventional feed mixing in Southeast Asian climate-stressed operations where heat reduces feed intake.
- EU Green Deal alignment:The Farm to Fork strategy's reduction targets for antimicrobial use are accelerating demand for gut health monitoring services bundled with nutritional interventions.
Industry Challenges
- Veterinary microbiology talent scarcity:Specialized expertise in avian necrotic enteritis pathology is concentrating within university research stations in the Netherlands and the United States, limiting field diagnostic capacity in emerging production regions.
- Multi-jurisdiction registration complexity:Divergent data requirements between the FDA, EMA, and ANVISA are extending product launch timelines and fragmenting development resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Necrotic Enteritis Treatment Market |
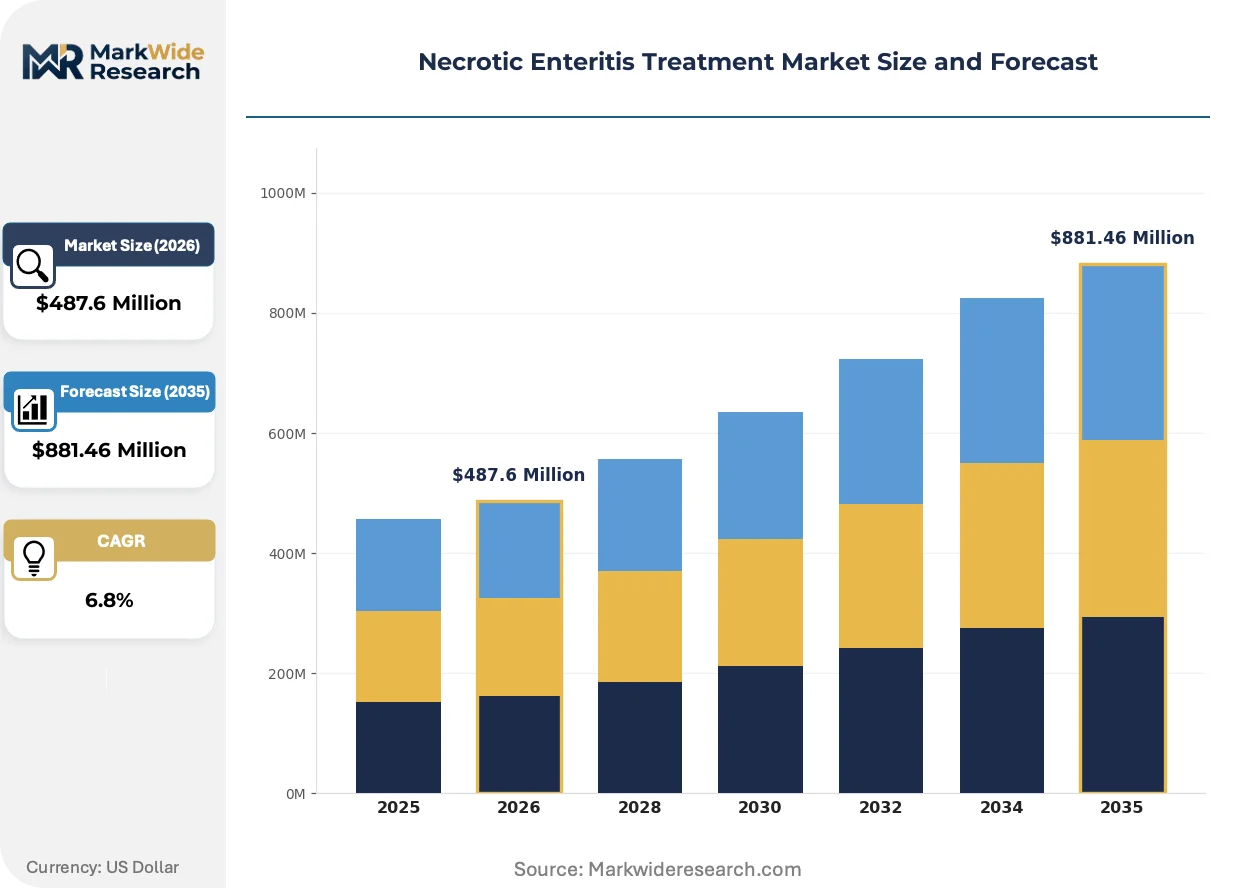
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Probiotics, Nutritional Supplements, Antiseptics Delivery Mode: Oral, Injectable, Topical, Intravenous End User: Veterinary Clinics, Hospitals, Research Institutions, Home Care Therapy Area: Animal Health, Poultry Care, Livestock Management, Equine Health |
| Companies Covered | Teva, Alcon, Prometic Life Sciences, Kemin Industries, GlaxoSmithKline, BioGaia Probiotics, Bayer, Merck & Co., Fresenius, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Necrotic Enteritis Treatment Market Shifts & Advancements
Biomarker-driven treatment protocols are displacing empirical dosing regimens across integrated poultry operations, while digital monitoring infrastructure enables real-time pathogen load tracking.
Phage therapy cocktails targeting Clostridium perfringens-specific virulence factors are integrating into research pipelines at major veterinary institutes, with commercial adoption concentrated in European antibiotic-restricted production zones. Dutch and Danish broiler cooperatives are piloting precision phage applications through automated drinking water systems, compressing the therapeutic response window from days to hours while reducing environmental antimicrobial discharge.
The EPA's expanded monitoring of poultry litter phosphorus content is forcing producers to recalibrate therapeutic dosing to minimize excreted residues, with downstream impacts on manure management economics. Operations in the Chesapeake Bay watershed face the strictest discharge limits, accelerating investment in water treatment infrastructure that captures unmetabolized therapeutic compounds before field application.
Consolidated buying cooperatives in Brazil's southern states are unbundling veterinary service contracts from feed supply agreements, creating standalone procurement channels for specialized necrotic enteritis interventions. This disintermediation is compressing distributor margins while rewarding suppliers with direct technical support capabilities and on-farm diagnostic infrastructure.
Necrotic Enteritis Treatment Market Segmentation
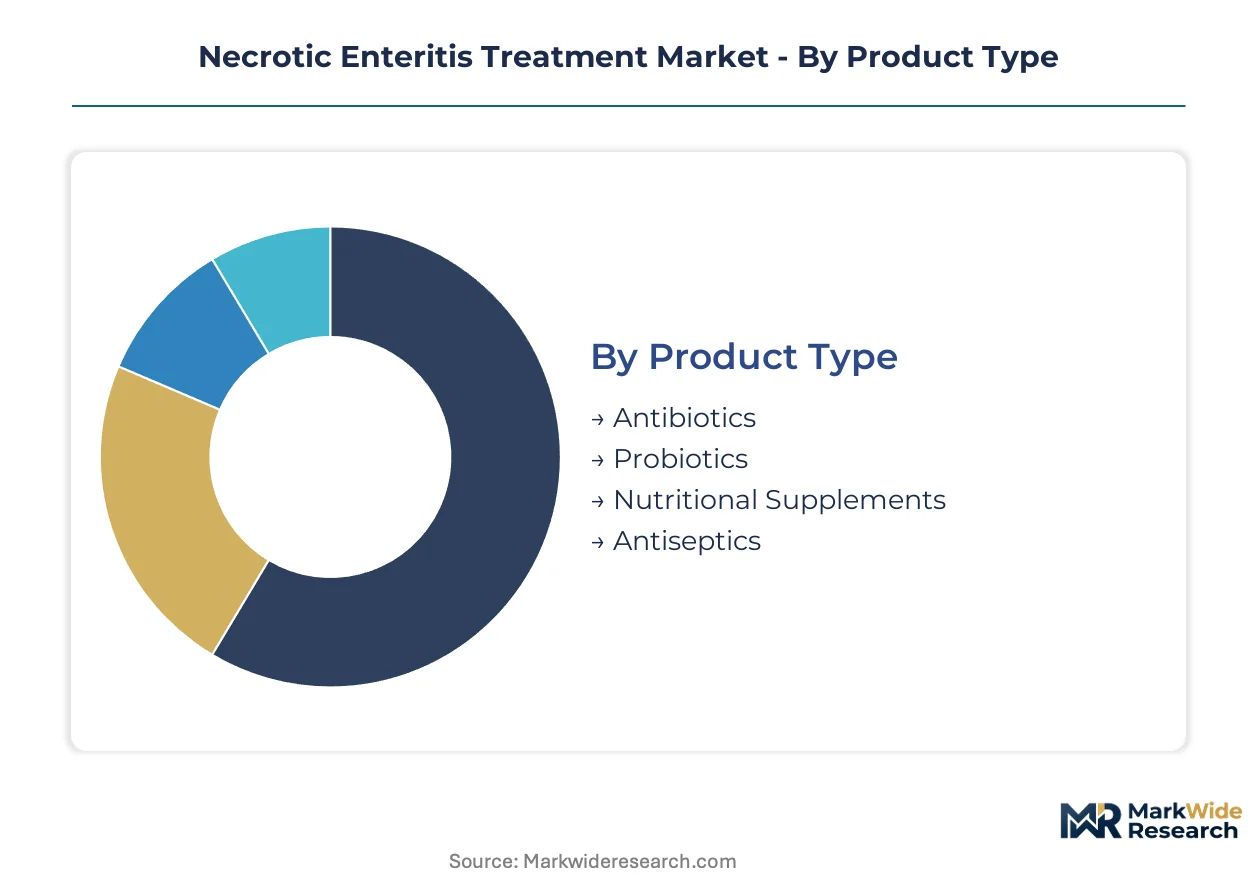
Product formulation and delivery pathway choices determine efficacy against Clostridium perfringens while navigating regulatory constraints on antimicrobial use. Segmentation reveals how producers balance mortality control with residue compliance and feed conversion economics.
Product Type:
Active ingredient chemistry defines regulatory classification and residue monitoring requirements across export-oriented poultry corridors.
- Antibiotics:Ionophores and therapeutic antimicrobials remain the clinical standard for acute outbreak suppression. Demand concentrates in Brazil's integrated processing complexes where veterinary prescription networks support rapid deployment against severe necrotic enteritis episodes.
- Probiotics:Competitive exclusion cultures and direct-fed microbials colonize gut epithelium to block pathogen attachment. Thailand's export-driven broiler operations are adopting multi-strain formulations to satisfy EU REACH documentation requirements for antibiotic-free product tiers.
- Nutritional Supplements:Enzyme-enhanced feed additives and organic acid blends modulate intestinal pH to suppress clostridial proliferation. Vietnam's Mekong Delta greenfield farms represent the steepest expansion trajectory for these non-antimicrobial interventions.
- Antiseptics:Gut-active biocides provide short-term pathogen suppression in water delivery systems. Limited adoption outside emergency protocols due to residue accumulation risks.
Mature deployment sits with Antibiotics. Newer deployment is concentrated in Nutritional Supplements.
Delivery Mode:
Administration route selection hinges on flock size, labor availability, and climate stress effects on feed intake patterns.
- Oral:Feed-mixed therapeutics leverage existing mill infrastructure for cost-efficient mass medication. São Paulo state operations standardize preventive inclusion rates across captive supply chains.
- Injectable:Precision dosing for high-value breeding stock and acute individual intervention. Paraná's grandparent flocks command premium positioning for parenteral antibiotic access.
- Topical:Limited relevance for enteric conditions; occasional use in combined infection protocols targeting external lesions.
- Intravenous:Reserved for critical care in research and elite genetic preservation settings.
Volume concentration follows Oral delivery. Margin capture concentrates in Injectable applications.
End User:
Procurement authority and technical capacity shape product specification and support service requirements.
- Veterinary Clinics:Diagnostic confirmation and prescription authority for medicated feeds. Đồng Tháp province operations rely on mobile veterinary services for necrotic enteritis confirmation.
- Hospitals:Specialized avian referral centers handling complex co-infections and antibiotic resistance profiling.
- Research Institutions:Efficacy trials and resistance surveillance for regulatory submission data packages. Dutch university stations concentrate expertise in clostridial pathogenesis.
- Home Care:Backyard and smallholder operations with limited diagnostic access; over-the-counter probiotic reliance.
Procurement scale concentrates with Veterinary Clinics. Technical sophistication concentrates in Research Institutions.
Therapy Area:
Species-specific pathogenesis and production economics dictate therapeutic investment thresholds.
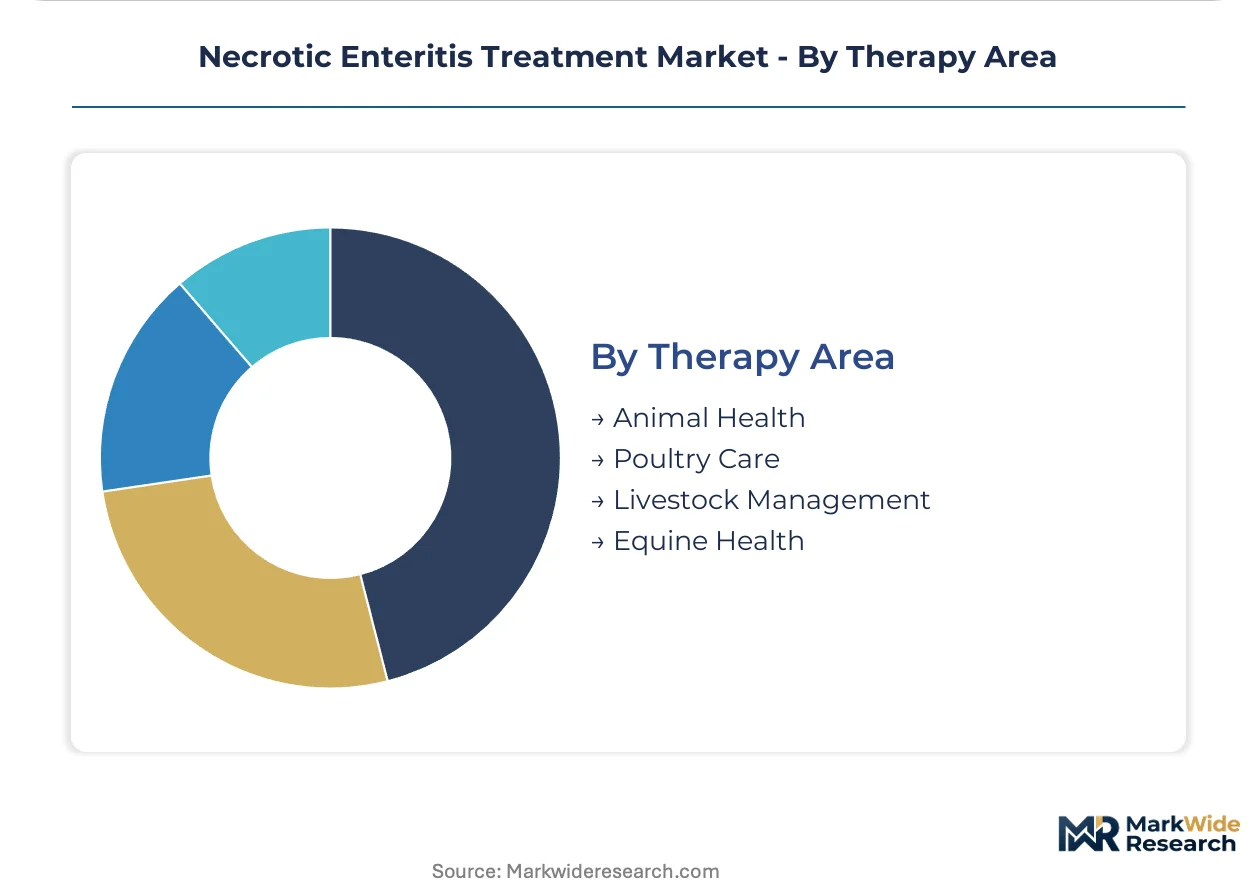
- Animal Health:Broad-spectrum veterinary applications spanning multiple livestock categories. Denmark's antibiotic-restricted production zones drive innovation in cross-species gut health protocols.
- Poultry Care:Intensive broiler and layer operations where necrotic enteritis inflicts the heaviest mortality and feed conversion penalties. Southeast Asian climate stress amplifies outbreak severity.
- Livestock Management:Ruminant and swine applications with distinct clostridial pathogen profiles; limited necrotic enteritis relevance.
- Equine Health:Minimal overlap; enteric clostridiosis in horses follows different therapeutic protocols.
Revenue concentration sits with Poultry Care. Diversification investment flows toward Animal Health.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Manaus Free Trade Zone incentives and Vietnam's Dinh Vu-Cat Hai Economic Zone concessions are concentrating pharmaceutical manufacturing for animal health. These zones attract formulators seeking proximity to broiler production clusters while navigating residue-testing protocols for export markets.
United States
The FDA's Veterinary Feed Directive prescription requirements extend procurement cycles for medicated feeds. Chesapeake Bay watershed operations face EPA phosphorus discharge limits that recalibrate therapeutic dosing. North Carolina's integrated poultry corridor anchors domestic demand for precision fermentation-derived antimicrobial peptides.
Brazil
ANVISA intensifies residue-testing protocols for EU-bound poultry exports. São Paulo state's consolidated processing complexes standardize preventive treatment protocols across captive feed mills. Paraná's grandparent breeding flocks command premium positioning for parenteral antibiotic access in acute outbreak management.
Vietnam
Đồng Tháp and An Giang provinces host greenfield broiler complexes lacking established supplier relationships. The country's national agricultural regulator aligns veterinary-grade documentation with EU REACH import standards. Mekong Delta operations adopt water-soluble delivery systems as heat stress reduces feed intake.
Netherlands
EMA veterinary medicines framework accelerates antibiotic reduction targets under EU Green Deal alignment. Dutch university research stations concentrate specialized expertise in clostridial pathogenesis. Wageningen-area cooperatives pilot precision phage applications through automated drinking water infrastructure.
Thailand
EU REACH documentation requirements drive adoption of multi-strain probiotic formulations in export-oriented operations. The national pharmaceutical regulator enforces veterinary prescription networks for medicated feeds. Chon Buri and Saraburi provinces anchor integrated processing corridors with standardized gut health monitoring services.
Necrotic Enteritis Treatment Market Competitive Landscape
North American pharmaceutical conglomerates anchor one tier; European nutritional specialists hold differentiated positions in non-antimicrobial alternatives. The vendor base stratifies across consolidated animal health divisions, dedicated feed additive formulators, and emerging precision fermentation operators. Three archetypes dominate: vertically integrated life science conglomerates, strain-specific probiotic developers, and recombinant protein technology licensors. Competitive moves concentrate on portfolio diversification into gut health monitoring services and backward integration into active pharmaceutical ingredient production.
Within the integrated life science tier, Merck & Co. and Bayer occupy positions exemplifying veterinary vaccine and therapeutic infrastructure deployment. Kemin Industries represents the specialized nutritional additive archetype, anchoring formulation expertise in competitive exclusion cultures and organic acid blends. These three entities collectively illustrate the competitive tension between antimicrobial stewardship compliance and performance-guaranteed alternative therapeutics.
| Leading Market Players |
|---|
| Teva |
| Alcon |
| Prometic Life Sciences |
| Kemin Industries |
| GlaxoSmithKline |
| BioGaia Probiotics |
| Bayer |
| Merck & Co. |
| Fresenius |
| Others |
Supply & Pricing Matrix
Precision fermentation methods for recombinant antimicrobial peptides are compressing production economics while redistributing manufacturing gravity toward biotechnology hubs with specialized fermentation infrastructure. This transition simultaneously erodes legacy ionophore pricing power and concentrates supply leverage among operators with captive bioprocessing capacity.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations as Brazil's integrated processors pay 15-25% markups for emergency antibiotic deployment against acute necrotic enteritis outbreaks. Three-tier pricing structure across veterinary-grade prescription, feed-grade preventive, and generic probiotic alternatives reflects certification tier and residue documentation completeness. Cost compression in probiotic formulations is intensifying because strain development amortization spreads across expanding Southeast Asian volumes. Smallholder operations in Vietnam's Mekong Delta exhibit highest price sensitivity; grandparent breeding flocks in Paraná state show least.
Supply Chain Analysis
Dual-sourcing requirements from EU export-oriented processors mandate qualified suppliers in both China and India for active pharmaceutical ingredients, insulating against single-country disruption. Clostridial therapeutic manufacturing draws from fermentation-derived bulk actives, specialized enteric coating materials, and precision dosing equipment. Tariff exposure on Chinese API imports threatens margin stability for US formulators. Distribution runs through captive feed mill networks in Brazil's southern states and veterinary distributor channels in Southeast Asian provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The necrotic enteritis treatment sector sits in a technology-transition phase where precision fermentation-derived antimicrobial peptides displace legacy ionophores in starter rations. This substitution pattern demands strategic repositioning across incumbent, entrant, and investor archetypes.
For Market Incumbents: To counter margin erosion from generic probiotic commoditization, Merck and Bayer should deepen backward integration into precision fermentation capacity in North Carolina's biotechnology corridor. ANVISA's intensified residue-testing protocols for EU-bound exports create certification investment leverage against regional competitors lacking veterinary-grade documentation infrastructure. For New Entrants and Emerging Players: Begin with water-soluble delivery system innovation targeting Vietnam's Đồng Tháp greenfield complexes where heat-stressed operations reduce feed intake and demand precision drinking water dosing. Technical service bundling with on-farm diagnostic infrastructure offers the most penetrable go-to-market angle against established feed-additive distributors. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated animal health conglomerates seeking gut health monitoring service capabilities. Long-term viability hinges on 5-10 year antimicrobial stewardship trajectory alignment. The signal to watch is EU Green Deal acceleration of Farm to Fork reduction targets, which would compress antibiotic addressable market faster than alternative therapeutic performance gaps close.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Recombinant antimicrobial peptide production in North Carolina biotechnology hubs reduces unit costs against legacy ionophores. |
| Veterinary-Grade Certification Investment | ANVISA-aligned residue documentation unlocks EU export eligibility for Brazil's integrated processing corridors. |
| Water-Soluble Delivery System Development | Precision dosing infrastructure captures share from feed-mixing in Southeast Asian climate-stressed operations. |
| Gut Health Monitoring Service Bundling | Real-time pathogen load tracking aligns with EU Green Deal antimicrobial reduction targets for Dutch cooperatives. |
| Dual-Source API Supplier Qualification | Parallel China-India manufacturing relationships insulate against import licensing volatility and logistics disruption. |
Research Methodology
Independent corroboration across veterinary pharmaceutical executives, feed mill procurement directors, and regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from FDA Veterinary Feed Directive filings, ANVISA residue-testing protocols, EU REACH import documentation, and SEC 10-K disclosures from listed animal health conglomerates. Bottom-up volume estimates from country-level broiler production data triangulate against top-down market sizing from therapeutic consumption patterns.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product chemistry, delivery mode, end-user procurement authority, and regional regulatory cluster. CAGRs derive from historical consumption trajectory analysis adjusted for antimicrobial policy inflection points. Forecast inputs incorporate broiler flock expansion rates in Vietnam's Mekong Delta and precision fermentation capacity buildout timelines in North Carolina.
Underlying measurement precision varies by segment; antibiotic volume data carries tighter precision than emerging probiotic efficacy variance. Forecasts reflect assumptions about EU Green Deal implementation pace and FDA prescription requirement enforcement consistency. Deviation in ANVISA-EU regulatory alignment would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Chronic Liver Diseases Therapeutics Market
Gastroenterology
Hirschsprung Disease Treatment Market
Gastroenterology
Gallstone Market
Gastroenterology
Diverticular Disease Therapeutics Market
Gastroenterology
US Inflammatory Bowel Disease Treatment Market
Gastroenterology
Malignant Ascites Market
Gastroenterology
High Definition Ultrasound Gastroscope Market
Gastroenterology
Colon Hydrotherapy Market
Gastroenterology
Zollinger Ellison Syndrome Treatment Market
Gastroenterology
Intestinal Fistula Treatment Market
Gastroenterology
Crohns Disease Therapeutics Market
Gastroenterology
Anal Fissure Treatment Market
Gastroenterology
Inflammatory Bowel Disease Market
Gastroenterology
Acute Pancreatitis Market
Gastroenterology
Gastritis Treatment Market
Gastroenterology
Intestinal Pseudo-Obstruction Treatment Market