
 Colon Hydrotherapy Market | 2026-2036
Colon Hydrotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Colon Hydrotherapy Market Outlook
The EU Medical Device Regulation is decoupling low-quality imports from compliant supply channels across European wellness markets. Herrmann Apparatebau GmbH anchors German engineering standards in closed-system manufacturing. Prime Pacific Health Innovations Corporation competes through North American distribution density. Cerajivan Healthtech leverages cost-optimized portable units for emerging clinic networks.
Colon hydrotherapy delivers temperature-controlled, filtered water infusion into the large intestine to facilitate waste elimination, with closed systems maintaining pressure parameters between 0.2 and 2.0 psi for patient safety. The equipment serves detoxification protocols, constipation management, and preoperative bowel preparation across clinical and wellness settings. Closed systems dominate installed base value given their therapeutic control and higher per-session pricing, while portable systems capture fastest unit growth as home care segments expand. Advanced filtration technology concentrates margin pools through consumable attachment revenue and certification premium capture.
FDA device classification for colonic irrigation equipment shapes United States market access through 510(k) clearance requirements, while the EU MDR imposes clinical evidence thresholds on manufacturers seeking CE marking. Germany's KBA-equivalent medical device oversight through BfArM adds national-layer compliance complexity for imported systems. Stakeholders must monitor evolving home-use regulatory boundaries as wellness-to-medical positioning shifts determine addressable market scope and reimbursement eligibility.
Market Dynamics
The EU Medical Device Regulation's clinical evidence requirements are restructuring competitive access across European wellness markets, forcing manufacturers to choose between premium certification investment and market exit. This regulatory compression concentrates value capture among engineering-intensive closed-system producers while accelerating portable segment fragmentation.
Growth Catalysts
- Integrative medicine normalization:United States wellness clinics embed colonic irrigation within broader detoxification protocols, expanding addressable patient touchpoints beyond standalone hydrotherapy centers.
- EU MDR compliance differentiation:Tightened CE marking thresholds filter low-quality imports, creating margin expansion for certified manufacturers serving German wellness centers.
- Home care portability demand:Lightweight closed-system variants enable clinic-to-consumer service extension, capturing patients seeking privacy and schedule flexibility.
Market Restraints
- Stainless steel and medical-grade polymer input volatility:Raw material cost swings compress margins for equipment fabricators lacking long-term supply contracts.
- German engineering concentration:Closed-system manufacturing gravity in Baden-Württemberg and Bavaria creates geographic supply risk and extended lead times for non-European buyers.
- Reimbursement exclusion:Most national health systems classify colonic irrigation as elective wellness, limiting patient access to out-of-pocket payment capacity.
Strategic Opportunities
- Preoperative bowel preparation expansion:Surgical centers in France and Italy evaluate hydrotherapy protocols as alternatives to chemical laxatives for colonoscopy preparation.
- Consumable filtration attachment revenue:Multi-stage carbon and UV filter replacement cycles generate recurring income streams independent of equipment sales cycles.
- India wellness tourism integration:Ayurveda and naturopathy retreat centers in Kerala and Karnataka adopt closed-system hydrotherapy as complementary detoxification modalities.
Industry Challenges
- CE marking clinical evidence compilation:Small and mid-size manufacturers face documentation burdens and notified body queue delays stretching eighteen to thirty-six months.
- Cross-trained technician scarcity:Wellness centers struggle to recruit personnel certified in both device operation and patient contraindication assessment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colon Hydrotherapy Market |
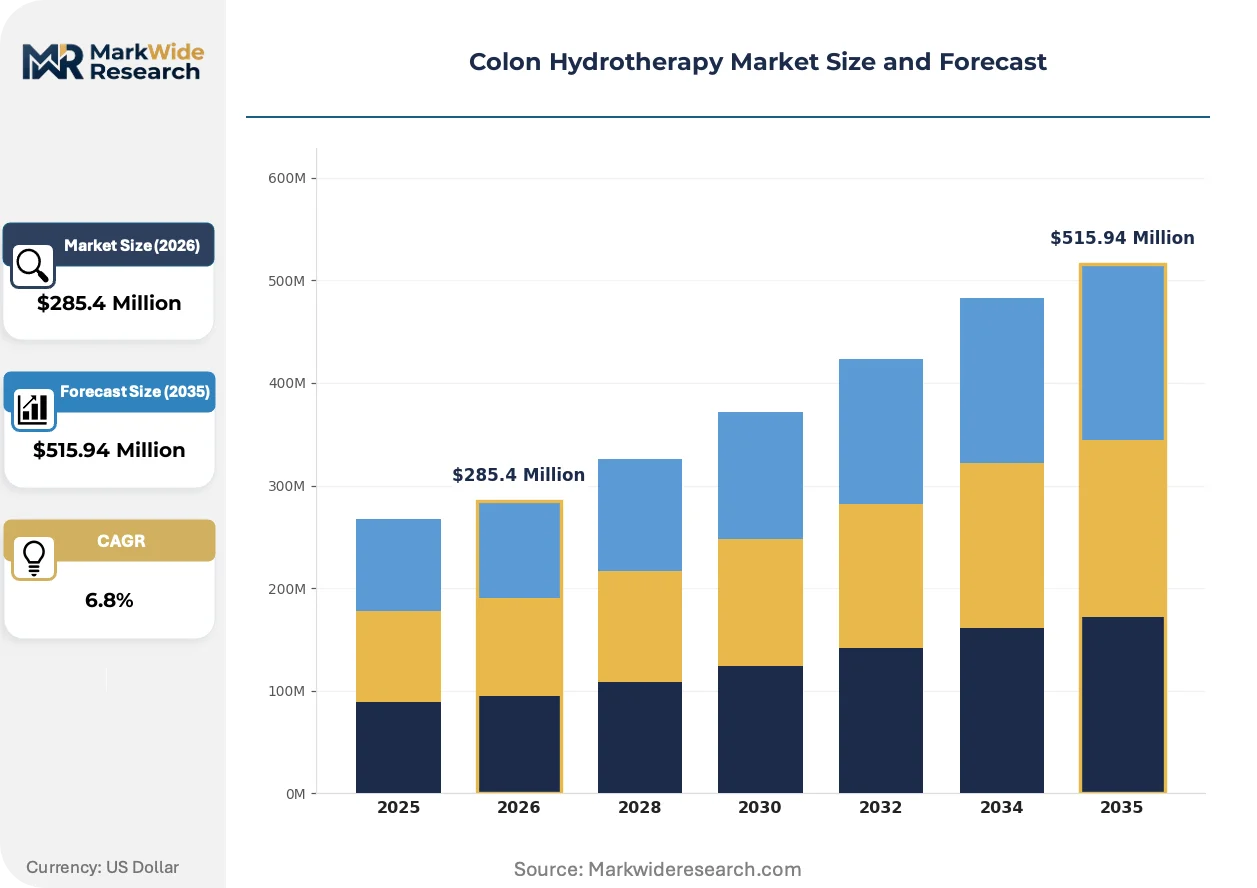
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open System, Closed System, Portable System, Stationary System End User: Clinics, Wellness Centers, Home Care, Spa Facilities Technology: Manual, Automated, Hybrid, Advanced Filtration Application: Detoxification, Constipation Relief, Preventive Care, Postoperative Care |
| Companies Covered | Cerajivan Healthtech, Beijing Fogool Science & Technology Co. Ltd, Prime Pacific Health Innovations Corporation, iCLear Limited, Zhengzhou Gold Elite Industry Co. Ltd, Herrmann Apparatebau GmbH, Acea Medica Ltd, Dotolo Research Corporation, TRANSCOM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colon Hydrotherapy Market Strategic Shifts
Equipment intelligence and regulatory digitization are compressing the gap between wellness positioning and clinical-grade accountability. Manufacturers now compete on traceability infrastructure as much as therapeutic efficacy.
Closed-system pressure modulation with real-time digital feedback is overtaking analog gauge monitoring in premium installations. Integrative medicine clinics in California and New York adopt sensor-integrated units that log session parameters for patient records. This capability is compressing liability exposure while enabling outcome documentation that supports wellness-to-medical positioning shifts.
The EU MDR's unique device identification and post-market surveillance requirements are restructuring documentation obligations for CE-marked equipment. Manufacturers must maintain clinical evidence registries and systematic literature reviews throughout product lifecycles. German and French importers now demand supplier EUDAMED database registration as a procurement prerequisite, filtering non-compliant sources from distribution channels.
Subscription-based equipment access is displacing outright purchase in North American clinic networks. Wellness center operators in Texas and Florida lease closed-system units with bundled maintenance and filter replenishment, converting capex to opex while securing technology refresh guarantees. This model concentrates vendor risk in utilization forecasting and remote diagnostics capability.
Colon Hydrotherapy Market Segmentation
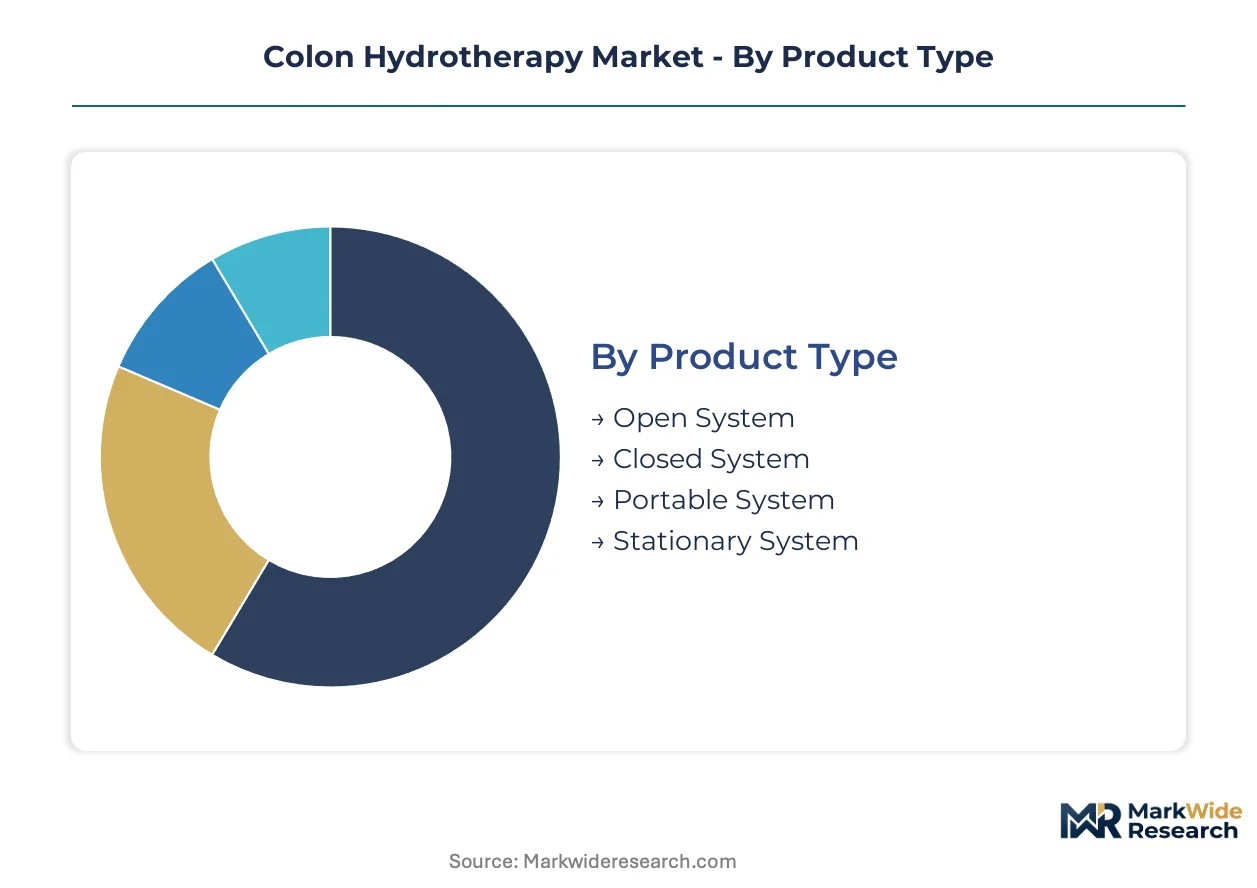
Segmentation in colon hydrotherapy equipment separates premium clinical-grade systems from wellness-accessible alternatives. Manufacturers configure pressure controls, filtration stages, and mobility features to match specific end-use safety requirements and reimbursement constraints.
Product Type:
Customization intensity spans from fully configurable closed systems to standardized portable units, with engineering depth determining margin capture across the spectrum.
- Closed System:Pressure-regulated architecture maintains 0.2-2.0 psi parameters through automated feedback loops. German wellness centers specify these for liability-sensitive installations where session documentation supports medical positioning. FDA 510(k) clearance requirements concentrate demand among US integrative medicine clinics seeking reimbursement-adjacent credibility.
- Portable System:Lightweight variants under 15 kg enable clinic-to-consumer service extension. Home care demand in Florida and Texas accelerates fastest as privacy preferences reshape patient touchpoints. Subscription leasing models convert capital expenditure to operational outlay for wellness networks.
- Open System:Gravity-fed designs without active pressure management serve budget-conscious spa operators. Kerala Ayurveda retreat centers adopt these for complementary detoxification protocols where therapeutic claims remain limited.
- Stationary System:Fixed-installation units with integrated water treatment infrastructure dominate hospital-adjacent surgical centers. French preoperative bowel preparation trials specify these for colonoscopy protocol standardization.
Leading the category by volume: Closed System. Growing fastest: Portable System.
End User:
Procurement sophistication escalates from individual home purchasers to institutional procurement committees, with compliance documentation requirements scaling accordingly.
- Clinics:Integrative medicine networks in California and New York demand sensor-integrated units with session logging capabilities. Outcome documentation supports wellness-to-medical positioning shifts that expand addressable patient bases beyond elective payers.
- Wellness Centers:EU MDR compliance filters supplier pools as German operators require EUDAMED-registered equipment. Margin pressure from certification costs concentrates procurement among multi-site chains with volume leverage.
- Home Care:Privacy-driven demand segments concentrate in North American suburbs where schedule flexibility outweighs clinical supervision preferences. Lightweight closed-system variants capture this expansion.
- Spa Facilities:Aesthetic positioning limits technical specification intensity. Open systems dominate where regulatory scrutiny remains minimal and session pricing competes with massage and thermal therapies.
Revenue concentration: Clinics. Steepest expansion trajectory: Home Care.
Technology:
Automation depth determines operator skill requirements and liability exposure, with filtration sophistication generating recurring consumable revenue independent of hardware cycles.
- Advanced Filtration:Multi-stage carbon, UV, and reverse osmosis configurations generate attachment revenue through 6-12 month replacement cycles. German engineering standards specify these for CE-marked equipment serving medical-adjacent applications.
- Automated:Digital pressure modulation with real-time feedback compresses technician training burdens. US clinic networks standardize on these to reduce cross-trained staff scarcity constraints.
- Hybrid:Manual override capabilities on automated platforms serve mixed-use facilities transitioning between wellness and clinical positioning. Italian surgical centers evaluate these for preoperative protocol flexibility.
- Manual:Analog gauge monitoring persists in price-sensitive emerging markets. Operator skill dependency limits expansion where technician certification infrastructure remains underdeveloped.
Widest installed base: Automated. Gaining share fastest: Advanced Filtration.
Application:
Therapeutic claim intensity shapes regulatory scrutiny and reimbursement eligibility, with medical positioning commanding premium pricing against wellness-classified alternatives.
- Detoxification:Wellness-center protocols in Texas and Florida embed colonic irrigation within broader cleansing regimens. Out-of-pocket payment dependency limits addressable market to discretionary income segments.
- Constipation Relief:Clinical positioning targets gastroenterology referral networks where symptom documentation supports medical necessity claims. US integrative medicine clinics capture these patient flows.
- Preventive Care:Screening-adjacent positioning in French and Italian markets explores hydrotherapy as colonoscopy preparation alternative. Regulatory classification uncertainty constrains rapid expansion.
- Postoperative Care:Surgical center protocols in Bavaria evaluate closed-system hydrotherapy for bowel function restoration. Reimbursement coding alignment determines commercial viability.
Dominant revenue source: Detoxification. Climbing the fastest: Preventive Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's precision engineering corridor anchors European closed-system manufacturing, with Stuttgart-Tübingen clusters supplying CE-marked equipment to wellness networks across the continent.
United States
California and New York integrative medicine clinics embed colonic irrigation within detoxification protocols, expanding patient touchpoints beyond standalone centers. FDA 510(k) clearance requirements filter market access, concentrating procurement among certified manufacturers. Austin and Miami wellness networks drive home-care portable demand through subscription leasing models.
Germany
BfArM oversight adds national-layer compliance complexity atop EU MDR requirements, extending certification timelines for imported systems. Stuttgart-based engineering clusters dominate closed-system fabrication, setting pressure-control benchmarks of 0.2-2.0 psi. Berlin and Munich wellness chains now mandate EUDAMED-registered suppliers, filtering low-quality imports from distribution channels.
France
Surgical centers in Lyon and Marseille evaluate hydrotherapy protocols as colonoscopy preparation alternatives to chemical laxatives. ANSM medical device vigilance requirements shape importer procurement criteria, favoring traceability-integrated equipment. The Île-de-France region concentrates wellness center expansion as Parisian clinics medicalize service positioning.
India
Kerala and Karnataka Ayurveda retreat centers adopt closed-system hydrotherapy as complementary detoxification modalities within wellness tourism packages. CDSCO medical device rules impose import registration requirements on foreign manufacturers. Bangalore clinic networks source cost-optimized portable units for emerging urban wellness chains.
Italy
Preoperative bowel preparation trials in Milan and Rome surgical centers explore hydrotherapy for colonoscopy protocol standardization. Ministry of Health device classification uncertainty constrains rapid reimbursement expansion. Northern Italian wellness clusters concentrate demand for hybrid automated-manual systems serving mixed-use facilities.
Colon Hydrotherapy Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and engineering intensity, with CE-marked closed-system fabricators capturing value pools that open-system assemblers cannot access. The vendor base organizes into three tiers: German engineering-intensive specialists, North American distribution-heavy networks, and Asian cost-optimized portable producers. Strategic moves concentrate on regulatory compliance pre-emption and subscription-based equipment access models that convert capital expenditure to recurring revenue.
Among German GmbH-structured engineering houses, Herrmann Apparatebau GmbH exemplifies the premium-tier archetype through Baden-Württemberg manufacturing concentration. Prime Pacific Health Innovations Corporation occupies the North American distribution-density position, while Cerajivan Healthtech represents the portable-system cost optimization vector for emerging clinic networks. These three anchors illustrate how geographic origin and corporate structure map to competitive positioning without requiring specific product or financial disclosures.
| Leading Market Players |
|---|
| Cerajivan Healthtech |
| Beijing Fogool Science & Technology Co. Ltd |
| Prime Pacific Health Innovations Corporation |
| iCLear Limited |
| Zhengzhou Gold Elite Industry Co. Ltd |
| Herrmann Apparatebau GmbH |
| Acea Medica Ltd |
| Dotolo Research Corporation |
| TRANSCOM |
| Others |
Value Chain & Pricing Dynamics
Stainless steel and medical-grade polymer input costs cascade through three-tier pricing structures separating CE-marked closed systems from open-system spa alternatives, with German engineering premiums reflecting Baden-Württemberg fabrication concentration and extended lead times for non-European buyers.
Pricing Analysis
Throughput-linked session economics anchor value-based pricing for closed-system installations, with sensor-integrated units commanding premiums against analog-monitoring alternatives. Certification tier—FDA 510(k) versus CE marking under EU MDR—drives price differentiation alongside after-sales filter replenishment bundling. Cost compression in portable segments intensifies as Asian manufacturers scale cost-optimized units for home care demand. Wellness center chains exhibit lowest price sensitivity given liability documentation requirements, while individual spa operators remain most elastic.
Supply Chain Analysis
Direct-to-clinic channels handle institutional procurement for integrative medicine networks, while distributor-mediated flows serve fragmented wellness center demand. Manufacturing concentrates in Germany, China, and the United States, with Baden-Württemberg engineering clusters supplying precision pressure-control components. Supply chains draw from stainless steel mills, medical-grade polymer extruders, and multi-stage filtration membrane producers. Single-source vulnerability concentrates in German precision valve and sensor suppliers. Distribution runs through medical device importers with EUDAMED registration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR notified body queue delays stretching eighteen to thirty-six months constrain certified equipment availability, propping pricing power for compliant manufacturers.
For Market Incumbents: Deploy subscription-based equipment access models to convert capital expenditure to recurring revenue streams, locking wellness center operators into multi-year filter replenishment cycles. Deepen backward integration into stainless steel component fabrication to buffer raw material volatility. Fortify against portable-system entrants by accelerating EUDAMED database registration as a procurement prerequisite for German distribution partners. For New Entrants and Emerging Players: Capture home care privacy demand in North American suburbs through lightweight closed-system variants under 15 kg, bypassing clinical supervision requirements. Target Kerala and Karnataka Ayurveda retreat centers in India where wellness tourism integration remains underpenetrated by CE-marked suppliers. Lead with subscription leasing propositions that convert capex to opex for emerging clinic networks lacking capital deployment capacity. For Investors and Strategic Acquirers: FDA 510(k) clearance receipt is the leading indicator that wellness-to-medical positioning shifts are gaining regulatory traction, expanding reimbursement-adjacent addressable markets. Prioritize acquisition targets with established notified body relationships and clinical evidence registries compliant with EU MDR post-market surveillance requirements. Monitor preoperative bowel preparation trial outcomes in French and Italian surgical centers as inflection signals for medical classification expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EUDAMED registration filters low-quality imports from German wellness center procurement. |
| Hospital System Partnership | French surgical center trials for colonoscopy preparation expand medical positioning credibility. |
| Software Companion Development | Sensor-integrated session logging compresses liability exposure for California integrative clinics. |
| Reimbursement Strategy | Constipation relief documentation targets gastroenterology referral network capture. |
| Backward Integration | In-house stainless steel component production buffers against polymer input volatility. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving biomedical engineers, wellness center operators, hospital purchasing committee members, and medical device distribution specialists. FDA 510(k) clearance databases, EU MDR EUDAMED registrations, BfArM device vigilance reports, and import-export customs declarations supplied validation benchmarks. Bottom-up equipment shipment tracking and top-down wellness service revenue estimation were reconciled through iterative triangulation.
Data-stream reconciliation across shipment volumes, installed base estimates, and session pricing surveys generated consistent growth trajectories across the projection horizon. Segmentation dimensions modeled include product architecture, end-user procurement sophistication, automation depth, and therapeutic claim intensity. CAGRs were derived from curve-fitting procedures applied to historical certification timelines and expansion patterns. Filter replacement cycle frequencies and subscription lease penetration rates served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR enforcement consistency, notified body capacity constraints, and home-use regulatory boundary shifts. Forecasts reflect assumptions regarding certification timeline stability and wellness-to-medical positioning traction. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Gastric Cancer Market
Gastroenterology
Gastrointestinal Drugs Market
Gastroenterology
Fecal Incontinence Market
Gastroenterology
Digestive Health Market
Gastroenterology
Duodenal Ulcer Treatment Market
Gastroenterology
Global Gastrointestinal Stent Market
Gastroenterology
Ultrasound Gastroscopes Market
Gastroenterology
Gastritis Treatment Market
Gastroenterology
Diverticular Disease Therapeutics Market
Gastroenterology
Digestive Health Products Market
Gastroenterology
Acute Pancreatitis Market
Gastroenterology
Peptic Ulcer Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market
Gastroenterology
Gastroesophageal Reflux Disease Therapeutics Market
Gastroenterology
Malignant Ascites Market
Gastroenterology
Gastroesophageal Junction Adenocarcinoma Therapeutics Market