
 Diabetes Diagnostics Market | 2026-2036
Diabetes Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetes Diagnostics Market Analysis
Home care patients are bifurcating from hospital-dependent testing as reimbursement shifts toward outpatient chronic disease management. Abbott Laboratories leverages integrated sensor-to-reader ecosystems that sustain recurring test strip revenue. Roche Diagnostics anchors European laboratory diagnostics with centralized analyzer platforms that dominate hospital purchasing committees.
Diabetes diagnostics encompasses devices, reagents, and systems that quantify blood glucose, glycated hemoglobin, or ketone levels through enzymatic, electrochemical, or optical detection methods, primarily enabling therapeutic adjustment and complication prevention. Continuous glucose monitors command premium positioning as real-time data streams replace episodic fingerstick workflows. Blood glucose meters retain volume leadership in emerging markets where cost sensitivity shapes procurement decisions. A1C test kits capture margin pools through laboratory-automated high-throughput processing.
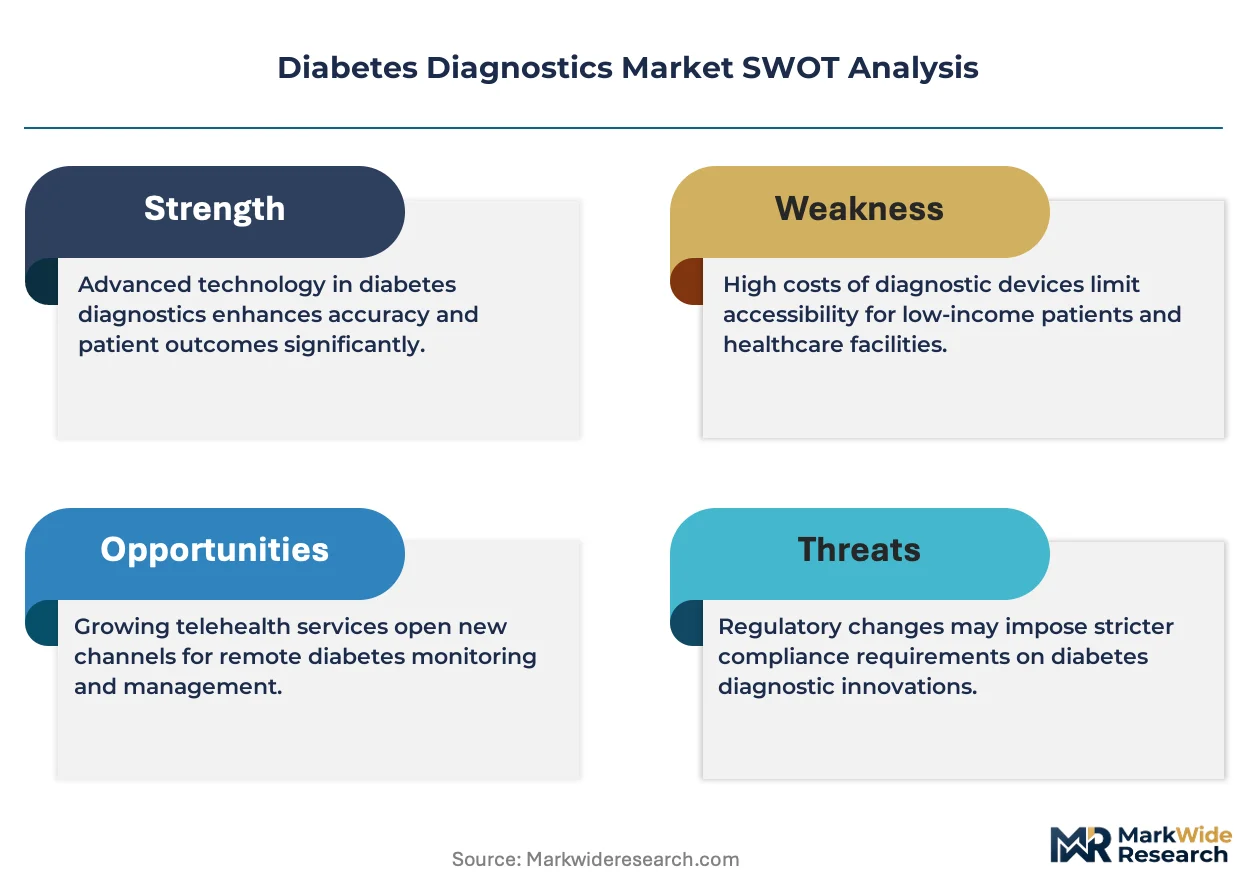
FDA premarket review under 21 CFR Part 862 and EMA IVDR classification shape device accuracy thresholds and clinical validation requirements that determine market access timelines. The EU AI Act introduces algorithmic transparency mandates for software-integrated glucose prediction tools. Stakeholders must monitor evolving payer evidence requirements for continuous monitoring reimbursement expansion beyond insulin-intensive populations.
Market Dynamics
Continuous glucose monitoring is fragmenting the traditional episodic testing paradigm as real-time data streams displace fingerstick workflows across outpatient settings. Reimbursement frameworks in the United States and Germany now favor remote patient monitoring, accelerating capital reallocation toward integrated sensor ecosystems.
Growth Catalysts
- CMS Remote Patient Monitoring Codes:United States reimbursement expansion for continuous glucose data transmission creates sustainable revenue streams for device manufacturers serving Medicare populations.
- Enzymatic Biosensor Miniaturization:Electrochemical detection architectures now enable subcutaneous implantable sensors with extended wear durations, reducing patient burden in home care settings.
- China Chronic Disease Management Initiative:National health commission directives mandate diabetes screening coverage expansion, driving procurement volume for point-of-care A1C analyzers in tier-two hospital networks.
Market Restraints
- Platinum Group Metal Input Volatility:Electrochemical sensor electrodes depend on ruthenium and palladium coatings, exposing manufacturers to commodity price swings from South African and Russian supply corridors.
- FDA 510(k) Clinical Validation Burden:Non-invasive optical glucose sensors face extended premarket timelines due to predicate device scarcity and accuracy threshold stringency under 21 CFR Part 862.
- Test Strip Commoditization:Third-party generic strip manufacturers capture pharmacy shelf space, compressing margins for branded meter ecosystems in price-sensitive emerging markets.
Strategic Opportunities
- India Tier-3 City Penetration:Underdiagnosed diabetic populations in smaller urban centers present whitespace for affordable smartphone-connected glucometer distribution through pharmacy chain partnerships.
- EU AI Act Algorithmic Transparency:Predictive glucose forecasting software integrated with continuous monitors gains competitive differentiation through compliant machine-learning documentation.
- Closed-Loop Insulin Pump Convergence:Sensor-augmented pump systems that automate insulin delivery represent the next integration frontier, requiring partnerships between glucose monitor and infusion device specialists.
Industry Challenges
- Biocompatibility Engineering Talent Scarcity:Polymer scientists capable of optimizing hydrogel membranes for 14-day wear durations command premium compensation, constraining R&D team scaling.
- IVDR Technical Documentation Complexity:European Union In Vitro Diagnostic Regulation classification shifts for software-integrated devices demand expanded clinical evidence packages, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetes Diagnostics Market |
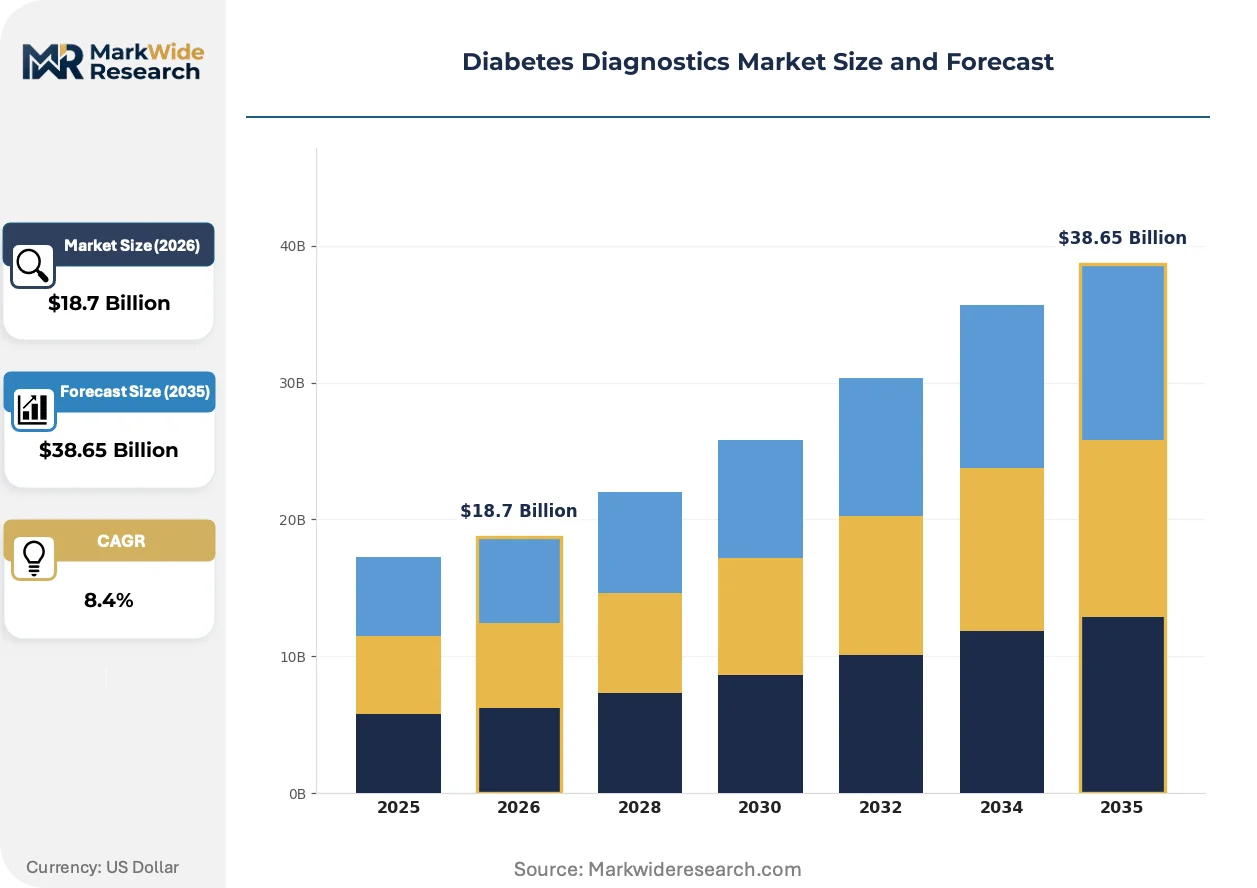
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Meters, Continuous Glucose Monitors, Test Strips, A1C Test Kits End User: Hospitals, Diabetes Clinics, Home Care, Research Laboratories Technology: Enzymatic, Electrochemical, Optical, Meter-based Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, Siemens Healthineers, Becton, Dickinson and Company, Dexcom, Medtronic, Johnson & Johnson, Novo Nordisk, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetes Diagnostics Market Emerging Trajectories
Non-invasive sensing modalities and artificial intelligence integration are redefining accuracy benchmarks and patient adherence models. Hardware-software convergence creates new competitive moats while regulatory clarity around algorithmic decision-support tools accelerates product pipeline maturation.
Optical glucose sensing through near-infrared spectroscopy and Raman scattering is fragmenting the invasive testing monopoly. Research consortia in Germany and Japan pilot wrist-worn prototypes for pre-diabetic populations seeking lifestyle feedback without skin penetration. These platforms compress the addressable market for conventional lancet-based meters among wellness-conscious consumers.
EMA IVDR post-market surveillance requirements now mandate systematic vigilance reporting for software-integrated glucose prediction tools. Device manufacturers must maintain algorithm version control and performance drift documentation across distributed sensor fleets. Continuous monitor vendors with European Union market authorization are restructuring quality management systems to accommodate real-world evidence collection.
Pharmacy benefit managers in the United States are unbundling device procurement from test strip replenishment contracts. Self-insured employers now negotiate direct agreements with continuous glucose monitor suppliers, bypassing traditional durable medical equipment distributors. This channel compression is most visible among technology sector employers offering diabetes management as a covered wellness benefit.
Diabetes Diagnostics Market Segmentation
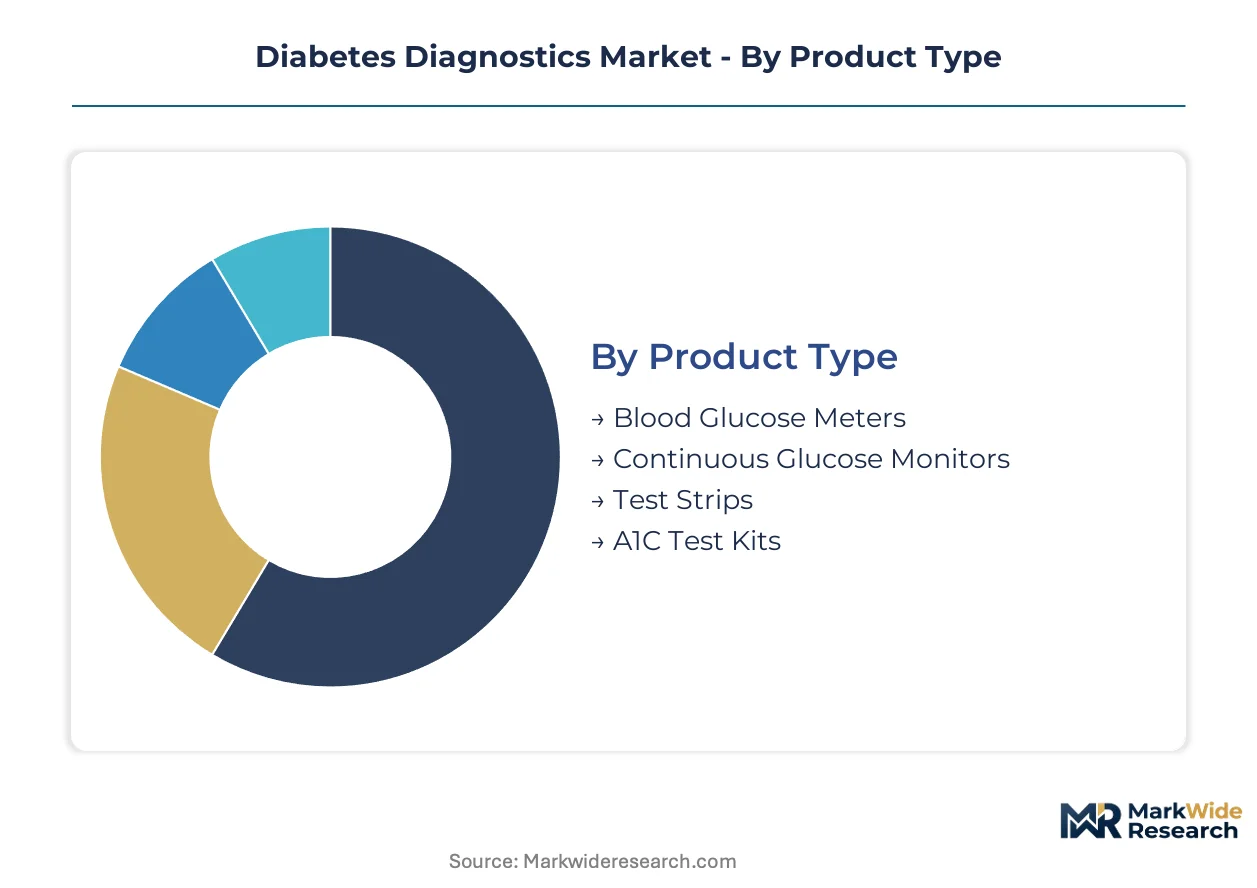
Diabetes diagnostics segmentation reveals divergent commercial logics across hardware, software, and consumable categories. Technology choices determine reimbursement pathways, while end-user concentration shapes channel strategy and margin architecture.
Product Type:
Domestic manufacturing dominates consumables and legacy meters, whereas continuous glucose monitors flow through multinational supply chains anchored in Ireland, Malaysia, and Costa Rica.
- Blood Glucose Meters:Handheld electrochemical devices measuring capillary glucose through enzymatic test strip reactions. Procurement concentrates in India's tier-2 and tier-3 cities where pharmacy-distributed affordable units address undiagnosed populations. Cost sensitivity constrains feature expansion.
- Continuous Glucose Monitors:Subcutaneous sensor-reader ecosystems transmitting real-time glucose data to handheld receivers or smartphones. Demand clusters in Germany and the United States where CMS and statutory health insurance reimbursement covers insulin-intensive patients. Extended wear durations reduce patient burden.
- Test Strips:Single-use enzymatic reagents consumed with each fingerstick measurement.
- A1C Test Kits:Laboratory and point-of-care assays quantifying glycated hemoglobin for three-month glucose averaging.
Blood glucose meters command the established base. The steepest expansion runs through continuous glucose monitors.
End User:
Volume distribution follows reimbursement policy: hospital procurement committees favor centralized analyzers, while home care growth accelerates where remote patient monitoring codes apply.
- Hospitals:Centralized laboratory diagnostics and bedside point-of-care testing for inpatient glycemic management. Purchasing committees in the United States and Germany prioritize analyzer throughput and EHR integration. Capital equipment cycles extend replacement timelines.
- Home Care:Self-monitoring by patients outside clinical settings using personal meters or prescribed continuous monitors. Expansion accelerates in the United States through CMS remote patient monitoring reimbursement expansion beyond traditional durable medical equipment channels.
- Diabetes Clinics:Outpatient specialty centers managing complex cases.
- Research Laboratories:Academic and pharmaceutical sites conducting clinical trials and biomarker discovery.
Hospitals anchor procurement volume. Home care is gaining share fastest through reimbursement realignment.
Technology:
Electrochemical architectures dominate commercialized products, while optical modalities remain concentrated in German and Japanese research consortia pursuing non-invasive validation.
- Electrochemical:Amperometric glucose detection through enzyme-immobilized electrodes measuring hydrogen peroxide generation. Manufacturing concentrates in facilities optimized for platinum group metal coating processes. Ruthenium and palladium supply volatility from South African and Russian corridors constrains margin stability.
- Enzymatic:Glucose oxidase or dehydrogenase catalytic reactions producing measurable signals.
- Optical:Near-infrared spectroscopy and Raman scattering for transdermal glucose estimation.
- Meter-based:Legacy reflectance photometry systems in cost-optimized emerging market devices.
Electrochemical platforms capture the revenue base. Optical approaches are climbing the fastest through pre-diabetic wellness applications.
Application:
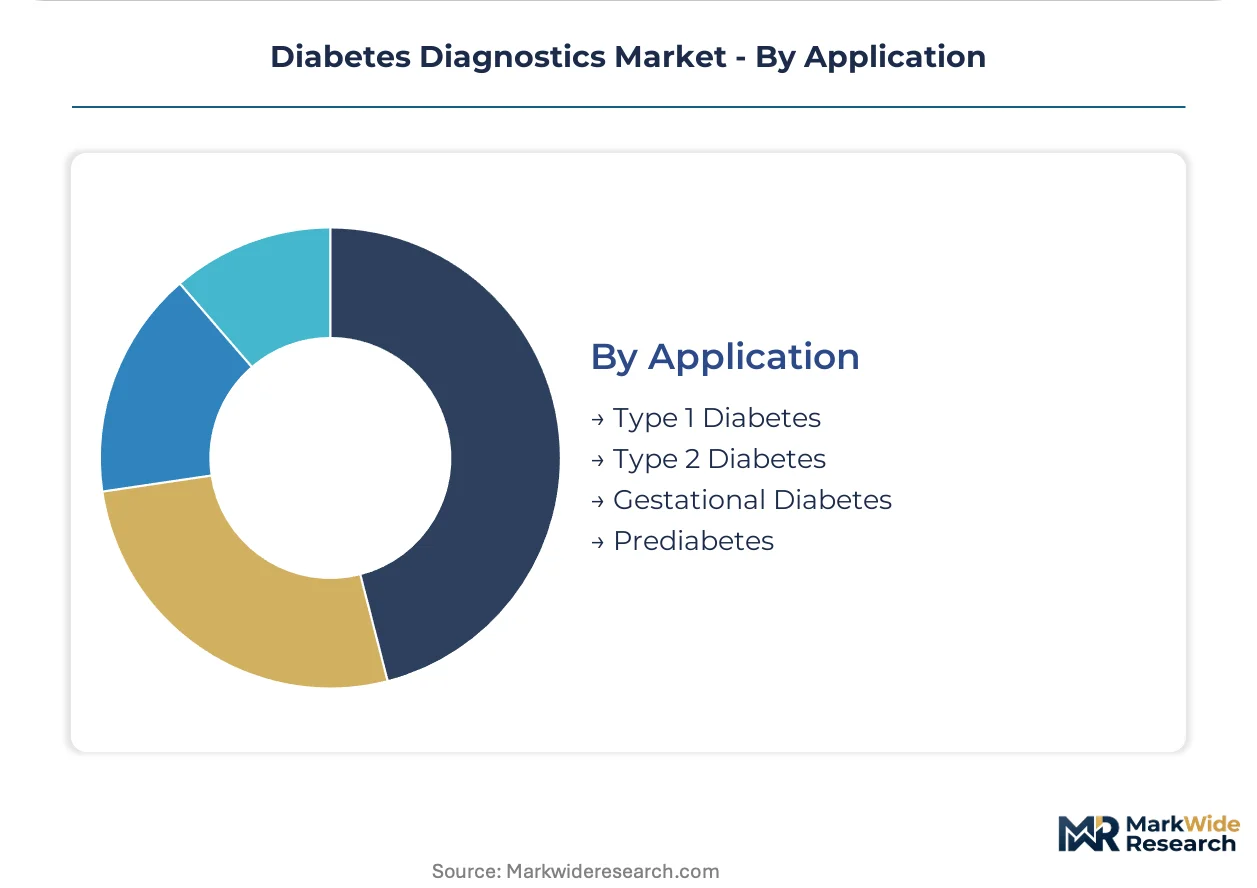
Type 1 populations drive continuous monitor penetration, while Type 2 volume concentrates in episodic testing markets with slower technology transition.
- Type 1 Diabetes:Absolute insulin deficiency requiring intensive glucose monitoring for dosing decisions. Continuous glucose monitor adoption concentrates in the United States and Germany where reimbursement frameworks cover real-time data systems. Closed-loop pump integration represents the next technology frontier.
- Type 2 Diabetes:Insulin resistance and progressive beta-cell dysfunction affecting the vast diagnostic population. Testing frequency varies by therapy intensity, with episodic fingerstick workflows persisting where oral medication management dominates.
- Gestational Diabetes:Glucose intolerance during pregnancy requiring temporary monitoring protocols.
- Prediabetes:Elevated glucose below diagnostic thresholds, driving lifestyle intervention testing.
Type 2 diabetes commands the patient volume base. Prediabetes screening is expanding most quickly through national prevention initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia exports continuous glucose monitor subassemblies to United States distributors, while Costa Rica serves European assembly operations. Ireland hosts European regulatory approval hubs for sensor-to-reader ecosystems. Supply chains bifurcate between Asian component fabrication and Western final assembly.
United States
CMS remote patient monitoring reimbursement codes now cover continuous glucose data transmission for Medicare populations. FDA premarket review under 21 CFR Part 862 shapes accuracy thresholds for non-invasive optical sensors. Manufacturing concentrates in Massachusetts and California where sensor-reader integration facilities cluster near academic medical centers.
Germany
Statutory health insurance funds expanded continuous monitor coverage for insulin-intensive patients in outpatient settings. EMA IVDR classification mandates systematic vigilance reporting for software-integrated glucose prediction tools. The Rhine-Ruhr corridor anchors centralized analyzer production for hospital laboratory networks.
China
National Health Commission directives mandate diabetes screening coverage expansion in tier-two hospital networks. NMPA clearance pathways accelerate for point-of-care A1C analyzers serving chronic disease management initiatives. Manufacturing clusters in Shenzhen and Suzhou produce cost-optimized electrochemical test strips for domestic and export markets.
India
Underdiagnosed diabetic populations in tier-three cities drive pharmacy-distributed glucometer procurement. CDSCO regulatory harmonization with IMDRF standards streamlines import pathways for multinational sensor manufacturers. Distribution networks concentrate in Mumbai and Bangalore where diagnostic device importers maintain regional warehousing.
Diabetes Diagnostics Market Vendor Landscape
Listed leaders compete with private specialists across reimbursement access and sensor ecosystem integration. The vendor base separates into multinational conglomerates with diversified diagnostics portfolios and focused sensor-technology developers. Three archetypes dominate: integrated platform providers, consumable-specialist manufacturers, and algorithm-centric software-integrated device developers. M&A activity concentrates on sensor-to-pump convergence capabilities, while geographic expansion targets underpenetrated tier-three cities in emerging markets.
Among United States-based platform developers, Abbott Laboratories and Dexcom occupy positions as integrated ecosystem anchors. Roche Diagnostics represents the European laboratory-centric archetype with centralized analyzer dominance. Medtronic exemplifies the convergence-focused specialist pursuing closed-loop insulin delivery integration.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| Siemens Healthineers |
| Becton, Dickinson and Company |
| Dexcom |
| Medtronic |
| Johnson & Johnson |
| Novo Nordisk |
| Bio-Rad Laboratories |
| Others |
Supply Flow & Price Mechanics
Enzymatic biosensor miniaturization is displacing legacy electrochemical architectures in continuous glucose monitors, simultaneously shifting manufacturing gravity toward Ireland and Malaysia while compressing per-unit sensor economics through extended 14-day wear durations. This substitution dynamic rewards manufacturers with captive coating capabilities while exposing commodity test strip producers to margin erosion from third-party generic competition.
Pricing Analysis
Next-generation continuous glucose monitors command subscription-based pricing at premiums over legacy blood glucose meters, while prior-generation test strips face commodity spot-market dynamics. Three-tier pricing structure across premium sensor-reader ecosystems, standard hospital analyzers, and economy pharmacy-distributed meters reflects FDA clearance tier and reimbursement code eligibility. Pricing pressure stems from generic strip manufacturers capturing pharmacy shelf space in India's tier-2 and tier-3 cities. Home care patients demonstrate highest price sensitivity, whereas hospital procurement committees prioritize analyzer throughput over unit cost.
Supply Chain Analysis
Strategic stockpiling of platinum group metals distinguishes sensor manufacturers exposed to South African and Russian supply corridor volatility from just-in-time test strip assemblers. Component fabrication concentrates in Malaysia, Costa Rica, and China, with final sensor-reader integration anchored in Ireland and Massachusetts. Ruthenium and palladium electrode coatings, hydrogel membrane polymers, and semiconductor substrates constitute critical input dependencies. Single-source vulnerability runs through South African platinum group metal refining. Distribution runs through pharmacy chains in emerging markets and direct-to-employer agreements in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer scientists capable of optimizing 14-day hydrogel biocompatibility command compensation premiums that constrain R&D team scaling across the competitive set, creating asymmetric capability capture opportunities for organizations with existing materials science depth.
For Market Incumbents: Shield recurring revenue streams in continuous glucose monitors by deepening backward integration into platinum group metal coating processes, reducing exposure to South African and Russian supply volatility. Fortify hospital analyzer positions through EHR integration investments that extend capital equipment replacement cycles and raise switching costs for purchasing committees evaluating Roche Diagnostics alternatives. For New Entrants and Emerging Players: Differentiate on algorithmic transparency compliance under EU AI Act mandates for predictive glucose forecasting software, capturing European market access ahead of legacy vendors restructuring quality management systems. Target India's tier-3 cities through smartphone-connected glucometer distribution partnerships with pharmacy chains, exploiting underdiagnosed population whitespace and CDSCO regulatory harmonization with IMDRF standards. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed sensor-technology specialists lacking closed-loop insulin pump convergence capabilities, presenting bolt-on acquisition opportunities for infusion device manufacturers seeking vertical integration. Watch FDA 510(k) clearance velocity for non-invasive optical sensors as inflection indicator for technology-generation substitution timelines; acceleration signals disruption of fingerstick workflows among pre-diabetic wellness segments.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy Expansion | CMS remote patient monitoring code capture secures Medicare population access beyond traditional durable medical equipment channels. |
| Sensor-to-Pump Convergence Partnership | Closed-loop insulin delivery integration requires glucose monitor and infusion device specialist alliances under FDA 21 CFR Part 862. |
| EU AI Act Algorithmic Documentation | Machine-learning version control systems enable competitive differentiation in software-integrated glucose prediction tools. |
| Platinum Group Metal Supply Security | Captive ruthenium and palladium coating capabilities insulate margin stability from South African and Russian corridor volatility. |
| Tier-3 City Distribution Network Buildout | Pharmacy chain partnerships in India's underdiagnosed urban centers address whitespace in affordable glucometer penetration. |
Methodological Framework
A spread of perspectives from hospital purchasing committee members, biomedical engineers at continuous glucose monitor manufacturers, GPO contracts managers, and CMS reimbursement policy specialists converged on the working assumptions. Primary interview insights combined with secondary validation against FDA 510(k) filings, EMA IVDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up sensor shipment estimates and top-down chronic disease epidemiology triangulated market sizing across the analysis window.
Segmentation dimensions modeled include product type hierarchy, end-user concentration, electrochemical versus optical technology pathways, and Type 1 versus Type 2 diabetes application intensity. CAGRs derived from fitted growth curves applied to reimbursement expansion trajectories and screening initiative mandates. Forecast inputs incorporated platinum group metal price volatility indices and IVDR compliance timeline assumptions for software-integrated devices.
The analysis sits within stated boundaries; outcomes outside sustained CMS remote patient monitoring reimbursement expansion or accelerated NMPA clearance pathways would require recalibration. Forecasts reflect assumptions regarding enzymatic biosensor wear duration improvements and EMA post-market surveillance documentation burdens. Revision becomes warranted when FDA predicate device scarcity for non-invasive optical sensors crosses thresholds that extend premarket timelines beyond competitive windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Europe Womens Health Diagnostics Market
Diagnostics
Malaria Diagnostics Market
Diagnostics
Extraction Kits Market
Diagnostics
Global Tissue Diagnostics Market
Diagnostics
In-Vitro Diagnostics (IVD) Instruments Market
Diagnostics
Sexually Transmitted Diseases Diagnostics Market
Diagnostics
Blood Culture Media Market
Diagnostics
In-Vitro Diagnostics (IVD) Packaging Market
Diagnostics
Meningitis Diagnosis and Treatment Market
Diagnostics
Semen Analysis Systems Market
Diagnostics
Global Chemiluminescence Immunoassay (CLIA) Market
Diagnostics
Primary Care POC Diagnostics Market
Diagnostics
Global Blood Culture Tests Market
Diagnostics
Connected Diagnostics Market
Diagnostics
Cancer Tissue Diagnostics Market
Diagnostics
In Vitro Diagnostic Antibodies Market