
 Chile in Vitro Diagnostics Market | 2026-2036
Chile in Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Chile in Vitro Diagnostics Market Outlook
Multi-source procurement for reagent kits is hardening across Chile's public laboratory networks. Roche Holding AG leverages its centralized distribution hub in Santiago to sustain supply continuity for high-throughput immunoassay systems. Abbott Laboratories anchors its position through direct technical service contracts with the Servicio de Salud Metropolitano Central. bioMérieux SA differentiates via specialized microbiology panels calibrated for regional pathogen profiles.
In vitro diagnostics encompasses analytical testing performed on biological specimens outside the living organism, utilizing reagent-based chemical reactions, optical detection systems, and software algorithms to quantify biomarkers with precision thresholds typically below nanogram-per-milliliter sensitivity. Molecular diagnostics commands premium pricing due to nucleic acid amplification complexity, while immunoassay platforms generate volume throughput across Chile's hospital network. Hematology instrumentation represents a mature replacement cycle segment, whereas infectious disease applications absorb expanded testing capacity following ISP protocol updates.
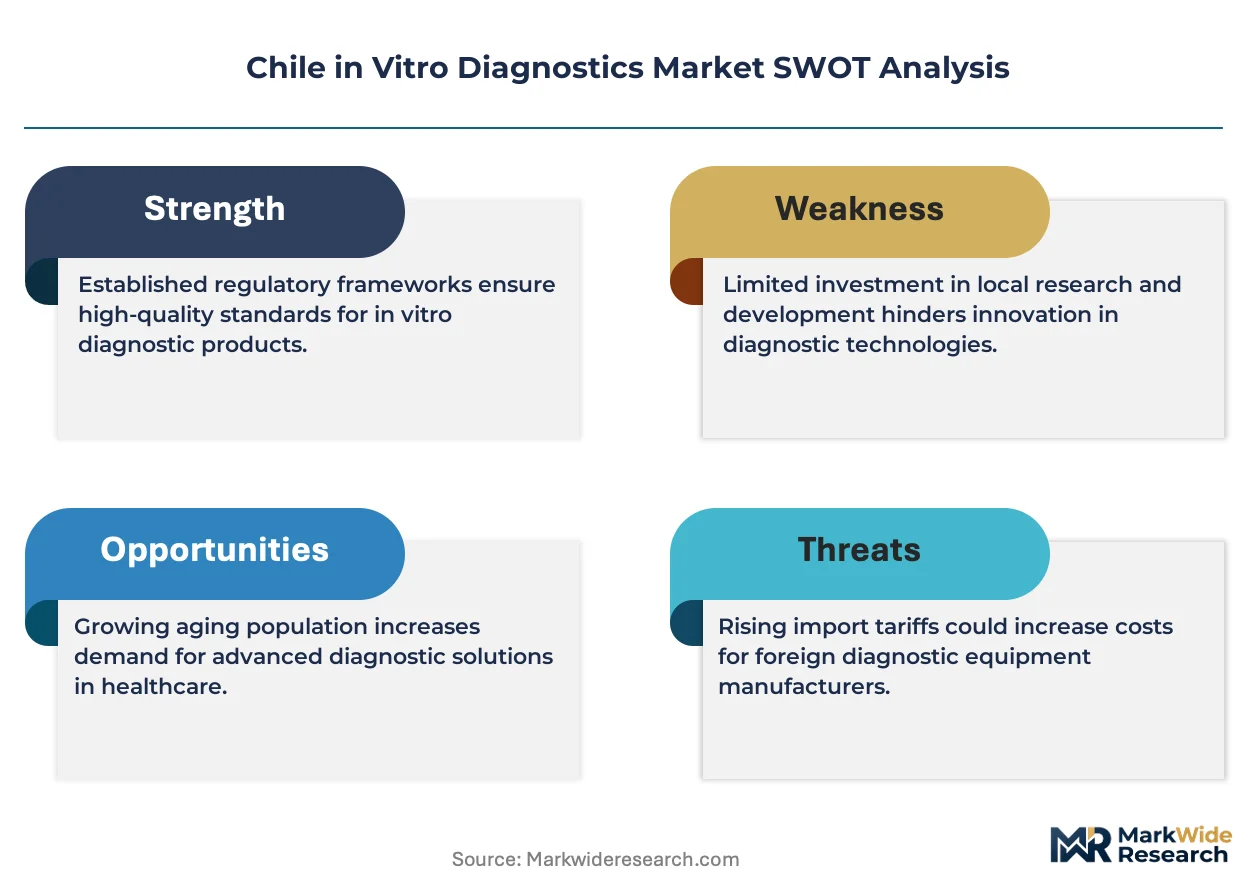
Chile's Instituto de Salud Pública (ISP) enforces pre-market registration and batch-release verification for all imported diagnostic reagents, elevating compliance costs for non-established suppliers. The national laboratory accreditation program under the Ministry of Health mandates proficiency testing participation, filtering market access toward technically resourced manufacturers. Stakeholders must monitor ISP's alignment with Mercosur technical standards and the pace of molecular test reimbursement integration into Chile's AUGE guaranteed-care framework.
Market Dynamics
ISP's batch-release verification mandate for imported reagents is compressing supplier timelines and elevating technical compliance costs across Chile's laboratory procurement landscape. Public hospital networks are consolidating testing volumes onto automated platforms while private oncology centers demand specialized molecular panels.
Growth Catalysts
- AUGE Framework Expansion:Chile's guaranteed-care program is integrating molecular diagnostic reimbursement codes for oncology and infectious disease applications. This creates pull-through demand for high-complexity testing infrastructure in metropolitan Santiago.
- Public Hospital Automation:Servicio de Salud Metropolitano Central is deploying high-throughput immunoassay systems across its network. Centralized procurement is standardizing platform selection and locking in multi-year reagent supply agreements.
- ISP-Mercosur Alignment:Chile's national health authority is harmonizing technical standards with regional trade bloc protocols. This streamlines registration pathways for established Mercosur suppliers while raising barriers for non-aligned manufacturers.
Market Restraints
- Import Dependency Concentration:Reagent supply chains concentrate through Santiago's centralized distribution hub. Disruption at this node propagates delays to Valparaíso oncology centers and regional public laboratories.
- Currency Volatility Exposure:Diagnostic equipment and consumables are dollar-denominated imports. Peso depreciation against the US dollar directly inflates landed costs for public sector procurement budgets.
- Technical Talent Scarcity:Molecular diagnostics requires certified laboratory technologists with nucleic acid amplification expertise. Training pipeline gaps limit operational scaling for complex test menus.
Strategic Opportunities
- Valparaíso Oncology Cluster:Specialized cancer centers in this port city are expanding companion diagnostic capabilities. Localized technical service partnerships can anchor regional market presence.
- Point-of-Care Integration:Decentralized testing platforms are penetrating primary care networks outside Santiago. This channel expansion reduces logistics burden for routine infectious disease screening.
- Proficiency Testing Services:Ministry of Health accreditation mandates create recurring revenue streams for external quality assurance providers. Laboratories require independent validation for ISP compliance documentation.
Industry Challenges
- Legacy Platform Interoperability:Public hospital networks operate mixed-vendor instrument fleets. Data integration between hematology, chemistry, and molecular systems requires custom middleware development.
- ISP Registration Timelines:Pre-market approval for novel diagnostic reagents extends 12-18 months. Batch-release testing adds further delay before commercial distribution authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile in Vitro Diagnostics Market |
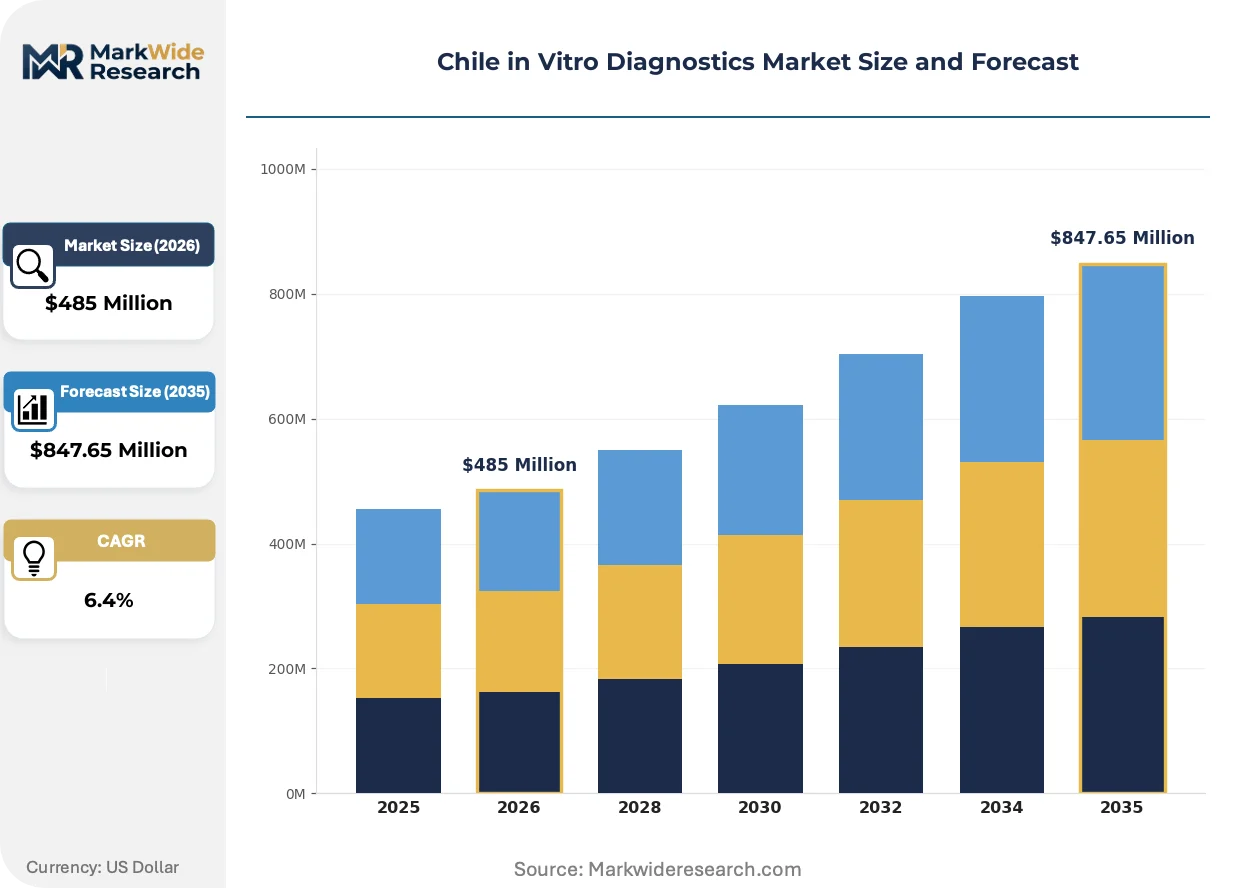
| Market Size in 2026 | $485 Million |
| Market Size in 2035 | $847.65 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Controls End User: Hospitals, Clinics, Laboratories, Research Facilities Technology: Molecular Diagnostics, Immunoassays, Hematology, Microbiology Application: Infectious Diseases, Cancer Diagnostics, Genetic Testing, Autoimmune Disorders |
| Companies Covered | Roche Holding AG, Abbott Laboratories, Thermo Fisher Scientific Inc, Danaher Corporation, Becton, Dickinson and Company, Siemens Healthineers AG, bioMérieux SA, Sysmex Corporation, Bio-Rad Laboratories, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile in Vitro Diagnostics Market Strategic Shifts
Digital pathology and artificial intelligence-assisted image analysis are penetrating Chile's diagnostic infrastructure. These technologies are compressing turnaround times for histopathology while reshaping workforce skill requirements.
Next-generation sequencing platforms are rewriting the economics of hereditary cancer screening in Santiago's private laboratory sector. Clinica Alemana and Fundacion Arturo Lopez Perez are adopting panel-based testing for BRCA and Lynch syndrome mutations. This technology is compressing the cost-per-variant-detected metric and displacing single-gene Sanger sequencing workflows.
ISP's updated technical standard for molecular diagnostic validation is tightening analytical performance requirements for viral load quantification assays. Laboratories must demonstrate linearity across expanded dynamic ranges and submit cross-platform correlation studies. HIV and hepatitis C testing programs in the public sector are most affected, with reference laboratories accelerating instrument replacement cycles.
Consolidated procurement through ChileCompra is concentrating purchasing power within the Ministry of Health's central supply division. Regional health services are losing autonomy over equipment selection, with standardized tender specifications favoring multi-analyzer contracts. This behavioral shift is most visible in the Metropolitano and Valparaiso regions where hospital network integration is most advanced.
Chile in Vitro Diagnostics Market Segmentation
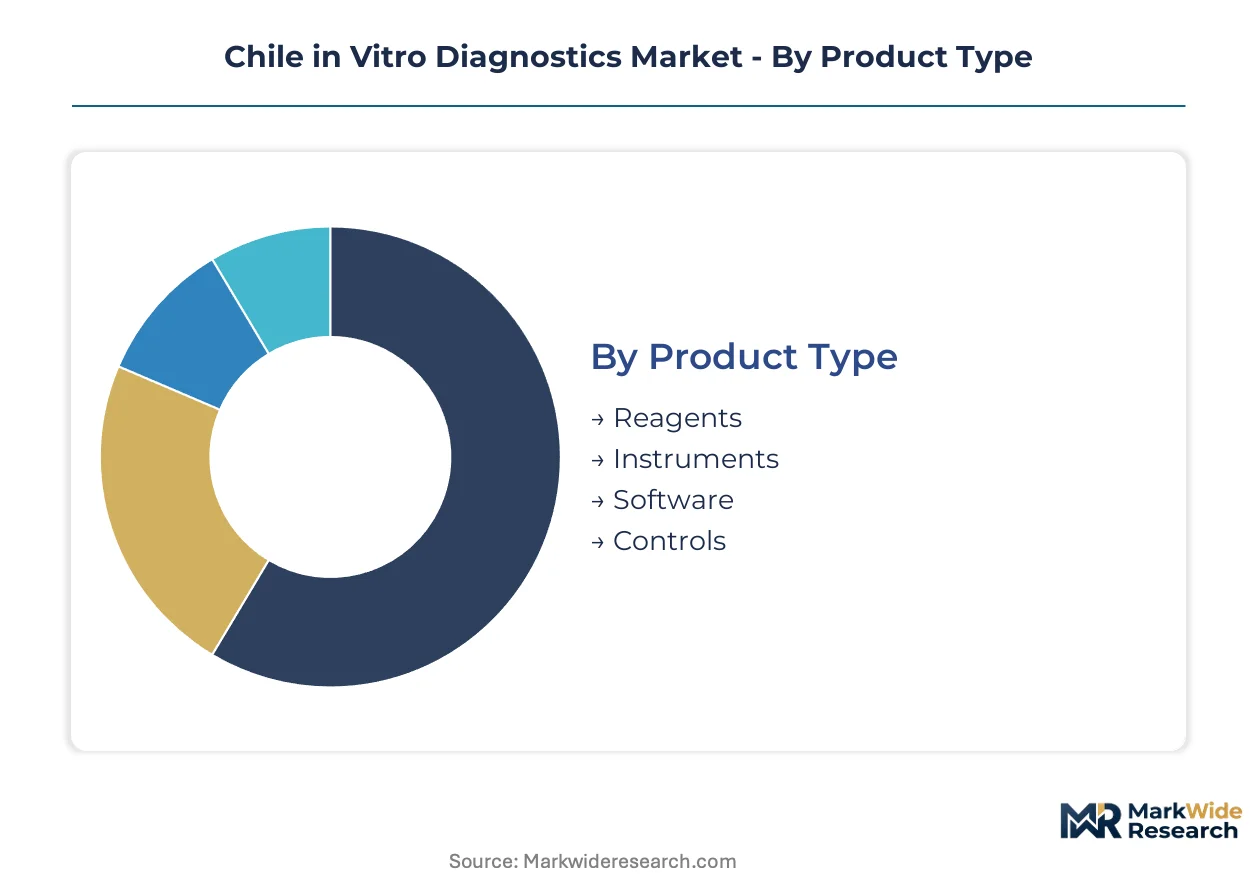
Chile's IVD segmentation reveals how procurement consolidation and ISP regulatory tiers reshape competitive positioning across product categories. Each dimension carries distinct margin profiles and compliance burdens that determine supplier viability in Santiago's metropolitan laboratory cluster versus regional networks.
Product Type:
Standalone consumables dominate routine testing workflows, while integrated system-instrument bundles concentrate in high-throughput hospital networks.
- Reagents:Chemical and biological reactive agents formulated for specific analyte detection, with shelf-life stability requirements calibrated to ISP batch-release timelines. Public hospital networks in Santiago's Servicio de Salud Metropolitano Central absorb the largest procurement volumes under multi-year supply agreements.
- Instruments:Automated analyzers, sample processors, and detection platforms requiring ISP technical certification for electromagnetic compatibility and analytical performance. Valparaíso oncology centers are driving placements of molecular amplification systems for companion diagnostic workflows.
- Software:Laboratory information management systems and instrument middleware enabling data integration across mixed-vendor fleets. Regional public laboratories outside Santiago prioritize interoperability modules over advanced analytics.
- Controls:Quality assurance materials and calibrators used for proficiency testing compliance under Ministry of Health accreditation mandates.
Volume placements concentrate in Reagents; the faster expansion belongs to Instruments.
End User:
Customer type determines pricing tolerance and technical service intensity, with public procurement channels operating on standardized tender specifications.
- Hospitals:Acute-care facilities with centralized laboratory infrastructure spanning chemistry, hematology, and blood bank operations. The Servicio de Salud Metropolitano Central network is consolidating testing onto automated immunoassay platforms with locked reagent contracts.
- Clinics:Primary care and specialty outpatient facilities with point-of-care testing capacity for rapid infectious disease screening. Decentralized networks in Chile's southern regions are expanding rapid diagnostic coverage.
- Laboratories:Independent reference laboratories and hospital-affiliated facilities performing esoteric testing menus. Santiago's metropolitan cluster hosts the highest concentration of molecular diagnostic capacity.
- Research Facilities:Academic and clinical research organizations with non-routine assay development requirements and flexible procurement pathways outside ChileCompra frameworks.
Procurement volume clusters in Hospitals; Research Facilities are climbing the fastest as hereditary cancer screening expands.
Technology:
Platform selection follows reimbursement integration into Chile's AUGE framework, with molecular modalities commanding premium positioning.
- Molecular Diagnostics:Nucleic acid amplification, hybridization, and sequencing-based detection with analytical sensitivity thresholds below picogram quantities. ISP's updated viral load quantification standards are accelerating instrument replacement in public sector HIV and hepatitis C programs.
- Immunoassays:Antibody-antigen binding reactions deployed across chemistry and endocrinology testing menus with established automation protocols. High-throughput systems anchor the standardized procurement specifications emerging from ChileCompra consolidation.
- Hematology:Complete blood count and coagulation analysis with mature replacement cycles and limited differentiation between vendor platforms.
- Microbiology:Culture-based and rapid pathogen identification systems calibrated to regional resistance profiles. bioMérieux SA has anchored presence through specialized panels targeting Chile-specific bacterial strains.
Instrument placements concentrate in Immunoassays; Molecular Diagnostics is gaining share fastest through AUGE reimbursement expansion.
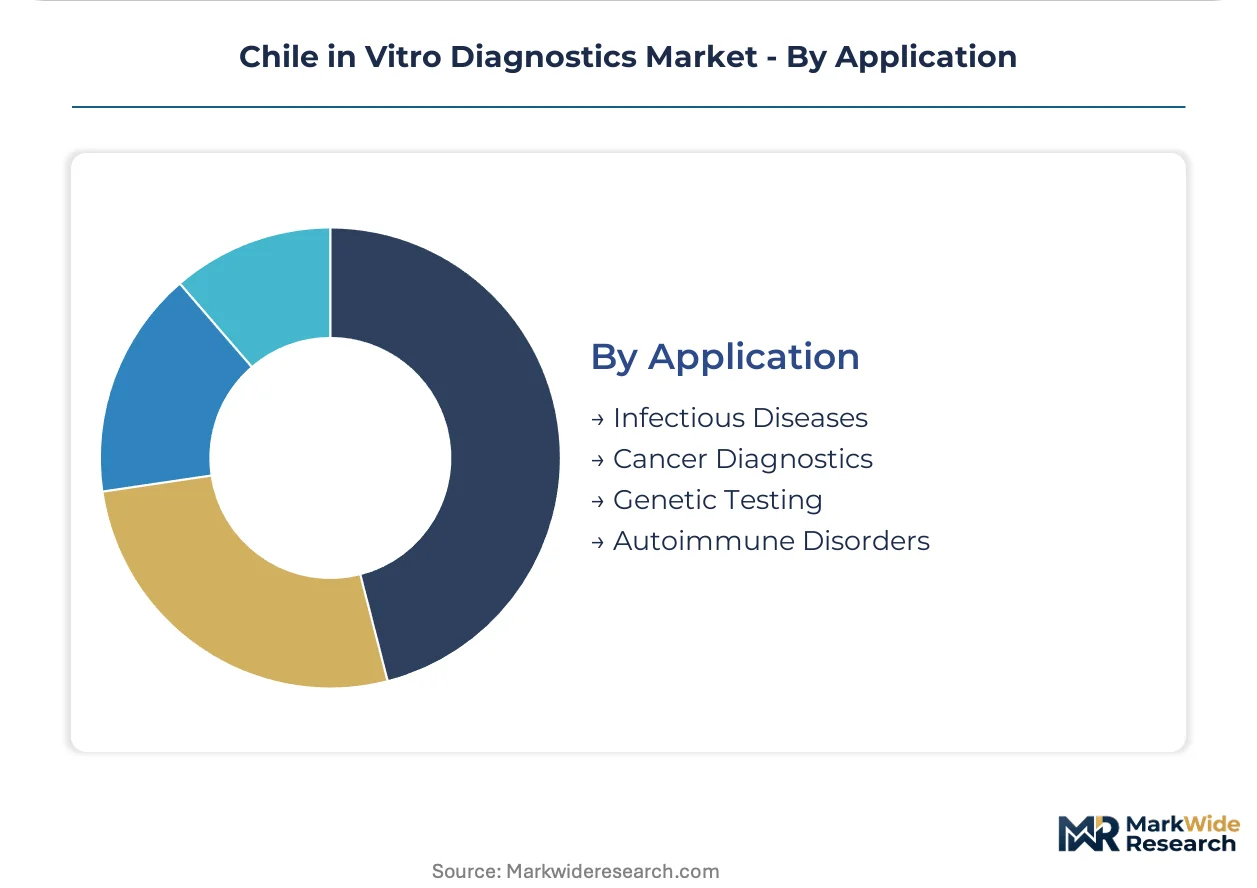
Application:
Disease-area segmentation aligns with epidemiological burden and guaranteed-care coverage priorities under national health policy.
- Infectious Diseases:Diagnostic testing for viral, bacterial, and parasitic pathogens with public health surveillance integration. ISP protocol updates for HIV and hepatitis C viral load monitoring are reshaping laboratory capacity requirements.
- Cancer Diagnostics:Oncology testing spanning histopathology, tumor markers, and companion diagnostics for targeted therapy selection. Clinica Alemana and Fundacion Arturo Lopez Perez in Santiago are adopting next-generation sequencing panels for BRCA and Lynch syndrome screening.
- Genetic Testing:Hereditary disease screening and pharmacogenomic analysis with emerging reimbursement pathways outside core AUGE coverage.
- Autoimmune Disorders:Rheumatology and endocrinology testing menus with established immunoassay automation and limited molecular penetration.
Testing volume concentrates in Infectious Diseases; Cancer Diagnostics shows the steepest expansion trajectory as private oncology investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biological specimen collection networks and reagent distribution infrastructure anchor Chile's IVD geography around Santiago's metropolitan laboratory cluster and Valparaíso's specialized oncology corridor.
Metropolitan Santiago
The Servicio de Salud Metropolitano Central absorbs the largest public procurement volumes for automated immunoassay systems. ISP batch-release verification mandates compress supplier timelines for reagents entering through Santiago's centralized distribution hub. Private laboratories in the Las Condes and Providencia districts concentrate molecular diagnostic capacity for hereditary cancer screening.
Valparaíso Region
Specialized oncology centers in this Pacific port city are expanding companion diagnostic capabilities for targeted therapy selection. Clinica Alemana and Fundacion Arturo Lopez Perez anchor private investment in next-generation sequencing panels. The regional health service is integrating viral load quantification capacity under ISP's updated HIV and hepatitis C protocol standards.
Biobío Region
Concepción's academic medical centers drive demand for research-grade diagnostic instrumentation outside core procurement frameworks. The Universidad de Concepción's hospital network operates mixed-vendor fleets requiring interoperability middleware. Regional laboratories face extended logistics timelines for reagent replenishment from Santiago's distribution hub.
Araucanía Region
Temuco's primary care networks are expanding point-of-care testing capacity for decentralized infectious disease screening. The regional health service lacks certified technologists with nucleic acid amplification expertise. ISP proficiency testing mandates filter market access toward technically resourced manufacturers with established Chilean technical service presence.
Chile in Vitro Diagnostics Market Competitive Environment
Global majors compete with regional champions across reagent supply continuity and technical service intensity. The vendor base stratifies between consolidated multi-platform suppliers and specialized microbiology panel providers. Swiss and US-based conglomerates occupy the high-throughput hospital network tier, while French specialists anchor regional pathogen calibration positioning. Dominant competitive moves include multi-year reagent lock-in contracts and direct technical service partnerships with metropolitan health services.
Among Swiss-headquartered conglomerates, Roche Holding AG exemplifies the centralized distribution archetype through its Santiago hub sustaining supply continuity. Abbott Laboratories represents the direct service contract model with established Servicio de Salud Metropolitano Central relationships. bioMérieux SA occupies the specialized panel differentiation position through regional pathogen profile calibration.
| Leading Market Players |
|---|
| Roche Holding AG |
| Abbott Laboratories |
| Thermo Fisher Scientific Inc |
| Danaher Corporation |
| Becton, Dickinson and Company |
| Siemens Healthineers AG |
| bioMérieux SA |
| Sysmex Corporation |
| Bio-Rad Laboratories, Inc. |
| Others |
Value Chain & Pricing Dynamics
US dollar-denominated reagent imports cascade through Chile's peso-sensitive procurement system, compressing margins for public hospital networks while amplifying pricing power for distributors with hedged currency positions. The concentration of landed costs through Santiago's centralized hub stratifies procurement tiers between metropolitan laboratories with volume leverage and regional facilities absorbing forex volatility.
Pricing Analysis
Service bundling separates premium-tier suppliers with embedded technical contracts from unbundled reagent vendors competing on landed cost alone. Three-tier pricing structure across premium, standard, and economy levels reflects ISP certification grade, with batch-release verified reagents commanding spreads over non-validated alternatives. Pricing pressure stems from ChileCompra consolidated tenders standardizing multi-year agreements. Public sector procurement committees exhibit highest price sensitivity; private oncology centers in Valparaíso prioritize companion diagnostic accuracy over unit cost.
Supply Chain Analysis
Domestic-content rules are absent from Chile's IVD regulatory framework, leaving sourcing decisions tethered to ISP registration pathways rather than local manufacturing mandates. Reagent supply concentrates in the United States, Germany, and France, with molecular diagnostic components drawing from Swiss and Japanese precision manufacturing bases. Polymerase chain reaction primers, fluorogenic probes, and automated analyzer subassemblies anchor import dependency. Single-source vulnerability propagates from Santiago's distribution hub to regional laboratories. Distribution runs through distributor-anchored technical service networks with direct hospital contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's IVD market is consolidating around ISP-registered suppliers with technical service infrastructure, squeezing non-compliant reagent traders from public procurement channels.
For Market Incumbents: Hedge currency exposure through peso-denominated service contracts indexed to Chile's central bank reference rate. Secure multi-year reagent lock-ins with Servicio de Salud Metropolitano Central before ChileCompra standardization accelerates. Vertical integration into proficiency testing services captures recurring revenue from Ministry of Health accreditation mandates. Threat: emerging regional distributors with Mercosur-aligned registration shortcuts. For New Entrants and Emerging Players: Regional laboratory service partnerships offer the most penetrable channel for molecular diagnostic platforms outside Santiago's saturated metropolitan cluster. Target Temuco's primary care networks and Concepción's academic medical centers with point-of-care infectious disease screening bundles. Go-to-market angle: ISP batch-release pre-certification partnerships with established reference laboratories to compress registration timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized microbiology panel providers with regional pathogen calibration capabilities in Valparaíso and Biobío regions. Long-term viability hinges on AUGE reimbursement integration for molecular oncology testing. Acquisition target archetype: mid-scale laboratories with locked public sector contracts and certified nucleic acid amplification technologists. Signal to watch: ISP alignment with Mercosur technical standards accelerating registration pathway bifurcation.| Strategic Initiative | Industry Significance |
|---|---|
| ISP Batch-Release Pre-Certification | Compresses 12-18 month registration timelines for novel reagent entrants. |
| ChileCompra Consolidated Tender Participation | Locks multi-year supply agreements with standardized platform specifications. |
| Valparaíso Oncology Technical Service Partnership | Anchors regional presence for companion diagnostic instrument placements. |
| Proficiency Testing Service Expansion | Captures recurring revenue from Ministry of Health accreditation mandates. |
| Point-of-Care Platform Integration | Reduces logistics burden for decentralized infectious disease screening. |
Study Parameters
Document review covered ISP regulatory filings, ChileCompra procurement databases, and AUGE reimbursement protocol updates, complemented by interviews with laboratory directors at Servicio de Salud Metropolitano Central, biomedical engineers at Clinica Alemana, and procurement managers at Fundacion Arturo Lopez Perez. Secondary validation drew from Ministry of Health accreditation records, Mercosur technical standard harmonization documents, and regional health service budget disclosures. Bottom-up instrument placement estimates triangulated against top-down market size calculations across the analysis window.
Historical shipment data cross-referenced with panel input from distributor technical service heads shaped the analytical framework. Segmentation dimensions modeled include product type, end user category, technology platform, and application area, with geographic procurement cluster as an additional industry-specific dimension. CAGRs were derived from regression analysis of annual placement volumes against AUGE reimbursement expansion trajectories. Forecast inputs incorporated ISP protocol update schedules and molecular test menu expansion timelines.
Several conditions sit outside the modeled scope, including unannounced ISP regulatory shifts, abrupt peso depreciation episodes, and supply chain disruptions at Santiago's distribution hub. Forecasts reflect assumptions regarding AUGE reimbursement integration pace and Mercosur alignment completion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Breast Cancer Diagnostics Market
Diagnostics
Global Neurodiagnostics Market
Diagnostics
Global Tissue Diagnostics Market
Diagnostics
Hepatitis E Diagnostic Tests Market
Diagnostics
Mycoplasma Diagnostics Market
Diagnostics
Treponema Pallidum Tests Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
Point of Care (Poc) Molecular Diagnostics Market
Diagnostics
FISH Probe Market
Diagnostics
Blood Glucose Testing Devices Market
Diagnostics
Canada in-Vitro Diagnostics Market
Diagnostics
Global Rapid Diagnostic Kits Market
Diagnostics
Global Women's Health Diagnostics Market
Diagnostics
Glucose Biosensors Market
Diagnostics
In-Vitro Diagnostics Enzymes Market
Diagnostics
Spain in-Vitro Diagnostics Market