
 North America Autoimmune Disease Diagnostics Market | 2026-2036
North America Autoimmune Disease Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Autoimmune Disease Diagnostics Market Analytics
A capital-intensity divergence between fully integrated platform vendors and reagent-focused specialists is redrawing competitive boundaries in autoimmune diagnostics. Abbott Laboratories leverages its installed base of high-throughput immunoassay analyzers to sustain recurring revenue streams across hospital networks. Siemens Healthineers anchors its position through deep vertical integration from assay development to automated sample processing systems.
Autoimmune disease diagnostics encompasses laboratory and point-of-care methods that detect autoantibodies, immune complexes, and inflammatory markers through immunological and molecular techniques, typically requiring sensitivity thresholds below 10 IU/mL for clinically relevant detection. These systems serve rheumatologists, neurologists, and primary care physicians in distinguishing autoimmune pathologies from infectious or malignant mimics. Reagents and assays capture the dominant share of recurring revenue as laboratories consume antibodies, substrates, and calibrators with each test cycle. ELISA technology leads in routine screening volume due to its cost structure and established protocol familiarity, while microarray platforms compete in multiplexed panels that simultaneously profile dozens of autoantibody specificities.
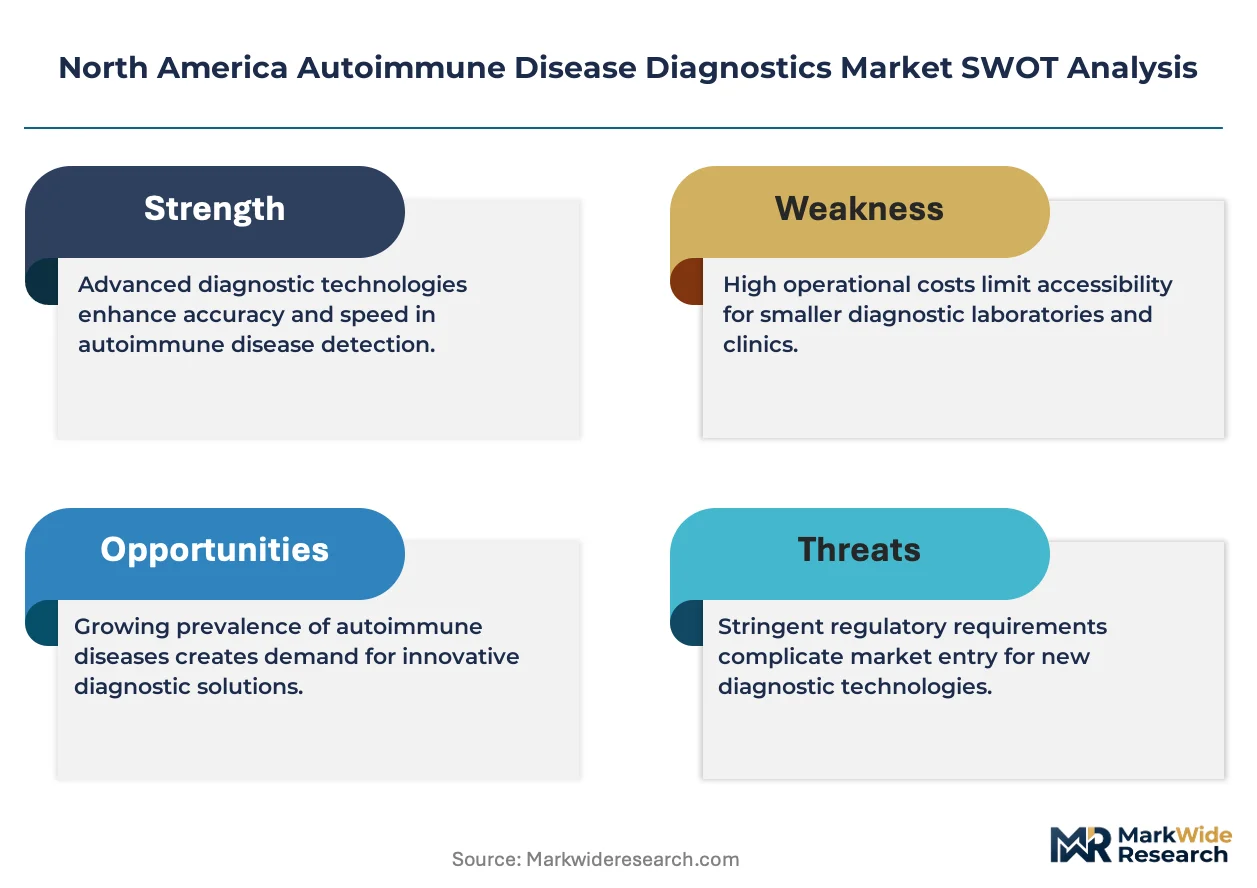
FDA oversight of in vitro diagnostic devices and laboratory-developed tests shapes validation burdens and commercialization timelines for new autoimmune assays entering the US market. Health Canada's regulatory framework for Class III and IV medical devices imposes parallel conformity requirements that manufacturers must navigate for Canadian market access. Clinical Laboratory Improvement Amendments standards enforced by CMS govern analytical performance expectations that directly influence analyzer purchasing criteria. Stakeholders must monitor how evolving FDA guidance on algorithm-based diagnostic outputs reshapes software and AI-integrated platforms within autoimmune testing workflows.
Market Dynamics
Hospital laboratories across the United States and Canada are consolidating autoimmune testing volumes onto high-throughput platforms to capture economies of scale previously lost to reference laboratory send-outs. This operational restructuring is compressing vendor selection criteria toward integrated systems capable of processing thousands of samples daily with minimal manual intervention.
Growth Catalysts
- CLIA Laboratory Certification Standards:CMS enforcement of analytical performance benchmarks drives replacement cycles for aging immunoassay analyzers in hospital core laboratories. Facilities pursuing high-complexity testing designations must demonstrate continuous quality monitoring capabilities.
- Multiplexed Autoantibody Profiling:Microarray platforms enable simultaneous detection of dozens of specificities from single serum samples, reducing reflex testing cascades and accelerating differential diagnosis timelines for complex rheumatologic presentations.
- Integrated Health System Consolidation:Large US hospital networks standardize instrument platforms across multiple sites to negotiate favorable reagent pricing and simplify technical training requirements for laboratory personnel.
Market Restraints
- Specialized Reagent Supply Concentration:Monoclonal antibody production for diagnostic assays concentrates among limited contract manufacturing organizations, creating vulnerability to batch variability and extended lead times for critical raw materials.
- FDA Laboratory-Developed Test Oversight:Evolving guidance on algorithm-based diagnostic outputs imposes additional validation burdens for AI-integrated autoimmune platforms, extending commercialization timelines and elevating regulatory compliance costs.
- Manual ELISA Protocol Persistence:Established cost structures and technician familiarity with conventional enzyme-linked immunosorbent methods slow adoption of fully automated alternatives in smaller clinical laboratories.
Strategic Opportunities
- Canadian Provincial Laboratory Networks:Health Canada's Class III device framework creates pathways for US-validated autoimmune platforms to expand into Ontario and Quebec regional health systems with centralized procurement structures.
- Point-of-Care Rheumatology Clinics:Rapid quantitative immunoassay readers enable same-visit autoantibody testing in specialty practices, reducing referral delays and capturing diagnostic revenue currently flowing to hospital laboratories.
- AI-Assisted Pattern Interpretation:Machine learning algorithms applied to indirect immunofluorescence imaging standardize subjective morphological assessments and reduce inter-observer variability in antinuclear antibody screening.
Industry Challenges
- Cross-Platform Assay Harmonization:Variability in calibrator materials and antibody specificity across manufacturer systems produces discordant quantitative results that complicate longitudinal patient monitoring.
- Legacy Analyzer Integration Complexity:Hospital information systems require customized middleware development to connect newer autoimmune platforms with existing laboratory information management infrastructure.
- Specialized Immunology Training Deficits:Shortages of medical laboratory scientists with expertise in complex autoantibody interpretation limit expansion of in-house testing menus despite available instrumentation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Autoimmune Disease Diagnostics Market |
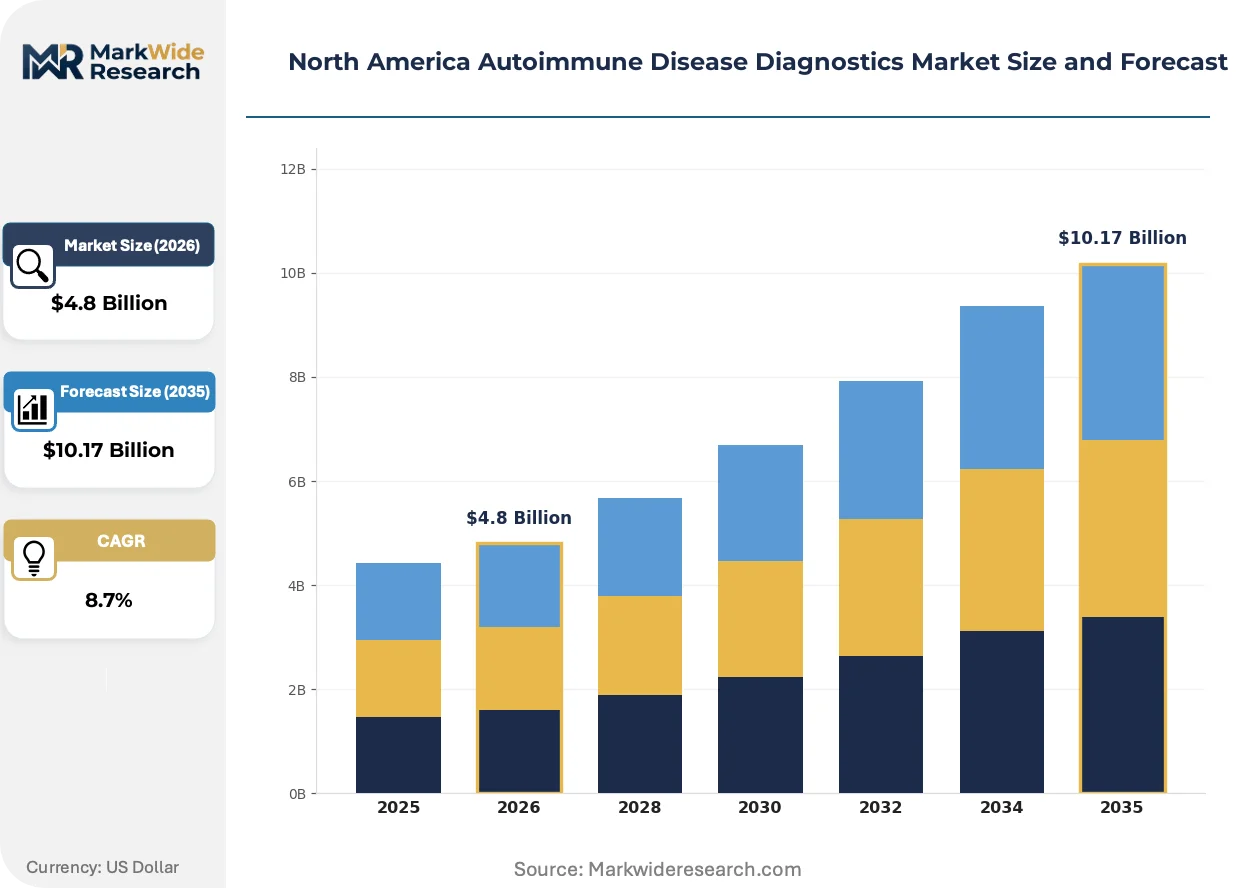
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Assays, Analyzers, Software Technology: ELISA, PCR, Microarray, Immunofluorescence End User: Hospitals, Clinical Labs, Research Institutes, Home Care Application: Rheumatoid Arthritis, Systemic Lupus Erythematosus, Multiple Sclerosis, Others |
| Companies Covered | Abbott Laboratories, Bio-Rad Laboratories, Siemens Healthineers, Thermo Fisher Scientific, F. Hoffmann-La Roche, Quest Diagnostics, Biomérieux, Werfen Group, Grifols, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Autoimmune Disease Diagnostics Market Evolving Landscape
Technological convergence between molecular diagnostics and classical serology is dissolving traditional boundaries between autoimmune testing methodologies. Vendors are repositioning platform architectures to accommodate simultaneous detection of nucleic acid, protein, and cellular markers within unified analytical workflows.
Multiplex bead-based immunoassays are fragmenting the conventional sequential testing paradigm for connective tissue disease evaluation. Rheumatology practices in large US academic medical centers are adopting these platforms to replace multiple single-analyte ELISA orders with comprehensive panels. The technology is fragmenting revenue concentration among reference laboratories by enabling hospital laboratories to retain complex autoimmune testing that previously required external referral.
FDA guidance on clinical decision support software is reshaping validation requirements for algorithm-integrated autoimmune diagnostic systems. Manufacturers must now demonstrate analytical and clinical validity for software components that interpret pattern recognition or generate diagnostic probability scores. Smaller platform developers face disproportionate compliance burdens relative to established immunoassay vendors with dedicated regulatory affairs infrastructure.
Health system procurement committees are consolidating vendor relationships to reduce operational complexity across distributed laboratory networks. Large integrated delivery networks in Texas and California are negotiating enterprise-wide reagent contracts that bundle autoimmune, infectious disease, and endocrine testing consumables. This concentration is visible most prominently in the US Southeast, where regional hospital alliances have standardized on single-manufacturer chemistry and immunoassay platforms to maximize volume-based pricing leverage.
North America Autoimmune Disease Diagnostics Market Segmentation
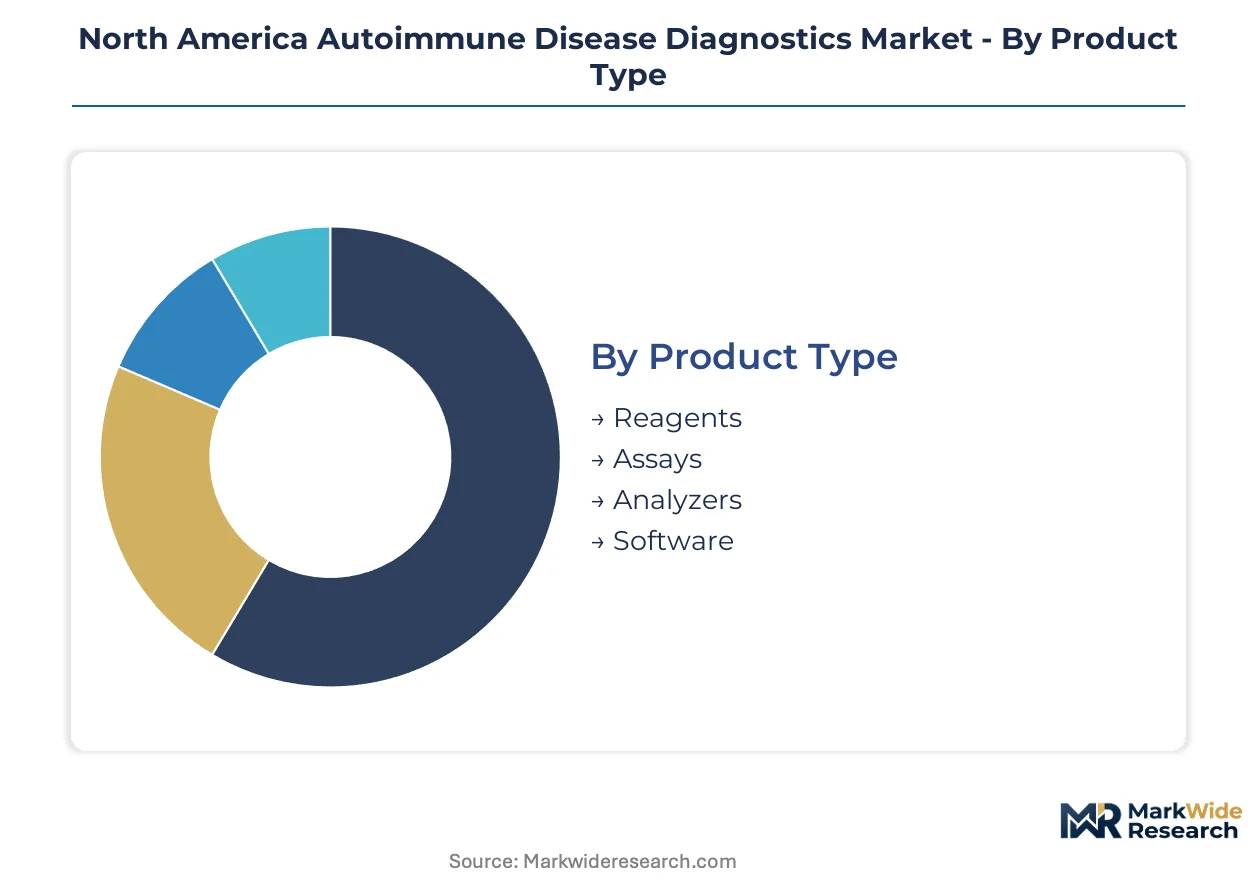
Segmentation in autoimmune diagnostics reveals how purchasing decisions fragment across technical specifications, regulatory requirements, and care delivery settings. Understanding these divisions exposes where vendor consolidation pressures concentrate and where specialized players retain defensible positions.
Product Type:
Reagents face the most acute substitution pressure as open-system analyzers gain hospital laboratory adoption, enabling third-party reagent sourcing that erodes proprietary consumable lock-in.
- Reagents:Enzyme conjugates, substrate solutions, and wash buffers constitute the highest-margin recurring revenue stream in autoimmune testing workflows. Hospital laboratories in Texas and California health systems negotiate enterprise reagent contracts that bundle autoimmune, infectious disease, and endocrine consumables to maximize volume leverage.
- Assays:Pre-packaged test kits with calibrators and controls reduce protocol variability but lock facilities into manufacturer-specific platforms. Academic medical centers in the US Northeast favor multiplexed assay panels that consolidate multiple autoantibody specificities into single test orders.
- Analyzers:Automated immunoassay platforms process thousands of samples daily with minimal technician intervention. Large integrated delivery networks standardize on single-manufacturer chemistry and immunoassay systems to simplify training and maintenance logistics.
- Software:Middleware connecting analyzers to laboratory information management systems requires customized development for legacy infrastructure integration. FDA guidance on clinical decision support algorithms imposes additional validation burdens for AI-integrated pattern interpretation modules.
Reagents retain volume leadership; software holds the steepest expansion curve as AI-assisted diagnostics reshape pattern interpretation workflows.
Technology:
Cost tier stratification separates high-throughput hospital core laboratories from smaller clinical facilities, with capital intensity determining where each technology gains adoption.
- ELISA:Enzyme-linked immunosorbent assays dominate routine screening volume due to established protocol familiarity and favorable cost structures. Smaller clinical laboratories across the US Southeast persist with manual ELISA methods despite automation availability, slowing platform replacement cycles.
- Microarray:Bead-based multiplex platforms simultaneously detect dozens of autoantibody specificities from single serum samples. Rheumatology practices at US academic medical centers adopt these systems to replace sequential single-analyte testing cascades.
- PCR:Nucleic acid amplification methods detect genetic markers associated with autoimmune susceptibility and pharmacogenomic response. Research institutes leverage PCR for HLA typing applications that guide biologic therapy selection in inflammatory arthritis.
- Immunofluorescence:Indirect immunofluorescence remains the reference standard for antinuclear antibody screening despite subjective pattern interpretation requirements. Machine learning algorithms are standardizing morphological assessments to reduce inter-observer variability in high-volume hospital laboratories.
ELISA maintains installed base dominance; microarray platforms are expanding most quickly as health systems consolidate testing menus onto multiplexed systems.
End User:
Customer type determines purchasing authority structure, with centralized procurement in integrated networks contrasting against decentralized decision-making in independent settings.
- Hospitals:In-house laboratory expansion reduces reference laboratory send-out costs for complex autoimmune panels. Hospital core laboratories in Ontario and Quebec regional health systems centralize testing volumes to capture economies of scale.
- Clinical Labs:Independent reference laboratories compete on turnaround time and specialized test menus that hospital facilities cannot support. CLIA certification requirements drive continuous quality monitoring investments that favor larger laboratory networks.
- Research Institutes:Investigational use of novel biomarker platforms precedes clinical assay commercialization by several years. NIH-funded autoimmune research centers validate candidate markers for eventual diagnostic translation.
- Home Care:Point-of-care quantitative immunoassay readers enable same-visit autoantibody testing in rheumatology specialty practices. Rapid diagnostic platforms reduce referral delays and capture revenue currently flowing to hospital laboratories.
Hospitals command the largest procurement volumes; home care settings are climbing the fastest as point-of-care platforms expand into specialty practice workflows.
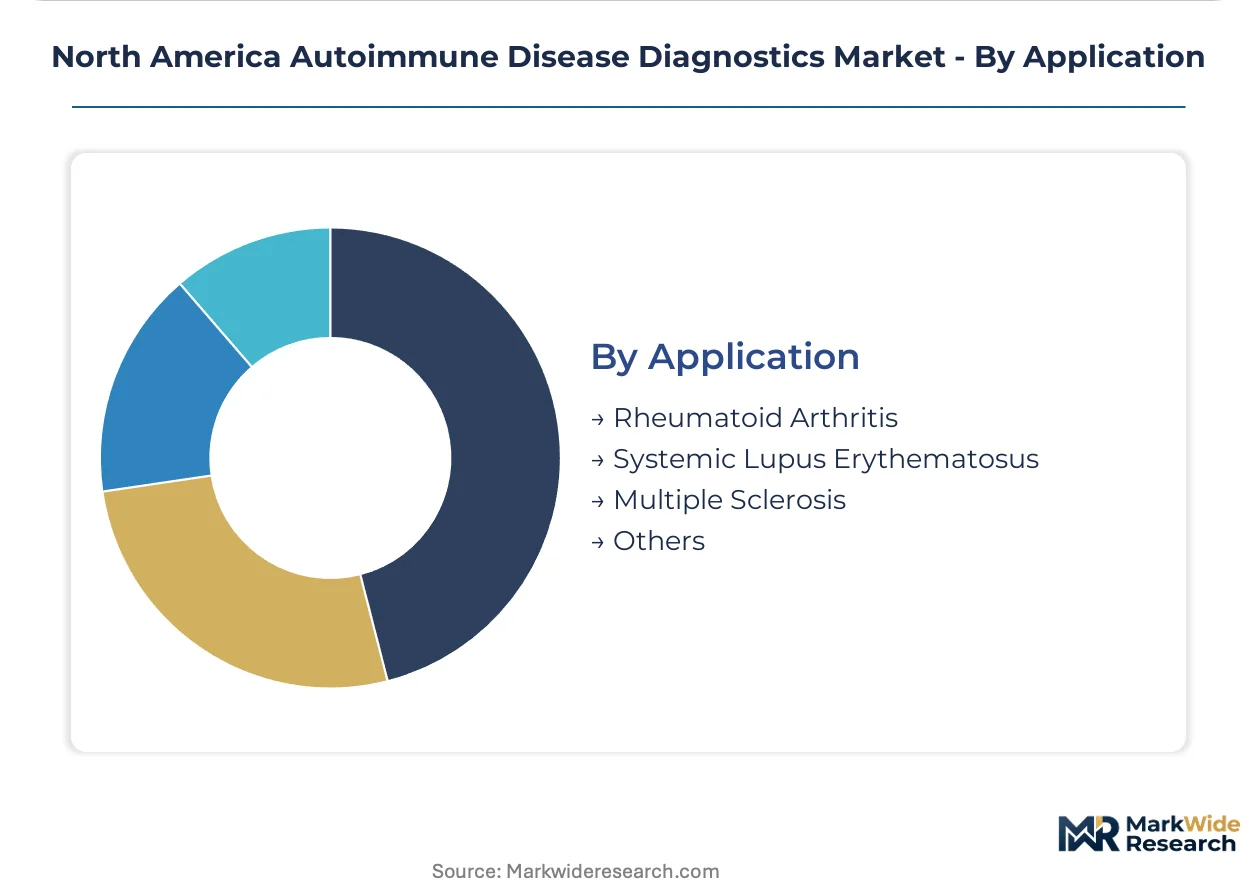
Application:
Maturity differentiation separates well-established diagnostic markets from emerging testing categories where clinical utility evidence continues accumulating.
- Rheumatoid Arthritis:Anti-CCP antibody testing achieves high diagnostic specificity for early disease detection and treatment initiation. Rheumatologists in US metropolitan markets rely on combined RF and anti-CCP panels to distinguish inflammatory arthritis subtypes.
- Systemic Lupus Erythematosus:Multi-organ involvement necessitates comprehensive autoantibody profiling beyond standard ANA screening. Lupus diagnosis requires integration of clinical criteria with serologic findings that vary across disease flares.
- Multiple Sclerosis:Cerebrospinal fluid oligoclonal banding and serum neuromyelitis optica antibody testing support differential diagnosis from other demyelinating conditions. Neurology practices in Canadian provincial health systems access centralized neuroimmunology reference services.
- Others:Celiac disease, inflammatory bowel disease, and autoimmune thyroid conditions expand addressable testing beyond rheumatology and neurology specialties. Gastroenterology and endocrinology practices generate incremental demand for tissue transglutaminase and TSH receptor antibody assays.
Rheumatoid Arthritis retains the deepest diagnostic penetration; the Others category is gaining share fastest as autoimmune testing expands into adjacent specialties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital laboratories in the United States exhibit the lowest price elasticity for high-throughput autoimmune platforms, while Canadian provincial networks and Mexican clinical facilities demonstrate greater sensitivity to capital expenditure constraints and reagent pricing structures.
United States
Integrated delivery networks in Texas and California drive volume consolidation for automated immunoassay analyzers through enterprise-wide procurement contracts. FDA oversight of laboratory-developed tests and clinical decision support software shapes validation requirements for new diagnostic platforms entering the market. The US Southeast anchors regional standardization efforts where hospital alliances have consolidated onto single-manufacturer chemistry and immunoassay systems.
Canada
Ontario and Quebec regional health systems centralize autoimmune testing volumes to capture economies of scale previously lost to reference laboratory send-outs. Health Canada's Class III and IV medical device framework imposes conformity requirements that parallel FDA validation standards for diagnostic platforms. Provincial laboratory networks in Western Canada are expanding in-house testing menus to reduce dependency on external reference services.
Mexico
Private hospital chains in Mexico City and Monterrey represent the primary demand concentration for automated autoimmune diagnostics as public sector laboratories rely on manual ELISA methods. COFEPRIS regulatory pathways for in vitro diagnostic devices create compliance timelines that favor established multinational platform vendors over emerging entrants. The Bajío Region's growing medical tourism infrastructure is attracting capital investment in diagnostic laboratory capacity.
North America Autoimmune Disease Diagnostics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in autoimmune diagnostics, with full-platform vendors controlling installed base economics while reagent-focused players compete on assay specificity and menu breadth. The competitive terrain splits between capital-intensive system manufacturers and consumables specialists, with middleware and software vendors occupying an emerging third position. Strategic moves concentrate on reagent contract consolidation across health system networks and regulatory pre-validation of multiplexed assay panels to accelerate hospital laboratory adoption.
Among US-based diversified health technology companies, Abbott Laboratories and Thermo Fisher Scientific exemplify the integrated platform archetype, while Bio-Rad Laboratories represents the specialized reagent and quality controls segment. Siemens Healthineers anchors the European multinational position with deep backward integration from assay development through automated sample processing systems. These three entities occupy positions that span the capital-to-consumables spectrum, reflecting how vendor selection criteria in hospital laboratories favor integrated procurement relationships over point-solution sourcing.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Bio-Rad Laboratories |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche |
| Quest Diagnostics |
| Biomérieux |
| Werfen Group |
| Grifols |
| Others |
Value Network & Pricing Analysis
Hospital laboratory consolidation onto high-throughput autoimmune analyzers concentrates purchasing power among integrated delivery networks, compressing price floors for reagent contracts while elevating the strategic value of enterprise-wide consumable agreements. This scale dynamic reshapes vendor economics by tethering profitability to recurring revenue streams rather than capital equipment margins.
Pricing Analysis
Reagent and consumable service contracts capture lifetime value in autoimmune diagnostics, with multi-year assay supply agreements generating recurring revenue that exceeds initial analyzer placement costs. Three-tier pricing structure across premium, standard, and economy levels segments buyers by testing volume and integration complexity. Cost compression in standard-tier ELISA reagents intensifies as open-system analyzers enable third-party sourcing. Smaller clinical laboratories in the US Southeast exhibit highest price sensitivity, while academic medical centers prioritize assay specificity over per-test economics.
Supply Chain Analysis
Port congestion on trans-Pacific trade lanes elevates inbound logistics costs for monoclonal antibody raw materials sourced from contract manufacturing organizations. Production concentrates in the United States, Germany, and China, with diagnostic-grade antibody production drawing from specialized bioreactor facilities. Critical dependencies include recombinant protein substrates, fluorescence-labeled detection antibodies, and polymerase chain reaction reagents. Single-source vulnerability in specialized immunoglobulin production creates exposure to batch variability. Distribution runs through regional health system warehouses and third-party logistics providers serving hospital laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated delivery networks in Texas and California, fragmenting vendor relationships as procurement committees consolidate enterprise-wide reagent contracts across multiple testing categories.
For Market Incumbents: Consolidate reagent contract penetration across hospital network expansions to defend against open-system substitution. Deepen backward integration into monoclonal antibody production to reduce dependency on concentrated contract manufacturing organizations. Anchor installed base economics through analyzer placement incentives that lock in long-term consumable commitments. For New Entrants and Emerging Players: Differentiate on AI-assisted pattern interpretation for indirect immunofluorescence screening, where algorithm validation gaps create white-space opportunities. Target Canadian provincial laboratory networks in Ontario and Quebec, where Health Canada Class III pathways favor US-validated platforms entering centralized procurement structures. Pursue point-of-care rheumatology clinic partnerships as a direct distribution channel bypassing hospital laboratory gatekeepers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors reagent-focused specialists with multiplexed assay menus over capital-intensive platform vendors facing replacement cycle compression. Five-to-ten year viability hinges on regulatory pre-validation capabilities for algorithm-integrated diagnostics. Acquisition targets should demonstrate FDA 510(k) submission experience for AI-assisted pattern recognition modules. Monitor FDA guidance evolution on laboratory-developed test oversight as an inflection indicator for compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Multiplexed Assay Panel Expansion | Consolidates sequential testing cascades into single orders, capturing volume from reference laboratories. |
| AI Pattern Interpretation Validation | Addresses FDA clinical decision support software requirements for algorithm-integrated diagnostic platforms. |
| Canadian Provincial Network Entry | Leverages Health Canada Class III conformity pathways to access Ontario and Quebec centralized procurement. |
| Point-of-Care Platform Development | Enables same-visit autoantibody testing in rheumatology practices, reducing hospital laboratory referral leakage. |
| Reagent Contract Enterprise Consolidation | Bundles autoimmune, infectious disease, and endocrine consumables to maximize volume-based pricing leverage. |
Research Methodology
A spread of perspectives from hospital laboratory directors, rheumatology practice administrators, GPO contracts managers, and diagnostic platform product managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, Health Canada device licensing records, CMS CLIA certification databases, and hospital procurement contract disclosures. Bottom-up testing volume estimates triangulated against top-down health system expenditure patterns.
Segmentation dimensions modeled include product type, technology platform, end-user setting, and application area across the analysis window. Analytical framework incorporated installed base dynamics, replacement cycle timing, and reagent consumption rates to derive expansion trajectories. CAGRs reflect convergence of historical volume trends, health system consolidation patterns, and regulatory pathway timelines for multiplexed assay approvals.
Decision-makers should treat outputs as directional under assumptions of continued integrated delivery network expansion and stable FDA oversight frameworks for laboratory-developed tests; material deviation would warrant model refresh. Specific risk factors include algorithm-based diagnostic guidance revisions, monoclonal antibody supply disruptions, and point-of-care platform technology shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Critical Care Diagnostics Market
Diagnostics
Allergy Diagnostics Market
Diagnostics
Global Liver Disease Diagnostics Market
Diagnostics
Global Liver Cancer Diagnostics Market
Diagnostics
Global Hepatitis Diagnostic Test Market
Diagnostics
Japan in-Vitro Diagnostics Market
Diagnostics
Clostridium Diagnostics Market
Diagnostics
Canada in-Vitro Diagnostics Market
Diagnostics
Lipid Panel Test Market
Diagnostics
Cryptococcal Antigen Lateral Flow Assay Test Market
Diagnostics
HIV/HBV/HCV Test Kits Market
Diagnostics
Europe Colorectal Cancer Diagnostics Market
Diagnostics
Diagnostic Enzymes Market
Diagnostics
Global Comprehensive Metabolic Panel Market
Diagnostics
Mycoplasma Diagnostics Market
Diagnostics
Prenatal Diagnostics Market