
 Direct Fluorescent Antibody Test Kits Market | 2026-2036
Direct Fluorescent Antibody Test Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Direct Fluorescent Antibody Test Kits Market Analytics
The end-user base for direct fluorescent antibody test kits is broadening beyond traditional hospital laboratories into decentralized diagnostic centers and pharmaceutical quality-control operations. Thermo Fisher Scientific leverages its extensive distribution infrastructure to serve high-volume clinical accounts across multiple continents. Bio-Rad Laboratories differentiates through specialized reagent systems that integrate with automated immunofluorescence platforms. Merck KGaA sustains competitive positioning by anchoring its portfolio in research-grade antibodies that feed downstream diagnostic development pipelines.
Direct fluorescent antibody test kits employ fluorochrome-conjugated antibodies that bind target antigens in tissue sections or cell smears, with visualization requiring excitation wavelengths typically between 450-495 nm for FITC or 540-580 nm for TRITC conjugates; these systems serve primarily as rapid diagnostic tools for viral and bacterial pathogen identification in clinical and veterinary settings. Diagnostic Tests command the largest revenue share within product type segments due to recurring reagent consumption in hospital laboratories, while Research Use applications exhibit the fastest expansion trajectory driven by preclinical vaccine development programs at pharmaceutical companies. Flow Cytometry technology segments capture premium pricing through instrument-reagent bundling arrangements, whereas Rapid Tests penetrate point-of-care settings where microscopy infrastructure remains unavailable.
FDA clearance requirements under the Clinical Laboratory Improvement Amendments establish performance benchmarks that shape product development timelines for manufacturers seeking United States market access, while the European Union's In Vitro Diagnostic Regulation imposes stricter clinical evidence standards that filter smaller competitors from CE-marking pathways. Stakeholders must monitor evolving regulatory convergence between FDA and notified body expectations, as divergence in analytical validation requirements threatens to fragment global product configurations and inflate compliance expenditures for multi-jurisdictional portfolios.
Market Dynamics
CLIA complexity requirements and FDA clearance timelines are compressing product development cycles, forcing manufacturers to front-load analytical validation investments before commercial launch. This regulatory gravity is reshaping competitive entry barriers across the United States market.
Growth Catalysts
- High-throughput infectious disease screening:Hospital-affiliated reference laboratories are expanding automated immunofluorescence platforms to handle rising specimen volumes from respiratory and enteric pathogen panels.
- IVDR clinical evidence standards:The European Union's stricter CE-marking pathways are filtering smaller competitors, creating acquisition targets for established kit manufacturers seeking portfolio expansion.
- Preclinical vaccine development:Pharmaceutical quality-control operations are consuming research-grade antibodies at accelerated rates to support accelerated timelines for novel viral vector programs.
Market Restraints
- Fluorochrome supply concentration:FITC and TRITC conjugate production clusters in specialized chemical manufacturers with limited geographic diversification, exposing kit makers to input cost volatility.
- Microscopy infrastructure dependency:Rapid test penetration at point-of-care settings remains constrained where excitation wavelength equipment is unavailable, limiting addressable market expansion.
- Regulatory divergence:Diverging analytical validation requirements between FDA and notified body expectations threaten to fragment global product configurations and inflate compliance expenditures.
Strategic Opportunities
- Decentralized diagnostic centers:Independent clinical laboratories in secondary United States markets remain underpenetrated by automated platform bundling arrangements that currently dominate tertiary hospital systems.
- Veterinary pathogen identification:Companion animal diagnostic networks are adopting human-clinical assay formats with species-specific antibody modifications, opening parallel revenue streams.
- Flow cytometry-instrument convergence:Reagent bundling with cell-sorting platforms is consolidating purchasing decisions at pharmaceutical research sites seeking unified procurement contracts.
Industry Challenges
- Specialized microscopy technologist scarcity:Clinical laboratories face recruitment gaps for personnel trained in fluorescence interpretation, slowing assay validation and quality assurance throughput.
- Legacy LIS integration complexity:Automated immunofluorescence platforms require middleware development to connect with existing laboratory information systems, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct Fluorescent Antibody Test Kits Market |
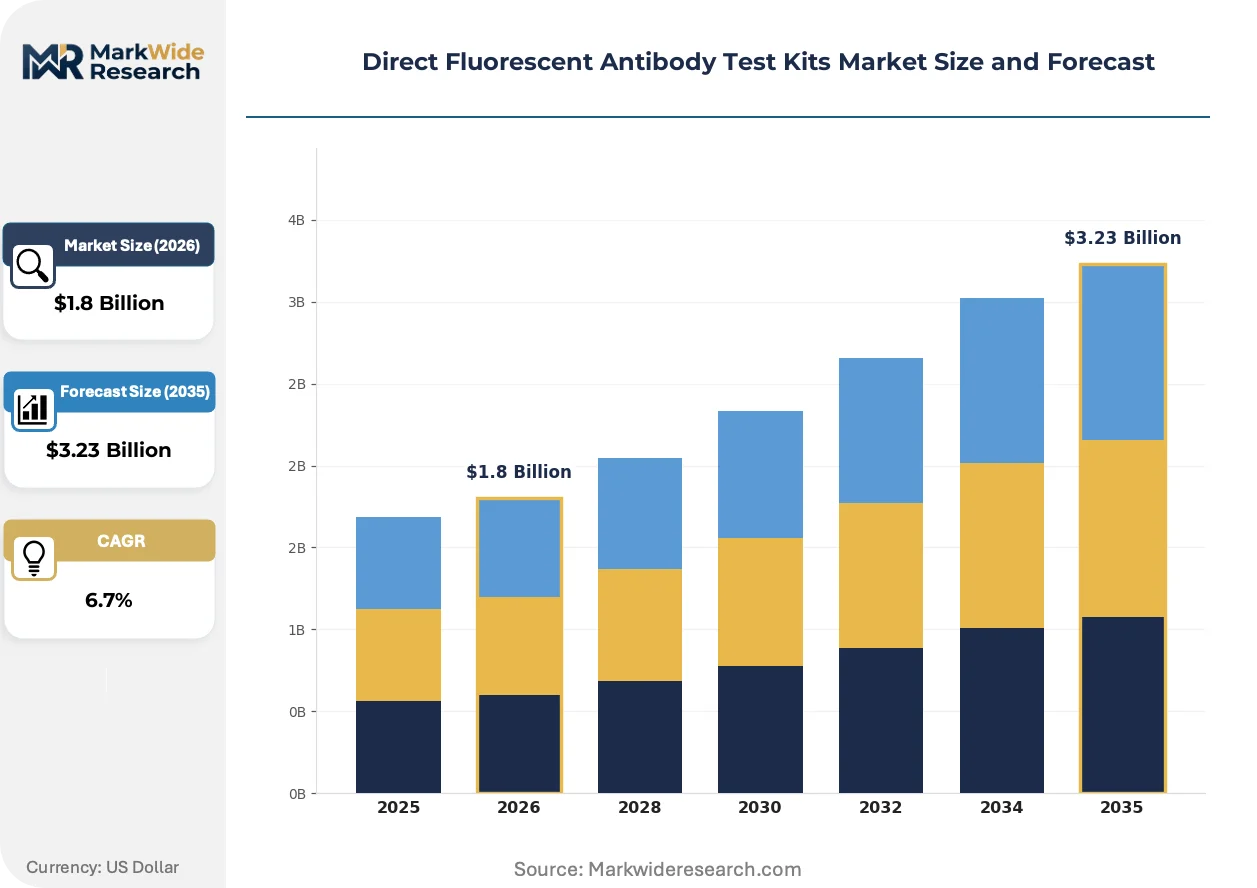
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Research Use, Diagnostic Tests, Quality Control, Environmental Monitoring End User: Clinical Laboratories, Research Institutions, Pharmaceutical Companies, Diagnostic Centers Application: Infectious Diseases, Autoimmune Disorders, Cancer Detection, Vaccine Development Technology: Immunofluorescence, Flow Cytometry, Microscopy, Rapid Tests |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Merck KGaA, Carl Zeiss AG, PerkinElmer, Abcam plc, Quidel Corporation, Leica Microsystems, OLYMPUS CORPORATION, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct Fluorescent Antibody Test Kits Market Evolving Landscape
Multiplexing capabilities and spectral unmixing algorithms are compressing the traditional workflow distinction between screening assays and confirmatory testing. This technological convergence is redrawing competitive boundaries between rapid test and flow cytometry segments.
Multiplexed fluorescent antibody panels are consolidating what were previously separate single-pathogen assays into combined respiratory or enteric screening formats. Hospital laboratories with high-throughput infectious disease screening needs are adopting these consolidated workflows to reduce reagent inventory complexity and technologist hands-on time. The structural consequence is compressing pricing power for standalone single-analyte kits as bundled multiplex offerings capture larger share of laboratory budgets.
The European Union's In Vitro Diagnostic Regulation imposes stricter clinical evidence standards than predecessor directives, extending CE-marking timelines for novel assay introductions. Manufacturers are responding by prioritizing portfolio rationalization, discontinuing low-volume SKUs rather than funding retrospective clinical studies. Smaller competitors without dedicated regulatory affairs infrastructure are exiting the European market, concentrating supply among multi-jurisdictional portfolio holders.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships at United States hospital-affiliated reference laboratories. These buying collectives are unbundling instrument-reagent contracts to negotiate separate pricing for high-volume consumables, compressing margin structures that previously subsidized platform placement. The shift is most visible in multi-hospital health systems where laboratory standardization mandates override individual site preferences.
Direct Fluorescent Antibody Test Kits Market Segmentation
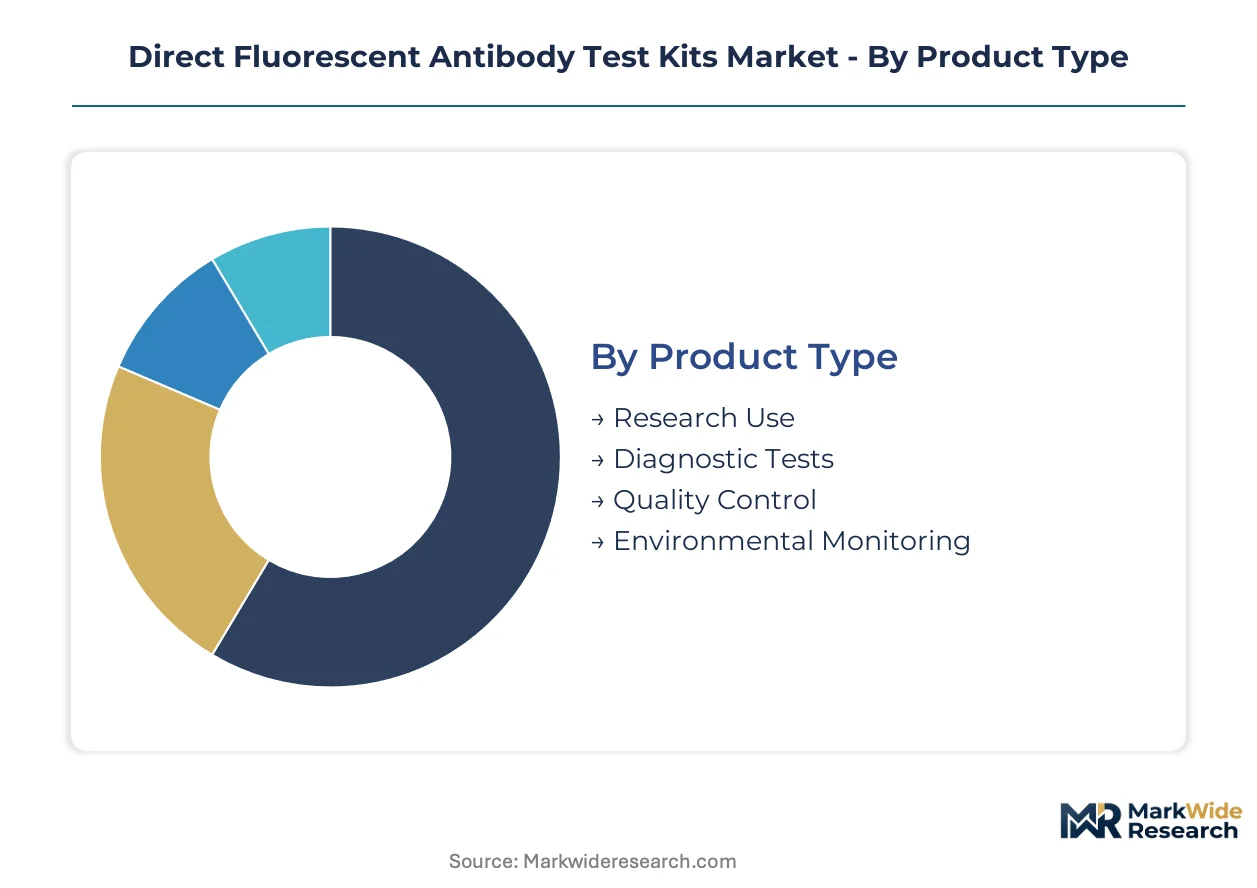
Segmentation in direct fluorescent antibody test kits reveals distinct capital requirements and regulatory pathways across product configurations. Manufacturers must align development investments with the specific compliance burdens and instrumentation needs of each segment cluster.
Product Type:
Capital intensity varies sharply across product types, with diagnostic tests demanding the heaviest upfront investment in FDA clearance and CLIA validation infrastructure.
- Research Use:Antibody conjugates formulated for preclinical investigations require less regulatory documentation but demand rigorous lot-to-lot consistency for reproducible data. Pharmaceutical quality-control operations in Massachusetts and North Carolina consume these reagents at accelerated rates to support viral vector program timelines.
- Diagnostic Tests:FDA-cleared kits for clinical pathogen identification carry the steepest analytical validation burden, with manufacturers front-loading clinical studies before commercial launch. Hospital-affiliated reference laboratories in high-throughput screening configurations represent the concentrated demand base for these regulated products.
- Quality Control:Standardized reagent panels for bioprocessing monitoring.
- Environmental Monitoring:Specialized conjugates for water and food safety surveillance.
Diagnostic Tests absorb the bulk of installed capacity; Research Use is expanding most quickly.
End User:
Customer type determines purchasing modality, with consolidated procurement patterns diverging sharply between institutional buyers and decentralized operators.
- Clinical Laboratories:Hospital-affiliated reference laboratories drive volume through automated platform standardization mandates. Group purchasing organizations in multi-hospital health systems are unbundling instrument-reagent contracts to negotiate separate consumable pricing, compressing margin structures.
- Research Institutions:Academic medical centers and government laboratories prioritize antibody specificity and publication-grade documentation over cost optimization. Preclinical vaccine development programs at these sites are consuming research-grade antibodies at accelerated rates.
- Pharmaceutical Companies:Unified procurement contracts for reagent-instrument bundling.
- Diagnostic Centers:Independent clinical laboratories in secondary markets seeking automated platform access.
Clinical Laboratories dominate current revenue concentration; Diagnostic Centers are climbing the fastest as point-of-care networks expand.
Application:
Application focus shapes the technical specification stack, with infectious disease panels requiring the broadest pathogen coverage and autoimmune assays demanding the highest specificity thresholds.
- Infectious Diseases:Respiratory and enteric pathogen panels require multiplexed fluorescent antibody configurations to consolidate previously separate single-analyte workflows. Hospital laboratories are adopting these combined formats to reduce reagent inventory complexity and technologist hands-on time.
- Vaccine Development:Viral vector characterization and immunogenicity assessment drive demand for research-grade conjugates with defined epitope specificity. Preclinical programs at pharmaceutical sites are accelerating consumption timelines for these specialized reagents.
- Autoimmune Disorders:Antinuclear antibody and related autoantibody detection with stringent specificity requirements.
- Cancer Detection:Tumor marker identification and minimal residual disease monitoring applications.
Infectious Diseases commands the largest share of current kit shipments; Vaccine Development is gaining share fastest as novel platform programs advance.
Technology:
Technology platform selection locks customers into specific instrumentation ecosystems, with flow cytometry creating the stickiest vendor relationships through cell-sorter bundling arrangements.
- Flow Cytometry:Instrument-reagent bundling with cell-sorting platforms consolidates purchasing decisions at pharmaceutical research sites seeking unified procurement contracts. These configurations capture premium pricing through integrated software and calibration standard packages.
- Rapid Tests:Lateral flow and cartridge-based formats penetrate point-of-care settings where microscopy infrastructure remains unavailable. Penetration constraints persist where excitation wavelength equipment is absent, limiting addressable market expansion in resource-limited configurations.
- Immunofluorescence:Traditional slide-based assays with direct conjugate binding for clinical pathology.
- Microscopy:Manual and automated imaging systems for fluorescence interpretation.
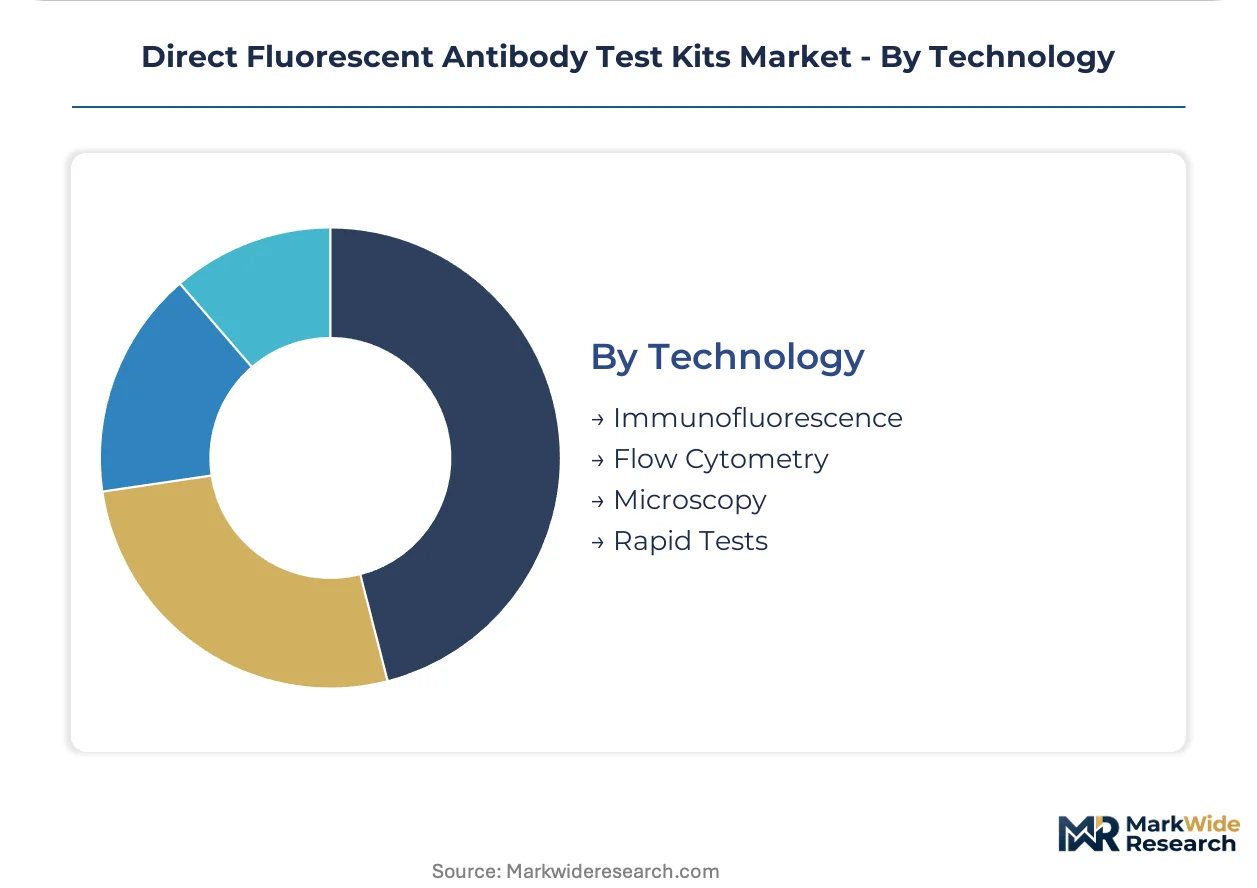
Immunofluorescence retains the broadest installed base; Flow Cytometry shows the steepest expansion trajectory as pharmaceutical research budgets concentrate in cell analysis platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fluorochrome production concentrates in German and Swiss chemical manufacturers, creating input dependencies that shape kit assembly economics across North American and Asian diagnostic markets.
United States
FDA clearance pathways under CLIA complexity requirements drive analytical validation investments for manufacturers targeting hospital-affiliated reference laboratories. The agency's 510(k) premarket notification process compresses development timelines for automated immunofluorescence platforms. Massachusetts and North Carolina pharmaceutical clusters consume research-grade antibodies at accelerated rates for viral vector program support.
Germany
The EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence standards than predecessor directives, extending CE-marking timelines for novel assay introductions. Manufacturers prioritize portfolio rationalization, discontinuing low-volume SKUs rather than funding retrospective clinical studies. Baden-Württemberg's precision optics corridor supplies excitation wavelength equipment to diagnostic laboratories across the European Union.
China
NMPA medical device registration requirements for imported diagnostic reagents create compliance barriers for foreign kit manufacturers seeking domestic hospital access. The national pharmaceutical regulator mandates local clinical trial data for Class III in vitro diagnostic approvals. Shanghai and Suzhou biotech parks host contract research organizations facilitating multinational analytical validation studies.
Japan
PMDA quality management system inspections for foreign manufacturers extend market entry timelines for fluorescent antibody test kits. METI's healthcare technology assessment frameworks influence reimbursement pathways for automated diagnostic platforms. Tokyo and Osaka metropolitan laboratory networks standardize on instrument-reagent bundling arrangements from established multinational suppliers.
India
CDSCO medical device rules classify fluorescent antibody test kits as Class C or D devices requiring import licenses and local testing for registration. The country's national pharmaceutical regulator has streamlined approval pathways for diagnostics manufactured in special economic zones. Hyderabad and Bangalore contract research organizations support preclinical vaccine development programs consuming research-grade conjugates.
Direct Fluorescent Antibody Test Kits Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue point-of-care rapid test formats and veterinary pathogen identification applications. The market structure consolidates around three to five multinational portfolio holders with dedicated regulatory affairs infrastructure, filtering smaller competitors from CE-marking pathways. Strategic archetypes include diversified life science conglomerates with extensive distribution infrastructure, specialized reagent system developers integrating with automated platforms, and research-grade antibody suppliers feeding downstream diagnostic pipelines. Dominant competitive moves center on instrument-reagent bundling arrangements and geographic expansion through acquisition of regional regulatory expertise.
Within the diversified conglomerate tier, Thermo Fisher Scientific exemplifies scale-driven platform standardization across high-volume clinical accounts. Bio-Rad Laboratories occupies a position among specialized reagent system developers, while Merck KGaA anchors the research-grade antibody supply segment. These three entities represent distinct competitive vectors: distribution infrastructure depth, automated platform integration capability, and upstream antibody development expertise.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Merck KGaA |
| Carl Zeiss AG |
| PerkinElmer |
| Abcam plc |
| Quidel Corporation |
| Leica Microsystems |
| OLYMPUS CORPORATION |
| Others |
Value Network & Pricing Analysis
Fluorescence microscopy technologist scarcity in Massachusetts and North Carolina widens labor-cost differentials between automated platform tiers and manual assay configurations, compressing margin spreads at the economy end while premium bundled systems capture pricing power through certified operator requirements.
Pricing Analysis
High-volume consumables in hospital-affiliated reference laboratories trade at thin margins subsidized by instrument placement contracts, while low-volume research-grade antibody conjugates sustain premium positioning through lot-specific certification documentation. Price differentiation hinges on FDA clearance tier and analytical validation depth, with CLIA moderate-complexity kits commanding substantial premiums over research-use-only equivalents. Cost compression in the standard tier intensifies as group purchasing organizations unbundle instrument-reagent arrangements and negotiate consumable pricing separately. Point-of-care rapid test buyers exhibit highest price sensitivity due to limited reimbursement pathways, whereas pharmaceutical quality-control operations prioritize antibody specificity over unit cost optimization.
Supply Chain Analysis
Fluorochrome conjugate production rests on German and Swiss specialty chemical manufacturers with limited geographic diversification, exposing kit assemblers to input cost volatility when feedstock supplies tighten. FITC and TRITC dye synthesis, antibody purification media, and excitation wavelength calibration standards draw from concentrated European supply bases. Single-source vulnerability in fluorochrome intermediates creates procurement risk during regulatory inspections or force majeure events at Baden-Württemberg production facilities. Distribution runs through multinational life science distributors serving hospital laboratories and direct manufacturer relationships with pharmaceutical research sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance burdens under FDA and IVDR frameworks are filtering smaller competitors from CE-marking pathways, positioning the market as a consolidation play where dedicated regulatory affairs infrastructure determines survival.
For Market Incumbents: Hedge against margin compression by deepening backward integration into antibody production and securing captive fluorochrome supply arrangements with German chemical manufacturers. Prioritize CLIA high-complexity certification investments to defend positioning against automated platform competitors. Consolidate procurement relationships with multi-hospital health systems before group purchasing organizations complete vendor rationalization programs. For New Entrants and Emerging Players: Independent clinical laboratories in secondary United States markets represent an underserved buyer archetype with limited automated platform penetration and unmet demand for rapid respiratory pathogen panels. Veterinary diagnostic networks adopting human-clinical assay formats with species-specific modifications offer parallel revenue streams with lighter regulatory burdens. Pursue white-label manufacturing partnerships with established CE-mark holders to bypass direct IVDR clinical evidence requirements. For Investors and Strategic Acquirers: Re-rating potential sits with specialized reagent developers possessing automated platform integration capabilities given the accelerating shift toward unified procurement contracts at pharmaceutical research sites. Long-term viability favors entities with dual FDA-IVDR regulatory infrastructure spanning diagnostic and research use portfolios. Watch for inflection signals in preclinical viral vector program funding announcements from Massachusetts and North Carolina biotech clusters.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR CE Marking Pathway | European market access now requires retrospective clinical studies that smaller competitors cannot fund. |
| Automated Platform Integration | Instrument-reagent bundling consolidates purchasing decisions at hospital-affiliated reference laboratories. |
| Backward Integration into Antibody Production | In-house conjugate manufacturing reduces dependency on European fluorochrome suppliers and stabilizes input costs. |
| Veterinary Pathogen Panel Development | Companion animal diagnostic networks adopt human-clinical formats with species-specific modifications. |
| Multiplexed Assay Consolidation | Combined respiratory and enteric panels reduce reagent inventory complexity for high-throughput screening operations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with clinical laboratory directors, regulatory affairs specialists at diagnostic manufacturers, biomedical engineers at pharmaceutical quality-control operations, and group purchasing organization contracts managers. FDA 510(k) premarket notification databases, EMA IVDR technical documentation summaries, and import-export records for fluorochrome conjugates provided demand-side calibration points. Bottom-up kit shipment estimates triangulated against top-down laboratory capital expenditure surveys.
Reconciliation of instrument placement data with consumable throughput assumptions shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user configuration, application focus, and technology platform, with additional granularity on CLIA complexity classification and regional regulatory cluster. CAGRs derived from fitted growth curves applied to validated base-year estimates, incorporating pharmaceutical viral vector program pipeline data and hospital laboratory automation adoption curves as industry-specific forecast inputs.
Revisions become necessary when IVDR implementation timelines shift, fluorochrome supply disruptions materialize, or CLIA complexity reclassification alters competitive entry barriers. Forecasts reflect documented assumptions regarding regulatory convergence between FDA and notified body expectations. A small set of named triggers warrants ongoing watch: group purchasing organization vendor consolidation announcements, preclinical vaccine development funding inflections, and European fluorochrome manufacturer capacity expansion decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Fructosamine Test Market
Diagnostics
Home Diagnostics Market
Diagnostics
Global Hepatitis Diagnostic Test Market
Diagnostics
Global Yersiniosis Diagnostics and Treatment Market
Diagnostics
Psychosis Diagnostics Market
Diagnostics
Europe Colorectal Cancer Diagnostics Market
Diagnostics
Bilirubin Blood Test Market
Diagnostics
Global Stroke Diagnostics Market
Diagnostics
Global Blood Transfusion Diagnostics Market
Diagnostics
Global Neurodiagnostics Market
Diagnostics
Global Autoimmune Disease Diagnostics Market
Diagnostics
In-Vitro Diagnostics Enzymes Market
Diagnostics
Global Rheumatoid Arthritis Diagnostic Tests Market
Diagnostics
Global Prostate Specific Antigen (PSA) Test Market
Diagnostics
France in-Vitro Diagnostics Market
Diagnostics
Veterinary Diagnostics Market