
 Middle East and Africa in-Vitro Diagnostics Market | 2026-2036
Middle East and Africa in-Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa in-Vitro Diagnostics Market Outlook
CE-IVDR certification tier is bifurcating the Middle East and Africa in-Vitro Diagnostics Market into compliant and non-compliant supply channels. Abbott Laboratories leverages its pre-existing regulatory dossiers to sustain premium positioning across Gulf Cooperation Authority tender processes. bioMérieux SA anchors its regional footprint through localized reagent production in Morocco, while Sysmex Corporation competes aggressively on hematology automation in South African public hospital networks.
In-Vitro Diagnostics encompasses reagent-driven analytical systems, benchtop instruments, and companion software used to detect disease markers, pathogens, and metabolic conditions outside living organisms. These systems typically operate through photometric, electrochemical, or nucleic acid amplification principles to deliver quantitative diagnostic outputs for clinical decision-making. Reagents command the dominant margin pool due to recurring purchase obligations tied to installed instrument bases, while PCR technology segments are capturing accelerated capital allocation as molecular laboratory infrastructure expands across the region. Hospital end users concentrate procurement volume through centralized tender systems, though home care channels are emerging as a structural growth vector in diabetes monitoring and infectious disease self-testing protocols.
Saudi Food and Drug Authority and South African Health Products Regulatory Authority standards are tightening import clearance requirements for IVD kits, compelling manufacturers to submit localized stability data and Arabic labeling documentation. CE-IVDR technical documentation obligations are filtering into Gulf procurement specifications, effectively extending European regulatory gravity into Middle Eastern purchasing decisions. Stakeholders must monitor divergent national registration timelines and pre-qualification pathways, as fragmented regulatory reciprocity across the region continues to shape market access economics and distribution partner selection criteria.
Market Dynamics
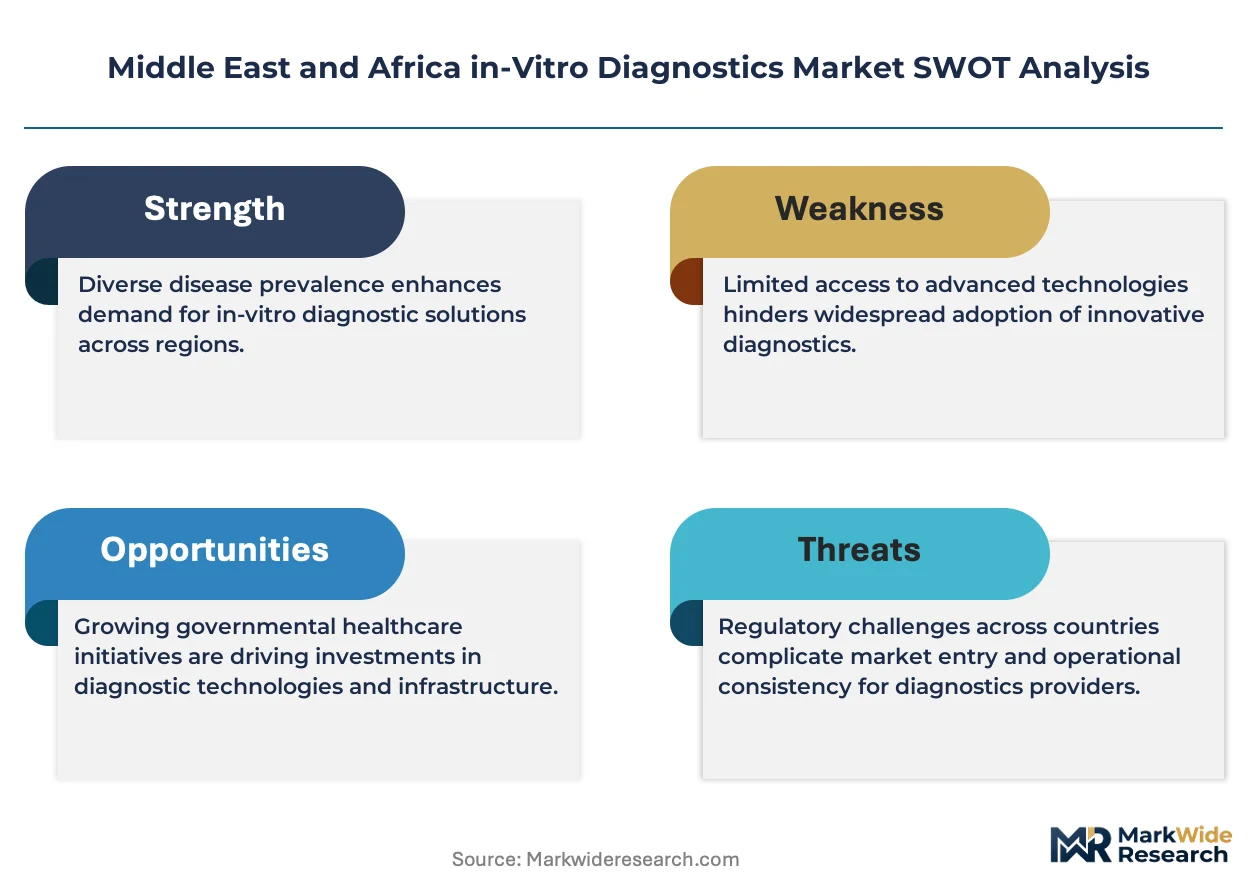
CE-IVDR certification requirements are compressing supply channels across the Middle East and Africa, bifurcating procurement flows into compliant and non-compliant tiers while reshaping distributor selection criteria and tender eligibility.
Growth Catalysts
- Saudi Food and Drug Authority localization mandates:Import clearance rules now require Arabic labeling and stability data, creating captive demand for regional regulatory expertise and compliant manufacturing partnerships.
- Molecular testing infrastructure expansion:PCR-based infectious disease panels are capturing disproportionate capital allocation in Nigeria and Kenya as tuberculosis-HIV co-detection protocols gain regulatory traction.
- National health insurance reforms:South Africa's procurement centralization is redirecting volume toward hospital-based laboratories with expanded molecular testing menus.
Market Restraints
- Reagent cost volatility:Recurring purchase obligations tied to installed instrument bases concentrate margin extraction with upstream chemical suppliers, squeezing mid-tier distributor economics.
- Regulatory fragmentation:Divergent national registration timelines across Gulf Cooperation Authority member states and sub-Saharan markets compound compliance overhead without reciprocity mechanisms.
- Technical limitation in cold chain:Temperature-sensitive reagent stability requirements restrict rural penetration and last-mile distribution reach in thermally challenging climates.
Strategic Opportunities
- Underpenetrated home care channels:Diabetes monitoring and infectious disease self-testing protocols are emerging as structural growth vectors outside hospital procurement systems.
- CE-IVDR regulatory tailwind:Gulf procurement specifications are filtering European technical documentation obligations into tender requirements, advantaging pre-certified suppliers.
- Technology convergence:Photometric and electrochemical detection principles are merging with companion software platforms to enable point-of-care quantitative outputs.
Industry Challenges
- Certification timeline compression:South African Health Products Regulatory Authority pre-qualification pathways and Saudi Food and Drug Authority dossier reviews are extending time-to-revenue for new entrants.
- Integration complexity with legacy hematology systems:Automation upgrades in public hospital networks require interoperability with existing benchtop instruments and reagent supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa in-Vitro Diagnostics Market |
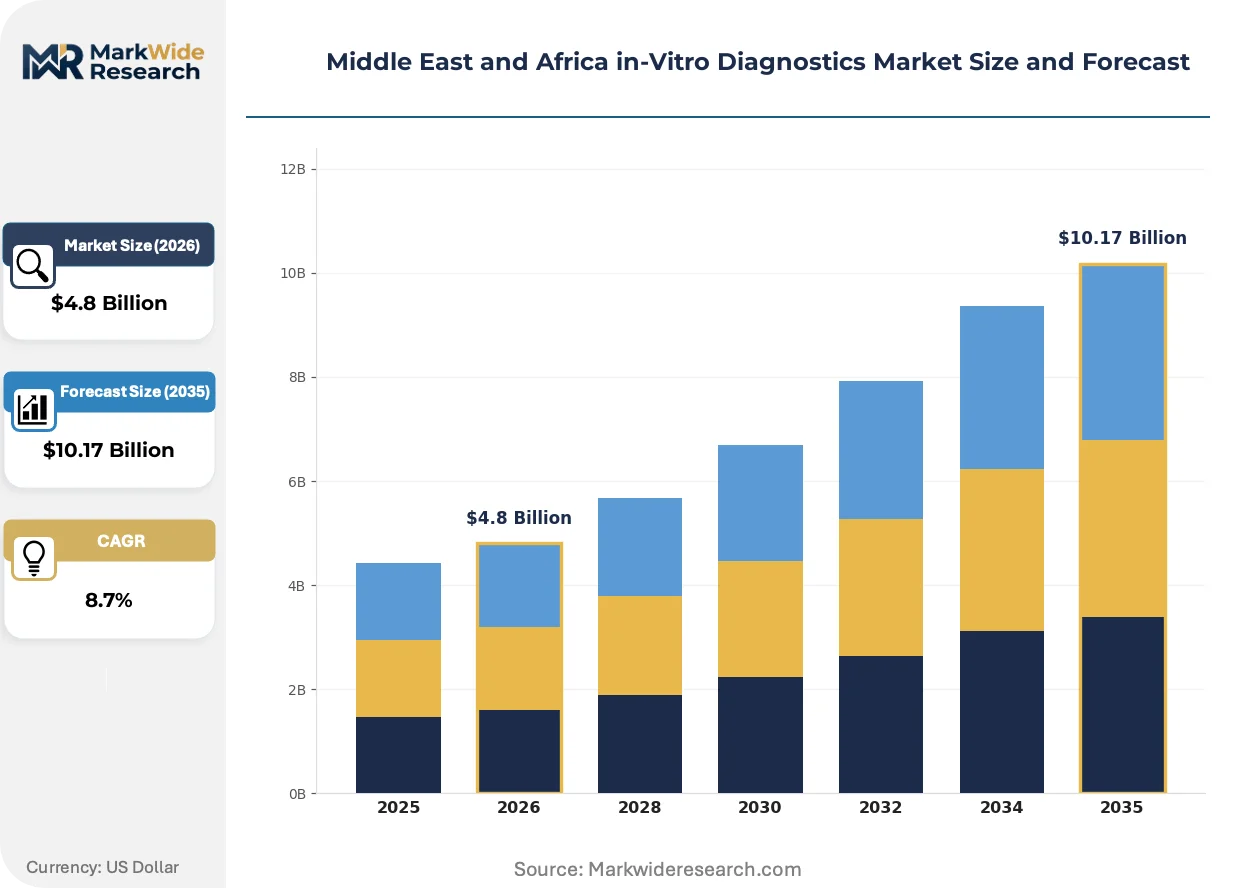
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Accessories Application: Clinical Diagnostics, Blood Testing, Pathology, Drug Discovery End User: Hospitals, Laboratories, Home Care, Clinics Technology: ELISA, PCR, Fluorescence, Microarray |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Becton Dickinson and Company, Sysmex Corporation, bioMérieux SA, Siemens Healthineers AG, Danaher Corporation, Bio-Rad Laboratories, Thermo Fisher Scientific Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa in-Vitro Diagnostics Market Strategic Shifts
Digital connectivity and decentralized testing architectures are redistributing diagnostic value capture away from centralized laboratories toward distributed care settings and patient-directed monitoring ecosystems.
Multiplex PCR platforms are fragmenting infectious disease testing workflows by consolidating tuberculosis, HIV, and hepatitis detection into single-run panels. Hospital-based laboratories in Kenya and Nigeria are adopting these systems to reduce turnaround times and reagent inventory complexity. The technology is fragmenting volume concentration previously held by reference laboratories into mid-sized clinical sites with moderate throughput requirements.
Saudi Food and Drug Authority import clearance tightening is extending European regulatory gravity into Gulf procurement decisions. Manufacturers must now submit localized stability data and Arabic labeling documentation to maintain tender eligibility. Hematology and molecular testing segments are responding by pre-positioning regulatory dossiers before national insurance reform implementation.
Centralized tender systems in South Africa are concentrating procurement volume through hospital networks while squeezing distributor margins. Direct manufacturer engagement with procurement authorities is displacing traditional multi-tier distribution for high-value instrument contracts. This channel compression is most visible in hematology automation and PCR platform acquisitions within public hospital networks.
Middle East and Africa in-Vitro Diagnostics Market Segmentation
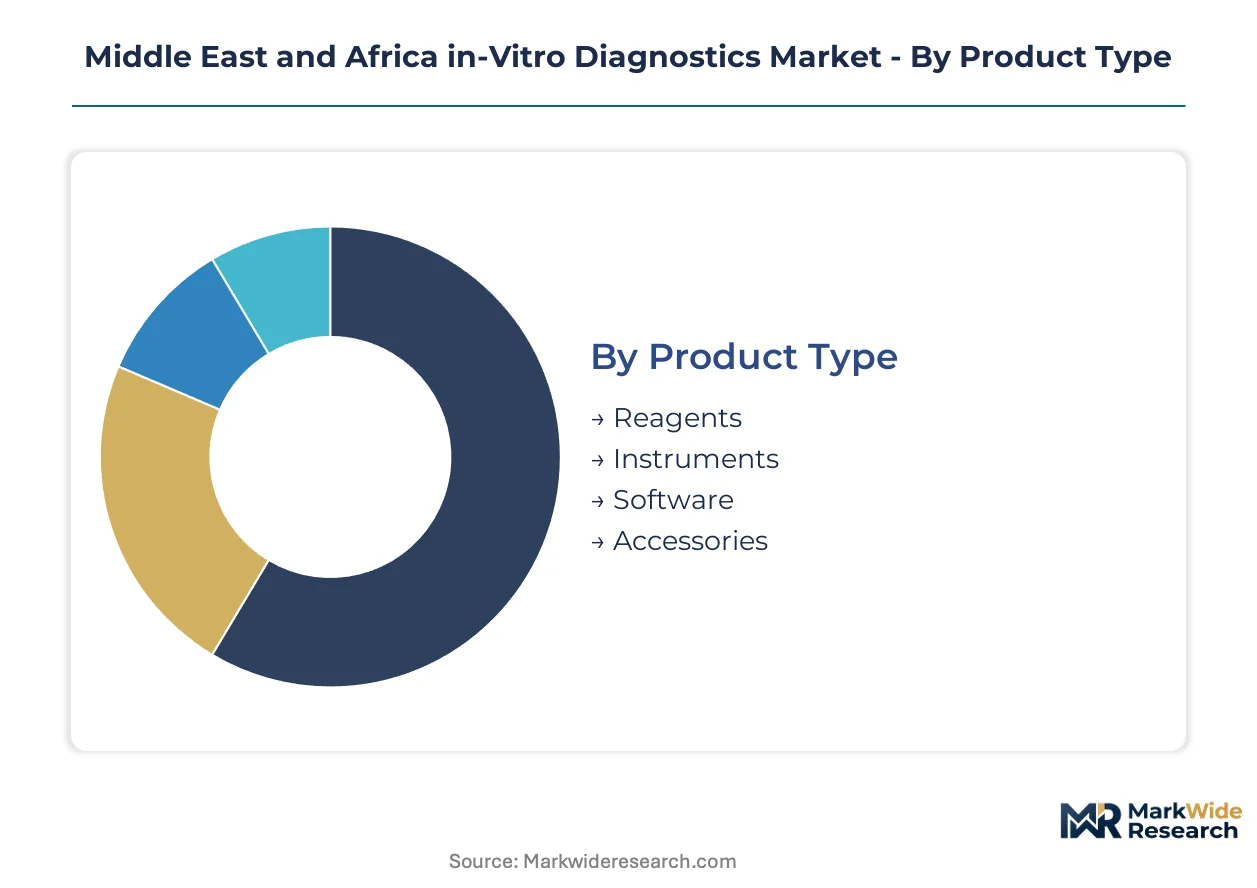
Segmentation in the Middle East and Africa in-Vitro Diagnostics Market reveals how procurement centralization, regulatory tiering, and infrastructure gaps reshape competitive positioning across product categories and end-use channels. Understanding these divisions exposes where substitution pressures and margin extraction concentrate.
Product Type:
Reagent-driven business models face intensifying substitution pressure from open-system consumables and third-party compatible chemistries that erode manufacturer lock-in.
- Reagents:These consumable chemical preparations include antibodies, enzymes, nucleic acid probes, and calibration standards required for assay execution. Procurement in Saudi Arabia and South Africa concentrates through hospital tender systems that bundle multi-year reagent supply with instrument placement. SFDA localization mandates for Arabic labeling and stability documentation create compliance barriers that protect incumbent suppliers from gray-market substitution.
- Instruments:Analytical hardware spans photometric readers, thermal cyclers, hematology analyzers, and automated sample processors. Kenyan and Nigerian public health programs are prioritizing PCR platform acquisitions with tuberculosis-HIV co-detection capabilities. Capital constraints across sub-Saharan markets sustain demand for refurbished and entry-tier systems despite performance trade-offs.
- Software:Laboratory information management systems and instrument control interfaces enable workflow automation and regulatory data integrity. Integration requirements with legacy hospital IT infrastructure slow adoption outside Gulf Cooperation Authority tertiary centers.
- Accessories:Pipette tips, reaction vessels, and sample collection devices complete testing workflows. Price sensitivity in distributed primary care settings drives procurement toward lowest-unit-cost suppliers regardless of brand alignment.
Reagents retain volume leadership; software holds the steepest expansion curve as laboratory digitization accelerates.
Application:
Cost tier differentiation separates premium molecular diagnostics from commoditized screening assays, with reimbursement policy determining viable price floors.
- Clinical Diagnostics:Routine chemistry, immunoassay, and hematology testing for disease monitoring and therapeutic management. South Africa's national health insurance reforms are centralizing high-volume testing into designated hospital laboratories while squeezing peripheral clinic margins.
- Blood Testing:Transfusion screening, coagulation profiling, and blood component quality verification. Saudi Arabia's SFDA mandates increasingly align with CE-IVDR technical documentation standards, filtering European regulatory requirements into Gulf procurement specifications.
- Pathology:Tissue-based diagnostics including histology, cytology, and immunohistochemistry for cancer classification. Pathologist scarcity across the region concentrates service delivery in urban academic medical centers.
- Drug Discovery:Biomarker validation and companion diagnostic development supporting pharmaceutical clinical trials. Activity clusters in South Africa and Morocco where contract research organizations serve multinational sponsors.
Clinical diagnostics commands procurement volume; drug discovery shows the most rapid expansion as regional trial infrastructure matures.
End User:
Customer type determines channel economics, with centralized hospital tenders extracting price concessions unavailable to fragmented clinic purchasers.
- Hospitals:Tertiary and secondary medical centers with integrated laboratory departments performing high-complexity testing. Public hospital networks in Kenya and Nigeria are expanding molecular testing menus through development finance institution capital injections.
- Laboratories:Independent diagnostic service providers and reference laboratories serving outpatient and institutional clients. South African pathology groups are consolidating to defend margin position against national health insurance procurement centralization.
- Home Care:Patient-directed glucose monitoring, infectious disease self-testing, and anticoagulation management. Diabetes prevalence in Gulf Cooperation Authority states drives retail channel expansion for self-monitoring blood glucose systems.
- Clinics:Primary care and specialty outpatient facilities with limited on-site testing capability. Cold chain limitations and reagent shelf-life constraints restrict rural clinic access to temperature-sensitive assays.
Hospitals dominate absolute demand; home care channels are climbing the fastest as chronic disease self-management protocols proliferate.
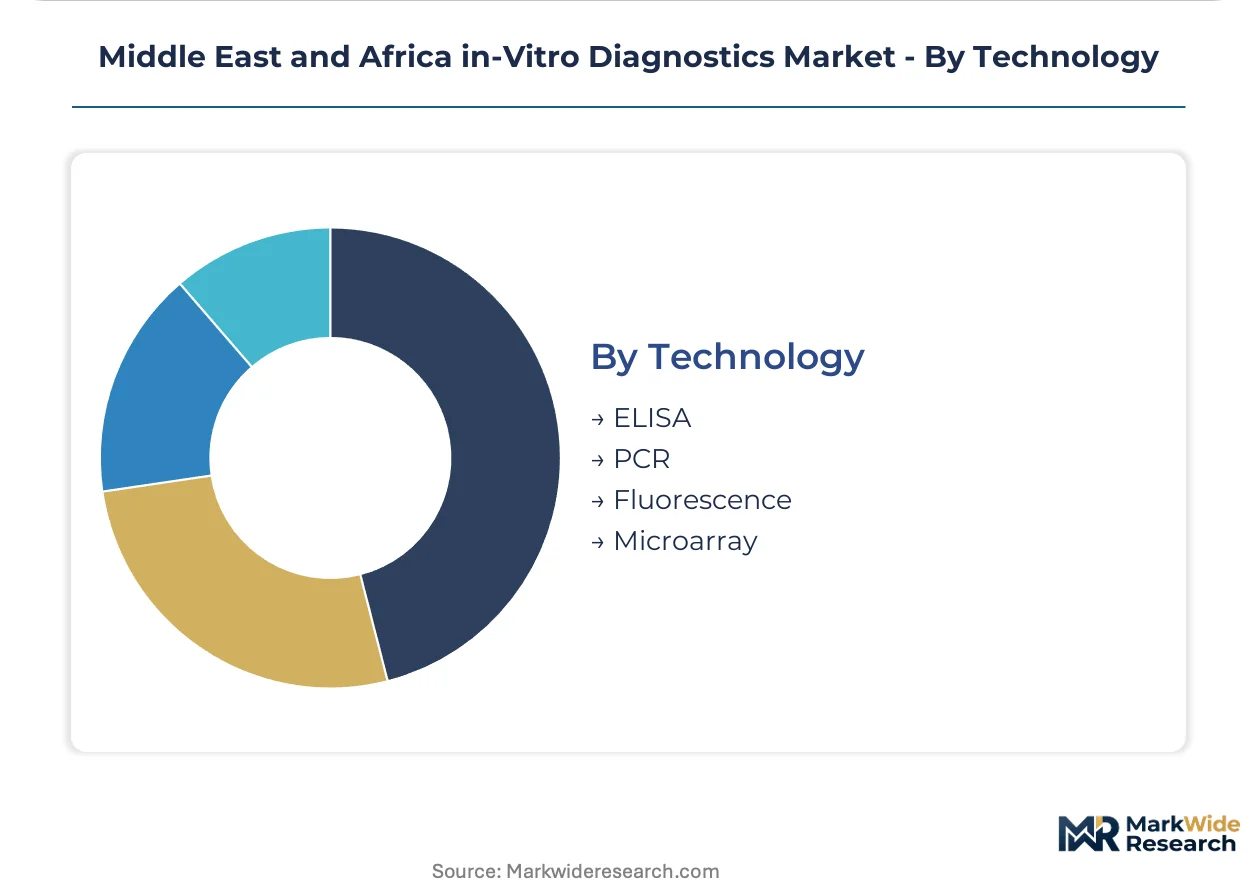
Technology:
Supply concentration in PCR thermal cycler manufacturing creates procurement bottlenecks, while fluorescence and microarray platforms compete for capital allocation in mid-tier laboratories.
- ELISA:Enzyme-linked immunosorbent assay platforms for antibody and antigen detection in infectious disease and autoimmune screening. Mature technology with established supply chains sustains dominance in resource-constrained settings despite longer turnaround times.
- PCR:Polymerase chain reaction systems enabling nucleic acid amplification for pathogen detection and genetic analysis. Multiplex tuberculosis-HIV-hepatitis panels are fragmenting volume concentration from reference laboratories into mid-sized Kenyan and Nigerian hospital sites.
- Fluorescence:Fluorometric detection methods for quantitative immunoassay and cell-based analysis. Point-of-care instrument miniaturization is expanding deployment beyond centralized laboratory settings.
- Microarray:High-density nucleic acid probe arrays for parallel genetic variant detection and expression profiling. Complexity and interpretive expertise requirements limit adoption to South African academic medical centers and Gulf tertiary institutions.
ELISA maintains installed base leadership; PCR platforms are gaining share fastest as molecular infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across the Middle East and Africa in-Vitro Diagnostics Market. Gulf Cooperation Authority states absorb premium-tier instrument pricing through centralized procurement budgets, while sub-Saharan buyers prioritize reagent cost-per-test minimization over system sophistication.
Saudi Arabia
SFDA import clearance tightening drives localization partnerships for Arabic labeling compliance. The national regulator now mandates stability data submission for IVD kit registration, extending European CE-IVDR documentation requirements into tender specifications. Riyadh-based hospital networks concentrate molecular testing infrastructure investment ahead of national insurance reform implementation.
South Africa
National health insurance reforms centralize high-volume diagnostic procurement through designated hospital laboratories. SAHPRA pre-qualification pathways extend time-to-revenue for new market entrants. Johannesburg and Cape Town academic medical centers anchor pathology service delivery where specialist scarcity constrains rural expansion.
Nigeria
Tuberculosis-HIV co-detection protocols capture development finance institution capital for PCR platform deployment. The national regulator maintains fragmented registration timelines without Gulf-style reciprocity mechanisms. Lagos and Abuja hospital networks fragment infectious disease testing volume from reference laboratories into mid-sized clinical sites.
Kenya
Public health programs prioritize multiplex PCR acquisitions with single-run tuberculosis-HIV-hepatitis capabilities. Ministry of Health procurement specifications align with WHO pre-qualification standards rather than European regulatory frameworks. Nairobi laboratory clusters concentrate molecular infrastructure while cold chain limitations restrict rural reagent distribution.
United Arab Emirates
MOHAP standards increasingly incorporate CE-IVDR technical documentation into import clearance criteria. Dubai and Abu Dhabi tertiary centers drive hematology automation demand through centralized tender systems. Private hospital networks absorb premium instrument pricing while government procurement emphasizes total cost-of-ownership reagent contracts.
Middle East and Africa in-Vitro Diagnostics Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa in-Vitro Diagnostics Market. Multinational manufacturers with pre-existing regulatory dossiers capture premium-tier Gulf tenders, while regional distributors and refurbished equipment suppliers serve price-constrained sub-Saharan demand. The competitive structure separates into three strategic archetypes: CE-IVDR-certified premium suppliers, localized reagent manufacturers, and cost-optimized distribution intermediaries. Consolidation pressure concentrates around hematology automation and molecular platform segments, while reagent-compatible third-party chemistries erode manufacturer lock-in economics.
Within the premium-tier certified segment, Abbott Laboratories and bioMérieux SA exemplify archetypes leveraging pre-positioned regulatory documentation to sustain tender eligibility across Gulf Cooperation Authority procurement cycles. Sysmex Corporation occupies a position representing hematology automation specialists competing aggressively in South African public hospital network upgrades. These three entities anchor distinct competitive vectors: regulatory dossier depth, localized production infrastructure, and instrument-reagent bundled contracting.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Becton Dickinson and Company |
| Sysmex Corporation |
| bioMérieux SA |
| Siemens Healthineers AG |
| Danaher Corporation |
| Bio-Rad Laboratories |
| Thermo Fisher Scientific Inc. |
| Others |
Value Chain & Pricing Dynamics
Open-system reagent chemistries replacing manufacturer-locked consumables are redrawing procurement geography across the Middle East and Africa, compressing margin pools in Gulf Cooperation Authority tenders while opening price-accessible pathways for Kenyan and Nigerian hospital networks previously excluded from premium supply tiers.
Pricing Analysis
After-sales reagent contracts and multi-year service bundles capture lifetime value exceeding instrument sale margins by substantial multiples. Three-tier pricing structure across premium CE-IVDR-certified, standard WHO-prequalified, and economy refurbished-equipment levels separates Gulf hospital tenders from sub-Saharan clinic procurement. Cost compression in economy tiers intensifies as third-party compatible chemistries erode manufacturer lock-in. Price sensitivity concentrates among rural clinic purchasers facing cold chain constraints, while Gulf private hospital networks absorb premium instrument pricing with limited negotiation leverage.
Supply Chain Analysis
Dubai-Jebel Ali port congestion and Red Sea transit disruptions periodically choke reagent import flows into East African markets. Manufacturing concentration rests on Germany, USA, and China for thermal cycler hardware, while reagent biochemical precursors draw from Switzerland and Singapore. Single-source vulnerability in PCR polymerase enzymes creates procurement risk during geopolitical trade restrictions. Distribution runs through manufacturer-direct hospital contracts in South Africa and Saudi Arabia, layered distributor networks elsewhere.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa in-Vitro Diagnostics Market is approaching a platform-economics inflection where instrument-reagent interoperability standards determine competitive survival, catalyzed by Saudi Food and Drug Authority mandates for Arabic-labeling compliance that favor ecosystem-ready suppliers over point-product vendors.
For Market Incumbents: Compound regulatory dossier depth into Gulf tender eligibility by pre-positioning CE-IVDR technical documentation ahead of national insurance reform implementation. Secure backward integration into reagent biochemical production to defend margin position against third-party compatible chemistries eroding manufacturer lock-in economics. For New Entrants and Emerging Players: Lead with home care channel penetration in Gulf Cooperation Authority diabetes monitoring segments, where retail pharmacy distribution bypasses hospital procurement centralization. Target underpenetrated infectious disease self-testing protocols through pharmacy-direct models rather than tender-dependent institutional sales. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors CE-IVDR-certified platform specialists with installed base expansion capability over pure reagent manufacturers facing substitution pressure. Long-term viability over the coming decade hinges on software companion development and laboratory information system integration depth. Watch for Saudi national insurance reform implementation timing as inflection indicator for Gulf procurement volume reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVDR Certification Pathway | SFDA tender eligibility now requires European technical documentation submission. |
| Localized Reagent Production | Morocco-based manufacturing secures Arabic labeling compliance for Gulf markets. |
| Hospital System Partnership | Direct engagement with South African NHI designated laboratories displaces distributor tiers. |
| Software Companion Development | Laboratory information system integration enables workflow automation in Kenyan sites. |
| Reimbursement Strategy | WHO pre-qualification alignment opens development finance institution capital in Nigeria. |
Study Parameters
Initial hypotheses were tested against primary input from hospital laboratory directors, biomedical equipment procurement officers, regulatory affairs specialists at national health authorities, and distribution channel managers across Dubai, Johannesburg, and Nairobi, then refined through secondary validation against SFDA registration databases, SAHPRA pre-qualification filings, WHO pre-qualification lists, and customs import records. Bottom-up instrument placement counts and top-down healthcare expenditure allocations were triangulated to constrain estimate variance.
Variance decomposition across product type, application, end user, technology, and national regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macro healthcare indicators. Modeled inputs included tuberculosis-HIV co-detection protocol adoption curves, national health insurance reform implementation schedules, and cold chain infrastructure expansion timelines.
The analysis sits within stated boundaries; outcomes outside sustained Gulf procurement budget allocation and stable Red Sea logistics corridors would require recalibration. Practitioners should keep alternative scenarios live as CE-IVDR reciprocity negotiations and national insurance reform implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Predictive and Presymptomatic Testing Market
Diagnostics
Pancreatic Cyst Diagnostics Market
Diagnostics
Global Lateral Flow Assay Market
Diagnostics
Global Autoimmune Disease Diagnostics Market
Diagnostics
Global Tissue Diagnostics Market
Diagnostics
In-Vitro Diagnostics (IVD) Instruments Market
Diagnostics
Melioidosis Diagnostic Market
Diagnostics
Anatomic Pathology Market
Diagnostics
Antigen Skin Test Market
Diagnostics
Spain in-Vitro Diagnostics Market
Diagnostics
Global Diagnostic Radiopharmaceuticals and Contrast Media Market
Diagnostics
HDL Cholesterol Kits Market
Diagnostics
Global STD Diagnostics Market
Diagnostics
US Prostate Cancer Nuclear Medicine Diagnostics Market
Diagnostics
Global Yersiniosis Diagnostics and Treatment Market
Diagnostics
Argentina in Vitro Diagnostics Market