
 IVD Antibody Market | 2026-2036
IVD Antibody Market Size, Share, and Industry Trends Forecast 2026-2036
IVD Antibody Market Insights
China is fragmenting as domestic biotech firms build GMP-grade antibody production campuses to serve local IVD manufacturers. Roche Diagnostics leverages its captive reagent supply chain to lock in long-term contracts with European reference labs. Thermo Fisher Scientific anchors its position through recombinant antibody engineering platforms that reduce lot-to-lot variability. Abbott Laboratories competes on point-of-care instrument compatibility, bundling antibodies with automated analyzers.
An in vitro diagnostic antibody is a purified immunoglobulin or engineered binding protein manufactured through hybridoma culture, phage display, or recombinant expression in mammalian or microbial systems, typically specified by affinity constants in the nanomolar to picomolar range and validated for specificity against clinical biomarkers; its primary purpose is to detect, quantify, or localize target analytes in patient-derived specimens for disease screening, diagnosis, or therapeutic monitoring. Monoclonal antibodies occupy the largest revenue share due to their batch consistency and regulatory acceptance in high-stakes cancer diagnostics, while recombinant antibodies represent the fastest-expanding product class as manufacturers seek animal-origin-free alternatives that simplify FDA and EMA filings. Among applications, infectious disease diagnostics remains the most mature segment with established reimbursement, though cancer diagnostics commands premium pricing where antibodies serve as companion diagnostic reagents tied to targeted therapies.
The FDA regulates IVD antibodies as Class II or III medical device components under 21 CFR 820 quality system requirements, while the EMA's In Vitro Diagnostic Medical Devices Regulation imposes stricter performance validation and post-market surveillance obligations across EU member states. China's NMPA now requires domestic clinical validation data for antibody-based IVD kits, slowing foreign kit approvals while accelerating local substitution. Japan's PMDA maintains separate master file protocols for antibody raw materials that create compliance friction for non-Japanese suppliers. Stakeholders must monitor divergent regulatory clock speeds as countries prioritize health security through localized supply chains over harmonized standards.
Market Dynamics
The FDA's evolving guidance on companion diagnostics is compressing validation timelines while simultaneously elevating performance thresholds, forcing antibody suppliers to rebuild quality systems around biomarker-specific evidence packages rather than platform-level clearances.
Growth Catalysts
- Automated immunoassay platform expansion:Clinical diagnostic laboratories in the United States are installing high-throughput systems that consume antibody reagents at 3-4x the rate of manual methods.
- EMA MDR implementation:The EU's stricter post-market surveillance obligations are filtering out low-quality antibody suppliers and consolidating procurement around validated manufacturers.
- Companion diagnostic mandates:Oncology drug approvals increasingly require parallel antibody-based tests, embedding reagent demand into pharmaceutical development pipelines.
Market Restraints
- Fetal bovine serum price volatility:Hybridoma culture depends on serum inputs subject to supply shocks from drought-affected grazing regions.
- Chinese domestic production surge:State-subsidized GMP campuses are displacing import demand and creating regional oversupply.
- Lot-to-lot variability penalties:Reference labs now reject antibody batches exceeding 5% coefficient of variation, compressing effective manufacturing yield.
Strategic Opportunities
- India's diagnostic infrastructure buildout:The country's PLI scheme for medical devices is attracting contract manufacturers seeking localized antibody supply.
- Recombinant antibody animal-origin-free status:Simplified FDA and EMA filings are opening premium pricing tiers for engineered binding proteins.
- Point-of-care instrument bundling:Antibody-analyzer pairings lock in recurring revenue streams through consumable pull-through.
Industry Challenges
- Hybridoma cell line documentation:Master file submissions now require 15-year lineage traceability that legacy collections cannot satisfy.
- Cross-reactivity validation burden:Expanding biomarker panels demand antibody specificity testing against 200+ interferent proteins per assay.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IVD Antibody Market |
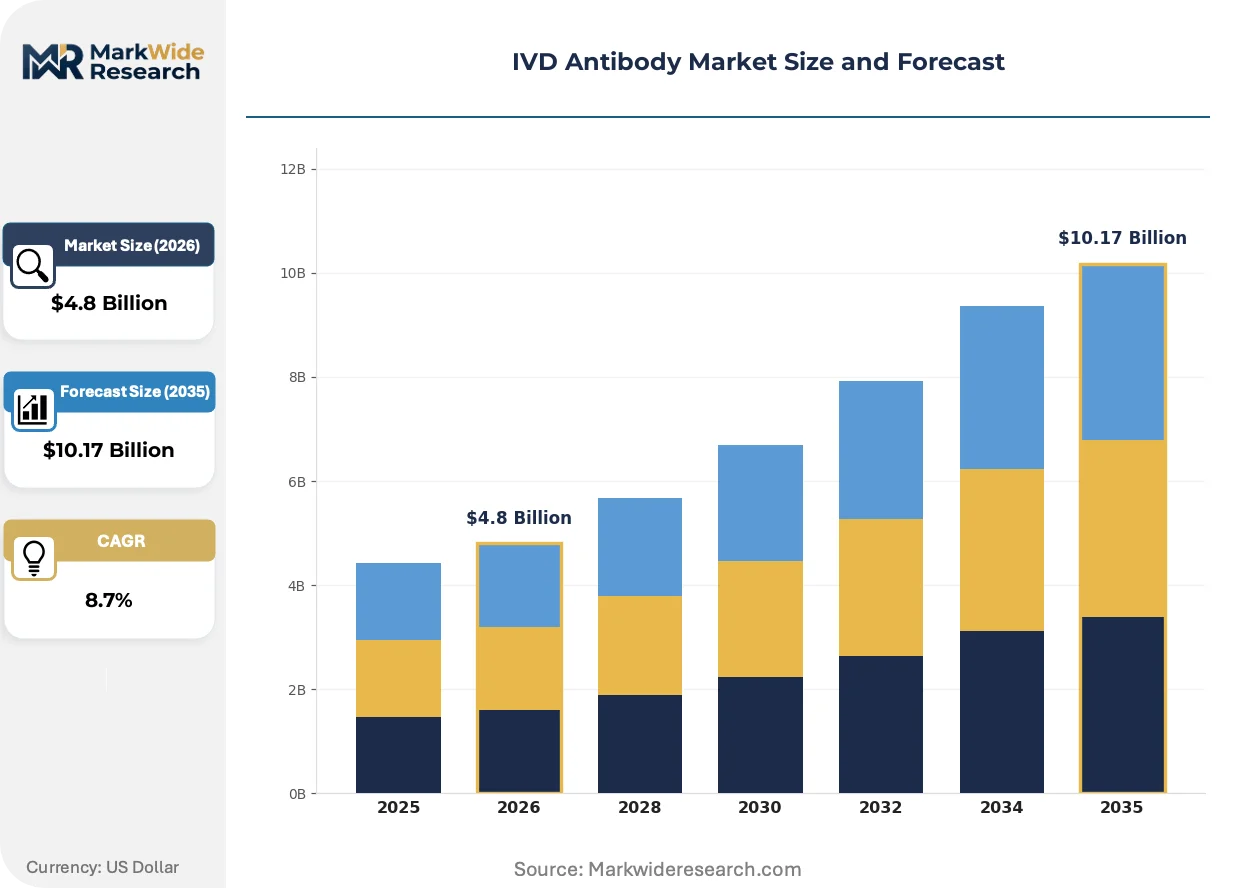
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Polyclonal Antibodies, Recombinant Antibodies, Antibody Fragments Application: Infectious Disease Diagnostics, Cancer Diagnostics, Autoimmune Disease Testing, Blood Typing End User: Hospitals, Diagnostic Laboratories, Academic Institutions, Research Organizations Technology: ELISA, Western Blotting, Immunohistochemistry, Flow Cytometry |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Thermo Fisher Scientific, Danaher Corporation, Siemens Healthineers, Bio-Rad Laboratories, Becton Dickinson and Company, Abcam plc, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IVD Antibody Market Trends and Innovations
Recombinant expression systems and synthetic binding architectures are displacing traditional hybridoma methods, compressing development cycles from months to weeks while fragmenting competitive advantage away from cell line libraries toward computational design capabilities.
Phage display libraries paired with next-generation sequencing are rendering obsolete the hybridoma-dependent monoclonal antibody production that dominated IVD supply chains for four decades. European reference labs now specify recombinant sourcing in tenders, and the technology is compressing supplier margins on legacy serum-dependent products while enabling rapid specificity engineering against novel biomarkers.
China's NMPA now requires domestic clinical validation data for antibody-based IVD kit approvals, creating compliance friction for foreign manufacturers. The policy is forcing multinationals to establish local clinical trial partnerships or cede the market to domestic biotech firms with established investigator networks and existing biomarker cohorts.
Hospital network consolidation in the United States is centralizing procurement decisions at the system level, displacing the individual laboratory purchasing autonomy that historically fragmented antibody supplier relationships. Three-tier pricing structures across premium, standard, and economy levels are emerging as consolidated buyers negotiate volume-commitment contracts spanning multiple instrument platforms.
IVD Antibody Market Segmentation
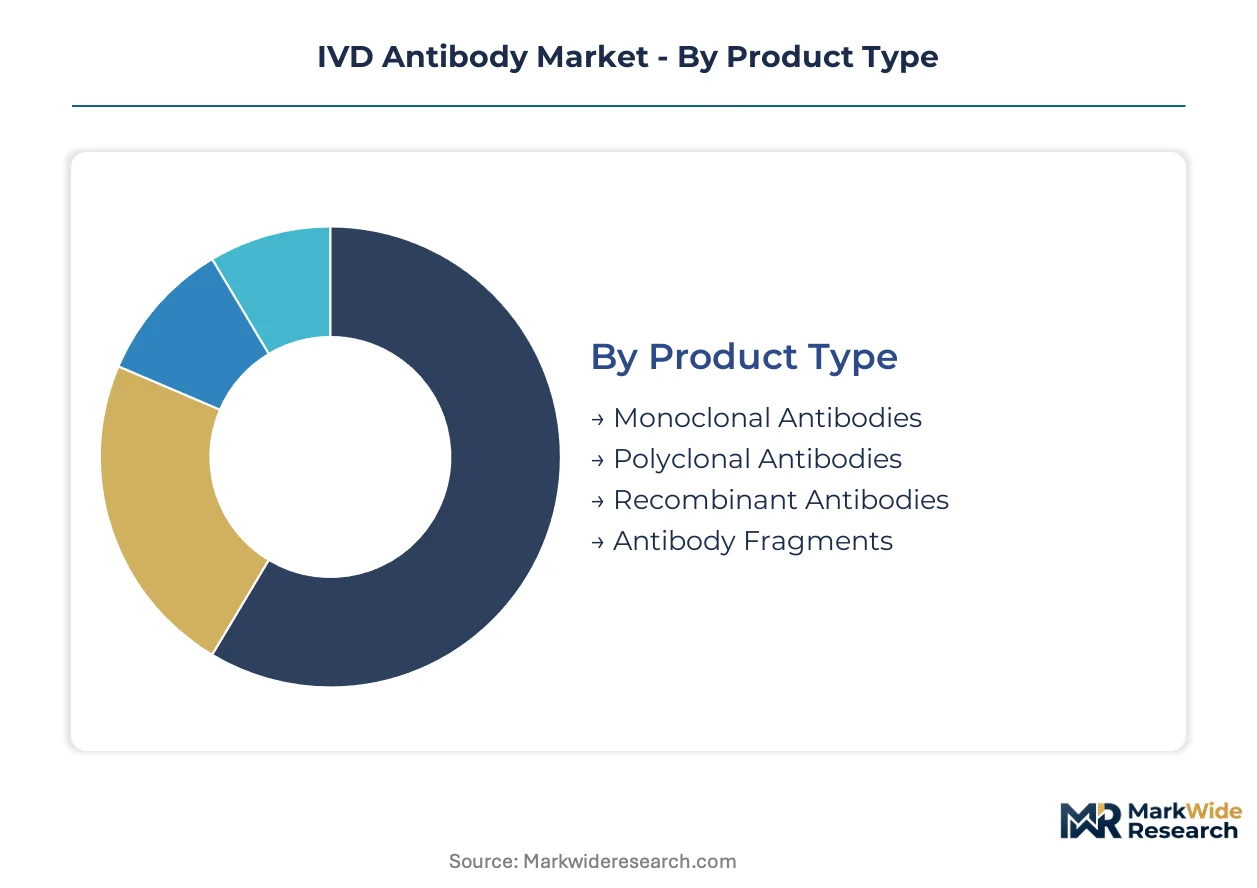
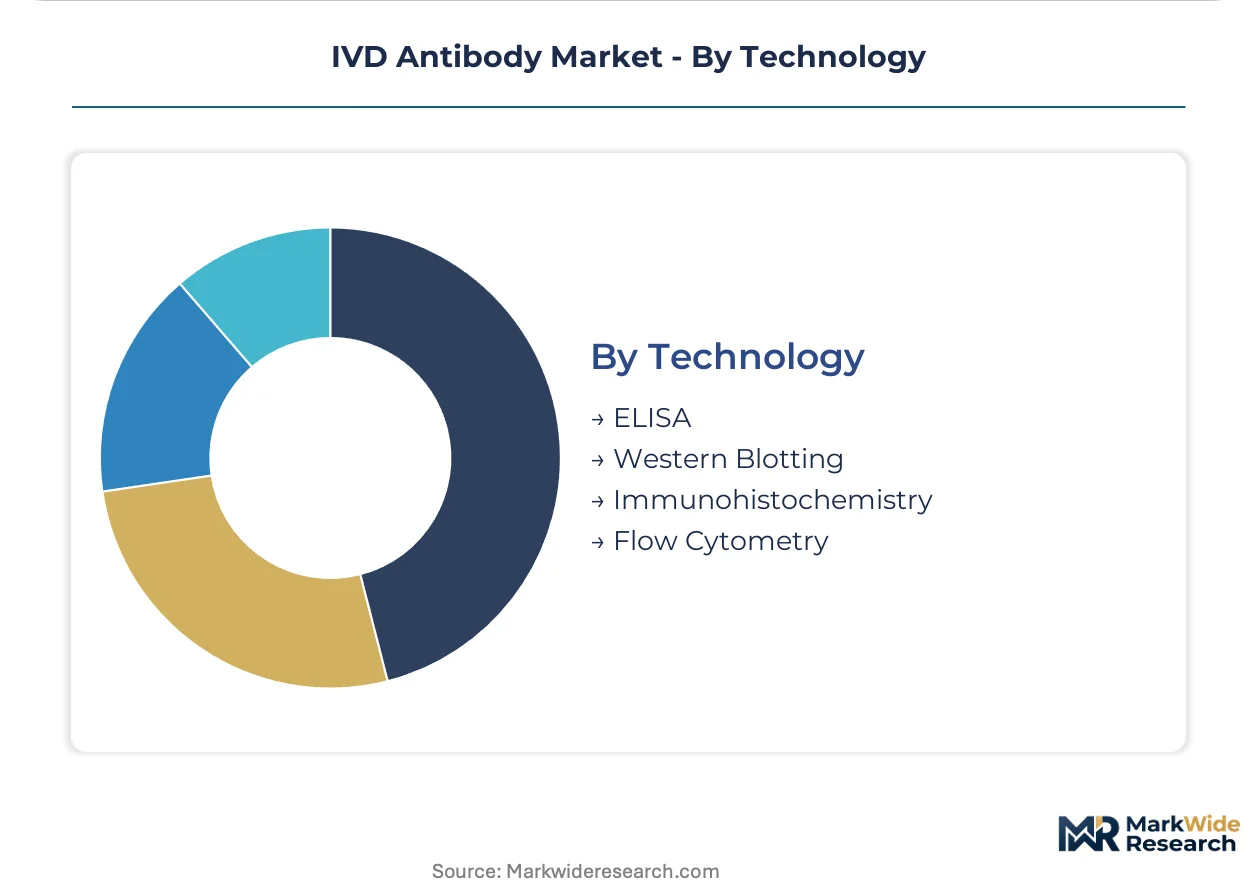
IVD antibody procurement patterns diverge sharply across product architectures and testing modalities. Each segment carries distinct regulatory burdens, manufacturing scale requirements, and aftermarket service intensities that reshape supplier economics.
Product Type:
After-sales service intensity varies dramatically by antibody production platform, with hybridoma-derived products demanding lot-to-lot stability monitoring and recombinant systems requiring sequence verification protocols.
- Monoclonal Antibodies:Hybridoma-derived immunoglobulins with established master cell banks provide batch consistency critical for FDA Class III companion diagnostics. United States hospital networks consolidate procurement around suppliers with documented 15-year cell line traceability.
- Recombinant Antibodies:Animal-origin-free binding proteins engineered through mammalian expression systems simplify EMA MDR filings and command premium positioning in European tenders. Their defined sequences enable rapid specificity optimization against novel biomarkers.
- Polyclonal Antibodies:Serum-derived heterogeneous immunoglobulin pools retain cost advantages in blood typing applications where absolute specificity is less critical than broad reactivity coverage.
- Antibody Fragments:ScFv and Fab constructs produced in microbial systems offer reduced molecular weight for tissue penetration in immunohistochemistry workflows.
By volume, monoclonal antibodies lead. By growth pace, recombinant antibodies are expanding most quickly.
Application:
Reimbursement density and test complexity create tiered margin structures across diagnostic use cases, with oncology applications supporting multi-year antibody supply contracts.
- Infectious Disease Diagnostics:Mature segment with established CPT codes and high-throughput immunoassay consumption. Automated platforms in United States reference labs drive reagent pull-through at 3-4x manual method rates.
- Cancer Diagnostics:Companion diagnostic mandates embed antibody demand into pharmaceutical development pipelines. Premium pricing reflects biomarker specificity requirements and parallel regulatory filings with targeted therapies.
- Autoimmune Disease Testing:ANA and rheumatoid factor panels utilize well-characterized antibody reagents with stable demand from hospital core laboratories.
- Blood Typing:Regulatory-mandated serology testing maintains consistent procurement volumes with limited supplier switching due to validation costs.
Infectious disease testing generates the highest absolute reagent volume. Cancer diagnostics shows the steepest expansion trajectory as biomarker panels proliferate.
End User:
Procurement autonomy concentrates differently across institutional types, with consolidated health systems displacing fragmented laboratory purchasing.
- Diagnostic Laboratories:Reference labs and hospital networks negotiate multi-year volume commitments spanning instrument platforms. Three-tier pricing structures emerge as consolidated buyers segment procurement across premium, standard, and economy antibody grades.
- Hospitals:Point-of-care instrument bundling locks in recurring revenue through analyzer-antibody pairings, particularly in emergency department infectious disease panels.
- Academic Institutions:Research-grade antibody procurement emphasizes lot-specific validation data and publication traceability rather than clinical regulatory packages.
- Research Organizations:Contract research organizations prioritize rapid turnaround on custom antibody projects with flexible specificity requirements.
Diagnostic laboratories command the largest procurement scale. Hospital point-of-care expansion is climbing the fastest.
Technology:
Platform compatibility requirements constrain antibody format selection, with detection method sensitivity dictating affinity specifications.
- ELISA:Enzyme-linked immunosorbent assay platforms dominate high-throughput infectious disease screening with standardized antibody coating protocols.
- Immunohistochemistry:Tissue-based cancer diagnostics requires antibodies validated against formalin-fixed paraffin-embedded specimens with demonstrated epitope stability.
- Flow Cytometry:Fluorophore-conjugated antibodies for cell surface marker analysis demand rigorous cross-reactivity testing against leukocyte populations.
- Western Blotting:Research applications utilize denatured-protein reactive antibodies with less stringent lot-to-lot consistency requirements than clinical platforms.
ELISA maintains the broadest installed base. Immunohistochemistry is gaining share fastest as tissue-based companion diagnostics expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics corridors underwrite Europe's antibody reagent distribution, while direct rail links from Shanghai's Yangshan Deep Water Port feed manufacturing inputs into East Asian IVD clusters.
United States
Hospital network consolidation in Texas and the Southeast is centralizing procurement decisions at the system level, displacing fragmented laboratory purchasing. The FDA's evolving companion diagnostics guidance is compressing validation timelines while elevating performance thresholds. The Greater Boston biotech corridor anchors recombinant antibody engineering, with Cambridge-based facilities supplying reference labs nationwide.
Germany
European reference labs in Munich and Hamburg now specify recombinant antibody sourcing in tenders, filtering procurement toward animal-origin-free suppliers. The EMA's MDR implementation imposes stricter post-market surveillance obligations that favor validated manufacturers with documented quality systems. The Rhine-Ruhr industrial basin concentrates GMP-grade production campuses serving domestic IVD kit makers.
China
State-subsidized GMP campuses in Suzhou and Hangzhou are displacing import demand for diagnostic antibodies. The NMPA now requires domestic clinical validation data for antibody-based IVD kit approvals, slowing foreign approvals while accelerating local substitution. The Yangtze River Delta biotech cluster houses the fastest-expanding recombinant production capacity in Asia.
Japan
Point-of-care instrument bundling in Tokyo and Osaka metropolitan hospitals locks in recurring antibody revenue through analyzer-consumable pairings. The PMDA maintains separate master file protocols for antibody raw materials that create compliance friction for non-Japanese suppliers. The Kansai region's diagnostic device manufacturers are consolidating procurement around domestic antibody suppliers with established regulatory track records.
India
The PLI scheme for medical devices is attracting contract manufacturers seeking localized antibody supply for infectious disease diagnostics. CDSCO regulations are tightening import documentation requirements for clinical-grade reagents. The Hyderabad-Bengaluru pharmaceutical corridor is emerging as a hub for research-grade antibody production serving contract research organizations.
IVD Antibody Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying validated reagents to consolidated buyers. The vendor base stratifies into three tiers: multinational conglomerates with captive reagent supply chains, mid-scale recombinant engineering specialists, and regional hybridoma-dependent producers facing margin compression. Two strategic archetypes dominate: automated instrument bundlers securing long-term consumable contracts, and recombinant platform owners exploiting simplified regulatory filings. Consolidation through vertical integration and strategic partnerships for biomarker-specific validation packages are the dominant competitive moves.
Among the diversified health technology conglomerates, Roche Diagnostics, Abbott Laboratories, and Thermo Fisher Scientific occupy positions that exemplify divergent competitive vectors. Roche Diagnostics leverages its captive reagent supply chain to anchor European reference lab relationships. Abbott Laboratories represents the instrument-bundling archetype, embedding antibody consumption within point-of-care platform ecosystems. Thermo Fisher Scientific sits within the recombinant engineering tier, where defined sequences enable rapid specificity optimization against novel biomarkers.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Siemens Healthineers |
| Bio-Rad Laboratories |
| Becton Dickinson and Company |
| Abcam plc |
| Agilent Technologies |
| Others |
Pricing and Supply Chain Analysis
The Port of Rotterdam's cold-chain logistics corridors shape cost dynamics across European antibody distribution, concentrating supply-side leverage among GMP-certified manufacturers while fragmenting downstream price differentiation across hospital network tiers.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts between consolidated United States hospital networks and antibody suppliers, with premium-mid-economy pricing differentiation anchored to FDA master file documentation depth and lot-to-lot variability coefficients. Certification grade and volume scale serve as the primary price differentiation drivers, while cost compression in the standard tier intensifies because of Chinese domestic production capacity expansion. Reference laboratories exhibit the least price sensitivity due to companion diagnostic validation requirements, whereas academic research institutions demonstrate the highest sensitivity to per-milligram pricing.
Supply Chain Analysis
Supplier-financing facilities extended by Roche Diagnostics and Thermo Fisher Scientific lock in multi-year antibody offtake commitments from European reference labs, reducing working capital pressure on downstream buyers. Manufacturing concentration centers on the United States, Germany, and China, with production drawing from fetal bovine serum, recombinant expression vectors, and phage display library inputs. Single-source vulnerability around serum supply from drought-affected grazing regions poses structural risk. Distribution runs through direct instrument-bundling contracts and third-party cold-chain logistics providers serving diagnostic laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through United States hospital network consolidation, displacing fragmented laboratory purchasing autonomy and forcing suppliers into volume-commitment negotiations at the system level.
For Market Incumbents: Insulate master cell bank documentation against evolving FDA lineage traceability requirements by digitizing 15-year hybridoma records and securing redundant recombinant expression capacity. Backward integration into fetal bovine serum sourcing hedges against supply shocks from drought-affected regions. Priority certification investment targets EMA MDR post-market surveillance compliance to filter out lower-tier competitors. For New Entrants and Emerging Players: India's PLI scheme for medical devices represents the most penetrable entry point, with contract manufacturers seeking localized antibody supply for infectious disease diagnostics creating immediate demand pull. Recombinant antibody engineering for animal-origin-free status opens premium positioning in European tenders. Go-to-market execution should anchor to CDSCO regulatory partnership pathways rather than import documentation routes. For Investors and Strategic Acquirers: Recombinant platform specialists with defined sequence libraries and rapid specificity optimization capabilities offer the strongest acquisition profile for long-term viability across the 5-10 year window. These assets command defensive positioning as phage display methods displace legacy hybridoma dependencies. The signal to monitor is NMPA domestic clinical validation data requirements, which will accelerate local substitution and compress foreign supplier margins in China.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Expression Platform Investment | Animal-origin-free status simplifies FDA and EMA filings for companion diagnostics. |
| Hospital System Partnership | Instrument bundling locks in recurring consumable revenue through analyzer-antibody pairings. |
| Regulatory Master File Digitization | 15-year hybridoma lineage documentation satisfies evolving FDA traceability mandates. |
| Geographic Manufacturing Footprint | Localized GMP campuses in India and China bypass import friction and CDSCO documentation barriers. |
| Biomarker-Specific Validation Package | Companion diagnostic co-development embeds antibody demand into pharmaceutical pipelines. |
Research Methodology
Operator-level perspectives from diagnostic laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs leads anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) filings, EMA MDR submissions, hospital procurement databases, and GPO contract repositories. Bottom-up antibody volume modeling and top-down market sizing triangulated across recombinant and hybridoma production platforms.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product architecture, application type, end-user institution, and detection technology platform. CAGRs derived from antibody consumption intensity per automated immunoassay installation, biomarker panel expansion rates in oncology, and regional regulatory clock speed differentials. Forecast inputs incorporated companion diagnostic mandate frequency and recombinant platform adoption curves.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles or biopharmaceutical R&D funding levels would shift the trajectory. Forecasts reflect assumptions around regulatory harmonization pace and serum supply stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
GCC in-Vitro Diagnostic Devices Market
Diagnostics
Tuberculosis (TB) Diagnostics Market
Diagnostics
Global Respiratory Syncytial Virus (RSV) Diagnostic Market
Diagnostics
Global Tissue Diagnostics Market
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market
Diagnostics
Gastrointestinal Diagnostics Market
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
At-Home Cancer Testing Market
Diagnostics
Viral Molecular Diagnostics Market
Diagnostics
Body Fluid Collection and Diagnostics Market
Diagnostics
Sperm Count Test Market
Diagnostics
Cushing's Syndrome Diagnostics and Therapeutics Market
Diagnostics
Global Prostate Specific Antigen (PSA) Test Market
Diagnostics
Global Veterinary POC Diagnostic Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Artificial Intelligence in IVD Market