
 Veterinary Rapid Diagnostic Tests Market | 2026-2036
Veterinary Rapid Diagnostic Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Rapid Diagnostic Tests Market Intelligence
Demand from independent veterinary clinics versus large centralized laboratories is bifurcating the market's customer base. This shift favors point-of-care solutions that provide immediate results, altering traditional diagnostic workflows. IDEXX Laboratories leverages its extensive portfolio of in-clinic analyzers and rapid tests to capture this trend. Zoetis competes through a combination of diagnostics, vaccines, and pharmaceuticals, while Virbac specializes in a targeted range of tests for specific animal health issues.
Veterinary rapid diagnostic tests are devices used for the swift detection of antigens, antibodies, or nucleic acids related to animal diseases. These tests, often employing technologies like enzyme-linked immunosorbent assays (ELISA), provide qualitative or semi-quantitative results in minutes. Their primary purpose is to enable timely clinical decisions at the point of care. Immunoassays, particularly those based on lateral flow assay technology, constitute the largest product segment, valued for their simplicity and speed in both companion animal and livestock settings.
Regulatory oversight from bodies like the US FDA's Center for Veterinary Medicine and the European Medicines Agency ensures test performance and safety. These agencies establish the validation requirements that manufacturers must meet for market approval. In parallel, organizations like the World Organisation for Animal Health (OIE) influence testing protocols for transboundary diseases. The key decision for manufacturers is allocating R&D between high-complexity molecular platforms and accessible, low-cost rapid formats.
Market Dynamics
The bifurcation of the customer base between large central laboratories and independent clinics is the central force shaping the market. This structural shift creates distinct demand for high-throughput systems versus accessible, immediate point-of-care formats like lateral flow assays.
Growth Catalysts
- Livestock Modernization:Government-led initiatives in countries like China to control epizootics, such as African Swine Fever, mandate widespread surveillance, boosting demand for rapid tests on farms.
- Companion Animal Healthcare:The humanization of pets in developed economies elevates spending on preventative care and wellness screening, expanding the use of in-clinic diagnostics in general practice.
- Lateral Flow Assay Technology:The inherent simplicity and speed of lateral flow immunoassays lower the barrier to adoption for non-specialist users in veterinary clinics and field settings.
Market Restraints
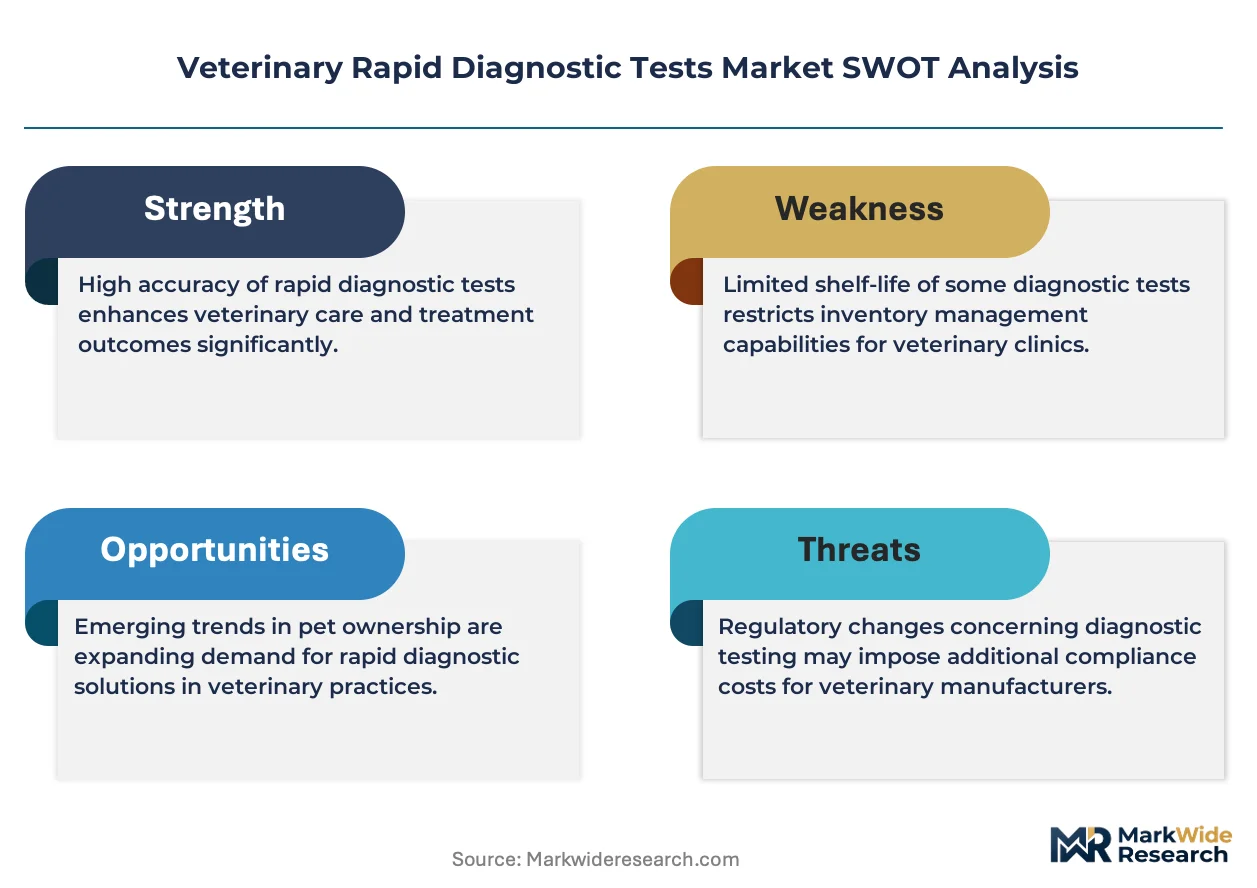
- Test Validation Hurdles:Stringent performance data and manufacturing quality requirements from regulatory bodies like the US FDA's Center for Veterinary Medicine and the EMA create long development timelines.
- Cost of Advanced Platforms:The capital expenditure for molecular or high-sensitivity immunoassay readers remains a significant barrier for smaller, independent veterinary practices and farms in emerging markets.
- Substitution by Lab Methods:For definitive diagnoses of complex or novel pathogens, traditional laboratory-based methods like bacterial culture or PCR are often required, limiting rapid tests to a screening role.
Strategic Opportunities
- Geographic Expansion:Underpenetrated markets in Southeast Asia and South America present opportunities for deploying rapid tests for livestock diseases critical to food security and trade.
- Technology Convergence:Integrating microfluidics with smartphone-based digital readers offers a pathway to create connected diagnostic ecosystems that automate result interpretation and data reporting.
- Zoonotic Disease Surveillance:Growing focus from organizations like the World Organisation for Animal Health (OIE) on one-health initiatives creates demand for new tests for emerging zoonotic pathogens.
Industry Challenges
- Data Integration Complexity:Linking results from diverse point-of-care devices into disparate veterinary practice management software systems remains a significant operational hurdle for clinics aiming for digitalization.
- Field Performance Variability:Ensuring consistent test accuracy and reliability when performed by users with varying skill levels in diverse environmental conditions is a persistent quality control challenge.
- Diagnostic Interpretation Skills:A gap exists in the training of some veterinary professionals on the nuances of interpreting semi-quantitative results and understanding the specific limitations of each test.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Rapid Diagnostic Tests Market |
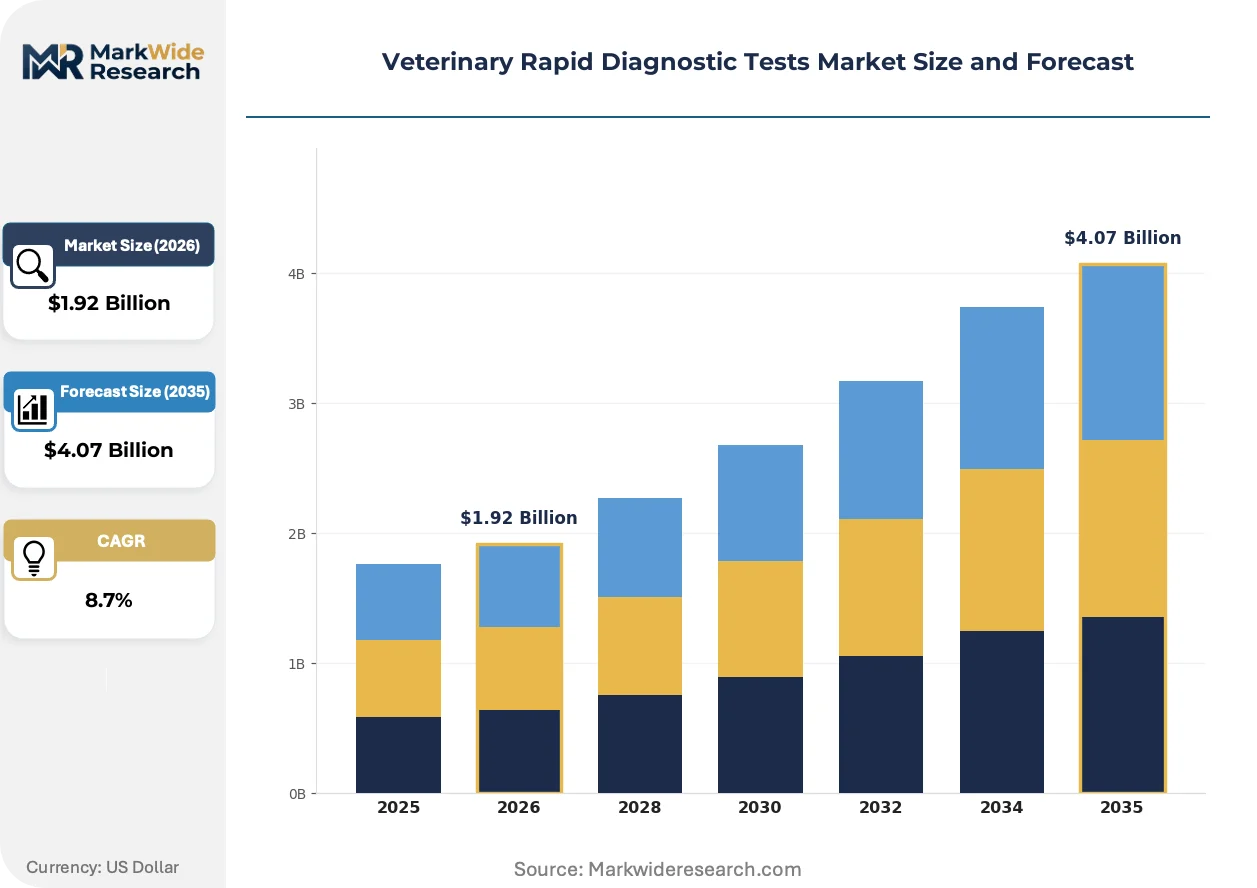
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $4.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassays, Molecular Diagnostics, Microbiological Tests, Clinical Chemistry, Hematology Animal Type: Companion Animals, Livestock, Poultry, Aquatic Species, Equine End User: Veterinary Clinics, Diagnostic Laboratories, Research Institutes, Mobile Vet Units Test Technology: ELISA, PCR, Lateral Flow Assays, Fluorescent Immunoassays, Microarray |
| Companies Covered | Virbac, Neogen Corporation, IDEXX Laboratories, Bionote, bioMérieux, Zoetis, Heska Corporation, Fassisi, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Rapid Diagnostic Tests Market Strategic Shifts & Innovations
Digitalization and decentralization are actively reshaping veterinary diagnostics. The migration of testing from centralized laboratories to the point of care in clinics and on farms is accelerating, driven by technologies that combine speed with connectivity for improved clinical workflows.
Multiplex lateral flow assays allow for the simultaneous detection of multiple analytes from a single sample. Large veterinary hospitals and commercial livestock operations are adopting this technology to screen for panels of common infectious diseases. This format is supplanting the use of multiple single-analyte tests, improving diagnostic efficiency, reducing sample volume requirements, and lowering the overall cost per result.
Updated guidance from the World Organisation for Animal Health (WOAH) on managing transboundary animal diseases is influencing national surveillance strategies. These protocols increasingly endorse the use of validated rapid tests for field-level screening to enable swift containment measures. The livestock sectors in major exporting nations, including Brazil and Australia, are most affected, adapting their biosecurity frameworks to incorporate these tools.
Veterinary clinics are transitioning from transactional test kit purchases to subscription-based service models. This shift often bundles in-clinic analyzers, a recurring supply of test consumables, and software support into a single periodic fee. This model disrupts traditional distributor-led sales channels, fostering direct relationships between manufacturers and end-users, a pattern most visible in the North American companion animal market.
Veterinary Rapid Diagnostic Tests Market Segmentation
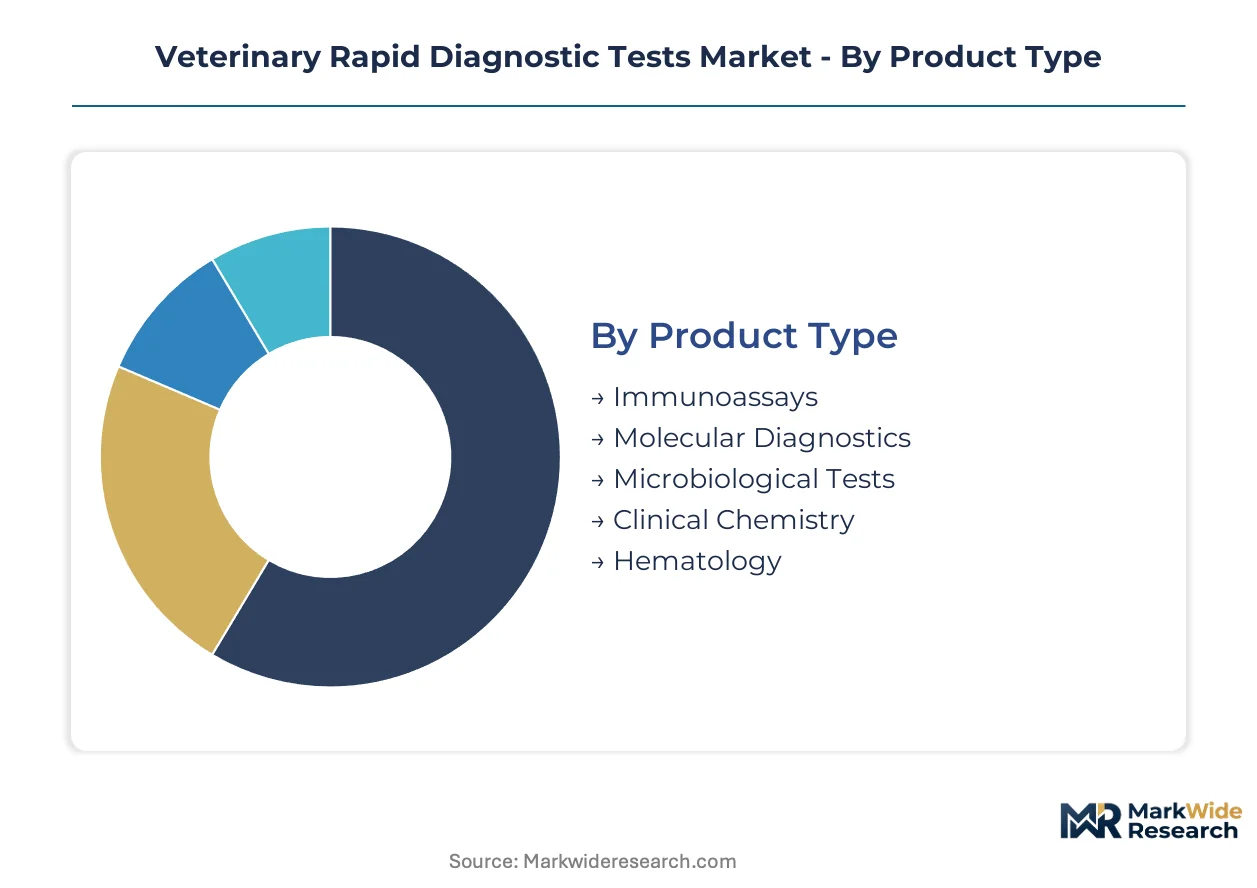
Understanding the distinct segments within the veterinary rapid diagnostic tests market reveals varying needs and growth trajectories. This granular analysis helps manufacturers align product development and market strategies with specific end-user demands. The market's structure reflects diverse technological preferences and operational scales across different animal health sectors.
Product Type:
The geographic distribution of product types often reflects regional veterinary infrastructure and prevalent disease profiles, with some tests gaining traction in export-oriented livestock regions.
- Immunoassays:These tests detect antigens or antibodies using immunological reactions, frequently employing ELISA or lateral flow formats. Demand for these user-friendly tests is high in companion animal practices across developed economies like the United States, driven by a need for quick in-clinic screening.
- Molecular Diagnostics:Utilizing techniques like PCR, these tests identify specific nucleic acid sequences for highly accurate pathogen detection. Commercial livestock operations in countries such as Brazil increasingly adopt molecular platforms for definitive diagnosis of economically significant diseases, ensuring herd health management.
- Microbiological Tests:These involve culturing and identifying microorganisms from samples, providing detailed information on bacterial or fungal infections. Diagnostic laboratories in Europe frequently employ these traditional methods for confirmation of antimicrobial resistance patterns.
- Clinical Chemistry:These tests measure various chemical components in blood or other body fluids, assessing organ function and metabolic status. Veterinary clinics utilize these for routine health panels and pre-surgical screenings.
- Hematology:Focusing on blood cell counts and characteristics, hematology tests diagnose conditions like anemia, inflammation, or infection. General veterinary practices widely use these for comprehensive patient evaluations.
Immunoassays commands the established base. The steepest expansion runs through Molecular Diagnostics.
Animal Type:
The market's animal type segmentation highlights a bifurcation between individual pet owner spending and large-scale commercial animal operations, each driving unique diagnostic requirements.
- Companion Animals:This segment includes pets such as dogs, cats, and exotic animals, where tests support preventative care, disease diagnosis, and wellness screening. Owners in countries like Canada prioritize advanced diagnostics for their pets, reflecting the humanization trend.
- Livestock:Covering cattle, pigs, and sheep, this segment demands rapid tests for disease surveillance, herd health management, and biosecurity. Government-led initiatives in China to control epizootics significantly boost demand for livestock diagnostics.
- Poultry:Rapid diagnostic tests for poultry are essential for managing flock health and preventing widespread outbreaks in commercial broiler and layer operations. Large-scale poultry farms in Southeast Asia rely on these tests for early disease detection.
- Aquatic Species:This category encompasses fish and shellfish, where tests monitor water quality and detect pathogens affecting aquaculture. Fish farms in Norway use specific tests to maintain the health of their farmed salmon populations.
- Equine:Diagnostic solutions for horses address athletic performance, infectious diseases, and reproductive health. Specialized equine veterinary practices in the United Kingdom frequently employ rapid tests for respiratory pathogens.
Growth in Companion Animals is driven by elevated spending on preventative care, while Livestock maintains a stable base due to mandatory surveillance programs.
End User:
The end-user landscape reflects a shift from centralized testing towards immediate point-of-care solutions, influencing the type and complexity of tests adopted.
- Veterinary Clinics:These independent or group practices perform a wide range of diagnostic tests for immediate clinical decision-making. The increasing availability of user-friendly lateral flow assays accelerates point-of-care adoption in these settings.
- Diagnostic Laboratories:Centralized facilities offer high-throughput testing and specialized diagnostics for complex cases, often receiving samples from multiple clinics. These laboratories in Germany provide confirmatory testing for rare or emerging animal diseases.
- Research Institutes:Academic and private research centers utilize rapid diagnostic tests for studying animal diseases, developing new therapies, and validating novel diagnostic platforms. Institutions in the United States often drive innovation in emerging pathogen detection.
- Mobile Vet Units:These units provide on-site veterinary care, requiring portable and robust rapid diagnostic tests for immediate results in field settings. Rural areas of Australia benefit from mobile units offering essential diagnostic services.
The demand landscape is shaped by the contrasting needs of Veterinary Clinics, which prioritize speed, and Diagnostic Laboratories, which focus on comprehensive analysis.
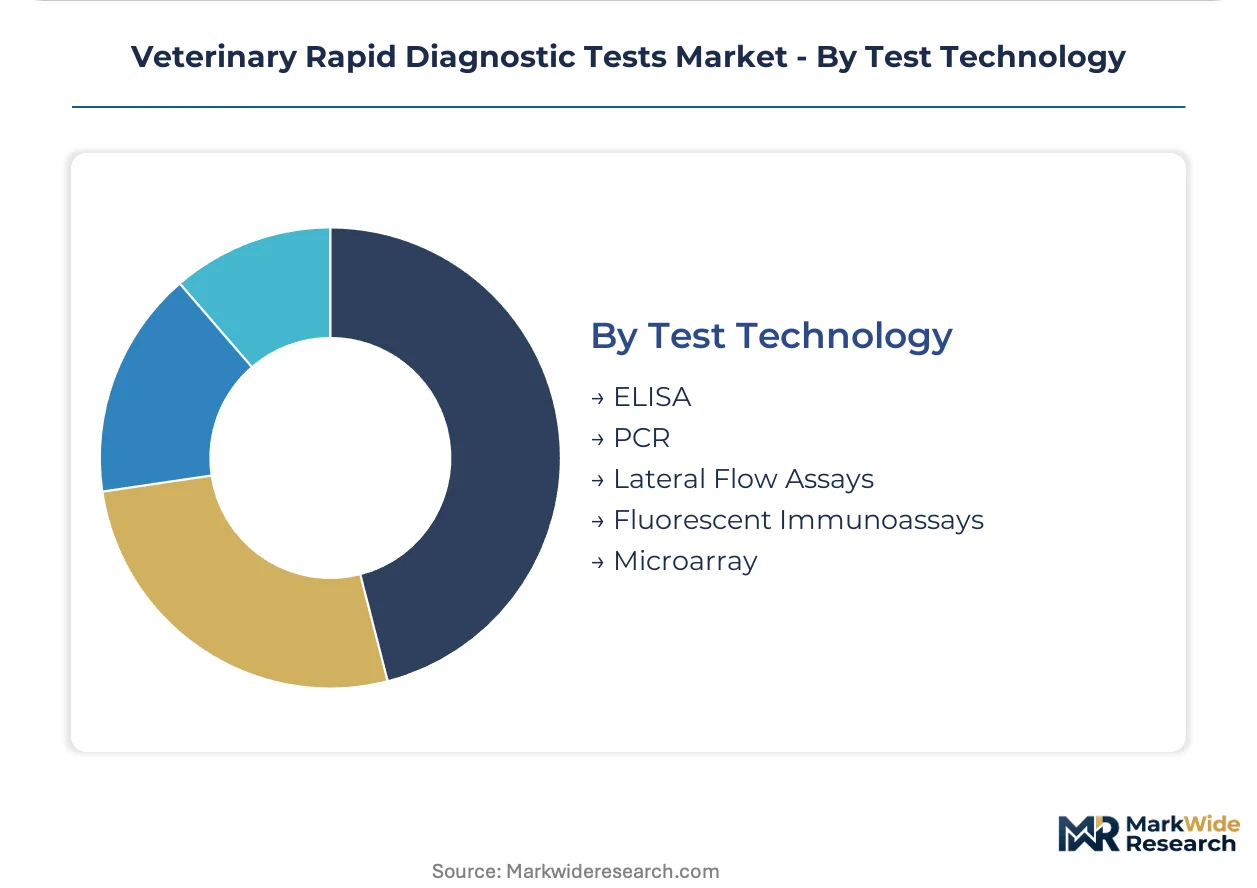
Test Technology:
The technological segmentation highlights a continuum from established, low-cost formats to advanced, high-precision platforms, each serving distinct diagnostic needs and operational scales.
- ELISA:Enzyme-linked immunosorbent assays are plate-based tests detecting antigens or antibodies with high sensitivity and specificity. Large diagnostic laboratories frequently use ELISA for batch testing of samples for common animal diseases.
- PCR:Polymerase Chain Reaction technology amplifies specific DNA or RNA sequences, offering definitive detection of pathogens even at low concentrations. Advanced veterinary hospitals in Japan implement PCR for precise identification of viral infections.
- Lateral Flow Assays:These user-friendly, paper-based tests provide rapid, qualitative or semi-quantitative results for point-of-care applications. Veterinary clinics widely adopt these for their simplicity and speed in diagnosing common conditions.
- Fluorescent Immunoassays:Utilizing fluorescent labels for enhanced sensitivity, these tests offer quantitative results for various biomarkers. Specialized diagnostic centers in France employ fluorescent immunoassays for more accurate disease monitoring.
- Microarray:This high-throughput technology allows simultaneous detection of multiple analytes, providing comprehensive genetic or protein profiling. Research institutes apply microarray for complex disease research and vaccine development.
Lateral Flow Assays offer foundational utility, with PCR pushing diagnostic boundaries in terms of accuracy and specificity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The flow of advanced diagnostic technologies from developed economies to emerging markets like China is accelerating the adoption of veterinary rapid tests. This global movement facilitates the modernization of animal healthcare infrastructure and biosecurity protocols. Veterinary rapid diagnostic tests are crucial for timely clinical decisions across diverse animal populations.
China
China's extensive livestock sector drives significant demand for rapid tests, particularly for epizootic disease control. Government-led initiatives, such as those addressing African Swine Fever, mandate widespread surveillance on farms. Modernization efforts in provinces like Henan and Sichuan boost the deployment of rapid diagnostic tools for herd health management.
United States
Elevated spending on companion animal preventative care fuels rapid test demand across the United States. The US FDA's Center for Veterinary Medicine ensures test performance and safety for market approval. Veterinary clinics in metropolitan areas like Los Angeles prioritize advanced in-clinic diagnostics for immediate patient evaluations.
Brazil
Commercial livestock operations in Brazil increasingly adopt molecular platforms for definitive disease diagnosis. ANVISA regulations ensure the quality of veterinary diagnostic products entering the Brazilian market. Major cattle-producing regions such as Mato Grosso drive the implementation of rapid tests for herd health management, impacting food security and trade.
Germany
German diagnostic laboratories frequently employ traditional microbiological methods for antimicrobial resistance confirmation. The European Medicines Agency (EMA) establishes validation requirements for veterinary test performance and safety. Research institutions in Berlin contribute to developing novel diagnostic platforms for complex animal health issues.
Australia
Mobile veterinary units in Australia require portable, robust rapid diagnostic tests for immediate field results. The TGA oversees the quality and safety of veterinary diagnostic products available in Australia. Livestock operations in Queensland adapt biosecurity frameworks to incorporate rapid tests for swift containment measures.
Veterinary Rapid Diagnostic Tests Market Key Industry Players
Listed leaders compete with private specialists across integrated diagnostic solutions, offering varied product portfolios for veterinary care. The market structure exhibits a blend of large, diversified animal health corporations and focused diagnostic test manufacturers. Strategic archetypes include comprehensive solution providers, specialized rapid test developers, and broader pharmaceutical companies with diagnostic divisions. Companies frequently engage in portfolio diversification and geographic expansion to capture emerging market opportunities. Technology convergence also drives competitive moves, particularly in digital reader integration and connected diagnostic ecosystems.
Among the integrated solution providers, IDEXX Laboratories exemplifies a strategy centered on extensive in-clinic analyzers and rapid tests for point-of-care adoption. Zoetis, a global animal health company, represents a diversified approach, combining diagnostics with vaccines and pharmaceuticals to address broad animal health needs. Virbac, operating as a French public limited company, sits within the specialized diagnostic players, focusing on a targeted range of tests for specific animal health issues, often for niche animal health markets. These entities collectively shape the competitive dynamics through their distinct market approaches and continuous innovation efforts.
| Leading Market Players |
|---|
| Virbac |
| Neogen Corporation |
| IDEXX Laboratories |
| Bionote |
| bioMérieux |
| Zoetis |
| Heska Corporation |
| Fassisi |
| Thermo Fisher Scientific |
| Others |
Cost & Logistics Intelligence
High-volume manufacturing of lateral flow assays creates scale economies, concentrating production among a few large players. This concentration influences pricing power and establishes competitive price floors for rapid diagnostic tests.
Pricing Analysis
The pricing gap between established lateral flow assays and advanced molecular diagnostic platforms reflects varying R&D investments. Subscription-based models for in-clinic analyzers and consumables are gaining traction, while test kits often follow per-unit transactional pricing. Price differentiation stems from test sensitivity and brand reputation, with integrated software support also adding value. Pricing softness for high-volume rapid tests is intensifying due to increasing competition and manufacturing scale. Independent veterinary clinics exhibit high price sensitivity for advanced platforms, contrasting with large diagnostic laboratories seeking comprehensive solutions.
Supply Chain Analysis
Inventory strategies for veterinary rapid tests balance just-in-time procurement for common components with strategic stockpiles for specialized reagents. Supply concentration for key diagnostic components exists in China and parts of Europe. Manufacturing relies on a steady supply of antibodies, enzymes, and nitrocellulose membranes. Single-source vulnerability for proprietary biological reagents presents a structural risk. Distribution runs through established distributor networks, although direct sales and subscription models are increasingly common for integrated solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense, as traditional laboratory-based methods like PCR continue to pose a threat for definitive diagnoses. Incumbents must navigate this challenge by enhancing rapid test capabilities.
For Market Incumbents:Secure leadership by deepening software integration with veterinary practice management systems, reducing data integration complexity. Expand multiplex lateral flow assay capabilities to offer broader screening panels, countering the need for multiple single-analyte tests. Invest in R&D for microfluidics to enhance point-of-care accuracy. This strategy defends against substitution by traditional laboratory methods and strengthens channel control through bundled service offerings.
For New Entrants and Emerging Players:Differentiate on technology convergence by integrating microfluidics with smartphone-based digital readers. Target underpenetrated markets in Southeast Asia for livestock disease surveillance, focusing on local disease prevalence. Develop tests for emerging zoonotic pathogens, leveraging one-health initiatives for demand. A direct-to-clinic go-to-market angle, emphasizing ease of use and automated data reporting, can penetrate independent veterinary practices.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among companies offering bundled in-clinic analyzers and consumable subscriptions. The long-term viability of this market is anchored in global trends like pet humanization and mandatory livestock surveillance. Acquisition targets should be specialized rapid test developers with robust R&D pipelines for multiplex assays or digital integration. The signal to watch is the widespread adoption of connected diagnostic ecosystems in independent clinics.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Multiplex Assay Portfolio | Allows simultaneous detection of multiple pathogens, improving diagnostic efficiency for large commercial livestock operations. |
| Develop Connected Diagnostic Ecosystems | Integrates point-of-care devices with practice management software, streamlining workflows for veterinary clinics. |
| Target Emerging Zoonotic Pathogen Detection | Addresses one-health initiatives from the World Organisation for Animal Health, creating new test demand. |
| Implement Subscription-Based Service Models | Fosters direct relationships between manufacturers and independent veterinary clinics, ensuring recurring revenue. |
| Geographic Expansion into Southeast Asia | Deploys rapid tests for critical livestock diseases, enhancing food security in underpenetrated markets. |
Research Approach
Cross-validation between industry stakeholder interviews and regulatory filings anchors the qualitative findings of this analysis. Primary research involved discussions with veterinary clinic owners, diagnostic laboratory managers, animal health researchers, and rapid test manufacturers. Secondary validation drew from US FDA's Center for Veterinary Medicine guidance, European Medicines Agency reports, and World Organisation for Animal Health publications. A combination of bottom-up market sizing and top-down revenue analysis ensured data triangulation.
Sensitivity analysis informed the projection of market dynamics across the analysis window, accounting for various growth scenarios. The analytical framework modeled segmentation dimensions including product type, animal type, end-user, test technology, and regional adoption rates. Compound annual growth rates were derived from historical trends and projected market expansion factors. Key forecast inputs included global pet ownership growth rates and regional livestock disease outbreak frequencies.
Material uncertainties — unforeseen regulatory changes or major disease outbreaks — sit outside the modeled envelope, as forecasts reflect underlying assumptions. The emergence of novel pathogens presents a specific risk factor. Revision becomes warranted when significant shifts in animal health policy or diagnostic technology adoption rates cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
France in-Vitro Diagnostics Market
Diagnostics
Gastrointestinal Diagnostics Market
Diagnostics
Predictive Disease Analytics Market
Diagnostics
Mycology Immunoassays Testing Market
Diagnostics
Europe Womens Health Diagnostics Market
Diagnostics
Global Pelvic Floor Diagnostic Testing Market
Diagnostics
Home Diagnostics Market
Diagnostics
Asia-Pacific Syndromic Multiplex Diagnostic Market
Diagnostics
Fertility Test Market
Diagnostics
Diabetic Assays Market
Diagnostics
Fructosamine Reagents Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
Latent Tuberculosis Infection Detection Market
Diagnostics
Rapid RNA Testing Kits Market
Diagnostics
Alzheimer's Diagnostics and Therapeutics Market
Diagnostics
UAE in Vitro Diagnostics Market