
 Japan in-Vitro Diagnostics Market | 2026-2036
Japan in-Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Japan in-Vitro Diagnostics Market Outlook
The EU Green Deal is restructuring procurement criteria for Japanese IVD suppliers exporting to European healthcare systems. Sysmex Corporation anchors hematology automation through its domestic manufacturing footprint. Roche Diagnostics competes in molecular diagnostics through extensive R&D partnerships with Japanese university hospitals. Fujirebio Holdings specializes in neurodegenerative biomarker assays, occupying a distinctive niche in Alzheimer's testing protocols.
In-vitro diagnostics encompasses medical tests performed on biological specimens outside the living organism, utilizing reagent-based chemical reactions, immunological binding, or nucleic acid amplification to detect analytes with sensitivity thresholds reaching picogram-per-milliliter concentrations. These systems serve clinical decision-making by enabling disease screening, therapeutic monitoring, and personalized treatment selection. Reagents and test kits command the dominant value share due to recurring consumption models, while next-generation sequencing represents the fastest-expanding technology segment as oncology panels migrate from research to routine diagnostics. Immunoassays sustain substantial volume in cardiovascular and diabetes applications where standardized workflows reduce per-test labor costs.
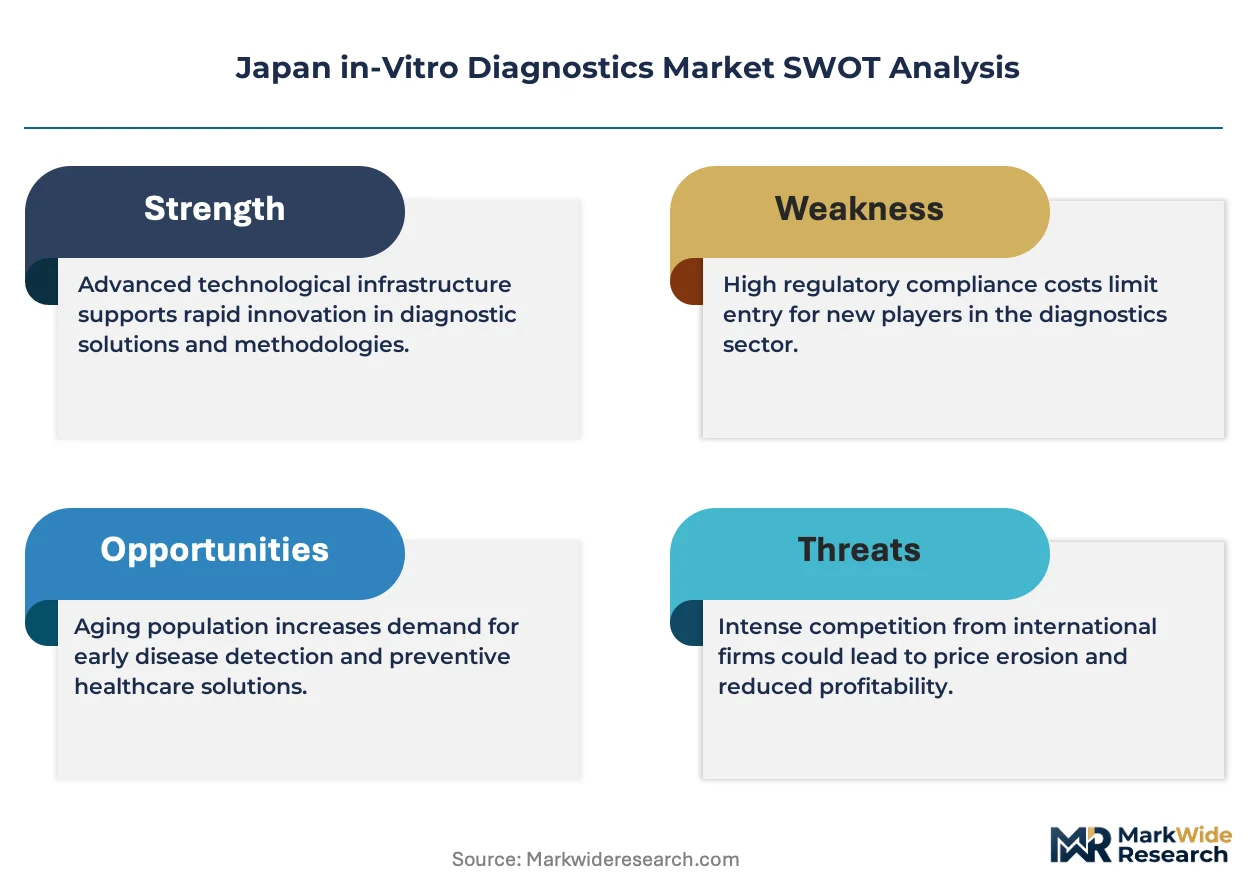
PMDA enforces stringent quality management system requirements under the Pharmaceutical and Medical Device Act, elevating compliance costs for foreign manufacturers seeking market entry. METI promotes domestic production of critical diagnostic components through industrial policy coordination with the Ministry of Health, Labour and Welfare. JIS standards govern instrument interoperability and data exchange protocols, shaping hospital procurement specifications. Stakeholders must monitor how Japan's reimbursement pricing revisions for innovative diagnostics will redistribute margin pools between instrument manufacturers and consumables suppliers.
Market Dynamics
Japan's in-vitro diagnostics sector faces a structural pivot as PMDA accelerates companion diagnostic approvals while hospital consolidation concentrates purchasing power among metropolitan academic medical centers.
Growth Catalysts
- Oncology panel expansion:Next-generation sequencing platforms are migrating from research laboratories into routine clinical workflows at Tokyo's cancer centers.
- METI industrial coordination:Domestic production incentives for critical diagnostic reagents reduce import dependency for time-sensitive immunoassay components.
- Neurodegenerative screening protocols:Alzheimer's biomarker assays are gaining reimbursement traction as Japan's aging population drives demand for early cognitive intervention.
Market Restraints
- Reagent cost volatility:Specialized antibodies and nucleic acid amplification chemistries face supply concentration from single-source foreign suppliers.
- PMDA quality system burden:Foreign manufacturers encounter elevated compliance costs under Pharmaceutical and Medical Device Act documentation requirements.
- Instrument interoperability limits:Legacy hospital information systems resist seamless integration with cloud-connected diagnostic platforms.
Strategic Opportunities
- Kansai region penetration:Osaka-Kobe medical corridor presents underdeveloped molecular testing capacity relative to Tokyo saturation.
- Home-based monitoring convergence:Point-of-care devices and telemedicine infrastructure create hybrid care models for chronic disease management.
- EU Green Deal alignment:Japanese suppliers can capture procurement preference by certifying sustainable manufacturing for European hospital exports.
Industry Challenges
- Bioinformatics talent scarcity:Genomic data interpretation and pipeline development outpace domestic training program output.
- Multi-platform integration complexity:Academic medical centers struggle to harmonize disparate instrument fleets under unified laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan in-Vitro Diagnostics Market |
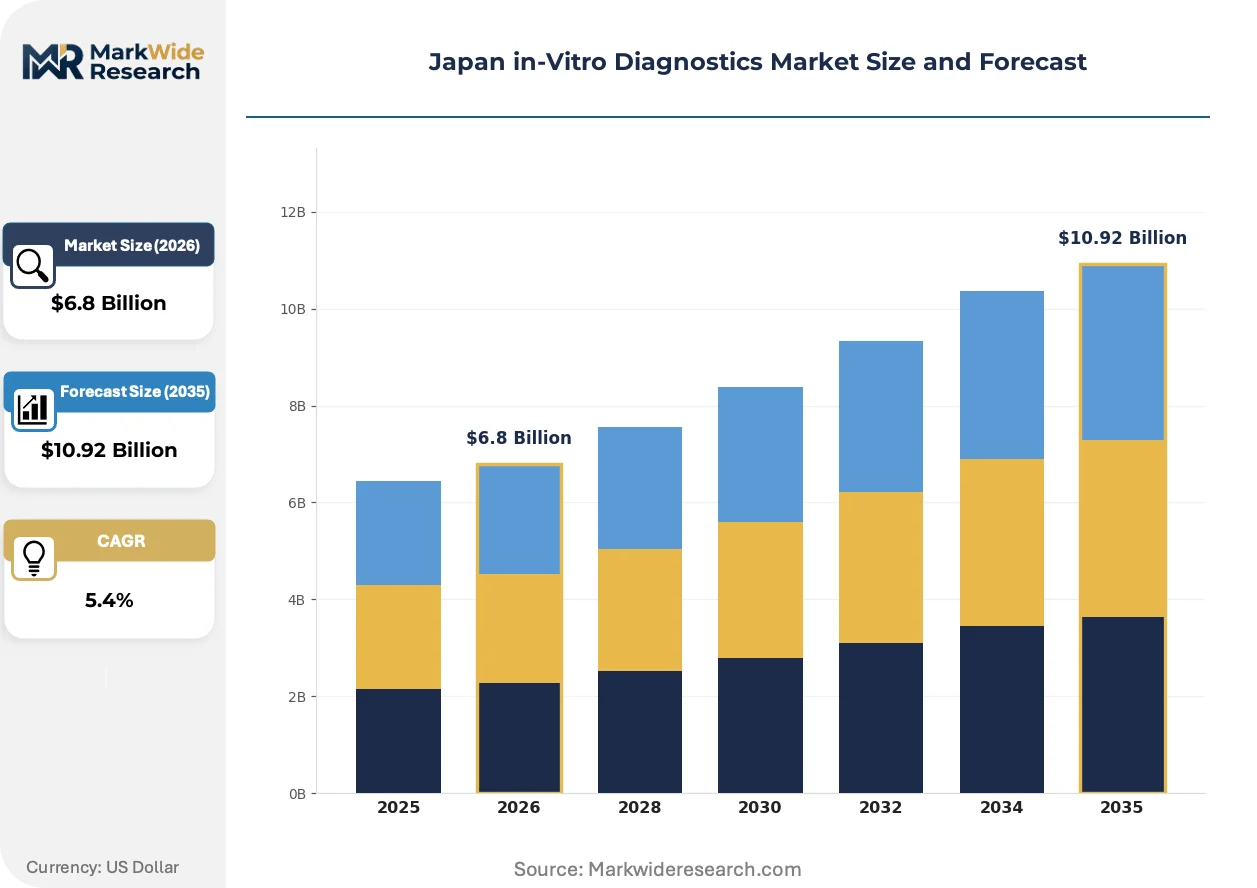
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Test Kits Application: Oncology, Infectious Diseases, Cardiovascular, Diabetes Technology: Polymerase Chain Reaction, Microarrays, Immunoassays, Next-Generation Sequencing End User: Hospitals, Laboratories, Home Care, Academic Institutions |
| Companies Covered | Roche Diagnostics, Sysmex Corporation, Abbott Laboratories, Danaher Corporation, bioMérieux, Thermo Fisher Scientific, Bio-Rad Laboratories, Siemens Healthineers, Fujirebio Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan in-Vitro Diagnostics Market Strategic Shifts
Digital pathology and artificial intelligence are compressing diagnostic turnaround times while reshaping laboratory workforce deployment across Japan's hospital networks.
Next-generation sequencing platforms is modularizing as vendors decouple hardware, wet chemistry, and bioinformatics into subscription-based components. Regional hospital networks in Hokkaido and Kyushu are adopting this architecture faster than independent urban laboratories. The shift is compressing capital expenditure barriers while accelerating test menu expansion without full instrument replacement cycles.
PMDA's streamlined companion diagnostic approval pathway is reducing time-to-market for oncology biomarker tests. Japanese pharmaceutical sponsors now coordinate parallel drug-diagnostic development earlier in clinical trial design. Molecular diagnostic manufacturers with established university hospital partnerships capture first-mover advantage in precision medicine protocols.
Consolidated purchasing consortia are displacing individual hospital procurement for high-volume reagent contracts. Tokyo metropolitan academic centers negotiate multi-year supply agreements directly with manufacturers, bypassing traditional distributor markups. This concentration is most visible in Kanto region hematology and chemistry analyzer placements where volume commitments secure preferential pricing tiers.
Japan in-Vitro Diagnostics Market Segmentation
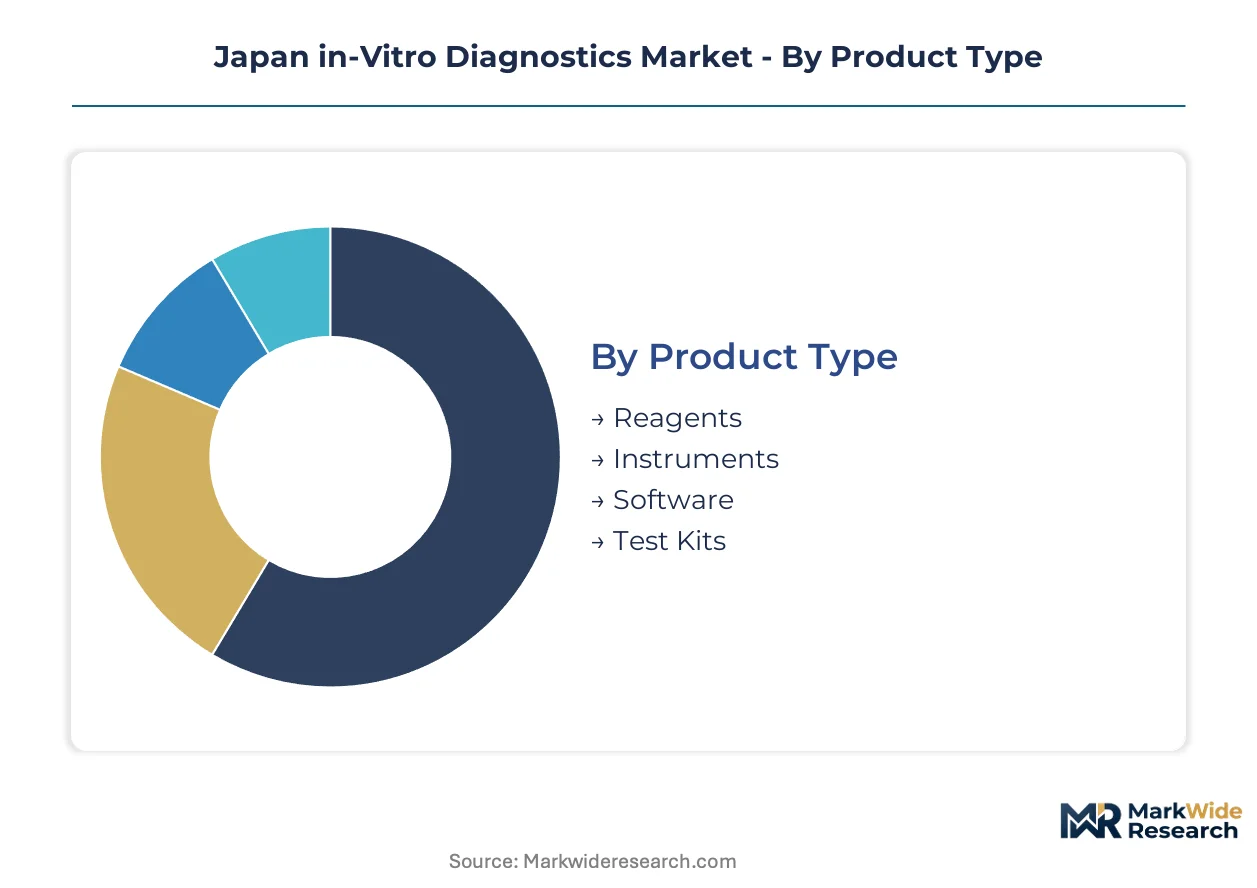
Japan's in-vitro diagnostics market fragments across four critical dimensions that determine procurement patterns and margin distribution. Supply concentration varies sharply by segment, with reagent manufacturers commanding recurring revenue streams while instrument vendors battle for placement in consolidated hospital networks.
Product Type:
Supply concentration tilts heavily toward consumables, where recurring purchase obligations lock hospital laboratories into long-term vendor relationships.
- Reagents:Specialized antibodies, nucleic acid amplification chemistries, and assay-specific consumables dominate value capture through recurring consumption models. Tokyo's metropolitan academic medical centers anchor demand as PMDA streamlines companion diagnostic approvals and molecular testing volumes expand.
- Instruments:Automated analyzers, sequencing platforms, and high-throughput screening systems require substantial capital deployment with extended replacement cycles. Osaka-Kobe medical corridor presents underdeveloped molecular testing capacity relative to Tokyo saturation, creating placement opportunities for newer hardware generations.
- Software:Laboratory information management systems and bioinformatics pipelines enable data integration across disparate instrument fleets.
- Test Kits:Pre-configured assay panels standardize workflows for routine diagnostic applications in cardiovascular and diabetes monitoring.
Today's leader: Reagents. Tomorrow's challenger: Software.
Application:
Cost tier stratification separates premium-priced oncology biomarker tests from standardized chronic disease panels, reshaping procurement negotiations.
- Oncology:Companion diagnostic assays and liquid biopsy panels command premium reimbursement as precision medicine protocols expand. Demand concentrates in Tokyo's cancer centers where next-generation sequencing platforms migrate from research into routine clinical workflows.
- Infectious Diseases:PCR-based pathogen detection and antimicrobial resistance profiling sustain volume in hospital microbiology laboratories.
- Cardiovascular:Troponin and natriuretic peptide immunoassays serve standardized workflows with reduced per-test labor costs.
- Diabetes:HbA1c and glucose monitoring reagents represent high-frequency, lower-margin testing with established reimbursement pathways.
Oncology claims the steepest expansion trajectory. Diabetes maintains volume dominance.
Technology:
Volume concentration favors mature immunoassay platforms while emerging modalities capture growth in academic medical center settings.
- Polymerase Chain Reaction:Thermal cycling instrumentation and nucleic acid amplification chemistries underpin infectious disease and oncology testing with established regulatory pathways.
- Microarrays:Genotyping panels and copy number variation analysis serve pharmacogenomic applications in consolidated metropolitan laboratories.
- Immunoassays:Chemiluminescence and enzyme-linked immunosorbent assays sustain substantial throughput in cardiovascular and endocrine diagnostics where workflow standardization reduces operational complexity.
- Next-Generation Sequencing:Massively parallel sequencing platforms and targeted oncology panels are modularizing into subscription-based components that compress capital barriers. Regional hospital networks in Hokkaido and Kyushu adopt this architecture faster than independent urban laboratories.
Immunoassays anchor current volume. Next-Generation Sequencing gains share fastest.
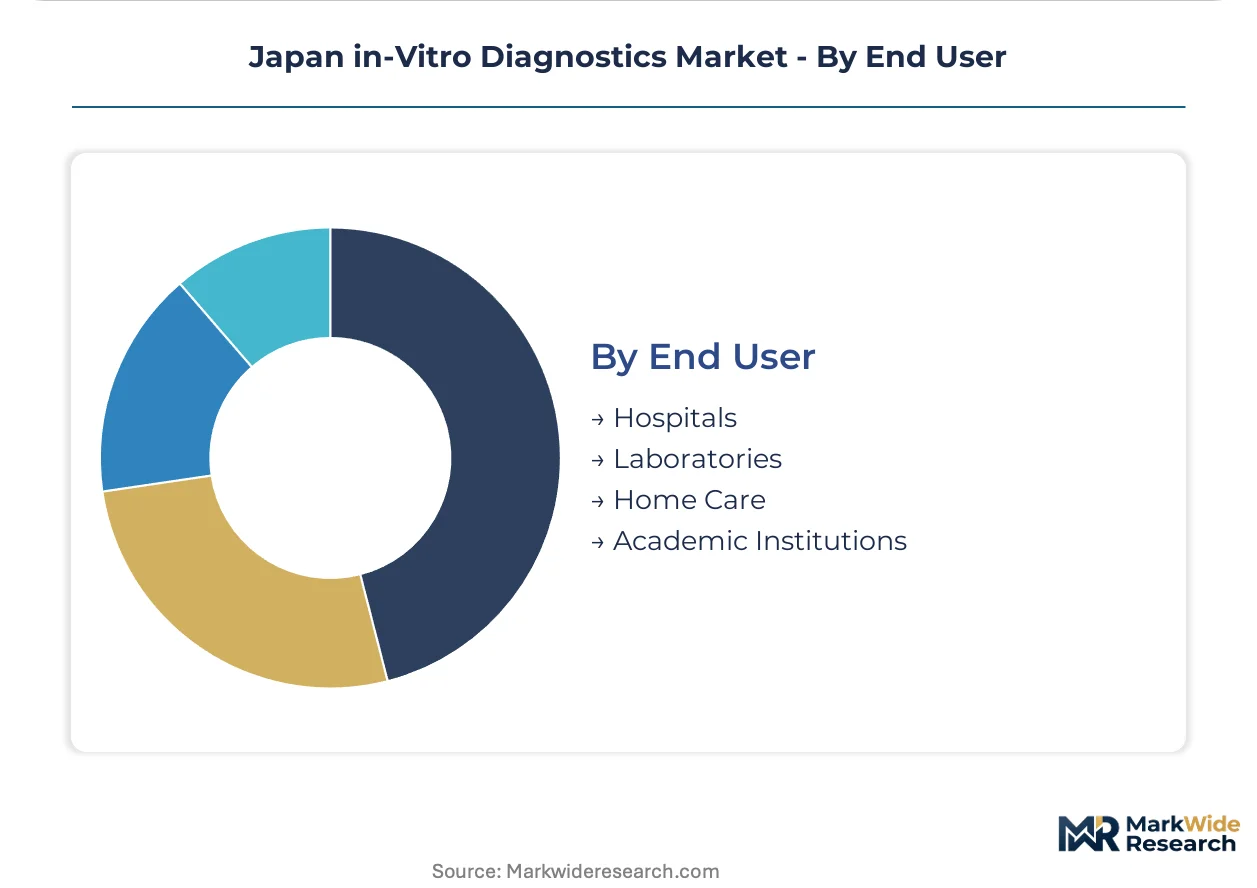
End User:
Customer type determines pricing power, with consolidated purchasing consortia displacing individual hospital procurement for high-volume contracts.
- Hospitals:Inpatient and outpatient diagnostic services drive reagent consumption through centralized laboratory operations. Consolidated purchasing consortia in the Kanto region negotiate multi-year supply agreements directly with manufacturers, bypassing traditional distributor markups.
- Laboratories:Independent reference laboratories and specialized testing facilities pursue differentiated assay menus.
- Home Care:Point-of-care devices and patient self-monitoring systems create hybrid care models for chronic disease management.
- Academic Institutions:Research-use-only assays and clinical trial support services bridge translational medicine pipelines.
Hospitals control procurement scale. Home Care represents the emerging frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's in-vitro diagnostics industry traces its modern roots to post-war reconstruction when domestic manufacturers scaled hematology and biochemistry platforms for hospital laboratories. Tokyo's metropolitan medical corridor emerged as the primary concentration of precision medicine adoption, anchored by academic medical centers that pioneered companion diagnostic protocols.
Kanto/Tokyo
Tokyo's cancer centers drive next-generation sequencing volumes as PMDA streamlines oncology biomarker approvals. METI coordinates domestic production incentives for critical diagnostic reagents through industrial policy alignment with the Ministry of Health, Labour and Welfare. The metropolitan academic medical corridor concentrates purchasing power through consolidated procurement consortia that negotiate multi-year supply agreements directly with manufacturers.
Kansai/Osaka
Osaka-Kobe medical corridor presents underdeveloped molecular testing capacity relative to Tokyo saturation, creating placement opportunities for newer hardware generations. JIS standards govern instrument interoperability specifications that shape hospital procurement decisions across the region. Regional hospital networks here adopt modular sequencing architectures faster than independent urban laboratories, compressing capital expenditure barriers.
Chubu/Nagoya
Nagoya's manufacturing heritage supports precision instrument production for automated analyzers and high-throughput screening systems. The Pharmaceutical and Medical Device Act elevates compliance costs for foreign manufacturers seeking market entry through this industrial hub. Medical device clusters in Aichi Prefecture coordinate component sourcing with diagnostic instrument assembly operations.
Kyushu
Fukuoka's biotech corridor attracts genomic data interpretation services as regional hospital networks adopt subscription-based sequencing components. PMDA quality management system requirements under the Pharmaceutical and Medical Device Act shape local regulatory consulting demand. The island's academic institutions bridge translational medicine pipelines between research-use-only assays and clinical trial support services.
Hokkaido
Sapporo's medical institutions pursue differentiated assay menus as geographic isolation necessitates self-sufficient diagnostic capabilities. Japan's reimbursement pricing revisions for innovative diagnostics redistribute margin considerations between instrument manufacturers and consumables suppliers across northern hospital networks. Regional laboratories here prioritize standardized workflows for cardiovascular and diabetes applications where per-test labor cost reduction matters most.
Japan in-Vitro Diagnostics Market Competitive Environment
Capital-heavy producers compete with asset-light designers across Japan's in-vitro diagnostics sector, where automated analyzer manufacturing demands substantial fixed investment while bioinformatics software development operates with minimal physical assets. The market structure tilts toward consolidated purchasing power at the customer end, with metropolitan academic medical centers displacing fragmented hospital procurement. Three archetypes dominate: diversified multinational health technology conglomerates with full diagnostic portfolios; specialized Japanese manufacturers with domestic manufacturing footprints and regulatory intimacy; and precision medicine-focused innovators concentrating on companion diagnostics and oncology biomarkers. Competitive moves center on strategic partnerships with university hospitals for clinical trial access and backward integration into critical reagent production to reduce import dependency.
Within the diversified multinational tier, Roche Diagnostics and Abbott Laboratories exemplify archetypes that leverage global R&D scale against localized regulatory navigation. Among Japan-based specialists, Sysmex Corporation occupies a position reflecting domestic manufacturing heritage in hematology automation, while Fujirebio Holdings represents the neurodegenerative biomarker niche with distinctive positioning in Alzheimer's testing protocols. These named entities anchor industry-level commentary without specifying individual strategic actions, product configurations, or financial performance metrics.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Sysmex Corporation |
| Abbott Laboratories |
| Danaher Corporation |
| bioMérieux |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Siemens Healthineers |
| Fujirebio Holdings |
| Others |
Value Chain & Pricing Dynamics
Backward integration into critical reagent production anchors both supply security and pricing power for Japanese IVD manufacturers responding to PMDA quality system requirements and METI domestic production incentives. This integration choice compresses import dependency for nucleic acid amplification chemistries while elevating compliance cost barriers for foreign competitors seeking market entry.
Pricing Analysis
Subscription-based modular pricing for next-generation sequencing platforms dominates as vendors decouple hardware, wet chemistry, and bioinformatics into tiered service components. Price differentiation rests on volume scale and PMDA companion diagnostic certification tier, with Tokyo's consolidated purchasing consortia extracting steeper discounts than regional hospital networks. Cost compression in standardized immunoassay reagents is intensifying because consolidated procurement displaces distributor markups. Academic medical centers demonstrate lowest price sensitivity for oncology biomarker panels, while regional laboratories in Hokkaido and Kyushu prioritize per-test economy.
Supply Chain Analysis
Single-source vulnerability sits with specialized antibody suppliers concentrated in the United States and Germany, where proprietary hybridoma cell lines and recombinant protein production anchor critical assay components. Raw material dependencies include high-purity enzymes, fluorescent dyes, and synthetic oligonucleotides that draw from Chinese and South Korean chemical manufacturing clusters. Tariff exposure on imported reagents elevates landed costs for foreign manufacturers navigating PMDA documentation requirements. Distribution runs through consolidated hospital procurement consortia in the Kanto region that negotiate direct manufacturer relationships, bypassing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's IVD sector represents a late-cycle quality story as precision medicine protocols shift demand toward premium-certified companion diagnostics and modular sequencing platforms. Oncology biomarker reimbursement traction and neurodegenerative screening protocol expansion justify specification upgrades across hospital laboratory networks.
For Market Incumbents: Deepen captive production of nucleic acid amplification chemistries to offset reagent cost volatility from single-source foreign suppliers. Fortify university hospital partnerships that secure first-mover positioning in PMDA-streamlined companion diagnostic approvals. METI industrial coordination incentives provide a funding lever for domestic manufacturing footprint expansion in the Chubu precision instrument cluster. For New Entrants and Emerging Players: PMDA's streamlined companion diagnostic approval pathway in Japan opens a window for precision medicine-focused innovators to establish clinical trial coordination capabilities with Tokyo cancer centers. White-space targets include the underdeveloped Osaka-Kobe molecular testing corridor and subscription-based bioinformatics services for regional hospital networks in Hokkaido. A go-to-market angle emphasizing modular sequencing architecture adoption compresses capital barriers for mid-tier facilities. For Investors and Strategic Acquirers: Roll-up economics work for specialized neurodegenerative biomarker assay developers because Alzheimer's testing protocol reimbursement creates predictable revenue streams in Japan's aging demographic structure. Long-term viability centers on platform-agnostic software capabilities that harmonize multi-vendor instrument fleets under unified laboratory information management systems. The signal to watch is PMDA reimbursement pricing revision timing for innovative diagnostics, which will redistribute margin pools between instrument and consumables suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Companion Diagnostic Submission | Accelerated approval pathways reduce time-to-market for oncology biomarker tests coordinated with pharmaceutical sponsors. |
| University Hospital Partnership | Clinical trial access and precision medicine protocol integration secure first-mover advantage in emerging diagnostic categories. |
| Domestic Reagent Manufacturing Scale-Up | METI production incentives reduce import dependency for time-sensitive immunoassay components under pharmaceutical regulations. |
| Modular Sequencing Platform Launch | Subscription-based architecture adoption in Hokkaido and Kyushu regional networks compresses capital expenditure barriers. |
| Cloud-Connected LIMS Integration | Artificial intelligence-enabled laboratory information systems address bioinformatics talent scarcity in genomic data interpretation. |
Study Parameters
Multiple input streams — laboratory director interviews, procurement manager surveys, and regulatory filing analysis — were reconciled to construct market estimates for Japan's in-vitro diagnostics sector. Primary discussions engaged biomedical engineers, hospital purchasing committee members, GPO contracts managers, and PMDA regulatory consultants across Tokyo, Osaka, and Fukuoka medical corridors. Secondary validation drew from PMDA approval databases, METI industrial policy white papers, JIS standards documentation, and hospital procurement contract records. Bottom-up instrument placement and reagent consumption models were triangulated against top-down healthcare expenditure flows.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation modeling across product type, application, technology, and end user dimensions. Oncology panel expansion rates, companion diagnostic approval velocities, and consolidated procurement penetration served as industry-specific forecast inputs. CAGRs were derived from trend extrapolation of historical placement data and reimbursement policy trajectory analysis.
Revisions become necessary when PMDA regulatory pathway modifications, METI incentive program adjustments, or reimbursement pricing reform announcements materialize with implementation timelines that alter manufacturer margin structures. Forecasts reflect documented assumptions regarding hospital consolidation velocity and precision medicine protocol adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Mycoplasma Diagnostics Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
Global Hemoglobin A1c Testing Devices Market
Diagnostics
Blood Ketone Test Meter Market
Diagnostics
Cushing's Syndrome Diagnostics and Therapeutics Market
Diagnostics
Creatinine Test Market
Diagnostics
Prenatal Diagnostics Market
Diagnostics
Global RSV Diagnostics Market
Diagnostics
Syndromic Multiplex Diagnostic Market
Diagnostics
Rapid Diagnostics Market
Diagnostics
Thrombosis and Hemostasis Biomarkers Market
Diagnostics
Critical Care Diagnostics Market
Diagnostics
Cellular Health Screening Market
Diagnostics
Global Exocrine Pancreatic Insufficiency (EPI) Therapeutics and Diagnostics Market
Diagnostics
Professional Diagnostics Market
Diagnostics
Global Kidney Cancer Diagnostics Market