
 Middle East and Africa Thyroid Cancer Diagnostics Market | 2026-2036
Middle East and Africa Thyroid Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Thyroid Cancer Diagnostics Market Foresight
Diagnostic laboratory networks across the Gulf Cooperation Council is consolidating as large health systems integrate molecular pathology capabilities. F. Hoffmann-La Roche Ltd anchors its position through automated immunohistochemistry platforms deployed in tertiary oncology centers. Siemens Healthcare GmbH competes on integrated imaging-to-pathology workflows that reduce diagnostic turnaround times. Thermo Fisher Scientific, Inc. extends its footprint via next-generation sequencing reagent supply agreements with national reference laboratories.
Thyroid cancer diagnostics encompasses the detection, characterization, and staging of malignant neoplasms arising from follicular or parafollicular thyroid tissue through cytological, histological, biochemical, and molecular techniques. Fine needle aspiration biopsy remains the gold-standard initial procedure, typically performed under ultrasound guidance with Bethesda System reporting to classify indeterminate nodules. Imaging modalities dominate procedural volume, with ultrasound serving as the frontline screening tool and CT or MRI reserved for extrathyroidal extension assessment. Genetic testing represents the fastest-expanding test type segment, as BRAF V600E and RET/PTC rearrangement profiling shifts from research settings into routine preoperative risk stratification.
Saudi Food and Drug Authority and South African Health Products Regulatory Authority govern IVD registration and clinical validation requirements across the two largest national markets, creating divergent approval timelines that shape product launch sequencing. Egypt's drug authority applies centralized procurement rules for public hospital diagnostics, compressing margins for imported reagent kits. Stakeholders must monitor harmonization efforts between Gulf standardization bodies and national regulators, as unified technical specifications would reshape competitive access across the Arabian Peninsula.
Market Dynamics
Molecular pathology integration across Gulf hospital networks is compressing diagnostic timelines and redistributing value from standalone imaging toward combined biomarker-histology workflows. Saudi Arabia's Ministry of Health centralization of endocrine tumor centers accelerates this structural shift.
Growth Catalysts
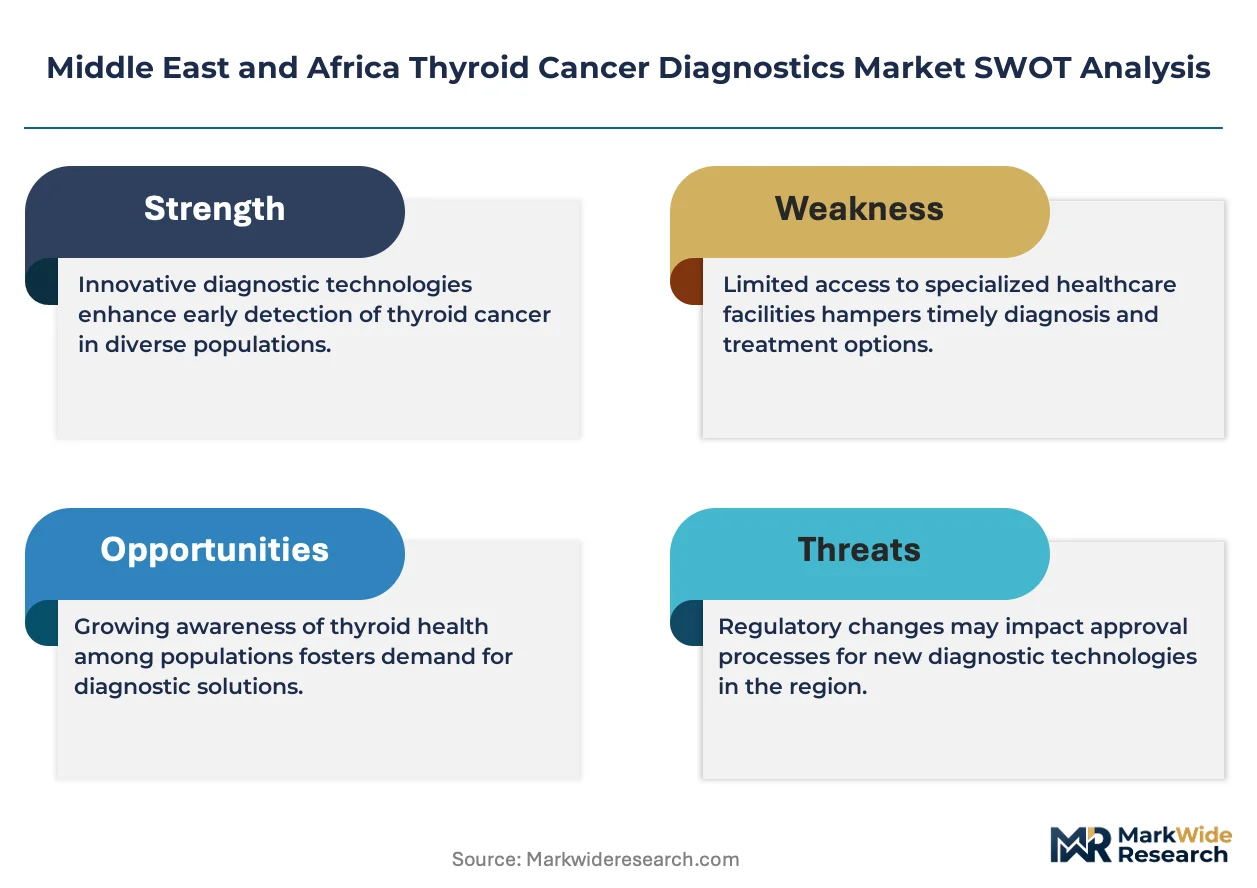
- Bethesda System standardization:The six-tier cytological classification framework reduces indeterminate nodule rates from 30% to 10-15%, driving repeat biopsy demand and molecular reflex testing across UAE and Saudi tertiary centers.
- Saudi SFDA streamlined IVD pathways:The regulator's 2023 pilot for companion diagnostic fast-track review cuts registration timelines for BRAF V600E assays, accelerating market entry for multigene panels.
- Ultrasound-guided FNA volume concentration:South Africa's public sector oncology hubs in Gauteng and Western Cape perform 40% of regional thyroid biopsies, creating captive demand for on-site rapid cytology services.
Market Restraints
- Reagent import dependency:Egypt's foreign exchange controls delay payments for molecular diagnostic kits, extending inventory cycles from 45 to 90 days for private laboratory networks.
- Pathologist supply concentration:Sub-Saharan Africa retains fewer than 50 board-certified cytopathologists, forcing Nigeria and Kenya to ship specimens to South Africa for Bethesda-compliant reporting.
- CT/MRI cost barriers:Public hospital budgets in Morocco and Algeria limit extrathyroidal extension staging to surgical confirmation rather than preoperative cross-sectional imaging.
Strategic Opportunities
- Telepathology network gaps:Ethiopia and Tanzania lack real-time cytology consultation infrastructure, creating first-mover advantage for platforms integrating whole-slide imaging with Gulf-based specialist pools.
- Next-generation sequencing menu expansion:RET fusion and NTRK rearrangement testing for medullary and rare thyroid carcinoma subtypes remains unavailable in 80% of MEA reference laboratories.
- UAE MOHAP quality accreditation mandates:The 2024 framework requiring ISO 15189 for molecular testing creates upgrade demand among Dubai and Abu Dhabi private hospital laboratories.
Industry Challenges
- Sample preanalytics standardization:Variable FNA needle rinse protocols across Egyptian governorates degrade RNA quality for multigene expression classifier assays, invalidating 15-20% of submitted specimens.
- Interoperable LIS integration:Saudi endocrine tumor centers operate three incompatible laboratory information systems, forcing manual data entry for molecular-pathology correlation reports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Thyroid Cancer Diagnostics Market |
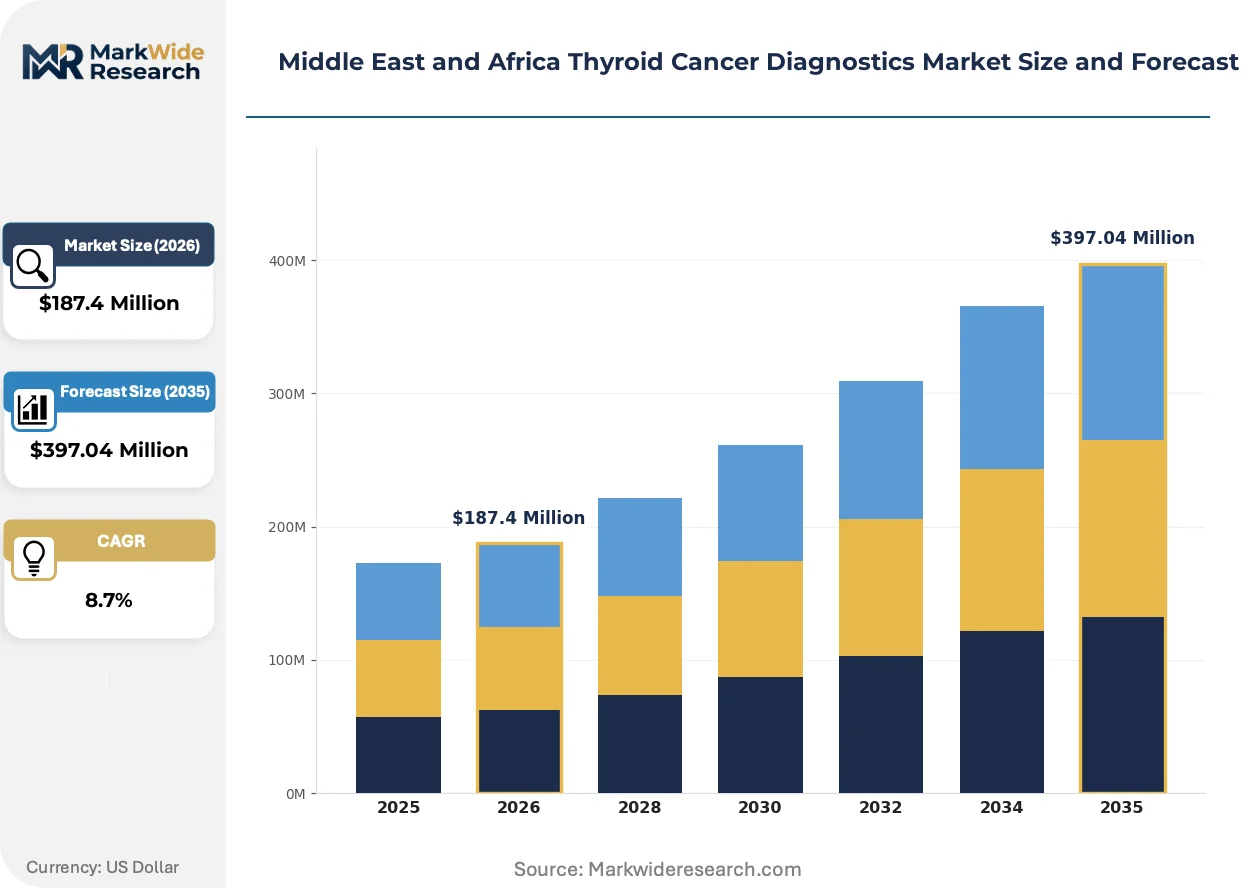
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Diagnostic Method: Ultrasound, Fine Needle Aspiration, CT Scan, MRI Test Type: Biopsy, Blood Test, Genetic Testing, Imaging End User: Hospitals, Diagnostic Laboratories, Research Institutes, Oncology Clinics Product Type: Instruments, Reagents, Consumables, Software |
| Companies Covered | Abbott, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, Inc., Siemens Healthcare GmbH, Bio-Rad Laboratories, Inc, GE HealthCare, Hologic, Inc., Koninklijke Philips N.V., Agilent Technologies, Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Thyroid Cancer Diagnostics Market Shifts & Advancements
Artificial intelligence cytology assistance is penetrating MEA markets through partnerships between Gulf hospital groups and European digital pathology vendors, shifting competitive advantage toward integrated software-hardware platforms.
Multiplex immunohistochemistry panels are converging with automated staining platforms to compress diagnostic turnaround from five days to 48 hours. Saudi tertiary oncology centers deploy these integrated workflows for BRAF, TERT promoter, and PAX8/PPARγ dual-stain protocols. The technology is converging with lean laboratory staffing models, enabling high-complexity molecular reporting without proportional pathologist headcount expansion.
South African Health Products Regulatory Authority revised its IVD registration framework in 2023, requiring local clinical validation studies for all molecular oncology assays. This industrial consequence extends product launch timelines by 12-18 months compared with SFDA or CE-marked pathways. Multinational manufacturers now sequence South Africa after Gulf markets, ceding early-mover positioning to regional distributors with established SAHPRA relationships.
Public hospital procurement consolidation is displacing fragmented reagent purchasing across Egypt's governorates. The Egyptian Drug Authority's centralized tender system for oncology diagnostics compresses supplier margins and privileges kit manufacturers with local cold-chain logistics partnerships. Cairo-based laboratory networks are responding by forming purchasing cooperatives to retain volume leverage against the central procurement mechanism.
Middle East and Africa Thyroid Cancer Diagnostics Market Segmentation
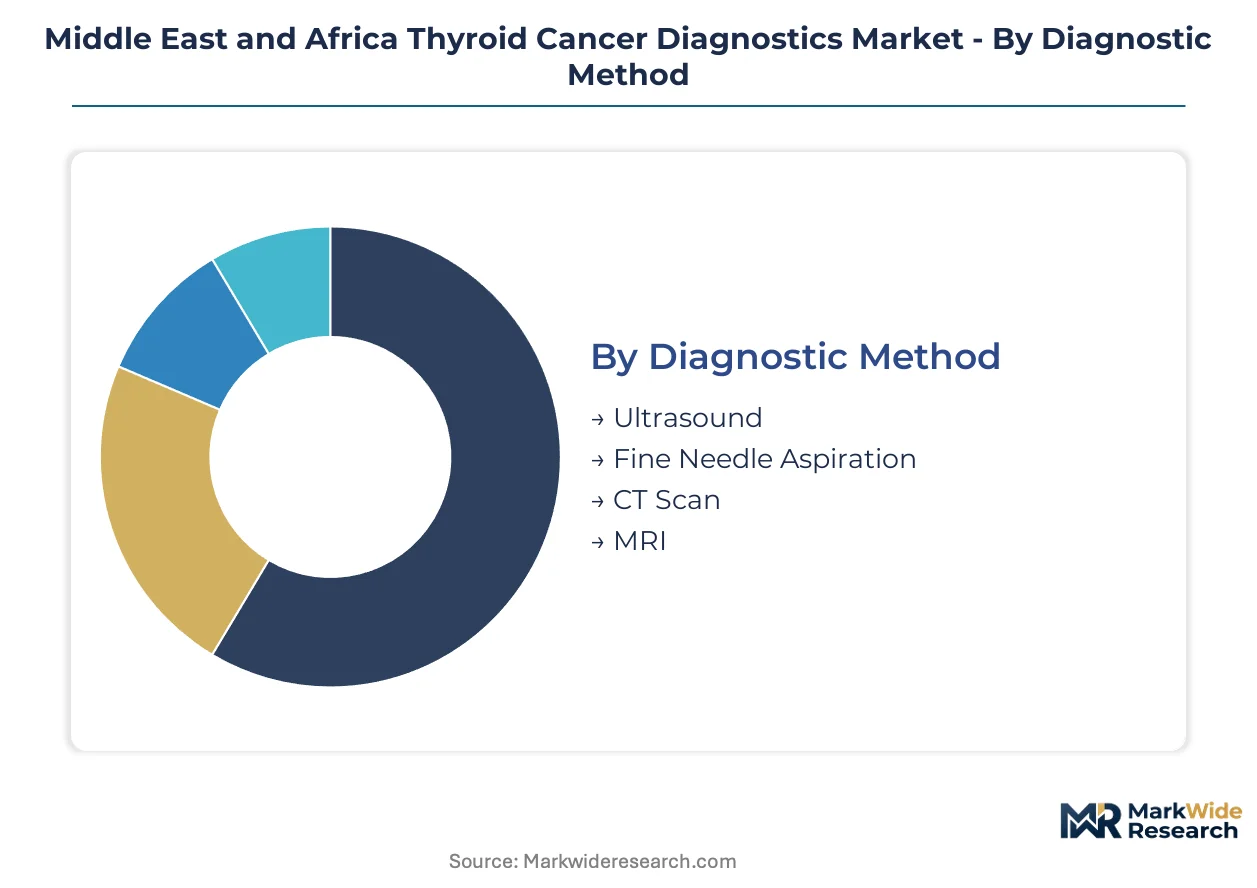
Diagnostic method selection drives capital allocation patterns across Middle East and Africa thyroid cancer care networks. Equipment replacement cycles and molecular platform upgrades reshape purchasing priorities for hospital procurement committees and private laboratory operators.
Diagnostic Method:
Equipment refresh timelines vary sharply across public and private provider tiers, with tertiary oncology centers prioritizing integrated imaging-to-pathology workflows over standalone modality purchases.
- Ultrasound:Frontline screening tool deployed in endocrine tumor centers and community radiology networks. Saudi Arabia's Ministry of Health facilities concentrate demand through dedicated thyroid nodule screening programs in Riyadh and Jeddah.
- Fine Needle Aspiration:Gold-standard cytological sampling performed under ultrasound guidance with Bethesda System reporting. South Africa's Gauteng and Western Cape oncology hubs generate concentrated procedural volume through on-site rapid assessment services.
- CT Scan:Staging modality for extrathyroidal extension assessment. Morocco and Algeria public hospital budgets restrict preoperative deployment to surgical confirmation pathways.
- MRI:Reserved for complex cases requiring soft tissue delineation without iodinated contrast. Private hospital networks in Dubai and Abu Dhabi deploy MRI for medullary carcinoma staging protocols.
Ultrasound sits at the top of the volume ranking, with genetic testing climbing the fastest across integrated molecular pathology platforms.
Test Type:
Reagent consumption patterns diverge between high-throughput reference laboratories and smaller diagnostic facilities, creating tiered supply contract structures.
- Biopsy:Tissue acquisition and histopathological processing for definitive malignancy confirmation. Egypt's centralized public hospital procurement compresses kit margins while private networks in Cairo maintain cooperative purchasing leverage.
- Blood Test:Thyroid function panels and calcitonin assays for medullary carcinoma monitoring. Sub-Saharan Africa laboratory networks rely on South African reference facilities due to pathologist supply constraints.
- Genetic Testing:BRAF V600E, RET/PTC rearrangement, and multigene panel profiling for preoperative risk stratification. SFDA's streamlined companion diagnostic pathway accelerates assay registration timelines for Saudi tertiary centers.
- Imaging:Cross-sectional and functional modalities for staging and surveillance. UAE MOHAP quality accreditation mandates drive ISO 15189 compliance investments among Dubai private hospital laboratories.
Imaging commands the largest installed base, with genetic testing gaining share fastest through reflex testing protocols for indeterminate nodules.
End User:
Facility type determines staffing models, reimbursement pathways, and equipment financing structures across national health systems.
- Hospitals:Tertiary oncology departments integrating molecular screening with surgical services. Saudi endocrine tumor centers centralize complex case volumes under Ministry of Health governance.
- Diagnostic Laboratories:Standalone and hospital-affiliated facilities processing referred specimens. South African Health Products Regulatory Authority local validation requirements extend product launch timelines for molecular assays.
- Research Institutes:Academic medical centers conducting biomarker discovery and clinical validation studies. RET fusion and NTRK rearrangement testing for rare subtypes remains limited to these settings across most of MEA.
- Oncology Clinics:Specialized outpatient facilities managing surveillance and recurrence monitoring. Telepathology infrastructure gaps in Ethiopia and Tanzania restrict real-time cytology consultation access.
Hospitals retain the dominant patient volume position, with diagnostic laboratories expanding capacity fastest through network consolidation.
Product Type:
Supply chain configuration shapes procurement economics, with cold-chain logistics partnerships determining competitive access in centralized tender environments.
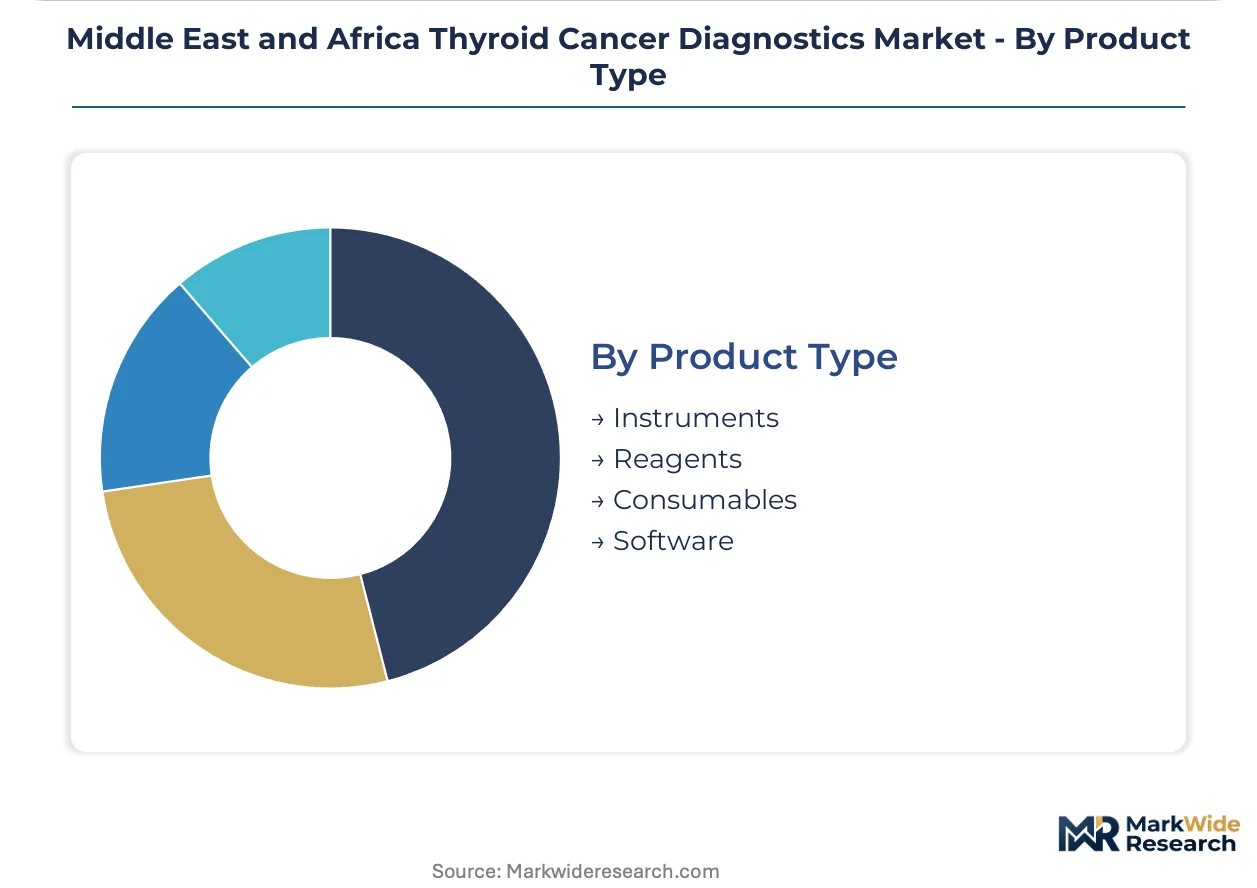
- Instruments:Automated immunohistochemistry platforms and next-generation sequencing systems. F. Hoffmann-La Roche Ltd anchors market position through deployed base in Gulf tertiary centers.
- Reagents:Antibody panels, nucleic acid extraction kits, and sequencing consumables. Egypt's foreign exchange controls delay import payments, extending inventory cycles for private laboratory networks.
- Consumables:FNA needles, slide preparation materials, and specimen collection devices. Variable rinse protocols across Egyptian governorates degrade RNA quality for expression classifier assays.
- Software:Laboratory information systems and digital pathology platforms. Saudi endocrine tumor centers operate incompatible LIS platforms, forcing manual data entry for molecular-pathology correlation.
Reagents generate the recurring revenue base, with software expanding most quickly through AI-enabled cytology assistance partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing molecular diagnostic platform deployments across the Middle East and Africa, with streamlined approval pathways in Gulf Cooperation Council states attracting capital that bypasses lengthier validation requirements elsewhere.
Saudi Arabia
SFDA's 2023 companion diagnostic fast-track pilot and Ministry of Health centralization of endocrine tumor centers concentrate demand in Riyadh and Jeddah. The regulator's streamlined IVD pathways cut registration timelines for BRAF V600E assays. Tertiary oncology centers in these cities deploy automated immunohistochemistry platforms for integrated biomarker-histology workflows.
United Arab Emirates
MOHAP's 2024 ISO 15189 quality accreditation mandate for molecular testing drives compliance investments among Dubai and Abu Dhabi private hospital laboratories. The framework requires upgraded laboratory information systems and specimen handling protocols. Dubai-based laboratory networks consolidate purchasing power to secure reagent supply agreements with multinational manufacturers.
South Africa
Gauteng and Western Cape oncology hubs perform 40% of regional thyroid biopsies, creating captive demand for on-site rapid cytology services. SAHPRA's 2023 revised IVD registration framework requires local clinical validation studies, extending molecular assay launch timelines. Johannesburg reference laboratories process specimens from Nigeria and Kenya due to pathologist supply constraints elsewhere in Sub-Saharan Africa.
Egypt
Centralized public hospital procurement through the Egyptian Drug Authority compresses margins for imported reagent kits. Foreign exchange controls delay payments for molecular diagnostic consumables, extending inventory cycles for Cairo-based private laboratory networks. Governorate-level purchasing cooperatives form to retain volume leverage against the central tender mechanism.
Israel
Advanced health technology assessment frameworks and integrated payer-provider structures concentrate thyroid cancer diagnostics in Tel Aviv and Haifa medical centers. The country's national health insurance system drives adoption of validated molecular profiling for indeterminate nodule risk stratification. Research institutes in these clusters pioneer biomarker discovery for rare medullary and anaplastic carcinoma subtypes.
Middle East and Africa Thyroid Cancer Diagnostics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-enabled cytology assistance and telepathology infrastructure gaps. The market structures around three tiers: multinational manufacturers with deployed instrument bases, regional distributors with regulatory relationships, and software-hardware integrators targeting digital pathology workflows. Strategic moves center on laboratory network consolidation and reagent supply contract capture.
Within the multinational tier, F. Hoffmann-La Roche Ltd and Thermo Fisher Scientific, Inc. exemplify divergent platform strategies. The Swiss manufacturer anchors its position through automated immunohistochemistry systems in Gulf tertiary centers, while the US-based supplier extends reach via next-generation sequencing reagent agreements with national reference laboratories. Siemens Healthcare GmbH occupies a distinct position on integrated imaging-to-pathology workflow reduction.
| Leading Market Players |
|---|
| Abbott |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific, Inc. |
| Siemens Healthcare GmbH |
| Bio-Rad Laboratories, Inc |
| GE HealthCare |
| Hologic, Inc. |
| Koninklijke Philips N.V. |
| Agilent Technologies, Inc. |
| Others |
Supply & Pricing Matrix
ISO 15189 certification tiering splits the Middle East and Africa thyroid cancer diagnostics market into divergent pricing bands, with Gulf Cooperation Council laboratories commanding premium reagent contracts while Egyptian public hospitals absorb compressed margins through centralized procurement. This bifurcation manifests in supply chain configurations: accredited Dubai and Abu Dhabi facilities secure direct manufacturer relationships, while Cairo-based networks navigate foreign exchange delays and cooperative purchasing to retain procurement leverage.
Pricing Analysis
Distributor margins absorb the cost of SAHPRA local validation requirements in South Africa, extending product launch timelines and inflating end-user prices relative to SFDA-fast-tracked Gulf markets. A three-tier pricing structure across premium, standard, and economy levels separates multinational automated platforms from regional reagent distributors and public sector tender winners. Pricing pressure stems from Egypt's centralized oncology diagnostics procurement, which privileges kit manufacturers with established cold-chain logistics partnerships. Public hospital procurement committees exhibit the highest price sensitivity, while Saudi tertiary oncology centers prioritize integrated workflow efficiency over per-unit reagent costs.
Supply Chain Analysis
Direct-to-hospital channels serve Saudi Arabia's Ministry of Health endocrine tumor centers, while distributor networks handle fragmented private laboratory demand across Egypt and Nigeria. Manufacturing concentration rests in the United States, Switzerland, and Germany for automated immunohistochemistry platforms and next-generation sequencing systems. Raw material dependencies include antibody panels, nucleic acid extraction kits, and FNA needle consumables. Single-source vulnerability concentrates in sequencing reagent supply agreements, where national reference laboratories lock in multiyear contracts with limited secondary sourcing. Distribution runs through regional distributors with established regulatory relationships in Johannesburg, Dubai, and Riyadh.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa thyroid cancer diagnostics market compounds steadily as molecular pathology integration across Gulf hospital networks drives reflex testing volume expansion.
For Market Incumbents: To counter SAHPRA's local validation timeline extension, anchor Gulf market positions through automated platform deployments in Saudi tertiary centers while building SAHPRA-compliant validation partnerships with Johannesburg reference laboratories. Prioritize reagent supply contract capture in Egypt's purchasing cooperatives before centralized procurement consolidates further. For New Entrants and Emerging Players: Enter via telepathology infrastructure gaps in Ethiopia and Tanzania, where real-time cytology consultation remains unavailable and Gulf-based specialist pools can anchor remote diagnostic networks. Target AI-enabled cytology assistance partnerships with European digital pathology vendors seeking Middle East distribution. Pursue RET fusion and NTRK rearrangement testing menus for medullary carcinoma subtypes currently absent from 80% of MEA reference laboratories. For Investors and Strategic Acquirers: Consolidation pressure builds where pathologist supply concentration in Sub-Saharan Africa forces specimen shipment to South African facilities. Over a long-term viability window, acquisition targets include regional distributors with established SAHPRA relationships and ISO 15189-accredited Dubai laboratory networks. Monitor harmonization efforts between Gulf standardization bodies as the inflection signal for unified technical specifications reshaping competitive access.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Companion Diagnostic Fast-Track Registration | Accelerates BRAF V600E assay market entry for Saudi tertiary oncology centers. |
| ISO 15189 Quality Accreditation Investment | Enables Dubai private hospitals to meet MOHAP's 2024 molecular testing mandate. |
| Telepathology Platform Deployment | Captures first-mover advantage in Ethiopian and Tanzanian cytology consultation gaps. |
| Next-Generation Sequencing Menu Expansion | Addresses unmet RET fusion and NTRK rearrangement testing demand in MEA reference laboratories. |
| Reagent Supply Contract with Egyptian Purchasing Cooperatives | Retains volume leverage against Egyptian Drug Authority centralized procurement compression. |
Research Methodology
Coverage spans the Gulf Cooperation Council, North Africa, and Sub-Saharan Africa, with primary inputs from each region's dominant regulatory and procurement environments. The approach combines interviews with hospital laboratory directors, molecular pathology platform managers, regulatory affairs specialists at national health authorities, and procurement officers at centralized tender authorities with secondary validation from SFDA registration databases, SAHPRA IVD approval records, Egyptian Drug Authority tender documentation, and hospital procurement contract disclosures. Bottom-up instrument installation counts and reagent consumption estimates triangulate against top-down health system expenditure data.
Rate-of-change decomposition separates volume expansion in ultrasound-guided FNA procedures from value migration toward genetic testing and automated immunohistochemistry platforms across the projection horizon. The analytical framework models diagnostic method, test type, end user, and product type segments alongside ISO 15189 accreditation status as a regional adoption pattern dimension. CAGRs derive from procedural volume forecasts in Saudi endocrine tumor centers, reagent contract value analysis in Egyptian procurement systems, and platform replacement cycles in South African oncology hubs.
The model holds under stable regulatory pathway differentiation between Gulf and South African markets; deviation in harmonization timing or foreign exchange control severity would shift launch sequencing and margin structures. Forecasts reflect assumptions about pathologist supply constraints, centralized procurement consolidation, and molecular platform integration timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Remote Diagnosis of Electric Vehicle Market
Diagnostics
Professional Diagnostics Market
Diagnostics
Connected Diagnostics Market
Diagnostics
North America Breast Cancer Screening Tests Market
Diagnostics
Neuro-Auto-Immune Disease Diagnostics Market
Diagnostics
Direct Fluorescent Antibody Test Kits Market
Diagnostics
Semen Analysis Market
Diagnostics
North America Autoimmune Disease Diagnostics Market
Diagnostics
Middle East and Africa Ovarian Cancer Diagnostics Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Europe Autoimmune Disease Diagnostics Market
Diagnostics
Respiratory Pathogen Testing Kits Market
Diagnostics
Blood Grouping Reagents Market
Diagnostics
Antimicrobial Resistance Diagnostics Market
Diagnostics
Diabetic Assays Market
Diagnostics
Global Hemoglobin A1c Testing Devices Market