
 Diabetic Assays Market | 2026-2036
Diabetic Assays Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetic Assays Market Analysis
Clinical laboratory technician specialization is rotating toward molecular diagnostics and biosensor calibration, tightening availability for conventional enzymatic assay workflows. Abbott leverages vertical integration across test strip manufacturing and continuous glucose monitor production to sustain cost advantages in homecare channels. F. Hoffmann-La Roche Ltd anchors hospital laboratory demand through automated analyzer systems that dominate high-throughput glucose testing environments.
Diabetic assays comprise analytical methods and consumable reagents designed to quantify blood glucose, glycated hemoglobin, and related metabolic markers, typically employing enzymatic oxidation reactions with glucose oxidase or hexokinase at specified temperature and pH conditions to ensure diagnostic accuracy for diabetes management. Continuous glucose monitors represent the fastest-growing product type as real-time data streams displace episodic fingerstick testing in intensive insulin therapy, while enzymatic assays retain the largest revenue pool within hospital and reference laboratory settings where regulatory validation requirements create switching costs. Test strips maintain substantial volume in retail pharmacy and homecare segments, though margin compression from private-label competition constrains branded positioning.
FDA premarket notification requirements under 21 CFR Part 862 govern glucose assay accuracy standards and predicate device comparisons, while Clinical Laboratory Improvement Amendments mandate proficiency testing for laboratory-based HbA1c methods. The Centers for Medicare & Medicaid Services reimbursement schedules directly shape adoption velocity for continuous versus episodic monitoring modalities. Stakeholders must monitor evolving FDA guidance on integrated closed-loop systems that combine glucose sensing with automated insulin delivery algorithms.
Market Dynamics
Continuous glucose monitoring platforms are compressing the addressable market for conventional enzymatic assays as real-time data streams restructure diabetes management workflows across hospital and homecare settings.
Growth Catalysts
- Automated analyzer deployment:Hospital laboratories accelerate replacement of manual glucose oxidase methods with high-throughput hexokinase systems to reduce turnaround times for critical care decisions.
- Integrated health system procurement:United States-based accountable care organizations consolidate purchasing of continuous monitoring devices through volume-based contracts that bundle sensors with data analytics.
- FDA 510(k) pathway streamlining:Predicate device comparisons for next-generation biosensors compress premarket notification timelines, enabling faster commercialization of non-invasive glucose sensing technologies.
Market Restraints
- Enzyme reagent cost volatility:Glucose oxidase and hexokinase raw material prices fluctuate with fermentation capacity constraints in Asian biomanufacturing hubs, squeezing margins on disposable test strips.
- Reference laboratory concentration:Quest Diagnostics and LabCorp networks control proficiency testing logistics for HbA1c methods, creating switching costs for smaller clinical laboratories seeking alternative vendors.
- Optical sensor calibration drift:Factory calibration assumptions degrade with patient physiology variation, limiting accuracy of non-invasive glucose monitors against fingerstick gold standards.
Strategic Opportunities
- Rural homecare penetration:Telehealth reimbursement expansions under CMS remote patient monitoring codes enable continuous glucose monitor deployment in underserved United States counties lacking endocrinology specialists.
- Closed-loop algorithm integration:Convergence of glucose sensing with automated insulin delivery creates demand for dual-function assay platforms that validate sensor accuracy against laboratory reference methods.
- Retail pharmacy channel expansion:CVS Health and Walgreens Boots Alliance build point-of-care HbA1c testing capabilities, opening direct-to-consumer revenue streams bypassing traditional laboratory intermediaries.
Industry Challenges
- Biosensor calibration expertise scarcity:Clinical laboratory technician training programs emphasize molecular diagnostics over electrochemical sensor maintenance, creating workforce gaps for continuous monitor validation.
- Interoperability certification complexity:FDA software-as-medical-device requirements for data integration between glucose monitors and electronic health records extend development timelines for platform-agnostic systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetic Assays Market |
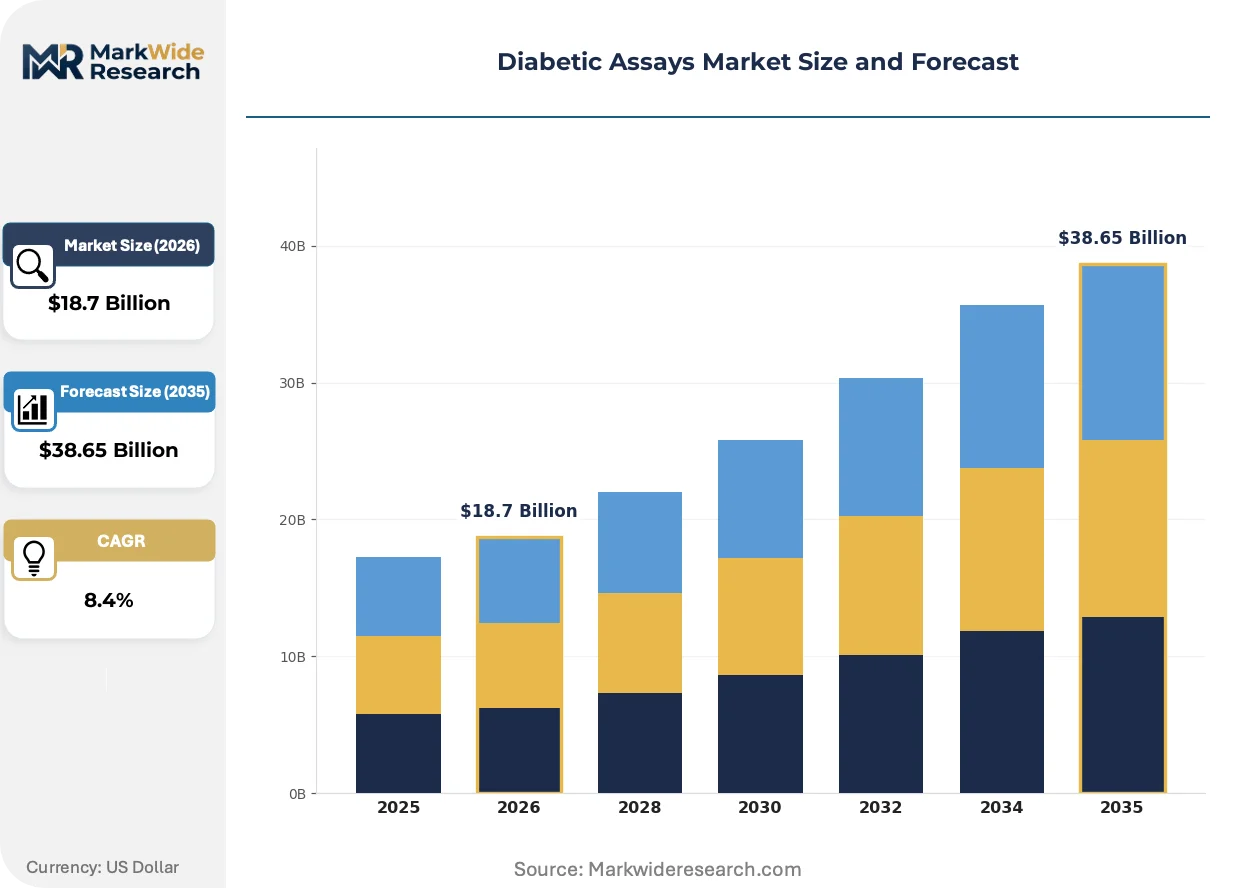
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Meters, Continuous Glucose Monitors, Reagents, Test Strips Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Monitoring End User: Hospitals, Clinics, Homecare, Retail Pharmacies Technology: Infrared Spectroscopy, Enzymatic Assays, Biosensors, Electrophoresis |
| Companies Covered | Abbott, F. Hoffmann-La Roche Ltd, Medtronic, Dexcom, Inc., Siemens Healthcare GmbH, Bio-Rad Laboratories, Inc., BioMerieux, DiaSorin S.p.A, Ortho Clinical Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetic Assays Market Emerging Trajectories
Real-time metabolic data streams are restructuring competitive advantage around software analytics and predictive algorithms rather than hardware accuracy alone. Three developments dominate strategic positioning.
Non-invasive optical glucose sensing is supplanting interstitial fluid-based electrochemical methods in wellness and pre-diabetes screening segments. Corporate wellness programs at UnitedHealth Group and Kaiser Permanente pilot smartphone-integrated spectroscopic devices for population-scale glucose trend monitoring. The technology is supplanting fingerstick-dependent disease management models with continuous lifestyle feedback loops that reduce progression to pharmacologic intervention.
Europe's Medical Device Regulation imposes stricter clinical evidence requirements for glucose monitoring software updates, forcing manufacturers to maintain post-market surveillance infrastructures. Class IIa reclassification of algorithm-modified continuous monitors triggers notified body review cycles that delay feature rollouts by 12-18 months. German and French hospital procurement offices now require MDR technical documentation as a gatekeeping criterion for tender participation.
Subscription-based sensor replacement models displace traditional device ownership in United States commercial insurance channels. Patients receive monthly shipments of disposable patches paired with mobile app coaching, replacing upfront capital expenditure with recurring revenue streams. This consumption pattern shift concentrates most visibly in employer-sponsored health plans administered by Express Scripts and OptumRx, where per-member-per-month budgeting aligns purchasing with pharmacy benefit management workflows.
Diabetic Assays Market Segmentation
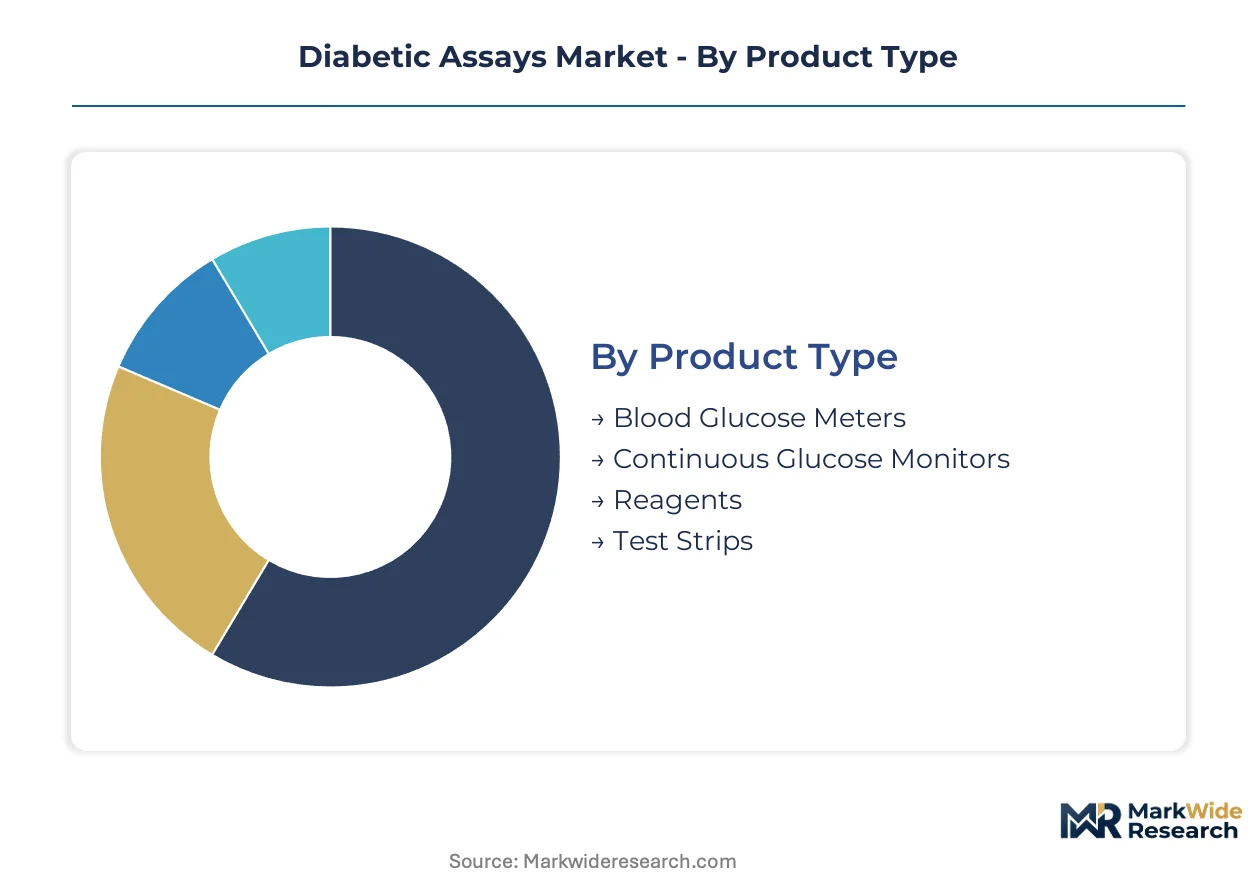
Segmentation reveals divergent growth vectors across the diabetic assays landscape. Product type splits between institutional laboratory systems and patient-worn devices, while end-user concentration determines reimbursement pathways and margin structures.
Product Type:
Domestic manufacturing dominates test strips and reagents, while continuous glucose monitors rely on Asian sensor fabrication and European software development.
- Blood Glucose Meters:Handheld electrochemical devices measuring capillary glucose via glucose oxidase or hexokinase reactions. Hospital procurement in the United States favors FDA-cleared units with data port connectivity to electronic health records, though homecare volume concentrates in retail pharmacy chains.
- Continuous Glucose Monitors:Interstitial fluid sensors transmitting real-time glucose data to receivers or smartphones. Demand clusters in employer-sponsored health plans and integrated delivery networks seeking to reduce HbA1c variability through automated alerts.
- Reagents:Enzyme-based liquid or lyophilized formulations for laboratory analyzers. Production concentrates in German and Swiss chemical manufacturing hubs serving reference laboratories.
- Test Strips:Single-use electrochemical strips for capillary blood application. Volume leadership sits with private-label pharmacy brands compressing branded margins in North American retail channels.
Test strips hold the largest share; momentum sits with continuous glucose monitors.
Application:
Type 2 diabetes generates absolute volume, while gestational diabetes commands premium pricing through obstetric specialist channels.
- Type 1 Diabetes:Absolute insulin deficiency requiring intensive glucose monitoring. Continuous monitor penetration approaches saturation in pediatric endocrinology practices at major United States academic medical centers.
- Type 2 Diabetes:Insulin resistance and progressive beta-cell dysfunction. Episodic testing dominates oral therapy management, though insulin-intensified subsets convert to continuous monitoring.
- Gestational Diabetes:Glucose intolerance diagnosed during pregnancy. Point-of-care testing in obstetric clinics drives reagent strip consumption with stricter glycemic targets than general diabetes populations.
- Monitoring:Surveillance of at-risk or pre-diabetic populations. Corporate wellness programs at UnitedHealth Group pilot non-invasive screening for progression prevention.
Type 2 diabetes holds the largest share; gestational diabetes shows the steepest expansion trajectory.
End User:
Institutional buyers consolidate purchasing through group purchasing organizations, while homecare channels fragment across retail and direct-to-consumer platforms.
- Hospitals:High-throughput central laboratories and point-of-care units in emergency departments. Automated hexokinase analyzers from Roche and Abbott dominate critical care glucose testing workflows.
- Clinics:Endocrinology and primary care practices. HbA1c point-of-care devices enable same-visit therapeutic adjustments, reducing referral laboratory dependency.
- Homecare:Patient-managed testing environments. Medicare reimbursement codes for remote patient monitoring expand continuous monitor eligibility to rural counties lacking specialist access.
- Retail Pharmacies:CVS Health and Walgreens Boots Alliance operate point-of-care HbA1c testing with immediate prescription fulfillment integration.
Hospitals hold the largest share; homecare gains share fastest through telehealth reimbursement expansion.
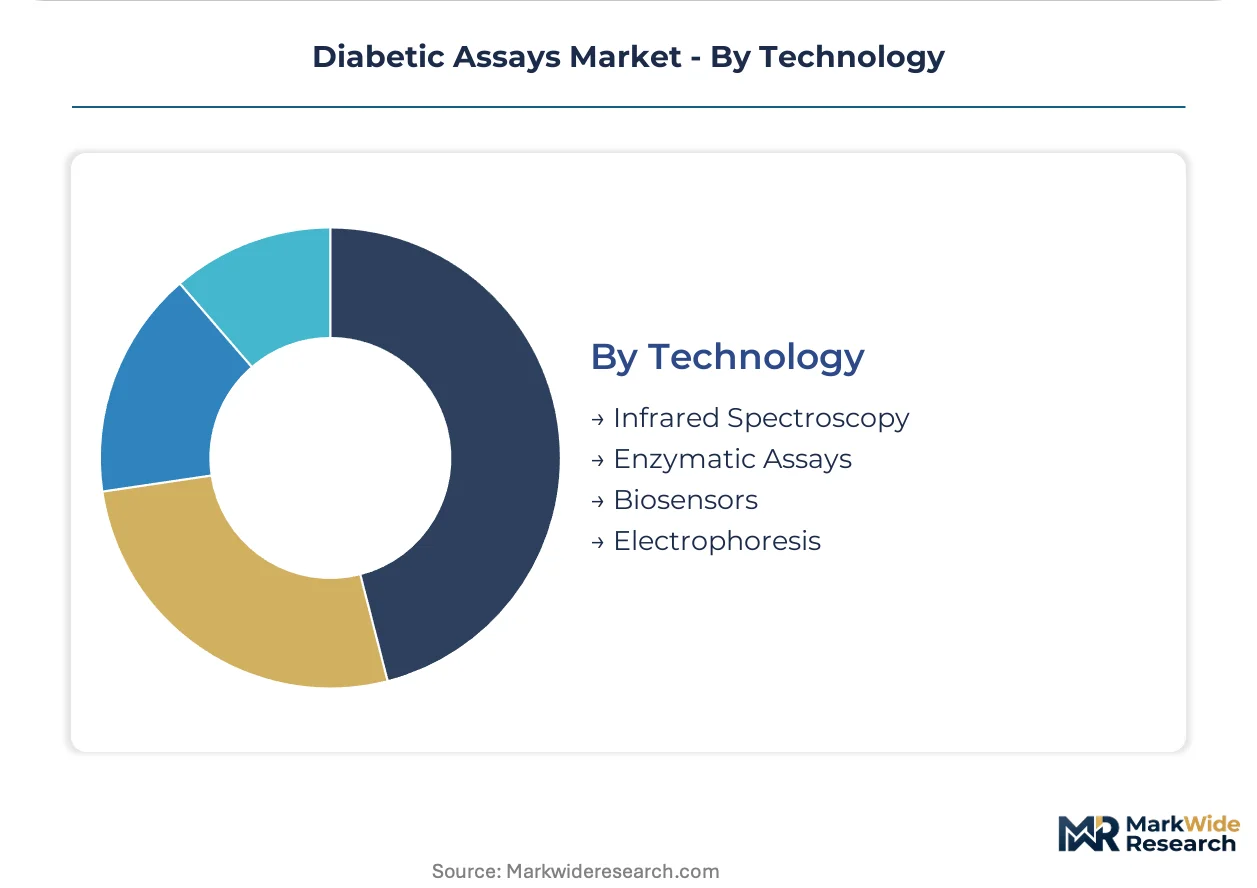
Technology:
Enzymatic methods anchor laboratory accuracy standards, while optical and electrochemical innovations target non-invasive or minimally invasive applications.
- Enzymatic Assays:Glucose oxidase or hexokinase catalytic reactions with colorimetric or amperometric detection. Reference laboratories maintain these as gold standard methods for FDA 510(k) predicate comparisons.
- Biosensors:Electrochemical transducers converting biological signals to measurable outputs. Continuous glucose monitors deploy amperometric glucose oxidase sensors with factory calibration algorithms.
- Infrared Spectroscopy:Non-invasive optical glucose detection through skin transmittance or reflectance. Wellness segment pilots at Kaiser Permanente target pre-diabetes population screening without fingerstick requirements.
- Electrophoresis:Charge-based separation for HbA1c quantification. High-complexity reference laboratories apply this for standardized proficiency testing against point-of-care methods.
Enzymatic assays hold the largest share; biosensors expand most quickly through continuous monitor platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways in the United States compress commercialization timelines for biosensor innovators, while reimbursement codes from the Centers for Medicare & Medicaid Services determine adoption velocity for continuous monitoring platforms across diverse geographies.
United States
Integrated health systems and accountable care organizations consolidate purchasing through volume-based contracts bundling sensors with analytics. Medicare remote patient monitoring codes expand continuous glucose monitor eligibility to rural counties lacking endocrinology specialists. The Minneapolis-St. Paul corridor anchors Medtronic's operational infrastructure for sensor fabrication and algorithm development.
Germany
Hospital procurement offices in Berlin and Munich require MDR technical documentation as gatekeeping criteria for glucose monitor tenders. Europe's Medical Device Regulation imposes stricter clinical evidence requirements for software updates, forcing manufacturers to maintain post-market surveillance infrastructures. The Baden-Württemberg cluster concentrates Roche's automated analyzer manufacturing serving reference laboratories across the continent.
China
NMPA streamlines predicate device comparisons for next-generation electrochemical sensors targeting the world's largest diabetes population. Domestic manufacturers exploit fermentation capacity in Jiangsu and Zhejiang provinces to secure glucose oxidase supply chains. The Yangtze River Delta hosts contract manufacturing for test strip exports to Southeast Asian markets.
Japan
METI funding programs accelerate non-invasive optical glucose sensing pilots within corporate wellness frameworks at major insurers. PMDA reviews for algorithm-modified continuous monitors trigger 12-18 month delays that favor established players with regulatory infrastructure. The Kansai region maintains precision chemical manufacturing for HbA1c reagent production serving domestic reference laboratories.
India
CDSCO fast-track approvals for affordable continuous monitors address price-sensitive Type 2 diabetes management in tier-2 cities. Government health insurance schemes under Ayushman Bharat expand point-of-care HbA1c testing in district hospitals lacking central laboratory infrastructure. The Maharashtra-Gujarat pharmaceutical corridor concentrates contract manufacturing for enzymatic reagent exports to African markets.
Diabetic Assays Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with vertical control over sensor fabrication and algorithm development separating scale players from component suppliers. The structure rewards backward integration into test strip manufacturing and electrochemical sensor production. Three archetypes dominate: diversified medtech conglomerates with hospital laboratory anchoring, pure-play continuous monitor specialists with software-centric business models, and diagnostic reagent houses with proficiency testing relationships. Competitive moves concentrate on strategic partnerships for closed-loop algorithm integration and geographic licensing for regulatory pathway acceleration.
Among diversified healthcare conglomerates, Abbott and F. Hoffmann-La Roche Ltd exemplify the integrated leader archetype through captive supply of enzymatic reagents and automated analyzer systems. Dexcom, Inc. occupies a position within the pure-play specialist tier, representing the software-centric model where predictive analytics rather than hardware accuracy alone determines competitive positioning. Siemens Healthcare GmbH anchors the European hospital procurement channel through technical documentation capabilities that satisfy MDR gatekeeping requirements.
| Leading Market Players |
|---|
| Abbott |
| F. Hoffmann-La Roche Ltd |
| Medtronic |
| Dexcom, Inc. |
| Siemens Healthcare GmbH |
| Bio-Rad Laboratories, Inc. |
| BioMerieux |
| DiaSorin S.p.A |
| Ortho Clinical Diagnostics |
| Others |
Supply Flow & Price Mechanics
Fermentation capacity utilization in Jiangsu and Zhejiang provinces anchors glucose oxidase production economics, concentrating cost leverage among Asian biomanufacturing hubs while compressing margin floors for disposable test strip producers dependent on spot enzyme procurement.
Pricing Analysis
Long-term offtake agreements between integrated health systems and continuous glucose monitor manufacturers dominate United States procurement, though retail pharmacy chains increasingly negotiate spot purchases for point-of-care HbA1c devices. Pricing stratifies across premium continuous monitoring subscriptions, standard analyzer reagent contracts, and economy private-label test strips. Cost compression in the strip segment intensifies because private-label pharmacy brands capture volume share from branded suppliers. Hospital laboratories exhibit lowest price sensitivity due to bundled analyzer service contracts, while uninsured homecare patients in rural counties face highest out-of-pocket exposure.
Supply Chain Analysis
Inventory lead times for electrochemical sensors stretch 8-14 weeks from Asian fabrication facilities to United States distribution centers, creating working capital intensity for manufacturers managing sensor obsolescence risk. Production concentrates in China for test strip substrates, Germany for automated analyzer systems, and the United States for algorithm development. Supply chains draw from glucose oxidase fermentation, printed circuit board fabrication, and medical-grade adhesive films. Single-source vulnerability concentrates in Asian sensor membrane suppliers. Distribution runs through group purchasing organizations for hospital systems and direct-to-consumer platforms for subscription sensor replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biosensor calibration expertise scarcity constrains laboratory workforce capacity for continuous monitor validation, tightening operational flexibility for health systems accelerating real-time glucose monitoring deployment.
For Market Incumbents: Shield reference laboratory relationships through proficiency testing logistics control against Quest Diagnostics and LabCorp network concentration. Capture backward integration into electrochemical sensor fabrication to secure supply continuity amid Asian fermentation capacity constraints. Prioritize FDA 510(k) predicate device libraries to accelerate competitor clearance timelines. For New Entrants and Emerging Players: CDSCO fast-track approvals for affordable continuous monitors in Indian tier-2 cities offer lowest regulatory friction for price-sensitive Type 2 diabetes management. Telehealth reimbursement expansion under CMS remote patient monitoring codes enables rural United States penetration without specialist infrastructure. Partner with retail pharmacy chains for point-of-care HbA1c placement bypassing hospital laboratory intermediaries. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pure-play continuous monitor specialists with software-centric business models and subscription sensor replacement. Long-term viability over the projection horizon favors targets with closed-loop algorithm integration capabilities and regulatory infrastructure spanning FDA and MDR pathways. Watch FDA guidance evolution on integrated closed-loop systems as inflection signal for platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Algorithm Integration | Convergence with automated insulin delivery creates dual-function platform demand at Medtronic and Abbott. |
| MDR Technical Documentation Investment | European hospital procurement gatekeeping requires post-market surveillance infrastructure at Siemens Healthcare. |
| Remote Patient Monitoring Reimbursement | CMS code expansion enables continuous monitor deployment in rural United States counties lacking endocrinology access. |
| Non-Invasive Optical Sensing Development | Corporate wellness pilots at Kaiser Permanente and UnitedHealth Group target pre-diabetes population screening. |
| Subscription Sensor Replacement Model | Express Scripts and OptumRx pharmacy benefit workflows align per-member-per-month budgeting with consumption patterns. |
Methodological Framework
Cross-validation between hospital procurement database analysis and clinician interview transcripts anchors the qualitative findings on continuous monitor adoption drivers. Primary interviews with endocrinology practice administrators, biomedical engineering directors, GPO contracts managers, and CMS reimbursement policy specialists combined with secondary validation against FDA 510(k) filings, hospital supply chain disclosures, and CMS Medicare claims data. Bottom-up test strip volume modeling and top-down continuous monitor revenue triangulation ensure segmentation consistency.
Sensitivity analysis across enzyme reagent cost volatility scenarios and biosensor accuracy degradation assumptions shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, diabetes application, end-user channel, and technology platform. CAGRs derive from installed base expansion rates and replacement cycle dynamics. Forecast inputs incorporate FDA clearance timeline distributions and MDR notified body review cycle durations.
Decision-makers should treat outputs as directional under stable reimbursement code structures and continuous manufacturing scale-up assumptions; material deviation would warrant model refresh. Forecasts reflect assumptions on telehealth policy continuity and Asian fermentation capacity expansion. Revision becomes warranted when optical sensor accuracy thresholds cross clinical acceptance boundaries or closed-loop regulatory guidance shifts materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
HIV Diagnostics Market
Diagnostics
Complement C3 ELISA Kits Market
Diagnostics
Mycology Immunoassays Testing Market
Diagnostics
Spain in-Vitro Diagnostics Market
Diagnostics
Sperm Count Test Market
Diagnostics
Global Sepsis Diagnostics Market
Diagnostics
At-Home Cancer Testing Market
Diagnostics
Middle East and Africa Ovarian Cancer Diagnostics Market
Diagnostics
Clostridium Diagnostics Market
Diagnostics
Global Paper Diagnostics Market
Diagnostics
Europe Autoimmune Disease Diagnostics Market
Diagnostics
Neglected Tropical Diseases Diagnosis Market
Diagnostics
Global HIV/AIDS Diagnostics Market
Diagnostics
Autoimmunity Immunoassay Market
Diagnostics
Global Rabies Diagnostics Market
Diagnostics
Molecular Diagnostics Market