
 Global Molecular Quality Controls Market | 2026-2036
Global Molecular Quality Controls Market Size, Share, and Industry Trends Forecast 2026-2036
Global Molecular Quality Controls Market Foresight
The molecular quality controls sector is consolidating around a widening gap between premium multiplexed standards and commodity single-analyte controls. Bio-Rad Laboratories leverages its long-standing proficiency in multiplexed reference materials to command premium positioning. Thermo Fisher Scientific anchors its portfolio through integrated workflow solutions that span sample prep through validation. F. Hoffmann-La Roche differentiates via proprietary digital PCR control architectures that reduce inter-lab variability.
Molecular quality controls comprise characterized nucleic acid preparations with defined target concentrations, manufactured through recombinant or native extraction methods to verify assay accuracy, precision, and detection limits across diagnostic platforms. Real-Time PCR controls retain the largest installed base due to infectious disease testing volume, while Next-Generation Sequencing standards represent the fastest-expanding category as tumor profiling and rare variant detection protocols multiply. Digital PCR controls command outsized margins because absolute quantification eliminates standard curve dependencies that plague relative methods.
The FDA's Clinical Laboratory Improvement Amendments and the EMA's In Vitro Diagnostic Regulation impose escalating analytical validation burdens that force laboratories to expand control utilization beyond minimum compliance thresholds. China's NMPA accelerates local registration requirements for imported molecular diagnostics, creating parallel demand for domestically manufactured control materials. Stakeholders must monitor how evolving pharmacogenomics guidelines from OECD harmonization initiatives reshape control panel specifications before committing to long-term manufacturing configurations.
Market Dynamics
Regulatory validation burdens from the FDA's Clinical Laboratory Improvement Amendments and EMA's In Vitro Diagnostic Regulation are forcing clinical laboratories to expand control utilization beyond minimum thresholds, compressing purchasing cycles and elevating specification requirements across all product tiers.
Growth Catalysts
- Precision medicine protocols:Tumor profiling and pharmacogenomics programs in the United States and Germany require multiplexed reference materials with defined variant allelic frequencies. Clinical laboratories validate NGS workflows against these standards before reporting patient results.
- IVDR implementation:The European Union's In Vitro Diagnostic Regulation mandates analytical validation for all molecular diagnostic assays placed on the market after May 2022. Manufacturers must demonstrate traceability to certified reference materials.
- Infectious disease surveillance:Digital PCR controls for absolute quantification of viral load are displacing relative quantification methods in reference laboratories handling emerging pathogen monitoring for public health agencies.
Market Restraints
- Lyophilized matrix costs:Stabilized nucleic acid preparations in synthetic or clinical matrices require expensive excipients and controlled-atmosphere manufacturing. Input cost volatility for molecular-grade reagents compresses margins for commodity control producers.
- Supplier concentration:Native extraction methods for rare pathogen controls depend on access to authenticated clinical specimens. Collection networks concentrate in the United States and Western Europe, creating geographic supply risk.
- Reference material scarcity:Certified reference materials for novel fusion transcripts and copy number variants remain unavailable from national metrology institutes, forcing laboratories to rely on inter-laboratory exchange agreements.
Strategic Opportunities
- China NMPA localization:Accelerated registration requirements for imported molecular diagnostics create parallel demand for domestically manufactured control materials with Chinese metrology traceability.
- Cell-free DNA applications:Liquid biopsy validation requires reference materials mimicking tumor-derived circulating DNA fragmentation patterns. This emerging application lacks standardized control formats.
- ISO 20395 convergence:The international standard for nucleic acid quantification is harmonizing digital PCR calibration procedures across jurisdictions, enabling cross-border control material acceptance.
Industry Challenges
- Metrology expertise scarcity:Digital PCR control production requires personnel proficient in absolute quantification uncertainty calculation. Clinical diagnostic manufacturers compete with pharmaceutical analytical development teams for this talent pool.
- Legacy platform integration:Real-time PCR instruments with closed software architectures resist third-party control material integration, forcing manual data entry workflows that introduce transcription errors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Molecular Quality Controls Market |
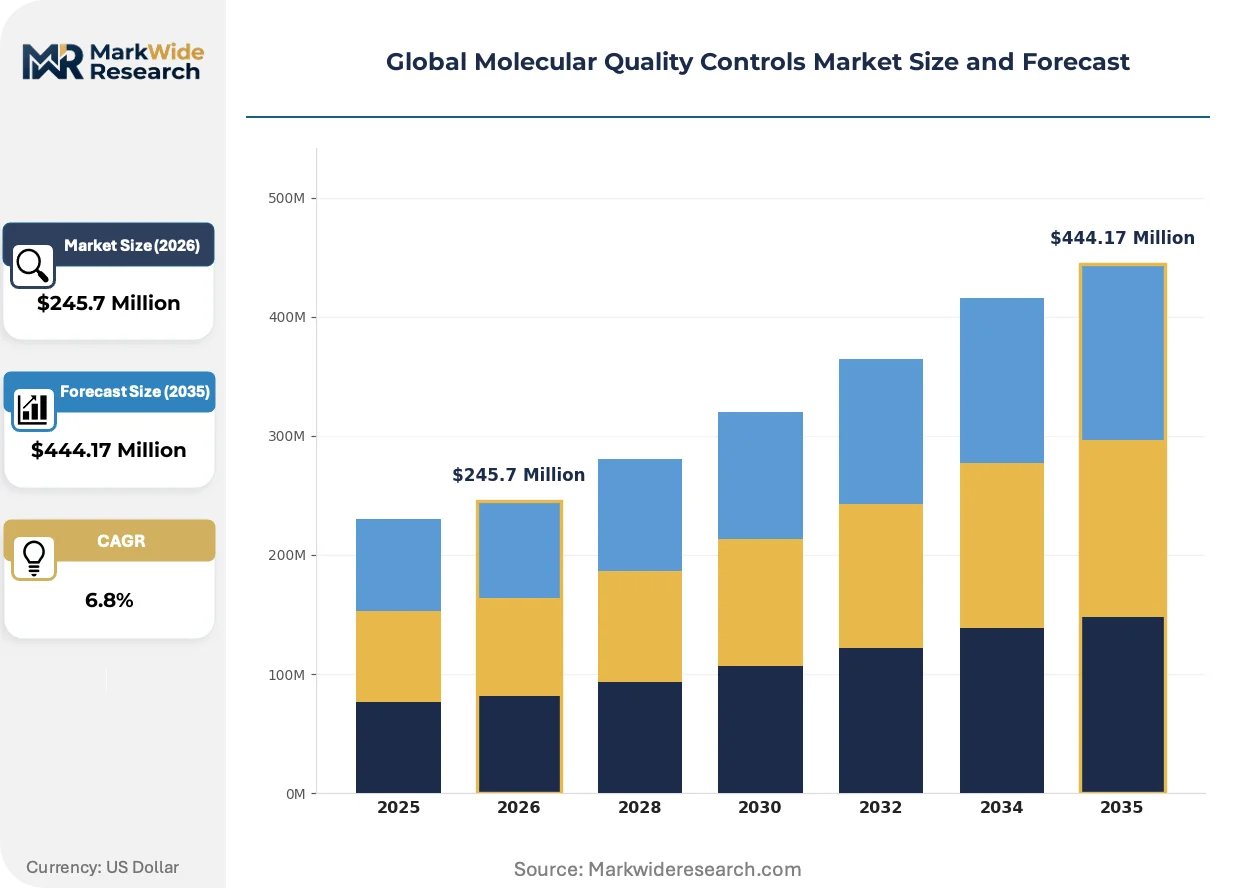
| Market Size in 2026 | $245.7 Million |
| Market Size in 2035 | $444.17 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Controls, Negative Controls, Quantitation Standards, Calibration Materials, Reference Samples, Control Kits Technology: Next-Generation Sequencing, Real-Time PCR, Microarray, Digital PCR, Hybridization, Mass Spectrometry Application: Infectious Disease Testing, Genetic Disorder Screening, Forensic Analysis, Pharmacogenomics, Agricultural Biotechnology, Veterinary Diagnostics End User: Clinical Laboratories, Research Institutes, Pharmaceutical Companies, Academic Centers, Contract Research Organizations, Diagnostic Centers |
| Companies Covered | Bio-Rad Laboratories, Thermo Fisher Scientific, F. Hoffmann-La Roche, Abbott Laboratories, LGC Limited, ZeptoMetrix Corporation, Microbiologics, Randox Laboratories, bioMérieux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Molecular Quality Controls Market Shifts & Advancements
Freeze-dried ambient-stable formats are displacing cold-chain-dependent liquid preparations, reshaping distribution economics and enabling point-of-care control deployment. This format shift intersects with regulatory pressure for decentralized testing validation.
Lyophilized bead technology is decentralizing molecular quality control distribution by eliminating frozen shipping requirements. Regional reference laboratories in Brazil and India are adopting ambient-stable formats for peripheral site proficiency testing. This logistics transformation is compressing the addressable market for cold-chain service providers while expanding control penetration into resource-limited settings.
EMA's In Vitro Diagnostic Regulation is mandating common technical specifications for control material labeling and stability claims. Manufacturers must revalidate shelf-life data under accelerated aging protocols before CE marking renewal. Multiplexed oncology panels face the steepest compliance burden due to complex stability claims for multi-analyte formulations.
Laboratory procurement departments are consolidating supplier relationships to reduce qualification overhead. Large health system networks in the United States now mandate single-source contracts for molecular controls spanning all platform technologies. This concentration behavior favors vendors with comprehensive portfolios across real-time PCR, digital PCR, and NGS applications.
Global Molecular Quality Controls Market Segmentation
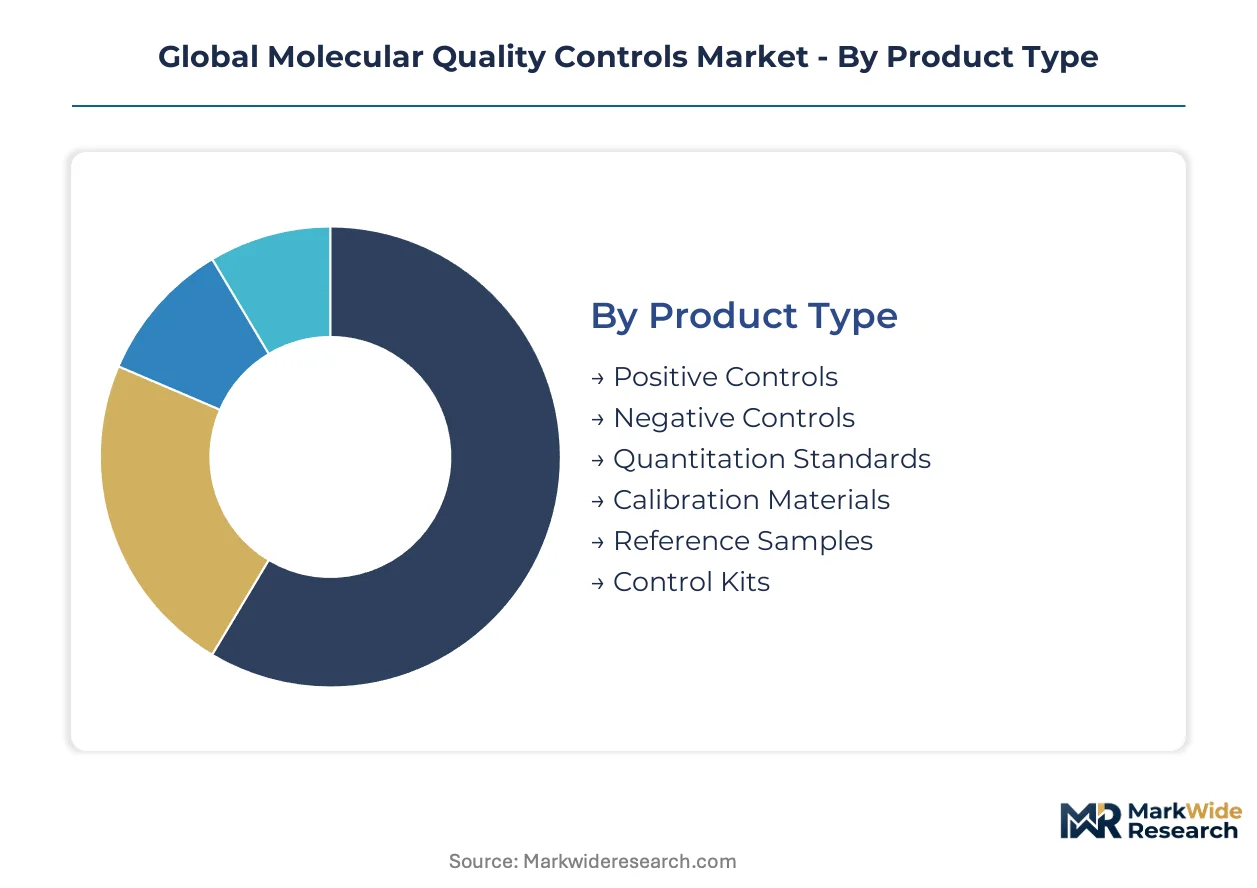
Molecular quality control segmentation reflects divergent regulatory burdens across product formats and analytical platforms. Laboratories select control categories based on FDA CLIA validation tiers, EMA IVDR traceability requirements, and NMPA localization mandates.
Product Type:
Certification intensity varies sharply across product types, with quantitative standards requiring ISO 17025-accredited reference material production while qualitative controls face lighter documentation burdens.
- Positive Controls:Characterized nucleic acid preparations with defined target sequences verify assay detection capability at specified concentrations. Clinical laboratories in the United States deploy these for FDA-mandated infectious disease panel validation. Demand concentrates in multiplexed formats as tumor profiling protocols expand.
- Quantitation Standards:Certified reference materials with absolute copy number concentrations enable digital PCR calibration without standard curve dependencies. German reference laboratories prioritize these for EMA IVDR analytical validation submissions. Supply scarcity for rare fusion transcript targets constrains penetration.
- Negative Controls:Nucleic acid preparations absent target sequences assess assay specificity and contamination.
- Calibration Materials:Traceable standards establishing measurement metrology for quantitative assays.
- Reference Samples:Characterized clinical specimens for inter-laboratory comparison studies.
- Control Kits:Pre-formulated multiplexed panels combining multiple control types for workflow integration.
Positive controls sit at the top of the volume ranking, with quantitation standards climbing the fastest.
Technology:
Platform selection determines manufacturing complexity, with absolute quantification technologies commanding premium pricing tiers against relative quantification methods.
- Real-Time PCR:Relative quantification controls dominate installed base due to infectious disease testing volume. Clinical laboratories in China leverage these for NMPA-registered diagnostic kit validation. Closed software architectures resist third-party integration.
- Next-Generation Sequencing:Multiplexed reference materials with defined variant allelic frequencies support tumor profiling and rare variant detection protocols. Academic medical centers in Germany adopt these for pharmacogenomics program accreditation. Complex stability claims for multi-analyte formulations steepen compliance burden.
- Digital PCR:Absolute quantification eliminates standard curve dependencies.
- Microarray:Legacy platform controls for comparative genomic hybridization applications.
- Hybridization:Probe-based detection controls for specific nucleic acid targets.
- Mass Spectrometry:Emerging platform for nucleic acid analysis validation.
Real-Time PCR maintains the largest installed base, though NGS gains share fastest as precision medicine protocols multiply.
Application:
End-use concentration shapes specification requirements, with clinical diagnostics demanding higher analytical validation documentation than research applications.
- Infectious Disease Testing:Viral load quantification controls for HIV, hepatitis, and respiratory pathogen panels. Public health reference laboratories in the United States deploy digital PCR formats for emerging pathogen surveillance. FDA CLIA mandates drive replacement frequency.
- Pharmacogenomics:Genotyping controls for drug metabolism enzyme variants guide therapeutic dosing. Hospital networks in Germany require these for EMA-compliant precision medicine programs. OECD harmonization initiatives reshape control panel specifications.
- Genetic Disorder Screening:Carrier screening and prenatal diagnostic controls.
- Forensic Analysis:DNA profiling standards for identity testing validation.
- Agricultural Biotechnology:GMO detection and trait verification controls.
- Veterinary Diagnostics:Pathogen detection standards for animal health surveillance.
Infectious disease testing anchors current demand volumes, while pharmacogenomics shows the steepest expansion trajectory.
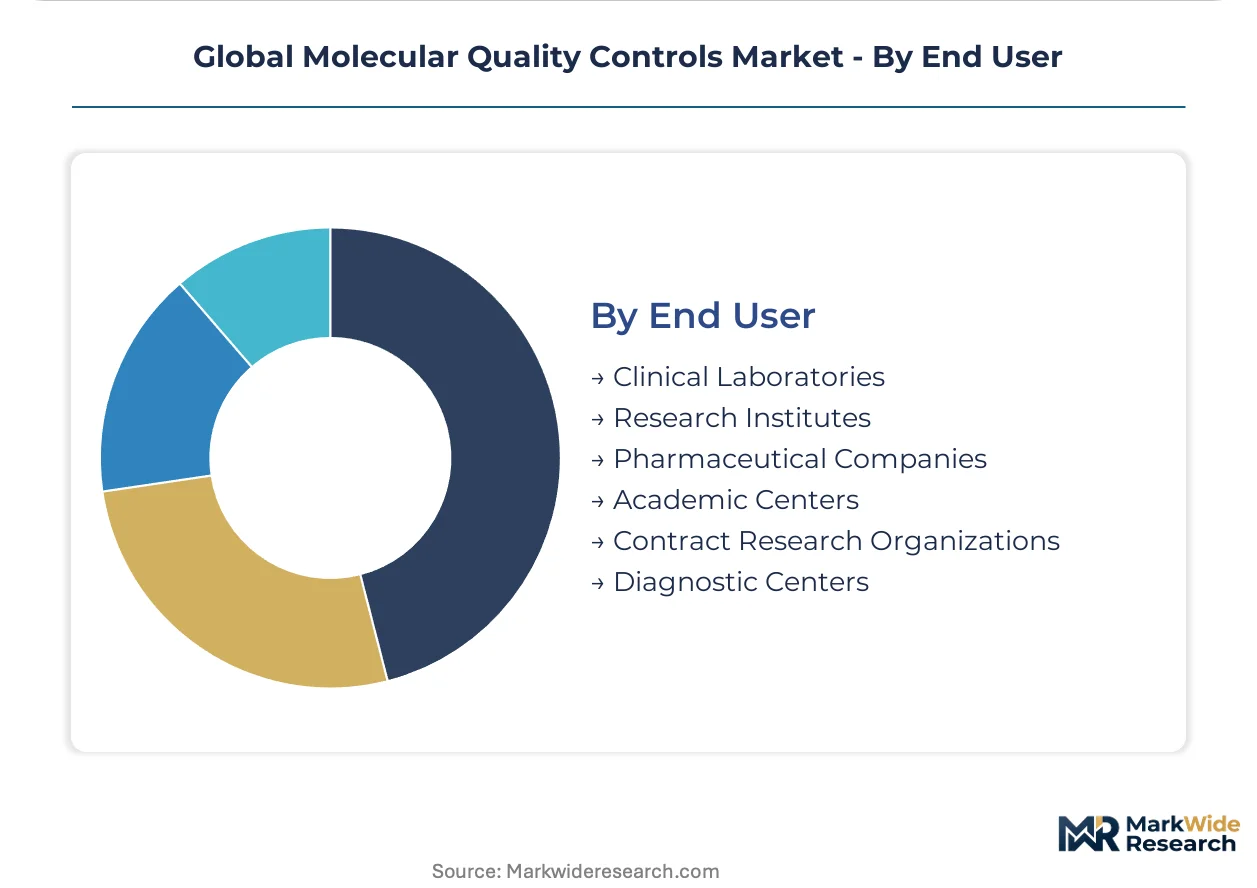
End User:
Procurement sophistication separates segments, with consolidated health system networks negotiating single-source contracts against fragmented research institute purchasing.
- Clinical Laboratories:Hospital-affiliated and independent diagnostic facilities with regulatory compliance obligations. Large United States health systems mandate comprehensive portfolio coverage across all platform technologies. Supplier qualification overhead drives consolidation.
- Pharmaceutical Companies:Companion diagnostic development and clinical trial validation requirements. CDSCO-registered trials in India create demand for locally traceable control materials. Metrology expertise scarcity constrains in-house production.
- Research Institutes:Academic and government research facilities with flexible specifications.
- Academic Centers:University-affiliated laboratories with grant-funded purchasing.
- Contract Research Organizations:Outsourced validation service providers.
- Diagnostic Centers:Point-of-care and decentralized testing facilities.
Clinical laboratories dominate procurement volumes, with pharmaceutical companies expanding most quickly as companion diagnostic pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical laboratory technologists and molecular diagnostic specialists concentrate in the United States, Germany, and China, anchoring regional demand patterns for quality control materials. These workforce clusters align with precision medicine infrastructure investments and regulatory validation requirements.
United States
Hospital network consolidation and FDA CLIA validation tiers drive demand for multiplexed reference materials. The FDA's Clinical Laboratory Improvement Amendments mandate expanded control utilization beyond minimum thresholds. Large health system networks in California and Texas now negotiate single-source contracts spanning all molecular diagnostic platforms.
Germany
Academic medical centers and pharmacogenomics programs require EMA-compliant analytical validation materials. The EMA's In Vitro Diagnostic Regulation mandates traceability to certified reference materials for all assays placed on the market. Industrial clusters in Bavaria and North Rhine-Westphalia host reference laboratories prioritizing digital PCR calibration standards.
China
NMPA localization mandates for imported diagnostics create parallel demand for domestically manufactured control materials. The NMPA accelerates registration requirements while emphasizing Chinese metrology traceability. Manufacturing facilities in the Yangtze River Delta and Pearl River Delta expand production of ambient-stable lyophilized formats.
United Kingdom
Research institute procurement and NHS laboratory consolidation reshape supplier relationships. The UK's departure from EU regulatory frameworks necessitates parallel validation documentation for EMA and domestic requirements. London and Southeast England clusters concentrate oncology panel validation activities for tumor profiling protocols.
India
CDSCO-registered clinical trials and pharmaceutical companion diagnostic development expand control material requirements. The CDSCO mandates local traceability for validation materials used in regulatory submissions. Contract research organizations in Maharashtra and Karnataka drive demand for cost-effective multiplexed control formats.
Global Molecular Quality Controls Market Competitive Landscape
Top-tier vendors anchor premium multiplexed and digital PCR segments, while mid-tier specialists compete on price-sensitive real-time PCR applications. The vendor base stratifies across three tiers: integrated diagnostic conglomerates with workflow-spanning portfolios, reference material specialists with ISO 17025-accredited production, and regional manufacturers serving localization mandates. Dominant competitive moves include portfolio diversification across platform technologies and geographic expansion through distributor partnerships in emerging markets.
Within the integrated conglomerate tier, Bio-Rad Laboratories and Thermo Fisher Scientific occupy positions exemplifying workflow-anchored competitive strategies. F. Hoffmann-La Roche represents the proprietary technology archetype through digital PCR control architectures. These three entities collectively illustrate how market positioning diverges between multiplexed reference material proficiency, integrated sample-to-validation solutions, and absolute quantification methodologies that reduce inter-laboratory variability.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche |
| Abbott Laboratories |
| LGC Limited |
| ZeptoMetrix Corporation |
| Microbiologics |
| Randox Laboratories |
| bioMérieux |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap reference material specialists in Germany and the United States anchor premium-tier production, their long-tenured customer relationships insulating pricing power while cold-chain logistics costs compress margins for commodity-grade competitors.
Pricing Analysis
Bundled workflow solutions command premium positioning against unbundled per-unit transactional sales. Pricing stratifies across ISO 17025-accredited certified reference materials, FDA-tier validation controls, and economy-grade qualitative preparations. Cost compression in lyophilized matrix production intensifies as molecular-grade reagent input costs fluctuate. Pharmaceutical companies show least price sensitivity due to companion diagnostic development timelines, while contract research organizations in India prioritize cost-effective multiplexed formats.
Supply Chain Analysis
Single-source vulnerability sits with authenticated clinical specimen collection networks concentrated in the United States, Germany, and the United Kingdom. Native extraction methods for rare pathogen controls draw from hospital-affiliated biorepositories and public health reference laboratories. Tariff exposure threatens cross-border distribution of temperature-sensitive liquid preparations. Distribution runs through regional reference laboratory hubs that qualify and redistribute to peripheral clinical sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in lyophilized ambient-stable formats, where elimination of frozen shipping costs enables price premiums alongside distribution reach into resource-limited settings.
For Market Incumbents: Anticipate regulatory consolidation by accelerating ISO 20395-aligned digital PCR calibration investments before EMA IVDR renewal deadlines compress competitor response windows. Defend multiplexed oncology panel positioning through backward integration into synthetic matrix production, reducing excipient cost volatility exposure. Channel control via single-source health system contracts in California and Texas limits emerging entrant access to high-volume validation workflows. For New Entrants and Emerging Players: Enter via cell-free DNA liquid biopsy control white space, where standardized reference materials mimicking tumor-derived circulating DNA fragmentation patterns remain undeveloped. Target CDSCO-registered pharmaceutical trials in India and NMPA localization mandates in China as the most penetrable demand clusters. Go-to-market traction requires Chinese metrology traceability partnerships for domestic manufacturing credibility. For Investors and Strategic Acquirers: Valuations sit cheapest among regional lyophilized format manufacturers lacking ISO 17025 accreditation but possessing established distribution in Brazil and India. Long-term viability favors acquisition targets with ambient-stable technology platforms and emerging market regulatory registrations. Monitor OECD pharmacogenomics harmonization initiative announcements as the inflection signal for control panel specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Accreditation Investment | EMA IVDR traceability mandates elevate certified reference material production barriers for competitors. |
| Lyophilized Format Scale-Up | Ambient-stable production eliminates cold-chain dependency and expands point-of-care deployment economics. |
| NMPA Localization Partnership | Chinese metrology traceability requirements create captive demand for domestically manufactured control materials. |
| Digital PCR Calibration Expansion | Absolute quantification expertise scarcity commands premium positioning against relative quantification methods. |
| Single-Source Health System Contracting | Large United States networks consolidate supplier relationships to reduce qualification overhead burdens. |
Research Methodology
Coverage spans the United States, Germany, China, the United Kingdom, and India, with primary inputs from each market cluster combined with secondary validation. Interviews with clinical laboratory directors, reference material production managers, regulatory affairs specialists at diagnostic manufacturers, and GPO contracts managers informed demand-side dynamics. Secondary sources included FDA CLIA guidance documents, EMA IVDR technical specifications, NMPA registration databases, hospital procurement records, and ISO standard development committee outputs. Bottom-up segment sizing triangulated against top-down market value estimates.
Granularity-level modeling applied product type, technology platform, application area, and end-user sophistication tier dimensions across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by average selling price evolution. Forecast inputs incorporated regulatory implementation timelines for EMA IVDR compliance deadlines, NMPA localization mandate acceleration, and pharmacogenomics program expansion rates in academic medical centers.
Inputs from regulatory filing databases and health system procurement platforms were available through the study window; gaps in real-time digital PCR instrument installed base data introduce uncertainty bands around absolute quantification control penetration estimates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Arbovirus Testing Market
Testing Services
Drug Tester Market
Testing Services
Candida Vaginitis Rapid Testing Market
Testing Services
Mycological Testing Market
Testing Services
Middle East and Africa IVD Regulatory Affairs Outsourcing Market
Testing Services
Pneumonia Testing Market
Testing Services
CRO Mass Spectroscopy Services Market
Testing Services
Trichomonas Rapid Testing Market
Testing Services
Zika Virus Testing Market
Testing Services
Fecal Calprotectin Test Market
Testing Services
Global GI Stool Testing Market
Testing Services
Beta-Hydroxybutyrate Testing Market
Testing Services
Industrial Radiography Testing Market
Testing Services
Global Lipid Panel Testing Market
Testing Services
Thrombophilia Testing Market
Testing Services
Apoptosis Testing Market